
 Global Rhamnolipid Market | 2026-2036
Global Rhamnolipid Market Size, Share, and Industry Trends Forecast 2026-2036
Global Rhamnolipid Market Intelligence
The European Union's Green Deal and its associated chemical strategies are restructuring demand for biodegradable surfactants like rhamnolipids. Evonik Industries AG leverages its large-scale fermentation capacity to serve multiple end-user segments. Stepan Company competes by offering a portfolio that includes both bio-based and conventional surfactants. Jeneil Biotech specializes in microbial fermentation processes, focusing on high-purity rhamnolipid production for niche applications.
Rhamnolipids are a class of glycolipid biosurfactants produced through the fermentation of specific bacterial strains, most notably Pseudomonas aeruginosa. These compounds exhibit excellent surface tension reduction and emulsifying properties, making them effective alternatives to synthetic surfactants. The cosmetics end-user segment leads in value due to the premium placed on 'green' ingredients in personal care formulations. Liquid forms represent a significant share, valued for their ease of handling and incorporation into existing manufacturing processes.
Regulatory frameworks like the US EPA's Safer Choice program and the EU's REACH regulation create market access advantages for biodegradable inputs. In China, the MEE's focus on water pollution control also indirectly supports the use of less harmful surfactants. Consequently, producers must navigate a complex patchwork of regional chemical safety and environmental marketing claim regulations to achieve market penetration.
Market Dynamics
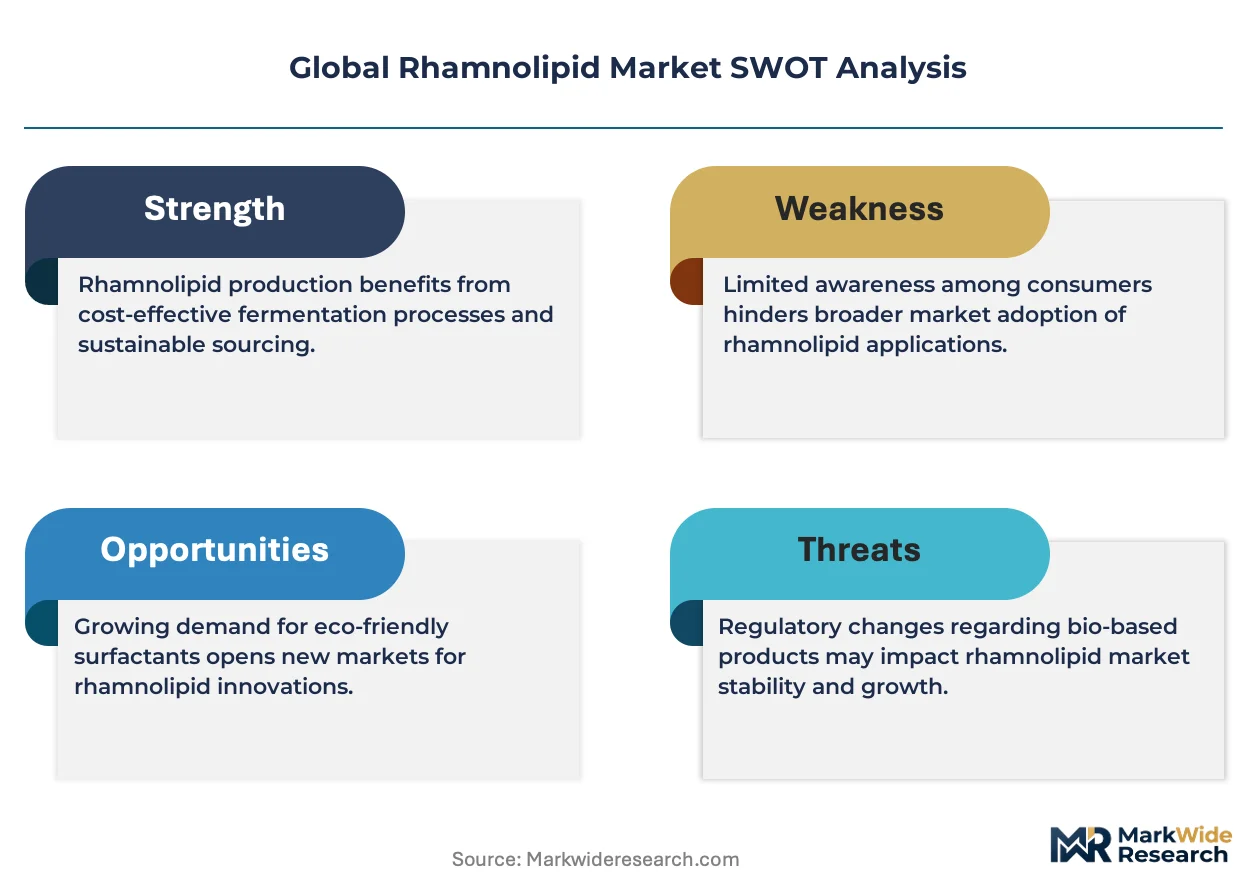
The central structural force shaping the rhamnolipid market is the regulatory-driven demand for sustainable surfactants colliding with the inherent scale-up complexities and higher costs of microbial fermentation compared to conventional petrochemical synthesis.
Growth Catalysts
- Regulatory Mandates:Frameworks like the European Union's REACH regulation and Green Deal are accelerating the phase-out of petroleum-based surfactants, directly benefiting biodegradable alternatives in industrial and consumer applications.
- Cosmetics Sector Demand:The personal care industry's focus on 'clean label' and 'green' formulations creates a premium market for bio-based ingredients, with consumers showing a willingness to pay more for products with verifiable environmental benefits.
- Fermentation Process Optimization:Advances in biotechnology, including strain engineering and downstream processing, are improving production yields and lowering costs, making rhamnolipids more competitive against synthetic surfactants.
Market Restraints
- Production Cost Disparity:The cost of microbial fermentation remains significantly higher than the synthesis of conventional surfactants, limiting adoption in price-sensitive applications like household detergents or industrial cleaning.
- Substrate Supply Volatility:Production is heavily dependent on specific carbon sources like vegetable oils or sugars, making input costs susceptible to fluctuations in agricultural commodity markets.
- Technical Performance Gaps:While effective, rhamnolipids may not match the performance of specialized synthetic surfactants in extreme temperature or pH conditions, restricting their use in certain demanding industrial processes.
Strategic Opportunities
- Agricultural Formulations:There is significant opportunity in developing rhamnolipid-based biopesticides and soil remediation agents, particularly in large agricultural economies like Brazil and the United States seeking sustainable farming solutions.
- Enhanced Oil Recovery:Niche, high-value applications in the energy sector, such as microbial enhanced oil recovery (MEOR), offer a new market where the unique emulsification properties can justify a premium price.
- Food and Beverage Applications:Securing regulatory approvals like GRAS (Generally Recognized as Safe) status from the US FDA would unlock vast potential for rhamnolipids as bio-emulsifiers in food processing.
Industry Challenges
- Fermentation Scale-Up:Translating laboratory success to cost-effective, large-scale industrial fermentation requires substantial capital investment in bioreactors and sterile processing equipment, creating a high barrier to entry.
- Purity and Standardization:The lack of global, harmonized standards for rhamnolipid purity and composition creates complexity for formulators and makes direct product-to-product comparisons difficult.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Rhamnolipid Market |
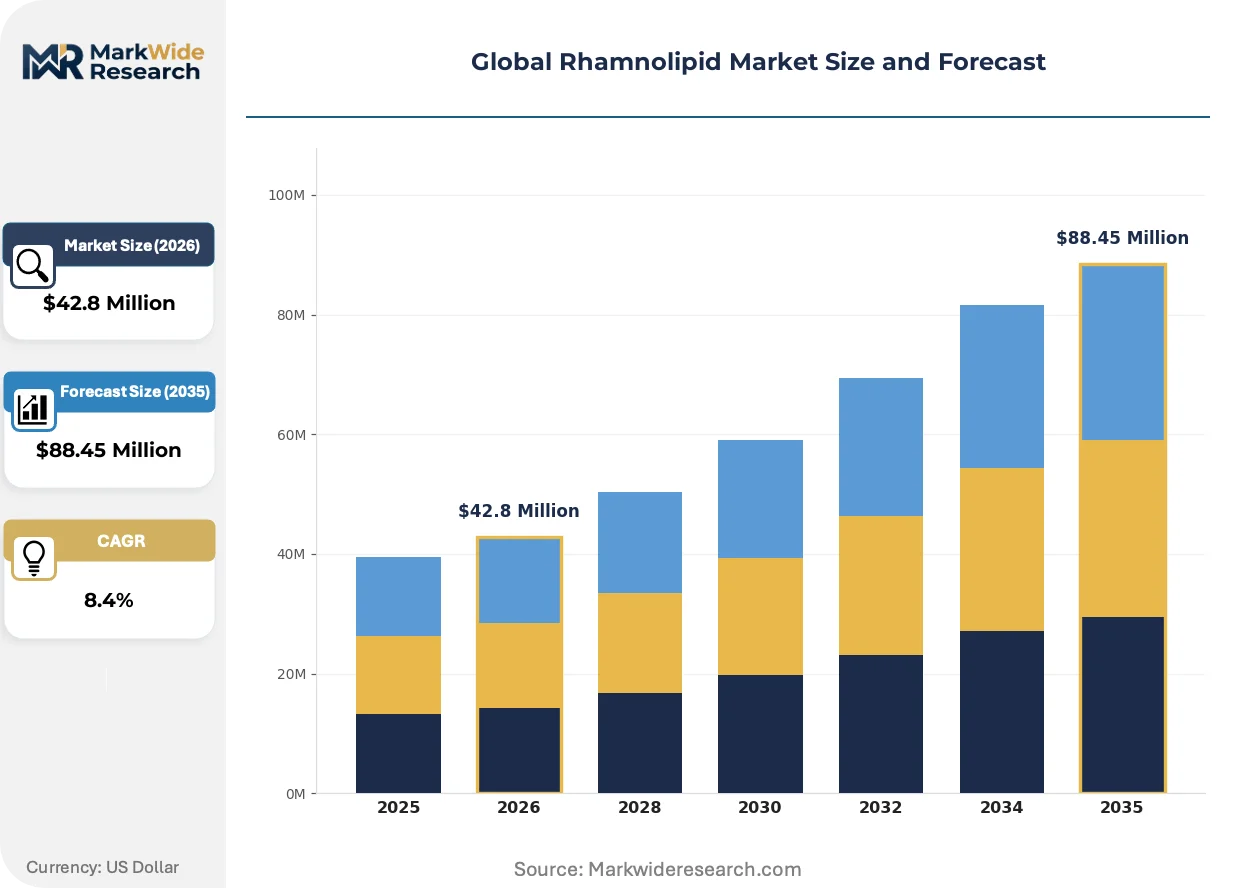
| Market Size in 2026 | $42.8 Million |
| Market Size in 2035 | $88.45 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rhamnolipid A, Rhamnolipid B, Rhamnolipid C, Rhamnolipid D End User: Agriculture, Cosmetics, Food & Beverage, Pharmaceuticals Form: Powder, Liquid, Paste, Granules Application: Surfactants, Biocontrol Agents, Emulsifiers, Antimicrobials |
| Companies Covered | Evonik Industries AG, Stepan Company, Jeneil Biotech, AGAE Technologies LLC, Biotensidon GmbH, TensioGreen Technology Corporation, Shaanxi Deguan Biotechnology Co., Ltd, Givaudan SA, Solvay S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Rhamnolipid Market Strategic Shifts & Innovations
The market's evolution is defined by the convergence of advanced bioprocessing techniques with clearer regulatory pathways for green chemistry. This combination is enabling rhamnolipids to move from niche academic materials to commercially viable industrial ingredients.
Solid-state fermentation (SSF) is an alternative production process that uses solid substrates and minimal water. Niche producers in the agricultural and food sectors are adopting this method to valorize waste streams like fruit pomace or grain husks. This technology is unifying the production of biosurfactants with agricultural waste management, creating potential for decentralized, circular-economy manufacturing models.
The US EPA's Safer Choice program establishes a clear benchmark and label for chemicals deemed safer for human health and the environment. This standard provides a distinct market access advantage for formulators who use certified ingredients in their products. The household cleaning and personal care segments are most affected, actively reformulating products to qualify for the Safer Choice label and appeal to environmentally conscious consumers.
A demand for ingredient traceability is altering sourcing behavior, especially within the premium personal care market. Formulators are bypassing traditional chemical distributors to establish direct relationships with fermentation specialists who can provide detailed documentation on substrate origin, including non-GMO and organic certifications. This shift is most pronounced in European markets like Germany and France, where regulatory and consumer expectations for supply chain transparency are highest.
Global Rhamnolipid Market Segmentation
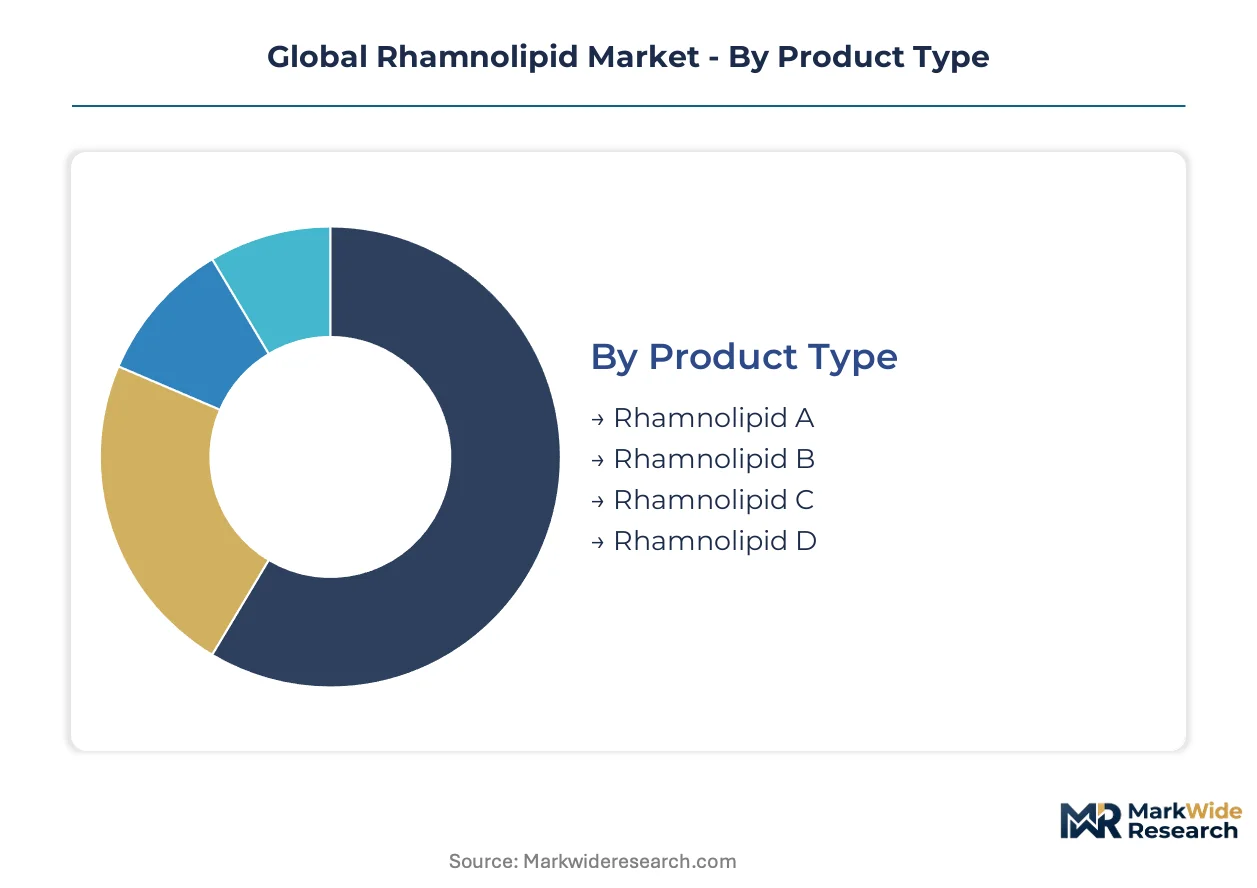
Understanding the market through segmentation reveals distinct demand patterns and regulatory influences across product types, end-user industries, physical forms, and specific applications. Each segment possesses unique drivers and adoption barriers, shaping the overall market trajectory for rhamnolipids.
Product Type:
Specific rhamnolipid product types face varying regulatory hurdles, influencing their market adoption and commercialization pathways.
- Rhamnolipid A:This mono-rhamnolipid variant often represents the simplest structural form, typically comprising one rhamnose molecule linked to a fatty acid chain. Demand concentrates in industrial cleaning and environmental remediation, where its broad-spectrum surface activity is valued.
- Rhamnolipid B:As a di-rhamnolipid, this type features two rhamnose units, offering enhanced emulsification and foaming properties compared to its mono-rhamnolipid counterparts. The cosmetics sector drives significant demand, valuing its mildness and bio-based origin in personal care formulations.
- Rhamnolipid C:This variant often possesses specific fatty acid chain lengths, tailoring its performance for targeted applications like agricultural biopesticides.
- Rhamnolipid D:Characterized by unique glycosidic linkages or fatty acid profiles, this type finds application in niche pharmaceutical excipients requiring high purity.
Leading the category by volume: Rhamnolipid A. Growing fastest: Rhamnolipid B.
End User:
End-user segments differentiate by their primary functional requirements for rhamnolipids, from surface activity to antimicrobial action.
- Agriculture:Rhamnolipids function as biopesticides, adjuvants, and soil remediation agents, supporting sustainable farming practices in large agricultural economies.
- Cosmetics:This segment places a premium on bio-based and 'clean label' ingredients for personal care formulations, utilizing rhamnolipids for their mild surfactant and emulsifying properties. European markets like Germany and France exhibit high demand due to stringent consumer preferences and regulatory support.
- Food & Beverage:Rhamnolipids offer potential as bio-emulsifiers and preservatives in food processing, pending regulatory approvals such as GRAS status from the US FDA. This sector seeks natural alternatives to synthetic additives for enhanced product stability and shelf life.
- Pharmaceuticals:This segment explores rhamnolipids for drug delivery systems, solubilizers, and antimicrobial agents, prioritizing high purity and biocompatibility.
The Cosmetics segment currently holds the largest share by revenue. The Food & Beverage sector demonstrates the steepest expansion trajectory.
Form:
The physical form of rhamnolipids dictates their ease of incorporation into manufacturing processes and logistical considerations for end-users.
- Powder:Powdered rhamnolipids provide advantages in terms of storage stability, reduced shipping weight, and precise dosing for dry-blend formulations. This form is particularly suitable for applications requiring long shelf life or controlled release.
- Liquid:This form offers excellent ease of handling and direct incorporation into existing aqueous manufacturing processes, minimizing formulation adjustments for many industrial and personal care applications. Its solubility makes it a preferred choice for high-volume production lines.
- Paste:This semi-solid form often results from concentrated production, finding use in applications where high active ingredient content and controlled dissolution are beneficial.
- Granules:Granular rhamnolipids offer dust-free handling and improved flow characteristics, making them suitable for bulk industrial applications and automated dispensing systems.
Liquid forms dominate current market consumption. Powdered rhamnolipids are gaining share fastest due to logistical benefits.
Application:
Different applications leverage specific performance characteristics of rhamnolipids, from surface activity to biological control.
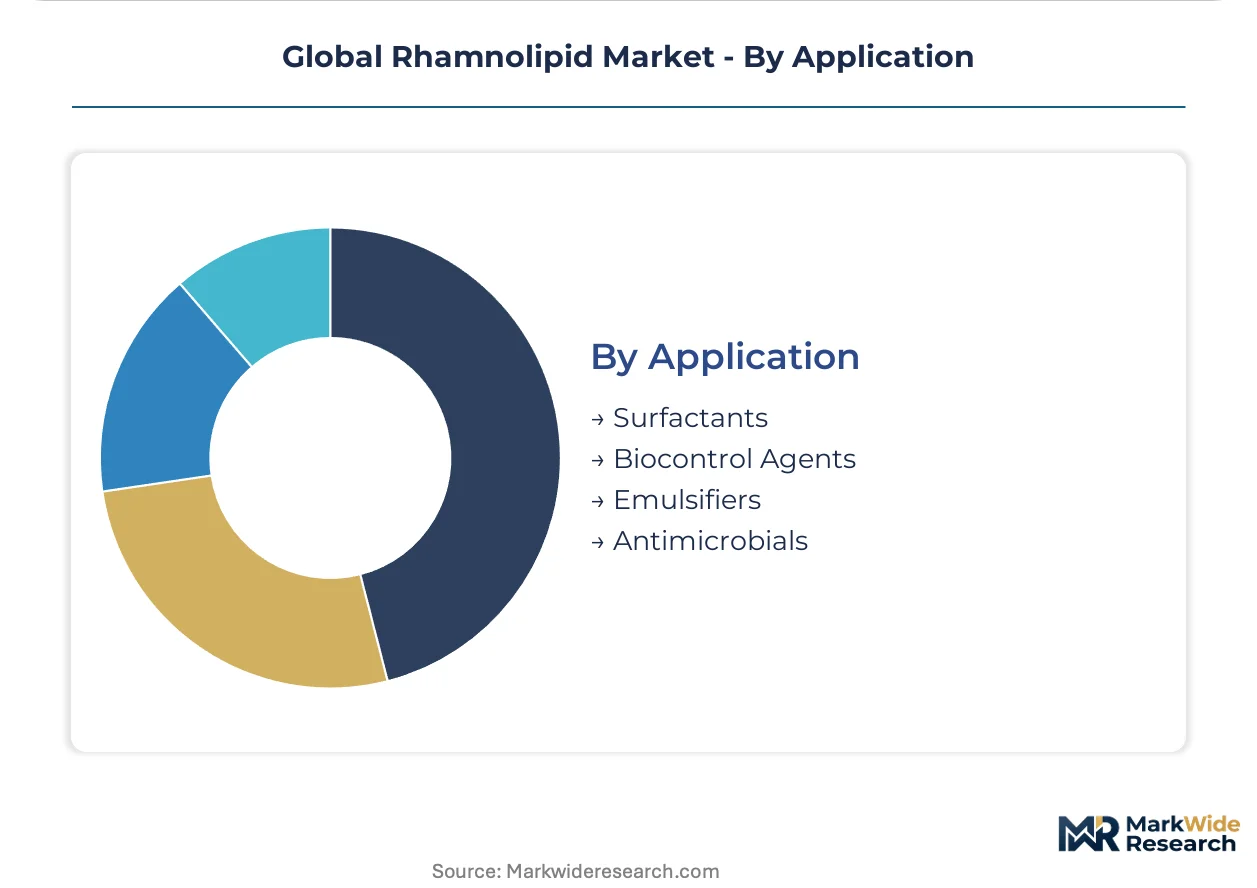
- Surfactants:Rhamnolipids excel as bio-based surfactants, significantly reducing surface tension and enabling effective cleaning and wetting in diverse industrial and consumer products. This primary application benefits from regulatory shifts promoting biodegradable alternatives.
- Biocontrol Agents:Rhamnolipids act as natural biopesticides and plant protection agents, offering an eco-friendly alternative in sustainable agriculture.
- Emulsifiers:Their ability to stabilize oil-in-water or water-in-oil mixtures makes rhamnolipids valuable bio-emulsifiers in cosmetics, food products, and enhanced oil recovery. The food and beverage industry particularly seeks natural emulsification solutions.
- Antimicrobials:These compounds exhibit broad-spectrum antimicrobial activity against bacteria and fungi, finding potential use in pharmaceuticals and food preservation.
Surfactant applications command the largest market segment. The Biocontrol Agents segment is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main region in Germany, a prominent hub for specialty chemicals, drives demand for rhamnolipids. This area benefits from strong industrial and consumer focus on sustainable ingredients. Formulators here actively seek bio-based alternatives for diverse applications.
Germany
German manufacturers exhibit strong demand for bio-based surfactants in cosmetics and industrial cleaning. The European Union's REACH framework and Green Deal accelerate the shift away from petroleum-derived chemicals. The chemical industry cluster around Ludwigshafen and Leverkusen actively integrates rhamnolipids into new product lines.
United States
The United States market shows significant potential in personal care, agriculture, and emerging food applications. The US EPA's Safer Choice program provides market access advantages for certified biodegradable ingredients. California's personal care industry, alongside agricultural states like Iowa, explores rhamnolipids for sustainable formulations.
China
Chinese chemical producers are increasingly adopting rhamnolipids, driven by water pollution control and green manufacturing initiatives. The MEE's focus on environmental protection indirectly supports the use of less harmful surfactants. Industrial zones within the Yangtze River Delta are exploring rhamnolipid applications in cleaning and environmental remediation.
Brazil
Brazilian agriculture presents a substantial opportunity for rhamnolipids as biopesticides, adjuvants, and soil remediation agents. ANVISA regulations for food additives could unlock new markets for bio-emulsifiers. The agribusiness sector in the São Paulo region investigates sustainable inputs for large-scale farming operations.
France
French cosmetic brands prioritize 'green' and 'clean label' ingredients, creating premium demand for rhamnolipids in personal care formulations. European Union regulations, including the Green Deal, reinforce consumer expectations for sustainable products. The Cosmetic Valley cluster near Chartres leads innovation in bio-based ingredient sourcing and application.
Global Rhamnolipid Market Key Industry Players
Premium-margin players sit above commodity-margin players across product purity and application specialization. The market structure involves a mix of large chemical conglomerates, specialized biotech firms, and niche ingredient suppliers. Companies pursue strategic partnerships, capacity expansion, and technology licensing to secure market position.
Large-scale chemical manufacturers like Evonik Industries AG anchor the market with extensive production capabilities, serving multiple end-user segments. Stepan Company represents a diversified player, offering both bio-based and conventional surfactants to a broad customer base. Within the specialized biotech tier, Jeneil Biotech exemplifies a company focusing on microbial fermentation processes for high-purity rhamnolipid production in niche applications.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Stepan Company |
| Jeneil Biotech |
| AGAE Technologies LLC |
| Biotensidon GmbH |
| TensioGreen Technology Corporation |
| Shaanxi Deguan Biotechnology Co., Ltd |
| Givaudan SA |
| Solvay S.A. |
| Others |
Cost & Logistics Intelligence
The global vegetable oil price index directly influences rhamnolipid production costs, cascading into distinct pricing tiers for industrial versus premium personal care applications. This commodity price volatility feeds back into manufacturer supply choices, impacting investment in fermentation capacity.
Pricing Analysis
Value-based pricing anchors rhamnolipid sales in specialized applications like pharmaceuticals and high-end cosmetics. Price differentiation stems from purity grade requirements, such as pharmaceutical-grade versus industrial-grade, and specific regulatory certifications like US EPA Safer Choice. Pricing pressure stems from the higher production costs of microbial fermentation compared to synthetic alternatives. The household detergents segment exhibits the highest price sensitivity, while the cosmetics and pharmaceutical sectors are less sensitive to price fluctuations.
Supply Chain Analysis
Dual-sourcing requirements mandate multi-supplier qualification for rhamnolipid procurement, particularly in regulated industries. Geographic supply concentration includes Germany, the United States, and China, where major producers operate large-scale fermentation facilities. The supply chain draws from specific raw material dependencies, including vegetable oils and sugars, creating exposure to agricultural commodity market volatility. Distribution runs through both traditional chemical distributors and direct relationships with specialized fermentation firms for transparent sourcing in premium markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rhamnolipid market is transitioning into a consolidation play, driven by stringent regulatory frameworks like the EU's Green Deal that disadvantage smaller, non-compliant producers.
For Market Incumbents:Acquire advanced bioprocessing IP to secure proprietary strain engineering and fermentation techniques. Expand large-scale fermentation capacity in strategic regions such as the European Union and the United States to meet growing demand for bio-based surfactants. Invest in downstream processing technologies to achieve higher purity levels, addressing performance gaps of rhamnolipids in extreme temperature or pH conditions. Pursue certifications like GRAS status from the US FDA to unlock new, high-value food and beverage applications.
For New Entrants and Emerging Players:Digital ingredient sourcing platforms offer new entrants a direct route to market for niche rhamnolipid formulations, bypassing traditional distribution channels. Target underpenetrated segments like agricultural biopesticides and specific pharmaceutical excipients. The food and beverage sector presents a significant white-space opportunity, particularly with pending regulatory approvals. Emphasize circular economy benefits of solid-state fermentation, valorizing agricultural waste streams as a sustainable go-to-market angle.
For Investors and Strategic Acquirers:Distressed-cycle entries favor specialized biotech firms in European markets, especially those with established fermentation infrastructure and strong intellectual property portfolios. The long-term viability of this market is strong, supported by persistent regulatory tailwinds and consumer demand for green chemistry. Identify acquisition targets with proven strain optimization capabilities and cost-effective production methods. Watch for significant breakthroughs in production cost reduction or widespread GRAS approvals as key inflection indicators.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Increases production volume to meet growing demand for sustainable surfactants. |
| Green Manufacturing Transition | Aligns production processes with environmental regulations and consumer preferences. |
| Long-term Supply Agreement | Secures consistent raw material input against commodity price volatility. |
| Joint Venture | Combines expertise for advanced bioprocess optimization and market access. |
| Product Launch in Agriculture | Diversifies revenue streams into the growing biopesticide and adjuvant markets. |
Research Approach
Document review covered EU REACH filings, US EPA Safer Choice program documentation, MEE environmental reports, and company 10-K reports, complemented by interviews with R&D directors, procurement managers, regulatory affairs specialists, and formulators. Primary data collection involved structured interviews with industry stakeholders across the value chain. This approach enabled comprehensive bottom-up and top-down triangulation of market data.
Historical market data cross-referenced with expert panel input formed the basis for quantitative projections across the modeling period. The analytical framework considered segmentation dimensions including product type, end-user industry, physical form, application, and regional regulatory clusters. Compound annual growth rates were derived from an analysis of market drivers, restraints, and strategic opportunities. Forecast inputs included biotechnology advancements and evolving regulatory policy shifts.
Inputs from published scientific literature and industry association reports were available through the study window; gaps in emerging application data introduce uncertainty bands around future adoption rates. Forecasts reflect assumptions regarding production cost reduction and regulatory approval timelines. Deviation in bioprocess cost reduction would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Naphthalene Sulfonate Market
Surfactants
Alkylamines Market
Surfactants
Acrylamide Tertiary-Butyl Sulfonic Acid (ATBS) Market
Surfactants
Superwetting Surfactants Market
Surfactants
Tetradecyl Chloride Market
Surfactants
Dioctyl Sulfosuccinates Components Market
Surfactants
Sodium Cumenesulfonate Market
Surfactants
Global Silicone Surfactants Market
Surfactants
North America Surfactants Market
Surfactants
Surfactant EOR Market
Surfactants
Emulsifying Wax Market
Surfactants
Amphoteric Emulsifier Market
Surfactants
Trisiloxane Market
Surfactants
Cetanol Market
Surfactants
Sugar-Based Surfactants Market
Surfactants
Powder Defoamers Market