
 Superwetting Surfactants Market | 2026-2036
Superwetting Surfactants Market Size, Share, and Industry Trends Forecast 2026-2036
Superwetting Surfactants Market Intelligence
Specialty formulation development for waterborne systems is rewriting the competitive positioning of superwetting surfactant suppliers. BASF SE leverages its extensive chemical portfolio to offer integrated solutions for coatings and agricultural clients. Evonik Industries AG specializes in silicone-based surfactants, targeting high-margin electronics and automotive applications. Dow Inc. competes on manufacturing scale and supply chain efficiency, particularly in commodity-grade products.
Superwetting surfactants are advanced chemical agents designed to drastically lower the surface tension of aqueous systems, often below 25 mN/m. Their primary function is to enable rapid spreading and penetration on hydrophobic or contaminated substrates, which is critical in high-speed industrial processes. Silicone-based products command a premium due to their superior performance in demanding applications like automotive coatings. The agriculture segment represents the fastest-growing application, driven by the need for efficient pesticide and herbicide delivery systems.
Regulatory frameworks, including the US Environmental Protection Agency's (EPA) Toxic Substances Control Act (TSCA) and Europe's REACH regulation managed by ECHA, mandate stringent evaluation of chemical persistence and aquatic toxicity. These rules directly influence raw material selection and product formulation, favoring surfactants with better environmental profiles. Navigating the trade-off between high-performance characteristics and regulatory compliance remains the central strategic challenge for manufacturers and formulators.
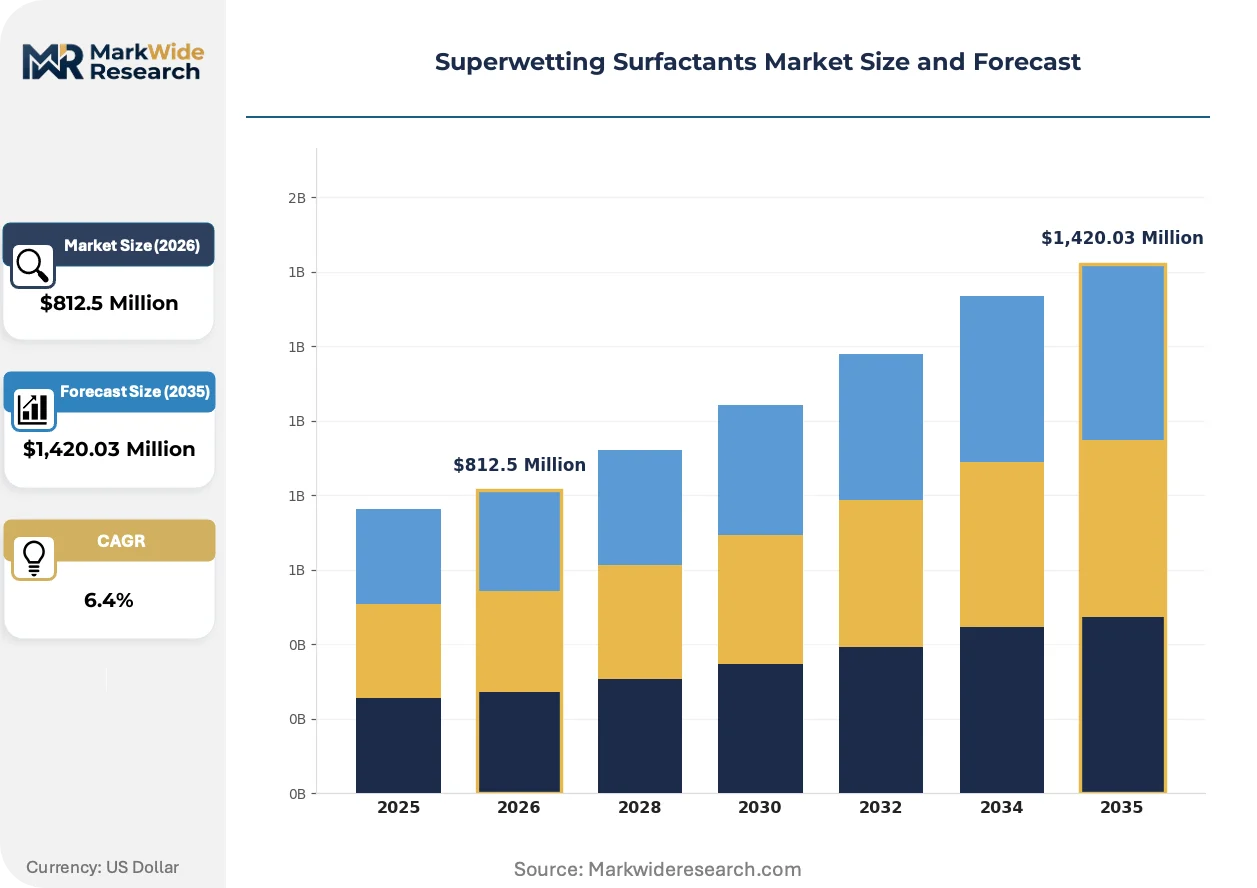
Market Dynamics
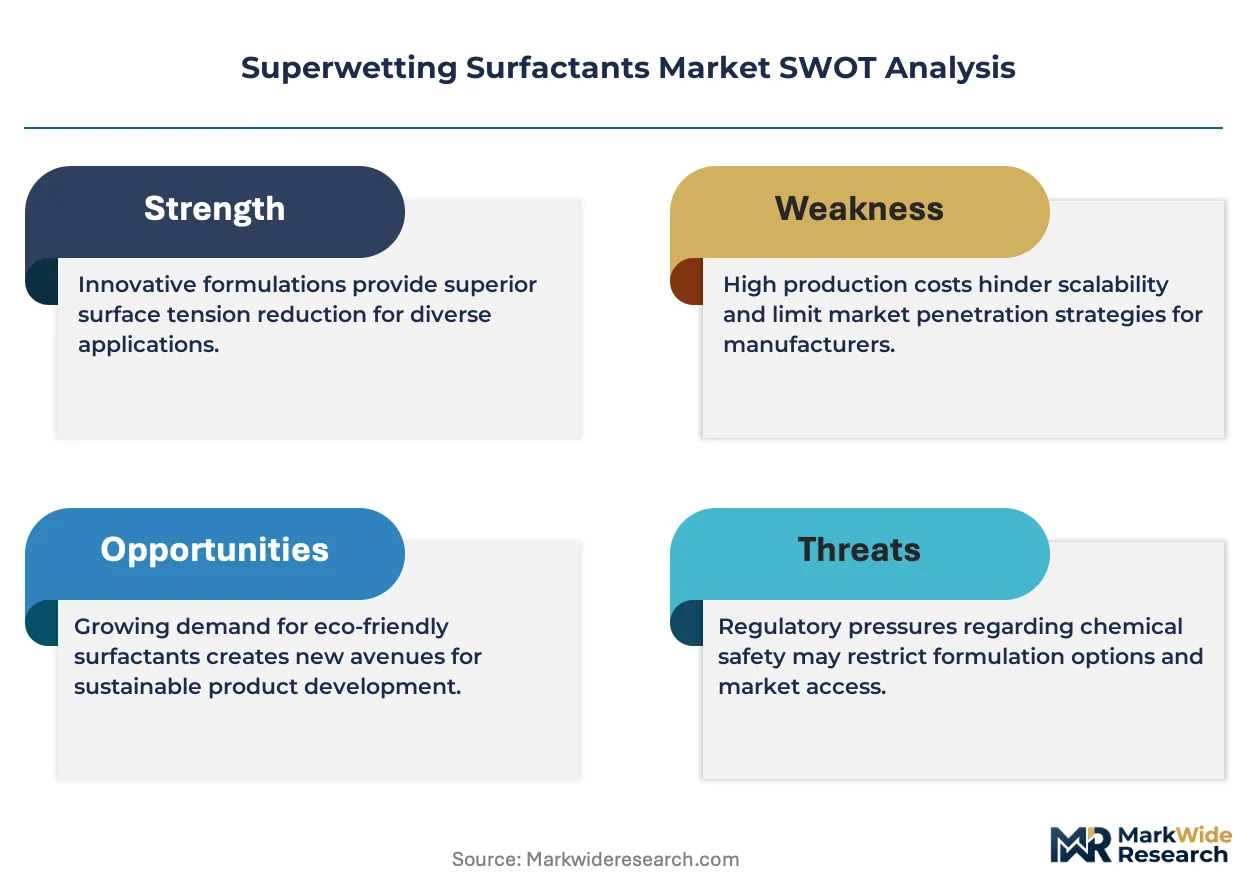
The central structural force shaping the market is the conflict between the need for ultra-high performance in advanced manufacturing and the stringent regulatory scrutiny over chemical persistence. This tension is particularly evident as formulators balance the superior wetting of silicone-based surfactants against the compliance demands of Europe's REACH framework.
Growth Catalysts
- Precision Agriculture:The drive for more efficient pesticide and herbicide application to maximize crop yields and minimize environmental runoff stimulates demand for adjuvants containing superwetting surfactants.
- Advanced Electronics Manufacturing:High-speed production of printed circuit boards and displays requires surfactants that can rapidly wet complex, hydrophobic surfaces, ensuring defect-free application of coatings and etchants.
- Industrial Coatings Innovation:The shift to waterborne coating systems in the automotive and industrial sectors necessitates the use of high-performance additives to achieve the surface finish and adhesion previously possible only with solvent-based systems.
Market Restraints
- Raw Material Volatility:The price and availability of key feedstocks, particularly siloxanes for silicone-based surfactants, are subject to significant fluctuation, impacting production costs and margin stability for manufacturers.
- Regulatory Hurdles:The extensive and costly data requirements for chemical registration under frameworks like the EPA's TSCA and ECHA's REACH create high barriers to entry for new molecules and can delay innovation.
- Substitution by Conventional Surfactants:In cost-sensitive, less-demanding applications, lower-priced conventional surfactants like alcohol ethoxylates can provide adequate performance, limiting the addressable market for premium superwetting products.
Strategic Opportunities
- Bio-based Formulations:Developing superwetting surfactants derived from renewable feedstocks presents a significant opportunity to capture market share among customers prioritizing sustainability and a favorable environmental profile.
- Emerging Economies:Agricultural sectors in Latin America and Southeast Asia represent underpenetrated markets where the introduction of advanced adjuvants can deliver substantial improvements in farming efficiency.
- Niche Technical Applications:Formulating surfactants for specialized uses such as medical diagnostics, microfluidics, and enhanced oil recovery opens new, high-margin revenue streams outside of traditional industrial segments.
Industry Challenges
- Reformulation Complexity:Adapting existing product lines to comply with evolving substance restriction lists under regulations like REACH without sacrificing critical performance attributes is a constant technical challenge for formulators.
- Specialized Talent Scarcity:There is a shortage of formulation chemists with the interdisciplinary expertise required to balance performance trade-offs, regulatory constraints, and cost targets across diverse end-uses like agrochemicals and coatings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Superwetting Surfactants Market |
| Market Size in 2026 | $812.5 Million |
| Market Size in 2035 | $1,420.03 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone-based, Fluorosurfactants, Non-ionic, Anionic Application: Coatings, Agriculture, Cleaning Products, Oil Recovery End User: Textiles, Personal Care, Automotive, Electronics Form: Liquid, Powder, Emulsion, Concentrate |
| Companies Covered | Evonik Industries AG, BASF SE, Dow Inc., Ashland Global Holdings Inc., Croda International Plc, Solvay S.A., Stepan Company, Clariant AG, Nouryon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Superwetting Surfactants Market Strategic Shifts & Innovations
Intensifying regulatory pressure for greener chemistries and end-user demands for greater process efficiency are accelerating product development. This is pushing innovation toward surfactants that offer superior performance at lower concentrations with improved environmental profiles.
Advanced molecular structures such as Gemini surfactants, which feature two hydrophilic and hydrophobic groups, provide exceptional surface tension reduction at very low use levels. Formulators of high-value digital printing inks and automotive clearcoats are adopting these chemistries to improve droplet spreading and substrate wetting. The extreme efficiency of these molecules is rendering obsolete the practice of using higher doses of conventional surfactants to achieve top-tier performance.
The US Environmental Protection Agency’s (EPA) risk evaluation process under the Toxic Substances Control Act (TSCA) is actively scrutinizing the aquatic toxicity and persistence of entire chemical classes. This regulatory action directly impacts raw material selection for products sold in North America. Consequently, formulators in industrial cleaning and agricultural markets are preemptively substituting materials under EPA review with alternative chemistries that possess more favorable and well-documented toxicological data.
A distinct behavioral shift sees end-users procuring integrated formulation support alongside chemical products, moving away from simple component purchasing. This trend disrupts the traditional distributor-led sales model, creating an advantage for suppliers capable of providing direct technical and regulatory guidance. The shift is most visible in the complex European coatings sector, where customers require collaborative support to ensure their final formulations meet all REACH requirements.
Superwetting Surfactants Market Segmentation
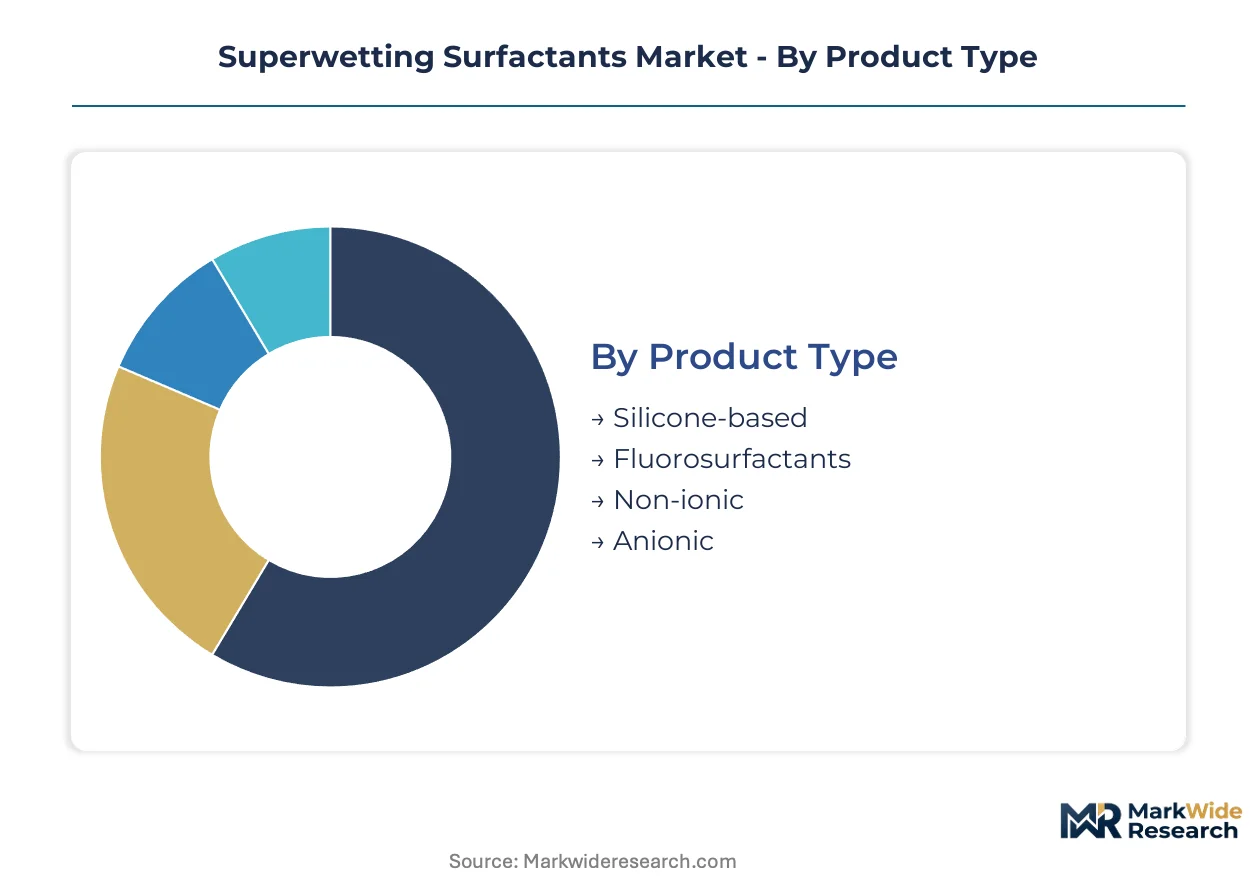
The segmentation of the superwetting surfactants market reveals the intricate balance between performance demands, regulatory compliance, and application-specific needs. Understanding these distinct segments allows manufacturers to tailor product development and market strategies effectively.
Product Type:
The varied product types of superwetting surfactants require differing levels of after-sales technical support, influencing supplier engagement models and customer retention strategies.
- Silicone-based:These surfactants utilize siloxane backbones to achieve ultra-low surface tension, delivering superior spreading and substrate wetting. Demand concentrates in high-performance automotive coatings and advanced electronics manufacturing due to their exceptional efficiency in demanding industrial processes.
- Fluorosurfactants:Characterized by highly electronegative fluorine atoms, these agents provide extreme surface tension reduction, often below 20 mN/m. Specialized applications in demanding sectors like fire-fighting foams and anti-fog coatings drive demand, despite increasing regulatory scrutiny from entities like the US Environmental Protection Agency (EPA).
- Non-ionic:These surfactants possess no charge, offering versatility and compatibility across a wide pH range in various formulations.
- Anionic:Carrying a negative charge, these are often cost-effective and find use in industrial cleaning and textile processing applications.
By volume, non-ionic surfactants dominate due to broad applicability. By growth pace, silicone-based products are expanding most quickly.
Application:
The cost tier of superwetting surfactants varies significantly across application segments, reflecting performance requirements and value added.
- Agriculture:Superwetting surfactants function as adjuvants, enhancing the efficacy of pesticides and herbicides by improving droplet spreading and leaf penetration. Precision agriculture initiatives globally drive demand for efficient chemical delivery systems, minimizing environmental runoff.
- Coatings:These additives reduce the surface tension of waterborne coating systems, enabling uniform film formation and adhesion on challenging substrates. The shift to sustainable waterborne formulations in the automotive and industrial sectors necessitates high-performance wetting agents.
- Cleaning Products:They improve the wetting and spreading of cleaning solutions on surfaces, enhancing dirt removal and rinse performance.
- Oil Recovery:Superwetting agents aid in enhanced oil recovery by altering rock wettability and reducing interfacial tension, facilitating oil displacement.
High-performance coatings and precision agriculture applications offer higher margin opportunities for advanced superwetting formulations.
End User:
Different end-user industries require tailored superwetting surfactant solutions, influencing product specifications and distribution channels.
- Automotive:The automotive industry utilizes superwetting surfactants in waterborne paints and clearcoats to achieve flawless finishes and robust adhesion. This sector demands consistent quality and high performance for aesthetic and protective layers.
- Electronics:In electronics manufacturing, these surfactants are critical for precise application of photoresists, etchants, and cleaning agents on complex circuit boards and displays. Rapid and defect-free processing is paramount for high-yield production.
- Textiles:Superwetting surfactants improve the penetration and uniform application of dyes and finishing agents onto textile fibers.
- Personal Care:These ingredients enhance the spreading properties and sensory feel of cosmetic and personal hygiene products.
Supply chain concentration for superwetting surfactants is highest in the automotive and electronics sectors due to specialized performance demands.
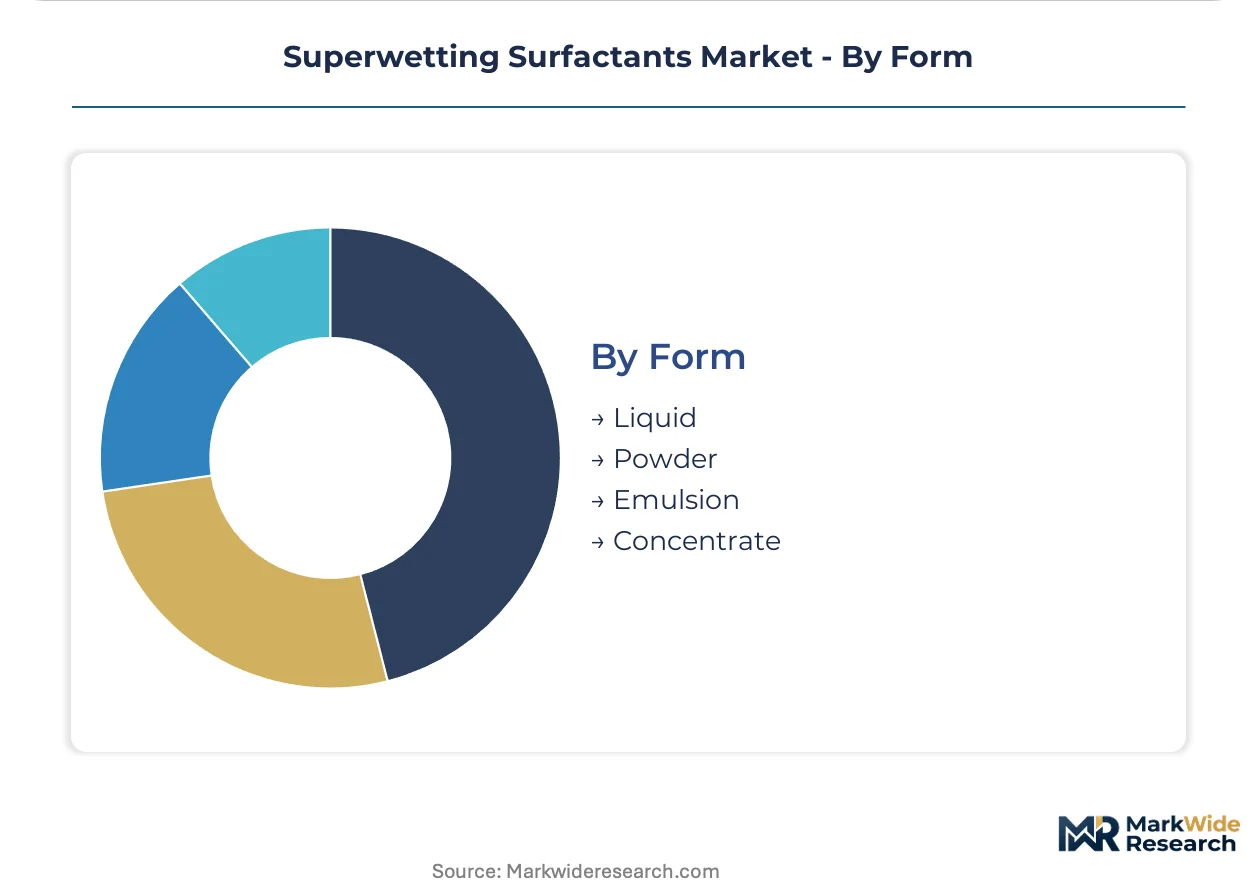
Form:
The physical form of superwetting surfactants directly impacts handling, storage, and dosage, influencing procurement volumes for end-users.
- Liquid:This is the most common form, favored for its ease of handling, mixing, and direct integration into liquid formulations. Liquid surfactants are widely used across diverse industrial and consumer applications.
- Emulsion:Emulsions are stable dispersions of one liquid in another, often used for delivering hydrophobic surfactants in aqueous systems. They offer improved stability and controlled release in specific applications like agrochemicals.
- Powder:Powder forms offer concentrated active ingredients, preferred for dry blend formulations or when water content is a concern.
- Concentrate:These highly concentrated products require dilution before use, offering advantages in shipping costs and storage efficiency for high-volume users.
Liquid forms represent the most mature segment, while concentrates are gaining traction for their logistical advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The superwetting surfactants market exhibits varied demand elasticity, with high-performance applications in electronics and automotive tolerating premium pricing, while agricultural and industrial cleaning segments remain more cost-sensitive. This contrast drives regional strategic focus for suppliers. Different regulatory frameworks also shape product development across key geographies.
China
Demand from advanced electronics manufacturing and precision agriculture boosts superwetting surfactant consumption. China's dual carbon goals encourage greener chemical formulations and efficient application methods across industries. Major chemical and electronics clusters in the Yangtze River Delta and Pearl River Delta drive significant volume.
United States
Agricultural adjuvants and high-performance industrial coatings are significant demand drivers for advanced surfactants. The US Environmental Protection Agency (EPA) scrutinizes chemical persistence and aquatic toxicity, influencing material selection. Silicon Valley and agricultural regions like the Midwest concentrate demand for specialized formulations.
Germany
The automotive and industrial coatings sectors require high-performance superwetting agents for waterborne systems. Europe's REACH regulation pressures formulators toward environmentally benign chemistries with favorable profiles. Major manufacturing hubs in Bavaria and North Rhine-Westphalia are key consumption centers for these additives.
India
Precision agriculture initiatives and expanding industrial sectors stimulate demand for efficient surfactant systems. The country's BIS standards increasingly emphasize product quality and environmental considerations for chemical imports. Industrial corridors in Maharashtra and Gujarat show rising adoption in textile and cleaning applications.
Japan
Advanced electronics and specialized automotive applications drive the need for ultra-low surface tension surfactants. METI regulations often prioritize chemical safety and efficiency in industrial processes, pushing innovation. Manufacturing centers in the Kanto region and Nagoya are critical for high-tech material demand.
Superwetting Surfactants Market Key Industry Players
Diversified chemical conglomerates and specialized niche players split the superwetting surfactants market, reflecting varying strategic priorities. Large, integrated chemical companies leverage extensive portfolios for broad application coverage and supply chain efficiency, particularly in commodity-grade products. Agile specialists, conversely, focus on high-performance silicone-based chemistries and advanced molecular structures for high-margin applications. Dominant competitive moves include portfolio diversification into bio-based alternatives and strategic partnerships for regulatory compliance and market access.
Within the global chemical industry, BASF SE and Dow Inc. exemplify the diversified chemical conglomerate archetype, offering broad product ranges across multiple end-use segments. These large-scale operators leverage their integrated supply chains to serve various industries, from agriculture to industrial coatings. Evonik Industries AG, a German-based specialty chemicals company, represents the focused high-performance player, particularly in silicone-based surfactants for demanding applications like electronics and automotive. These companies collectively anchor market supply through their extensive manufacturing capabilities and technical support.
| Leading Market Players |
|---|
| Evonik Industries AG |
| BASF SE |
| Dow Inc. |
| Ashland Global Holdings Inc. |
| Croda International Plc |
| Solvay S.A. |
| Stepan Company |
| Clariant AG |
| Nouryon |
| Others |
Cost & Logistics Intelligence
The Suez Canal's fluctuating transit costs directly influence the global superwetting surfactant supply, impacting raw material availability and the price differentiation of high-performance grades.
Pricing Analysis
Integrated formulation support drives significant lifetime value for superwetting surfactant suppliers, particularly in complex European coatings. Contract-based long-term offtake agreements represent the dominant pricing model for specialty grades. Performance efficacy and regulatory compliance certification act as key price differentiation drivers. Pricing softness affects commodity-grade non-ionic surfactants due to feedstock cost fluctuations, making agricultural buyers highly price-sensitive. High-performance electronics manufacturers show the least price sensitivity.
Supply Chain Analysis
Extended payment terms and dedicated supply-chain finance facilities support the capital-intensive production of superwetting surfactants. Geographic supply concentration centers in China and Germany for key intermediates, with the United States also contributing significantly. Production of silicone-based products depends on stable access to siloxanes, making commodity price volatility a structural supply chain risk. Distribution runs through a hybrid model combining direct sales for specialty chemicals and regional distributors for broader market access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Strategic advantage in the superwetting surfactants market hinges on specialized expertise. A scarcity of formulation chemists capable of balancing performance, regulatory demands, and cost targets creates a critical skill gap.
For Market Incumbents: Build regulatory compliance moats through proactive investment in toxicology studies for new chemistries. This defends against emerging regulatory threats like evolving ECHA REACH restrictions. Consolidate market share by acquiring smaller specialists with niche bio-based portfolios, leveraging existing distribution networks. Invest in advanced R&D for Gemini surfactants to counter performance pressure from new entrants.
For New Entrants and Emerging Players: Establish a beachhead in emerging economies like Latin America's agricultural sector, which remains underpenetrated. Focus on developing cost-effective, environmentally benign bio-based formulations to differentiate from established players. A direct-to-customer technical support model provides a strong go-to-market angle. Target niche technical applications such as microfluidics where performance demands justify premium pricing.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors agile specialty chemical firms with strong intellectual property in silicone-based and bio-based chemistries. Long-term viability depends on navigating evolving environmental regulations and demand for sustainable solutions. Target acquisition profiles include companies possessing advanced molecular structures like Gemini surfactants. The signal to watch is increased M&A activity for firms with validated ecotoxicological profiles.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Asia | Addresses growing demand from China's advanced electronics and India's agricultural sectors. |
| Bio-based Formulation Development | Captures market share among customers prioritizing sustainability and favorable environmental profiles. |
| Advanced Toxicology Data Generation | Proactively ensures compliance with stringent regulations like Europe's REACH and US EPA's TSCA. |
| Integrated Technical Support Services | Differentiates offerings by providing comprehensive formulation guidance to complex European coatings end-users. |
| Strategic Partnerships for Raw Material Security | Mitigates risks associated with commodity price volatility for key feedstocks like siloxanes. |
Research Approach
Two parallel data streams informed the analysis: primary interviews and secondary validation. Primary insights came from discussions with R&D directors, procurement leads at automotive OEMs, and agricultural formulators. Secondary research integrated customs data, chemical industry reports from Cefic, and corporate 10-K filings. This approach ensured robust bottom-up and top-down triangulation of market figures.
Forecast inputs considered historical market performance, current industry trends, and future technological adoption rates across the analysis window. The analytical framework modeled segmentation by product type, application, end-user, and form, alongside regional regulatory impacts. Compound annual growth rates were derived from a multi-variant regression analysis. Key industry-specific inputs included waterborne coatings penetration and precision agriculture adoption rates.
Stress conditions across raw material price volatility and regulatory enforcement levels were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding macro-economic stability and technological development trajectories. Geopolitical shifts or unforeseen supply chain disruptions would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Natural Wax Emulsion Market
Surfactants
Global Fluorosurfactants Market
Surfactants
Global Methyl Ester Sulfonate Market
Surfactants
Waxing Sponge Market
Surfactants
Oil-in-Water Anionic Emulsifier Market
Surfactants
Emulsifying Wax Market
Surfactants
Cetyl Chloride Market
Surfactants
Emulsion Stabilizers Market
Surfactants
Tetrabutylammonium Bromide Market
Surfactants
Global Calcium Sulfonate Market
Surfactants
North America Surfactants Market
Surfactants
Global Methyl Soyate Market
Surfactants
Cyclopentasiloxane Market
Surfactants
Sulfosuccinate Market
Surfactants
Fatty Methyl Ester Sulfonate Market
Surfactants
Global Low Foam Surfactants Market