
 Surfactant Cleansers and Adjuvants Market | 2026-2036
Surfactant Cleansers and Adjuvants Market Size, Share, and Industry Trends Forecast 2026-2036
Surfactant Cleansers and Adjuvants Market Analytics
Consolidation among personal care and household product manufacturers is repositioning procurement leverage toward large-volume buyers with formulation expertise. BASF SE leverages its integrated petrochemical feedstock position to secure cost advantages across anionic and nonionic surfactant lines. Evonik Industries differentiates through specialty silicone surfactants for high-margin cosmetic applications. Stepan Company anchors North American supply through bio-based feedstock investments and sulfonation infrastructure.
Surfactant cleansers and adjuvants comprise amphiphilic compounds that reduce interfacial tension between immiscible phases, typically synthesized through sulfonation, ethoxylation, or enzymatic processes with active matter concentrations ranging from 15% to 95%. Their primary commercial purpose spans detergency, emulsification, wetting, and foaming across consumer and industrial formulations. Liquid cleaners dominate volume consumption in household and institutional channels where dilution economics and dispensing convenience concentrate margin pools. Pharmaceutical-grade surfactants command premium positioning as parenteral and topical drug formulations require ultra-low impurity profiles certified under USP-NF and EP monographs. Oil recovery applications represent a structurally growing segment as enhanced oil recovery operations deploy surfactant flooding in mature basins.
EPA registration requirements under FIFRA govern agricultural adjuvant formulations in the United States, while REACH substance authorization in Europe restricts certain ethoxylated alkylphenols from consumer applications. FDA oversight of pharmaceutical-grade surfactants through ICH Q3D elemental impurity guidelines and USP <1092> excipient biopharmaceutics classification shapes qualification protocols for drug developers. China's NMPA alignment with ICH standards is accelerating local certification of surfactant excipients for generic injectables. Stakeholders must monitor regulatory divergence between biodegradability mandates in the EU Green Deal and emerging state-level restrictions on per- and polyfluoroalkyl substances in the United States, as these frameworks will determine which chemistries retain multi-jurisdictional market access.
Market Dynamics
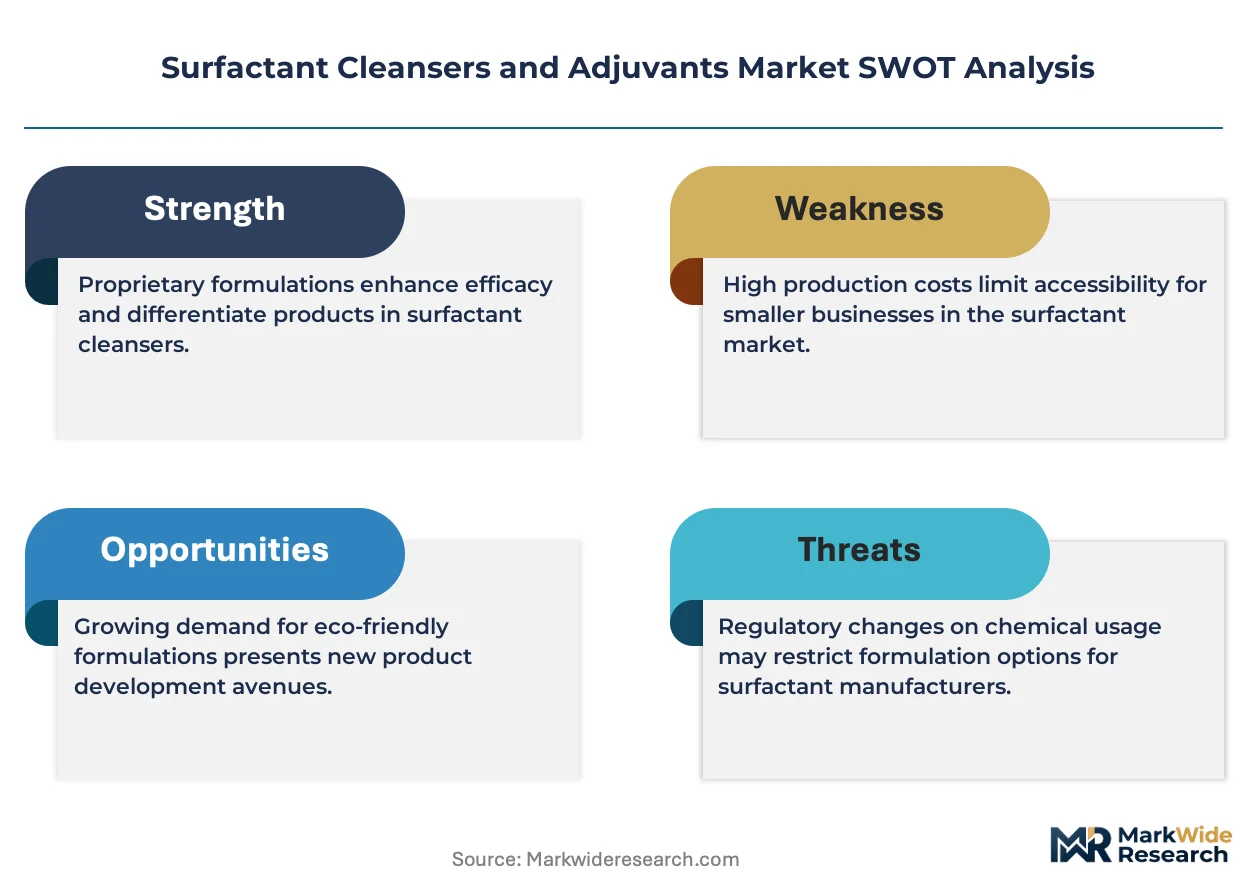
REACH substance authorization in Europe and tightening EPA standards in the United States are forcing surfactant manufacturers to reformulate away from ethoxylated alkylphenols and toward biodegradable alternatives, compressing legacy chemistry margins while opening premium positioning for compliant suppliers.
Growth Catalysts
- EU Green Deal biodegradability mandates:The EU Green Deal's stringent biodegradability requirements are accelerating replacement of nonylphenol ethoxylates in household detergents, creating pull for bio-based surfactants certified under OECD 301B protocols.
- Enhanced oil recovery operations:Surfactant flooding in mature basins across North America and the Middle East is expanding industrial volume demand as operators target residual oil mobilization in depleted reservoirs.
- Pharmaceutical-grade certification alignment:China's NMPA adoption of ICH Q3D guidelines is enabling domestic surfactant excipient suppliers to qualify for generic injectable formulations previously served by imports.
Market Restraints
- Feedstock cost volatility:Palm kernel oil and coconut oil price swings tied to Southeast Asian weather patterns and biofuel policy arbitrage compress margin predictability for natural surfactant producers.
- Sulfonation capacity concentration:North American sulfonation infrastructure clusters along the US Gulf Coast, creating hurricane exposure and logistics bottlenecks for anionic surfactant supply security.
- Fluorosurfactant substitution pressure:Per- and polyfluoroalkyl substances face emerging state-level restrictions in the United States, forcing reformulation of high-performance industrial applications where silicone alternatives underperform.
Strategic Opportunities
- Bio-based feedstock integration:Agricultural residue-derived alkyl polyglucosides from Brazilian sugarcane bagasse offer cost-advantaged routes to nonionic surfactants with carbon-negative certification potential.
- Microbiome-compatible cosmetic formulations:Mild amphoteric surfactants for skin microbiome preservation are capturing premium positioning in Korean and Japanese personal care markets where dermocosmetic science commands formulation premiums.
- Direct-to-compounder digital channels:Specialty surfactant distributors are deploying AI-driven formulation platforms that bypass traditional distributor tiers, capturing margin and technical relationship ownership with mid-scale personal care compounders.
Industry Challenges
- Multijurisdictional registration timelines:Agricultural adjuvant manufacturers face divergent EPA FIFRA, ECHA REACH, and Brazil ANVISA data requirements that extend product launch cycles and fragment regulatory affairs staffing.
- Pharmaceutical excipient qualification complexity:USP-NF and EP monograph compliance for parenteral-grade surfactants demands dedicated GMP facilities with elemental impurity testing capabilities that smaller suppliers cannot economically justify.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surfactant Cleansers and Adjuvants Market |
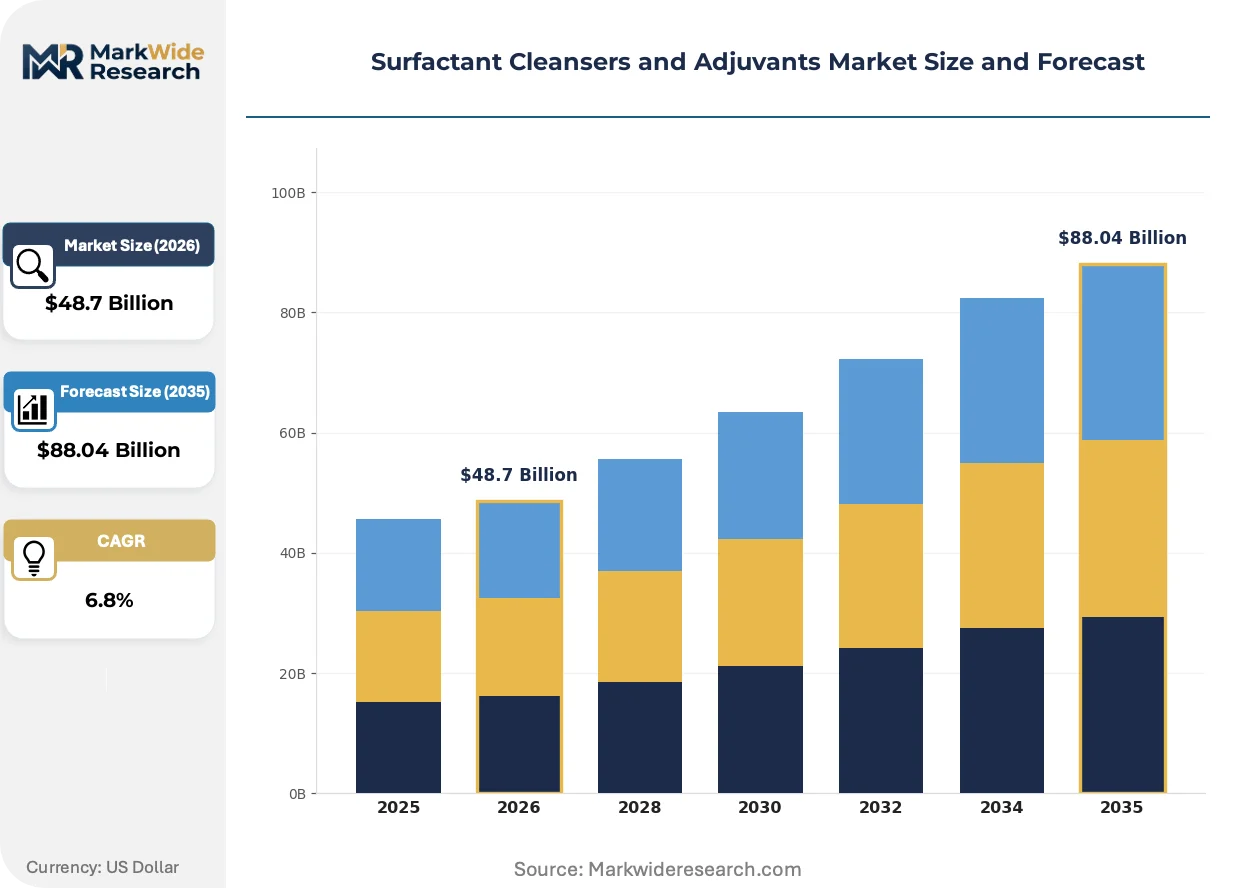
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Cleaners, Solid Cleaners, Powder Cleaners, Foam Cleaners Industry Vertical: Household, Industrial, Healthcare, Automotive Grade: Food Grade, Pharmaceutical Grade, Cosmetic Grade, Industrial Grade Application: Surface Cleaning, Personal Care, Agriculture, Oil Recovery |
| Companies Covered | BASF SE, Evonik Industries, Stepan Company, Akzo Nobel, Clariant, Croda International, Kao Corporation, Solvay, Huntsman, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surfactant Cleansers and Adjuvants Market Evolving Landscape
Enzymatic synthesis routes and biosurfactant fermentation platforms are disrupting conventional petrochemical processes, while regulatory chemistry restrictions and buyer sustainability scorecards are rewriting formulation specifications across end-use verticals.
Enzymatic transesterification for sugar-based surfactant production is converging with continuous processing reactor designs to reduce solvent use and energy intensity. European household care formulators are piloting these routes at commercial scale. The technology is converging with carbon accounting requirements to compress the cost premium versus conventional ethoxylation.
ECHA REACH authorization restrictions on 4-nonylphenol, branched and linear substances with ≥1% 4-nonylphenol are eliminating these surfactants from European consumer applications by 2025. Industrial users must qualify alternatives for metalworking fluids and textile processing. Personal care manufacturers are responding fastest, with reformulation cycles compressed to 18 months.
Formulation service unbundling is fragmenting traditional surfactant-distributor relationships as compounders seek direct technical partnerships with specialty chemical innovators. Mid-scale personal care brands in Southeast Asia are bypassing regional distributors to access biosurfactant expertise from fermentation specialists. This pattern is most visible in Indonesia and Vietnam where local formulation capabilities are deepening fastest.
Surfactant Cleansers and Adjuvants Market Segmentation
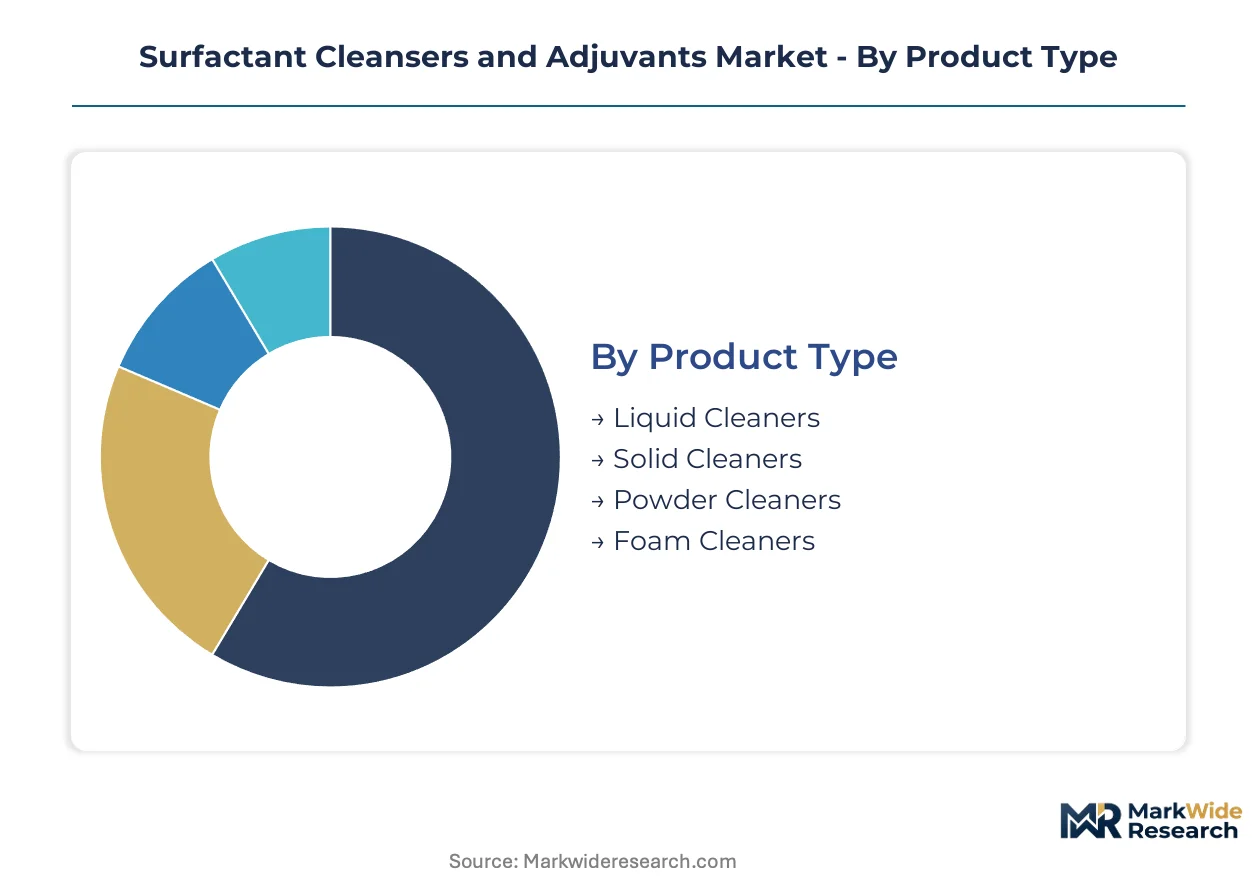
Surfactant formulation requirements diverge sharply across end-use specifications, with capital allocation decisions hinging on sulfonation infrastructure, GMP certification thresholds, and feedstock integration economics. Procurement patterns in this market track directly to grade purity standards and regulatory registration burdens.
Product Type:
Liquid and foam formats demand the heaviest upfront investment in automated filling lines and compatibility testing for packaging polymers.
- Liquid Cleaners:Water-based formulations with active matter concentrations of 15-40% dominate institutional channels where dilution economics concentrate procurement volumes. North American household brands are consolidating SKU ranges around concentrated liquids to reduce freight costs per cleaning cycle.
- Solid Cleaners:Compressed bars and blocks eliminate water content for freight efficiency, finding traction in cruise line and remote facility supply chains where storage space commands premium valuation. Manufacturing requires extrusion or casting equipment with lower throughput than liquid lines.
- Powder Cleaners:Spray-dried granules with built-in anti-caking agents serve emerging market households where tap water quality varies and consumers prefer controlled dosing.
- Foam Cleaners:Aerosol or pump-dispensed formats with specialized propellant or mechanical foaming agents target vertical surfaces and precision applications in automotive detailing and food processing sanitation.
Liquid cleaners absorb the bulk of installed capacity; foam cleaners are expanding most quickly in specialized industrial niches.
Industry Vertical:
Customer concentration and contract duration vary dramatically, with industrial buyers negotiating multi-year supply agreements while household channels fragment across retail formats.
- Household:Mass-market detergents and surface sprays operate on thin formulation margins offset by volume scale, with European retailers driving sustainability scorecard requirements into supplier contracts.
- Industrial:Metalworking fluids, textile processing, and hard surface sanitation demand surfactant packages engineered for extreme pH and temperature stability, commanding technical service premiums and longer qualification cycles.
- Healthcare:Hospital-grade disinfectants and instrument cleaners require EPA registration under FIFRA with substantiated kill claims against specified pathogens, creating regulatory moats for qualified suppliers.
- Automotive:Vehicle wash formulations and interior cleaners balance foaming performance with paint and polymer compatibility, with OEM specification approvals unlocking aftermarket positioning.
Household channels dominate volume throughput; healthcare qualification requirements sustain the steepest margin premiums.
Grade:
Certification infrastructure separates commodity producers from premium-positioned suppliers, with pharmaceutical-grade facilities requiring seven-figure validation investments.
- Pharmaceutical Grade:Parenteral and topical drug formulations demand USP-NF and EP monograph compliance with ICH Q3D elemental impurity testing, restricting supply to dedicated GMP facilities. China's NMPA alignment with ICH standards is accelerating domestic qualification of surfactant excipients.
- Cosmetic Grade:Personal care applications require microbiome compatibility and preservative system stability testing, with Korean and Japanese brands driving mild amphoteric surfactant specifications.
- Food Grade:Processing equipment cleaners and indirect food contact applications fall under FDA 21 CFR and EFSA safety evaluations, with kosher and halal certifications opening regional market access.
- Industrial Grade:Uncompromised cost efficiency for non-contact applications, with biodegradability mandates in the EU Green Deal forcing feedstock transitions even at this tier.
Industrial grade commands the greatest production volume; pharmaceutical grade carries the most restrictive entry barriers and pricing power.
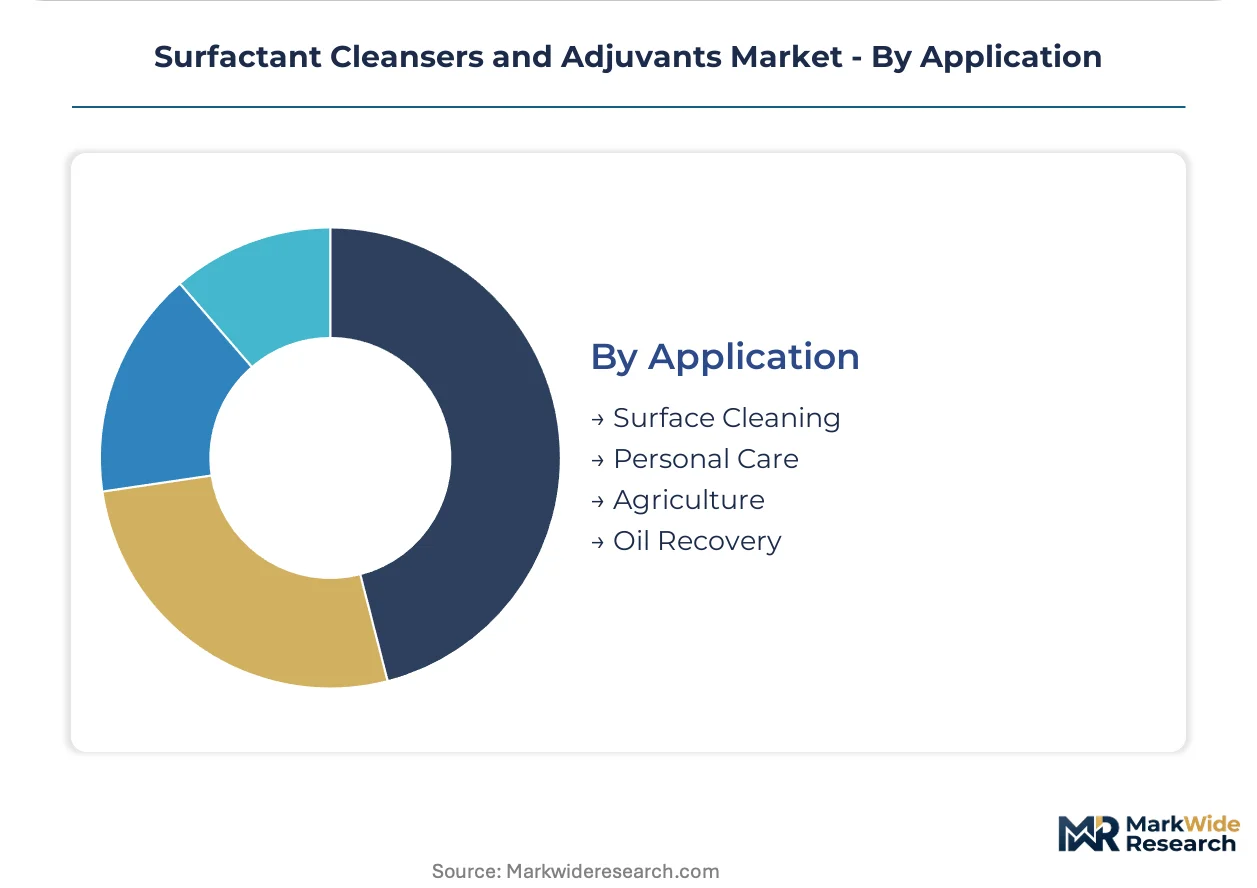
Application:
Performance specifications and regulatory exposure diverge, with oil recovery applications requiring reservoir-specific formulation while personal care demands consumer-perceptible sensory attributes.
- Surface Cleaning:Hard floor, kitchen, and bathroom formulations balance grease cutting with surface compatibility, with concentrate formats gaining share in commercial channels seeking to reduce packaging waste.
- Personal Care:Shampoo, body wash, and facial cleanser applications prioritize mildness profiles and foam aesthetics, with microbiome-preserving formulations capturing premium positioning in dermocosmetic markets.
- Agriculture:Pesticide adjuvants and tank-mix surfactants require EPA FIFRA registration with crop-specific tolerance data, extending product launch timelines compared to unregulated industrial applications.
- Oil Recovery:Surfactant flooding for enhanced oil recovery deploys specialized alkylbenzene sulfonates and petroleum sulfonates in mature basins across the Middle East and North America, with reservoir chemistry dictating customized formulation.
Surface cleaning anchors volume consumption; oil recovery applications are climbing the fastest as enhanced recovery operations expand in depleted reservoirs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates pharmaceutical-grade surfactant demand as domestic manufacturers scale output for regional supply. Germany anchors European formulation expertise under REACH substance authorization pressure. The United States maintains sulfonation infrastructure concentration along the Gulf Coast.
China
NMPA alignment with ICH Q3D guidelines accelerates domestic excipient qualification for generic injectables. Domestic manufacturers in Jiangsu and Zhejiang provinces scale pharmaceutical-grade output previously served by imports. Shanghai-based formulators expand microbiome-compatible cosmetic surfactant capabilities for Korean and Japanese brand supply.
Germany
EU Green Deal biodegradability mandates force feedstock transitions in household detergent formulations. ECHA REACH authorization restricts ethoxylated alkylphenols from consumer applications by 2025. BASF SE leverages integrated petrochemical feedstock positions at Ludwigshafen to secure cost advantages across anionic and nonionic lines.
United States
EPA FIFRA registration requirements govern agricultural adjuvant formulations with extended product launch timelines. Gulf Coast sulfonation infrastructure clusters create hurricane exposure risks for anionic surfactant supply security. Stepan Company anchors North American supply through bio-based feedstock investments and sulfonation capacity.
Japan
Mild amphoteric surfactants for skin microbiome preservation capture premium positioning in dermocosmetic markets. METI oversight of chemical substance manufacturing aligns with OECD 301B biodegradability protocols. Osaka-based personal care compounders deepen direct technical partnerships with fermentation specialists for biosurfactant sourcing.
Brazil
ANVISA data requirements for agricultural adjuvants extend registration cycles and fragment regulatory affairs staffing. Agricultural residue-derived alkyl polyglucosides from sugarcane bagasse offer carbon-negative certification potential. São Paulo state surfactant distributors deploy AI-driven formulation platforms bypassing traditional distributor tiers.
Surfactant Cleansers and Adjuvants Market Competitive Landscape
German producers anchor the integrated petrochemical tier; US specialists hold sulfonation infrastructure positions; Japanese and Korean players capture microbiome-compatible cosmetic premiums. The vendor base organizes around three strategic archetypes: feedstock-integrated multinationals, specialty silicone surfactant innovators, and bio-based fermentation platforms. Competitive moves concentrate on backward integration into agricultural feedstocks and capacity expansion in pharmaceutical-grade GMP facilities.
Within the integrated multinational tier, BASF SE and Evonik Industries exemplify divergent positioning strategies. BASF SE occupies the feedstock-integrated archetype through petrochemical backbone control. Evonik Industries represents specialty silicone surfactant differentiation for high-margin cosmetic applications. Stepan Company anchors the North American bio-based transition through dedicated sulfonation infrastructure investments.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries |
| Stepan Company |
| Akzo Nobel |
| Clariant |
| Croda International |
| Kao Corporation |
| Solvay |
| Huntsman |
| Others |
Value Network & Pricing Analysis
Palm kernel oil and coconut oil feedstock costs transmit directly from Southeast Asian plantation economics through to surfactant active matter pricing, with biofuel policy arbitrage in Indonesia and Malaysia amplifying volatility that compresses margin pools for natural surfactant producers serving European household detergent channels.
Pricing Analysis
Volume throughput concentrates in industrial-grade anionic surfactants where contract-based long-term offtake agreements anchor pricing stability, while pharmaceutical-grade certifications command premium-mid-economy pricing differentiation driven by USP-NF compliance burdens and elemental impurity testing capabilities. Cost compression in cosmetic-grade amphoteric surfactants is intensifying because Korean and Japanese dermocosmetic brands are consolidating supplier panels around microbiome-compatible specifications. Household detergent manufacturers exhibit the sharpest price sensitivity, whereas parenteral drug developers prioritize supply security over unit cost.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Houston orchestrate hub-and-spoke patterns for liquid surfactant concentrates, with bulk tanker movements feeding compounding facilities across downstream personal care and industrial channels. Manufacturing gravity centers on Germany, China, and the United States, with sulfonation infrastructure drawing from petroleum and natural gas feedstocks while bio-based production rests on palm kernel oil, coconut oil, and Brazilian sugarcane bagasse. Single-source vulnerability concentrates in Gulf Coast sulfonation clusters exposed to hurricane disruption. Distribution runs through chemical distributor networks with formulation technical service layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic synthesis routes and biosurfactant fermentation platforms are displacing conventional petrochemical processes, with European household care formulators piloting commercial-scale adoption that compresses the cost premium versus ethoxylation.
For Market Incumbents: Deploy backward integration into agricultural feedstocks to secure cost-advantaged supply of alkyl polyglucosides from Brazilian sugarcane bagasse and Southeast Asian palm derivatives. Anchor sulfonation capacity additions in hurricane-resilient geographies outside the US Gulf Coast to mitigate supply security exposure. Certification investment in ICH Q3D-compliant GMP facilities defends pharmaceutical-grade positioning against emerging Chinese domestic suppliers. For New Entrants and Emerging Players: Biosurfactant fermentation expertise offers entry into microbiome-compatible cosmetic formulations where Korean and Japanese dermocosmetic brands pay formulation premiums. Direct-to-compounder digital channels bypass traditional distributor tiers in Indonesia and Vietnam, capturing margin and technical relationship ownership with mid-scale personal care manufacturers. White space concentrates in pharmaceutical-grade excipients for generic injectables as China's NMPA accelerates domestic qualification. For Investors and Strategic Acquirers: NMPA alignment with ICH Q3D guidelines is the leading indicator that Chinese surfactant excipient suppliers will capture share from import-dependent generic injectable formulators. Long-term viability favors fermentation-based bio-surfactant platforms with carbon-negative certification potential over legacy petrochemical sulfonation assets. Target acquisition profiles center on specialty silicone surfactant innovators with cosmetic formulation partnerships and GMP-certified pharmaceutical-grade facilities with elemental impurity testing capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agricultural Feedstocks | Captive supply of Brazilian sugarcane bagasse and palm kernel oil secures cost advantages for bio-based alkyl polyglucoside production. |
| Pharmaceutical-Grade GMP Facility Expansion | USP-NF and ICH Q3D compliance unlocks parenteral excipient qualification for generic injectable supply to China's NMPA-regulated market. |
| Enzymatic Synthesis Platform Deployment | Continuous processing reactor designs reduce solvent use and energy intensity for sugar-based surfactant routes serving EU Green Deal mandates. |
| Direct-to-Compounder Digital Channel Launch | AI-driven formulation platforms bypass distributor tiers to capture margin and technical relationships with Southeast Asian personal care compounders. |
| Hurricane-Resilient Sulfonation Capacity Addition | Geographic diversification outside US Gulf Coast clusters mitigates supply security risks for anionic surfactant infrastructure. |
Research Methodology
Trade databases, chemical industry association reports, and regulatory filings formed the secondary backbone, cross-referenced with primary interviews involving surfactant plant managers, procurement leads at personal care OEMs, pharmaceutical formulation scientists, and agricultural adjuvant regulatory affairs directors. Bottom-up modeling of active matter volumes by grade tier and end-use application converged with top-down macroeconomic validation across the analysis window.
Historical trendline analysis of sulfonation capacity utilization, feedstock price indices, and pharmaceutical excipient import patterns informed the projection framework. Segmentation dimensions spanned product format, industry vertical, certification grade, and regional production hub. CAGRs were derived from elasticity-adjusted demand modeling with inputs from REACH substance authorization timelines and EPA FIFRA registration cycle durations.
Forecast precision tightens around the base case; tail outcomes carry wider variance under feedstock price volatility, regulatory divergence between EU biodegradability mandates and US state-level PFAS restrictions, and hurricane disruption of Gulf Coast infrastructure. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Isopropyl Myristate Market
Surfactants
Dodecanol Market
Surfactants
Global Sodium Lauryl Ether Sulfate [SLES] Market
Surfactants
Waxing Sponge Market
Surfactants
Amino Acid Surfactants Market
Surfactants
Micellar Water Market
Surfactants
Amphoteric Emulsifier Market
Surfactants
TEA Esterquats Market
Surfactants
Glycol Monostearate Market
Surfactants
Procream Market
Surfactants
Global Barium Petroleum Sulfonate Market
Surfactants
Polyoxyethylene Sorbitan Tristearate Market
Surfactants
Sodium Methyl Cocoyl Taurate Market
Surfactants
Benzyl Trimethyl Ammonium Chloride Market
Surfactants
Superwetting Surfactants Market
Surfactants
Natural Surfactants Market