
 Aerospace High-Performance Alloys Market | 2026-2036
Aerospace High-Performance Alloys Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace High-Performance Alloys Market Analysis
Commercial aviation is shifting toward higher-thrust, fuel-efficient propulsion architectures, pulling demand toward heat-resistant nickel superalloys in turbine sections. ATI leverages integrated titanium sponge-to-mill capabilities to anchor North American aerospace supply chains. VSMPO-AVISMA dominates Russian titanium output and sustains long-term contracts with Airbus and Boeing legacy programs. Carpenter Technology specializes in premium vacuum-melted alloys and differentiates through proprietary melt technologies for jet engine rotating components.
Aerospace high-performance alloys are metallic systems engineered to retain mechanical integrity above 540°C, with nickel-based superalloys typically containing 50-70% nickel plus chromium, cobalt, and refractory element additions produced via vacuum induction melting and vacuum arc remelting to prevent oxide inclusions that initiate fatigue cracking in rotating engine hardware. Titanium alloys lead structural airframe applications due to their strength-to-density ratio and corrosion immunity, while nickel alloys command the highest value pools in hot-section engine components where thermal barrier coating compatibility determines service life. Additive manufacturing represents the fastest-growing process segment as OEMs qualify laser powder bed fusion for complex bracket geometries that subtractive methods cannot economically produce.
FAA Part 25 airworthiness standards and EASA CS-25 certification requirements mandate extensive mechanical property datasets for alloy qualification, extending development timelines and elevating barriers for new material entrants. The EU Green Deal's sustainable aviation fuel trajectory and associated emission benchmarks are pressuring alloy producers to reduce melt shop energy intensity and demonstrate recycled content traceability. Stakeholders must monitor evolving powder specification standards from ASTM F3055 and ISO/ASTM 52900 as additive processes scale from prototyping to flight-certified production.
Market Dynamics
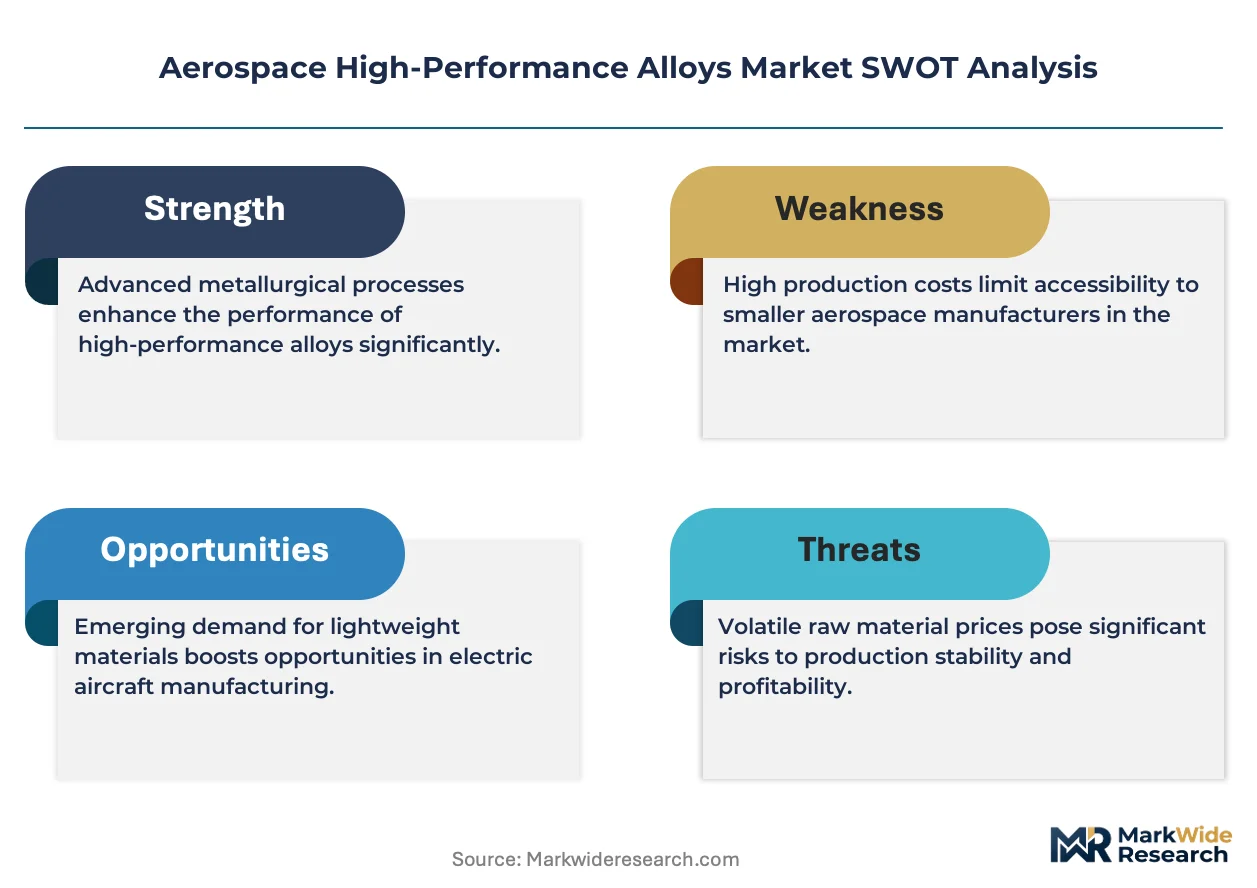
Commercial aviation OEMs are consolidating supplier bases for next-generation narrow-body platforms, compressing qualification timelines while FAA and EASA tighten material certification pathways for additive-manufactured flight-critical components. This tension between demand acceleration and regulatory rigor defines current market structure.
Growth Catalysts
- LEAP-1A engine ramp:Airbus A320neo production schedules pull demand for Rene 41 and Inconel 718 superalloys in high-pressure turbine sections.
- EU Green Deal SAF mandates:Emission benchmarks pressure alloy producers to reduce melt shop energy intensity and demonstrate recycled content traceability.
- Titanium sponge regionalization:US defense primes are anchoring domestic titanium procurement away from legacy import dependencies.
Market Restraints
- Sponge price volatility:Titanium sponge feedstock costs swing with energy-intensive Kroll process economics and chloride supply constraints.
- Russian supply concentration:VSMPO-AVISMA's dominance in titanium output creates geopolitical exposure for Airbus and Boeing legacy programs.
- Dual-melt capacity scarcity:Vacuum induction melting plus vacuum arc remelting infrastructure limits qualified superalloy output expansion.
Strategic Opportunities
- India defense localization:Hindustan Aeronautics and DRDO procurement shifts create captive demand for indigenous titanium alloy development.
- Laser powder bed fusion qualification:ASTM F3055 and ISO/ASTM 52900 standardization opens flight-certified production for complex bracket geometries.
- Japan METI critical materials strategy:National stockpiling incentives and recycling infrastructure investments reduce import dependency for nickel and cobalt.
Industry Challenges
- Metallurgical talent scarcity:Vacuum melt shop operators and powder metallurgy specialists retire faster than apprenticeship pipelines refill.
- Extended FAA Part 25 certification timelines:Mechanical property datasets for new alloy compositions require 18-36 month qualification cycles before airworthiness approval.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace High-Performance Alloys Market |
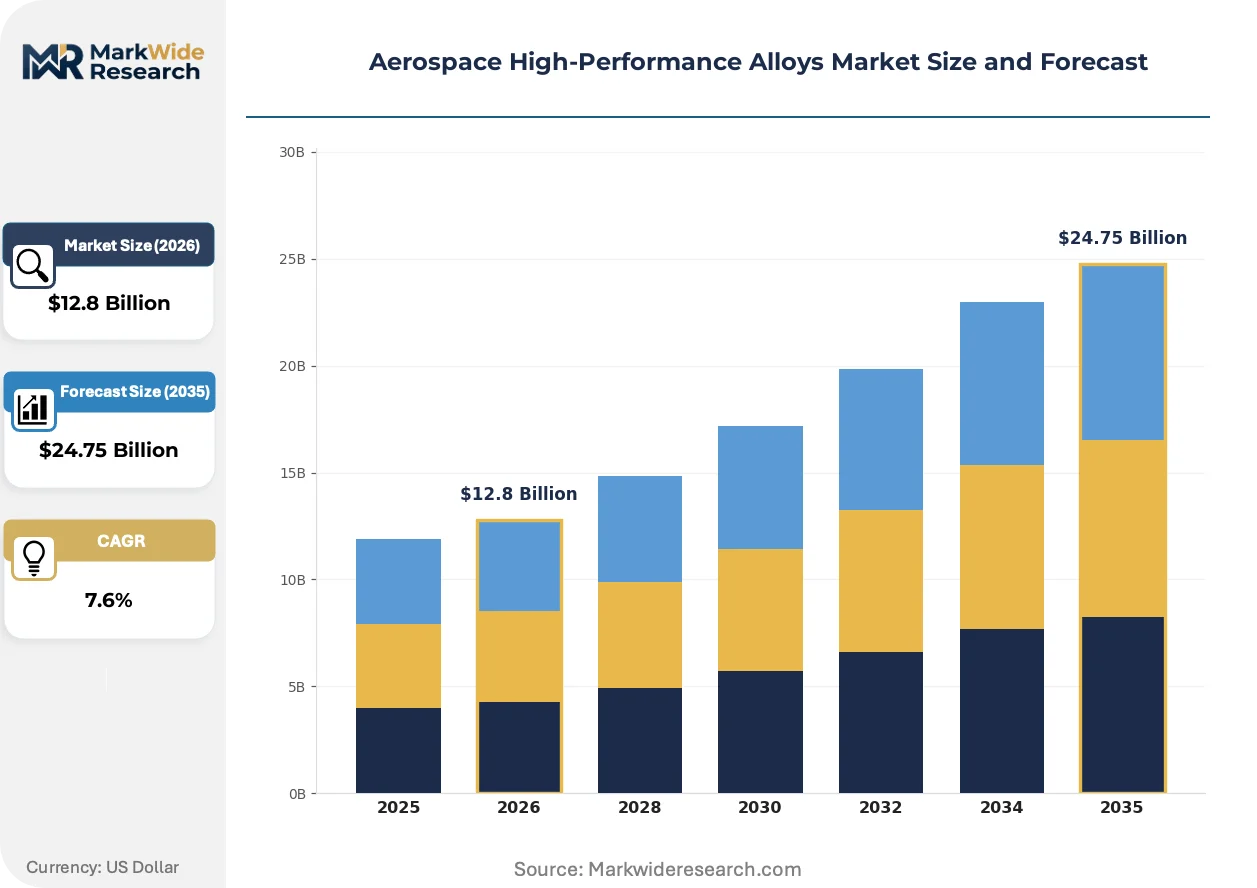
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $24.75 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum Alloys, Titanium Alloys, Nickel Alloys, Steel Alloys Manufacturing Process: Additive Manufacturing, Casting, Forging, Machining Application: Airframe, Engine Components, Landing Gear, Structural Parts End User: OEMs, Aftermarket Providers, Airlines, Defense Contractors |
| Companies Covered | Alcoa Corporation, ATI, Precision Castparts Corp., Carpenter Technology Corporation, VSMPO-AVISMA Corporation, Aperam, Haynes International, Arconic, Special Metals Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace High-Performance Alloys Market Emerging Trajectories
Additive manufacturing is compressing traditional forging and casting supply chains as OEMs qualify laser-based processes for flight-critical titanium and nickel components. Material qualification frameworks are racing to keep pace with process innovation.
Hot isostatic pressing of titanium powder metallurgy is consolidating supply chains for structural airframe brackets and landing gear components. Boeing and Airbus procurement teams are qualifying HIP near-net-shape parts for A350 and 787 programs. The technology is consolidating tier-2 and tier-3 forging capacity into integrated powder-to-part operations.
EASA CS-25 certification amendments for additive-manufactured rotating components are tightening non-destructive testing requirements and traceability standards. European engine OEMs face extended qualification timelines for laser powder bed fusion turbine blades. The regulations are forcing alloy producers to invest in in-process monitoring and digital twin validation systems.
Long-term throughput agreements are displacing spot market purchasing for titanium mill products. Airbus and Boeing supply chain teams are locking five-to-seven year contracts with ATI and VSMPO-AVISMA to secure heat-treated plate and billet capacity. The shift is most visible in US and French procurement offices managing A320neo and 737 MAX output ramps.
Aerospace High-Performance Alloys Market Segmentation
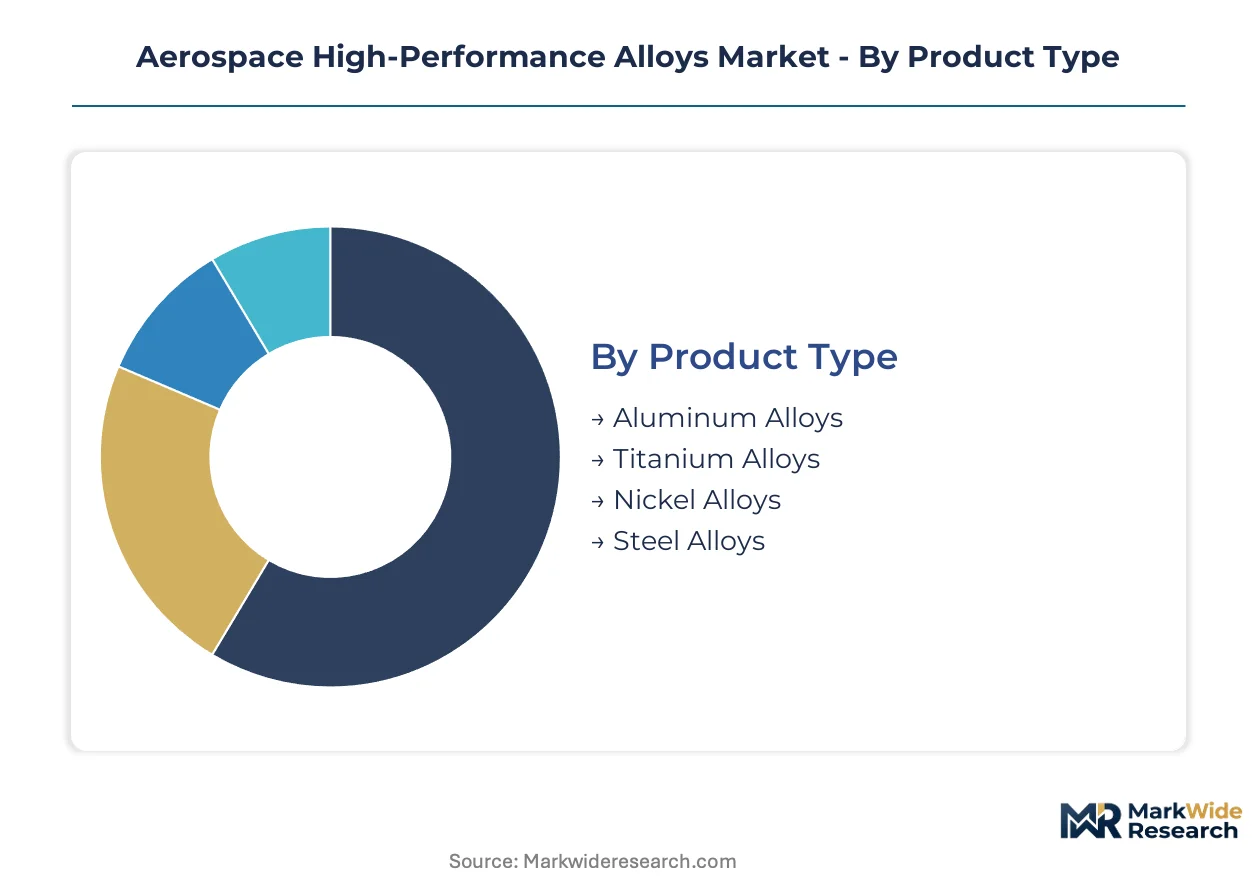
Alloy procurement decisions in aerospace track directly to thermal operating envelopes and airworthiness certification pathways. Each segmentation dimension reveals distinct margin structures and qualification barriers that shape supplier competitive position.
Product Type:
Thermal performance requirements drive alloy selection more than raw material cost, with engine OEMs paying premiums for creep resistance above 650°C.
- Nickel Alloys:Vacuum-melted superalloys containing 50-70% nickel with chromium and refractory element additions retain mechanical integrity in turbine sections above 540°C. Demand concentrates in high-pressure compressor and turbine blade castings for next-generation narrow-body propulsion systems, where FAA Part 25 fatigue datasets extend qualification timelines. Dual-melt capacity scarcity limits qualified output expansion.
- Titanium Alloys:Alpha-beta and near-alpha titanium grades deliver strength-to-density ratios superior to steel at half the weight, with corrosion immunity eliminating protective coatings. Boeing and Airbus procurement teams in the United States and France anchor long-term throughput agreements for heat-treated plate and billet feeding A320neo and 737 MAX airframe programs. Sponge price volatility from Kroll process energy intensity creates margin pressure.
- Aluminum Alloys:2XXX and 7XXX series aluminum-lithium formulations serve lower-temperature structural applications where density reduction outweighs thermal limits.
- Steel Alloys:Ultra-high-strength maraging and precipitation-hardened grades command landing gear and fastener applications requiring yield strengths above 1,500 MPa.
Nickel alloys lead on scale through engine content value concentration; titanium alloys lead on momentum through airframe weight reduction mandates.
Manufacturing Process:
Process selection determines geometric complexity limits and non-destructive testing burden, with flight-critical rotating components demanding the most stringent metallurgical qualification.
- Forging:Closed-die and isothermal forging of titanium and nickel alloys produces grain-aligned microstructures with superior fatigue resistance in rotating engine hardware. ATI and legacy forging houses in the United States maintain qualified press capacity for 10,000-ton titanium closed-die operations serving Boeing and defense prime contractor demand. Long lead times for die qualification compress effective capacity.
- Additive Manufacturing:Laser powder bed fusion and electron beam melting enable topology-optimized bracket geometries impossible through subtractive methods, with ASTM F3055 and ISO/ASTM 52900 standardization enabling flight-certified production. EASA CS-25 amendments for rotating components are tightening in-process monitoring requirements and extending qualification timelines for European engine OEMs. Powder specification traceability represents the primary barrier to scale.
- Casting:Directional solidification and single-crystal casting of nickel superalloys produces turbine blades with aligned grain structures for creep resistance.
- Machining:Five-axis CNC finishing of forgings and castings delivers final tolerances for bearing surfaces and attachment features.
Forging dominates current revenue through engine rotating component demand; additive manufacturing gains share fastest through geometric complexity premiums.
Application:
Operating temperature divides alloy selection, with hot-section engine components commanding value multiples over ambient-temperature structural applications.
- Engine Components:High-pressure turbine blades, combustor liners, and compressor disks require nickel superalloys with thermal barrier coating compatibility determining service life. LEAP-1A engine ramp schedules at Airbus A320neo production lines in France pull demand for Rene 41 and Inconel 718 in high-pressure turbine sections. Dual-melt infrastructure constraints limit output expansion.
- Airframe:Fuselage barrel sections, wing boxes, and empennage structures employ titanium alloys for strength-to-density optimization and aluminum-lithium for cost-sensitive secondary structures. Hot isostatic pressing of titanium powder metallurgy is consolidating tier-2 and tier-3 forging capacity into integrated powder-to-part operations for Boeing 787 and Airbus A350 programs. Qualification timelines for HIP near-net-shape parts are compressing.
- Landing Gear:Ultra-high-strength steel and titanium alloys withstand impact loads and fatigue cycles during takeoff and landing.
- Structural Parts:Floor beams, seat tracks, and cargo handling systems utilize aluminum and lower-grade titanium formulations.
Engine components lead on scale through unit content value; airframe applications lead on momentum through additive manufacturing qualification.
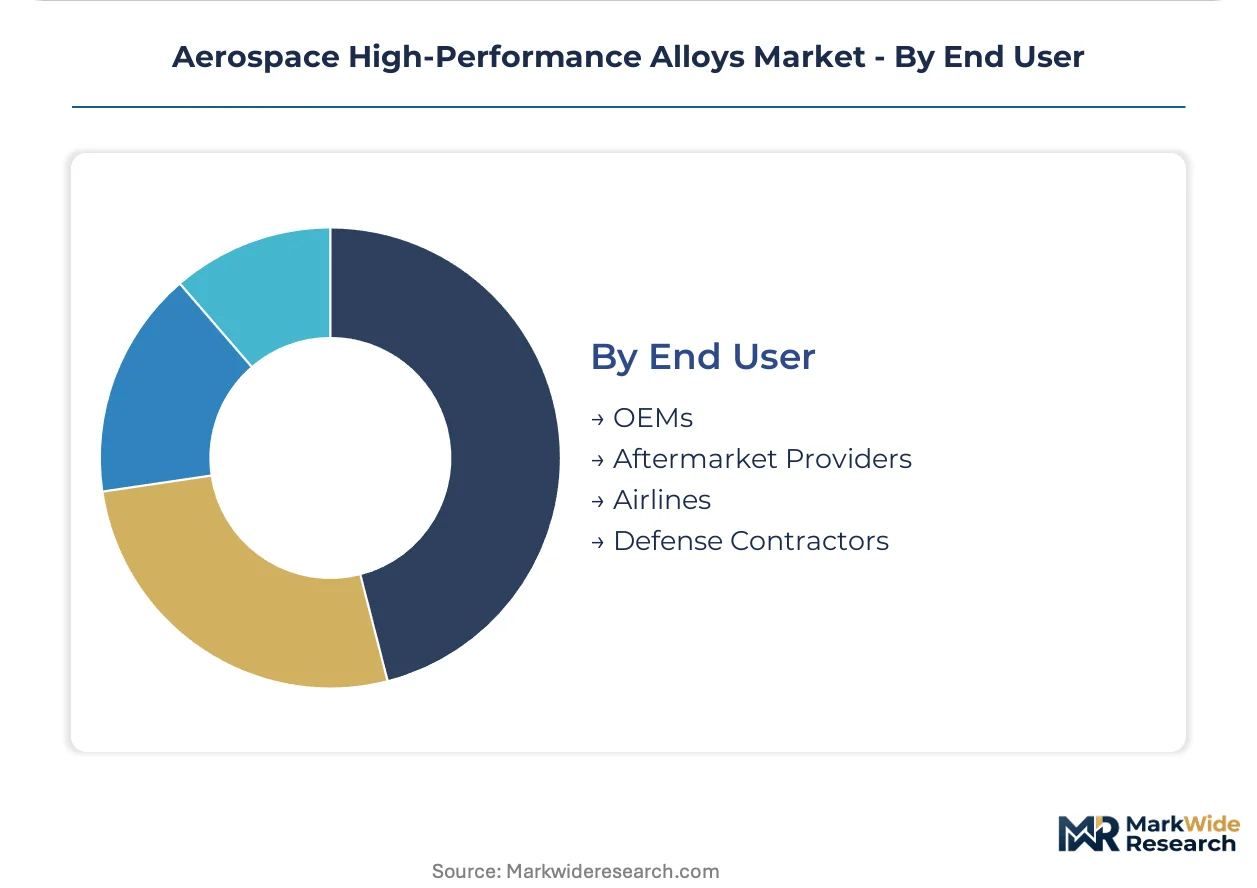
End User:
Procurement authority and qualification responsibility split between airframe and engine OEMs, with aftermarket providers operating under reverse-engineering constraints.
- OEMs:Boeing, Airbus, and engine manufacturers Safran, Rolls-Royce, and Pratt & Whitney specify alloy grades and approve supplier melt shops through source-controlled procurement. FAA and EASA certification standards mandate mechanical property datasets extending 18-36 months for new alloy compositions, elevating barriers for material entrants. Long-term throughput agreements are displacing spot market purchasing.
- Defense Contractors:US defense primes anchor domestic titanium procurement away from legacy import dependencies, with national security considerations overriding cost optimization. Lockheed Martin and Northrop Grumman supply chain teams in the United States are qualifying alternative sponge sources to reduce VSMPO-AVISMA concentration risk. ITAR and DFARS compliance adds qualification layers.
- Aftermarket Providers:MRO operators and parts distributors serve replacement demand under DER and DOA approvals, with alloy traceability requirements tightening.
- Airlines:Direct procurement remains limited to consumables and non-structural items, with fleet operators influencing OEM alloy selection through total cost of ownership feedback.
OEMs lead on scale through design authority concentration; defense contractors lead on momentum through supply chain regionalization mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping alloy production geography as energy-intensive melt shops migrate toward jurisdictions with lower carbon compliance costs and subsidized power tariffs. Producers are relocating vacuum induction capacity to exploit gaps between EU carbon border adjustments and US Inflation Reduction Act clean energy credits.
United States
Boeing's supply base and defense prime contractors anchor titanium and nickel alloy procurement through long-term throughput agreements. FAA Part 25 airworthiness standards mandate extensive mechanical property datasets that extend qualification timelines for new material entrants. The Pacific Northwest and Midwest industrial corridors concentrate ATI's integrated sponge-to-mill operations and Carpenter Technology's vacuum-melted specialty alloys.
France
Airbus A320neo production schedules in Toulouse pull demand for Rene 41 and Inconel 718 superalloys in high-pressure turbine sections. EASA CS-25 certification amendments for additive-manufactured components are tightening non-destructive testing requirements. The EU Green Deal's sustainable aviation fuel trajectory pressures alloy producers in the Occitanie and Auvergne-Rhône-Alpes regions to demonstrate recycled content traceability.
Japan
Domestic engine OEMs and airframe subcontractors sustain demand for premium vacuum-melted alloys in jet engine rotating components. METI's critical materials strategy funds national stockpiling incentives and recycling infrastructure investments to reduce import dependency for nickel and cobalt. The Chubu and Kansai industrial belts concentrate precision forging capacity serving regional aerospace supply chains.
India
Hindustan Aeronautics and DRDO procurement shifts are creating captive demand for indigenous titanium alloy development in defense applications. BIS standards for aerospace materials are converging with international qualification frameworks to accelerate domestic supplier certification. The Karnataka and Maharashtra aerospace clusters are absorbing technology transfer agreements for vacuum melt shop establishment.
United Kingdom
Rolls-Royce's Derby engineering center specifies alloy grades and approves supplier melt shops through source-controlled procurement for narrow-body and wide-body engine programs. The country's national aerospace regulator enforces EASA-aligned certification standards with additional domestic airworthiness requirements. The Midlands and South West England manufacturing corridors retain specialized forging and casting capacity for legacy and next-generation propulsion systems.
Aerospace High-Performance Alloys Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated titanium producers commanding premium positions in airframe supply chains while vacuum-melted alloy houses dominate engine rotating component qualifications. The vendor base organizes around three strategic archetypes: integrated sponge-to-mill operators, specialty vacuum-melted alloy houses, and precision forging specialists. M&A activity concentrates on securing dual-melt capacity scarcity, while strategic partnerships target additive manufacturing qualification pathways.
Among North American integrated producers, ATI and Carpenter Technology exemplify the vertically integrated archetype. ATI occupies a position anchored in domestic titanium sponge supply chains serving Boeing and defense prime contractor demand. Carpenter Technology sits within the premium vacuum-melted tier, representing specialized melt technology capabilities for fatigue-critical rotating hardware. Precision Castparts Corp. anchors the precision-forging segment.
| Leading Market Players |
|---|
| Alcoa Corporation |
| ATI |
| Precision Castparts Corp. |
| Carpenter Technology Corporation |
| VSMPO-AVISMA Corporation |
| Aperam |
| Haynes International |
| Arconic |
| Special Metals Corporation |
| Others |
Supply Flow & Price Mechanics
Additive manufacturing qualification is compressing traditional forging economics while concentrating procurement authority among OEMs with certified laser powder bed fusion supply chains. This process shift simultaneously elevates powder specification premiums and locks tier-2 suppliers into long-term throughput agreements with ATI and VSMPO-AVISMA.
Pricing Analysis
Direct-to-OEM contracting eliminates distributor margins for flight-critical nickel superalloys, with pricing stratifying across FAA-certified premium grades, EASA-equivalent standard tiers, and uncertified economy sponge feedstock. Cost compression in titanium mill products intensifies as Boeing and Airbus consolidate five-to-seven year billet agreements. Defense contractors exhibit lowest price sensitivity due to ITAR compliance premiums, while aftermarket MRO providers face margin pressure from traceability documentation requirements.
Supply Chain Analysis
FAA Part 25 and EASA CS-25 certification gating restricts qualified vacuum melt shop capacity to the United States, France, and Japan, creating artificial scarcity in dual-melt nickel superalloy output. The supply chain draws from Russian titanium sponge, Australian rutile, and Canadian cobalt concentrate, exposing Airbus and Boeing programs to single-source vulnerability from VSMPO-AVISMA concentration. Distribution runs through source-controlled OEM procurement offices rather than merchant distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Energy cost arbitrage between EU carbon border adjustments and US Inflation Reduction Act clean energy credits is repositioning vacuum induction capacity toward jurisdictions with subsidized power tariffs. Alloy producers exploit this geographic spread to defend margin structures.
For Market Incumbents: Cement dual-melt capacity scarcity through apprenticeship pipeline investments addressing retiring vacuum melt shop operators. Lock in five-to-seven year throughput agreements with Boeing and Airbus before alternative sponge sources achieve full FAA qualification. Threat substitution from additive manufacturing qualification delays demands preemptive powder metallurgy certification.
For New Entrants and Emerging Players: The premium-to-economy price gap in titanium sponge feedstock offers entry points for chloride-route producers with Kroll process cost advantages. Target India's defense localization mandates where Hindustan Aeronautics procurement shifts create captive demand for indigenous alloy development. Pursue technology transfer partnerships with established vacuum melt shops rather than greenfield certification.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialty vacuum-melted alloy houses with proprietary melt technologies for fatigue-critical rotating hardware. Long-term viability hinges on additive manufacturing qualification timelines compressing from prototyping to flight-certified production. Watch ASTM F3055 and ISO/ASTM 52900 standardization progress as inflection signal for powder specification traceability investments.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Titanium Sponge | ATI's captive Kroll process capacity insulates Boeing supply chains from Russian import volatility. |
| Dual-Melt Capacity Expansion | Vacuum induction plus vacuum arc remelting infrastructure scarcity limits qualified superalloy output expansion for LEAP-1A engine ramps. |
| Additive Manufacturing Qualification | Laser powder bed fusion certification under EASA CS-25 amendments opens flight-critical bracket production for topology-optimized geometries. |
| Defense Procurement Regionalization | US ITAR compliance and DFARS sourcing mandates redirect titanium procurement away from legacy VSMPO-AVISMA dependencies. |
| Recycling Infrastructure Investment | EU Green Deal emission benchmarks pressure melt shop energy intensity reduction through demonstrated recycled content traceability. |
Methodological Framework
Multiple input streams — primary interviews with vacuum melt shop operators, OEM procurement directors, and powder metallurgy specialists; secondary validation through FAA airworthiness directives, EASA certification amendments, and customs trade data; plus SEC filings from ATI and Carpenter Technology — were reconciled through bottom-up alloy demand modeling and top-down aerospace production forecasts.
Historical production volumes from Boeing and Airbus delivery schedules were cross-referenced against panel input from defense prime contractor supply chain executives. The analytical framework segments by alloy chemistry, manufacturing process qualification tier, thermal operating envelope, and end-user procurement authority across the projection horizon. CAGRs derive from engine content value concentration in narrow-body platforms and airframe weight reduction mandates.
Caveats apply where FAA Part 25 certification timeline extensions or EASA additive manufacturing standardization delays could materially shift the outlook. Forecasts reflect assumptions regarding LEAP-1A production ramp stability and Russian titanium supply continuity. A model refresh is warranted upon material change in dual-melt capacity commissioning or ASTM F3055 qualification thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Commercial Aircraft Honeycomb Core Market
Aerospace and Aircraft Materials
Global Aerospace Insulation Market
Aerospace and Aircraft Materials
Global Aerospace Adhesives Market
Aerospace and Aircraft Materials
Aerospace and Defense Composites Market
Aerospace and Aircraft Materials
Defense Aircraft Material Market
Aerospace and Aircraft Materials
Aerospace Carbon Fiber Market
Aerospace and Aircraft Materials
Aerospace Fasteners Market
Aerospace and Aircraft Materials
Global Aerospace Titanium Machining Market
Aerospace and Aircraft Materials
Global AFP/ATL Machines Market
Aerospace and Aircraft Materials
Electromagnetic and Radio Frequency Interference Coating Market
Aerospace and Aircraft Materials
Space Electronics Market
Aerospace and Aircraft Materials
Aerogel Market
Aerospace and Aircraft Materials
Commercial Aircraft Materials Market
Aerospace and Aircraft Materials
Commercial Aerospace Carbon Brakes Market
Aerospace and Aircraft Materials
Aerospace Radome Market
Aerospace and Aircraft Materials
Global Military Aerospace Coatings Market