
 Piezoelectric Devices Market | 2026-2036
Piezoelectric Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Piezoelectric Devices Market Intelligence
Industrial-grade precision specifications for piezoelectric actuators is collapsing the gap between laboratory performance and factory-floor reliability. CeramTec GmbH leverages captive ceramic formulation capabilities to dominate medical and industrial actuator supply. TDK Corporation anchors high-volume sensor production for consumer electronics and automotive customers across Asian manufacturing hubs. Physik Instrumente (PI) specializes in nanopositioning systems where sub-nanometer resolution commands sustained premium positioning.
Piezoelectric devices convert mechanical stress into electrical charge and vice versa through crystalline materials such as lead zirconate titanate or barium titanate, typically operating at resonant frequencies from kilohertz to megahertz ranges for sensing, actuation, or energy harvesting functions. Actuators and sensors together constitute the core revenue architecture, with actuators capturing the deepest margin pools in semiconductor lithography and life-science instrumentation while sensors extend volume through automotive knock-detection and industrial vibration monitoring deployments. Multi-layer ceramic technology is displacing traditional single-layer designs in miniature haptic feedback and inkjet printhead applications where stacked electrode configurations enable higher displacement at reduced drive voltages.
EPA chemical management protocols and REACH substance restrictions are forcing reformulation roadmaps away from lead-based piezoceramics toward potassium sodium niobate and bismuth-based alternatives. FDA device classification requirements for ultrasonic surgical and diagnostic equipment shape validation timelines and design control documentation burdens for healthcare-facing suppliers. ISO 13485 quality system mandates and EU MDR technical file requirements add parallel compliance layers that favor suppliers with established medical certification infrastructure. Stakeholders must monitor lead-free material qualification progress against performance parity benchmarks to time capacity transitions and avoid stranded inventory positions.
Market Dynamics
REACH substance restrictions and EPA chemical management protocols are forcing simultaneous material reformulation across European and North American supply chains, compressing lead-based piezoceramic conversion timelines while medical imaging OEMs accelerate precision actuator procurement.
Growth Catalysts
- Lead-free piezoceramic mandates:ECHA REACH restrictions on lead substances and evolving EPA protocols are creating regulated demand pull for potassium sodium niobate and bismuth-based formulations.
- Surgical robotics expansion:FDA device classification pathways for ultrasonic surgical equipment are validating precision actuator specifications in life-science instrumentation.
- Stuttgart-Munich automation corridor:Sensor-integrated manufacturing clusters serving German automotive OEMs are concentrating demand for industrial vibration monitoring systems.
Market Restraints
- Raw material supply concentration:Rare earth element processing for high-purity piezoceramic precursors concentrates in limited geographic zones, exposing formulators to input volatility.
- Performance parity gaps:Lead-free alternatives exhibit reduced electromechanical coupling coefficients versus legacy lead zirconate titanate, constraining substitution in high-precision applications.
- Certification timeline friction:EU MDR technical file requirements and ISO 13485 quality system mandates extend validation cycles for healthcare-facing suppliers.
Strategic Opportunities
- Energy harvesting integration:Convergence of piezoelectric thin-films with IoT sensor networks is opening deployment in structural health monitoring for civil infrastructure.
- Semiconductor lithography actuation:Sub-nanometer positioning requirements in EUV wafer stages represent underpenetrated premium segments outside incumbent supplier relationships.
- India PLI scheme alignment:Electronics manufacturing incentives under the country's production-linked initiative are attracting component localization for consumer sensor applications.
Industry Challenges
- Multi-standard compliance architecture:Simultaneous FDA, EPA, and EU MDR documentation burdens strain quality assurance bandwidth at mid-scale suppliers.
- Specialized ceramics talent scarcity:Formulation chemists with piezoceramic sintering expertise command premium compensation, constraining R&D expansion at emerging competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Piezoelectric Devices Market |
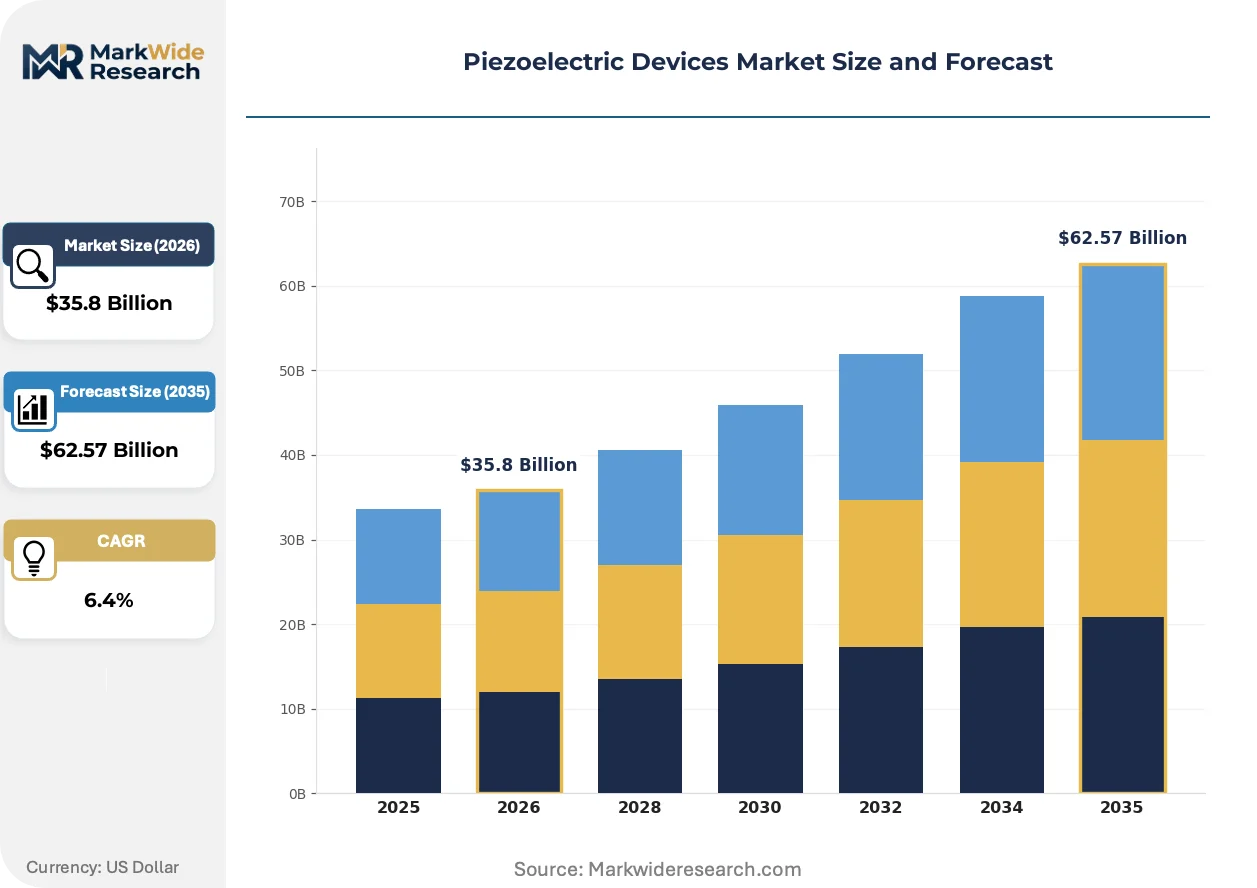
| Market Size in 2026 | $35.8 Billion |
| Market Size in 2035 | $62.57 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Actuators, Sensors, Harvesters, Transducers Technology: Analog, Digital, Multi-layer, Composite Application: Automotive, Aerospace, Healthcare, Consumer Electronics End User: Manufacturers, Research Institutions, OEMs, Military |
| Companies Covered | CeramTec GmbH, CTS Corporation, Kistler Group, Physik Instrumente (PI), Murata Manufacturing, TDK Corporation, APC International, Ltd., Piezosystem Jena, Honeywell International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Piezoelectric Devices Market Strategic Shifts & Innovations
Material science breakthroughs and regulatory chemistry mandates are restructuring competitive advantage around formulation capabilities rather than device assembly scale. Three developments dominate the transition window.
Multi-layer ceramic capacitor manufacturing techniques are migrating into piezoelectric actuator fabrication, enabling higher displacement outputs at reduced drive voltages through stacked electrode configurations. Inkjet printhead OEMs and haptic feedback developers in consumer electronics are adopting these architectures fastest. Single-layer bulk ceramic designs are supplanting traditional machined monolithic structures in miniature precision applications.
REACH Annex XVII restrictions on lead compounds are compelling reformulation investments across European supply chains, with ECHA authorization timelines determining commercial viability windows for substitute materials. Formulators must demonstrate equivalent electromechanical performance under MDR technical documentation standards. Medical device suppliers face the steepest compliance gradients as FDA 510(k) pathways require parallel toxicological substantiation.
Automotive OEMs are consolidating sensor procurement under platform-level agreements rather than component-level spot purchasing, compressing supplier qualification cycles and elevating quality system requirements. Tier-1 integrators in Germany and Japan are displacing fragmented distributor networks with direct manufacturer relationships. This concentration is most visible in knock-detection sensor supply for powertrain management systems.
Piezoelectric Devices Market Segmentation
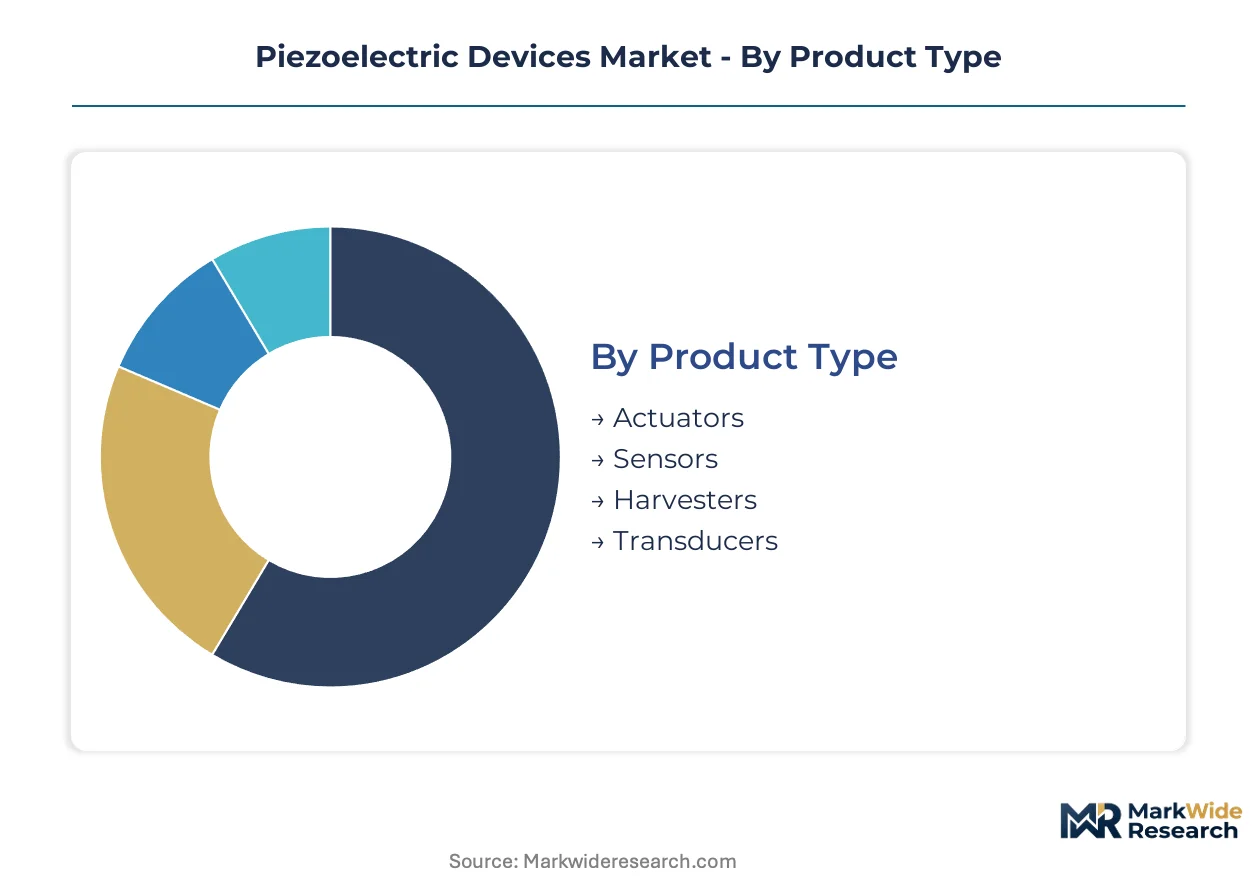
Piezoelectric device segmentation reflects divergent regulatory compliance burdens across medical, automotive, and industrial verticals. Material qualification timelines and certification documentation requirements vary sharply by end-use application, reshaping supplier portfolio priorities.
Product Type:
Regulatory differentiation separates medical-grade actuators subject to FDA device classification from industrial sensors governed by REACH substance restrictions.
- Actuators:Precision positioning mechanisms utilizing stacked ceramic layers achieve sub-nanometer resolution in semiconductor lithography and surgical robotics. EU MDR technical file requirements and FDA 510(k) pathways impose parallel validation burdens on healthcare-facing suppliers, compressing development timelines while deepening margin pools for qualified manufacturers.
- Sensors:Vibration detection and pressure measurement devices convert mechanical stress into electrical signals through crystalline ceramic elements. Automotive knock-detection procurement in Germany's Stuttgart-Munich corridor concentrates demand under platform-level agreements, displacing fragmented distributor networks with direct OEM relationships.
- Harvesters:Energy scavenging devices capture ambient mechanical vibration for IoT power supply.
- Transducers:Bidirectional electromechanical converters serve ultrasound imaging and industrial non-destructive testing.
Established volume favors sensors; emerging adoption favors harvesters.
Technology:
Cost tier differentiation separates mature analog architectures from premium multi-layer configurations commanding higher displacement efficiency.
- Multi-layer:Stacked electrode configurations derived from ceramic capacitor manufacturing enable higher displacement at reduced drive voltages. Inkjet printhead OEMs and haptic feedback developers in consumer electronics adopt these architectures fastest, while single-layer bulk designs persist in cost-sensitive industrial monitoring.
- Composite:Polymer-ceramic hybrids combining flexibility with electromechanical response serve structural health monitoring and wearable applications. Integration with civil infrastructure sensor networks in Japan and South Korea drives qualification programs for piezoelectric thin-film deposition.
- Analog:Traditional single-layer bulk ceramic designs dominate legacy industrial installations.
- Digital:Signal-conditioned outputs with embedded processing reduce external circuitry requirements.
Production scale concentrates in multi-layer; performance premium attaches to composite.
Application:
Customer type fragmentation separates platform-integrated automotive procurement from project-based aerospace contracting.
- Healthcare:Ultrasonic surgical and diagnostic equipment demands precision actuators with validated biocompatibility documentation. ISO 13485 quality system mandates and EU MDR technical file requirements add parallel compliance layers that favor suppliers with established medical certification infrastructure.
- Automotive:Powertrain knock-detection and active suspension systems drive high-volume sensor procurement under consolidated platform agreements. Tier-1 integrators in Germany and Japan compress supplier qualification cycles while elevating quality system requirements beyond fragmented distributor capabilities.
- Aerospace:Structural health monitoring and adaptive wing systems require specialized qualification protocols.
- Consumer Electronics:Haptic feedback and miniature acoustic components prioritize cost-optimized multi-layer architectures.
Margin depth concentrates in healthcare; volume expansion favors automotive.
End User:
Supply concentration varies sharply between captive in-house production at military contractors and outsourced procurement at commercial manufacturers.
- OEMs:Original equipment manufacturers in precision engineering and medical imaging integrate piezoelectric subsystems into finished capital equipment. Direct manufacturer relationships displace distributor intermediaries as automotive and semiconductor lithography customers consolidate procurement under long-term supply agreements.
- Research Institutions:National laboratories and university consortia drive material science breakthroughs in lead-free piezoceramic formulations. ECHA REACH authorization timelines and EPA chemical management protocols shape grant-funded development priorities toward potassium sodium niobate and bismuth-based alternatives.
- Manufacturers:Component suppliers serving diversified industrial markets.
- Military:Defense contractors with captive supply chains and specialized qualification requirements.
Procurement consolidation favors OEMs; technology push originates in research institutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in piezoelectric components tilt toward surplus positions in Germany and Japan against deficit absorption in the United States and India. China maintains near-balanced trade in processed ceramics while expanding domestic formulation capacity.
United States
EPA chemical management protocols are accelerating lead-free piezoceramic substitution timelines for automotive and medical device suppliers. FDA device classification requirements for ultrasonic surgical equipment compress validation cycles for precision actuator imports. Precision manufacturing clusters in Greater Boston and the Pacific Northwest concentrate demand for semiconductor lithography positioning systems.
Germany
ECHA REACH Annex XVII restrictions on lead compounds are compelling reformulation investments across Stuttgart and Munich precision engineering corridors. EU MDR technical file requirements and ISO 13485 quality system mandates favor established medical certification infrastructure. Sensor-integrated automation clusters serving BMW, Mercedes-Benz, and industrial OEMs are displacing fragmented distributor networks with direct manufacturer relationships.
Japan
METI industrial standards and dual carbon goals are shaping grant-funded priorities toward potassium sodium niobate alternatives. PMDA device registration pathways validate precision actuator specifications for domestic ultrasonic diagnostic equipment manufacturers. Kansai and Chubu industrial zones anchor high-volume multi-layer ceramic production for consumer electronics and automotive sensor applications.
China
NMPA medical device classification and MIIT industrial policies are accelerating localization of piezoceramic precursor processing. GB standards for electronic components are elevating quality system requirements beyond fragmented distributor capabilities. Yangtze River Delta manufacturing hubs concentrate inkjet printhead and haptic feedback module assembly for export markets.
India
PLI scheme electronics manufacturing incentives are attracting component localization for consumer sensor and automotive knock-detection applications. BIS certification requirements and CDSCO medical device rules extend validation timelines for healthcare-facing imports. Karnataka and Tamil Nadu industrial corridors concentrate contract assembly for smartphone haptic modules and industrial vibration monitors.
Piezoelectric Devices Market Key Industry Players
Concentration sits with German and Japanese specialists commanding premium positioning in medical and semiconductor applications, while Asian conglomerates anchor high-volume sensor production for automotive and consumer electronics. Three strategic archetypes dominate: captive ceramic formulators with in-house material science capabilities, precision motion specialists extracting margin from sub-nanometer resolution requirements, and diversified electronics manufacturers leveraging capacitor manufacturing techniques for actuator scaling. Capacity expansion and strategic partnerships represent the dominant competitive moves, with formulators seeking raw material security and device assemblers pursuing geographic diversification.
Within the captive formulation tier, CeramTec GmbH exemplifies vertical control over ceramic precursor supply, while TDK Corporation occupies a position bridging high-volume consumer electronics and automotive sensor markets. Physik Instrumente (PI) represents the precision motion specialist archetype, anchoring premium positioning in nanopositioning systems where resolution specifications command sustained margin premiums.
| Leading Market Players |
|---|
| CeramTec GmbH |
| CTS Corporation |
| Kistler Group |
| Physik Instrumente (PI) |
| Murata Manufacturing |
| TDK Corporation |
| APC International, Ltd. |
| Piezosystem Jena |
| Honeywell International |
| Others |
Cost & Logistics Intelligence
Ninety-to-one-hundred-day lead times for lead-free piezoceramic precursors concentrate pricing power with German and Japanese formulators holding captive sintering capabilities, while automotive OEM buyers extract volume discounts through consolidated platform agreements that compress margins at mid-scale assemblers.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure where pricing stratifies across medical-grade precision actuators, automotive knock-detection sensors, and economy-tier consumer haptic modules. Price differentiation rests on ISO 13485 certification tier and volume scale, with FDA-validated actuators commanding sustained premiums against REACH-compliant industrial alternatives. Cost compression in automotive sensor tiers is intensifying because Tier-1 integrators consolidate procurement under platform-level agreements. Medical device manufacturers exhibit lowest price sensitivity due to qualification timeline friction and performance parity requirements for lead-free formulations.
Supply Chain Analysis
Strategic stockpile preferences dominate raw material procurement as formulators buffer against rare earth element processing concentration in China and limited high-purity precursor supply from Germany and Japan. The supply chain draws from lead zirconate titanate and potassium sodium niobate ceramic formulations, multi-layer electrode stacks, and precision-machined monolithic substrates. Single-source vulnerability concentrates in ECHA REACH-authorized precursor suppliers facing compressed conversion timelines. Distribution runs through direct manufacturer relationships displacing fragmented distributor networks, particularly in Germany's Stuttgart-Munich automation corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive advantage as automotive OEMs consolidate sensor procurement under long-term agreements and medical device manufacturers demand interoperable precision actuator specifications across surgical robotics ecosystems.
For Market Incumbents: Shield formulation capabilities through backward integration into lead-free piezoceramic precursor processing, particularly potassium sodium niobate sintering expertise where specialized chemist scarcity constrains emerging competitors. Deepen captive ceramic production in Germany and Japan to defend against Tier-1 automotive integrators consolidating procurement under platform agreements. Prioritize ISO 13485 infrastructure investment to maintain medical certification moats as EU MDR technical file requirements extend validation cycles. For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for ultrasonic surgical equipment offer accelerated entry into precision actuator supply where incumbent qualification burdens create white-space opportunity. Target energy harvesting integration for civil infrastructure IoT networks in Japan and South Korea, where piezoelectric thin-film qualification programs remain underpenetrated. Pursue India PLI scheme alignment for consumer sensor localization, leveraging electronics manufacturing incentives to establish contract assembly footholds before automotive knock-detection procurement consolidates further. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified electronics conglomerates with dormant ceramic formulation assets that could achieve performance parity in lead-free alternatives through focused R&D capitalization. Prioritize mid-scale formulators with established ECHA REACH authorization progress and existing medical device supplier relationships over pure-play device assemblers facing margin compression. Watch lead-free electromechanical coupling coefficient benchmarks against legacy lead zirconate titanate as the inflection signal determining which formulation investments achieve commercial viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Precursor Processing | Captive sintering capabilities defend margin pools as REACH restrictions compress lead-based conversion timelines. |
| ISO 13485 Quality System Certification | Medical device infrastructure attracts healthcare-facing procurement as FDA 510(k) pathways extend validation burdens. |
| Multi-Layer Ceramic Actuator Scaling | Capacitor manufacturing techniques enable higher displacement efficiency for inkjet printhead and haptic feedback OEMs. |
| Platform-Level Supply Agreement Negotiation | Direct OEM relationships displace distributor networks in Germany's Stuttgart-Munich automotive corridor. |
| Lead-Free Formulation R&D Partnership | Potassium sodium niobate qualification programs align with ECHA authorization timelines and EPA chemical management protocols. |
Research Approach
The analysis maps precision actuators, vibration sensors, energy harvesters, and ultrasonic transducers, each validated through formulation chemists, Tier-1 automotive procurement directors, medical device regulatory affairs leads, and semiconductor lithography equipment engineers. Primary interview intelligence triangulates against secondary sources including ECHA REACH authorization databases, FDA 510(k) filing records, EPA chemical management protocol disclosures, and EU MDR technical documentation standards. Bottom-up unit economics and top-down macroeconomic indicators converge across the projection horizon.
Consistency checks against external benchmarks validate volume and value outputs across product type, technology tier, application vertical, and end-user category segmentation. CAGRs derive from modeled adoption curves for lead-free piezoceramic substitution, multi-layer ceramic displacement penetration, and automotive sensor platform consolidation. Industry-specific inputs include electromechanical coupling coefficient performance parity timelines and ECHA authorization commercial viability windows.
The analysis sits within stated boundaries; outcomes outside sustained REACH enforcement intensity and lead-free material qualification progress would require recalibration. Forecasts reflect assumptions regarding formulation R&D investment continuity and automotive OEM procurement consolidation velocity. Revision becomes warranted when lead-free electromechanical performance crosses parity thresholds with legacy lead zirconate titanate specifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
High-Precision Confocal Sensor Market
Sensors and Controls
Digital Array Microphone Market
Sensors and Controls
Lidar Ceilometer Market
Sensors and Controls
Capacitive Ceramic Pressure Sensors Market
Sensors and Controls
Inductive and LVDT Sensors Market
Sensors and Controls
India Digital Thermometer Market
Sensors and Controls
North America Wireless Sensors Market
Sensors and Controls
Multi-Axis Sensor Market
Sensors and Controls
Europe Acoustic Sensors Market
Sensors and Controls
Fingerprint Module Market
Sensors and Controls
Middle East and Africa Lidar Market
Sensors and Controls
Europe Human Machine Interface Market
Sensors and Controls
Automotive Cabin Air Quality Sensors Market
Sensors and Controls
Global Sensors and Actuators Market
Sensors and Controls
Asia-Pacific Water Detection Sensors Market
Sensors and Controls
Global Signal Conditioning Modules Market