
 Global Caffeic Acid Market | 2026-2036
Global Caffeic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Global Caffeic Acid Market Analysis
Specialty chemical distribution is rewriting access patterns for caffeic acid procurement across pharmaceutical and nutraceutical buyers. Merck KGaA leverages its life sciences division to sustain direct-to-laboratory channels in North America and Europe. Biosynth AG anchors its position through custom synthesis capabilities for research-grade caffeic acid derivatives. Wuhan Hezhong Bio-chemical Manufacture competes on fermentation-based production scale serving Asian pharmaceutical manufacturers.
Caffeic acid is a hydroxycinnamic acid with the molecular formula C9H8O4, synthesized through alkaline hydrolysis of chlorogenic acid or microbial fermentation of plant substrates; it functions primarily as an antioxidant, anti-inflammatory, and antimicrobial agent across food preservation, cosmetic formulation, and pharmaceutical development. Powder formulations dominate volume throughput due to stability in bulk handling and compatibility with encapsulation equipment, while liquid extracts capture premium positioning in cosmetic serums where solubility drives formulation efficiency. Nutraceutical applications lead growth velocity as consumer-directed antioxidant supplementation expands, though pharmaceutical-grade material commands the deepest margin pools due to certification burdens and documentation requirements.
FDA dietary supplement regulations and EFSA novel food assessments shape market access thresholds for caffeic acid entrants, with China's NMPA adding pharmaceutical-grade registration requirements for active ingredient imports. REACH compliance in Europe and evolving FDA GRAS determinations in the United States create divergent compliance cost structures that filter supplier participation by certification depth. Stakeholders must monitor regulatory harmonization pressures between pharmacopeial standards and food-grade specifications as these boundaries determine which production assets qualify for multi-segment supply.
Market Dynamics
Specialty chemical distribution networks are consolidating around fermentation-based production clusters in China, compressing procurement timelines for pharmaceutical-grade caffeic acid while forcing European and North American buyers to absorb REACH and FDA compliance premiums.
Growth Catalysts
- NMPA pharmaceutical-grade registration:China's tightened active ingredient import rules accelerate domestic API manufacturer scale-up, pulling volume through state-backed production facilities.
- Antioxidant supplement formulation:Nutraceutical end-users expand caffeic acid incorporation into encapsulated delivery systems, driven by consumer-directed preventive health expenditure.
- Fermentation process maturation:Microbial production from plant substrates achieves cost parity with alkaline hydrolysis of chlorogenic acid, unlocking supply elasticity.
Market Restraints
- Chlorogenic acid feedstock volatility:Coffee bean and apple peel supply fluctuations transmit directly into hydrolysis-based production cost structures.
- REACH purity certification burden:ECHA-mandated documentation requirements filter supplier participation, elevating European import thresholds above Asian domestic benchmarks.
- Synthetic antioxidant substitution:Butylated hydroxyanisole and tertiary butylhydroquinone maintain cost advantages in food preservation applications.
Strategic Opportunities
- Cosmetic serum solubility premium:Liquid extract formats capture formulation efficiency gains in South Korean and Japanese skincare manufacturing.
- EFSA novel food pathway:Regulatory clarity on phenolic acid safety assessments opens food-grade expansion beyond current supplement boundaries.
- Direct-to-laboratory channels:Research-grade derivative demand from contract research organizations bypasses traditional distributor markups.
Industry Challenges
- Pharmacopeial standard harmonization:Divergent USP, EP, and ChP monograph specifications force multi-certification inventory strategies.
- Specialized fermentation engineering talent:Microbial strain optimization expertise concentrates in Chinese and German biotechnology clusters, creating recruitment friction elsewhere.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Caffeic Acid Market |
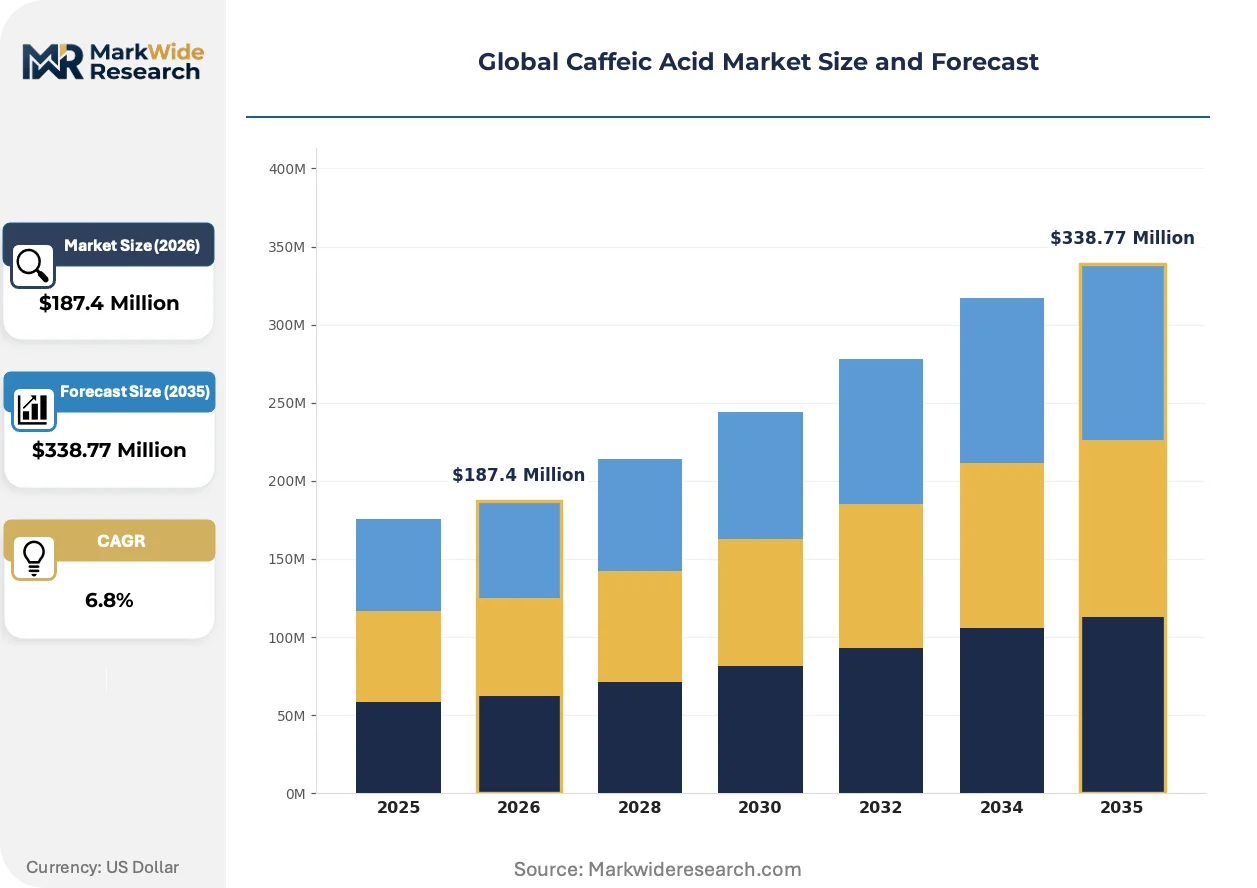
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Capsule, Tincture Application: Nutraceuticals, Cosmetics, Pharmaceuticals, Food Additives End User: Food Industry, Pharmaceutical Companies, Cosmetic Manufacturers, Nutraceutical Firms Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Cayman Chemical, Biosynth AG, Wuhan Hezhong Bio-chemical Manufacture, Hubei Yuancheng Technology Co., Ltd., Penta Manufacturing Company, Merck KGaA, BASF SE, Tokyo Chemical Industry, Sigma-Aldrich, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Caffeic Acid Market Emerging Trajectories
Production technology and regulatory classification boundaries are simultaneously shifting, compressing the gap between food-grade and pharmaceutical-grade supply qualifications while reshaping how buyers evaluate supplier capability depth.
Fermentation-based caffeic acid synthesis is migrating from pilot-scale demonstration to commercial backbone status. Asian pharmaceutical manufacturers now specify microbial routes in procurement tenders, displacing hydrolysis-dependent supply agreements. This technology diffusion compresses the premium previously attached to synthetic purity grades.
REACH authorization requirements for phenolic acid imports are tightening substance volume thresholds and downstream documentation obligations. European cosmetic and nutraceutical formulators now demand extended supply chain transparency from Asian producers. German and French distributors respond by consolidating supplier panels around pre-certified manufacturing assets.
Buyer qualification protocols now emphasize multi-jurisdiction certification depth over unit pricing. Large nutraceutical contract manufacturers in the United States and Italy are unbundling after-sales technical support from base material supply, creating separate service fee structures. This purchasing model evolution is most visible among North American direct-to-consumer supplement brands seeking rapid formulation iteration support.
Global Caffeic Acid Market Segmentation
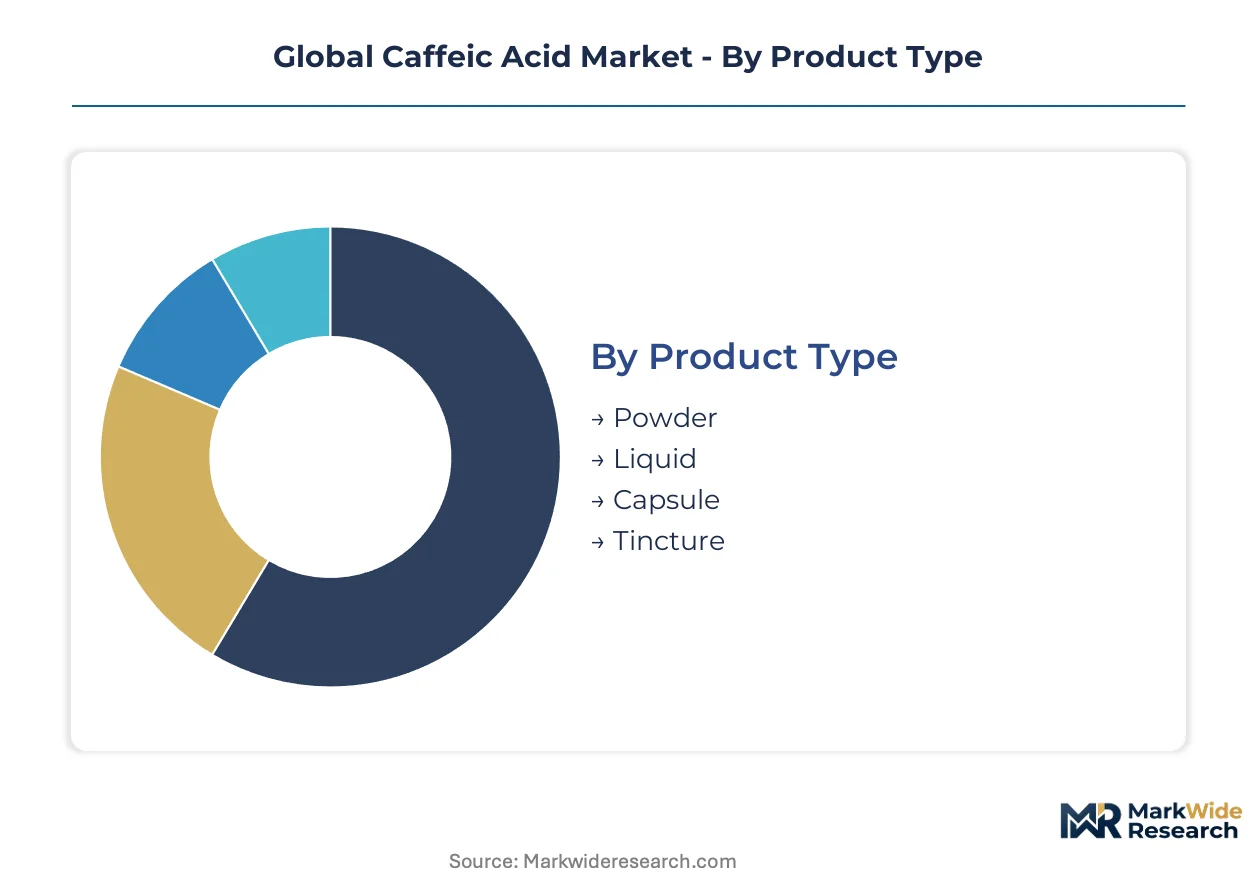
Caffeic acid procurement patterns diverge sharply across formulation formats and end-use certifications. Pharmaceutical buyers prioritize powder stability and documentation depth, while cosmetic formulators chase liquid solubility for serum applications.
Product Type:
Powder formats command mature supply infrastructure with established bulk handling protocols, while liquid and capsule formats occupy emerging positions with steeper technical barriers.
- Powder:Crystalline formulations with standardized particle size distribution enable encapsulation equipment compatibility and extended shelf stability. Nutraceutical contract manufacturers in the United States and Italy specify powder grades for high-volume antioxidant supplement production, driven by FDA dietary supplement cGMP documentation requirements.
- Liquid:Aqueous and ethanol-based solutions deliver immediate solubility for cosmetic serum integration without additional processing steps. South Korean and Japanese skincare manufacturers absorb premium positioning for liquid extracts where formulation efficiency accelerates product development cycles.
- Capsule:Pre-encapsulated caffeic acid reduces in-house manufacturing complexity for mid-tier supplement brands.
- Tincture:Alcohol-based preparations serve niche herbal medicine practitioners and specialty wellness retailers.
Powder handles the majority of throughput; liquid is the fastest mover on share.
Application:
Margin concentration follows certification burden, with pharmaceutical and food additive applications anchoring opposite ends of the compliance cost spectrum.
- Nutraceuticals:Encapsulated antioxidant supplements and functional beverage additives target consumer-directed preventive health expenditure. Direct-to-consumer brands in North America scale caffeic acid incorporation as EFSA novel food assessments gradually clarify regulatory boundaries for phenolic acid safety.
- Pharmaceuticals:Active pharmaceutical ingredient production demands USP, EP, and ChP monograph compliance with full supply chain documentation. China's NMPA registration requirements for imported active ingredients filter supplier participation to pre-certified manufacturing assets.
- Cosmetics:Antioxidant serums and anti-aging formulations leverage caffeic acid's free radical scavenging properties.
- Food Additives:Natural preservation applications compete with synthetic antioxidants BHA and TBHQ on cost positioning.
Pharmaceuticals captures the deepest margin pools; nutraceuticals is expanding most quickly.
End User:
Procurement sophistication varies by sector, with pharmaceutical companies demanding multi-jurisdiction certification depth and food industry buyers prioritizing volume scale.
- Pharmaceutical Companies:API manufacturers require fermentation-based production with full pharmacopeial documentation and REACH compliance for European export. German and Swiss biotechnology clusters concentrate specialized microbial strain optimization expertise.
- Nutraceutical Firms:Supplement brands and contract manufacturers source research-grade derivatives and custom synthesis capabilities from direct-to-laboratory channels.
- Cosmetic Manufacturers:Formulators in Osaka and Seoul specify liquid extract grades for premium skincare positioning.
- Food Industry:Processors evaluate caffeic acid against synthetic antioxidant cost structures in preservation applications.
Pharmaceutical companies dominate certification-intensive supply; nutraceutical firms are gaining share fastest.
Distribution Channel:
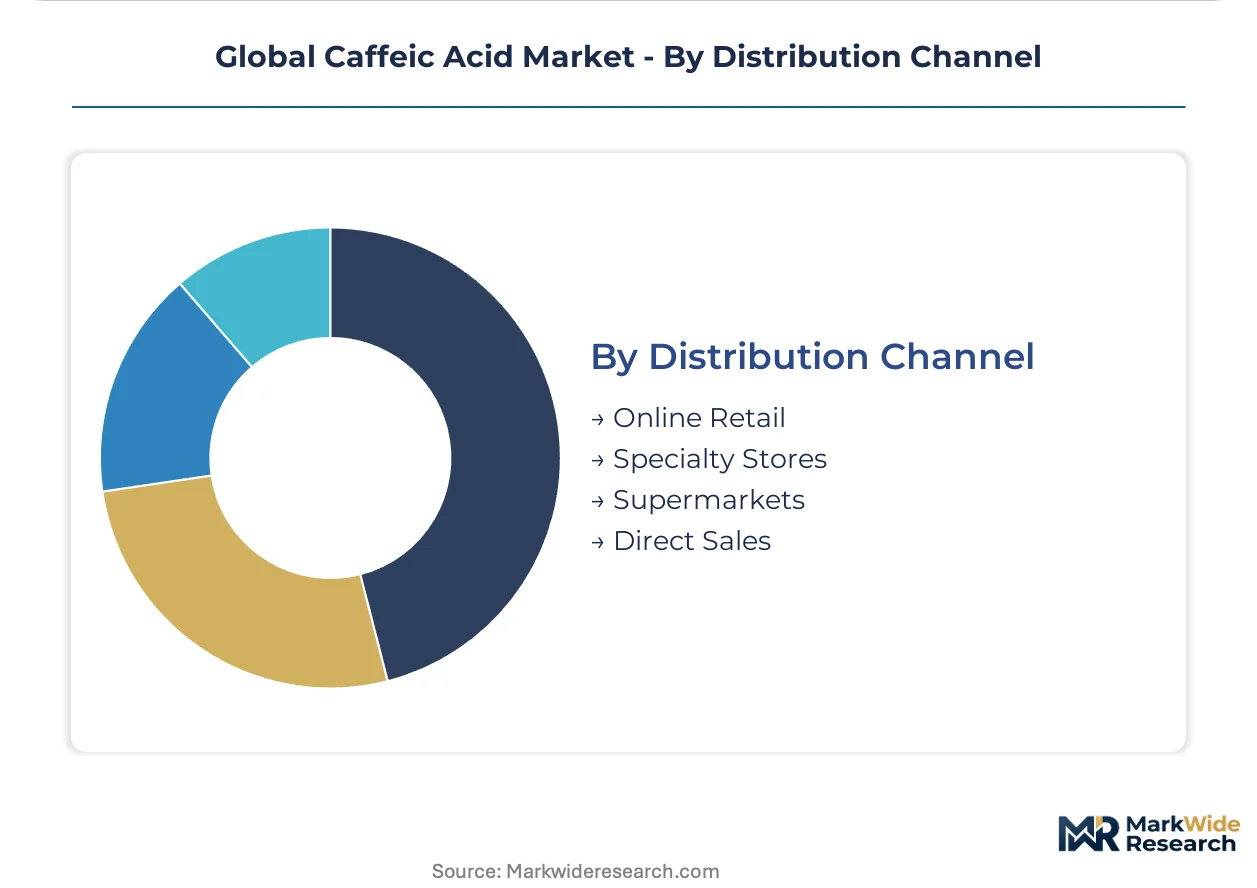
Channel selection reflects buyer scale and technical support requirements, with large manufacturers bypassing traditional distributor markups.
- Direct Sales:Laboratory chemical suppliers and fermentation specialists maintain technical service relationships with pharmaceutical API manufacturers. Biosynth AG and comparable specialty distributors anchor procurement through custom synthesis capabilities and after-sales formulation support.
- Online Retail:E-commerce platforms serve small-scale nutraceutical brands and research institutions with rapid reordering and transparent pricing.
- Specialty Stores:Regional distributors with REACH pre-certification consolidate European cosmetic and nutraceutical procurement.
- Supermarkets:Mass-market supplement retail captures consumer-facing antioxidant products with limited technical differentiation.
Direct sales handles the majority of pharmaceutical-grade volume; online retail is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NMPA pharmaceutical-grade registration requirements in China compress import timelines for API manufacturers while elevating domestic fermentation capacity. REACH compliance premiums in Europe and FDA dietary supplement cGMP documentation in the United States create divergent procurement cost structures across major consuming geographies.
China
Domestic pharmaceutical manufacturers scale active pharmaceutical ingredient production through state-backed fermentation facilities in Wuhan and Hubei province. NMPA tightened active ingredient import rules, accelerating volume concentration through pre-certified domestic assets. The Yangtze River Delta clusters specialized microbial strain optimization expertise serving Asian pharmaceutical contract manufacturers.
United States
Nutraceutical contract manufacturers in New Jersey and California specify powder grades for high-volume antioxidant supplement production. FDA dietary supplement cGMP documentation requirements filter supplier participation to pre-audited manufacturing assets. Direct-to-consumer supplement brands in the Pacific Northwest unbundle after-sales technical support from base material supply.
Germany
REACH authorization requirements for phenolic acid imports tighten substance volume thresholds and downstream documentation obligations. ECHA-mandated purity certification elevates European import thresholds above Asian domestic benchmarks. The Rhine-Main biotechnology corridor concentrates specialized fermentation engineering talent for microbial strain optimization.
Japan
Cosmetic formulators in Osaka specify liquid extract grades for premium skincare positioning where formulation efficiency accelerates product development cycles. METI standards for cosmetic ingredient safety assessments shape procurement qualification protocols. The Kansai region anchors demand for aqueous and ethanol-based caffeic acid solutions.
South Korea
Skincare manufacturers in Seoul absorb premium positioning for liquid extracts in antioxidant serum applications. MFDS cosmetic ingredient regulations drive extended supply chain transparency requirements from Asian producers. The Seoul Capital Area concentrates formulation R&D for free radical scavenging cosmetic applications.
Global Caffeic Acid Market Vendor Landscape
Fermentation specialists and laboratory chemical distributors split the market between pharmaceutical-grade certification depth and research-grade custom synthesis capabilities. The vendor base concentrates around Chinese production assets serving Asian API manufacturers and European distributors managing REACH compliance premiums. Three archetypes dominate: fermentation-scale producers, custom synthesis laboratories, and diversified life sciences conglomerates. Capacity expansion in microbial production routes and consolidation of pre-certified supplier panels constitute the dominant competitive moves.
Among diversified chemical conglomerates, BASF SE and Merck KGaA exemplify the certification-intensive tier serving pharmaceutical and nutraceutical end-users with multi-jurisdiction documentation depth. Tokyo Chemical Industry occupies a position within the research-grade supply segment. Biosynth AG and Cayman Chemical represent the custom synthesis archetype, anchoring direct-to-laboratory channels for derivative demand from contract research organizations.
| Leading Market Players |
|---|
| Cayman Chemical |
| Biosynth AG |
| Wuhan Hezhong Bio-chemical Manufacture |
| Hubei Yuancheng Technology Co., Ltd. |
| Penta Manufacturing Company |
| Merck KGaA |
| BASF SE |
| Tokyo Chemical Industry |
| Sigma-Aldrich |
| Others |
Supply Flow & Price Mechanics
REACH purity certification chokepoints in European ports determine both three-tier pricing spreads across pharmaceutical, nutraceutical, and food-grade tiers and the geographic shape of supplier consolidation around pre-certified Chinese fermentation assets. Buyers absorb documentation premiums that widen price differentials between REACH-compliant and uncertified material while forcing inventory strategies toward multi-jurisdiction qualified suppliers.
Pricing Analysis
Configured-to-order pricing for custom synthesis derivatives commands spreads of 40-60 percent above standard powder grades, with pharmaceutical-grade USP/EP/ChP certification adding further premiums over food-grade specifications. Price differentiation rests on fermentation purity tiers and after-sales technical support bundling, with large nutraceutical contract manufacturers unbundling services to compress base material costs. Cost compression in standard powder grades is intensifying as Chinese fermentation capacity scales, while pharmaceutical buyers show least price sensitivity due to API registration requirements. Food additive applications face greatest pricing pressure from synthetic antioxidant substitutes BHA and TBHQ.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now anchor supplier-financing arrangements for Asian fermentation specialists serving European distributors, with supply-chain finance facilities increasingly standard in API procurement contracts. Production concentrates in China, Germany, and Switzerland, with Wuhan and Hubei province anchoring microbial strain optimization capacity. Feedstock dependencies on chlorogenic acid from coffee bean and apple peel sources, plus specialized fermentation engineering talent, create vulnerability to agricultural commodity swings. Single-source vulnerability concentrates in pre-certified fermentation assets for pharmaceutical-grade material. Distribution runs through direct-to-laboratory channels for research-grade derivatives and specialty chemical distributors for bulk pharmaceutical procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized microbial strain optimization expertise concentrates in narrow geographic clusters, creating acquisition premiums for fermentation engineering talent and pre-certified production assets that outrun generic chemical manufacturing capabilities.
For Market Incumbents: Harden certification depth across USP, EP, and ChP monographs simultaneously to defend against Asian fermentation specialists capturing pharmaceutical-grade share through NMPA-registered export capacity. Add fermentation capacity in the Rhine-Main biotechnology corridor to anchor European supply security. Lock long-term chlorogenic acid feedstock agreements to neutralize agricultural commodity volatility. For New Entrants and Emerging Players: South Korean cosmetic serum manufacturers represent underpenetrated demand for liquid extract formats, with formulation efficiency requirements creating entry paths bypassing established powder-grade incumbents. Target direct-to-laboratory channels for research-grade derivative supply to contract research organizations, where custom synthesis capabilities command premium positioning without multi-jurisdiction certification burdens. Lead with aqueous solubility specifications and rapid formulation iteration support. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors fermentation-scale producers with pre-certified assets over hydrolysis-dependent legacy suppliers. Five-to-ten year viability hinges on microbial route cost parity and REACH documentation depth. Acquire specialists with NMPA-registered Chinese production and European distributor relationships. Watch EFSA novel food pathway decisions as inflection signal for nutraceutical-grade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlorogenic Acid Feedstock | Coffee bean and apple peel supply agreements neutralize hydrolysis route cost volatility for European producers. |
| Fermentation Capacity Expansion | Microbial production scale-up in Wuhan and Hubei province displaces alkaline hydrolysis cost structures for Asian API manufacturers. |
| Multi-Jurisdiction Certification Investment | Simultaneous USP, EP, and ChP compliance opens pharmaceutical-grade procurement to large nutraceutical contract manufacturers. |
| Direct-to-Laboratory Channel Development | Custom synthesis capabilities for research-grade derivatives bypass traditional distributor markups from contract research organizations. |
| Liquid Extract Format Premium Positioning | Aqueous and ethanol-based solutions capture formulation efficiency gains in South Korean and Japanese skincare manufacturing. |
Methodological Framework
Desk research of pharmacopeial monograph databases, customs trade flows, and NMPA registration filings preceded structured interviews with fermentation plant managers, pharmaceutical API procurement leads, nutraceutical contract manufacturing executives, and specialty chemical distribution channel partners. Primary fieldwork with Chinese fermentation specialists and German REACH compliance consultants combined with secondary validation through ECHA substance volume tracking, FDA cGMP inspection records, and SEC filings from diversified life sciences conglomerates. Bottom-up production capacity modeling triangulated against top-down demand segmentation across application categories.
Assumptions held fixed include current REACH authorization thresholds, NMPA import registration requirements, and EFSA novel food assessment timelines, while fermentation yield improvements and chlorogenic acid feedstock pricing varied across sensitivity scenarios. Segmentation dimensions modeled encompassed grade tier, end-use application, formulation format, and regional regulatory cluster. CAGRs derived from production capacity expansion schedules, import volume trajectories, and end-use demand elasticity parameters. Industry-specific inputs included microbial strain optimization rates and pharmacopeial standard harmonization pressures.
Practitioners should monitor EFSA novel food pathway decisions, NMPA registration rule adjustments, and fermentation yield breakthroughs for early signals of demand inflection or supply cost restructuring. Forecasts reflect documented assumptions on regulatory stability and technology diffusion rates. Macroeconomic commodity swings, regulatory harmonization acceleration, or synthetic biology disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Non-Commercial Acrylic Paints Market
Specialty Chemicals
Optical Whitening Agents Market
Specialty Chemicals
Biocides for Leather Market
Specialty Chemicals
Releasing Agents Market
Specialty Chemicals
Methyltrimethoxysilane Market
Specialty Chemicals
Fragrance-Release Control Agents for Long-Lasting Home Care Scents Market
Specialty Chemicals
Solanesol Market
Specialty Chemicals
Shikimic Acid Market
Specialty Chemicals
US Antimicrobial Plastics Market
Specialty Chemicals
Catharanthine Market
Specialty Chemicals
Toner Spray Market
Specialty Chemicals
Coconut Derived Emollients Market
Specialty Chemicals
Pyrrolidone Market
Specialty Chemicals
Mexoryl SX (Ecamsule) Market
Specialty Chemicals
2-(2,2,2-Trifluoroethoxy)-1,3,2-Dioxaphospholane-2-Oxide Market
Specialty Chemicals
Bond Breaker Market