
 Avobenzone Market | 2026-2036
Avobenzone Market Size, Share, and Industry Trends Forecast 2026-2036
Avobenzone Market Outlook
Asset-light contract manufacturing is narrowing the capital barrier for mid-tier cosmetic brands entering the avobenzone supply chain. BASF SE leverages its integrated feedstock position to sustain cost advantages across multiple UV filter chemistries. Evonik Industries AG anchors its competitiveness through specialized emulsion technologies that stabilize avobenzone against photodegradation. Jiangsu Litian Technology competes on manufacturing scale, serving Asian cosmetic manufacturers with localized production capacity.
Avobenzone is a dibenzoylmethane-derived organic compound that absorbs UVA radiation across the 320–400 nm wavelength range, functioning as a oil-soluble filter that requires photostabilizers such as octocrylene to prevent rapid degradation under solar exposure. Sunscreen applications dominate volume consumption, while skincare serums represent the fastest-growing segment as brands incorporate avobenzone into daily moisturizers with anti-aging positioning. Lotions maintain the largest share within product type segmentation due to familiar consumer application habits, whereas sprays gain traction among athletic and pediatric segments despite formulation complexity.
FDA oversight in the United States classifies avobenzone as a Category I sunscreen active, though the agency continues reviewing supplemental safety data under its ongoing monograph modernization process. The EU's REACH framework and Cosmetics Regulation 1223/2009 impose stricter hazard assessment protocols than North American standards, creating divergent compliance pathways for multinational suppliers. Stakeholders must monitor regulatory divergence between FDA and EMA approaches to systemic absorption studies, as this scientific debate will determine which formulation technologies receive market access across major economies.
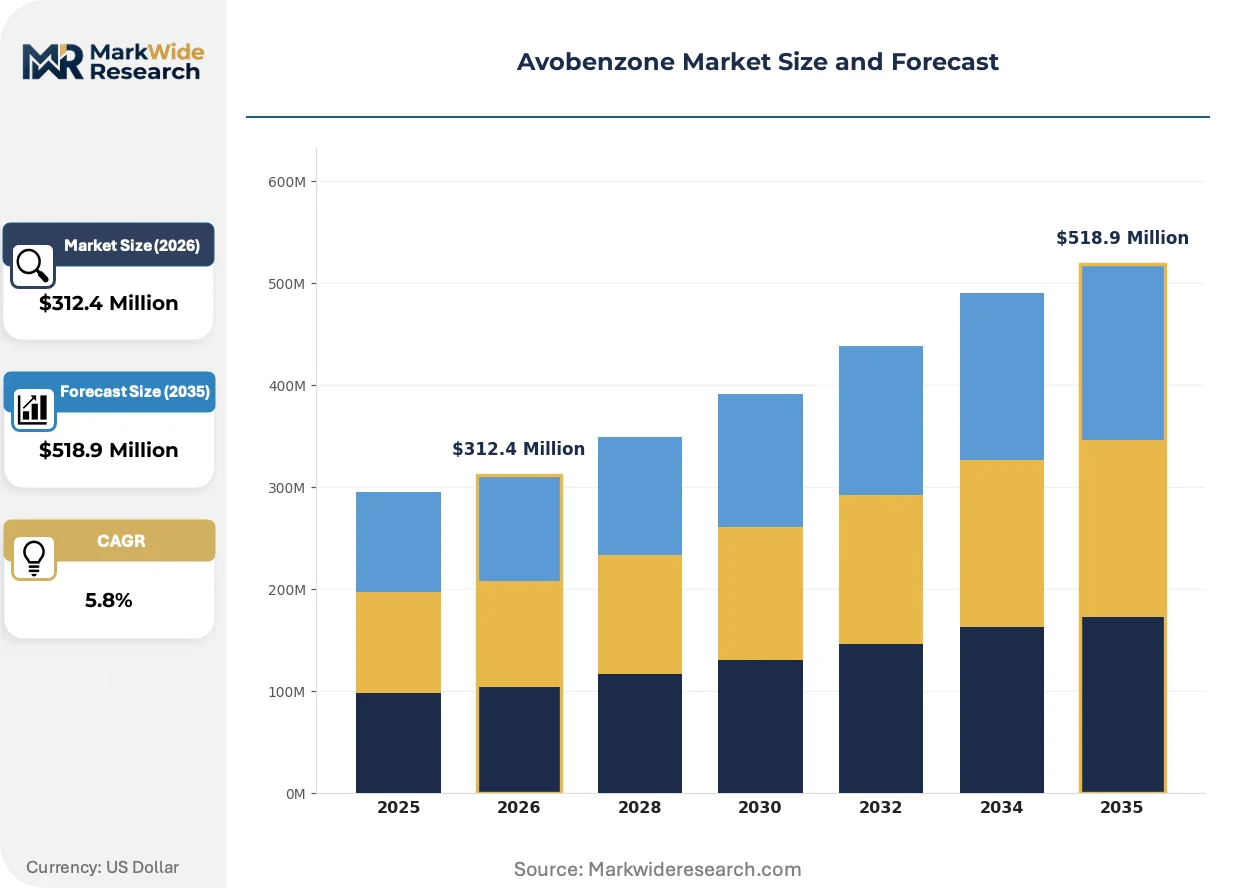
Market Dynamics
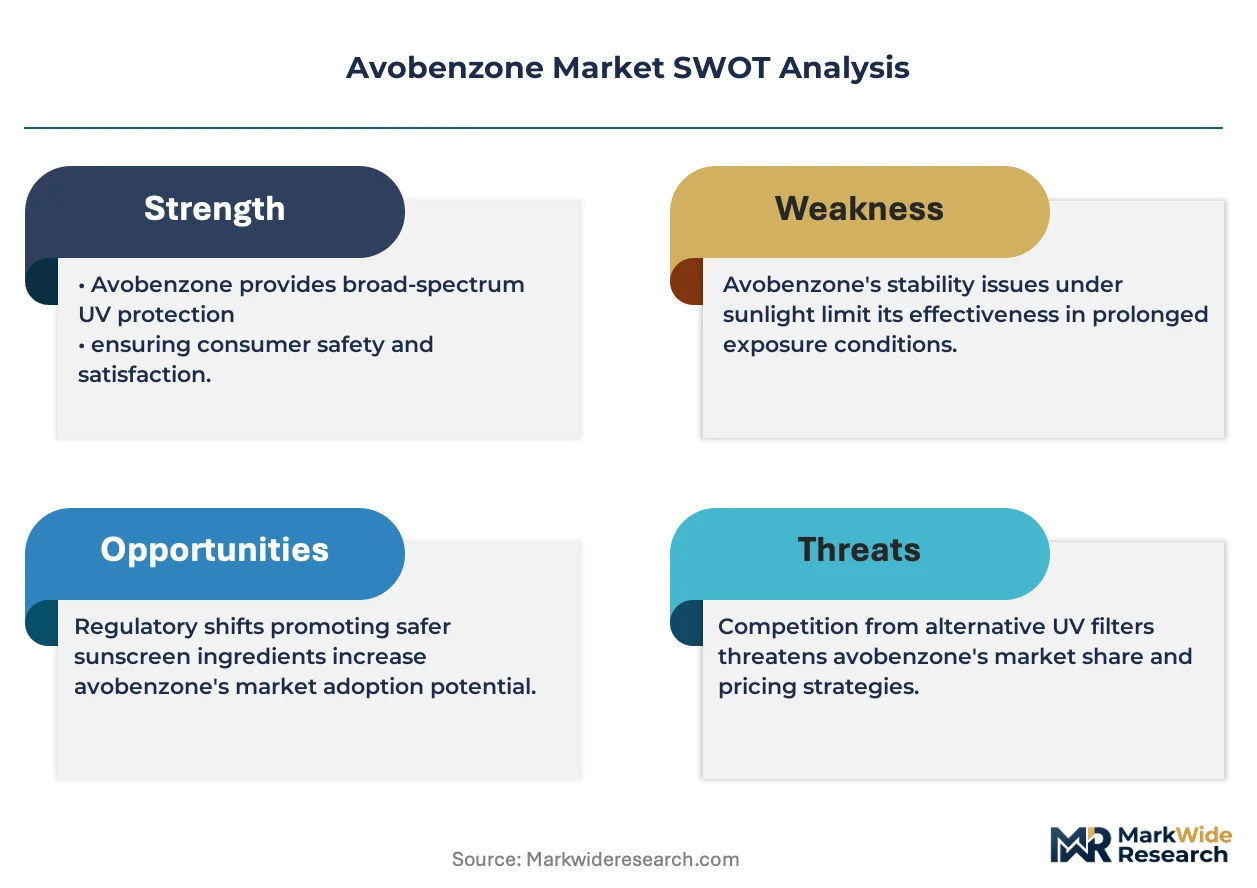
Photostabilizer formulation complexity is compressing margins for sunscreen manufacturers while simultaneously creating differentiation opportunities for suppliers with proprietary emulsion expertise. The technical barrier to prevent avobenzone photodegradation without octocrylene has become the decisive competitive variable.
Growth Catalysts
- REACH hazard assessment protocols:The EU's tightening safety reviews for chemical UV filters under REACH and Cosmetics Regulation 1223/2009 are accelerating reformulation cycles. This creates recurring demand for compliant avobenzone grades.
- Daily moisturizer integration:Skincare serums incorporating avobenzone into anti-aging positioning are expanding addressable volume beyond traditional beach-use occasions.
- Dermatologist channel concentration:Pharmacy chains in the United States are granting premium shelf placement to clinician-recommended sunscreens, concentrating demand pull through professional endorsement networks.
Market Restraints
- Petrochemical feedstock volatility:Dibenzoylmethane synthesis depends on benzene and acetone derivatives whose pricing fluctuates with crude oil indices.
- Photostabilizer dependency:Formulations require octocrylene or proprietary alternatives to prevent rapid UVA-induced degradation, adding cost and supply chain complexity.
- Systemic absorption scrutiny:FDA's ongoing monograph modernization process demands supplemental safety data, creating regulatory friction for new product approvals.
Strategic Opportunities
- Pediatric spray formulations:Athletic and children's segments show underpenetrated demand for convenient application formats despite formulation challenges.
- Asset-light manufacturing:Contract manufacturing platforms are lowering capital barriers for mid-tier cosmetic brands to enter avobenzone supply chains.
- Photostabilizer-free innovation:Encapsulation technologies and novel emulsion chemistries promise to eliminate octocrylene dependency.
Industry Challenges
- Formulation chemistry expertise scarcity:The specialized knowledge required to stabilize avobenzone in water-resistant matrices without compromising sensory properties is concentrated among senior cosmetic chemists.
- Dual regulatory pathway complexity:Multinational suppliers must simultaneously satisfy FDA's Category I classification requirements and EMA's stricter systemic absorption study protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Avobenzone Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lotions, Creams, Gels, Sprays Application: Cosmetics, Skincare, Sunscreen, Haircare End User: Individuals, Salons, Dermatology Clinics, Cosmetic Manufacturers Distribution Channel: Online Retail, Pharmacies, Supermarkets, Specialty Stores |
| Companies Covered | Ashland Global Holdings Inc., Evonik Industries AG, BASF SE, Croda International, Sensient Technologies Corporation, Merck KGaA, The Lubrizol Corporation, Jiangsu Litian Technology, DSM-Firmenich AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Avobenzone Market Strategic Shifts
Formulation science is converging with regulatory chemistry to redefine competitive advantage in UV protection. The technical frontier has shifted from raw material supply to stabilization expertise and clean-label compatibility.
Encapsulation technology is hybridizing avobenzone delivery systems. Silica-shell and lipid-matrix encapsulation methods physically isolate the molecule from degrading UV exposure and skin contact. Premium skincare brands in South Korea and France are adopting these systems for anti-aging daily wear products. This hybridizing approach is compressing demand for traditional octocrylene-dependent formulations while opening premium pricing tiers.
REACH authorization requirements are forcing earlier-stage hazard assessment integration. ECHA's systematic evaluation of endocrine-disrupting potential in organic UV filters is pushing suppliers to generate mechanistic toxicology data before regulatory deadlines. European formulators are most affected, with several major cosmetic houses accelerating reformulation timelines to secure uninterrupted market access.
Clean-label preferences are fragmenting procurement patterns. Retail buyers in Germany and the United States are demanding reef-safe and benzophenone-free certifications that complicate avobenzone positioning. Direct-to-consumer brands are bypassing traditional distribution through pharmacy and mass retail channels, instead building subscription models around dermatologist-formulated positioning. This shift is most visible in the United States, where telehealth-integrated skincare platforms are capturing younger demographics.
Avobenzone Market Segmentation
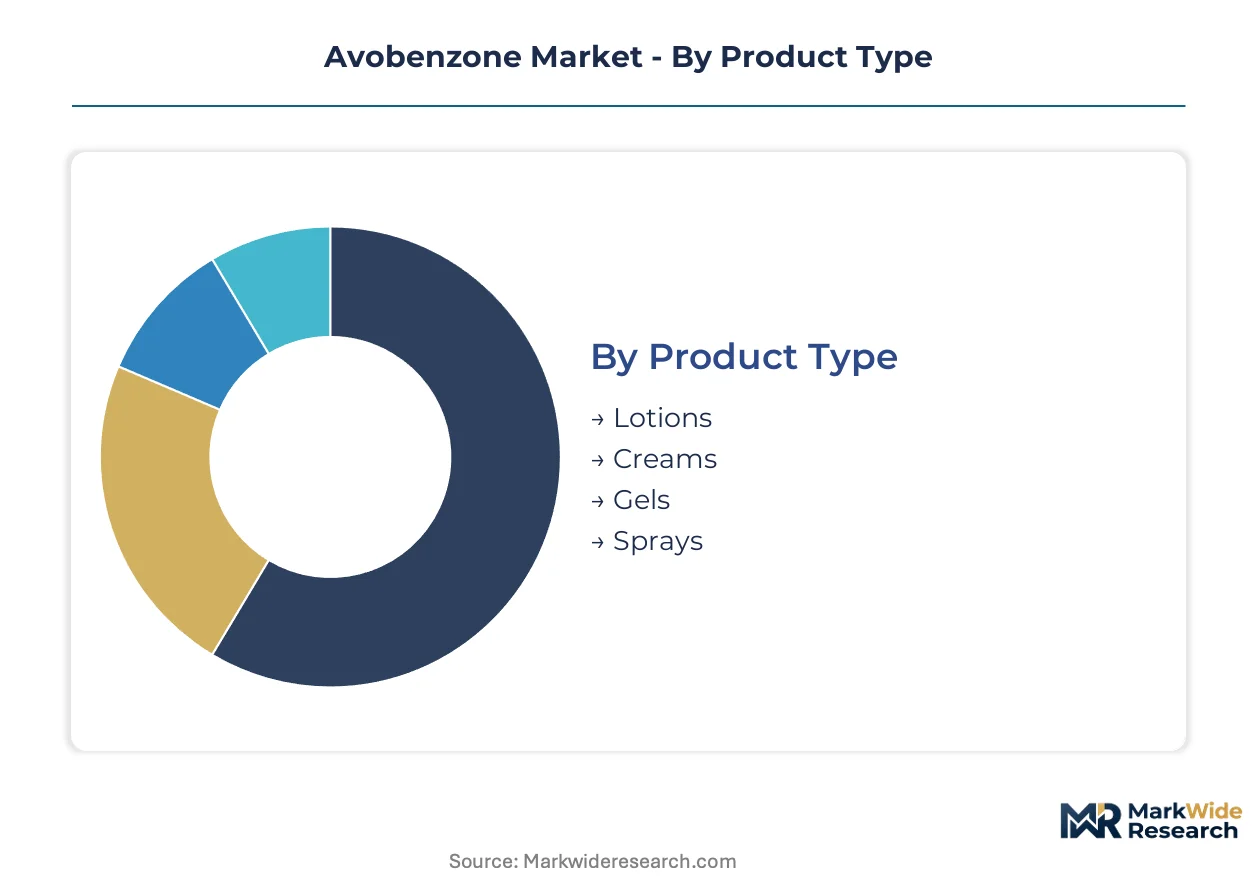
Segmentation in the avobenzone market reveals distinct technical and commercial pathways. Formulation requirements vary sharply across delivery formats, while regulatory pressure and consumer habits reshape channel strategies and end-user targeting.
Product Type:
After-sales service intensity tracks closely with formulation stability challenges and consumer education needs across delivery formats.
- Lotions:Oil-in-water emulsions dominate volume consumption due to familiar sensory properties and ease of spreading. Demand concentrates in United States pharmacy chains where dermatologist-recommended brands command premium shelf placement; water-resistance claims drive reformulation cycles.
- Sprays:Aerosol and pump-delivery systems require sophisticated emulsion engineering to prevent avobenzone photodegradation during application. Pediatric and athletic segments in Germany and Australia favor this format despite FDA scrutiny over inhalation exposure; convenience positioning justifies higher price points.
- Creams:Thicker, occlusive bases suit dry-skin positioning and winter-use occasions. French and Japanese cosmetic houses favor cream vehicles for anti-aging daily moisturizers with UVA protection claims.
- Gels:Alcohol-based or aqueous systems appeal to oily-skin demographics and male grooming lines. South Korean brands lead adoption of gel-sunscreen hybrids with matte-finish positioning.
Lotions hold the largest share; momentum sits with sprays.
Application:
Cost tier differentiation separates commodity UV protection from premium skincare positioning with anti-aging claims.
- Sunscreen:Beach and daily-wear formulations represent the core volume application, with broad-spectrum UVA/UVB claims mandatory for FDA Category I classification. United States demand pulls through pharmacy and dermocosmetic channels; reef-safe certification pressures are fragmenting procurement in Hawaii and Florida.
- Skincare:Serums and daily moisturizers incorporating avobenzone for photoaging prevention represent the steepest expansion trajectory. Premium positioning in South Korea and France leverages encapsulation technologies to eliminate octocrylene dependency and justify clean-label pricing.
- Cosmetics:Color cosmetics with integrated sun protection require micronized avobenzone grades that do not compromise pigment stability. Brazilian and Indian markets show rising interest in foundation-SPF hybrids.
- Haircare:Scalp-protection sprays and leave-in conditioners represent a niche application with formulation challenges around alcohol compatibility and sensory residue.
Sunscreen holds the largest share; skincare is climbing the fastest.
End User:
Volume concentration varies sharply between consumer-direct purchases and institutional procurement with technical specification requirements.
- Cosmetic Manufacturers:Large-scale formulators in Germany, United States, and Japan drive bulk avobenzone demand with exacting photostability specifications. Contract manufacturing platforms are lowering minimum order thresholds for mid-tier brands.
- Individuals:Direct consumer purchases through pharmacy and online channels dominate unit volume, with brand loyalty concentrated around dermatologist endorsement and sensory preference.
- Dermatology Clinics:Professional-dispensed sunscreens command premium pricing with clinical-strength positioning; United States and Australian clinics represent concentrated demand nodes.
- Salons:Post-treatment sun protection in aesthetic and spa settings favors elegant-finish formulations with retail markup potential.
Cosmetic manufacturers hold the largest share; momentum sits with dermatology clinics.
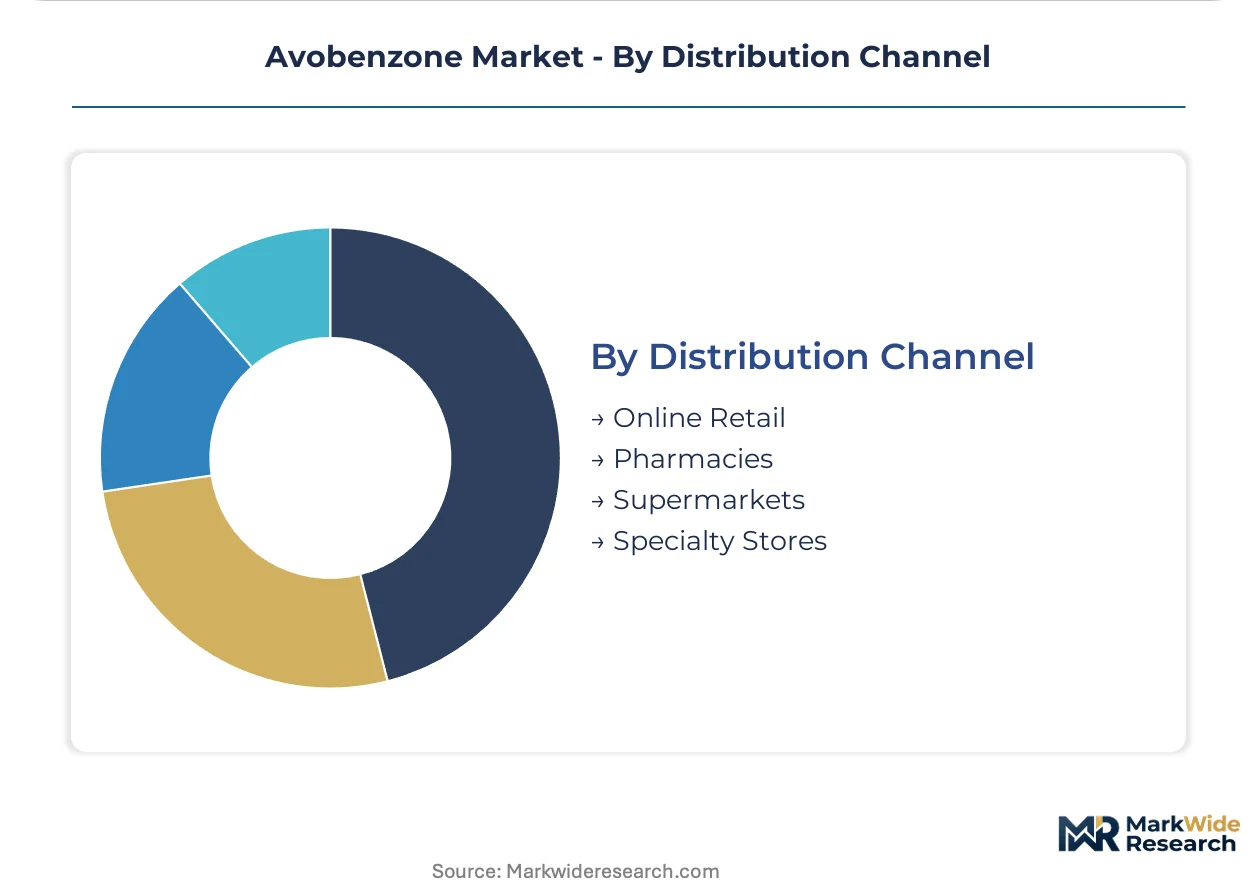
Distribution Channel:
Geography determines channel supremacy, with pharmacy dominance in Europe contrasting mass-retail and online traction in North America.
- Pharmacies:Clinician-recommended sunscreens in Germany, France, and United States secure preferential placement with trained staff consultation; regulatory alignment with national health frameworks reinforces channel authority.
- Online Retail:Direct-to-consumer subscription models and telehealth-integrated platforms are capturing younger demographics in United States and United Kingdom; clean-label and reef-safe certifications drive search-based discovery.
- Supermarkets:Mass-market volume in Brazil, India, and Southeast Asia moves through hypermarket chains with price-sensitive positioning and seasonal promotional cycles.
- Specialty Stores:Sephora, Douglas, and regional beauty retailers curate premium assortments with sensory testing and brand storytelling; South Korean and French markets show highest specialty-channel penetration.
Pharmacies hold the largest share; online retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances in avobenzone vary sharply by regulatory environment and downstream formulation demand. Countries with stringent UV filter safety protocols import higher-grade stabilized grades, while manufacturing hubs serve regional cosmetic clusters with localized production.
United States
FDA's Category I classification for avobenzone underpins pharmacy channel concentration and dermatologist endorsement networks. The agency's ongoing monograph modernization demands supplemental systemic absorption data, creating compliance friction for new entrants. New Jersey and California cosmetic corridors house reformulation laboratories serving mass-market and prestige brands respectively.
Germany
ECHA's REACH authorization timelines and endocrine-disrupting potential assessments accelerate hazard data generation requirements for UV filter suppliers. The country's dermocosmetic heritage channels demand through pharmacy networks with trained consultation staff. North Rhine-Westphalia's chemical cluster anchors BASF SE's integrated feedstock position for multiple UV filter chemistries.
France
ANSM enforces Cosmetics Regulation 1223/2009 with stricter hazard assessment protocols than North American counterparts, fragmenting procurement for multinational suppliers. Premium anti-aging skincare positioning drives encapsulation technology adoption. Paris-region cosmetic houses lead clean-label reformulation away from octocrylene-dependent stabilizers.
South Korea
MFDS regulates UV filters with alignment to EU safety standards while K-beauty export demand pulls high-volume avobenzone consumption. Daily-wear sunscreen-moisturizer hybrids expand addressable occasions beyond beach use. Seoul Capital Area formulation labs pioneer silica-shell encapsulation for photostabilizer-free positioning.
China
NMPA's sunscreen active inventory and safety data requirements create distinct approval pathways from FDA or EMA frameworks. Domestic cosmetic manufacturers source avobenzone for local brand development and export processing. Yangtze River Delta chemical parks host Jiangsu Litian Technology's manufacturing scale serving Asian formulators.
Avobenzone Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with feedstock or stabilization expertise. Market structure concentrates around integrated chemical conglomerates with captive benzene derivative supply, mid-tier Asian manufacturers competing on scale, and specialized emulsion technology providers. Three archetypes dominate: integrated petrochemical players, regional scale manufacturers, and formulation science specialists. Competitive moves center on photostabilizer-free encapsulation patents and asset-light contract manufacturing partnerships.
Among German-based integrated chemical groups, BASF SE and Evonik Industries AG occupy positions reflecting divergent strategic anchors—feedstock integration versus specialized emulsion expertise. Jiangsu Litian Technology exemplifies the Asia-Pacific scale-driven archetype with localized production capacity. These three represent distinct competitive vectors: upstream chemical integration, downstream formulation technology, and geographic manufacturing scale.
| Leading Market Players |
|---|
| Ashland Global Holdings Inc. |
| Evonik Industries AG |
| BASF SE |
| Croda International |
| Sensient Technologies Corporation |
| Merck KGaA |
| The Lubrizol Corporation |
| Jiangsu Litian Technology |
| DSM-Firmenich AG |
| Others |
Value Chain & Pricing Dynamics
Petrochemical feedstock volatility in benzene and acetone derivatives compresses margin spreads across avobenzone grades while simultaneously forcing supply chain consolidation toward integrated producers with captive chemical intermediates. This input-cost uncertainty stratifies pricing tiers between stabilized pharmaceutical-grade supply and commodity technical grades, with photostabilizer formulation complexity adding further differentiation layers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that dominate avobenzone procurement. Three-tier pricing structure across pharmaceutical-grade, cosmetic-grade, and technical-grade levels reflects photostability certification thresholds and REACH compliance documentation depth. Cost compression in mid-tier cosmetic-grade supply is intensifying because contract manufacturers are consolidating volume commitments to secure volume discounts. Mid-tier cosmetic brands exhibit highest price sensitivity due to working capital constraints, while multinational dermocosmetic houses prioritize photostability performance over unit cost.
Supply Chain Analysis
Asset-light contract manufacturing platforms in Germany, China, and South Korea hold the majority of formulation capacity serving mid-tier cosmetic brands. Feedstock supply draws from benzene derivatives sourced through BASF SE's integrated Ludwigshafen complex and acetone supply chains anchored in Rotterdam and Singapore petrochemical hubs. Single-source vulnerability concentrates in octocrylene photostabilizer supply, where three specialty chemical houses control global production. Distribution runs through regional cosmetic ingredient distributors with technical service capabilities, bypassing traditional commodity chemical trading channels for formulated grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Avobenzone competitive advantage hinges on scarce formulation chemistry expertise for photostabilization in water-resistant matrices, creating defensive moats for incumbents with senior cosmetic chemist teams and acquisition opportunities for investors targeting specialized emulsion technology assets.
For Market Incumbents: Build patent-protected encapsulation moats around silica-shell and lipid-matrix delivery systems that eliminate octocrylene dependency. Secure backward integration into dibenzoylmethane intermediates to insulate margins from benzene derivative volatility. Acquire boutique formulation houses in Seoul Capital Area and Paris-region clusters to capture clean-label R&D talent before regulatory deadlines force accelerated reformulation cycles. For New Entrants and Emerging Players: Pediatric spray formulations in Germany and Australia represent underpenetrated white-space where convenience positioning justifies premium pricing despite FDA inhalation exposure scrutiny. Target telehealth-integrated skincare platforms in United States with dermatologist-formulated subscription models that bypass traditional pharmacy channel gatekeepers. Lead with reef-safe certification and benzophenone-free positioning to capture search-based discovery among younger demographics. For Investors and Strategic Acquirers: The market sits at a regulatory-escalation phase that favors acquisition of specialized emulsion technology firms with ECHA-compliant hazard data packages. Long-term viability centers on photostabilizer-free innovation pipelines and REACH-authorized manufacturing assets. Watch for FDA monograph modernization rulings on systemic absorption thresholds as the critical signal for which formulation technologies receive market access clearance.| Strategic Initiative | Industry Significance |
|---|---|
| Photostabilizer-Free Encapsulation Patent Filing | Silica-shell delivery systems from Seoul labs eliminate octocrylene dependency for clean-label positioning. |
| REACH Authorization Data Package Investment | ECHA-compliant mechanistic toxicology studies secure uninterrupted European market access ahead of regulatory deadlines. |
| Asset-Light Contract Manufacturing Partnership | Toll manufacturing platforms lower capital barriers for mid-tier brands entering avobenzone supply chains. |
| Backward Integration into Dibenzoylmethane Intermediates | Captive benzene derivative supply insulates margin compression from crude oil-indexed feedstock volatility. |
| Dermatology Clinic Channel Direct Distribution | Professional-dispensed positioning in United States and Australian clinics commands premium pricing with clinical endorsement. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA monograph dockets, ECHA REACH authorization timelines, and customs trade data for benzene derivative flows. Primary interviews engaged cosmetic formulation chemists, procurement directors at multinational dermocosmetic houses, contract manufacturing executives, and pharmacy chain category managers. Secondary validation drew from SEC filings of integrated chemical conglomerates, MFDS sunscreen active registrations, and ANSM cosmetics safety assessments. Bottom-up volume estimates from grade-specific consumption patterns were triangulated against top-down market sizing from feedstock demand modeling.
Forecast inputs span product type segmentation across lotions, sprays, creams, and gels; application segmentation across sunscreen, skincare, cosmetics, and haircare; and end-user segmentation across cosmetic manufacturers, individuals, dermatology clinics, and salons. CAGRs were derived from regression analysis of historical volume trends against regulatory event timing and reformulation cycle frequencies. Industry-specific inputs include REACH authorization timeline probability distributions and FDA monograph modernization scenario weights.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Asian scale manufacturers or specialty encapsulation technology entrants would shift outcomes through accelerated price competition or premium-tier disruption. Quarterly review of ECHA endocrine-disrupting potential assessment progress and FDA supplemental safety data submissions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Automotive Silicone Market
Specialty Chemicals
Fatliquoring Agents Market
Specialty Chemicals
Perms and Relaxants Market
Specialty Chemicals
Global Photoacid Generators Market
Specialty Chemicals
Global Salicylic Acid Market
Specialty Chemicals
Chevron Seals Market
Specialty Chemicals
Europe Optical Brighteners Market
Specialty Chemicals
Croscarmellose Sodium Market
Specialty Chemicals
Cholesteryl Isostearate Market
Specialty Chemicals
Inorganic Flame Retardants Market
Specialty Chemicals
Bio-Wax Market
Specialty Chemicals
Specialty Oxidants Market
Specialty Chemicals
Lanolin Market
Specialty Chemicals
Global 28-Homobrassinolide Market
Specialty Chemicals
Global Immersion Oil Market
Specialty Chemicals
Natural Insect Repellent Market