
 Cloud Workload Protection Market | 2026-2036
Cloud Workload Protection Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Workload Protection Market Intelligence
The strategic divergence between agent-based and agentless security development is bifurcating the market's vendor landscape. This split separates vendors focused on deep endpoint visibility from those prioritizing broad, frictionless cloud asset discovery. CrowdStrike leverages its single-agent architecture to deliver integrated threat detection and response capabilities. In contrast, Orca Security specializes in agentless scanning, providing comprehensive visibility across the entire cloud estate without performance overhead.
Cloud Workload Protection encompasses security solutions designed to protect applications and data within virtual machines, containers, and serverless functions across any cloud environment. These platforms provide runtime security by monitoring process execution, file integrity, and network communication to block malicious activity in real-time. The hybrid cloud deployment model sees significant investment as enterprises seek unified security across on-premises and public cloud assets. Within solution types, threat detection and vulnerability management remain the largest segments, driven by the need for proactive risk reduction.
Regulatory frameworks significantly influence product requirements and purchasing decisions. The EU's GDPR imposes strict controls on personal data processing, necessitating solutions with strong compliance monitoring capabilities. In the United States, regulations like HIPAA mandate specific security controls for protecting health information in cloud environments, while standards from the ISO provide a global benchmark for security management. The key decision for enterprises is whether to consolidate security functions onto a single platform or pursue a best-of-breed approach for specialized workload types.
Market Dynamics
The central dynamic shaping the market is the strategic bifurcation between agent-based and agentless security philosophies. This divide influences vendor development priorities, go-to-market strategies, and enterprise adoption patterns across different cloud maturity levels and risk appetites.
Growth Catalysts
- Regulatory Mandates:The EU's GDPR is compelling enterprises to implement auditable data protection controls, directly driving investment in CWP solutions that can monitor data processing across complex hybrid cloud environments.
- Telecommunications Sector Adoption:Demand from telecommunications firms is accelerating as they deploy containerized network functions, which require specialized, high-performance security solutions capable of operating within orchestrated environments like Kubernetes.
- DevOps Integration:Widespread adoption of DevOps practices, particularly in the United States, necessitates embedding security earlier in the development lifecycle, making CWP tools for vulnerability scanning and runtime protection essential components of CI/CD pipelines.
Market Restraints
- Performance Overhead:Agent-based security solutions can introduce performance latency and increase resource consumption on host systems, meeting resistance from development teams focused on application performance and stability.
- Complex Pricing Models:Opaque and variable pricing structures, often tied to vCPUs, memory usage, or data throughput, create budget uncertainty for enterprises and act as a barrier to large-scale, predictable deployments.
- Cloud Native Tool Substitution:Security tools embedded within major cloud platforms, such as AWS GuardDuty or Microsoft Defender for Cloud, offer a convenient and often lower-cost alternative, posing a substitution threat for less critical workloads.
Strategic Opportunities
- Serverless Security:Protecting ephemeral, event-driven serverless functions represents a significant growth vector for vendors that can provide specialized, low-latency security solutions without impacting function execution time or cost.
- SME Market Penetration:Small and medium-sized enterprises in developing economies, particularly in Southeast Asia, remain an underpenetrated segment, creating an opportunity for vendors offering simplified, cost-effective, and easy-to-deploy CWP solutions.
- CNAPP Convergence:The integration of CWP with Cloud Security Posture Management (CSPM) and other capabilities into a unified Cloud-Native Application Protection Platform (CNAPP) presents a major opportunity to consolidate security functions and provide holistic visibility.
Industry Challenges
- Cloud Security Skills Gap:A persistent shortage of security professionals with combined expertise in cloud architecture, container orchestration, and threat analysis creates a significant operational challenge for adopting and managing advanced CWP platforms.
- Multi-Cloud Integration Complexity:Integrating a single CWP solution across heterogeneous multi-cloud and hybrid environments, each with unique APIs and configurations, presents substantial technical and operational hurdles for security teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Workload Protection Market |
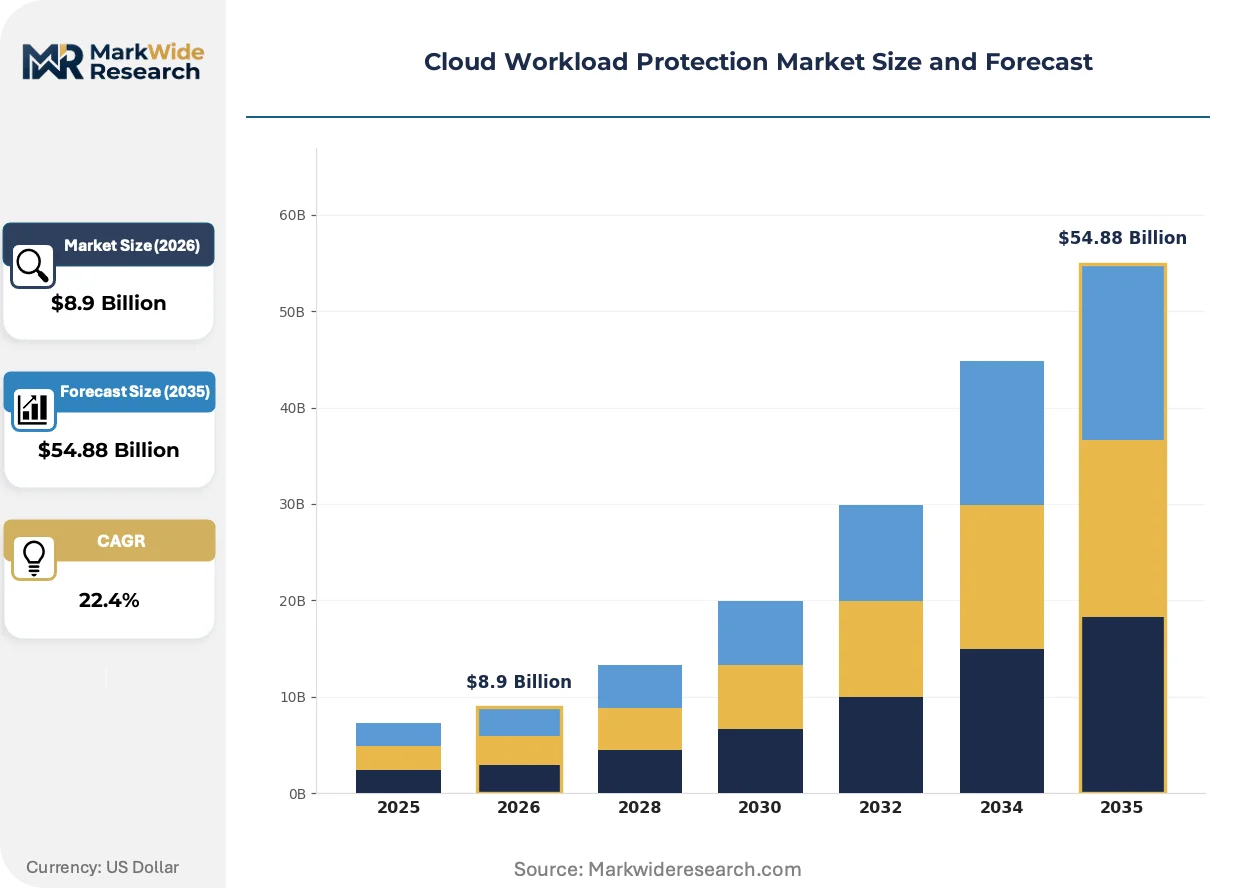
| Market Size in 2026 | $8.9 Billion |
| Market Size in 2035 | $54.88 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud, Community Cloud Solution Type: Threat Detection, Vulnerability Management, Compliance Monitoring, Identity Access Management, Behavioral Analytics Use Case: Data Protection, Application Security, Network Security, Incident Response, Configuration Management End User Industry: Telecommunications, Government Agencies, Educational Institutions, Media & Entertainment, Energy & Utilities |
| Companies Covered | Palo Alto Networks, Microsoft, Trend Micro, CrowdStrike, SentinelOne, Broadcom, Orca Security, Wiz, Check Point Software Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Workload Protection Market Strategic Shifts & Innovations
The evolution of cloud-native development is forcing a fundamental re-evaluation of security paradigms. Protection is shifting away from static, perimeter-based controls toward dynamic, context-aware security embedded directly within the application lifecycle and infrastructure.
Extended Berkeley Packet Filter (eBPF) technology provides deep kernel-level observability and security enforcement without requiring code modification. Cloud-native organizations are adopting eBPF-based tools for runtime security and network monitoring. This powerful, low-overhead approach is fragmenting the traditional agent-based security market by offering a more efficient alternative for container and Kubernetes environments.
Enforcement of the United States' HIPAA Security Rule is becoming more stringent for protecting health information in cloud settings. This trend compels healthcare organizations to implement CWP solutions that provide continuous monitoring, vulnerability management, and auditable logs for compliance. The vulnerability management and threat detection segments are most affected, as providers must demonstrate proactive risk reduction.
A behavioral change is emerging as enterprises pivot from single-vendor platform consolidation for all cloud security needs. Instead, security teams are adopting a best-of-breed strategy, choosing specialized CWP tools for critical workloads like containers while using native cloud provider tools for less sensitive assets. This trend is most visible in the financial services sector in North America, where risk stratification dictates security tool selection.
Cloud Workload Protection Market Segmentation
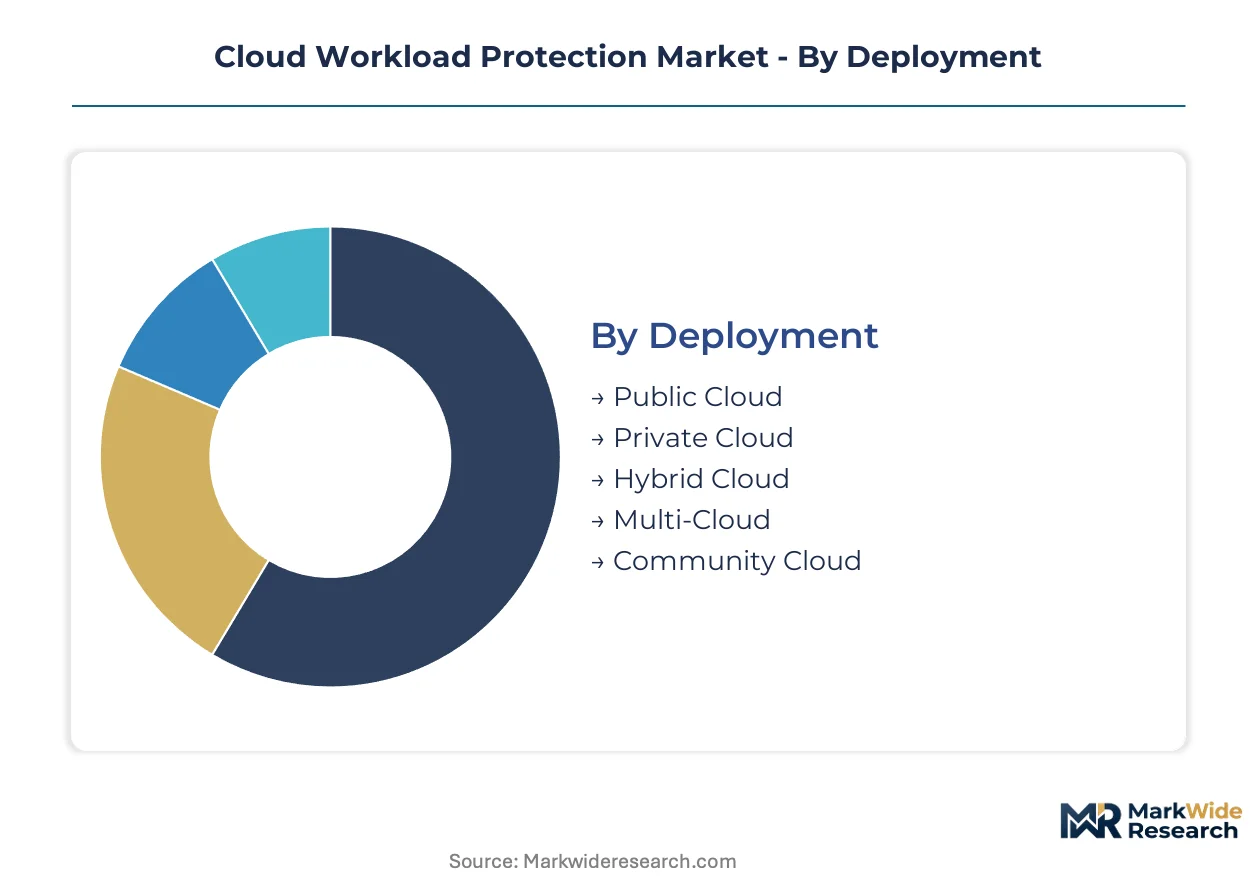
Cloud Workload Protection (CWP) market segmentation reveals distinct approaches to securing diverse cloud environments and applications. Understanding these segments helps enterprises align security investments with specific operational needs and compliance mandates. The market's complexity stems from varied deployment models and the specialized nature of security solutions.
Deployment:
The geographic distribution of cloud infrastructure often dictates the preferred CWP deployment models, with some regions favoring localized private clouds while others embrace distributed public cloud assets.
- Hybrid Cloud:This model integrates on-premises infrastructure with public cloud services, creating a unified environment for workloads. Enterprises in Germany and France adopt hybrid cloud for sensitive data residency requirements, balancing control with scalability.
- Multi-Cloud:Multi-cloud deployments involve using services from multiple public cloud providers simultaneously, enhancing resilience and avoiding vendor lock-in. North American financial institutions leverage multi-cloud strategies to diversify risk and optimize workload placement across different hyperscalers.
- Public Cloud:Workloads run entirely on third-party cloud infrastructure, offering high scalability and reduced operational overhead.
- Private Cloud:Dedicated cloud infrastructure managed by a single organization, providing enhanced control and security for critical data.
- Community Cloud:Shared cloud infrastructure for organizations with common concerns, such as specific security or compliance requirements.
Hybrid Cloud holds the largest share; momentum sits with Multi-Cloud.
Solution Type:
The application of CWP solutions varies significantly, addressing different stages of the security lifecycle from proactive identification to real-time defense against threats.
- Threat Detection:These solutions identify and alert on malicious activities, intrusions, and anomalies within cloud workloads in real-time. Organizations in the United States prioritize advanced threat detection to combat sophisticated cyber-attacks targeting public cloud infrastructure.
- Vulnerability Management:This segment focuses on identifying, assessing, and remediating security weaknesses in software, configurations, and infrastructure. European enterprises leverage vulnerability management tools to maintain continuous compliance with GDPR requirements.
- Compliance Monitoring:Tools that continuously assess cloud environments against regulatory standards and internal policies.
- Identity Access Management:Solutions that manage and control user access to cloud resources and applications.
- Behavioral Analytics:These systems analyze user and entity behavior to detect unusual patterns indicative of potential threats.
Threat Detection leads the market, while Vulnerability Management is expanding most quickly.
Use Case:
The maturity level of an organization's cloud adoption often dictates which CWP use cases receive the most investment, ranging from foundational data protection to advanced incident response.
- Data Protection:Solutions securing sensitive information stored and processed within cloud environments, including encryption, data loss prevention, and access controls. Financial services firms in Singapore prioritize data protection to meet stringent regulatory requirements and customer trust.
- Application Security:Focuses on protecting applications throughout their lifecycle, from development to runtime, against vulnerabilities and attacks. Technology companies in Ireland integrate application security into DevOps pipelines to secure their containerized microservices.
- Network Security:Safeguards network traffic and connectivity within and between cloud workloads and external networks.
- Incident Response:Provides tools and processes to detect, analyze, and mitigate security incidents effectively.
- Configuration Management:Ensures cloud resource configurations adhere to security best practices and compliance policies.
Data Protection forms the foundational element, with Application Security demonstrating significant future potential.
End User Industry:
The volume of cloud workloads and the criticality of data processed within different industries significantly influence their demand for specialized Cloud Workload Protection solutions.
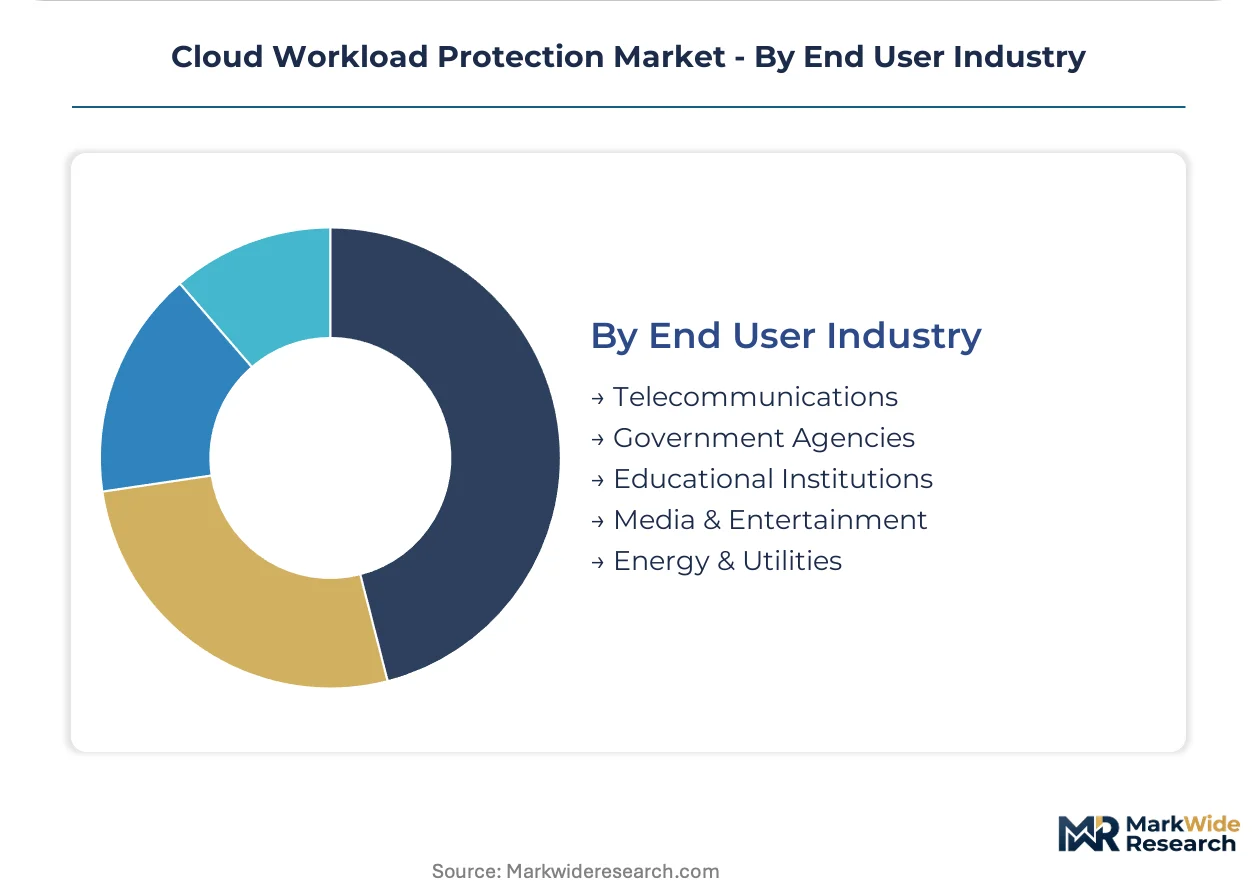
- Telecommunications:This sector utilizes CWP to secure containerized network functions and core infrastructure, ensuring high availability and compliance. Major telecom operators in the United Kingdom invest heavily in CWP for 5G network security and data privacy.
- Government Agencies:Public sector entities require robust CWP to protect classified data, citizen information, and critical national infrastructure. Federal agencies in the United States implement stringent CWP controls to meet NIST guidelines and safeguard sensitive government assets.
- Educational Institutions:Secure student data, research projects, and online learning platforms from cyber threats.
- Media & Entertainment:Protect digital content, intellectual property, and streaming platforms from unauthorized access and piracy.
- Energy & Utilities:Safeguard operational technology (OT) and critical infrastructure from cyber-physical attacks and data breaches.
Telecommunications represents a dominant customer base, and Government Agencies is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Cloud Workload Protection Market exhibits a varied landscape where countries with advanced public cloud infrastructure and robust regulatory frameworks often drive demand, while regions with emerging digital economies are rapidly increasing their adoption of security solutions. This dynamic creates a complex interplay of import and export of security technologies and expertise across different geographies.
United States
Extensive public cloud infrastructure and early adoption of DevOps practices create high demand for Cloud Workload Protection solutions in the United States. Regulations like HIPAA mandate stringent security controls for protecting health information in cloud environments, driving specific product requirements. Major technology hubs such as Silicon Valley and Seattle concentrate innovation in cloud security, fostering a competitive vendor ecosystem.
Germany
Enterprises in Germany prioritize hybrid cloud deployments for sensitive data residency requirements, balancing control with scalability. The EU's GDPR imposes strict controls on personal data processing, necessitating solutions with strong compliance monitoring capabilities. Industrial powerhouses in Bavaria and North Rhine-Westphalia invest in CWP to secure their critical operational technology and manufacturing data.
Singapore
Financial services firms in Singapore prioritize data protection to meet stringent regulatory requirements and uphold customer trust. The Monetary Authority of Singapore (MAS) guidance on cloud computing security influences purchasing decisions for CWP solutions. Singapore's role as a regional data center hub further concentrates demand for advanced cloud security platforms.
United Kingdom
Major telecom operators in the United Kingdom invest heavily in CWP for 5G network security and data privacy, driven by the need to secure containerized network functions. The UK's data protection regulations, aligned with GDPR principles, compel enterprises to implement auditable data protection controls. London's financial district and technology sector drive significant CWP adoption for compliance and threat mitigation.
Japan
Advanced digital transformation initiatives and a focus on data integrity fuel demand for Cloud Workload Protection in Japan. METI guidelines for cloud security influence enterprise adoption, emphasizing robust data governance and threat detection. Technology clusters in Tokyo and Osaka are at the forefront of integrating CWP into modern IT architectures.
Cloud Workload Protection Market Key Industry Players
Concentration sits with established cybersecurity vendors and cloud-native specialists, creating a tiered market structure. This market features a mix of broad platform providers and niche innovators. Strategic archetypes include comprehensive platform providers, specialized cloud-native security firms, and traditional security vendors adapting to cloud environments. Competitive moves often involve strategic partnerships to integrate disparate security functions and continuous portfolio diversification to address new cloud risks.
Within the cloud-native security segment, Orca Security exemplifies an agentless approach, providing comprehensive visibility across entire cloud estates without performance overhead. CrowdStrike represents a leader in the agent-based security model, leveraging its single-agent architecture for integrated threat detection and response. Microsoft, as a major hyperscaler, occupies a position offering embedded cloud-native tools, posing a substitution threat for less critical workloads.
| Leading Market Players |
|---|
| Palo Alto Networks |
| Microsoft |
| Trend Micro |
| CrowdStrike |
| SentinelOne |
| Broadcom |
| Orca Security |
| Wiz |
| Check Point Software Technologies |
| Others |
Cost & Logistics Intelligence
Cloud infrastructure scale economies directly influence vendor development costs, which in turn shape competitive pricing and entry barriers. This dynamic creates a tiered market where large platform providers can offer integrated solutions at lower price points.
Pricing Analysis
Enterprise buyers anchor a subscription-tiered pricing model for Cloud Workload Protection solutions. Price differentiation stems from customization levels for complex multi-cloud environments and the breadth of after-sales service and support. Pricing softness reflects intense competition from cloud-native tools embedded within hyperscaler platforms. Financial institutions and government agencies exhibit the least price sensitivity due to stringent compliance and data protection mandates.
Supply Chain Analysis
The United States and Western Europe anchor the software development and innovation supply for Cloud Workload Protection. The market draws from a global talent pool of cybersecurity professionals and relies heavily on hyperscaler cloud infrastructure for deployment. Vendor supply chains face structural risk from the persistent cloud security skills gap. Distribution runs through a mix of direct sales channels, strategic channel partners, and cloud marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Cloud Workload Protection market is undergoing a platform-economics inflection, driven by the convergence of disparate cloud security functions into unified Cloud-Native Application Protection Platforms (CNAPP).
For Market Incumbents: Compound existing agent-based capabilities by integrating advanced eBPF-based runtime security for Kubernetes environments. Deepen strategic partnerships with major hyperscalers to counter the threat of cloud-native tool substitution. Invest heavily in R&D for serverless function protection to maintain a competitive edge. Expand channel control through managed security service provider alliances.
For New Entrants and Emerging Players: Anchor in specialized niches like serverless security or highly regulated industries requiring specific compliance monitoring capabilities. Target the underpenetrated SME market in developing economies, particularly Southeast Asia, with simplified, cost-effective solutions. A go-to-market angle focused on frictionless agentless deployment and rapid time-to-value will resonate with smaller enterprises. Leverage open-source security frameworks for faster innovation cycles.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized cloud-native security firms with strong intellectual property in emerging areas like eBPF or behavioral analytics. Long-term viability rests on the continued expansion of cloud adoption and the increasing complexity of cloud-native architectures. The signal to watch is the rate of CNAPP platform consolidation, indicating market maturity and potential acquisition targets.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Firm | Integrates niche cloud-native capabilities, accelerating time-to-market for advanced security features. |
| Platform Integration | Unifies disparate security functions into a comprehensive CNAPP offering, enhancing customer value. |
| Geographic Expansion | Penetrates underserved markets like Southeast Asia, capturing new customer segments. |
| Product Launch | Introduces innovative serverless security solutions, addressing a critical emerging workload type. |
| Strategic Partnership | Strengthens ecosystem ties with hyperscalers, improving market access and product compatibility. |
Research Approach
A standing panel of CISOs, cloud architects, DevOps engineers, and security compliance officers provided ongoing calibration and validation for this market analysis. The research combined extensive primary interviews with industry stakeholders and rigorous secondary validation. Secondary data sources included regulatory filings, industry association reports, academic cybersecurity journals, and hyperscaler documentation, triangulated through both bottom-up and top-down approaches.
Output validation against external benchmarks ensured the analytical framework's robustness across the projection horizon. Segmentation dimensions modeled included deployment model, solution type, use case, end-user industry, and regional cloud maturity. Compound annual growth rates were derived from historical trends, current market dynamics, and future projections. Key forecast inputs included global cloud adoption rates, evolving regulatory changes, and enterprise cybersecurity spending trends.
Material uncertainties — including rapid technological disruptions or unforeseen geopolitical events — sit outside the modeled envelope, influencing future market trajectories. Forecasts reflect assumptions documented through a rigorous validation process. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Middle East and Africa Cybersecurity Market
Cybersecurity
Latin America IoT Security Market
Cybersecurity
SOC As a Service Market
Cybersecurity
Cloud Access Security Broker Market
Cybersecurity
Network Sandboxing Market
Cybersecurity
Middle East & Africa AI Cybersecurity Market
Cybersecurity
Morocco Cybersecurity Market
Cybersecurity
Web Filtering Market
Cybersecurity
Cloud Security in Banking Market
Cybersecurity
Cloud Security Market
Cybersecurity
Europe Data Exfiltration Market
Cybersecurity
Global Bug Bounty Platforms Market
Cybersecurity
Network Edge Security Solutions Market
Cybersecurity
Botnet Detection Market
Cybersecurity
Global Serverless Security Market
Cybersecurity
AI in Cybersecurity Market