
 Middle East & Africa AI Cybersecurity Market | 2026-2036
Middle East & Africa AI Cybersecurity Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East & Africa AI Cybersecurity Market Insights
Platform licensing revenue is fragmenting across endpoint security, cloud security, and managed services as vendors compete for recurring subscription income. Microsoft Corporation leverages its Azure cloud footprint to anchor hybrid deployment models across Gulf enterprise accounts. Palo Alto Networks, Inc. specializes in network security consolidation for financial institutions navigating stricter central bank protocols. Darktrace plc differentiates through autonomous response technology that reduces mean-time-to-detect in oil and gas operational technology environments.
Middle East & Africa AI cybersecurity encompasses machine learning and behavioral analytics systems engineered to detect, classify, and neutralize cyber threats in real time without human intervention, typically processing millions of events per second across distributed architectures. These systems serve primarily to protect critical infrastructure, financial transaction networks, and government digital services against evolving attack vectors including zero-day exploits and insider threats. Cloud security deployments are gaining share fastest as Saudi and Emirati enterprises migrate workloads from on-premises data centers to sovereign cloud instances. Network security retains the largest installed base but faces margin compression as commoditized firewall appliances give way to AI-enabled threat intelligence platforms. Behavioral analytics represents the emerging technology layer where vendors compete on algorithmic accuracy in identifying anomalous user patterns.
Saudi Arabia's National Cybersecurity Authority and the UAE's Telecommunications and Digital Government Regulatory Authority enforce mandatory incident reporting and critical infrastructure protection standards that directly shape procurement specifications for AI security platforms. South Africa's Protection of Personal Information Act and Kenya's Data Protection Act add compliance complexity for cross-border cloud deployments, favoring vendors with localized data residency architectures. Stakeholders must monitor how Gulf sovereign wealth fund investments in domestic AI research capacity alter vendor selection criteria away from global providers toward homegrown solutions.
Market Dynamics
Gulf sovereign wealth funds are redirecting procurement criteria toward domestic AI research capacity, forcing global cybersecurity vendors to establish local R&D presences or risk exclusion from critical infrastructure contracts.
Growth Catalysts
- Saudi Arabia's NCA mandates:Mandatory incident reporting and critical infrastructure protection standards are compelling oil and gas operators to deploy autonomous threat detection systems across operational technology environments.
- Smart city buildouts:Saudi and Emirati urban digitalization initiatives require security orchestration platforms capable of processing millions of events per second across distributed municipal architectures.
- Behavioral analytics maturation:Machine learning algorithms identifying anomalous user patterns are displacing signature-based detection in financial institutions navigating stricter central bank protocols.
Market Restraints
- Specialized talent scarcity:Shortages of cybersecurity engineers fluent in both Arabic compliance frameworks and machine learning operations constrain deployment velocity across Gulf enterprise accounts.
- Data residency architectures:South Africa's Protection of Personal Information Act and Kenya's Data Protection Act fragment cloud security procurement, favoring vendors with localized infrastructure over global platforms.
- Commoditized firewall margins:Traditional network security appliances face price compression as AI-enabled threat intelligence platforms capture budget allocation from hardware refresh cycles.
Strategic Opportunities
- Operational technology convergence:AI cybersecurity platforms are hybridizing with industrial control systems in Saudi Aramco and ADNOC facilities, creating integrated safety-security procurement bundles.
- Fintech ecosystem expansion:Dubai International Financial Centre and Riyadh's fintech hub require real-time transaction monitoring systems, opening specialized vendor opportunities.
- Sovereign cloud migration:UAE and Saudi enterprises shifting workloads from on-premises data centers to state-controlled cloud instances demand security architectures designed for hybrid sovereignty models.
Industry Challenges
- Algorithmic audit requirements:Central banks and telecommunications regulators increasingly demand explainable AI in security decision-making, complicating black-box neural network deployments.
- Legacy system integration friction:Oil and gas operational technology environments running decades-old SCADA architectures resist seamless API connectivity with cloud-native security platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East & Africa AI Cybersecurity Market |
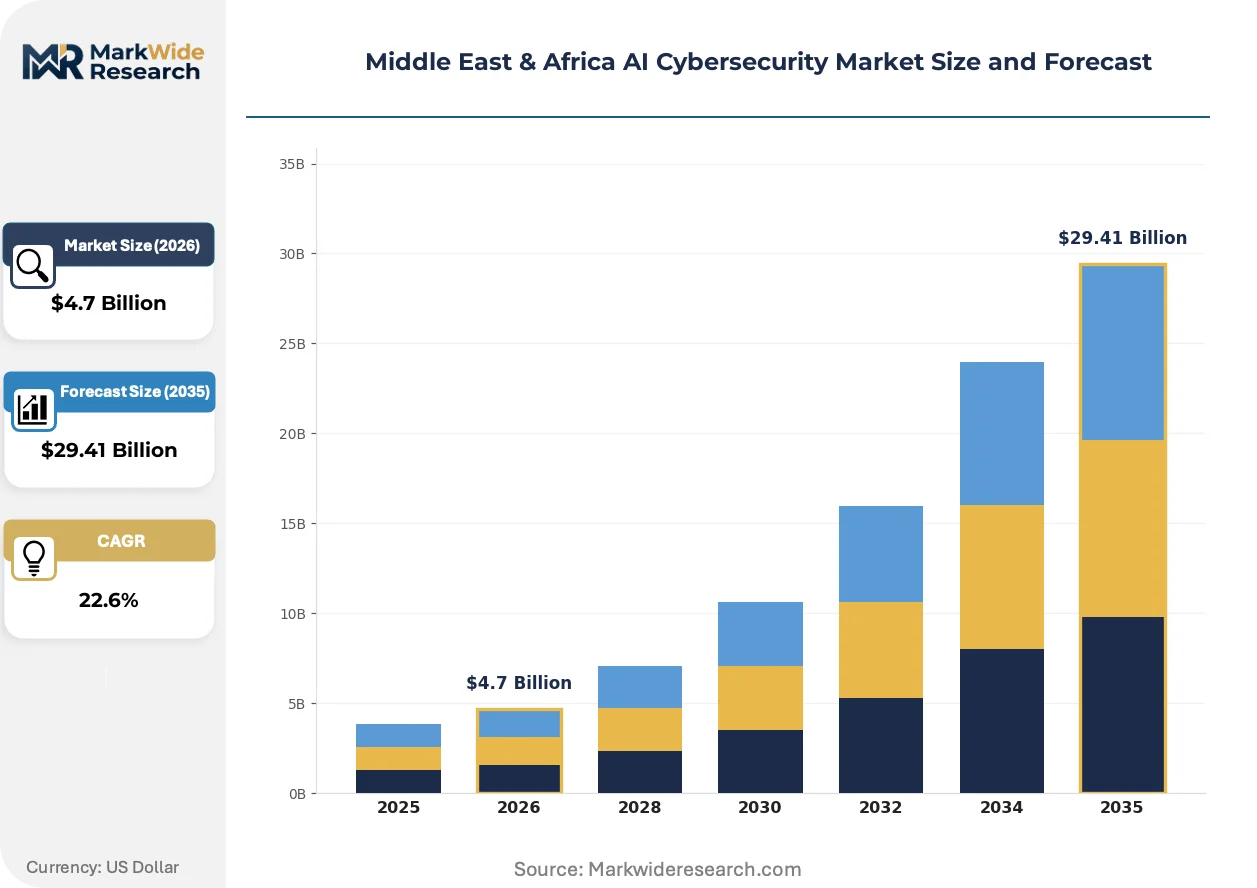
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $29.41 Billion |
| CAGR (2026 – 2036) | 22.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endpoint Security, Network Security, Cloud Security, Application Security Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Services End User: Government, BFSI, Healthcare, Retail Technology: Machine Learning, Natural Language Processing, Predictive Analytics, Behavioral Analytics |
| Companies Covered | Microsoft Corporation, Amazon Web Services, Inc., Cisco Systems, Inc., IBM Corporation, Palo Alto Networks, Inc., Fortinet, Inc., Check Point Software Technologies Ltd., Darktrace plc, NVIDIA Corporation, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East & Africa AI Cybersecurity Market Trends and Innovations
Autonomous response capabilities are compressing mean-time-to-detect metrics across critical infrastructure, while regulatory mandates in the Gulf and South Africa reshape vendor qualification criteria.
Extended detection and response platforms are hybridizing machine learning pipelines with human analyst workflows, enabling security operations centers in Dubai and Riyadh to triage alert volumes that previously required tenfold staffing. Financial institutions under UAE central bank supervision are adopting these systems fastest, with deployment timelines compressing from eighteen months to six months. The technology is hybridizing competitive positioning by rewarding vendors with pre-trained regional threat models over generic global datasets.
Saudi Arabia's National Cybersecurity Authority and the UAE's Telecommunications and Digital Government Regulatory Authority are tightening mandatory certification pathways for AI security platforms serving critical infrastructure operators. These frameworks now require documented algorithmic bias testing and localized data processing capabilities as preconditions for procurement eligibility. Vendors without Gulf-based security operations centers are restructuring partnership strategies to meet residency and response-time requirements.
Chief information security officers in Johannesburg and Cape Town are unbundling managed detection and response services from platform licensing, creating direct procurement relationships with specialized threat-hunting boutiques. This pattern disrupts the traditional systems-integrator channel that dominated enterprise security sales across sub-Saharan Africa. The shift is most visible in mining and logistics verticals where board-level cyber risk accountability has sharpened vendor performance scrutiny.
Middle East & Africa AI Cybersecurity Market Segmentation
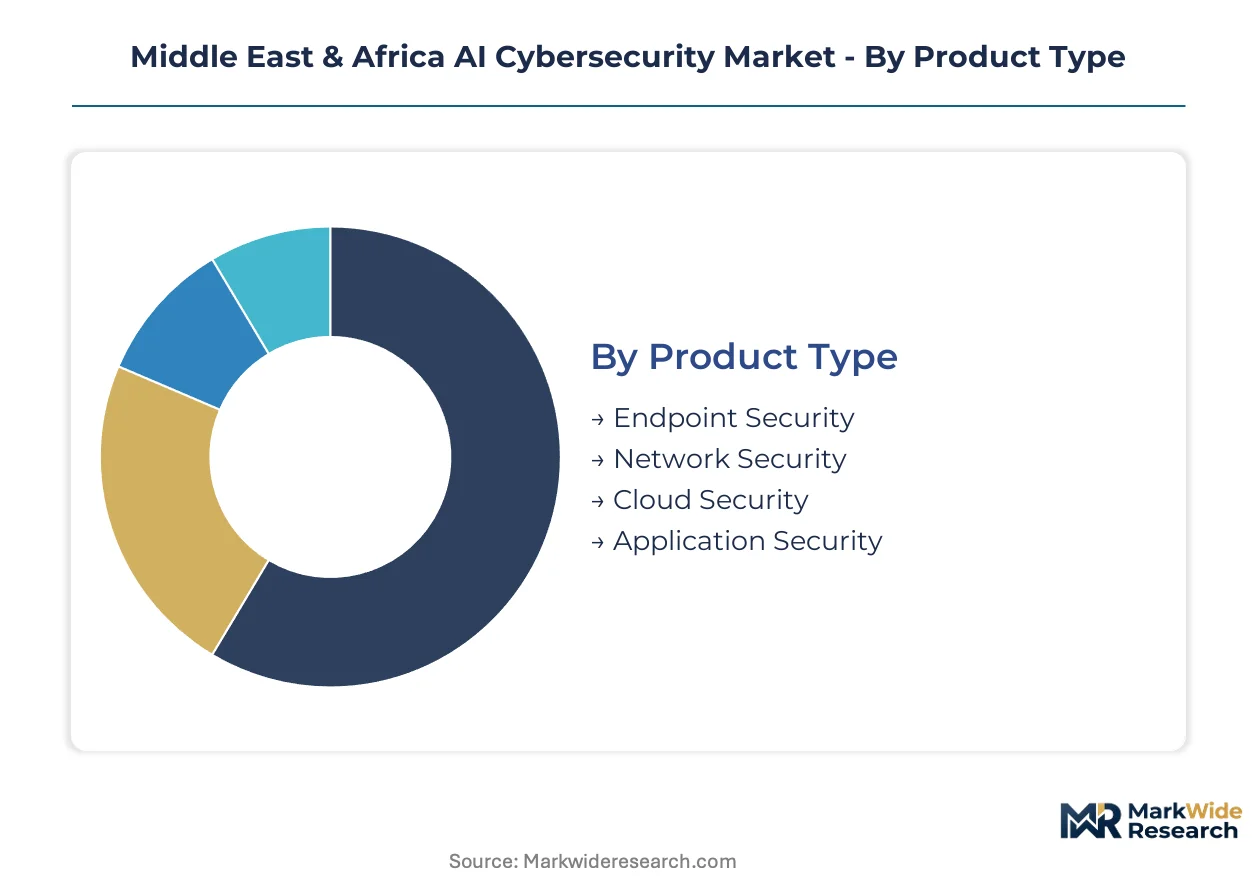
AI cybersecurity procurement across the Middle East and Africa fragments across four critical dimensions: product architecture, infrastructure placement, institutional buyer type, and underlying algorithmic engine. Each segmentation axis carries distinct regulatory, technical, and commercial imperatives that reshape vendor positioning in Saudi Arabia, the UAE, and South Africa.
Product Type:
Mature perimeter defenses coexist with emerging autonomous platforms as Gulf enterprises balance legacy refresh against cloud-native migration.
- Endpoint Security:Agent-based detection systems deploy across distributed workforces in Saudi Aramco and ADNOC facilities, where operational technology convergence demands real-time device-level threat containment. Procurement concentrates in oil and gas verticals navigating NCA mandates for critical infrastructure protection.
- Cloud Security:Workload protection platforms process millions of events per second across sovereign cloud instances in UAE and Saudi data centers. Dubai International Financial Centre fintechs drive fastest adoption as central bank protocols tighten cross-border data governance requirements.
- Network Security:AI-enabled threat intelligence layers displace commoditized firewall appliances in enterprise refresh cycles.
- Application Security:Runtime protection integrates with DevOps pipelines serving Riyadh's smart city buildouts.
Network security retains volume leadership; cloud security holds the steepest expansion curve.
Deployment Model:
Cost tier differentiation separates capital-intensive on-premises builds from operational expenditure models favoring recurring subscription revenue.
- Cloud-Based:Pure SaaS architectures eliminate data center overhead for mid-market enterprises in Johannesburg and Cape Town. South Africa's Protection of Personal Information Act constrains vendor selection to providers with localized processing nodes.
- Hybrid:Split workloads span on-premises SCADA systems and sovereign cloud instances in Saudi critical infrastructure. ADNOC and Saudi Aramco procurement bundles favor this model for operational technology convergence.
- On-Premises:Air-gapped deployments persist in defense and intelligence sectors with strict data residency mandates.
- Managed Services:Outsourced security operations centers address specialized talent scarcity across Gulf enterprise accounts.
Hybrid deployments capture the largest project values; cloud-based solutions are expanding most quickly.
End User:
Customer type segmentation reflects divergent risk appetites and regulatory exposure across institutional buyers.
- Government:National cybersecurity authorities in Saudi Arabia and the UAE mandate autonomous threat detection for digital service delivery. Procurement specifications require documented algorithmic bias testing and Gulf-based security operations centers.
- BFSI:Real-time transaction monitoring systems process high-velocity payments across Dubai International Financial Centre and Riyadh fintech hubs. UAE central bank supervision drives eighteen-to-six-month deployment compression timelines.
- Healthcare:Patient data protection requirements intersect with MOHAP and SFDA compliance frameworks in Emirates and Saudi facilities.
- Retail:Point-of-sale protection addresses payment card industry standards in South African and Kenyan markets.
Government verticals dominate absolute spending; BFSI applications gain share fastest.
Technology:
Algorithmic maturity separates production-grade machine learning from experimental natural language processing implementations.
- Machine Learning:Supervised and unsupervised models form the operational backbone of production security platforms across Gulf critical infrastructure. Pre-trained regional threat models outperform generic global datasets in Dubai and Riyadh security operations centers.
- Behavioral Analytics:Anomalous user pattern identification displaces signature-based detection in financial institutions navigating stricter central bank protocols. Algorithmic audit requirements from telecommunications regulators complicate black-box neural network deployments.
- Natural Language Processing:Phishing detection and threat intelligence parsing remain secondary to core detection engines.
- Predictive Analytics:Forecasting models anticipate attack vectors in smart city municipal architectures.
Machine learning retains technical dominance; behavioral analytics climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia consumes AI cybersecurity as sovereign capability infrastructure, while the UAE treats it as financial services enabler and South Africa deploys it for compliance-driven enterprise protection. This consumption-mix differential shapes divergent procurement specifications across the region.
Saudi Arabia
National oil companies and smart city developers drive autonomous threat detection procurement at scale. The National Cybersecurity Authority mandates critical infrastructure protection standards that require documented algorithmic bias testing. Riyadh and the Eastern Province concentrate deployment, with Saudi Aramco facilities integrating AI security into operational technology convergence bundles.
United Arab Emirates
Dubai International Financial Centre fintechs and sovereign cloud migration projects compress deployment timelines from eighteen to six months. The Telecommunications and Digital Government Regulatory Authority enforces mandatory certification pathways with localized data processing requirements. Abu Dhabi anchors government and energy sector procurement, while Dubai leads financial services adoption.
South Africa
Johannesburg and Cape Town enterprises unbundle managed detection services from platform licensing to address board-level cyber risk accountability. The Protection of Personal Information Act fragments cloud security procurement toward vendors with localized infrastructure nodes. Mining and logistics verticals concentrate demand as specialized threat-hunting boutiques disrupt traditional systems-integrator channels.
Israel
Defense and intelligence sectors sustain air-gapped deployment demand for strict data residency mandates. The national cyber directorate shapes procurement specifications for autonomous response capabilities in critical infrastructure. Tel Aviv's technology cluster feeds algorithmic innovation into regional threat models deployed across Gulf security operations centers.
Egypt
Government digital service delivery and banking sector modernization drive initial AI security platform adoption. The central bank and telecommunications regulator tighten supervision of cross-border data flows affecting cloud security vendor selection. Cairo concentrates deployment as public sector entities navigate compliance complexity for hybrid sovereignty models.
Middle East & Africa AI Cybersecurity Market Competitive Landscape
Capability concentration sits with specialized autonomous response vendors; scale advantage sits with hyperscale cloud providers anchoring hybrid deployment models. The market structures around three tiers: global platforms with sovereign cloud integration, network security consolidators serving financial institutions, and behavioral analytics specialists reducing mean-time-to-detect in operational technology environments. Dominant competitive moves include establishing Gulf-based security operations centers to meet residency requirements and restructuring partnership strategies around localized R&D presences.
Among cloud-platform providers, Microsoft Corporation and Amazon Web Services, Inc. exemplify the scale-driven tier leveraging existing data center footprints to anchor hybrid workloads. Palo Alto Networks, Inc. occupies a consolidation position for network security procurement in regulated financial environments. Darktrace plc represents the autonomous response archetype competing on algorithmic accuracy in oil and gas operational technology deployments. These three anchors illustrate how vendor qualification criteria are shifting toward pre-trained regional threat models and documented compliance with Gulf certification pathways.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Amazon Web Services, Inc. |
| Cisco Systems, Inc. |
| IBM Corporation |
| Palo Alto Networks, Inc. |
| Fortinet, Inc. |
| Check Point Software Technologies Ltd. |
| Darktrace plc |
| NVIDIA Corporation |
| Others |
Pricing and Supply Chain Analysis
Red Sea shipping corridor cost volatility is compressing margins for hardware-dependent security vendors while amplifying price differentiation between subscription-native platforms and appliance-heavy incumbents. Gulf sovereign wealth fund procurement preferences for localized R&D presence are reshaping supply chain geography, forcing tier-one vendors to absorb regional facility costs into premium pricing tiers.
Pricing Analysis
Long-term managed security service contracts dominate enterprise procurement in Saudi Aramco and ADNOC facilities, compressing spot-market opportunities for standalone software licensing. Three-tier pricing structure across premium, standard, and economy levels segments by algorithmic sophistication and Gulf-based security operations center availability. Pricing pressure stems from commoditized firewall refresh cycles as AI-enabled threat intelligence platforms capture budget allocation. Mid-market enterprises in Johannesburg and Cape Town exhibit highest price sensitivity; national oil companies in the Eastern Province demonstrate lowest sensitivity due to sovereign capability mandates.
Supply Chain Analysis
Contract manufacturing for AI security hardware concentrates in Taiwan, Malaysia, and Vietnam, with firmware development increasingly migrating to UAE and Saudi-based engineering centers. Specialized GPU clusters for behavioral analytics training draw from NVIDIA supply allocations and domestic cloud infrastructure investments. Single-source vulnerability in advanced semiconductor fabrication creates procurement risk for autonomous response platform vendors. Distribution runs through hyperscale cloud marketplaces and regional systems integrators serving NCA-mandated critical infrastructure operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Managed detection and response service layers are expanding faster than hardware licensing across Middle East and Africa enterprise accounts, creating attach-rate opportunities for vendors with Gulf-based security operations infrastructure.
For Market Incumbents: Harden algorithmic audit documentation to meet UAE Telecommunications and Digital Government Regulatory Authority certification requirements for explainable AI in security decision-making. Deepen backward integration into sovereign cloud infrastructure partnerships to defend against hyperscale platform encroachment in hybrid deployment models. Anchor recurring revenue through operational technology convergence bundles integrating industrial control system safety protocols. For New Entrants and Emerging Players: Egypt's government digital service delivery and banking sector modernization represent underpenetrated white-space with compressed procurement timelines relative to saturated Gulf markets. Target fintech ecosystems in Riyadh's financial hub with pre-trained regional threat models outperforming generic global datasets. Establish direct channel relationships with mining and logistics verticals in South Africa where board-level cyber risk accountability is disrupting traditional systems-integrator dominance. For Investors and Strategic Acquirers: Carve-out targets emerge from defense technology conglomerates spinning off civilian-facing autonomous response capabilities. Long-term viability centers on vendors with documented compliance against Saudi National Cybersecurity Authority bias-testing frameworks and localized data processing architectures. Monitor sovereign wealth fund direct investment patterns in domestic AI research capacity as signal for vendor selection criteria shift away from global providers.| Strategic Initiative | Industry Significance |
|---|---|
| Gulf-Based Security Operations Center Establishment | Meets UAE and Saudi data residency mandates for critical infrastructure procurement eligibility. |
| Operational Technology Convergence Bundle Development | Captures integrated safety-security procurement at Saudi Aramco and ADNOC facilities. |
| Pre-Trained Regional Threat Model Investment | Outperforms generic datasets in Dubai and Riyadh financial institution deployments. |
| Managed Detection and Response Service Unbundling | Addresses South African mining and logistics board-level cyber risk accountability demands. |
| Algorithmic Bias Testing Documentation | Satisfies mandatory certification pathways for Saudi National Cybersecurity Authority compliance. |
Research Methodology
Cross-validation between primary interviews with CISOs at Saudi Aramco and ADNOC, platform engineers at Dubai International Financial Centre fintechs, and regulatory affairs leads at UAE Telecommunications and Digital Government Regulatory Authority anchors the qualitative findings. Secondary validation draws from SEC filings of listed cybersecurity vendors, hyperscaler capex disclosures for sovereign cloud infrastructure, and Saudi National Cybersecurity Authority procurement specification releases. Bottom-up triangulation across deployment model segmentation and top-down calibration against sovereign wealth fund investment flows ensures analytical consistency.
Calibration against historical adoption curves in financial services and oil and gas verticals shapes the projection framework across the analysis window. Segmentation dimensions modeled include product architecture, deployment model, end-user vertical, and algorithmic engine type. CAGRs derive from regression analysis of procurement volume against regulatory mandate implementation timelines and smart city buildout acceleration. Industry-specific inputs incorporate NCA compliance deadline schedules and central bank protocol evolution in UAE and Saudi markets.
The forecast holds incumbent behavior within observed patterns; aggressive localization investments by hyperscale cloud providers or sovereign wealth fund direct AI research capacity building would shift outcomes substantially. Quarterly review of Gulf-based security operations center establishment announcements and algorithmic bias testing framework updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Malaysia Cybersecurity Market
Cybersecurity
China Cybersecurity Market
Cybersecurity
Finland Cybersecurity Market
Cybersecurity
Data-Centric Security Market
Cybersecurity
Canada Ransomware Protection Market
Cybersecurity
Domain Name System (DNS) Firewall Market
Cybersecurity
Global File Integrity Monitoring Market
Cybersecurity
Bahrain Cybersecurity Market
Cybersecurity
Cybersecurity in Gaming Market
Cybersecurity
Brazil Cybersecurity Market
Cybersecurity
Cloud Firewalls Market
Cybersecurity
Data Center Logical Security Market
Cybersecurity
Homomorphic Encryption Market
Cybersecurity
Global Cyber Security in Healthcare Market
Cybersecurity
Sweden Cybersecurity Market
Cybersecurity
Taiwan Cybersecurity Market