
 Data Quality and Data Governance Solution Market | 2026-2036
Data Quality and Data Governance Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Data Quality and Data Governance Solution Market Outlook
Market Context
North American cloud infrastructure build-out is rewriting competitive dynamics for enterprise data governance. Informatica leverages its hybrid integration heritage to anchor multi-cloud deployments for Fortune 500 clients. Alation competes through behavioral analytics that sustain user adoption rates across distributed data catalogs. Databricks differentiates by embedding governance directly within lakehouse architectures, reducing friction between analytics and compliance workflows.
Technical Definition and Segment Structure
Data quality and data governance solutions encompass software platforms that enforce consistency, accuracy, and policy compliance across organizational data assets through automated profiling, lineage tracking, and metadata management. These systems integrate with existing data pipelines to prevent downstream analytical errors and regulatory violations while enabling self-service discovery for business users. Cloud-based deployment is capturing the fastest expansion as enterprises retire on-premises master data hubs, though hybrid configurations retain the largest margin pools due to complex integration requirements. Metadata management is maturing into a standalone budget line as organizations confront AI model traceability mandates, while data cleansing remains volume-driven with thinner differentiation.
Regulatory Framework
GDPR enforcement by European data protection authorities and the EU AI Act's risk-classification requirements are reshaping product roadmaps toward automated compliance documentation. The US SEC's climate disclosure rules and HIPAA security provisions are driving healthcare and financial services buyers toward solutions with pre-built regulatory templates. Organizations must monitor how fragmented national data localization laws fragment vendor architectures and inflate implementation costs.
Market Dynamics
Cloud migration mandates from financial services and healthcare enterprises are compressing procurement cycles for data governance platforms, forcing vendors to re-architect deployment models around multi-cloud abstraction layers.
Growth Catalysts
- EU AI Act risk-classification mandates:European enterprises must deploy automated lineage tracking for high-risk AI systems, creating procurement urgency for governance vendors with pre-built audit trails.
- Healthcare data interoperability:HIPAA security provisions and the 21st Century Cures Act are compelling US hospital systems to consolidate fragmented patient data under unified governance frameworks.
- Real-time streaming analytics:Manufacturing and logistics firms are embedding data quality checks directly within Apache Kafka and Apache Flink pipelines to prevent defective sensor data from corrupting operational dashboards.
Market Restraints
- Specialized engineering talent scarcity:Implementation of metadata management systems requires rare combinations of SQL optimization, API architecture, and regulatory domain expertise, inflating professional services costs.
- Legacy mainframe integration:Fortune 500 enterprises with IBM Db2 and COBOL-dependent core systems face 18-24 month timelines to expose structured data assets to modern governance catalogs.
- Fragmented national data localization laws:Brazil's LGPD, India's DPDP Act, and China's PIPL impose conflicting residency requirements that force vendors to maintain redundant infrastructure stacks.
Strategic Opportunities
- Southeast Asian banking modernization:Singapore's MAS 637 guidelines and Indonesia's OJK regulations are driving tier-2 financial institutions toward first-generation data governance adoption.
- AI model provenance tooling:Convergence of MLOps pipelines with governance catalogs creates whitespace for vendors offering automated training-data-to-model lineage documentation.
- Embedded governance APIs:Snowflake and Databricks marketplace channels enable point-solution vendors to distribute data quality checks as native integrations rather than standalone platforms.
Industry Challenges
- Data steward role definition:Enterprises struggle to recruit professionals who bridge business domain expertise with technical metadata engineering, delaying catalog adoption.
- Cross-functional alignment friction:Legal, IT security, and analytics teams maintain conflicting priorities for data access policies, complicating workflow automation design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Quality and Data Governance Solution Market |
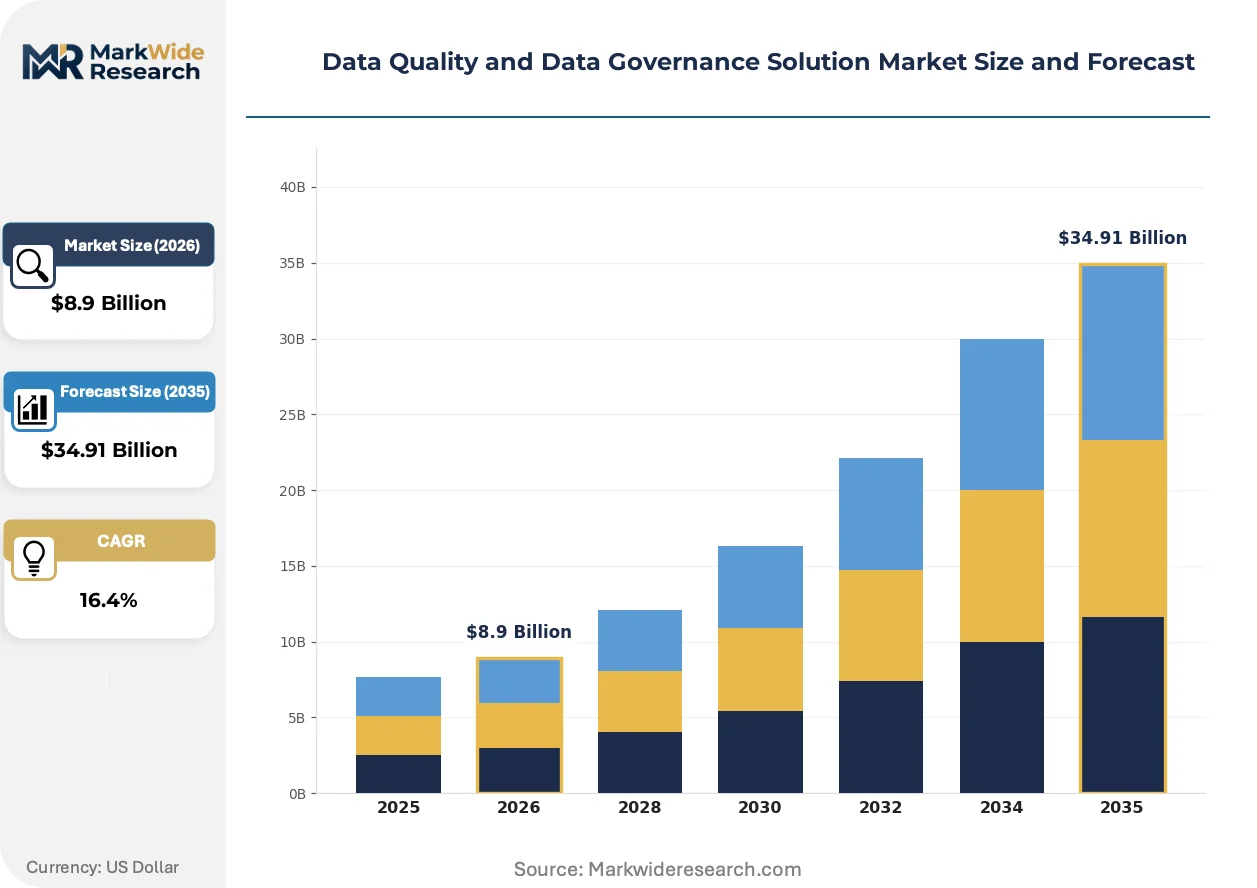
| Market Size in 2026 | $8.9 Billion |
| Market Size in 2035 | $34.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Data Cleansing, Data Profiling, Data Integration, Metadata Management Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Services End User: Retail, Healthcare, BFSI, Telecommunications Industry Vertical: Manufacturing, Education, Government, Others |
| Companies Covered | Collibra, Informatica, Alation, Ataccama, Databricks, OvalEdge, SAP Master Data Governance, Precisely, Oracle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Quality and Data Governance Solution Market Strategic Shifts
Active metadata architectures are displacing passive repository models, enabling governance systems to automatically trigger policy enforcement based on real-time data usage patterns rather than static classification rules.
Data fabric technology is hybridizing point-to-point integration approaches with centralized semantic layers. Large pharmaceutical and automotive manufacturers are deploying knowledge-graph-powered fabrics to unify ERP, CRM, and IoT sensor streams under common business vocabularies. This convergence is compressing the traditional ETL-to-catalog pipeline into single-plane orchestration, reducing the vendor count in typical enterprise stacks.
CSRD sustainability reporting mandates are forcing European manufacturers to trace carbon footprint data through multi-tier supplier networks. The regulation requires auditable lineage from raw material extraction through finished goods distribution, accelerating investment in supply-chain-specific governance modules. German automotive suppliers and French luxury goods houses represent the most advanced adopters, with deployment timelines compressed to meet 2025 disclosure deadlines.
Self-service data marketplace models are displacing ticket-based access workflows. Business units at US financial services firms now procure certified datasets through internal exchanges with embedded quality scores and usage-based pricing. This behavioral shift concentrates purchasing authority within line-of-business budgets rather than central IT, altering vendor sales motion from technical validation to business outcome demonstration.
Data Quality and Data Governance Solution Market Segmentation
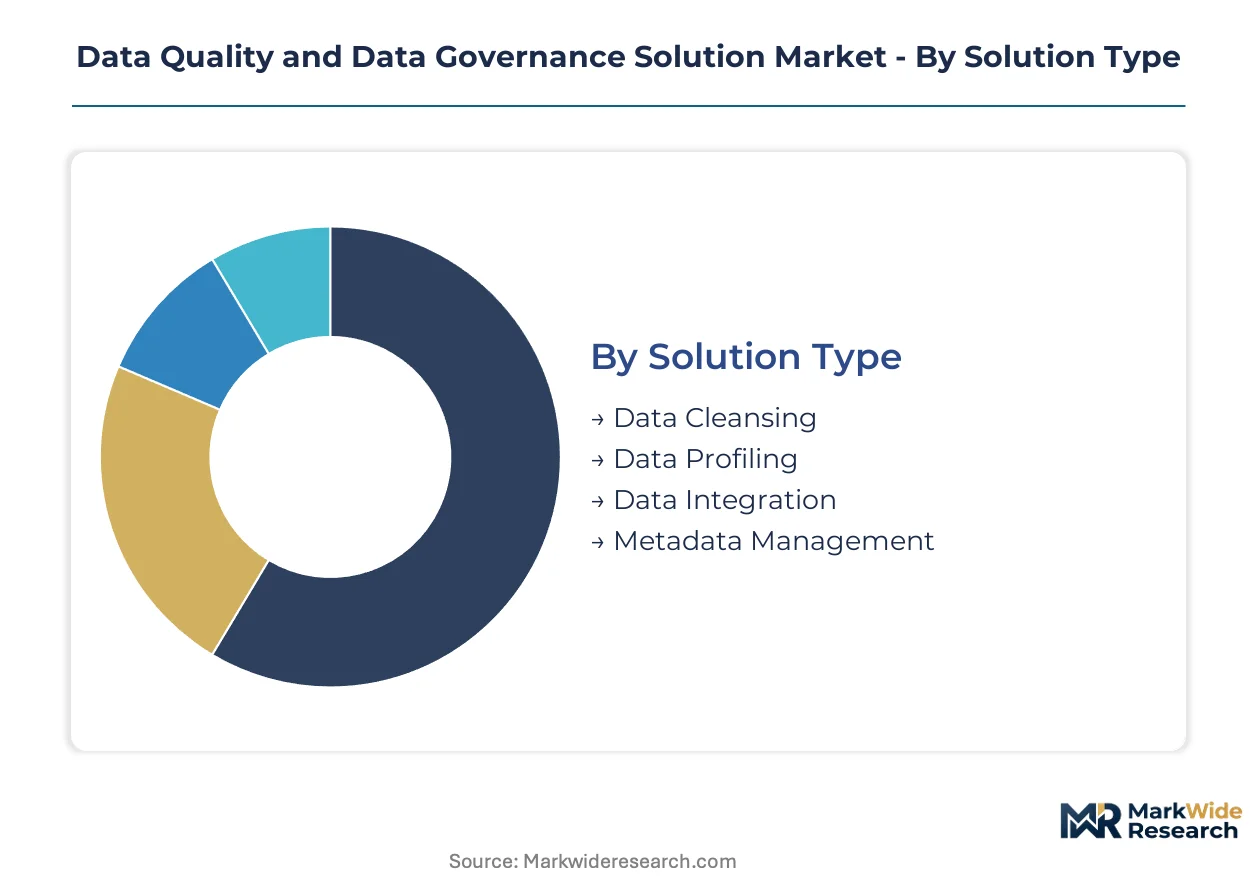
Segmentation in data quality and governance solutions reveals how procurement cycles, technical complexity, and regulatory exposure vary across deployment modes and buyer profiles. Understanding these fault lines helps vendors calibrate pricing, professional services intensity, and roadmap prioritization.
Solution Type:
Cycle times differ sharply across solution types, with data cleansing tools turning over fastest due to volume-driven commoditization while metadata management contracts extend longest because of enterprise-wide architectural integration.
- Data Cleansing:Automated deduplication, standardization, and validation routines that scrub raw datasets before analytical consumption. US hospital systems under HIPAA security provisions deploy these tools fastest, though margin compression from open-source alternatives limits vendor pricing power.
- Metadata Management:Centralized repositories capturing technical, business, and operational metadata to enable data discovery and lineage tracking. European manufacturers facing CSRD sustainability reporting mandates drive premium procurement here, with German automotive suppliers requiring auditable supplier network traceability.
- Data Profiling:Statistical analysis engines that assess column-level completeness, uniqueness, and distribution patterns across data stores.
- Data Integration:ETL/ELT pipelines that harmonize disparate sources into governed target schemas.
Data cleansing anchors the volume base while metadata management gains share at the steepest rate.
Deployment Model:
Cost tier stratification separates this category, with managed services commanding the highest per-seat pricing due to bundled operational support while on-premises deployments concentrate among buyers with sunk infrastructure investments.
- Cloud-Based:Multi-tenant SaaS platforms with elastic scaling and API-native architecture. US financial services firms expanding AWS and Azure footprints drive fastest adoption here, compressing procurement cycles to under 90 days for departmental deployments.
- Hybrid:Split architectures keeping sensitive data on-premises while pushing analytics workloads to cloud. India's DPDP Act residency requirements and sectoral localization rules force this configuration among domestic banks and insurers.
- On-Premises:Perpetual-license software deployed within customer data centers.
- Managed Services:Fully outsourced governance operations with SLAs covering data quality scores and compliance documentation.
On-premises deployments retain the largest installed base while cloud-based solutions are expanding most quickly.
End User:
Application criticality varies by end user, with BFSI buyers demanding real-time lineage for trading algorithms while retail prioritizes batch-mode customer data hygiene.
- BFSI:Risk-weighted capital calculations, anti-money laundering surveillance, and SEC climate disclosure documentation. The EU AI Act risk-classification mandates for credit-scoring algorithms create urgent procurement timelines among Frankfurt and Paris-based banking groups.
- Healthcare:Patient identity matching, clinical trial data integrity, and HIPAA security provision compliance. The 21st Century Cures Act interoperability requirements compel US hospital systems toward unified governance frameworks.
- Retail:Omnichannel customer identity resolution and supply chain master data harmonization.
- Telecommunications:Subscriber data privacy management and network equipment configuration governance.
BFSI anchors the revenue base while healthcare climbs the fastest as regulatory deadlines compress.
Industry Vertical:
Maturity gaps define this category, with manufacturing exhibiting the most advanced IoT sensor governance practices while government lags in cloud migration due to procurement rigidity.
- Manufacturing:Shop-floor sensor data quality, digital thread traceability, and supplier sustainability certification tracking. German automotive suppliers and French luxury goods houses lead CSRD-driven deployments with compressed timelines for carbon footprint lineage.
- Government:Citizen identity registries, tax data integrity, and cross-agency data sharing frameworks. Brazil's LGPD and India's DPDP Act force redundant infrastructure stacks that inflate implementation costs.
- Education:Student information system consolidation and research data management.
- Others:Energy, media, and professional services with fragmented governance maturity.
Manufacturing anchors the advanced-use-case base while government verticals show the steepest expansion trajectory as national data localization laws proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States enterprises consume data governance solutions through cloud-native procurement channels, compressing deployment timelines below 90 days for departmental rollouts, while European buyers prioritize automated lineage documentation to satisfy AI Act audit requirements.
United States
Financial services firms and hospital systems anchor domestic demand, with AWS and Azure footprints expanding fastest among Fortune 500 clients. SEC climate disclosure rules and HIPAA security provisions drive procurement toward pre-built regulatory templates. New York Metro and Greater Boston banking clusters deploy real-time lineage for trading algorithms under compressed implementation schedules.
Germany
Automotive suppliers and industrial manufacturers command premium metadata management contracts for CSRD sustainability reporting. EU AI Act risk-classification mandates create urgent procurement timelines among Frankfurt-based banking groups. Bavaria and Baden-Württemberg industrial corridors lead carbon footprint lineage deployments with 2025 disclosure deadlines forcing accelerated vendor selection.
France
Luxury goods houses and pharmaceutical manufacturers invest in supplier network traceability for CSRD compliance. GDPR enforcement by CNIL reshapes product roadmaps toward automated compliance documentation. Paris-based banking groups and Lyon manufacturing clusters represent the most advanced governance adopters in continental Europe.
United Kingdom
London financial services firms drive demand for multi-cloud abstraction layers as regulatory reporting complexity intensifies. Post-Brexit data localization requirements fragment vendor architectures for cross-border operations. The Southeast corridor concentrates procurement authority among tier-1 investment banks and insurance groups modernizing legacy mainframe integrations.
India
Domestic banks and insurers adopt hybrid deployment models under DPDP Act residency requirements. RBI guidelines on data localization force redundant infrastructure stacks that inflate implementation costs. Mumbai and Bangalore technology corridors concentrate tier-2 financial institution modernization toward first-generation governance adoption.
Data Quality and Data Governance Solution Market Competitive Environment
Capability concentration sits with specialized metadata engineering vendors; scale advantage sits with cloud-platform incumbents with distribution through marketplace channels. The vendor base organizes around three tiers: legacy integration specialists with hybrid deployment heritage, lakehouse-native platforms embedding governance within analytics workflows, and point-solution vendors distributing through Snowflake and Databricks marketplaces. Dominant competitive moves include strategic partnerships for multi-cloud abstraction layers and portfolio diversification into AI model provenance tooling.
Among cloud-platform incumbents, Databricks exemplifies the lakehouse-native archetype by embedding governance directly within analytics architectures, while Informatica occupies a position representing hybrid integration heritage for Fortune 500 multi-cloud deployments. Collibra anchors the specialized metadata management tier, with its behavioral analytics sustaining user adoption across distributed data catalogs.
| Leading Market Players |
|---|
| Collibra |
| Informatica |
| Alation |
| Ataccama |
| Databricks |
| OvalEdge |
| SAP Master Data Governance |
| Precisely |
| Oracle |
| Others |
Value Chain & Pricing Dynamics
Cloud infrastructure concentration in the United States and Western Europe anchors margin pools for data governance vendors, as hyperscaler compute costs and API licensing fees concentrate procurement leverage among platform-native buyers. SaaS delivery models compress professional services margins while expanding recurring revenue capture for metadata management specialists.
Pricing Analysis
Long-term enterprise contracts dominate data governance procurement, with three-year SaaS subscriptions locking in price escalators indexed to cloud storage growth. Price differentiation stems from certification tier—ISO 27001 and SOC 2 Type II compliance command 25-40% premiums—and vertical customization depth, with HIPAA-enabled healthcare modules priced above generic financial services templates. Pricing pressure runs through the data cleansing tier as open-source Apache Spark and Great Expectations libraries displace commercial deduplication tools. Healthcare buyers exhibit highest price sensitivity due to constrained IT budgets, while BFSI procurement teams prioritize audit trail completeness over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for data governance hardware appliances, though pure-play SaaS vendors remain insulated. Software supply chains draw from India for engineering talent, Ireland for EU data residency infrastructure, and Singapore for Asia-Pacific latency optimization. GPU compute dependencies for AI model lineage tracking rest on NVIDIA's foundry arrangements in Taiwan and South Korea. Single-source vulnerability concentrates in identity management middleware from Okta and Microsoft Entra. Distribution runs through direct enterprise sales teams for Fortune 500 accounts, with hyperscaler marketplaces capturing mid-market volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Open-source data quality libraries and embedded governance features from Databricks and Snowflake threaten standalone vendor economics, forcing incumbents to defend platform stickiness through workflow integration depth.
For Market Incumbents: Harden defensive moats by embedding governance APIs directly into MLOps pipelines, neutralizing the threat from lakehouse-native competitors. Prioritize backward integration into cloud infrastructure provisioning to capture compute-margin pools currently flowing to AWS and Azure. Certification investment in EU AI Act compliance templates creates switching costs among Frankfurt and Paris banking groups. For New Entrants and Emerging Players: Build out AI model provenance tooling as a standalone wedge, targeting European manufacturers under CSRD sustainability reporting mandates with carbon footprint lineage modules. Southeast Asian tier-2 banks in Indonesia and Vietnam represent the most penetrable geography, with first-generation governance adoption cycles compressing to six-month validation periods. Go-to-market motion should route through regional system integrators with existing central bank relationships. For Investors and Strategic Acquirers: Capital is best deployed toward specialized metadata engineering firms with behavioral analytics IP sustaining user adoption rates. Long-term viability across the analysis window favors vendors with hybrid deployment heritage serving Fortune 500 mainframe modernization cycles. The signal to watch is consolidation velocity among point-solution vendors distributing through Snowflake and Databricks marketplaces, as channel dependency shifts pricing power toward platform owners.| Strategic Initiative | Industry Significance |
|---|---|
| AI Model Provenance Tooling | Automated training-data-to-model lineage satisfies EU AI Act risk-classification mandates for credit-scoring algorithms. |
| Multi-Cloud Abstraction Partnerships | Unified governance planes reduce procurement friction for AWS-Azure-Google Cloud deployments at US financial services firms. |
| CSRD Compliance Module Development | Carbon footprint traceability through supplier networks captures German automotive and French luxury goods procurement cycles. |
| Embedded Governance API Distribution | Native Snowflake and Databricks marketplace integrations displace standalone platform sales motions. |
| Hybrid Deployment Heritage Leverage | Mainframe-to-cloud data lineage capabilities secure Fortune 500 clients with IBM Db2 and COBOL core systems. |
Study Parameters
Operator-level perspectives from chief data officers, enterprise architects, regulatory compliance leads, and cloud procurement officers anchored the qualitative base for this analysis. Primary interviews with these stakeholders combined with secondary validation from SEC 10-K filings, hyperscaler capex disclosures, and EU regulatory impact assessments. Bottom-up sizing of vendor revenue pipelines triangulated against top-down IT budget allocation surveys across BFSI, healthcare, and manufacturing verticals.
Scenario-bracketing around cloud migration velocity and regulatory enforcement intensity framed the analytical approach across the projection horizon. Segmentation dimensions modeled include deployment architecture, solution type, end-user industry, and geographic regulatory cluster. CAGRs were derived from elasticity-adjusted adoption curves and replacement cycle analysis. Industry-specific forecast inputs incorporated AI Act implementation timelines and CSRD disclosure deadline clustering.
The forecast holds incumbent behavior within observed patterns; aggressive platform bundling moves by Databricks and Snowflake would shift outcomes toward embedded governance displacement. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Remote Integration Solutions Market
Digital Solutions
Global Web Hosting Service Market
Digital Solutions
Germany Smart Office Market
Digital Solutions
Model Based Enterprise Market
Digital Solutions
Enterprise Asset Management (EAM) Market
Digital Solutions
Asia-Pacific Smart Government Market
Digital Solutions
Asia-Pacific Computer Aided Engineering Market
Digital Solutions
Container Orchestration Market
Digital Solutions
Global Process Orchestration Market
Digital Solutions
Digital Commerce Software Market
Digital Solutions
Global Enterprise Metadata Management Market
Digital Solutions
Global Advocacy Software Market
Digital Solutions
Incidence Management Software Market
Digital Solutions
Digital Rights Management (DRM) Market
Digital Solutions
Community Forum Market
Digital Solutions
Content Moderation Services Market