
 Global 3D Architecture Software Market | 2026-2036
Global 3D Architecture Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global 3D Architecture Software Market Foresight
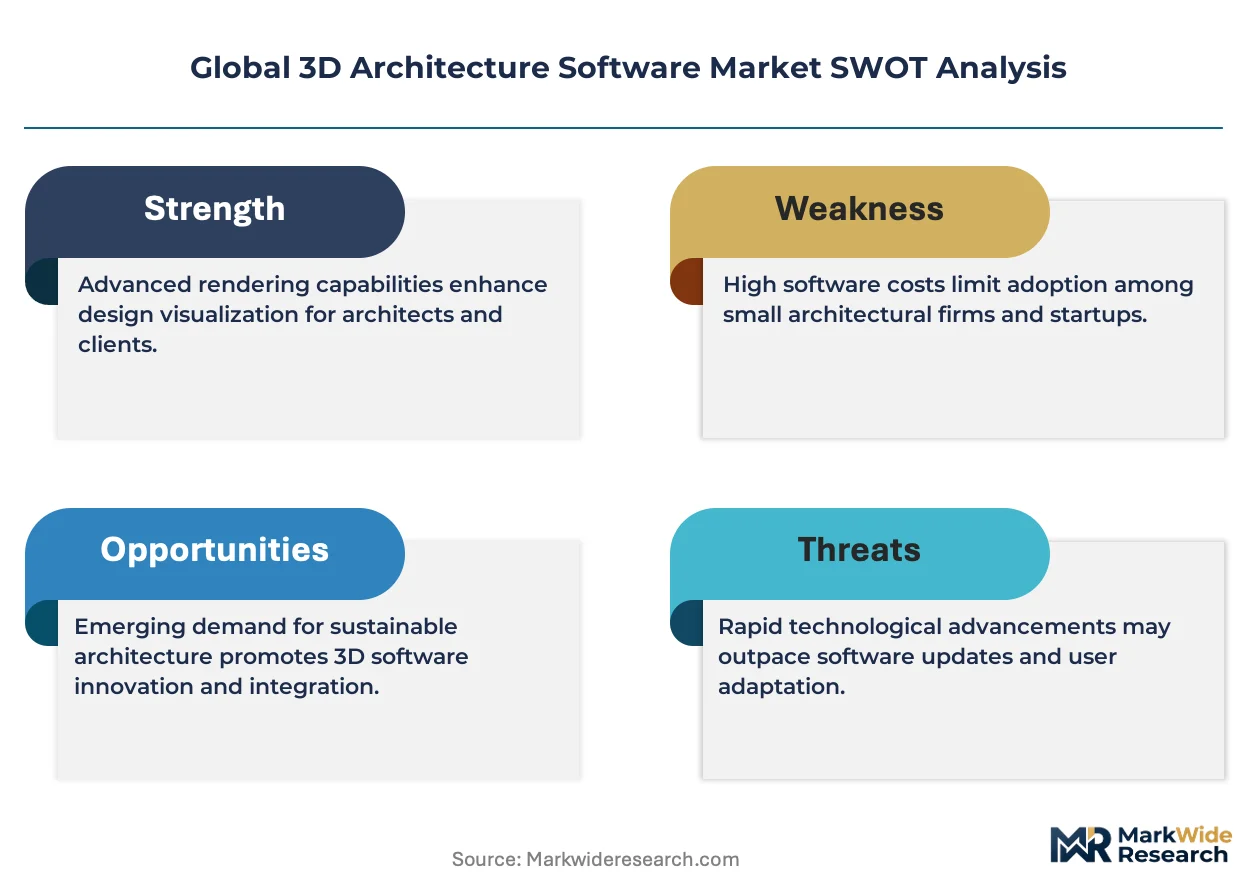
The gap between premium enterprise suites and entry-level design tools is shifting from feature count to data interoperability and multi-stakeholder collaboration depth. Autodesk Inc. leverages its Revit ecosystem to anchor high-end BIM workflows across large-scale commercial projects. Nemetschek Group competes through an open-BIM philosophy that sustains cross-platform compatibility for mid-market architectural firms.
3D architecture software encompasses computer-aided design applications that generate, manipulate, and render spatial models through parametric modeling engines, polygonal mesh systems, and real-time ray-tracing pipelines. These platforms serve primary commercial purposes spanning conceptual massing studies, construction documentation, and facilities lifecycle management. Cloud-based deployment leads in new subscription growth as remote collaboration becomes standard, while on-premise installations retain dominance in government and defense-adjacent projects where data sovereignty controls access. BIM technology commands the deepest margin pools through long-term enterprise contracts, whereas AR visualization represents the fastest-expanding segment as field verification use cases multiply.
The EU Green Deal's embodied-carbon reporting requirements and the US EPA's building energy performance standards are reshaping software specification lists toward environmental impact calculators and material databases. China's GB standards for green building certification and Japan's METI directives on construction productivity are accelerating platform localization demands across Asia-Pacific. Stakeholders must monitor whether regulatory divergence in sustainability metrics fragments data standards or creates openings for middleware vendors that normalize compliance across jurisdictions.
Market Dynamics
Cloud-native parametric modeling is compressing deployment cycles from months to days, forcing incumbents to rearchitect legacy codebases while specialized vendors capture mid-market share through API-first interoperability layers.
Growth Catalysts
- EU Green Deal embodied-carbon mandates:Building performance standards in Germany, France, and the Netherlands now require lifecycle carbon calculators embedded directly into BIM workflows, creating pull for environmental impact modules.
- Generative design algorithms:Machine-learning topology optimization reduces material waste in structural systems by 15-40% according to engineering firm case studies, accelerating adoption in commercial high-rise construction.
- China's GB/T 50378 green building certification:Provincial implementation in Guangdong and Jiangsu provinces mandates digital energy modeling for public projects above 20,000 square meters.
Market Restraints
- GPU compute cost volatility:Real-time ray-tracing and neural rendering pipelines depend on NVIDIA and AMD datacenter silicon, with spot pricing fluctuations of 30-60% disrupting SaaS margin structures.
- Data sovereignty fragmentation:Russia's data localization laws and China's Cybersecurity Law require on-premise or sovereign-cloud deployments, complicating vendor expansion into government-adjacent segments.
- Interoperability protocol stagnation:IFC 4.3 adoption remains uneven across Asian markets, forcing costly translation middleware and project-specific data bridges.
Strategic Opportunities
- India's Smart Cities Mission:Urban infrastructure digitization across 100 metropolitan areas creates demand for localized BIM platforms with vernacular construction typology libraries.
- AR field verification convergence:Spatial computing headsets from Apple and Meta are converging with photogrammetry pipelines, enabling real-time as-built validation without specialized survey crews.
- US Inflation Reduction Act commercial rebates:Section 179D tax deductions for energy-efficient building retrofits are driving demand for existing-building energy modeling tools previously underutilized in renovation workflows.
Industry Challenges
- Computational design skill scarcity:Architecture graduates lack proficiency in visual scripting environments like Grasshopper or Dynamo, forcing firms to hire from game development and industrial design talent pools.
- Legacy CAD migration complexity:Decades of DWG archives and custom LISP routines create technical debt that stalls cloud transitions despite executive mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global 3D Architecture Software Market |
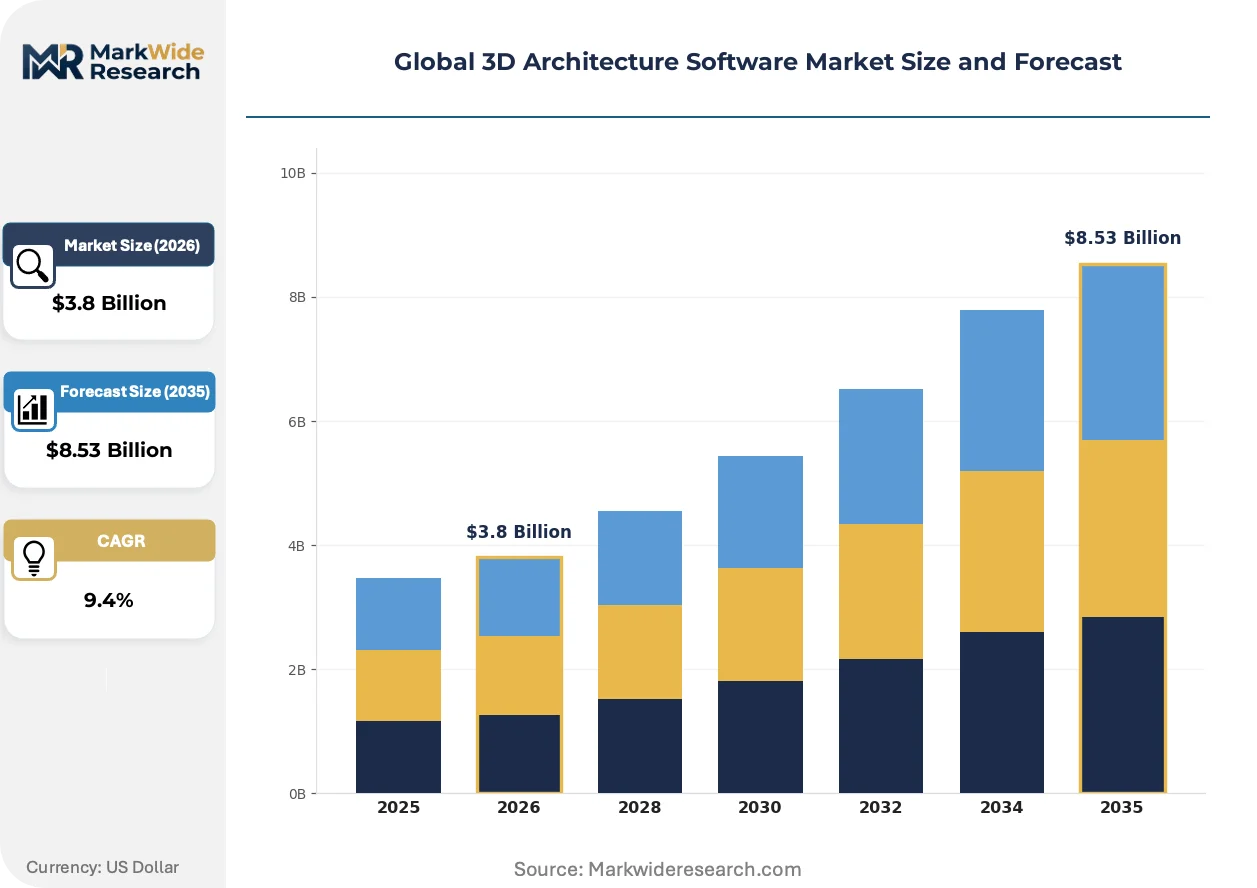
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
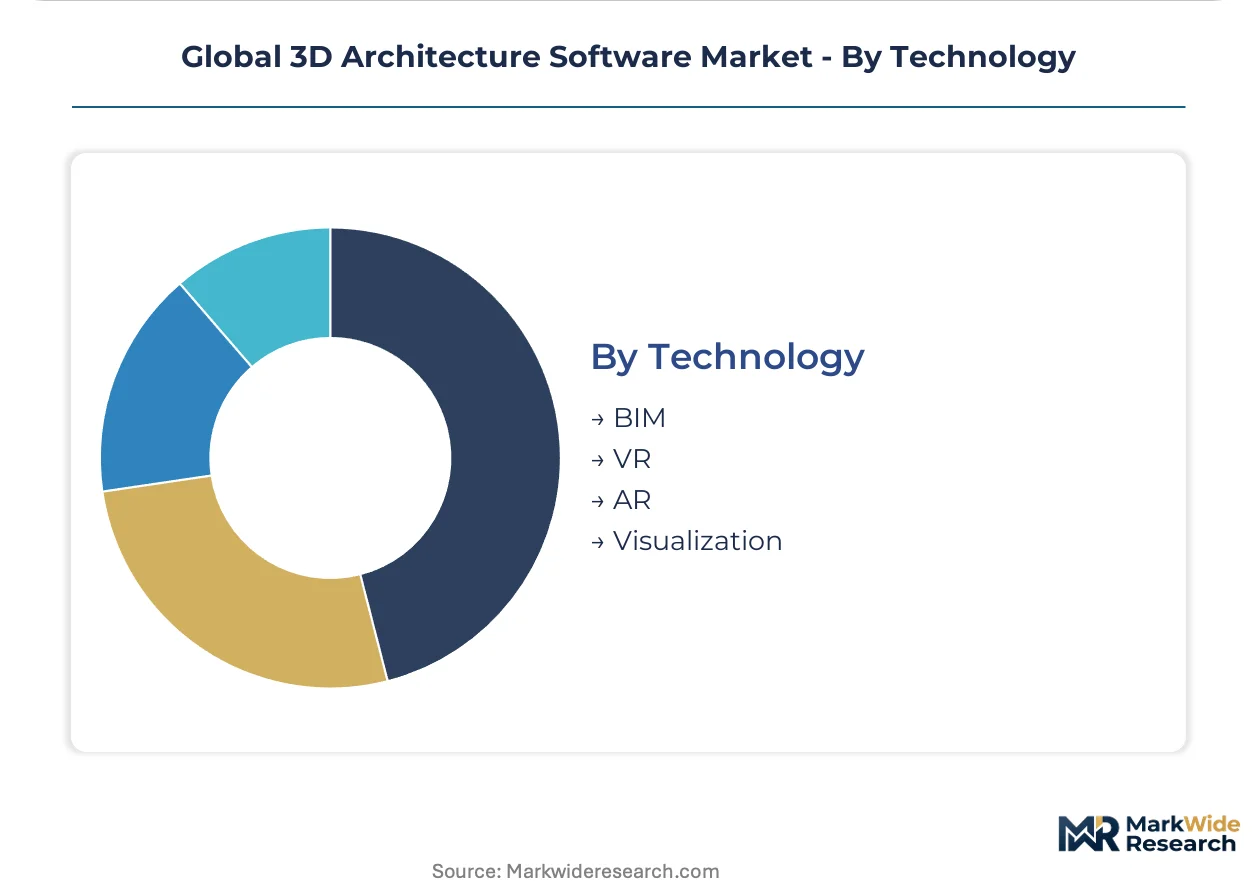
| Segmentation | Product Type: On-Premise, Cloud-Based, Hybrid, Plugin End User: Architectural Firms, Construction Companies, Urban Planners, Educational Institutions Application: Building Design, Landscape Architecture, Interior Design, Simulation Technology: BIM, VR, AR, Visualization |
| Companies Covered | Autodesk Inc., Nemetschek Group, Bentley Systems, Trimble Inc., Dassault Systèmes, Hexagon AB, Siemens Digital Industries Software, Graphisoft, Bricsys, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global 3D Architecture Software Market Shifts & Advancements
Artificial intelligence inference at the edge is redistributing computational workloads from centralized render farms to field devices, collapsing feedback loops between design intent and construction reality.
Neural radiance fields (NeRFs) are converging with traditional CAD geometry, enabling photorealistic scene reconstruction from smartphone captures without structured light scanners. Small and mid-sized architectural practices in Spain and Italy are adopting these pipelines for heritage documentation and renovation surveying. The technology is converging with established BIM platforms through plugin architectures that bypass native geometry kernels entirely.
Japan's METI Construction DX Promotion Grant subsidizes platform adoption only for solutions demonstrating open API compliance and domestic data residency. This policy is accelerating localization of foreign software stacks while creating protected niches for domestic vendors like FORUM8 and Graphisoft Japan. Prefecture-level procurement in Tokyo and Osaka now prioritizes platforms with Japanese-language support documentation and local server infrastructure.
Subscription fatigue among boutique studios is driving unbundling of previously monolithic suites, with firms purchasing standalone rendering engines, clash detection modules, and collaboration layers from separate vendors. This pattern is most pronounced in Portugal, Denmark, and Australia's design-build sector, where project-based staffing favors OpEx flexibility over perpetual license accumulation. Channel partners are responding with usage-based billing orchestration rather than seat-count negotiations.
Global 3D Architecture Software Market Segmentation
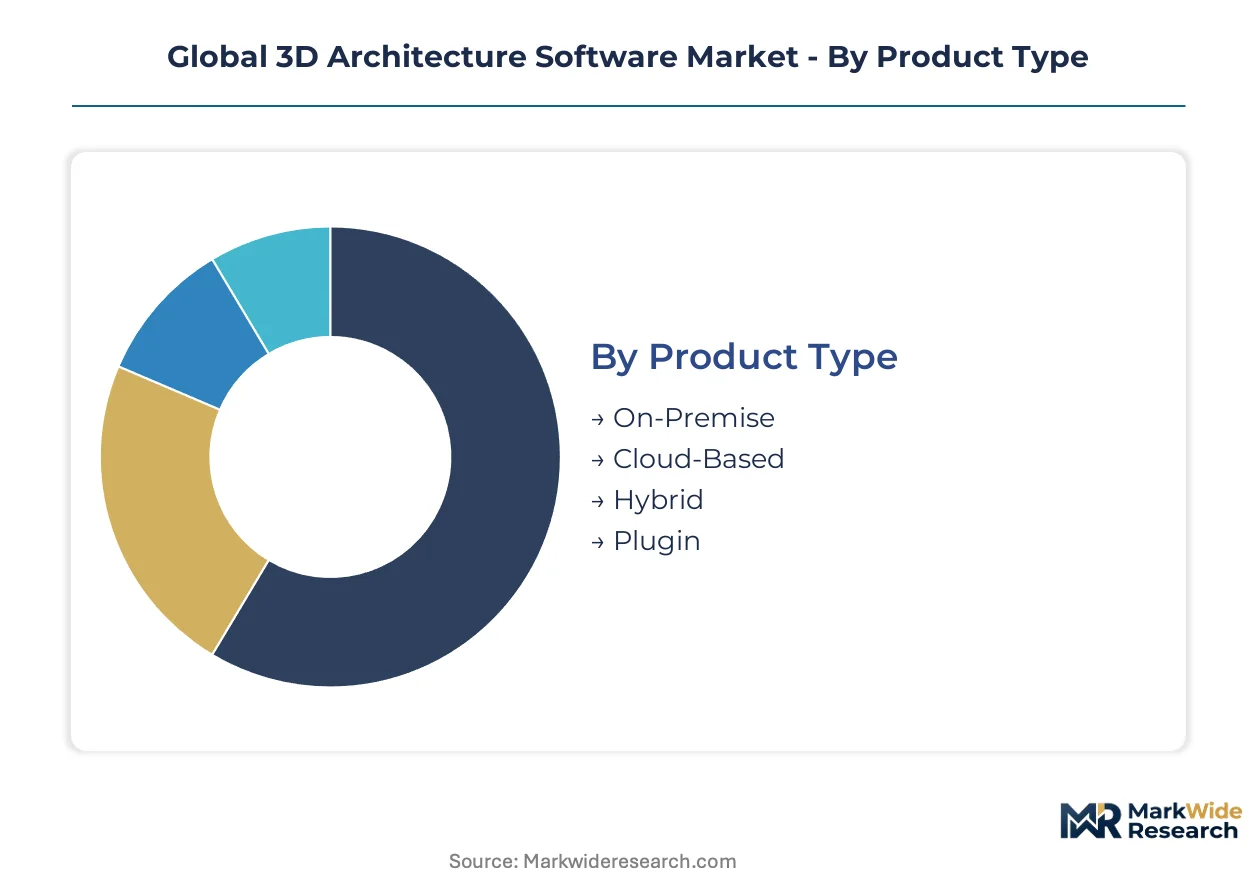
Segmentation reveals how deployment models, user workflows, and rendering technologies partition margin pools differently across the 3D architecture software stack. Each dimension exposes distinct vendor positioning strategies and buyer procurement patterns.
Product Type:
Cloud-native architectures concentrate development investment from Autodesk, Nemetschek, and Trimble, while legacy codebases sustain on-premise revenue in regulated verticals.
- Cloud-Based:Browser-accessible parametric engines with real-time collaboration layers dominate new subscription growth. Demand clusters in Germany, the United States, and China where distributed project teams require synchronous model editing across time zones.
- On-Premise:Perpetual-licensed installations with local geometry kernels retain dominance in government and defense-adjacent projects. Russia's data localization laws and China's Cybersecurity Law mandate sovereign infrastructure, preserving this segment despite cloud pressure.
- Hybrid:Split-compute architectures cache sensitive geometry locally while offloading rendering to elastic cloud nodes.
- Plugin:Modular extensions that augment native CAD kernels with specialized analysis tools or interoperability bridges.
Cloud-Based absorbs the bulk of installed capacity; Hybrid is expanding most quickly as firms navigate compliance complexity.
End User:
Procurement authority varies sharply by buyer type, with construction companies consolidating vendor relationships across project portfolios while architectural firms favor best-of-breed toolchains.
- Construction Companies:Enterprise buyers standardizing BIM workflows across commercial high-rise and infrastructure portfolios. Turner Construction and Skanska mandate platform-wide data interoperability, pulling environmental impact modules for EU Green Deal compliance.
- Architectural Firms:Design-centric practices prioritizing conceptual massing flexibility and rendering quality. Mid-market studios in Portugal and Denmark drive unbundling of monolithic suites toward standalone rendering engines and clash detection modules.
- Urban Planners:Public-sector users requiring city-scale digital twin integration and vernacular typology libraries for India's Smart Cities Mission.
- Educational Institutions:Universities and technical colleges training next-generation practitioners, creating pipeline lock-in through curriculum-embedded software subsidies.
Construction Companies command the deepest contract values; Urban Planners are climbing the fastest as metropolitan digitization accelerates.
Application:
Workflow differentiation separates geometry-intensive design phases from simulation-driven validation stages, with distinct computational requirements shaping vendor specialization.
- Building Design:Structural and envelope modeling for commercial, residential, and institutional projects. Generative design algorithms reduce material waste in high-rise construction, with machine-learning topology optimization gaining traction among engineering firms.
- Interior Design:Space planning and material specification workflows. Real-time ray-tracing pipelines from Enscape and Chaos enable photorealistic client presentations without dedicated render farms.
- Landscape Architecture:Terrain modeling and ecological systems integration for site-responsive projects.
- Simulation:Energy performance, daylighting, and structural analysis requiring physics engines and environmental databases.
Building Design anchors the largest revenue base; Simulation is gaining share fastest as regulatory energy modeling mandates proliferate.
Technology:
Technology stacks stratify by computational intensity and hardware dependency, with neural rendering and spatial computing redistributing workloads from centralized servers to edge devices.
- BIM:Parametric building information modeling with embedded lifecycle data. Enterprise contracts span multi-year facilities management, commanding the deepest margin pools through long-term subscription lock-in.
- Visualization:Real-time and offline rendering pipelines producing photorealistic imagery. GPU compute cost volatility from NVIDIA and AMD datacenter silicon disrupts SaaS margin structures in this segment.
- AR:Spatial computing overlays for field verification. Apple Vision Pro and Meta Quest convergence with photogrammetry pipelines enables as-built validation without specialized survey crews.
- VR:Immersive walkthrough environments for client review and design coordination.
BIM retains the steepest expansion trajectory in absolute dollars; AR is expanding most quickly as hardware-software integration matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Francisco anchors the deepest concentration of cloud-native architecture software development, with Autodesk and Trimble engineering teams driving real-time collaboration features that compress deployment cycles from months to days.
United States
Section 179D tax deductions from the Inflation Reduction Act fuel demand for existing-building energy modeling tools across commercial retrofit portfolios. The EPA's building performance standards tighten compliance thresholds for large commercial structures. Dallas-Fort Worth and Atlanta construction clusters standardize BIM workflows across mixed-use developments.
Germany
EU Green Deal embodied-carbon mandates pull environmental impact modules into BIM workflows for commercial high-rise projects. The national building code now requires lifecycle carbon calculators embedded directly into design documentation. Munich and Frankfurt engineering firms adopt generative design algorithms to reduce structural material waste.
China
GB/T 50378 green building certification mandates digital energy modeling for public projects above 20,000 square meters in Guangdong and Jiangsu provinces. The Cybersecurity Law requires sovereign-cloud or on-premise deployments for government-adjacent construction. Shenzhen and Shanghai urban digitization initiatives concentrate demand for localized BIM platforms.
Japan
METI Construction DX Promotion Grant subsidizes platform adoption contingent on open API compliance and domestic data residency. Prefecture-level procurement in Tokyo and Osaka prioritizes Japanese-language support documentation and local server infrastructure. Nagoya engineering clusters integrate FORUM8 and Graphisoft Japan solutions into infrastructure workflows.
India
The Smart Cities Mission drives urban infrastructure digitization across 100 metropolitan areas, creating demand for vernacular construction typology libraries. Central Electricity Authority building codes tighten energy performance standards for commercial developments. Bengaluru and Hyderabad technology corridors incubate domestic BIM platform startups serving mid-market architectural firms.
Global 3D Architecture Software Market Competitive Landscape
Premium-margin players sit above commodity-margin players across data interoperability depth and multi-stakeholder collaboration capabilities. The market stratifies into three tiers: enterprise suite vendors anchoring high-end BIM workflows, open-BIM specialists capturing mid-market share through cross-platform compatibility, and modular plugin vendors unbundling monolithic suites for boutique studios. Dominant competitive moves include API-first interoperability layer development and sovereign-cloud localization partnerships for data-sensitive jurisdictions.
Within the enterprise suite tier, Autodesk Inc. and Nemetschek Group occupy positions defined by ecosystem breadth versus architectural openness philosophy. Bentley Systems exemplifies infrastructure-specialized positioning with heavy civil and utilities focus. These three vendors anchor distinct competitive vectors: Autodesk leverages Revit ecosystem lock-in across large-scale commercial projects, Nemetschek sustains cross-platform compatibility for mid-market firms resisting single-vendor dependency, and Bentley concentrates on transportation and utility digital twins where geometric complexity exceeds standard architectural workflows.
| Leading Market Players |
|---|
| Autodesk Inc. |
| Nemetschek Group |
| Bentley Systems |
| Trimble Inc. |
| Dassault Systèmes |
| Hexagon AB |
| Siemens Digital Industries Software |
| Graphisoft |
| Bricsys |
| Others |
Supply & Pricing Matrix
Construction company procurement consolidation across commercial high-rise portfolios anchors subscription-based SaaS pricing with tiered seat-count scaling. Autodesk and Nemetschek extract premium rates from enterprise mandates while mid-market studios in Portugal and Denmark drive unbundling toward usage-based billing orchestration.
Pricing Analysis
Value-based pricing tied to project throughput and multi-stakeholder collaboration depth commands premium positioning. Three-tier pricing structure across enterprise, professional, and studio levels separates perpetual-license holdouts from cloud-native subscriptions. Cost compression in the mid-market intensifies because GPU compute volatility from NVIDIA datacenter silicon disrupts SaaS margin structures. Boutique architectural practices exhibit highest price sensitivity, while Turner Construction and Skanska accept long-term enterprise lock-in for interoperability guarantees.
Supply Chain Analysis
Computational design talent scarcity in Germany, the United States, and China constrains platform development velocity and customer implementation capacity. Software engineering draws from game development pipelines, industrial design programs, and academic research institutions. Single-source vulnerability rests on NVIDIA and AMD datacenter silicon for real-time ray-tracing pipelines. Distribution runs through direct enterprise sales teams, value-added resellers, and hyperscaler marketplace listings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market is consolidating into a vertical-integration race where control over geometry kernels and rendering pipelines determines margin capture. Players are pursuing backward integration into AI training infrastructure and edge compute deployment.
For Market Incumbents: Cement ecosystem lock-in through Revit-to-Construction-Cloud data gravity and API-first interoperability layers that neutralize open-BIM challengers. Deepen captive supply of generative design algorithms through proprietary machine-learning topology optimization. Defend against NeRF-based photogrammetry disruptors by acquiring smartphone-capture pipeline specialists.
For New Entrants and Emerging Players: Capture India's Smart Cities Mission whitespace with vernacular typology libraries and localized BIM platforms serving Bengaluru and Hyderabad mid-market firms. India's 100-metropolitan-area digitization program offers lowest competitive density. Lead with sovereign-cloud compliance and regional language documentation to bypass Autodesk-Nemetschek channel presence.
For Investors and Strategic Acquirers: The window for entry favors computational design specialists with Grasshopper-Dynamo proficiency and game-engine rendering expertise. Five-to-ten-year viability hinges on AR field-verification convergence with photogrammetry pipelines. Monitor Apple Vision Pro and Meta Quest enterprise adoption curves as hardware-software integration inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Revit-to-Construction-Cloud data gravity anchors high-end BIM workflows across large-scale commercial projects. |
| Acquisition of Specialist Firm | NeRF-based photogrammetry pipelines enable smartphone-capture surveying without structured light scanners. |
| Geographic Expansion | Sovereign-cloud localization partnerships satisfy Russia's data localization laws and China's Cybersecurity Law mandates. |
| Strategic Partnership | Open API compliance with Japan's METI Construction DX Promotion Grant unlocks prefecture-level procurement in Tokyo. |
| Product Launch | Generative design algorithms with machine-learning topology optimization reduce structural material waste in high-rise construction. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with BIM managers at construction companies, platform engineers at software vendors, IT procurement officers at architectural firms, and integration specialists at channel partners combined with secondary validation. SEC 10-K disclosures, EU Green Deal implementation reports, and China's GB standards documentation supplemented modeling. Bottom-up deployment-model sizing and top-down regional macro anchoring enabled triangulation.
Granularity-level modeling addressed deployment architecture, organization size tier, vertical application, integration complexity, and regional regulatory cluster across the projection horizon. CAGRs derived from segment-level adoption curves and technology-diffusion patterns. Energy performance standard tightening and embodied-carbon reporting mandates served as demand-side forecast inputs alongside GPU compute cost trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory divergence in sustainability metrics and neural rendering hardware-software integration velocity. Forecasts reflect assumptions about EU Green Deal enforcement consistency and China's GB/T 50378 provincial implementation pace. Material deviation in GPU datacenter silicon pricing or IFC 4.3 adoption timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Technology
Middle East and Africa 3D 4D Technology Market
3D Technology
APAC 3D Telepresence Market
3D Technology
3D Reconstruction Market
3D Technology
3D Geospatial Technologies Market
3D Technology
3D Rendering Market
3D Technology
Global 3D 4D Technology Market
3D Technology
APAC 3D 4D Technology Market
3D Technology
Visualization and 3D Rendering Software Market
3D Technology
Global 3D Mapping and 3D Modeling Market
3D Technology
3D Scanner Market
3D Technology
Global Mobile 3D Sensing Market
3D Technology
Contactless 3D Laser Scanner Market
3D Technology
3D Technology Market
3D Technology
Digital Holography Market
3D Technology
3D Mobile Mapping Market
3D Technology
Molecular Modeling Market