
 Bangladesh Telecommunication Industry Market | 2026-2036
Bangladesh Telecommunication Industry Market Size, Share, and Industry Trends Forecast 2026-2036
Bangladesh Telecommunication Industry Market Insights
BTRC licensing renewal cycles for spectrum and unified licenses is unwinding competitive dynamics among operators. Grameenphone Ltd. leverages its extensive rural distribution to sustain subscriber depth across 64 districts. Robi Axiata Limited anchors its position through integrated mobile financial services and content platforms. Banglalink Digital Communications Ltd. competes aggressively on data pricing to capture youth-centric digital consumption segments.
The Bangladesh telecommunication industry encompasses wired and wireless communication infrastructure delivering voice, data, and broadband services through cellular towers, fiber optic cables, and satellite links operating across frequency bands from 700 MHz to 3.5 GHz. Its primary purpose is enabling connectivity for financial inclusion, e-governance, and logistics coordination across one of South Asia's densest populations. Mobile services dominate revenue generation while fiber optics infrastructure represents the fastest-expanding technology segment driven by enterprise cloud adoption and government digitization mandates. Residential customer segments remain volume-heavy though commercial and government enterprises yield superior margin pools through managed service contracts and dedicated leased line arrangements.
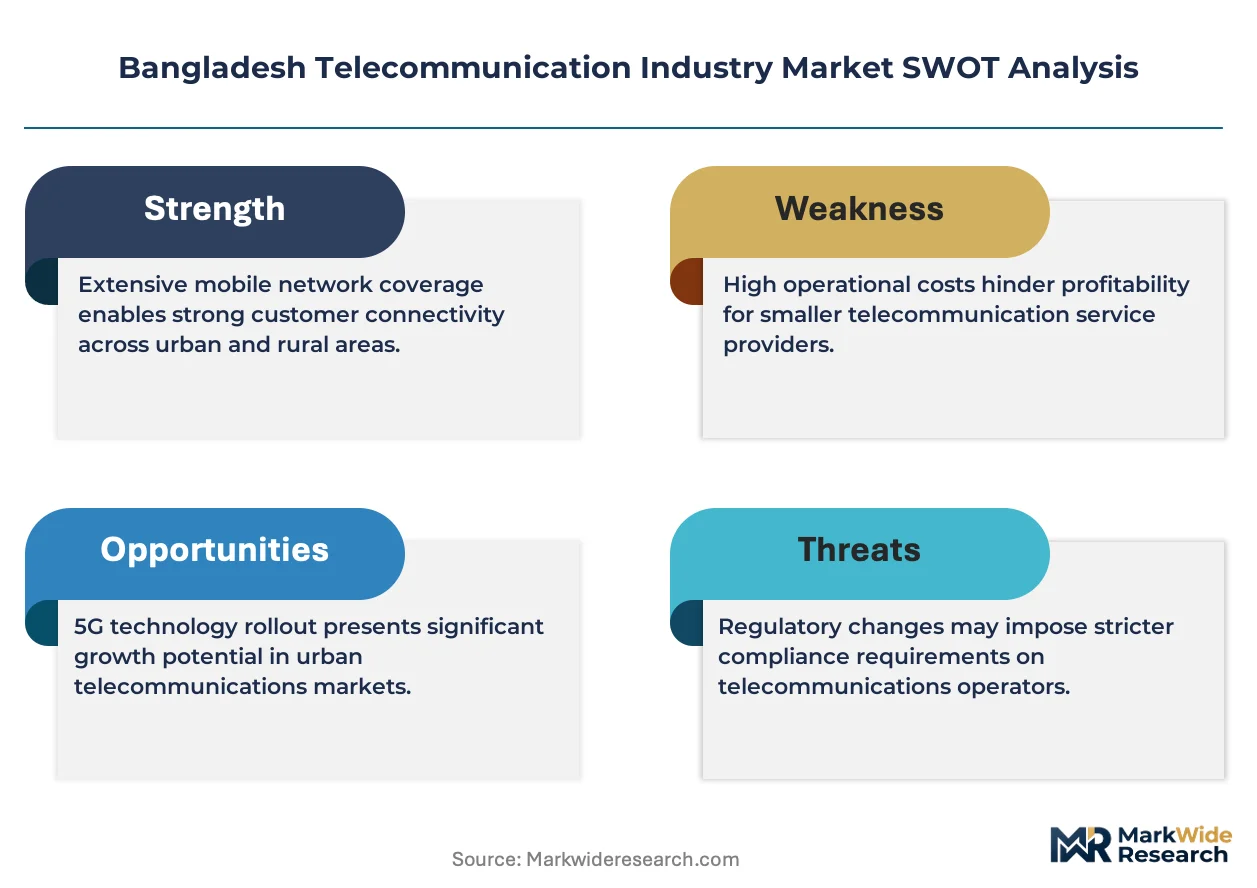
BTRC spectrum auction frameworks and tower sharing directives determine capital efficiency thresholds for operators while the Bangladesh Competition Commission scrutinizes market concentration in mobile financial services. BTRC's mandatory biometric SIM registration requirements and data localization standards shape customer onboarding costs and cloud architecture decisions for providers. Stakeholders must monitor BTRC's pending 5G spectrum allocation timeline and tower infrastructure unbundling enforcement to calibrate capital deployment priorities.
Market Dynamics
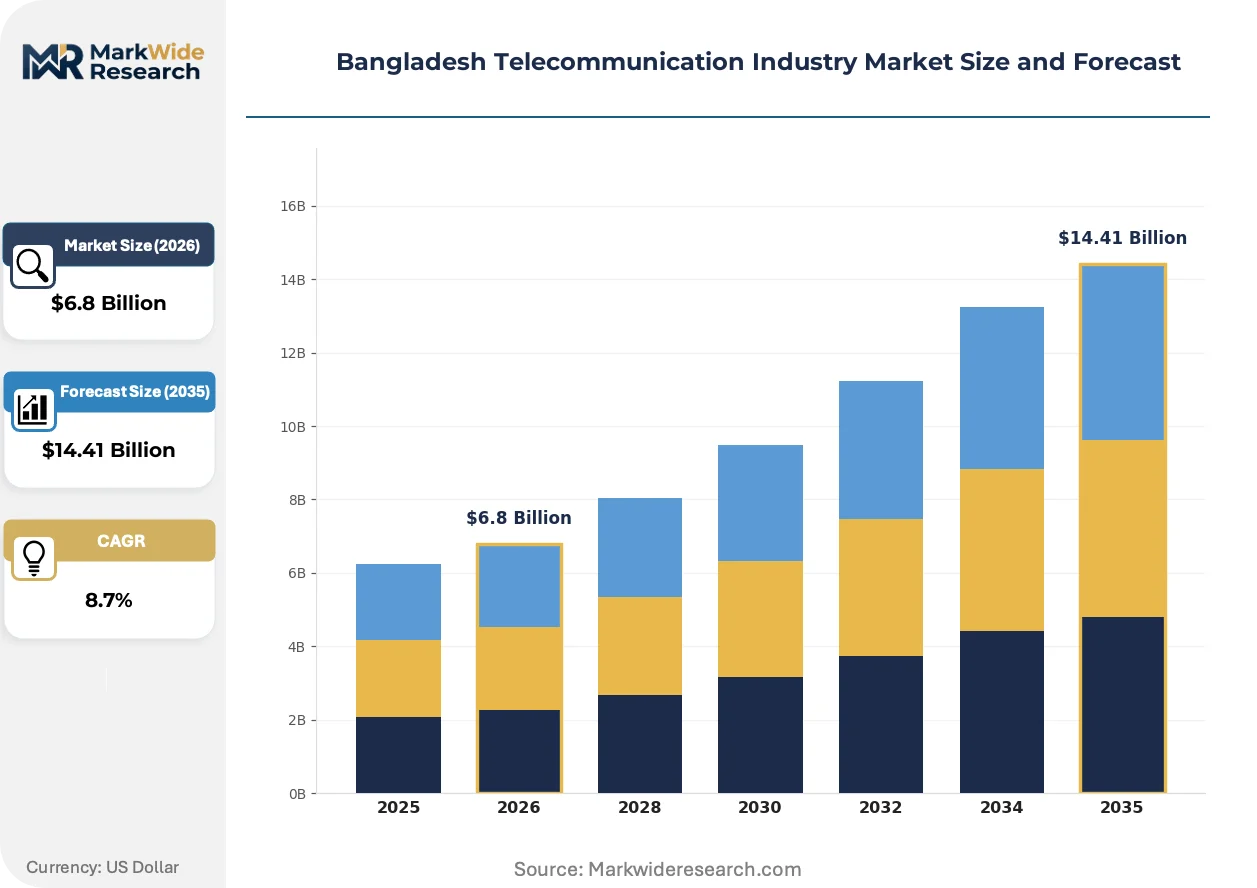
BTRC's tower sharing mandate and pending 5G spectrum allocation are compressing infrastructure economics while forcing operators to recalibrate capital deployment across Dhaka's enterprise corridor and rural micro-entrepreneur networks.
Growth Catalysts
- Rural Mobile Financial Services:Deepening adoption among agricultural micro-entrepreneurs in 64 districts expands transaction volume beyond urban centers.
- BTRC Biometric SIM Registration:Mandatory verification protocols reduce fraud while creating authenticated subscriber bases for digital service layering.
- Enterprise Cloud Migration:Government digitization mandates and port-centric logistics demands in Chattogram accelerate fiber optic infrastructure deployment.
Market Restraints
- Input Cost Volatility:Tower steel and imported networking equipment expose operators to currency fluctuation risks against the Bangladeshi taka.
- Supply Concentration Risk:Limited domestic fiber optic cable manufacturing concentrates procurement dependence on Chinese and Korean suppliers.
- Regulatory Friction:BTRC data localization standards impose redundant infrastructure requirements that inflate cloud architecture costs for international providers.
Strategic Opportunities
- Underpenetrated Sylhet Division:Tea estate corridors and cross-border trade zones present untapped demand for dedicated leased line services.
- 5G-Enabled Industrial IoT:Convergence of low-latency cellular with manufacturing automation creates managed service contracts for export-oriented garment clusters.
- Bangladesh Competition Commission Mobile Financial Services Oversight:Regulatory clarity on market concentration thresholds enables compliant product expansion into credit and insurance adjacencies.
Industry Challenges
- RF Engineering Talent Scarcity:Specialized spectrum optimization and network planning capabilities outpace domestic technical education output.
- Legacy 2G/3G System Integration:Maintaining backward-compatible infrastructure while overlaying 4G and 5G architectures fragments maintenance protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bangladesh Telecommunication Industry Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile, Fixed Line, Internet, VoIP Technology: 4G, 5G, Fiber Optics, LTE Customer Type: Residential, Commercial, Government, Enterprises Distribution Channel: Direct Sales, Retail Stores, Online, Distributors |
| Companies Covered | Grameenphone Ltd., Robi Axiata Limited, Banglalink Digital Communications Ltd., Teletalk Bangladesh Limited, ADN Telecom Limited, Bangladesh Telecommunications Company Limited, Bangladesh Submarine Cable Company Limited, Fiber@Home Limited, Link3 Technologies Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bangladesh Telecommunication Industry Market Trends and Innovations
Active network function virtualization and open RAN architectures are dismantling proprietary hardware lock-ins across Bangladesh's operator base, compressing vendor concentration while enabling multi-vendor interoperability.
Massive MIMO antenna arrays is miniaturizing base station footprints while maintaining spectral efficiency gains. Grameenphone and Robi Axiata are piloting compact 32T32R configurations in Dhaka's dense urban cores. The technology is miniaturizing rooftop and pole-mounted deployment options, reducing site acquisition friction in rights-of-way-constrained municipalities.
BTRC's pending 5G spectrum allocation framework will impose coverage obligations on 700 MHz and 3.5 GHz license winners. The regulation forces rural rollout commitments alongside urban capacity builds. Operators are pre-positioning tower fiberization and power backup systems to meet accelerated deployment timelines once auction terms finalize.
Enterprise procurement of connectivity services is consolidating through managed service aggregators rather than direct operator relationships. Large garment manufacturers and logistics operators in Chattogram are outsourcing network management to specialized IT integrators. This channel shift is most pronounced among export-oriented enterprises requiring SLA-backed international private leased circuits.
Bangladesh Telecommunication Industry Market Segmentation
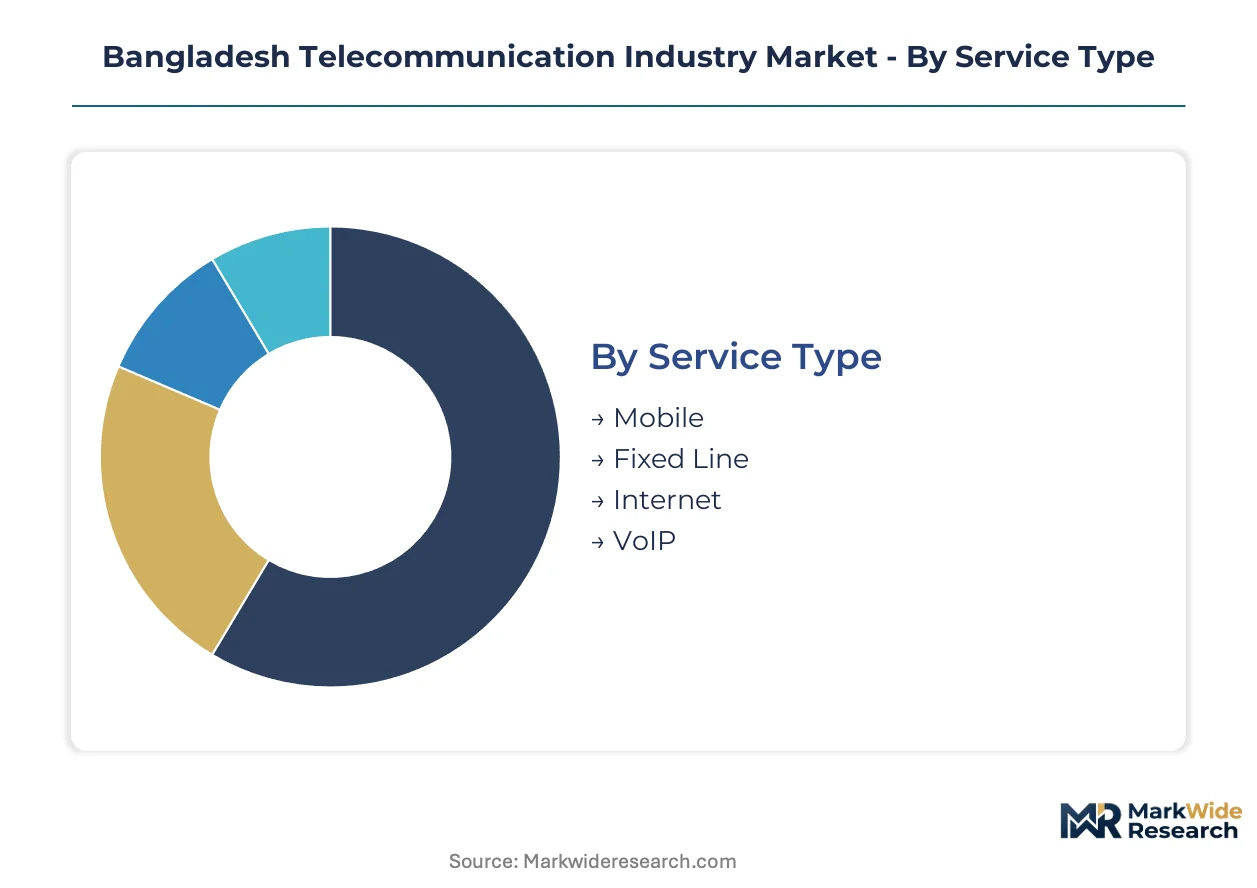
Segmentation in Bangladesh's telecommunication industry reveals how BTRC regulatory frameworks, infrastructure economics, and customer procurement patterns create distinct competitive arenas. Each dimension exposes different margin pools and capital deployment requirements for operators navigating tower sharing mandates and spectrum allocation cycles.
Service Type:
BTRC's unified licensing regime treats service categories as interchangeable under single permits, yet revenue recognition and quality-of-service obligations vary sharply across each segment.
- Mobile:Voice and data services delivered through cellular networks across 700 MHz to 3.5 GHz spectrum bands. Dhaka's enterprise corridor and Chattogram's port logistics zone concentrate ARPU premiums as mobile financial services adoption deepens among rural micro-entrepreneurs across 64 districts.
- Internet:Broadband connectivity via fixed wireless and fiber-to-the-home architectures. Government digitization mandates and enterprise cloud migration in Dhaka's commercial districts drive fiber optic infrastructure expansion as the fastest-expanding technology segment.
- Fixed Line:Traditional copper and fiber-based voice services. Legacy infrastructure maintenance costs weigh on operator economics as subscriber migration to mobile accelerates.
- VoIP:Packet-switched voice over IP protocols. International call termination regulations and OTT platform competition compress standalone revenue potential.
Mobile handles the majority of throughput; Internet is the fastest mover on share.
Technology:
Cost tier differentiation separates capital-intensive next-generation deployments from legacy maintenance obligations, with BTRC coverage mandates forcing parallel investment streams.
- 4G:LTE-Advanced networks operating on 1800 MHz and 2100 MHz bands. Urban capacity builds in Dhaka and Chattogram absorb the bulk of current capital expenditure as operators maximize spectral efficiency before 5G transition.
- Fiber Optics:Dense wavelength division multiplexing and GPON architectures for enterprise and residential broadband. Port-centric logistics demands and government cloud mandates accelerate deployment timelines.
- 5G:New radio standards awaiting BTRC spectrum allocation framework. Pending 700 MHz and 3.5 GHz auction terms will impose rural rollout commitments alongside urban capacity investments.
- LTE:Earlier-generation 4G deployments requiring backward compatibility maintenance. Spectrum refarming pressures intensify as operators reallocate frequencies to 4G-Advanced and 5G.
Fiber Optics captures the steepest expansion trajectory; 4G carries the dominant installed base.
Customer Type:
Volume-maturity trade-offs define this dimension, with residential segments driving subscriber scale and commercial entities yielding superior margin capture through managed service contracts.
- Enterprises:Large corporations requiring SLA-backed dedicated leased lines and managed network services. Export-oriented garment clusters in Chattogram and financial institutions in Dhaka concentrate procurement through IT integrator aggregators.
- Government:Public sector entities under digitization mandates. E-governance initiatives and data localization standards create demand for compliant domestic cloud connectivity.
- Commercial:Small and medium businesses with standardized connectivity needs. Price sensitivity limits margin expansion despite transaction volume scale.
- Residential:Individual consumers dominating subscriber counts. Volume-heavy economics strain infrastructure utilization during peak demand windows.
Enterprises deliver the highest margin per connection; Residential supplies the subscriber depth.
Distribution Channel:
Geography-access friction determines channel effectiveness, with rural penetration requiring physical presence while urban procurement shifts toward digital interfaces.
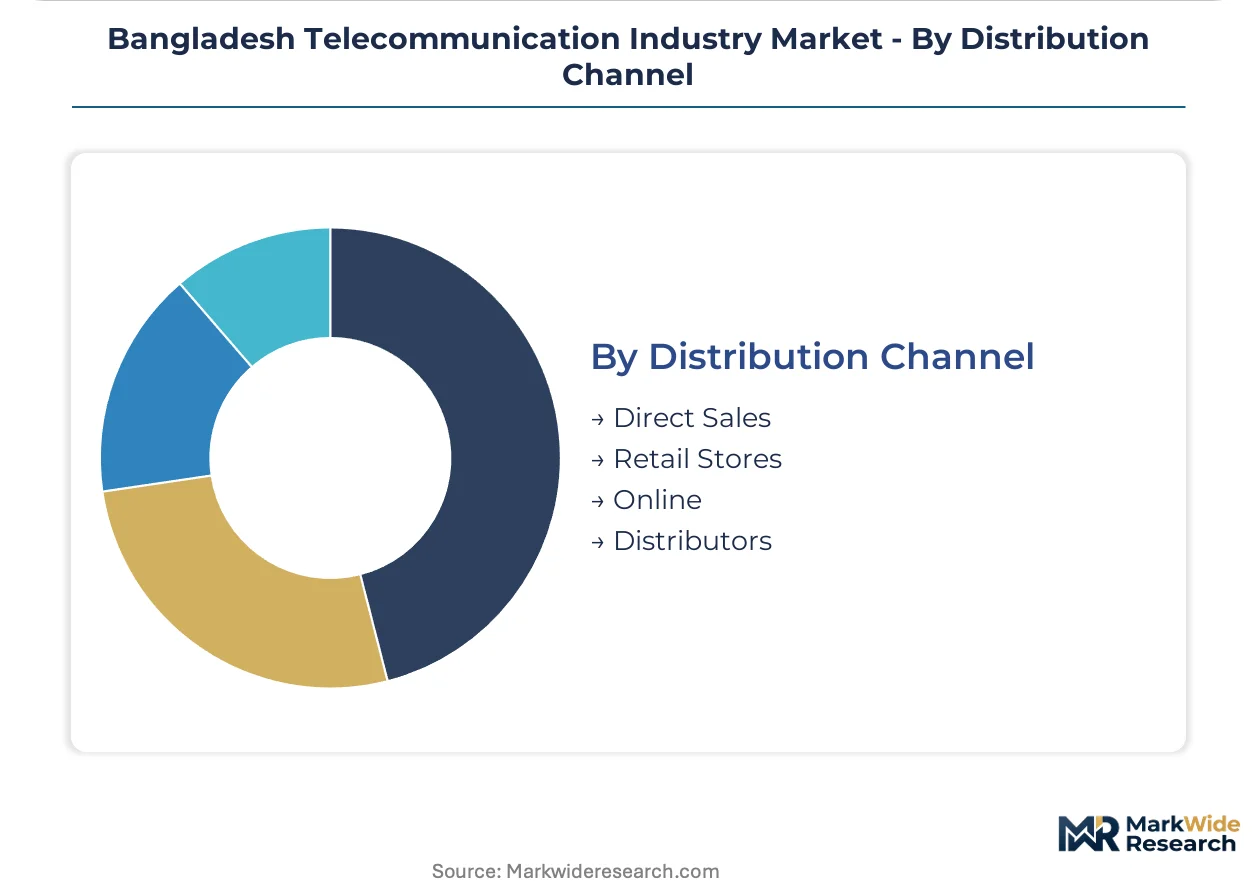
- Retail Stores:Branded and independent physical outlets for SIM sales and recharge services. Grameenphone's 64-district rural distribution network exemplifies coverage-driven competitive positioning.
- Direct Sales:Operator-led enterprise account teams for complex managed service negotiations. Large garment manufacturers and logistics operators in Chattogram prefer direct relationship models for SLA customization.
- Distributors:Wholesale intermediaries extending reach into secondary towns and rural markets. Inventory financing and commission structures shape operator economics.
- Online:Digital platforms for plan selection and SIM delivery. Urban youth-centric segments drive adoption as data pricing competition intensifies.
Retail Stores maintain the widest geographic footprint; Direct Sales commands the highest contract value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
BTRC's tower sharing mandate and biometric SIM registration protocols are redistributing infrastructure investment across Bangladesh's eight administrative divisions, with capital clustering in Dhaka's enterprise corridor while rural micro-entrepreneur networks drive subscriber expansion in peripheral regions.
Dhaka Division
Enterprise cloud migration and government digitization mandates concentrate fiber optic deployment in Dhaka's commercial districts. BTRC's data localization standards require domestic cloud architecture investments from international providers. The capital's enterprise corridor absorbs the majority of managed service contracts for SLA-backed leased lines.
Chattogram Division
Port-centric logistics demands and export-oriented garment clusters accelerate dedicated connectivity procurement. The Bangladesh Competition Commission scrutinizes mobile financial services concentration in this commercial hub. Chattogram's industrial zones outsource network management to IT integrators for international private leased circuits.
Rajshahi Division
Agricultural micro-entrepreneurs deepen mobile financial services adoption across rural distribution networks. BTRC's spectrum auction frameworks impose rural coverage obligations that redirect capital from urban centers. The division's agricultural corridors present untapped demand for authenticated subscriber-based digital services.
Sylhet Division
Tea estate corridors and cross-border trade zones generate demand for dedicated leased line services. The division remains underpenetrated relative to national infrastructure density benchmarks. Sylhet's commercial hubs attract preliminary fiberization investments ahead of formal 5G spectrum allocation.
Khulna Division
Shrimp processing clusters and Mongla port logistics create specialized connectivity requirements for temperature-controlled supply chains. Rural subscriber acquisition costs rise where tower sharing mandates intersect with dispersed population settlements. Khulna's industrial sub-regions pilot compact Massive MIMO configurations for rights-of-way-constrained deployments.
Bangladesh Telecommunication Industry Market Competitive Landscape
Player mix skews toward integrated mobile network operators with unified licensing privileges under BTRC frameworks. Market structure concentrates around three dominant cellular providers while specialized fiber and submarine cable operators occupy infrastructure-tier positions. Strategic archetypes include rural distribution depth players, integrated mobile financial services platforms, and aggressive data pricing competitors. Dominant competitive moves encompass tower infrastructure unbundling compliance and pre-positioned 5G fiberization investments ahead of spectrum auction finalization.
Among Dhaka-headquartered operators, Grameenphone Ltd. and Robi Axiata Limited exemplify contrasting strategic archetypes. Grameenphone occupies a position anchored in 64-district rural distribution networks that sustain subscriber depth. Robi Axiata represents the integrated platform approach combining cellular infrastructure with mobile financial services layering. Banglalink Digital Communications Ltd. sits within the price-competitive tier targeting youth-centric digital consumption segments through aggressive data pricing postures.
| Leading Market Players |
|---|
| Grameenphone Ltd. |
| Robi Axiata Limited |
| Banglalink Digital Communications Ltd. |
| Teletalk Bangladesh Limited |
| ADN Telecom Limited |
| Bangladesh Telecommunications Company Limited |
| Bangladesh Submarine Cable Company Limited |
| Fiber@Home Limited |
| Link3 Technologies Limited |
| Others |
Pricing and Supply Chain Analysis
Long-term managed service contracts lock in both tower infrastructure access and price visibility for Bangladeshi operators navigating BTRC's unbundling mandates. These multi-year agreements tether procurement costs to fiberization timelines while insulating enterprise buyers from currency fluctuation risks against the taka.
Pricing Analysis
Volume scale creates the primary spread between Dhaka enterprise corridors and rural micro-entrepreneur networks. Subscription-tiered data plans dominate consumer segments while SLA-backed dedicated leased lines command premium positioning among Chattogram garment exporters. Cost compression in residential mobile data intensifies as Banglalink competes aggressively for youth-centric digital consumption. Enterprise buyers exhibit lowest price sensitivity due to managed service bundling requirements.
Supply Chain Analysis
Inventory lead times for 5G-ready base station equipment stretch across Chinese and Korean manufacturing hubs. Tower steel and imported networking hardware draw from concentrated East Asian supplier bases. Single-source vulnerability concentrates in domestic fiber optic cable manufacturing capacity. Distribution runs through IT integrator aggregators for enterprise procurement in export-oriented industrial zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bangladesh's telecommunication market functions as a service-attach opportunity where mobile financial services layering expands faster than underlying connectivity hardware. Recurring revenue from authenticated subscriber-based digital services outpaces ARPU growth from pure data consumption.
For Market Incumbents: Consolidate tower infrastructure positions through BTRC-mandated sharing compliance before 5G spectrum allocation finalizes. Lock in rural site access rights across Rajshahi's agricultural corridors to preempt coverage obligation costs. Vertical integration into fiber optic backhaul reduces dependence on Chinese cable imports. For New Entrants and Emerging Players: BTRC biometric SIM certification fast-tracks unlock authenticated subscriber bases for credit and insurance adjacencies. Sylhet Division's underpenetrated tea estate corridors present white-space demand for dedicated leased line services. Partner with IT integrators already embedded in Chattogram's garment cluster procurement channels. For Investors and Strategic Acquirers: Capital is best deployed toward fiber infrastructure operators with pre-positioned 5G backhaul capabilities. Long-term viability hinges on regulatory clarity from Bangladesh Competition Commission mobile financial services oversight. Watch BTRC's pending spectrum auction timeline as the inflection signal for infrastructure valuation resets.| Strategic Initiative | Industry Significance |
|---|---|
| Tower Infrastructure Unbundling | BTRC mandates force asset-light operating models while concentrating ownership among specialized infrastructure funds. |
| 5G Fiber Backhaul Pre-positioning | Operators race to fiberize rural towers ahead of coverage obligations tied to 700 MHz and 3.5 GHz licenses. |
| Mobile Financial Services Integration | Robi Axiata's platform approach demonstrates how authenticated subscribers enable credit and insurance layering. |
| Enterprise Managed Service Aggregation | Chattogram garment exporters outsource network management to IT integrators for SLA-backed international circuits. |
| Rural Distribution Network Expansion | Grameenphone's 64-district physical presence sustains subscriber depth where digital channels fail. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across Bangladesh's eight administrative divisions. Primary interviews captured BTRC regulatory affairs leads, network planning engineers at Grameenphone and Robi Axiata, tower infrastructure procurement managers, and mobile financial services product heads. Secondary validation drew from BTRC spectrum auction notices, Bangladesh Competition Commission filings, operator annual disclosures, and customs data on networking equipment imports. Bottom-up subscriber and revenue modeling triangulated against top-down macroeconomic projections.
Across the analysis window, forecasts segment by service type, technology generation, customer tier, and distribution channel. CAGRs derive from historical trajectory analysis adjusted for regulatory inflection points including pending 5G allocation and biometric SIM mandate enforcement. Industry-specific inputs incorporate BTRC tower sharing compliance timelines and fiber optic deployment rates across Dhaka's enterprise corridor.
The analysis sits within stated boundaries; outcomes outside BTRC's announced regulatory timeline would require recalibration. Forecasts reflect documented assumptions about spectrum allocation sequencing and currency stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Nigeria Telecom Market
Telecommunications
Rich Communication Services (RCS) Messaging Market
Telecommunications
Saudi Arabia Telecom Market
Telecommunications
Global SMB Telecom Voice and Data Services Market
Telecommunications
Denmark ICT Market
Telecommunications
Fixed LTE Market
Telecommunications
Russia Telecom Market
Telecommunications
Asia Pacific Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Cloud Telephony Service Market
Telecommunications
5G Transport Networks Market
Telecommunications
Digital Mobile Radio (DMR) Market
Telecommunications
Costa Rica Telecom Market
Telecommunications
Embedded SIM (Esim) Market
Telecommunications
5G Connections Market
Telecommunications
Germany Critical Communication Market
Telecommunications
Belgium ICT Market