
 Colombia Telecom Market | 2026-2036
Colombia Telecom Market Size, Share, and Industry Trends Forecast 2026-2036
Colombia Telecom Market Outlook
The capital-intensity divergence between fiber-heavy incumbents and mobile-first challengers is redrawing competitive boundaries in Colombian telecommunications. Claro leverages its integrated fixed-mobile infrastructure to sustain pricing power across residential broadband. ETB SA ESP anchors its position through municipal fiber deployments in Bogotá and surrounding corridors. WOM Colombia competes aggressively on mobile data tariffs without comparable wireline depth.
Telecom encompasses the transmission of voice, data, and video across wired and wireless infrastructure operating at frequencies from 700 MHz to 39 GHz with fiber backhaul capacities reaching 100 Gbps per strand. The sector serves commercial coordination, consumer connectivity, and public administration through layered protocol stacks. Broadband Internet and 5G technology represent the fastest-expanding revenue pools as enterprise customers migrate workloads to cloud-based deployment models. Fixed-Line services occupy mature margin territory while Digital TV faces structural compression from over-the-top streaming alternatives.
Colombia's Ministry of Information and Communications Technologies (MinTIC) enforces spectrum allocation rules and infrastructure-sharing mandates under the ICT modernization framework. The Communications Regulation Commission (CRC) governs interconnection tariffs and wholesale access terms that determine challenger viability. Stakeholders must monitor spectrum auction timelines and tower zoning reforms that will dictate capital deployment efficiency across the forecast horizon.
Market Dynamics
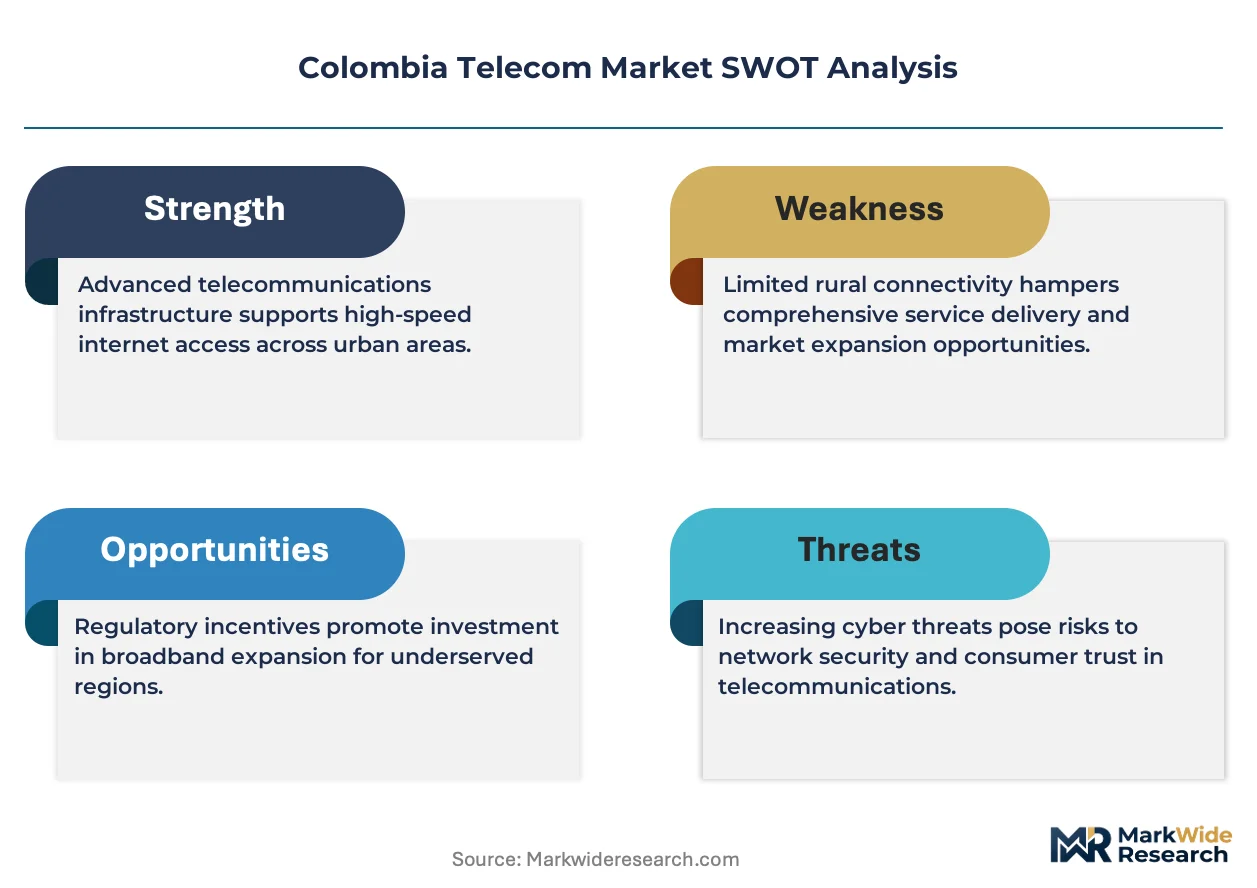
Colombia's ICT modernization law is forcing infrastructure-sharing mandates that compress capital efficiency gaps between fiber-heavy incumbents and mobile-first challengers. This regulatory architecture redistributes competitive advantage toward operators with existing dense metro fiber footprints.
Growth Catalysts
- MinTIC Spectrum Framework:The ministry's allocation rules for 5G mid-band frequencies enable challenger operators to access wholesale tower infrastructure without greenfield buildout costs.
- Enterprise Cloud Migration:Colombian financial institutions and logistics operators are accelerating workload transfers to hyperscale platforms, driving demand for symmetric fiber connectivity and SD-WAN overlay services.
- Bogotá Metropolitan Densification:Fiber deployment intensity in the capital corridor exceeds national averages by substantial margins, creating network effect advantages for operators with established presence.
Market Restraints
- Copper Retirement Costs:Legacy PSTN infrastructure decommissioning imposes stranded asset write-downs on operators with historic fixed-line dominance, compressing free cash flow for reinvestment.
- Tower Zoning Fragmentation:Municipal permitting variance across Colombia's 32 departments creates deployment timeline unpredictability, particularly in secondary cities outside Bogotá's streamlined regulatory environment.
- OTT Substitution Pressure:Streaming platforms displace linear pay-TV subscriber bases, eroding a historically stable revenue pool that subsidized broadband infrastructure amortization.
Strategic Opportunities
- Antioquia and Valle del Cauca Expansion:Medellín and Cali metropolitan zones exhibit fiber penetration gaps relative to Bogotá, presenting whitespace for operators with capital deployment flexibility.
- Convergence of Fixed Wireless and Fiber:5G fixed wireless access technology enables rapid broadband deployment in neighborhoods lacking last-mile fiber duct availability, shortening subscriber acquisition cycles.
- ICT Modernization Incentives:Tax depreciation accelerations for rural connectivity investments under the modernization framework improve project returns in underserved municipalities.
Industry Challenges
- Fiber Splicing Technician Scarcity:Deployment velocity constraints emerge from limited certification programs producing field-ready fusion splicing specialists at scale.
- Interconnection Rate Disputes:CRC-mandated wholesale pricing determinations create margin uncertainty for challenger operators dependent on incumbent network access.
- Legacy Billing System Integration:Converged fixed-mobile service bundles require reconciliation of disparate OSS/BSS platforms, extending product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colombia Telecom Market |
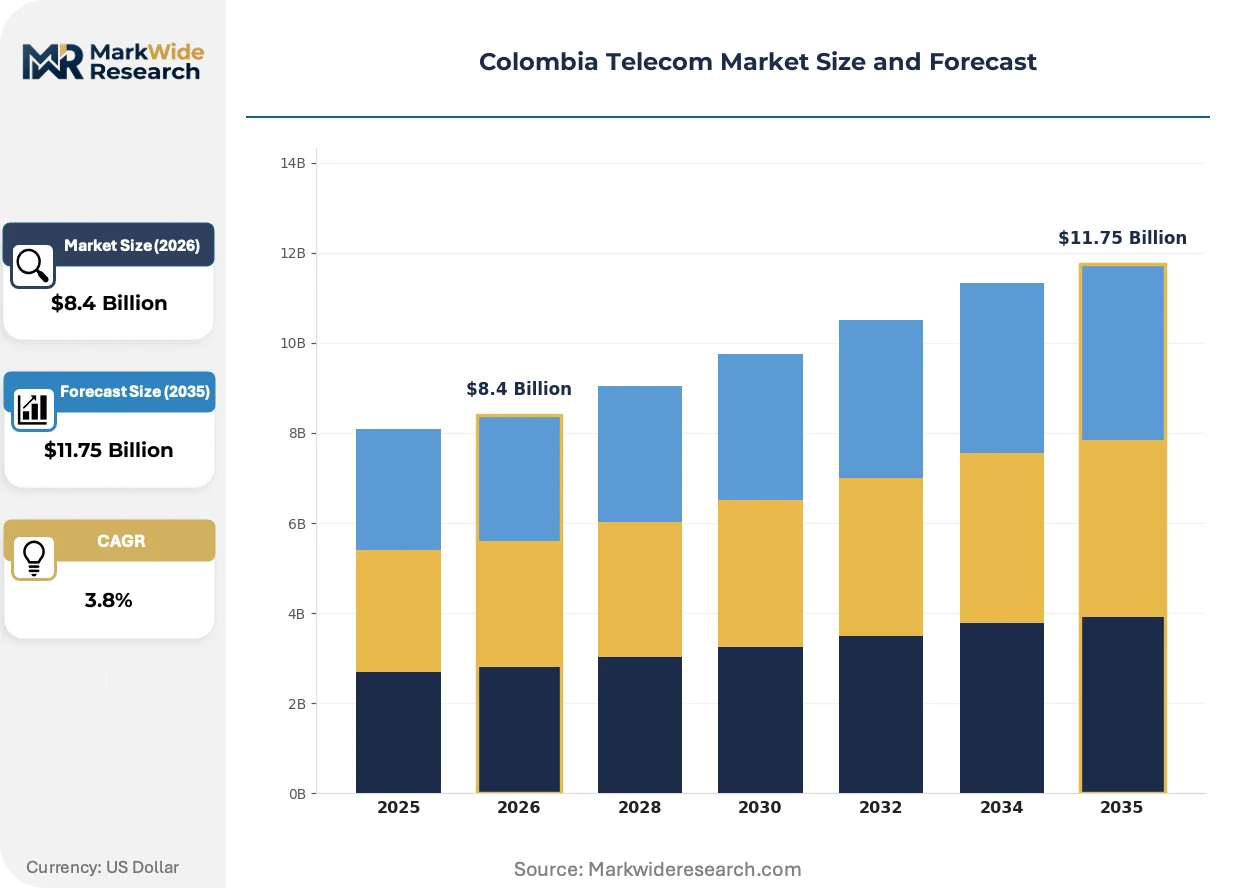
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $11.75 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile Voice, Broadband Internet, Fixed-Line, Digital TV Technology: 4G LTE, 5G, Fiber Optic, DSL Customer Type: Residential, Small Business, Enterprise, Government Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Services |
| Companies Covered | WOM Colombia, ETB SA ESP, Claro, Avantel, Edatel, Movistar Colombia, Virgin Mobile Colombia, Une Epm, Tigo Colombia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colombia Telecom Market Strategic Shifts
Network architecture decisions in Colombian telecommunications are separating into distinct operational models based on underlying infrastructure heritage. This divergence shapes capital allocation patterns and service portfolio priorities across the competitive landscape.
Open RAN deployment is bifurcating mobile network economics by enabling multi-vendor radio access configurations that reduce equipment vendor lock-in. Challenger operators in Colombia are adopting these architectures aggressively to compress unit economics, while integrated incumbents maintain proprietary stack continuity to preserve operational simplicity. The structural consequence is a widening gap in network modernization cadence between capital-constrained and capital-abundant players.
MinTIC's infrastructure-sharing mandates under the ICT modernization framework compel reciprocal site access and co-location pricing transparency. This regulatory architecture reduces barriers to 5G densification for operators lacking tower portfolios, while compressing rental yield premiums for infrastructure-focused entities. Mobile challengers with limited owned physical infrastructure benefit disproportionately from these access terms.
Enterprise procurement of connectivity services is consolidating toward multi-year framework agreements with built-in scalability clauses and service-level guarantees. Colombian financial institutions and multinational logistics operators now prioritize operational expenditure predictability over unit rate minimization, favoring providers with demonstrable network redundancy and cybersecurity certification depth. This preference shift is most pronounced in Bogotá's corporate corridor where procurement functions have professionalized telecommunications category management.
Colombia Telecom Market Segmentation
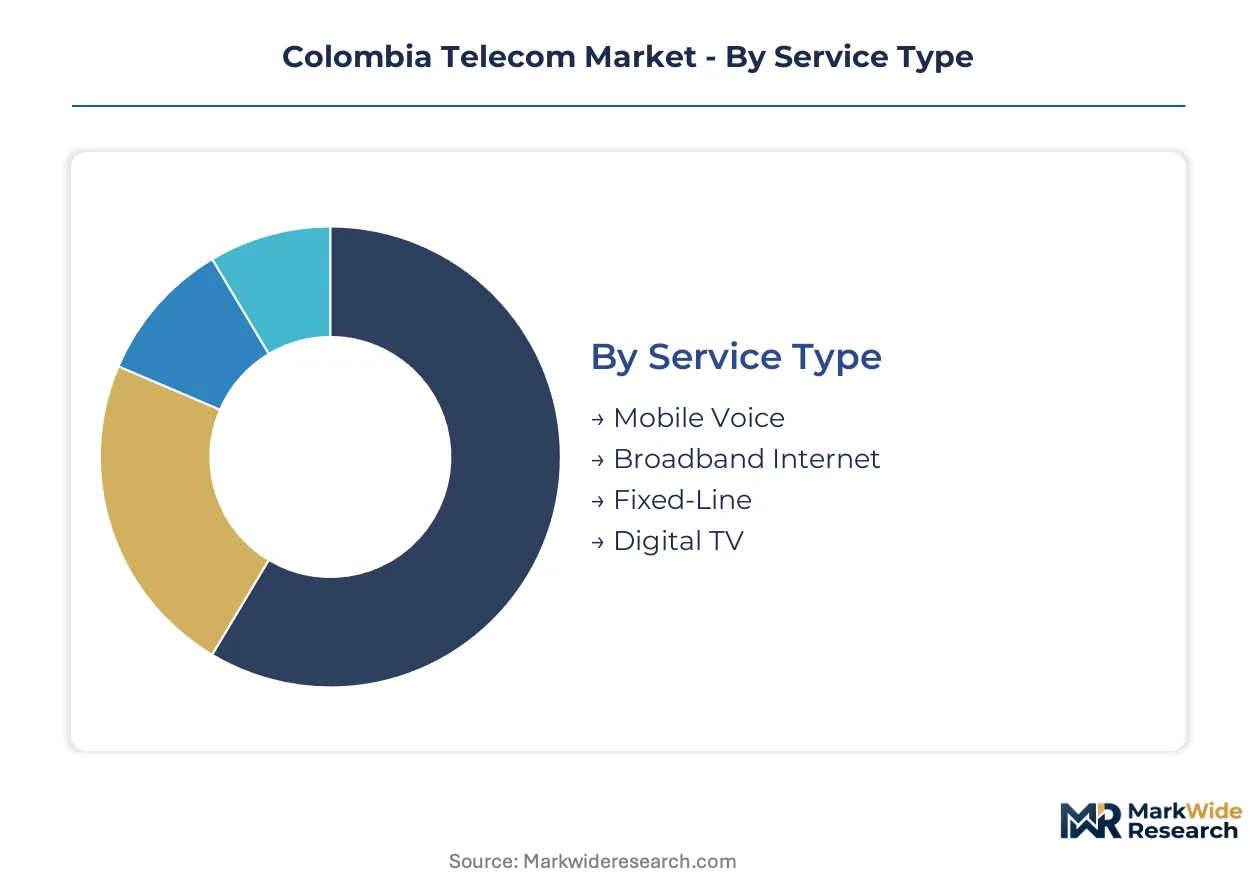
Service differentiation in Colombian telecommunications reflects divergent regulatory treatment and infrastructure economics. Each segment carries distinct margin profiles and capital intensity requirements that shape operator portfolio priorities.
Service Type:
MinTIC's infrastructure-sharing mandates under the ICT modernization framework create asymmetric competitive dynamics across service categories.
- Broadband Internet:Symmetric fiber connectivity supports enterprise cloud migration and SD-WAN overlay demand from Bogotá financial institutions. Capital deployment concentrates in metropolitan corridors where duct access and municipal permitting streamline last-mile construction.
- Mobile Voice:Legacy circuit-switched infrastructure transitions toward VoLTE and 5G packet-core architectures. Revenue per subscriber compresses as over-the-top messaging platforms displace traditional voice traffic, particularly among younger demographics in urban centers.
- Fixed-Line:PSTN copper retirement accelerates under modernization timelines, stranding historic infrastructure investments while freeing operational expenditure for fiber reinvestment.
- Digital TV:Linear pay-TV subscriber bases erode as streaming platforms capture viewing hours, eliminating a revenue pool that historically subsidized broadband infrastructure amortization.
Established volume favors Fixed-Line; emerging adoption favors Broadband Internet.
Technology:
Capital allocation intensity separates deployment models by spectrum access costs and fiber trenching economics.
- 5G:Mid-band spectrum allocations enable fixed wireless access deployment in neighborhoods lacking last-mile fiber duct availability. CRC-mandated wholesale tower access terms reduce greenfield buildout requirements for challenger operators.
- Fiber Optic:Single-strand capacities reaching 100 Gbps support enterprise workload migration to hyperscale platforms. Deployment velocity constraints emerge from limited fusion splicing technician certification programs.
- 4G LTE:Mature radio access networks sustain mobile data traffic in secondary cities outside Bogotá's accelerated 5G densification timeline.
- DSL:Copper-based delivery occupies declining market position as fiber overbuilds accelerate in metropolitan zones and fixed wireless bridges rural connectivity gaps.
Legacy infrastructure favors 4G LTE; network modernization investment favors 5G.
Customer Type:
Procurement sophistication and contract structure vary sharply across buyer categories.
- Enterprise:Multi-year framework agreements with built-in scalability clauses and service-level guarantees prioritize operational expenditure predictability over unit rate minimization. Colombian financial institutions and multinational logistics operators demand demonstrable network redundancy and cybersecurity certification depth.
- Government:Public administration connectivity requirements flow through centralized procurement processes with domestic preference provisions and rural coverage mandates under ICT modernization incentives.
- Residential:Price-sensitive demand concentrates in bundled fixed-mobile offerings requiring converged OSS/BSS platform integration.
- Small Business:Fragmented procurement patterns favor standardized service tiers with limited customization and rapid installation turnaround.
Contract value concentration favors Enterprise; subscriber volume scale favors Residential.
Deployment Model:
Operational control and capital efficiency tradeoffs shape enterprise connectivity procurement.
- Managed Services:Outsourced network operations with performance-based contracting transfer operational risk to service providers while delivering predictable expenditure profiles for Colombian corporate procurement functions.
- Cloud-Based:Software-defined networking overlays enable rapid service provisioning and geographic expansion without physical infrastructure ownership, aligning with enterprise cloud migration timelines.
- Hybrid:Split architectures retain sensitive workloads on-premises while bursting non-critical traffic to cloud infrastructure, addressing data sovereignty concerns in regulated sectors.
- On-Premises:Dedicated infrastructure deployments persist in security-sensitive applications requiring air-gapped network segmentation.
Operational complexity favors On-Premises; scalability and speed-to-deployment favor Cloud-Based.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Residential subscribers in secondary municipalities exhibit acute price sensitivity, while Bogotá-based enterprises prioritize service-level guarantees over rate minimization. This demand-elasticity divergence shapes operator capital allocation across Colombian territory.
Bogotá Capital District
Enterprise cloud migration from financial institutions drives symmetric fiber demand in the metropolitan zone. MinTIC's infrastructure-sharing mandates accelerate 5G densification through wholesale tower access. El Dorado International Airport corridor anchors logistics connectivity requirements with redundant network specifications.
Antioquia Department
Medellín's metropolitan area exhibits fiber penetration gaps relative to Bogotá, creating whitespace for deployment expansion. ICT modernization incentives offer tax depreciation accelerations for rural connectivity investments. Rionegro's cargo airport cluster generates enterprise-grade connectivity procurement from logistics operators.
Valle del Cauca Department
Cali's industrial base sustains demand for managed services and SD-WAN overlays from manufacturing exporters. The Communications Regulation Commission governs interconnection tariffs affecting challenger operator viability. Buenaventura port complex requires maritime-grade telecommunications redundancy for shipping coordination.
Santander Department
Bucaramanga's hydrocarbon services sector purchases dedicated fiber links for field operations coordination. National hydrocarbon regulator ANH mandates communication standards for upstream petroleum infrastructure. Barrancabermeja refinery corridor concentrates industrial telecommunications procurement.
Atlántico Department
Barranquilla's port modernization drives maritime logistics connectivity demand with international bandwidth requirements. Caribbean coastal permitting regimes differ from Andean municipal processes, affecting tower deployment timelines. Free Trade Zone industrial parks specify redundant carrier access for tenant requirements.
Colombia Telecom Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across Colombian telecommunications. Integrated operators with legacy fixed-line infrastructure sustain pricing power through fiber depth, while mobile-first challengers compete on data tariff aggression. The market structure separates into three strategic archetypes: fiber-heavy incumbents, mobile-centric disruptors, and municipal-anchored regional operators. Dominant competitive moves include infrastructure-sharing compliance under ICT modernization mandates and fixed-mobile convergence bundling.
Within the integrated incumbent tier, Claro and Movistar Colombia occupy positions defined by metropolitan fiber density and cross-service bundling capability. ETB SA ESP anchors the municipal-specialist archetype through Bogotá-centric infrastructure control. WOM Colombia exemplifies the mobile-first challenger model, competing without comparable wireline asset depth.
| Leading Market Players |
|---|
| WOM Colombia |
| ETB SA ESP |
| Claro |
| Avantel |
| Edatel |
| Movistar Colombia |
| Virgin Mobile Colombia |
| Une Epm |
| Tigo Colombia |
| Others |
Value Chain & Pricing Dynamics
MinTIC's infrastructure-sharing mandates under Colombia's ICT modernization framework gate both supplier qualification for network equipment vendors and price differentiation among operators simultaneously. Operators with pre-qualified vendor relationships and established tower co-location agreements command premium positioning in enterprise procurement, while challengers face compressed margins on comparable service tiers.
Pricing Analysis
Service contract renewals and managed services extensions drive lifetime value for Colombian operators more than initial subscriber acquisition. Three-tier pricing structure across premium, standard, and economy levels separates enterprise-grade SLAs with cybersecurity certification from residential bundles with basic support. Pricing pressure stems from WOM Colombia's aggressive mobile data tariffs forcing incumbents to match consumer rates without comparable wireline depth. Residential subscribers in secondary municipalities exhibit acute price sensitivity, while Bogotá-based financial institutions prioritize operational expenditure predictability over unit rate minimization.
Supply Chain Analysis
China and South Korea anchor optical transport equipment and radio access network component manufacturing for Colombian operators. Fiber optic cable draws from Chinese producers, while 5G baseband units and antenna arrays source from South Korean and Finnish suppliers. Single-source vulnerability concentrates in specialized fusion splicing equipment where limited certification programs constrain technician availability. Distribution runs through authorized distributor networks with MinTIC-mandated equipment homologation requirements adding qualification layers before field deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Colombia's telecom market sits in a cyclical recovery phase as enterprise cloud migration from financial institutions and logistics operators drives infrastructure refresh cycles. The ICT modernization framework's tax depreciation accelerations for rural connectivity investments provide counter-cyclical stimulus to capital deployment.
For Market Incumbents: Secure fiber densification advantages in Bogotá's metropolitan corridor before challengers exploit infrastructure-sharing mandates to narrow coverage gaps. Defend against WOM Colombia's tariff aggression by accelerating fixed-mobile convergence bundling that mobile-first competitors cannot replicate without wireline asset depth. Prioritize municipal permitting relationships in Antioquia and Valle del Cauca to preempt whitespace entry. For New Entrants and Emerging Players: Lead with fixed wireless access deployment in Medellín and Cali neighborhoods lacking last-mile fiber duct availability, where deployment velocity exceeds trenching timelines. Target enterprise SD-WAN procurement in Rionegro's cargo airport cluster and Buenaventura's port modernization, where logistics operators prioritize rapid installation turnaround over incumbent brand recognition. Emphasize cloud-based service provisioning to bypass legacy OSS/BSS integration burdens that slow integrated operators. For Investors and Strategic Acquirers: MinTIC's upcoming spectrum auction timelines reshape the acquisition landscape toward operators with cleared capital structures for mid-band 5G participation. Long-term viability across the projection horizon favors targets with dense metro fiber footprints and demonstrated wholesale tower access utilization under ICT modernization mandates. Watch CRC interconnection rate determinations as the signal for challenger operator margin sustainability and consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Fiber Densification in Bogotá Corridor | Enterprise cloud migration from Bancolombia and Grupo Aval drives symmetric connectivity demand with premium SLAs. |
| 5G Fixed Wireless Access Deployment | Medellín and Cali neighborhoods lacking duct access enable rapid subscriber acquisition without trenching permits. |
| Infrastructure-Sharing Compliance | MinTIC mandates reduce greenfield tower buildout costs for mobile challengers entering secondary municipalities. |
| SD-WAN Overlay Service Launch | Colombian logistics operators at El Dorado and Rionegro airports prioritize operational expenditure predictability. |
| Copper Retirement Acceleration | PSTN decommissioning under modernization timelines frees operational expenditure for fiber reinvestment in metropolitan zones. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with network planning executives at integrated incumbents, procurement leads at challenger mobile operators, municipal connectivity officers in Bogotá and Medellín, and enterprise IT directors at Colombian financial institutions. Secondary validation drew from MinTIC spectrum allocation filings, CRC interconnection tariff determinations, ANH hydrocarbon communication mandates, and customs data on optical equipment imports. Bottom-up service revenue modeling triangulated against top-down macroeconomic projections across the analysis window.
Across the analysis window, the forecast framework models segmentation by service type, technology generation, customer procurement sophistication, and deployment operational control. CAGRs derive from regression analysis against broadband penetration elasticities and enterprise cloud adoption curves. Industry-specific inputs include fiber splice technician certification program throughput, municipal permitting timeline variance across Colombia's 32 departments, and tower co-location pricing transparency under ICT modernization mandates.
The analysis sits within stated boundaries; outcomes outside sustained enterprise cloud migration velocity or CRC-mandated wholesale access terms would require recalibration. Forecasts reflect documented assumptions on spectrum auction timing and infrastructure-sharing compliance enforcement. Recalibration cycles align with material shifts in MinTIC regulatory determinations and hydrocarbon sector communication standard revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Cambodia Telecom Market
Telecommunications
5G Fronthaul and Backhaul Equipment Market
Telecommunications
Software Defined Radio Market
Telecommunications
Singapore Telecom Market
Telecommunications
Global B2B Telecommunication Market
Telecommunications
Voice Over LTE (Volte) Market
Telecommunications
Cloud RAN Market
Telecommunications
C-RAN Market
Telecommunications
Argentina Telecom Market
Telecommunications
Malaysia Telecom Towers Market
Telecommunications
Indonesia B2B Telecom Market
Telecommunications
5G System Integration Market
Telecommunications
Norway Telecom Market
Telecommunications
South Africa Telecom Tower Market
Telecommunications
MENA Mobile Virtual Network Operator Market
Telecommunications
Satellite Broadband Communication in Public Safety Market