
 Cloud Project Portfolio Management (CPPM) Market | 2026-2036
Cloud Project Portfolio Management (CPPM) Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Project Portfolio Management (CPPM) Market Outlook
Multi-source cloud provisioning is repositioning how enterprises acquire project portfolio capabilities, shifting from monolithic ERP suites to best-of-breed SaaS assemblies. Oracle anchors its position through deep database-to-application integration across hybrid environments. ServiceNow competes by extending IT service management workflows into strategic portfolio planning. Atlassian differentiates through developer-centric project tracking that bridges agile execution with portfolio-level visibility.
Cloud Project Portfolio Management denotes a software architecture enabling centralized planning, resource allocation, and progress tracking across multiple concurrent initiatives through browser-accessible platforms with API-driven interoperability and role-based access controls. Its primary purpose is to replace fragmented spreadsheet and on-premise project tools with real-time dashboards that aggregate status across distributed teams. The deployment dimension shows hybrid cloud configurations capturing expanding interest as enterprises retain sensitive financial data on private infrastructure while leveraging public cloud elasticity for collaboration workloads. Within solution type, SaaS delivery dominates procurement patterns among mid-market buyers seeking reduced capital expenditure, while proprietary platforms sustain premium pricing through embedded AI analytics and predictive risk scoring.
The EU AI Act, GDPR, and ISO 27001 standards collectively shape vendor certification requirements and enterprise procurement criteria across European markets. US buyers navigate overlapping obligations from SEC disclosure rules for material cybersecurity incidents and HIPAA safeguards when healthcare projects intersect with portfolio systems. Stakeholders must monitor how evolving cross-border data localization mandates redefine acceptable deployment architectures for multinational program offices.
Market Dynamics
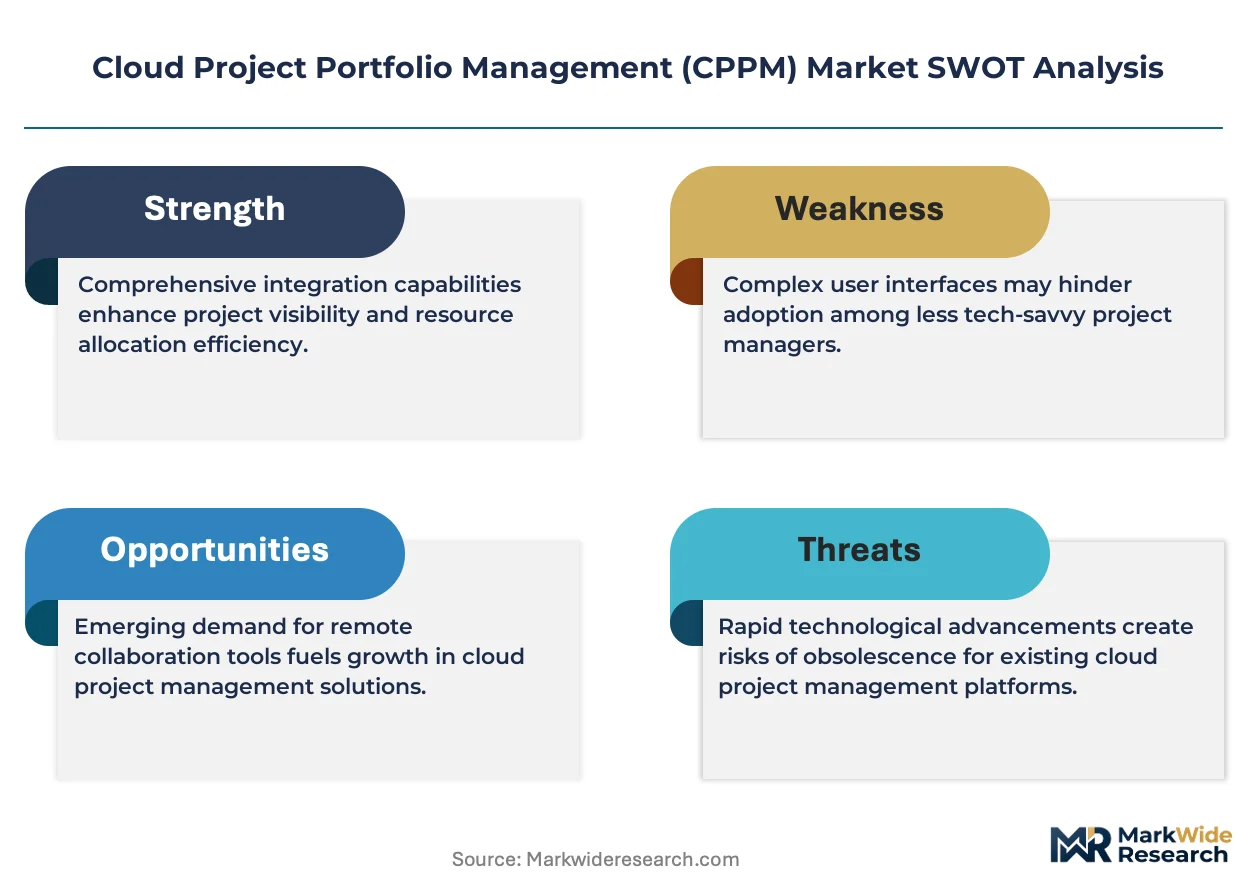
Financial services firms and industrial conglomerates are forcing architectural fragmentation in Cloud Project Portfolio Management procurement, abandoning monolithic ERP suites for modular SaaS assemblies that demand API-native interoperability and real-time data sovereignty controls.
Growth Catalysts
- EU AI Act compliance mandates:European enterprises require auditable workflow platforms with embedded algorithmic transparency logs, accelerating replacement of legacy on-premise systems.
- Hybrid cloud elasticity:Manufacturing and pharmaceutical sectors leverage public cloud collaboration layers while retaining sensitive financial data on private infrastructure.
- Germany's industrial digitalization:Conglomerates operating across automotive and chemical verticals seek unified project orchestration spanning physical production and software transformation initiatives.
Market Restraints
- Cross-border data localization friction:Divergent sovereignty requirements between EU member states and third-country transfer rules complicate multinational deployment architectures.
- API interoperability costs:Best-of-breed SaaS assemblies demand substantial integration expenditure to maintain data consistency across fragmented vendor stacks.
- Specialized talent scarcity:Shortage of professionals combining cloud architecture expertise with portfolio management methodology creates implementation bottlenecks.
Strategic Opportunities
- ISO 27001 certification differentiation:Vendors embedding predictive risk scoring and automated compliance documentation capture premium positioning in regulated European procurement.
- Edge-to-cloud orchestration:Convergence of IoT sensor networks with portfolio dashboards enables real-time resource reallocation for distributed manufacturing programs.
- Mid-market SaaS penetration:Reduced capital expenditure models attract professional services and regional healthcare systems previously locked out of enterprise-tier pricing.
Industry Challenges
- GDPR audit trail complexity:Multi-tenant platforms must reconstruct data lineage across third-party API calls, stretching engineering resources and delaying release cycles.
- Legacy ERP migration friction:Custom workflow configurations in incumbent systems resist standardized extraction, inflating professional services requirements and compressing margin structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Project Portfolio Management (CPPM) Market |
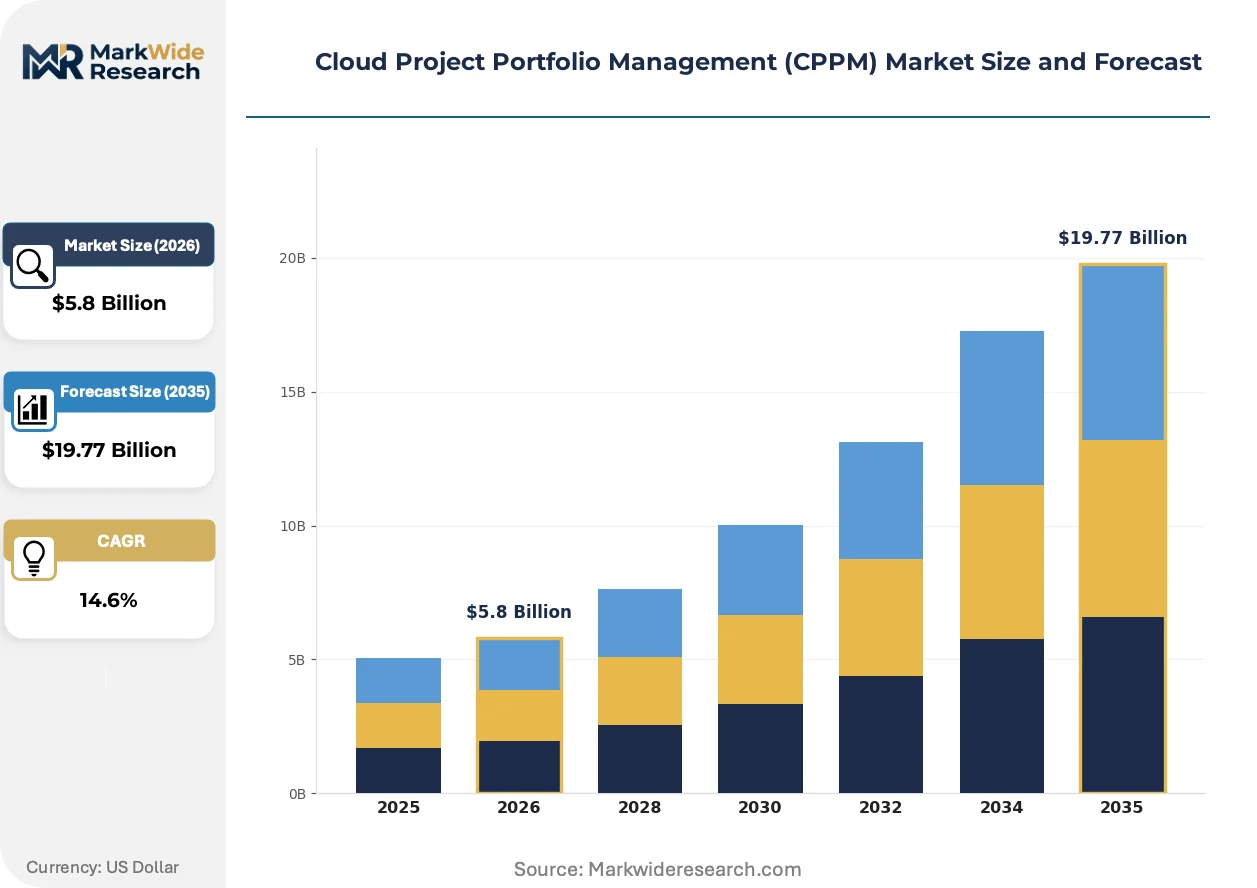
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $19.77 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Solution Type: Open Source, Proprietary, SaaS, On-Premise User Type: Small Enterprises, Medium Enterprises, Large Corporations, Freelancers Industry Vertical: IT Services, Financial Services, Construction, Healthcare |
| Companies Covered | Oracle, ServiceNow, Atlassian, Smartsheet, Microsoft, Broadcom, Hewlett Packard Enterprise, Planview, SAP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Project Portfolio Management (CPPM) Market Strategic Shifts
Generative AI capabilities are embedding into portfolio orchestration layers, shifting competitive advantage from static resource allocation toward predictive scenario modeling and automated risk surfacing.
Natural language query interfaces are converging with structured project data repositories to enable non-technical stakeholders to generate status reports without SQL expertise. Mid-market professional services firms and regional healthcare systems adopt these tools fastest, compressing the traditional business analyst intermediary layer and flattening organizational decision hierarchies.
The EU AI Act's algorithmic transparency requirements are forcing vendors to expose decision logic behind automated resource recommendations. This regulatory pressure fragments product roadmaps as engineering teams divert capacity from feature expansion to explainability infrastructure. German automotive and French pharmaceutical buyers now mandate documentation trails as standard procurement criteria, reshaping vendor qualification processes.
Subscription fatigue among enterprise buyers is fragmenting long-term contracts into modular component purchases. Procurement teams increasingly unbundle portfolio planning from resource management and financial tracking, selecting point solutions with superior interoperability over integrated suites. This pattern concentrates in North American technology and financial services verticals where internal integration capabilities outstrip vendor all-in-one offerings.
Cloud Project Portfolio Management (CPPM) Market Segmentation
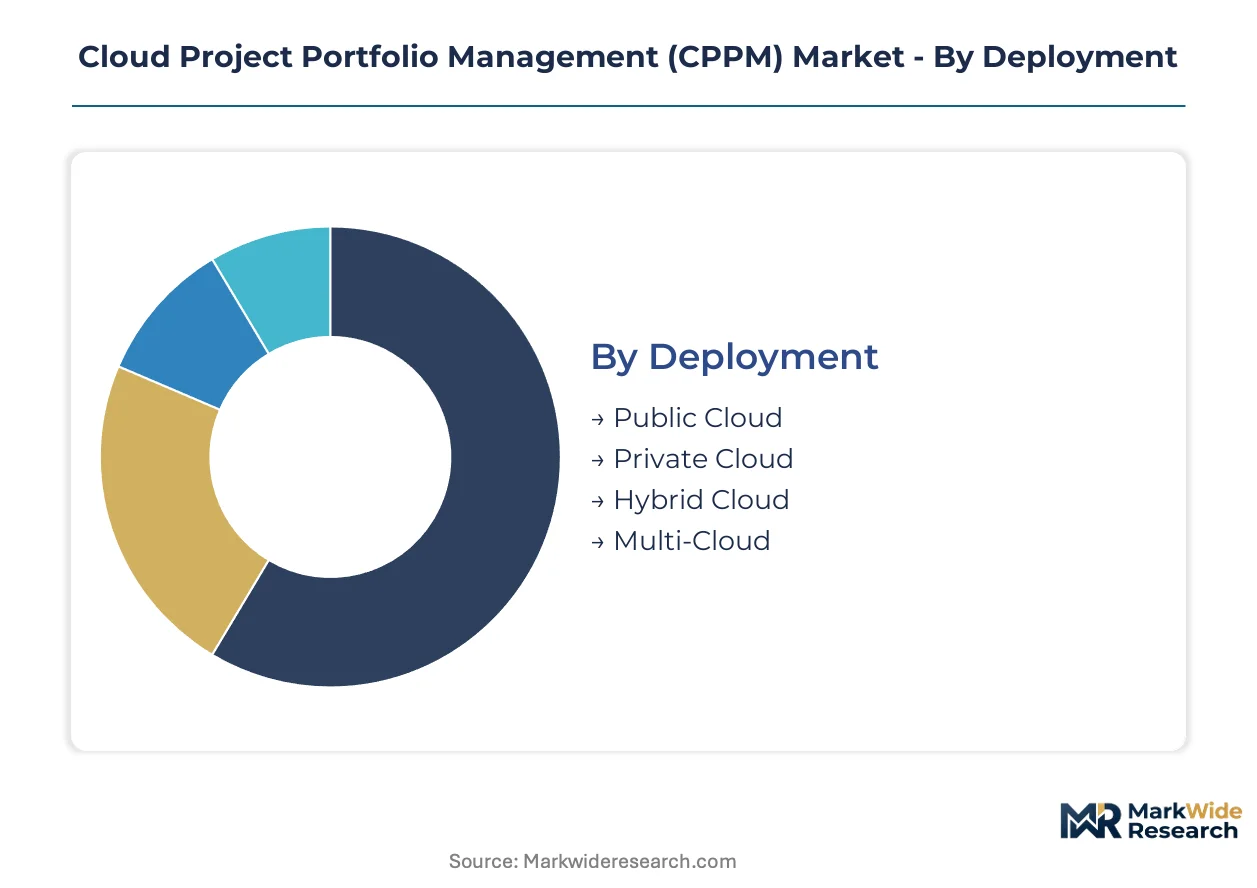
Cloud Project Portfolio Management architectures fragment across deployment models, ownership structures, and organizational scale, with each configuration demanding distinct capital commitments and compliance postures. Procurement teams weight these trade-offs against data sovereignty requirements and integration complexity.
Deployment:
Capital intensity peaks with private infrastructure buildouts, while public consumption models shift expenditure to operational budgets.
- Public Cloud:Third-party managed infrastructure delivers elastic compute without facility investment. Financial services firms in Frankfurt and Singapore concentrate demand here for development sandboxes and non-sensitive collaboration workloads, though GDPR Article 44 transfer mechanisms complicate multi-jurisdictional deployments.
- Private Cloud:Dedicated single-tenant environments demand substantial upfront hardware and operational staffing. German automotive conglomerates and Swiss pharmaceutical manufacturers anchor demand for air-gapped installations handling intellectual property and regulatory submission data.
- Hybrid Cloud:Split architectures retain sensitive financial records on-premises while bursting collaborative workloads to public tiers.
- Multi-Cloud:Orchestration across competing hyperscaler platforms reduces vendor lock-in but multiplies integration expenditure.
Private Cloud absorbs the bulk of installed capacity; Hybrid Cloud is expanding most quickly.
Solution Type:
Ownership models diverge sharply in total cost of ownership, with proprietary platforms commanding premium positioning through embedded compliance tooling.
- SaaS:Subscription delivery eliminates perpetual license procurement and shifts upgrade responsibility to vendors. Mid-market professional services firms across North America and regional healthcare systems in the Nordics drive fastest adoption, attracted by reduced capital expenditure and ISO 27001-certified multi-tenant environments.
- Proprietary:Vendor-controlled codebases with embedded AI analytics and predictive risk scoring command substantial premiums. Large European financial institutions mandate these platforms for EU AI Act algorithmic transparency requirements, accepting vendor lock-in for audit-ready documentation trails.
- Open Source:Community-maintained codebases demand substantial internal engineering for enterprise hardening.
- On-Premise:Perpetual licenses with local installation persist in defense and classified government programs.
SaaS deployments dominate new procurement velocity; Proprietary platforms capture the steepest pricing premiums.
User Type:
Organizational scale determines feature complexity requirements and support tier expectations.
- Large Corporations:Multi-divisional program offices demand enterprise-grade governance, resource leveling across hundreds of concurrent initiatives, and dedicated customer success management. Industrial conglomerates in Germany and technology multinationals in the United States anchor this segment, requiring API-native interoperability with existing ERP investments.
- Medium Enterprises:Growth-stage companies seek scalable platforms without enterprise overhead. Professional services firms with 200-2,000 employees across Canada and Australia concentrate here, prioritizing rapid implementation and pre-configured workflow templates over customization depth.
- Small Enterprises:Limited IT staffing drives preference for turnkey configurations with minimal implementation support.
- Freelancers:Individual practitioners utilize stripped-down project tracking for client billing and milestone management.
Large Corporations command the deepest feature roadmaps; Medium Enterprises are climbing the fastest in absolute seat additions.
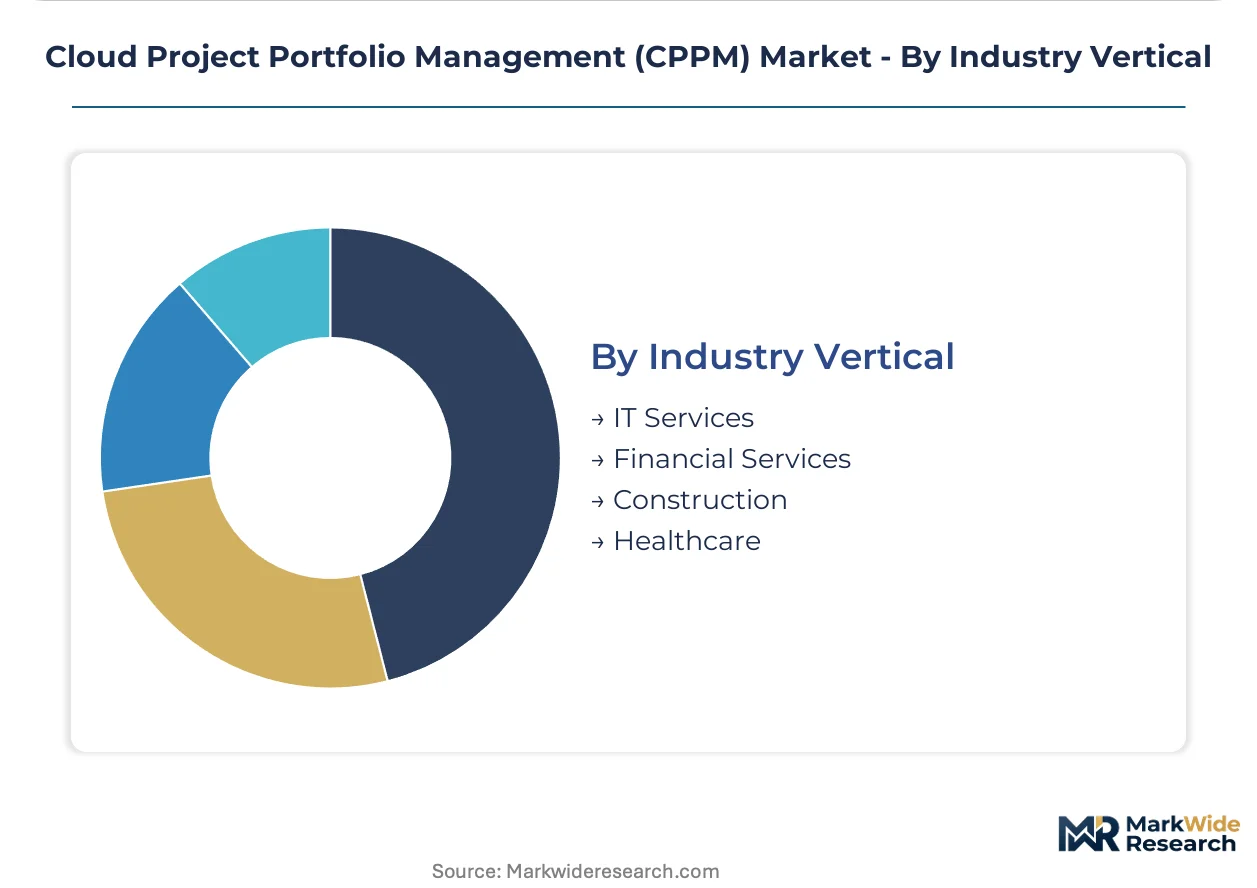
Industry Vertical:
Sector-specific compliance and workflow patterns reshape platform requirements across verticals.
- Financial Services:SEC disclosure rules for material cybersecurity incidents and overlapping HIPAA obligations for healthcare-adjacent portfolios demand hardened audit trails. Investment banks in New York and insurance conglomerates in London drive procurement of platforms with embedded risk scoring and real-time regulatory reporting.
- Healthcare:Patient data proximity constrains deployment architectures and mandates Business Associate Agreements with vendors. Hospital systems in California and national health services in England prioritize ISO 27001 certification and granular role-based access controls for research project portfolios.
- IT Services:Agile methodology dominance favors developer-centric tools with sprint-to-portfolio rollup visibility.
- Construction:Physical project delivery requires integration with building information modeling and supply chain logistics platforms.
Financial Services maintains the largest installed base; Healthcare is gaining share fastest as post-pandemic digitalization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Financial services firms in the United States and industrial conglomerates in Germany concentrate the highest CPPM procurement velocity, with compliance-driven replacement cycles accelerating across both markets.
United States
Investment banks in New York and technology multinationals in Seattle drive demand for API-native portfolio orchestration. SEC disclosure rules for material cybersecurity incidents mandate hardened audit trails, pushing buyers toward platforms with embedded risk scoring. Silicon Valley SaaS vendors capture mid-market share through reduced capital expenditure models.
Germany
Automotive conglomerates in Stuttgart and chemical manufacturers in Ludwigshafen seek unified project orchestration spanning physical production and software transformation. EU AI Act algorithmic transparency requirements reshape vendor qualification, with documentation trails now standard procurement criteria. Frankfurt financial services firms anchor hybrid cloud adoption for development sandboxes.
United Kingdom
Insurance conglomerates in London and professional services firms in the Square Mile prioritize ISO 27001-certified multi-tenant environments. GDPR Article 44 transfer mechanisms complicate multi-jurisdictional deployments for multinational program offices. Edinburgh-based fintech clusters adopt developer-centric tools with sprint-to-portfolio rollup visibility.
Japan
Electronics manufacturers in Tokyo and automotive suppliers in Nagoya leverage METI industrial digitalization incentives for cloud migration. JIS standards compliance shapes procurement criteria for manufacturing portfolio systems. Osaka-based pharmaceutical firms demand granular role-based access controls for research project portfolios.
India
IT services exporters in Bangalore and Hyderabad adopt agile methodology platforms bridging execution with portfolio-level visibility. RBI data localization guidelines constrain deployment architectures for financial services projects. Mumbai-based conglomerates seek scalable platforms without enterprise overhead for digital transformation initiatives.
Cloud Project Portfolio Management (CPPM) Market Competitive Environment
Strategic partnerships dominate the current landscape as vendors assemble best-of-breed SaaS ecosystems through API-native interoperability. The vendor base concentrates around three tiers: hyperscale cloud platforms with database-to-application integration, IT service management extenders with workflow automation, and developer-centric specialists with agile execution tools. Two archetypes define competitive positioning: ERP incumbents defending through hybrid environment coverage, and cloud-native challengers attacking through reduced implementation friction. M&A activity and geographic expansion represent the dominant competitive moves, with buyers seeking specialized talent and regional compliance expertise.
Within the hyperscale platform tier, Oracle and Microsoft exemplify database-to-application integration strategies across hybrid environments. ServiceNow occupies a position among IT service management extenders, bridging operational workflows into strategic portfolio planning. Atlassian anchors the developer-centric specialist archetype, representing agile execution tools that flatten organizational decision hierarchies through natural language interfaces.
| Leading Market Players |
|---|
| Oracle |
| ServiceNow |
| Atlassian |
| Smartsheet |
| Microsoft |
| Broadcom |
| Hewlett Packard Enterprise |
| Planview |
| SAP |
| Others |
Value Chain & Pricing Dynamics
API engineering labor costs in Bangalore and Hyderabad cascade through SaaS subscription tiers, with vendor engineering centers in India feeding premium pricing for proprietary platforms while standardized SaaS offerings absorb margin compression from automated deployment pipelines.
Pricing Analysis
Volume concentrates in mid-market SaaS tiers where per-seat economics dominate procurement decisions, while margin concentrates in proprietary deployments embedding EU AI Act compliance tooling. Pricing stratifies across enterprise-grade platforms with embedded risk analytics, standard multi-tenant SaaS with ISO 27001 certification, and economy tiers for regional healthcare systems with limited IT staffing. Cost compression in standard tiers is intensifying because hyperscaler infrastructure commoditization erodes differentiation. Regional healthcare systems in the Nordics exhibit highest price sensitivity; large European financial institutions demonstrate lowest sensitivity due to regulatory mandate coverage.
Supply Chain Analysis
India's domestic-content requirements for government cloud procurement are reshaping vendor data center buildouts, with local presence mandates forcing hyperscalers to establish Mumbai and Hyderabad facilities. Engineering talent concentrates in India, Ireland, and Poland, with platform development drawing from Bangalore IT services exporters and Dublin-based European headquarters. Raw material dependencies span hyperscaler compute capacity, open-source framework maintenance, and specialized compliance documentation services. Single-source vulnerability runs through concentrated hyperscaler infrastructure for multi-tenant deployments. Distribution runs through direct vendor sales for enterprise accounts and cloud marketplace channels for mid-market procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud Project Portfolio Management sits in a technology-transition phase as generative AI capabilities displace static resource allocation tools with predictive scenario modeling.
For Market Incumbents: Hedge against API interoperability cost inflation by deepening captive engineering presence in Poland and Ireland, where EU AI Act compliance expertise concentrates. Acquire specialized algorithmic transparency tooling vendors to defend against cloud-native challengers attacking through reduced implementation friction. Certification investment in automated compliance documentation represents the critical defensive lever. For New Entrants and Emerging Players: EU AI Act algorithmic transparency requirements in Germany open a window for niche vendors offering explainability infrastructure as standalone modules. Target mid-market professional services firms in Canada and Australia with pre-configured workflow templates and natural language query interfaces. A developer-centric go-to-market angle bridging agile execution with portfolio visibility captures fastest adoption velocity. For Investors and Strategic Acquirers: Consolidation of procurement teams unbundling integrated suites into modular component purchases is the leading indicator that interoperability specialists will command premium valuations. Over the medium-term horizon, acquisition targets should profile as mid-cap SaaS vendors with proven API-native architectures and established ISO 27001 certification. Watch for German automotive conglomerates mandating documentation trails as standard procurement criteria as the definitive demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-native interoperability with Oracle and ServiceNow ecosystems captures enterprise procurement mandates. |
| Acquisition of Specialist Firm | Algorithmic transparency tooling vendors address EU AI Act compliance requirements reshaping German qualification processes. |
| Geographic Expansion | Mumbai and Hyderabad data centers satisfy India's domestic-content rules for government cloud portfolios. |
| Strategic Partnership | Hyperscaler alliances with Microsoft and AWS accelerate hybrid cloud elasticity for manufacturing workloads. |
| Product Launch | Natural language query interfaces flatten decision hierarchies in mid-market professional services firms. |
Study Parameters
Independent corroboration across primary interviews with CTOs, IT procurement officers, platform engineers, and integration specialists, alongside secondary validation through SEC filings, hyperscaler capex disclosures, cloud marketplace data, and compliance certification databases, underwrites the qualitative findings. Bottom-up segmentation modeling triangulates against top-down market sizing from vendor revenue disclosures and enterprise software spending surveys.
Comparable-period anchoring to pre-pandemic baseline years establishes the forecast window trajectory across deployment models, organization size tiers, vertical adoption patterns, integration complexity levels, and regional regulatory clusters. CAGRs derive from fitted growth curves applied to validated baseline values, with inputs spanning IT services employment trends, EU regulatory implementation timelines, and hyperscaler infrastructure expansion announcements.
The model assumes a particular technology adoption path; alternative pathways for generative AI integration would alter the outlook if explainability infrastructure investment lags regulatory mandate acceleration. Forecasts reflect documented assumptions about compliance timeline adherence and talent availability in key engineering hubs. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
IT Service Management Market
Digital Solutions
Digital String Encoder Market
Digital Solutions
United Kingdom Digital Twin Market
Digital Solutions
Online Advocacy Platform Market
Digital Solutions
Software Defined Application and Infrastructure Market
Digital Solutions
Track and Trace Solutions Market
Digital Solutions
Cloud Backup and Recovery Market
Digital Solutions
Policy Orchestration Market
Digital Solutions
Cloud Based Simulation Application Market
Digital Solutions
Premium Messaging Market
Digital Solutions
Big Data As a Service (Bdaas) Market
Digital Solutions
Global Cloud Monitoring Tools Market
Digital Solutions
Asia Pacific B2C Legal Services Market
Digital Solutions
Digital Business Support System Market
Digital Solutions
Global Corporate Volunteering Platform Market
Digital Solutions
Graphical Situational Display Market