
 Agriculture Software Market | 2026-2036
Agriculture Software Market Size, Share, and Industry Trends Forecast 2026-2036
Agriculture Software Market Analysis
Open-source data protocols are broadening the interoperability of cloud-based farm management systems, reducing switching costs for growers. Deere & Company leverages its embedded hardware-software ecosystem to dominate precision agriculture platforms. Trimble Inc. sustains technology leadership in GNSS-guided field operations across North America and Europe. AGCO Corporation differentiates through open-platform architecture that integrates third-party agronomic data layers.
Agriculture software encompasses digital platforms that collect, process, and visualize agronomic data to optimize crop and livestock operations, typically integrating satellite imagery, sensor telemetry, and predictive analytics algorithms into unified decision-support dashboards. Farm management software anchors the largest revenue pool by consolidating financial, operational, and compliance workflows for enterprise-scale producers. Precision agriculture represents the fastest-expanding segment as variable-rate input applications demonstrate measurable yield improvements and input cost reductions. Cloud-based deployment models are capturing share from on-premises installations by enabling real-time field-to-office synchronization and reducing IT infrastructure burdens for mid-sized farming operations.
The United States Department of Agriculture channels conservation compliance requirements through software-enabled record-keeping, while the EPA mandates nutrient management documentation that precision agriculture tools satisfy. The EU Green Deal's Farm to Fork Strategy and CSRD reporting obligations are compelling European agribusiness firms to adopt traceability software for supply chain emissions accounting. Stakeholders must evaluate whether platform consolidation or specialized point solutions offer superior returns as data sovereignty and cross-border interoperability standards crystallize across jurisdictions.
Market Dynamics
Platform consolidation pressures are reshaping competitive positioning as large-scale agribusinesses demand unified data ecosystems over fragmented point solutions. The EU Green Deal's Farm to Fork Strategy and USDA conservation compliance mandates are accelerating standardization requirements across cloud-based farm management systems.
Growth Catalysts
- EU Green Deal Farm to Fork Strategy:Mandates precision agriculture tools to reduce chemical inputs across European arable operations, creating regulatory pull for variable-rate application software.
- USDA conservation compliance:Channels federal conservation program requirements through software-enabled record-keeping, embedding digital documentation into commercial row-crop operations.
- Sensor telemetry convergence:Integration of soil moisture probes, weather stations, and drone imagery into unified dashboards is compressing decision cycles for enterprise producers.
Market Restraints
- Data interoperability friction:Proprietary data formats from embedded hardware ecosystems lock growers into single-vendor platforms, elevating switching costs.
- Rural broadband deficits:Connectivity gaps in agricultural heartlands limit real-time cloud synchronization for mid-sized farming operations.
- Cybersecurity exposure:Centralized farm data repositories attract ransomware targeting, with limited IT security infrastructure across producer operations.
Strategic Opportunities
- CSRD emissions accounting:EU Corporate Sustainability Reporting Directive obligations are compelling agribusiness firms to adopt traceability software for supply chain carbon documentation.
- Livestock management digitization:Cattle and dairy operations remain underpenetrated relative to crop-focused platforms, presenting white space for animal health monitoring integration.
- Open-source protocol adoption:AgGateway's ADAPT framework and similar interoperability standards are enabling third-party data layer integration, reducing platform lock-in.
Industry Challenges
- Agronomic data science talent scarcity:Shortage of professionals bridging crop science, data engineering, and software development constrains vendor R&D velocity.
- Legacy equipment integration:Retrofitting decades-old machinery with IoT connectivity requires custom hardware adapters, complicating deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agriculture Software Market |
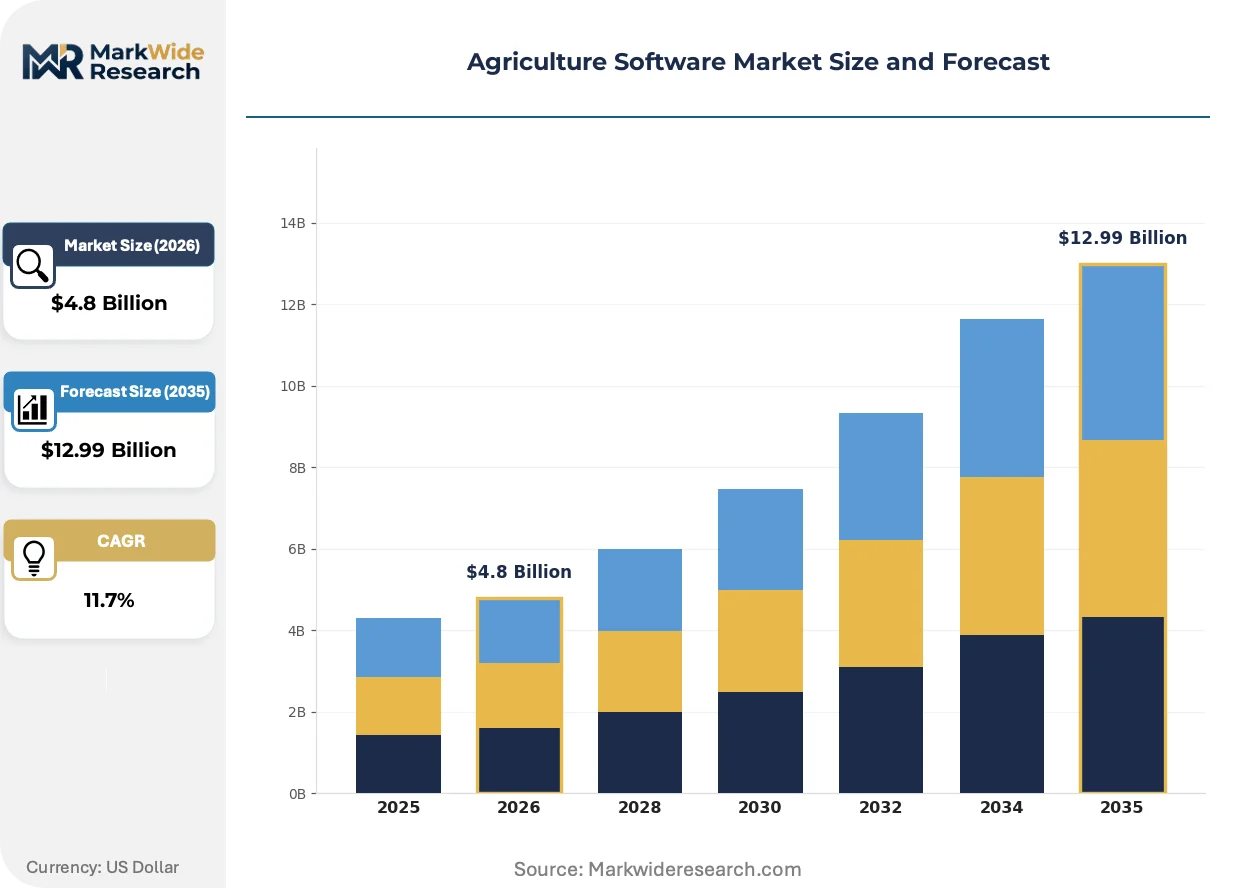
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Farm Management, Irrigation Management, Precision Agriculture, Livestock Management Deployment: On-Premises, Cloud-Based, Hybrid, Mobile End User: Farmers, Agricultural Cooperatives, Agribusiness Companies, Research Institutions Application: Crop Monitoring, Yield Prediction, Soil Analysis, Resource Management |
| Companies Covered | Deere & Company, Trimble Inc., AGCO Corporation, CNH Industrial N.V., Topcon Corporation, Raven Industries, AG Leader Technology, Bayer AG, Corteva Agriscience, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agriculture Software Market Emerging Trajectories
Edge computing architectures are electrifying field-level data processing, reducing latency for autonomous equipment decisions. Satellite imagery resolution improvements and AI-driven pest detection are compressing response windows. Subscription pricing models are displacing perpetual licenses across mid-market segments.
Computer vision systems trained on crop disease pattern recognition are electrifying early-intervention protocols for fungal and pest pressures. Large-scale grain operations in the US Corn Belt and Ukrainian wheat belts are deploying these tools at scale during 2024 growing seasons. The technology is compressing yield loss windows from weeks to days, restructuring crop protection procurement cycles around real-time alerts rather than calendar schedules.
The EU CSRD and F-Gas Regulation are mandating granular emissions documentation across agricultural supply chains. European dairy cooperatives and arable conglomerates must now source farm-level input data for scope 3 reporting. Specialty crop operations in Spain, the Netherlands, and Poland are responding by consolidating previously siloed field records into unified traceability platforms.
Consolidated procurement by agricultural cooperatives is concentrating software purchasing power. French and German farm cooperatives now negotiate enterprise licenses covering thousands of member operations, displacing individual grower subscriptions. This channel shift is most visible in nitrogen management and carbon credit verification software categories, where cooperative-scale data aggregation unlocks premium pricing tiers.
Agriculture Software Market Segmentation
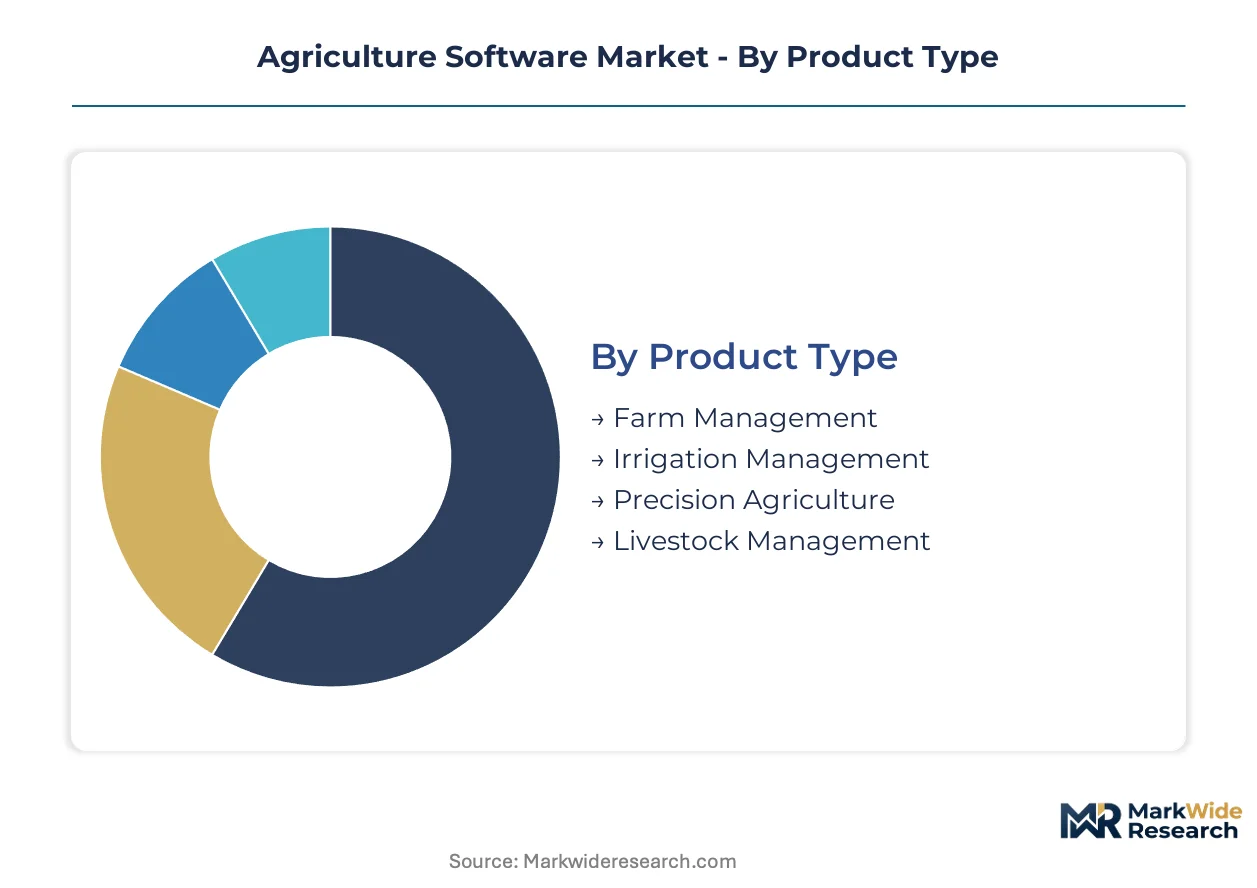
Agriculture software vendors architect platform roadmaps around four intersecting dimensions. Product functionality, deployment architecture, customer scale, and agronomic application layer together determine pricing tiers and implementation complexity.
Product Type:
USDA conservation compliance documentation requirements apply differentially across product categories, with precision agriculture tools bearing the heaviest validation burden for nutrient management reporting.
- Farm Management:Consolidates financial ledgers, operational workflows, and regulatory documentation into unified dashboards for enterprise-scale producers. Demand concentrates among US Corn Belt operations where federal program participation requires software-enabled record retention. The EPA's nutrient management mandates embed these platforms into commercial row-crop compliance infrastructure.
- Precision Agriculture:Variable-rate input applications guided by real-time sensor telemetry and satellite imagery demonstrate measurable yield improvements. European arable operations under the EU Green Deal's Farm to Fork Strategy deploy these tools to satisfy chemical reduction mandates. The technology compresses decision cycles from seasonal to daily intervals.
- Irrigation Management:Soil moisture probe integration with weather station telemetry optimizes water application scheduling.
- Livestock Management:Animal health monitoring and herd tracking systems remain underpenetrated relative to crop-focused platforms.
Leading the category by volume: Farm Management. Growing fastest: Precision Agriculture.
Deployment:
Cost tier stratification separates premium cloud subscriptions from economy on-premises licenses, with hybrid architectures capturing mid-market operations balancing control and convenience.
- Cloud-Based:Real-time field-to-office synchronization reduces IT infrastructure burdens for mid-sized farming operations. French and German agricultural cooperatives negotiate enterprise licenses covering thousands of member operations through this deployment model. The architecture enables cooperative-scale data aggregation for nitrogen management and carbon credit verification.
- On-Premises:Local data retention satisfies operations with limited rural broadband connectivity or heightened cybersecurity concerns. Ukrainian grain operations and remote Australian wheat belts deploy these installations where cloud synchronization remains unreliable.
- Hybrid:Edge computing architectures process field-level data locally while batching analytics to cloud repositories.
- Mobile:Smartphone-native interfaces dominate smallholder penetration strategies in developing agricultural economies.
Dominant by deployment share: Cloud-Based. Expanding most quickly: Hybrid configurations bridging latency-sensitive field operations with centralized analytics.
End User:
Customer scale determines feature depth, with agribusiness companies requiring multi-entity consolidation while individual farmers prioritize single-farm simplicity.
- Agribusiness Companies:Large-scale operations demand unified data ecosystems over fragmented point solutions, driving platform consolidation across North American and European markets. The EU CSRD reporting obligations compel these enterprises to adopt traceability software for supply chain emissions accounting. Multi-tenant architectures support complex organizational hierarchies.
- Agricultural Cooperatives:Consolidated procurement concentrates software purchasing power across French, German, and Polish member networks. Cooperative-scale data aggregation unlocks premium pricing tiers for nitrogen management and carbon credit verification categories.
- Farmers:Individual grower subscriptions face displacement as cooperative purchasing gains traction.
- Research Institutions:Academic and government agricultural research stations require open-platform architectures for experimental data integration.
Highest revenue concentration: Agribusiness Companies. Fastest-growing customer segment: Agricultural Cooperatives consolidating previously fragmented purchasing decisions.
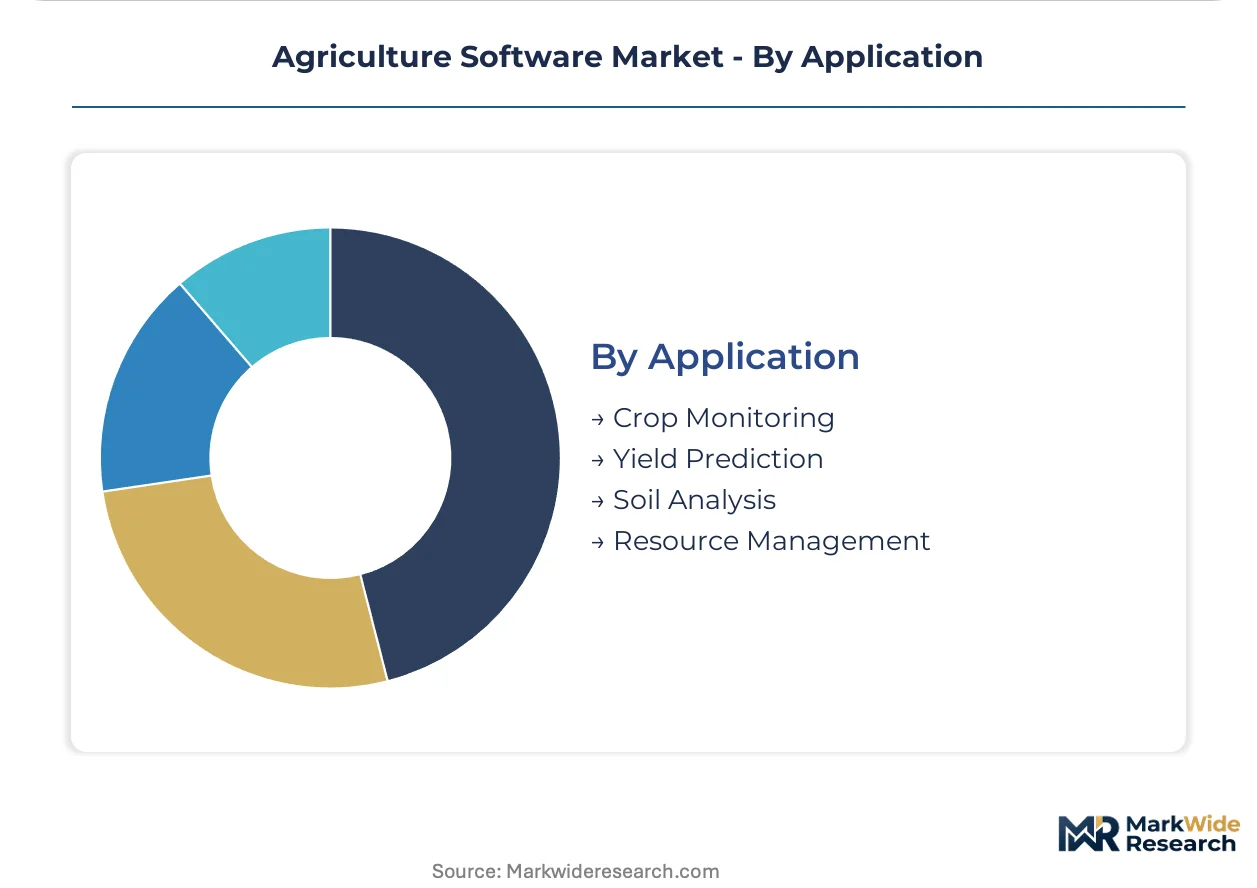
Application:
Application maturity varies by agronomic function, with crop monitoring achieving mainstream adoption while yield prediction algorithms remain in refinement phases.
- Crop Monitoring:Computer vision systems trained on disease pattern recognition compress yield loss windows from weeks to days. US Corn Belt and Ukrainian wheat belt operations deployed these tools at scale. The technology restructures crop protection procurement around real-time alerts rather than calendar schedules.
- Yield Prediction:Machine learning models integrating satellite imagery, weather data, and soil telemetry forecast harvest outcomes with improving accuracy. Spanish and Dutch specialty crop operations utilize these capabilities for contract pricing negotiations and supply chain planning.
- Soil Analysis:Digital soil mapping and nutrient profiling guide variable-rate fertilization strategies.
- Resource Management:Integrated water, energy, and input tracking supports sustainability reporting requirements.
Widest deployment: Crop Monitoring. Steepest expansion trajectory: Yield Prediction as algorithm accuracy improves and grower trust deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones for agricultural technology in California's Central Valley, the Netherlands' Food Valley, and Israel's Galilee Research Region concentrate venture deployment and pilot program density for digital farm platforms.
United States
The USDA channels conservation compliance documentation through software-enabled record-keeping systems across commercial row-crop operations. Federal program participation requirements embed digital platforms into Corn Belt compliance infrastructure. Iowa and Illinois field operations deploy variable-rate application tools at scale to satisfy nutrient management mandates from the EPA.
Germany
French and German agricultural cooperatives negotiate enterprise licenses covering thousands of member operations, consolidating previously fragmented purchasing decisions. The EU Green Deal's Farm to Fork Strategy mandates precision agriculture tools to reduce chemical inputs across arable operations. Bavarian and Lower Saxony farming clusters deploy traceability software to satisfy CSRD emissions accounting obligations for supply chain carbon documentation.
Netherlands
Specialty crop operations in Dutch greenhouse belts consolidate siloed field records into unified traceability platforms for scope 3 reporting. The F-Gas Regulation mandates granular emissions documentation across agricultural supply chains. Wageningen University's research corridor anchors applied development for computer vision systems trained on crop disease pattern recognition.
Brazil
Large-scale grain operations in Mato Grosso and Goiás deploy satellite-guided variable-rate input applications to optimize soybean and corn yields. The country's national agricultural research corporation channels precision agriculture adoption through extension programs. São Paulo state's agribusiness conglomerates demand multi-tenant architectures supporting complex organizational hierarchies for compliance documentation.
Australia
Remote wheat belt operations deploy on-premises installations where cloud synchronization remains unreliable across vast pastoral zones. The national agricultural regulator mandates traceability standards for export grain certification. Queensland and Western Australia farming cooperatives aggregate member data for nitrogen management and carbon credit verification software procurement.
Agriculture Software Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated hardware-software ecosystems commanding premium positioning against modular point solutions. The vendor base concentrates around three strategic archetypes: embedded equipment manufacturers with captive software platforms, independent precision agriculture specialists, and open-architecture integrators enabling third-party data layers. Dominant competitive moves include platform consolidation through strategic partnerships and geographic expansion via cooperative-scale enterprise licensing.
Among embedded equipment manufacturers, Deere & Company and Trimble Inc. occupy positions exemplifying hardware-software ecosystem dominance, while AGCO Corporation represents the open-platform integrator archetype enabling third-party agronomic data layer integration.
| Leading Market Players |
|---|
| Deere & Company |
| Trimble Inc. |
| AGCO Corporation |
| CNH Industrial N.V. |
| Topcon Corporation |
| Raven Industries |
| AG Leader Technology |
| Bayer AG |
| Corteva Agriscience |
| Others |
Supply Flow & Price Mechanics
EU CSRD emissions accounting obligations gate qualified supply for carbon traceability modules, restricting premium-tier pricing access to vendors with verified audit trails and cooperative-scale data aggregation capabilities.
Pricing Analysis
Short lead-time premiums apply to cloud-based farm management deployments requiring rapid field-to-office synchronization, while spot inventory discounts emerge for standardized on-premises licenses in bandwidth-constrained regions. Three-tier pricing structure across premium, standard, and economy levels separates enterprise multi-tenant architectures from cooperative-scale subscriptions and individual grower mobile licenses. Cost compression in mid-market cloud tiers is intensifying because French and German agricultural cooperatives negotiate consolidated enterprise licenses covering thousands of member operations. Individual farmers show highest price sensitivity, while agribusiness companies demonstrate lowest sensitivity due to compliance documentation requirements embedding platforms into operational infrastructure.
Supply Chain Analysis
Reverse-logistics flows for IoT sensor hardware refurbishment and telemetry device remanufacturing concentrate in Germany, the Netherlands, and the United States, where equipment manufacturers maintain captive aftermarket service networks. Component sourcing draws from Taiwanese semiconductor foundries for edge computing chipsets, South Korean battery suppliers for field sensor power systems, and Israeli imaging specialists for computer vision modules. Single-source vulnerability concentrates around GNSS receiver chipsets tethered to limited qualified vendors. Distribution runs through agricultural cooperative procurement channels displacing individual grower direct sales across European arable belts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Agriculture software has become a vertical-integration race, with hardware-software ecosystem control and cooperative-scale data aggregation representing the decisive downstream levers players are pursuing.
For Market Incumbents: Lock in cooperative procurement relationships through multi-year enterprise licenses covering nitrogen management and carbon credit verification categories. Deepen embedded hardware-software ecosystem control by capturing telemetry sensor supply chains. Open-source interoperability protocols from emerging integrators threaten proprietary data format lock-in.
For New Entrants and Emerging Players: AI-driven pest detection algorithms trained on crop disease pattern recognition offer a technology-first wedge into US Corn Belt and Ukrainian wheat belt operations. Livestock management digitization remains the most penetrable application layer. Pursue channel partnerships with French and German agricultural cooperatives for cooperative-scale deployment.
For Investors and Strategic Acquirers: Consolidated cooperative procurement surpassing individual grower subscriptions is the leading indicator that platform economics are shifting toward enterprise-scale vendors. Five-to-ten year viability favors vendors with multi-tenant architectures and CSRD-compliant traceability modules. Monitor open-source protocol adoption rates as inflection signal for platform lock-in erosion.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies fragmented point solutions into cooperative-scale data ecosystems for EU CSRD compliance. |
| Strategic Partnership | Locks in agricultural cooperative procurement channels across French and German member networks. |
| Acquisition of Specialist Firm | Captures livestock management digitization capabilities in underpenetrated cattle and dairy segments. |
| Geographic Expansion | Penetrates Brazilian Mato Grosso soybean operations through extension program channel partnerships. |
| Product Launch | Deploys computer vision systems for fungal pressure detection in US Corn Belt growing seasons. |
Methodological Framework
Independent corroboration across precision agriculture platform engineers, agricultural cooperative procurement directors, and EPA compliance officers underwrites the qualitative findings. Primary interviews with farm management software CTOs, agronomic data scientists, and channel integration specialists combined with secondary validation from USDA conservation program documentation, EU Green Deal regulatory filings, and SEC 10-K disclosures from embedded equipment manufacturers. Bottom-up deployment modeling and top-down market sizing triangulate volume estimates.
Comparable-period anchoring to historical adoption curves for precision agriculture tools and farm management software installations structured the forecast window across the analysis window. Segmentation dimensions modeled include product functionality, deployment architecture, customer scale, and agronomic application layer. CAGRs derived from trend extrapolation of cooperative procurement concentration and regulatory compliance embedding rates. Industry-specific inputs encompass satellite imagery resolution improvements and AI-driven pest detection algorithm accuracy trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rural broadband deployment delays and cybersecurity incident frequency. Practitioners should monitor open-source protocol adoption rates and cooperative procurement consolidation velocity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Online Reputation Management Software Market
Digital Solutions
Cloud MFT Services Market
Digital Solutions
Digital Signature Market
Digital Solutions
Retail Warehouse Management Systems Market
Digital Solutions
Water Level and Storage Monitoring Software Market
Digital Solutions
North America Smart Card Market
Digital Solutions
Global E-Visa Market
Digital Solutions
Real-Time Temperature and Location Monitoring Platforms for Cold Chain Market
Digital Solutions
Mexico Digital Twin Market
Digital Solutions
Global E-Passport and E-Visa Market
Digital Solutions
Global Insight As a Service Market
Digital Solutions
Docketing Solution Market
Digital Solutions
Global Multichannel Campaign Management Market
Digital Solutions
Global Service Delivery Platform Market
Digital Solutions
Reverse Logistics Visibility and Disposition Optimization Platforms Market
Digital Solutions
North America Product Design and Development Services Market