
 Qatar Cloud Managed Services Market | 2026-2036
Qatar Cloud Managed Services Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Cloud Managed Services Market Insights
The direct-to-enterprise channel is narrowing as hyperscalers and local telecom operators consolidate access to Qatar's regulated data center zones. MEEZA QSTP LLC anchors sovereign cloud capacity through its Qatar Science and Technology Park facilities. Ooredoo Q.P.S.C competes on fiber-connected edge nodes, while Amazon Web Services navigates compliance via local partnership structures.
Cloud managed services encompass the ongoing administration, optimization, and security of distributed computing resources across public, private, and hybrid architectures, typically governed by SLAs defining uptime thresholds, patch cadence, and incident response windows. The primary purpose is to transfer operational complexity from client IT staff to specialized providers, freeing capital for core business functions. Security Management commands premium pricing as Qatar's financial services and energy verticals face escalating threat surfaces, while Hybrid Cloud deployments outpace single-environment alternatives among enterprises balancing latency-sensitive workloads with burst capacity needs.
Qatar's National Cybersecurity Agency and the Qatar Communications Regulatory Authority shape market access through data localization mandates and critical infrastructure protection standards, compelling foreign providers to establish domestic presence. The Ministry of Transport and Communications reinforces this through smart city procurement rules requiring certified local hosting. Stakeholders must monitor evolving certification requirements and sovereign cloud specifications before committing to long-term platform investments.
Market Dynamics
Qatar's National Cybersecurity Agency data sovereignty mandates are compressing deployment timelines as foreign providers scramble to establish domestic hosting capacity. Energy sector enterprises now demand localized infrastructure for operational technology workloads.
Growth Catalysts
- Data Localization Mandates:The National Cybersecurity Agency requires critical infrastructure data to reside within Qatar's borders, forcing enterprise migration to certified domestic facilities.
- Smart City Procurement Rules:Ministry of Transport and Communications specifications for Lusail and Msheireb developments mandate certified local cloud hosting for government-adjacent projects.
- Edge Computing Integration:Latency-sensitive oil and gas sensor networks are driving fiber-connected edge node deployment across the Ras Laffan industrial zone.
Market Restraints
- Domestic Data Center Capacity Scarcity:Limited certified facilities in Doha and Lusail create queuing delays for enterprise workload onboarding.
- Specialized Talent Shortage:Qatar's domestic labor pool lacks sufficient certified cloud architects and cybersecurity specialists for sovereign cloud operations.
- Foreign Provider Partnership Requirements:Qatar Communications Regulatory Authority rules compel non-domestic hyperscalers to operate through local joint ventures, adding structural friction.
Strategic Opportunities
- Financial Services Expansion:Qatar Central Bank digital transformation directives are opening sovereign cloud demand among Islamic banks and investment funds.
- AI Workload Sovereignty:Emerging National Cybersecurity Agency guidance on artificial intelligence data handling creates compliant hosting demand for model training infrastructure.
- Healthcare Digitalization:Ministry of Public Health electronic health record mandates are driving compliant cloud migration among Hamad Medical Corporation facilities.
Industry Challenges
- Certification Timeline Compression:National Cybersecurity Agency facility accreditation processes extend 12-18 months, delaying revenue recognition for new market entrants.
- Legacy System Integration Complexity:Energy sector operational technology environments run decades-old SCADA systems requiring specialized middleware for cloud connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Cloud Managed Services Market |
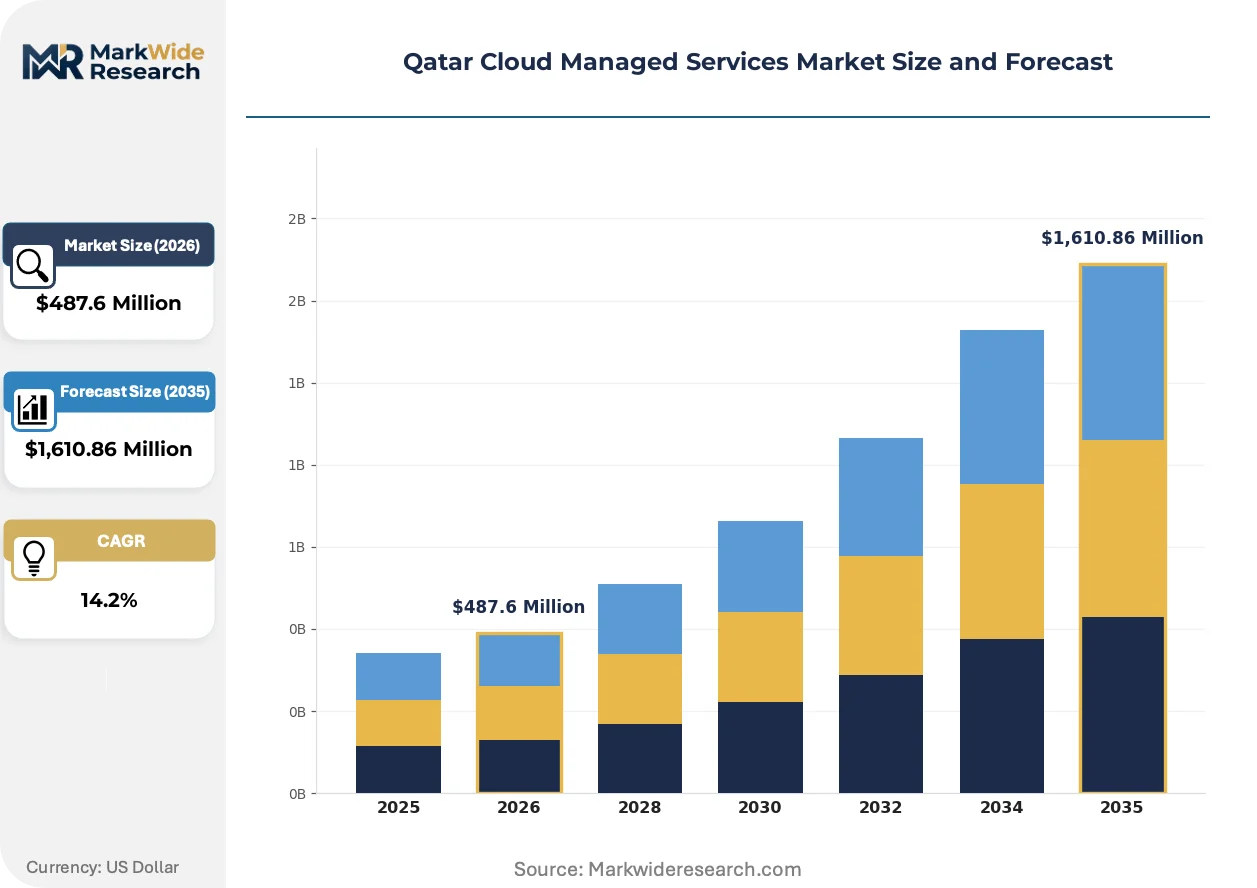
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,610.86 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Infrastructure Management, Application Management, Security Management, Network Management Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Client Type: Small Businesses, Enterprises, Government Agencies, Non-Profits Industry Vertical: Healthcare, Financial Services, Education, Retail |
| Companies Covered | MEEZA QSTP LLC, Gulf Business Machines Qatar W.L.L., Diyar Group, Paramount Computer Systems FZ-LLC, Ooredoo Q.P.S.C, Vodafone Qatar, Microsoft, Amazon Web Services, Oracle Cloud, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Cloud Managed Services Market Trends and Innovations
Workload placement logic is fragmenting across Qatar's regulated zones as enterprises balance latency, sovereignty, and burst capacity requirements. Providers are racing to certify multi-zone architectures.
Container orchestration is migrating from generic Kubernetes distributions to hardened, sovereign-compliant platforms. Qatar's defense and energy contractors are adopting these platforms for classified and operational technology workloads. The shift is compressing procurement cycles as security-cleared alternatives replace standard commercial offerings.
National Cybersecurity Agency critical infrastructure protection standards are mandating zero-trust architecture implementation across certified facilities. Financial services and energy verticals face the steepest compliance curves. Domestic providers are embedding these requirements into baseline service offerings to accelerate enterprise onboarding.
Buyer contracting behavior is consolidating around multi-year managed service agreements with embedded compliance guarantees. Systems integrators are displacing direct hyperscaler relationships in Doha's enterprise corridor. Energy sector procurement teams now prioritize sovereign cloud certifications over price optimization in vendor selection criteria.
Qatar Cloud Managed Services Market Segmentation
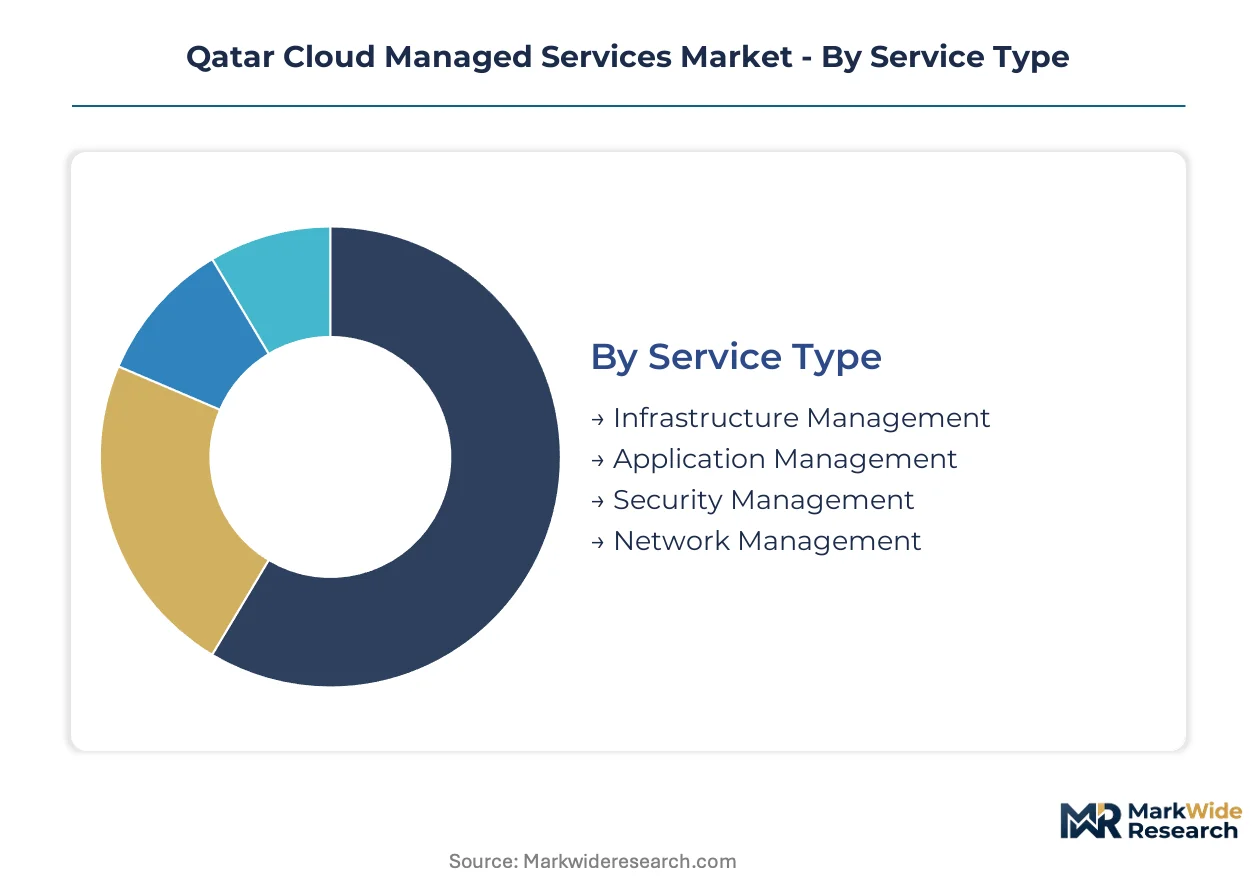
Segmentation in Qatar's cloud managed services market reveals how regulatory pressure and infrastructure constraints reshape provider strategies. Each dimension exposes distinct procurement patterns across the emirate's concentrated enterprise base.
Service Type:
Cost tier differentiation separates commodity infrastructure operations from premium security and application layers. Qatar's compliance environment compresses margins at the base while expanding premiums at the top.
- Infrastructure Management:Server provisioning, storage tiering, and compute orchestration form the operational backbone. Energy sector enterprises in Ras Laffan Industrial City consume bulk capacity here, constrained by domestic data center scarcity and extended onboarding queues.
- Security Management:Threat detection, incident response, and zero-trust architecture implementation command premium pricing. Qatar Central Bank directives and National Cybersecurity Agency standards drive financial services demand, with Islamic banks prioritizing sovereign-certified providers over cost optimization.
- Application Management:Database administration, middleware tuning, and SaaS integration support line-of-business systems.
- Network Management:SD-WAN deployment, traffic optimization, and latency-sensitive connectivity for distributed operations.
Security Management holds installed capacity. Application Management is rotating up the share rankings.
Deployment Model:
Application criticality and data sensitivity dictate environment selection, with latency requirements and burst capacity needs creating hybrid preferences.
- Hybrid Cloud:Workloads split between on-premises private infrastructure and public burst capacity. Energy sector operational technology environments in Doha and Lusail favor this model, balancing SCADA system latency requirements with seasonal compute spikes.
- Private Cloud:Dedicated single-tenant infrastructure with full sovereignty guarantees. Government agencies and defense contractors mandate this tier, driven by National Cybersecurity Agency critical infrastructure protection standards and data localization mandates.
- Public Cloud:Shared multi-tenant resources with standardized SLAs and rapid provisioning.
- Multi-Cloud:Orchestrated workloads across two or more hyperscaler environments for resilience and vendor diversification.
Private Cloud holds installed capacity. Hybrid Cloud is climbing the fastest among deployment alternatives.
Client Type:
Customer scale determines contract structure, with procurement sophistication varying sharply across the emirate's concentrated public and private sectors.
- Enterprises:Large organizations with dedicated IT procurement functions and multi-year managed service agreements. Qatar's energy majors and financial institutions anchor this segment, embedding sovereign cloud certifications and compliance guarantees into vendor selection criteria.
- Government Agencies:Public sector entities subject to Ministry of Transport and Communications procurement rules. Smart city developments in Lusail and Msheireb mandate certified local hosting, creating structured demand for domestic provider partnerships.
- Small Businesses:Mid-market and emerging companies with limited internal cloud expertise.
- Non-Profits:Charitable and civil society organizations with constrained budgets and basic compliance requirements.
Enterprises hold installed capacity. Government Agencies are gaining share fastest through smart city procurement expansion.
Industry Vertical:
End-use concentration shapes service packaging, with sector-specific compliance requirements fragmenting provider offerings across Qatar's economy.
- Financial Services:Islamic banks, investment funds, and insurance operators subject to Qatar Central Bank digital transformation directives. Sovereign cloud demand concentrates here as institutions migrate core banking platforms to certified domestic facilities.
- Healthcare:Hospital systems and clinics responding to Ministry of Public Health electronic health record mandates. Hamad Medical Corporation facilities are driving compliant cloud migration, with patient data sovereignty requirements blocking standard public cloud deployment.
- Education:Universities and technical institutes modernizing research computing and administrative systems.
- Retail:Consumer-facing commerce operators with seasonal demand volatility and e-commerce platform requirements.
Financial Services holds installed capacity. Healthcare is rotating up the share rankings through accelerated digitalization timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ras Laffan Industrial City's fiber optic backbone and Hamad International Airport's data corridor position Qatar as a Gulf digital infrastructure node. Domestic cloud capacity concentrates where these transport layers intersect with regulatory zones.
Doha Metropolitan Area
Financial services institutions and energy headquarters anchor demand in the capital's West Bay and Msheireb districts. Qatar Central Bank directives on digital banking infrastructure compel sovereign cloud deployment. The Qatar Science and Technology Park hosts certified facilities serving Islamic banks and investment funds migrating core systems.
Lusail Smart City
Ministry of Transport and Communications procurement rules mandate certified local hosting for government-adjacent developments. The Lusail Marina and Entertainment City districts require edge-connected infrastructure for IoT and surveillance workloads. Domestic providers queue enterprise onboarding requests amid facility scarcity.
Ras Laffan Industrial Zone
Operational technology networks in LNG processing and petrochemical complexes drive latency-sensitive edge node deployment. National Cybersecurity Agency critical infrastructure standards require localized SCADA system hosting. Energy majors balance private infrastructure with burst capacity for seismic processing workloads.
Al Wakrah and Mesaieed
Industrial corridors south of Doha house manufacturing and logistics operations requiring compliant cloud connectivity. The Hamad Port's customs and trade systems generate structured demand for certified data residency. Emerging healthcare facilities respond to Ministry of Public Health electronic record mandates.
Umm Salal and Northern Qatar
Suburban expansion and education city satellite campuses create distributed demand for administrative and research computing. Qatar Foundation's technology park extensions seek sovereign-certified alternatives to central Doha facilities. Northern industrial zones await fiber-connected edge infrastructure deployment.
Qatar Cloud Managed Services Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower scope. Market structure tilts toward consolidated access channels as hyperscalers and domestic operators partition certified facility capacity. Three archetypes dominate: sovereign-certified domestic providers, telecom-anchored regional operators, and foreign hyperscalers operating through local partnership structures. Competitive moves concentrate on certification acquisition and fiber-connected edge node expansion.
Within the sovereign-certified tier, MEEZA QSTP LLC occupies a position anchored at Qatar Science and Technology Park facilities. Ooredoo Q.P.S.C and Vodafone Qatar represent telecom-anchored regional operators competing on fiber-connected infrastructure. Among global platforms, Amazon Web Services and Microsoft exemplify foreign hyperscalers navigating compliance through local partnership structures rather than direct operation.
| Leading Market Players |
|---|
| MEEZA QSTP LLC |
| Gulf Business Machines Qatar W.L.L. |
| Diyar Group |
| Paramount Computer Systems FZ-LLC |
| Ooredoo Q.P.S.C |
| Vodafone Qatar |
| Microsoft |
| Amazon Web Services |
| Oracle Cloud |
| Others |
Pricing and Supply Chain Analysis
Doha and Lusail's certified data center clusters concentrate domestic cloud capacity, granting sovereign-certified providers substantial pricing leverage over foreign hyperscalers navigating partnership requirements. Energy sector buyers in Ras Laffan face extended onboarding queues that compress their negotiating position, while financial institutions absorb premium security management rates driven by Qatar Central Bank compliance mandates.
Pricing Analysis
Volume-discount tiering structures stratify across sovereign certification grades, with National Cybersecurity Agency-accredited facilities commanding substantial premiums over standard commercial offerings. Price differentiation centers on data residency guarantees and zero-trust architecture implementation, with Islamic banks and energy majors showing minimal price sensitivity compared to mid-market enterprises. Pricing pressure stems from domestic facility scarcity extending procurement timelines, though certified providers maintain margin protection through queuing mechanisms. Government agencies exhibit the least price sensitivity due to Ministry of Transport and Communications procurement rules mandating local hosting regardless of cost.
Supply Chain Analysis
Export-control regimes limiting advanced semiconductor and encryption technology flows constrain Qatar's access to cutting-edge server hardware and security appliances. Geographic supply concentration centers on the United States, Taiwan, and South Korea for high-performance computing components, with the emirate drawing from these markets through distributor channels. Raw material dependencies span silicon wafers, specialized cooling systems, and fiber-optic transmission equipment. Single-source vulnerability runs through Taiwan's advanced chip fabrication capacity. Distribution runs through Dubai-based regional logistics hubs before final customs clearance at Hamad International Airport's data corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qatar's cloud managed services market fragments across compliance tiers, with National Cybersecurity Agency certification requirements and smart city procurement rules creating defendable niches for specialized operators. Sovereign cloud demand from Islamic banks and healthcare digitalization initiatives multiplies addressable segments beyond commodity infrastructure provision.
For Market Incumbents: Build certification moats through accelerated National Cybersecurity Agency facility accreditation to capture queuing premiums before foreign hyperscalers establish domestic partnerships. Expand fiber-connected edge nodes across Ras Laffan Industrial Zone to anchor energy sector operational technology workloads. Defend against telecom-anchored regional operators by embedding zero-trust architecture into baseline service offerings. For New Entrants and Emerging Players: Pursue healthcare vertical specialization targeting Hamad Medical Corporation electronic health record migration timelines, where patient data sovereignty requirements block standard public cloud deployment. Target Al Wakrah and Mesaieed industrial corridors for compliant logistics and customs connectivity. Lead with Ministry of Public Health certification partnerships to bypass direct competition with established financial services providers. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because data localization mandates and critical infrastructure protection standards compound switching costs across the projection horizon. Acquisition targets should display sovereign cloud certifications and established Qatar Science and Technology Park presence. Monitor National Cybersecurity Agency artificial intelligence data handling guidance issuance as inflection indicator for model training infrastructure demand.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification Acquisition | National Cybersecurity Agency accreditation unlocks energy and financial services procurement pipelines. |
| Fiber-Connected Edge Node Expansion | Ras Laffan Industrial Zone latency requirements anchor operational technology workload capture. |
| Healthcare Vertical Partnership | Ministry of Public Health mandates drive compliant electronic health record migration demand. |
| Zero-Trust Architecture Integration | Critical infrastructure protection standards embed compliance into baseline managed service offerings. |
| AI Workload Sovereignty Positioning | Emerging guidance on artificial intelligence data handling creates model training infrastructure demand. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across Qatar's concentrated enterprise base, encompassing cloud architects at energy majors, procurement officers at Islamic banks, and infrastructure planners at domestic data center operators. Secondary validation drew from Qatar Central Bank digital transformation directives, National Cybersecurity Agency facility accreditation records, Ministry of Transport and Communications smart city procurement specifications, and hyperscaler partnership disclosure filings. Bottom-up triangulation across service-type segmentation and top-down reconciliation against national ICT expenditure frameworks anchored volume estimates.
Calibration against historical facility deployment timelines and certification queue lengths refined capacity constraint assumptions across the projection horizon. Segmentation dimensions modeled encompass service type, deployment model, client scale, and industry vertical, with sovereign compliance tier treated as cross-cutting modifier. CAGRs were derived from elasticity-adjusted demand curves reflecting data localization mandate enforcement intensity. Forecast inputs incorporated Qatar Science and Technology Park expansion timelines and Ras Laffan fiber backbone completion schedules.
Sensitivities concentrate around National Cybersecurity Agency certification timeline compression and foreign hyperscaler partnership structure liberalization. Forecasts embed assumptions regarding sustained data residency enforcement and smart city procurement rule continuity. Cross-checking against Ministry of Transport and Communications infrastructure budget allocations is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
Integrated Workplace Management System (IWMS) Market
Enterprise Services
Europe Managed Infrastructure Services Market
Enterprise Services
Asia Pacific Enterprise Collaboration Market
Enterprise Services
Enterprise Service Bus Software Market
Enterprise Services
Global Managed Infrastructure Service Market
Enterprise Services
Proactive Services Market
Enterprise Services
Shared Services Center Market
Enterprise Services
North America Contingent Workforce Management Market
Enterprise Services
Global Enterprise Data Integration Market
Enterprise Services
Employee Engagement Market
Enterprise Services
US Enterprise Asset Management Market
Enterprise Services
United States Management Consulting Services Market
Enterprise Services
Open Source ERP Market
Enterprise Services
North America Public Sector Consulting and Advisory Services Market
Enterprise Services
Contingent Staffing Solutions Market
Enterprise Services
Global Enterprise Content Collaboration Market