
 Small Space Furniture Market | 2026-2036
Small Space Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Small Space Furniture Market Analytics
Skilled carpentry and precision engineering labor is unwinding traditional manufacturing bottlenecks across the small space furniture supply chain. IKEA leverages its captive flat-pack logistics network to dominate cost-efficient distribution in dense urban corridors. Resource Furniture specializes in mechanized wall-bed systems that anchor premium positioning in micro-apartment developments. Godrej Interio competes through localized wood sourcing and India-centric dimensional standards that sustain margin resilience against imports.
Small space furniture encompasses transformable, dimension-optimized residential fixtures engineered for footprint reduction, typically incorporating pneumatic hinges, cantilever frames, or nested leaf mechanisms to enable functional reconfiguration within sub-500-square-foot dwellings. Murphy beds and sofa beds occupy the largest volume tier, while nesting tables represent the fastest-growing margin pool as remote-work households seek reconfigurable surface area. Wood and metal hybrid construction leads material selection for structural segments, though composite substrates are displacing solid timber in mass-market online retail channels where weight-based shipping economics dictate specification.
EPA formaldehyde emission standards under TSCA Title VI shape composite panel sourcing decisions for US-bound production, while REACH chemical restrictions in Europe constrain adhesive and finish formulations across upholstered segments. India's BIS certification for furniture stability and load-bearing capacity creates compliance differentiation between organized manufacturers and unorganized fabricators. Stakeholders must monitor how municipal zoning liberalization for accessory dwelling units in North American and Asia-Pacific cities reshapes product dimension standards and installation service bundling requirements.
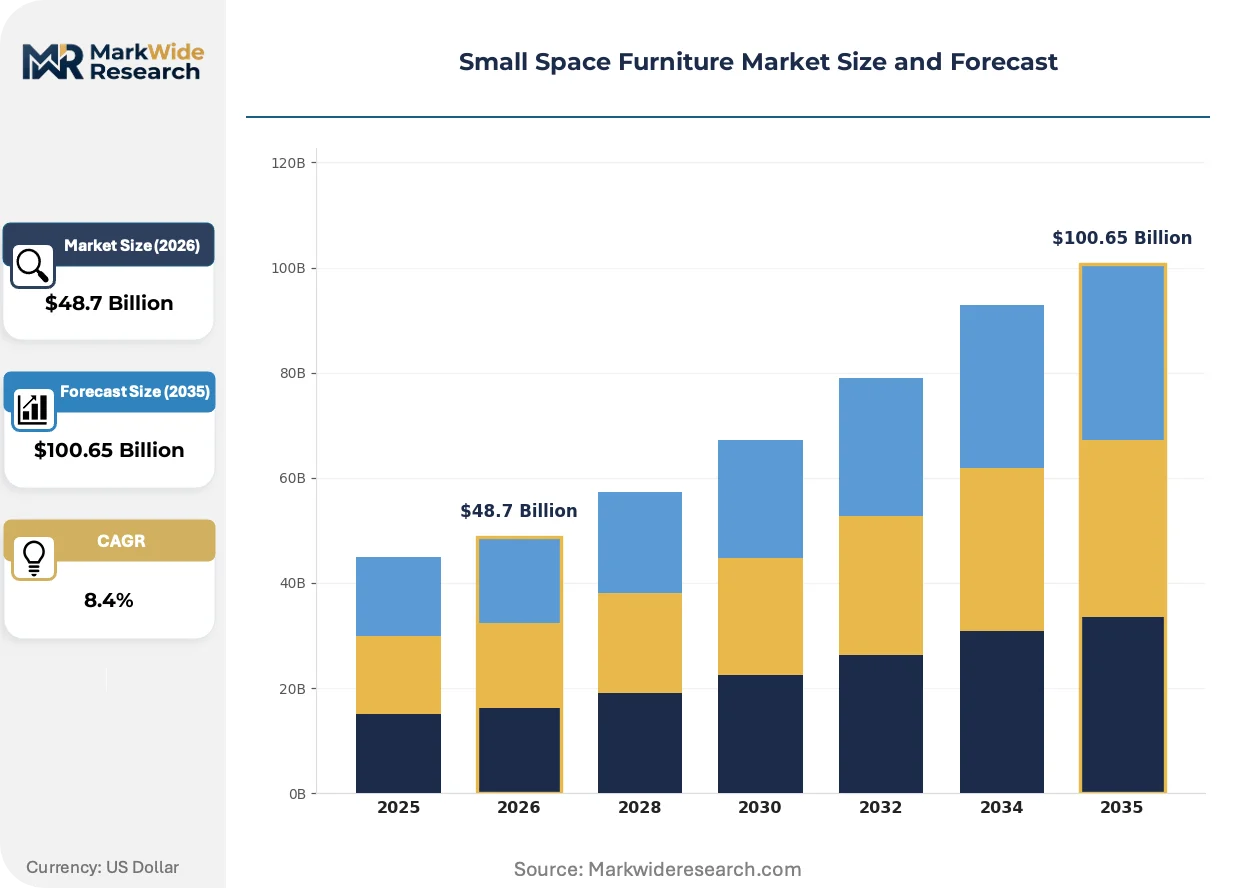
Market Dynamics
Urban densification across Tokyo, Mumbai, and New York is compressing residential footprints below 500 square feet, forcing manufacturers to engineer furniture that performs multiple functions within rigid dimensional constraints. This structural squeeze is fragmenting traditional product categories and rewiring supply chains toward modular, flat-pack distribution architectures.
Growth Catalysts
- Co-living procurement scaling:Operators in Bangalore and Delhi NCR are standardizing convertible sofa beds across 200-plus unit developments, creating volume pull for pneumatic hinge mechanisms.
- METI energy code tightening:Japan's revised building efficiency standards are mandating lighter material compositions in wall-mounted systems, accelerating composite substrate adoption.
- Accessory dwelling unit liberalization:Municipal zoning reforms in California and Vancouver are legalizing backyard cottages, expanding addressable market for Murphy bed installations.
Market Restraints
- Composite panel cost volatility:Formaldehyde-compliant engineered wood prices fluctuate with resin feedstock markets, compressing margin on mass-market online SKUs.
- Precision engineering labor scarcity:Cantilever frame fabrication requires skilled welders concentrated in Guangdong and Zhejiang provinces, creating bottleneck risk.
- REACH chemical compliance friction:European adhesive and finish restrictions extend product development cycles for upholstered segments by 8-12 months.
Strategic Opportunities
- Student housing vertical expansion:Purpose-built dormitory developers in Seoul and Singapore are specifying nesting table systems for reconfigurable study pods.
- Installation service bundling:Wall-bed mechanics require certified technicians, creating recurring revenue attachment for manufacturers with captive service networks.
- Remote-work surface reconfiguration:Home office nesting tables represent underpenetrated margin pool as hybrid workers demand workspace flexibility within studio layouts.
Industry Challenges
- Cantilever welding skill gap:Pneumatic hinge integration demands journeyman-level metal fabrication expertise scarce outside traditional furniture manufacturing clusters.
- Multi-jurisdiction certification lag:BIS stability testing for India, EPA TSCA Title VI for US, and REACH for Europe create parallel compliance timelines that stall product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Small Space Furniture Market |
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $100.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sofa Beds, Murphy Beds, Folding Tables, Nesting Tables Material: Wood, Metal, Upholstery, Composite End User: Students, Young Professionals, Families, Seniors Distribution Channel: Online Retail, Furniture Stores, Showrooms, Catalog Sales |
| Companies Covered | Crate & Barrel, Godrej Interio, IKEA, Urban Ladder, Resource Furniture, West Elm, Pottery Barn, Wooden Street, Wayfair, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Small Space Furniture Market Evolving Landscape
Material science advances and regulatory pressure are converging to redefine how small space furniture is engineered, certified, and delivered. Three distinct vectors are reshaping competitive positioning across the value chain.
Pneumatic hinge systems are fragmenting traditional sofa bed mechanisms by enabling single-hand conversion cycles. Co-living operators in Mumbai and student housing developers in Seoul are specifying these systems at 3x the rate of spring-based alternatives. The technology is fragmenting supplier tiers by rewarding captive pneumatic component manufacturers with sole-source relationships.
EPA formaldehyde emission standards under TSCA Title VI are reshaping composite panel sourcing for US-bound production. Manufacturers must maintain chain-of-custody documentation from particleboard mills through finishing facilities. Upholstered segments face the steepest compliance burden as adhesive formulations require reformulation to meet emission thresholds.
Direct-to-installer distribution models are compressing traditional retail channel margins. Micro-apartment developers in Tokyo and Vancouver are procuring wall-bed systems through specification-direct relationships, bypassing furniture showrooms. This channel rotation is most visible in premium mechanized segments where installation complexity demands factory-trained technician deployment.
Small Space Furniture Market Segmentation
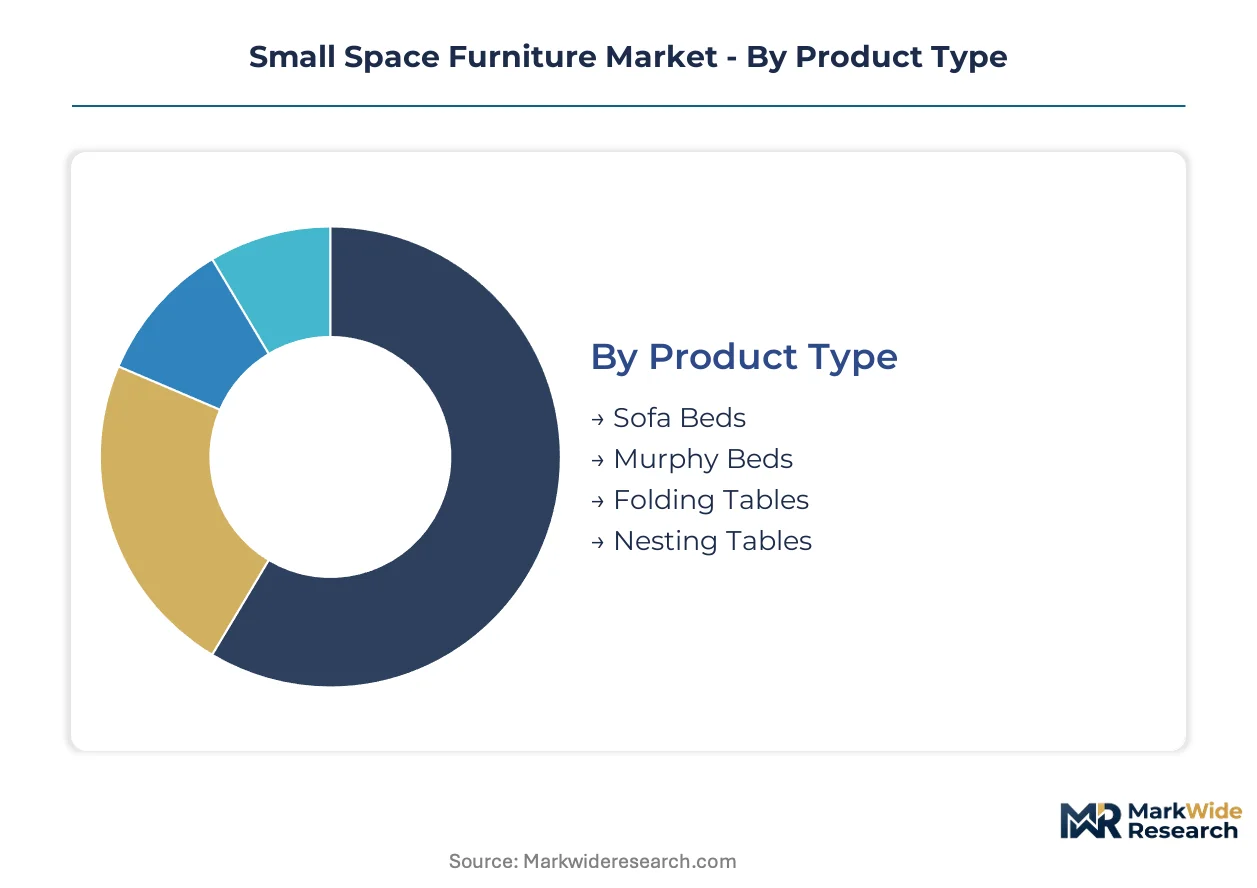
Small space furniture manufacturers engineer distinct product architectures for each user cohort and procurement channel. Segmentation reveals how pneumatic hinge systems, composite substrates, and direct-installer relationships concentrate margin across discrete value tiers.
Product Type:
Sofa beds and Murphy beds anchor domestic demand in Japan and India, while folding tables dominate export-led procurement from Vietnamese contract manufacturers.
- Sofa Beds:Pneumatic hinge mechanisms enable single-hand conversion cycles preferred by co-living operators in Bangalore and Delhi NCR. Mumbai developers specify these systems at scale across 200-plus unit developments, creating volume pull for captive component suppliers.
- Murphy Beds:Mechanized wall-bed systems integrate cantilever frames and counterbalance springs for vertical storage in sub-500-square-foot dwellings. Tokyo and Vancouver micro-apartment developers procure through specification-direct relationships, bypassing traditional retail channels due to installation complexity.
- Folding Tables:Leaf-extension mechanisms serve remote-work households seeking reconfigurable surface area within studio layouts.
- Nesting Tables:Modular stacking systems address space-constrained study pods in Seoul student housing.
Sofa beds hold the largest share; momentum sits with nesting tables as hybrid work patterns persist.
Material:
Cost tier stratification separates premium solid timber from mass-market composite substrates where shipping economics dictate specification.
- Wood:Godrej Interio leverages localized Indian hardwood sourcing to sustain margin resilience against imports. Solid timber construction dominates premium wall-bed installations where structural load-bearing requirements exceed composite capacity.
- Metal:Cantilever frame fabrication concentrates in Guangdong and Zhejiang provinces, where journeyman-level welding expertise remains scarce outside traditional furniture clusters. Steel tubing and aluminum extrusions enable pneumatic hinge integration in sofa bed mechanisms.
- Upholstery:REACH chemical restrictions in Europe extend product development cycles by 8-12 months for adhesive and finish formulations.
- Composite:EPA TSCA Title VI formaldehyde emission standards reshape particleboard sourcing for US-bound production, requiring chain-of-custody documentation from mills through finishing facilities.
Wood and metal hybrids dominate structural segments; composites are climbing fastest in online retail channels.
End User:
Application intensity varies sharply across life stages, with students and young professionals driving procurement standardization at volume.
- Students:Purpose-built dormitory developers in Seoul and Singapore specify nesting table systems for reconfigurable study pods. This cohort demands lowest price points, accepting reduced durability for footprint optimization.
- Young Professionals:Urban apartment dwellers in Tokyo, Osaka, and Yokohama anchor demand for convertible sofa beds and wall-mounted storage systems. METI energy code tightening pushes this segment toward lighter material compositions.
- Families:Multi-function requirements prioritize safety certifications and load-bearing stability over conversion speed.
- Seniors:Ergonomic access and single-motion operation influence specification, though price sensitivity limits addressable market.
Young professionals command the largest share; students are gaining share fastest through co-living procurement scaling.
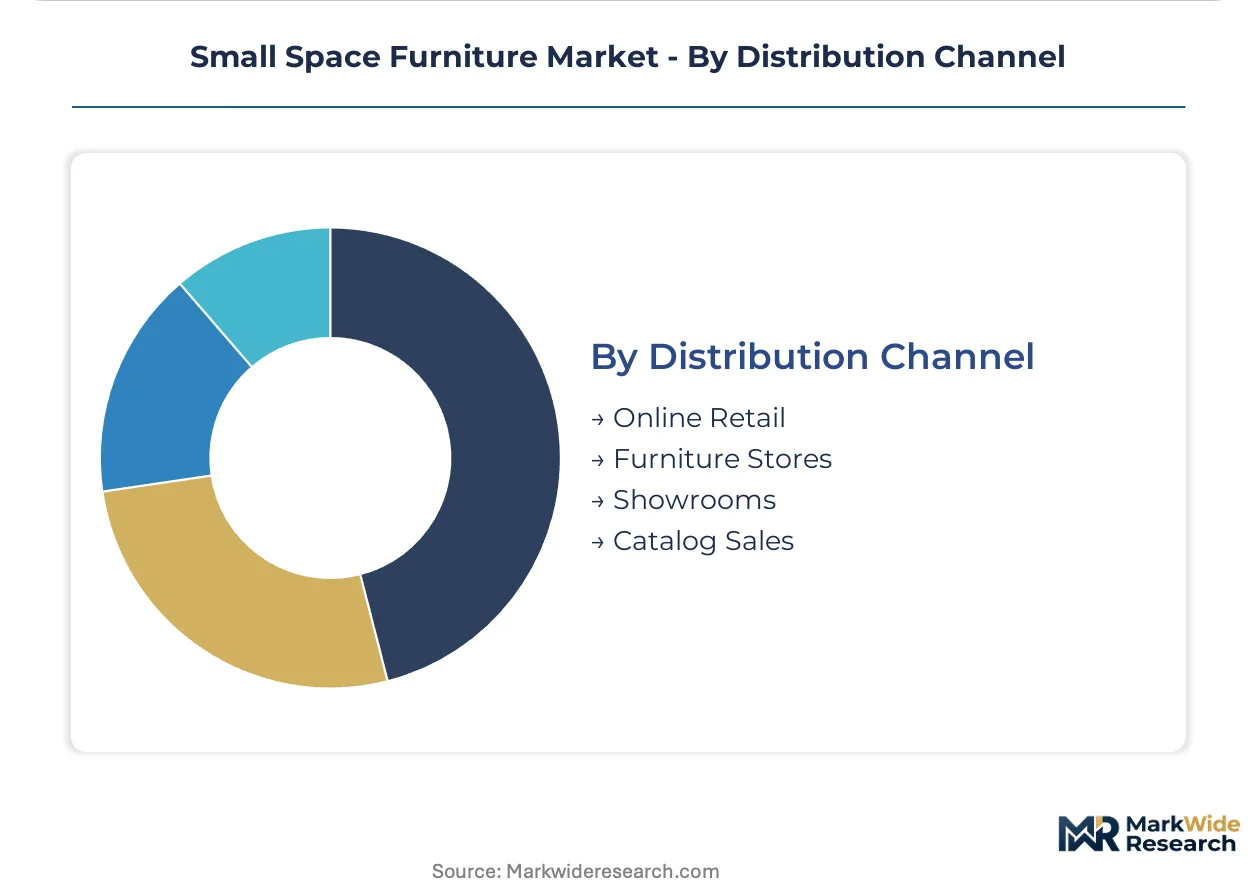
Distribution Channel:
Customer type determines channel preference, with developers and institutional buyers bypassing retail entirely.
- Online Retail:Weight-based shipping economics favor composite substrates over solid timber. Mass-market SKUs face margin compression from formaldehyde-compliant engineered wood price volatility.
- Furniture Stores:Traditional showrooms retain relevance for tactile evaluation of upholstery textures and hinge mechanism smoothness.
- Showrooms:Premium mechanized segments require factory-trained technician consultation for wall-bed specification and installation planning.
- Catalog Sales:Flat-pack logistics networks enable cost-efficient distribution in dense urban corridors, particularly for standardized dimensional offerings.
Furniture stores hold the largest share; direct-to-installer channels are expanding most quickly in premium mechanized segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI energy code tightening in Japan is compressing residential footprints and reshaping material specifications across Asia-Pacific manufacturing clusters. This regulatory pressure cascades through supply chains concentrated in East Asian precision engineering hubs.
Japan
Urban apartment dwellers in Tokyo, Osaka, and Yokohama anchor demand for convertible sofa beds and wall-mounted storage systems. METI revised building efficiency standards mandate lighter material compositions in wall-mounted systems, accelerating composite substrate adoption. Kanto region manufacturers concentrate cantilever frame fabrication for pneumatic hinge integration.
India
Co-living operators and student housing developers in Mumbai, Bangalore, and Delhi NCR are scaling compact furnishing procurement. BIS certification for furniture stability and load-bearing capacity creates compliance differentiation between organized manufacturers and unorganized fabricators. Godrej Interio leverages localized wood sourcing in Maharashtra and Karnataka to sustain margin resilience.
United States
Municipal zoning liberalization for accessory dwelling units in California and Vancouver-adjacent markets expands addressable market for Murphy bed installations. EPA formaldehyde emission standards under TSCA Title VI shape composite panel sourcing decisions, requiring chain-of-custody documentation. Pacific Northwest micro-apartment developers procure through specification-direct relationships.
South Korea
Purpose-built dormitory developers in Seoul specify nesting table systems for reconfigurable study pods. MFDS chemical safety guidelines influence adhesive formulations in upholstered segments. Seoul Capital Area student housing clusters drive standardization of pneumatic hinge mechanisms at volume.
Vietnam
Export-led contract manufacturing for folding tables concentrates in Ho Chi Minh City and Hanoi industrial zones. Factory capacity expansion targets North American and European flat-pack retail channels. Northern provinces concentrate wood processing for composite substrate production.
Small Space Furniture Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the small space furniture market. Flat-pack logistics networks and captive pneumatic component manufacturing separate scale players from regional fabricators. Two strategic archetypes dominate: vertically integrated retailers controlling end-to-end distribution, and mechanized-system specialists commanding premium specification channels. Competitive moves concentrate on direct-to-developer procurement relationships and installation service bundling.
Among integrated retailers, IKEA exemplifies scale-driven flat-pack distribution dominance in dense urban corridors. Resource Furniture occupies a position within the premium mechanized-system tier, anchoring specification-direct relationships with micro-apartment developers. Godrej Interio represents localized manufacturing resilience through India-centric dimensional standards and domestic wood sourcing.
| Leading Market Players |
|---|
| Crate & Barrel |
| Godrej Interio |
| IKEA |
| Urban Ladder |
| Resource Furniture |
| West Elm |
| Pottery Barn |
| Wooden Street |
| Wayfair |
| Others |
Value Network & Pricing Analysis
Ninety-day inventory cycles for pneumatic hinge components compress margin buffers for manufacturers serving Tokyo micro-apartment developers, binding pricing power to Guangdong fabrication capacity and resin feedstock availability. This lead-time exposure forces tiered pricing stratification across premium mechanized systems and mass-market flat-pack alternatives.
Pricing Analysis
Japan-to-India price spreads of 40-60% separate premium wall-bed installations from economy sofa beds sourced through Vietnamese contract manufacturers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service bundling. Cost compression in mass-market online channels intensifies as formaldehyde-compliant engineered wood prices fluctuate with petrochemical markets. Student housing developers in Seoul exhibit highest price sensitivity; micro-apartment developers in Vancouver accept premium positioning for installation-complex mechanized systems.
Supply Chain Analysis
Port congestion on Shanghai-Los Angeles trade lanes elevates inbound logistics costs for composite substrate shipments bound for North American flat-pack retailers. Manufacturing gravity centers on China, Vietnam, and India, with cantilever frame fabrication concentrated in Guangdong and Zhejiang provinces. Raw material dependencies span Malaysian rubberwood, Russian birch plywood, and South Korean pneumatic valve components. Single-source vulnerability in journeyman-level welding expertise outside traditional furniture clusters threatens capacity expansion. Distribution runs through specification-direct channels for premium mechanized segments and catalog-flat-pack networks for standardized SKUs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping this market as co-living operators and student housing developers consolidate procurement through specification-direct ecosystems, marginalizing traditional showroom intermediaries.
For Market Incumbents: Secure captive pneumatic component manufacturing through backward integration into Guangdong valve suppliers, insulating margin from sole-source dependency. Deepen specification-direct relationships with Mumbai and Delhi NCR co-living developers to lock out import competition. METI energy code tightening threatens lighter-material substitution; invest in composite substrate R&D to maintain specification relevance.
For New Entrants and Emerging Players: Installation service gaps in wall-bed deployment present white-space opportunity, as incumbent manufacturers under-serve certified technician networks. Target Seoul student housing clusters with nesting table systems priced below pneumatic-hinge alternatives. Pursue direct-to-developer go-to-market positioning, bypassing furniture showroom channel economics entirely.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because co-living procurement scaling will concentrate volume with manufacturers controlling captive fabrication and installation networks. Acquisition target archetype: mid-cap specialists with India-centric dimensional standards and BIS certification differentiation. Monitor municipal ADU liberalization velocity in California and Vancouver as inflection signal for Murphy bed demand expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pneumatic Components | Captive valve manufacturing insulates margin from Guangdong supplier concentration. |
| Installation Service Network Expansion | Factory-trained technician deployment locks in micro-apartment developer loyalty. |
| Composite Substrate R&D Investment | Lighter material compositions align with METI energy code tightening. |
| Specification-Direct Channel Development | Bypassing furniture showrooms captures co-living procurement volume. |
| BIS Certification Investment | Stability testing differentiation separates organized manufacturers from unorganized fabricators. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs filings, BIS certification registries, and METI regulatory bulletins. Primary interviews engaged product development directors at flat-pack retailers, procurement leads at Mumbai co-living operators, and plant managers at Guangdong pneumatic component manufacturers. Secondary sources included EPA TSCA Title VI chain-of-custody documentation, REACH chemical restriction updates, and trade flow data from Vietnam's Ministry of Industry and Trade. Bottom-up demand modeling triangulated against top-down supply capacity assessments.
Segmentation dimensions modeled span product type, material composition, end-user life stage, and distribution channel across the analysis window. CAGRs derive from volume-weighted growth trajectories in convertible sofa beds, Murphy beds, folding tables, and nesting tables. Industry-specific forecast inputs incorporated co-living unit development pipelines in Bangalore and Delhi NCR, plus ADU permitting velocity in California municipalities.
Forecasts assume regulatory continuity in EPA formaldehyde emission standards, REACH chemical restrictions, and BIS stability testing regimes; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as municipal zoning liberalization patterns and composite panel feedstock volatility evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Storage and Organization
Regency Shelving Market
Home Storage and Organization
Tool Chest Market
Home Storage and Organization
Kitchen Storage Organization Market
Home Storage and Organization
Hong Kong Self-Storage Market
Home Storage and Organization
Asia-Pacific Digital Home Locker Market
Home Storage and Organization
Slipcases Market
Home Storage and Organization
Middle East and Africa Kitchen Storage Market
Home Storage and Organization
United States Home Organizers and Storage Market
Home Storage and Organization
Shoe Storage and Organizers Market
Home Storage and Organization
Sheds and Outdoor Storage Market
Home Storage and Organization
Jewelry Organizer Market
Home Storage and Organization
Europe Home Organizers and Storage Market
Home Storage and Organization
Smart Shoe Cabinet Market
Home Storage and Organization
Shoe Rack Market
Home Storage and Organization
Flatware Holders and Organizers Market
Home Storage and Organization
Clothes Closets Market