
 Intelligent Airways Transportation Market | 2026-2036
Intelligent Airways Transportation Market Size, Share, and Industry Trends Forecast 2026-2036
Intelligent Airways Transportation Market Outlook
Aviation authorities is rotating toward logistics providers as the dominant buyer archetype in intelligent airways procurement. SITA leverages its passenger processing heritage to compete in air traffic management digitization. Honeywell Corporation anchors its position through avionics integration for advanced air mobility platforms. Cisco Systems sustains network infrastructure dominance across connected airport ecosystems.
Intelligent Airways Transportation encompasses autonomous aerial systems, artificial intelligence-driven traffic coordination, and networked sensor architectures designed to manage unmanned and manned vehicle coexistence in controlled airspace. The technology stack relies on real-time data fusion at sub-second latency to prevent collision events and optimize routing efficiency. Artificial Intelligence and IoT currently lead technology deployment, while Autonomous Systems capture expanding margin pools as regulatory frameworks mature. Advanced Air Mobility and Air Traffic Management Systems represent the fastest-growing product categories, with Drones maintaining volume leadership in near-term deployments.
FAA Part 107 waivers and the EU AI Act create dual compliance burdens for cross-border operators seeking unified certification. EASA's special condition frameworks for vertical take-off and landing aircraft are forcing manufacturers to redesign control architectures before European market entry. Stakeholders must monitor regulatory divergence between the United States and European Union as the primary determinant of platform development roadmaps and partnership structures.
Market Dynamics
FAA Part 107 waivers and EASA special condition frameworks are forcing manufacturers to maintain parallel certification tracks, fragmenting development roadmaps and partnership structures across the Atlantic. This regulatory divergence sits at the center of competitive positioning in intelligent airways.
Growth Catalysts
- Beyond-Visual-Line-of-Sight Operations:FAA certification pathways for BVLOS flight are unlocking commercial drone fleet deployment at scale in the United States. Logistics providers are accelerating procurement of autonomous systems for last-mile parcel networks.
- Urban Air Mobility Corridors:Dallas and Los Angeles are advancing operational readiness for passenger-carrying eVTOL services. Municipal infrastructure investments in vertiports and charging stations are creating localized demand clusters.
- EU AI Act Compliance Infrastructure:Artificial intelligence-driven traffic coordination systems are gaining procurement priority as European operators pre-position for algorithmic accountability mandates. Software vendors are embedding explainability modules into air traffic management platforms.
Market Restraints
- Lithium-Ion Battery Supply Concentration:Cathode material processing concentrates in China, exposing eVTOL manufacturers to input cost volatility and geopolitical supply interruptions. Cell production bottlenecks are extending aircraft delivery timelines.
- Dual Certification Burden:Cross-border operators seeking unified FAA-EASA approval face redundant testing protocols and documentation requirements. Small and mid-sized developers lack capital to sustain parallel regulatory engagements.
- Radar-Detect-and-Avoid Limitations:Existing ground-based radar infrastructure cannot reliably track small uncrewed aircraft below 500 feet. Sensor fusion architectures remain unproven at commercial traffic densities.
Strategic Opportunities
- Emergency Medical Services:Organ transport and rural hospital connectivity represent underpenetrated application segments with premium pricing tolerance. Blood product delivery networks in the Mountain West United States are piloting dedicated air corridors.
- 5G Network Slicing:Ultra-reliable low-latency communication links are enabling command-and-control handoffs between ground stations and airborne platforms. Telecommunications infrastructure convergence with aviation systems is creating new partnership models.
- Inflation Reduction Act Tax Credits:Clean aviation technology incentives are subsidizing hydrogen fuel cell and battery-electric propulsion development. Domestic manufacturing requirements are reshaping supplier location decisions.
Industry Challenges
- Air Traffic Controller Skill Shortage:Remote pilot certification programs lack standardized curricula across training institutions. Simulator-based instruction is not producing operators capable of managing mixed-traffic scenarios.
- Legacy System Integration Complexity:Existing FAA automation infrastructure operates on 1980s-era software architectures. Modern uncrewed traffic management platforms require middleware layers that introduce latency and failure points.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intelligent Airways Transportation Market |
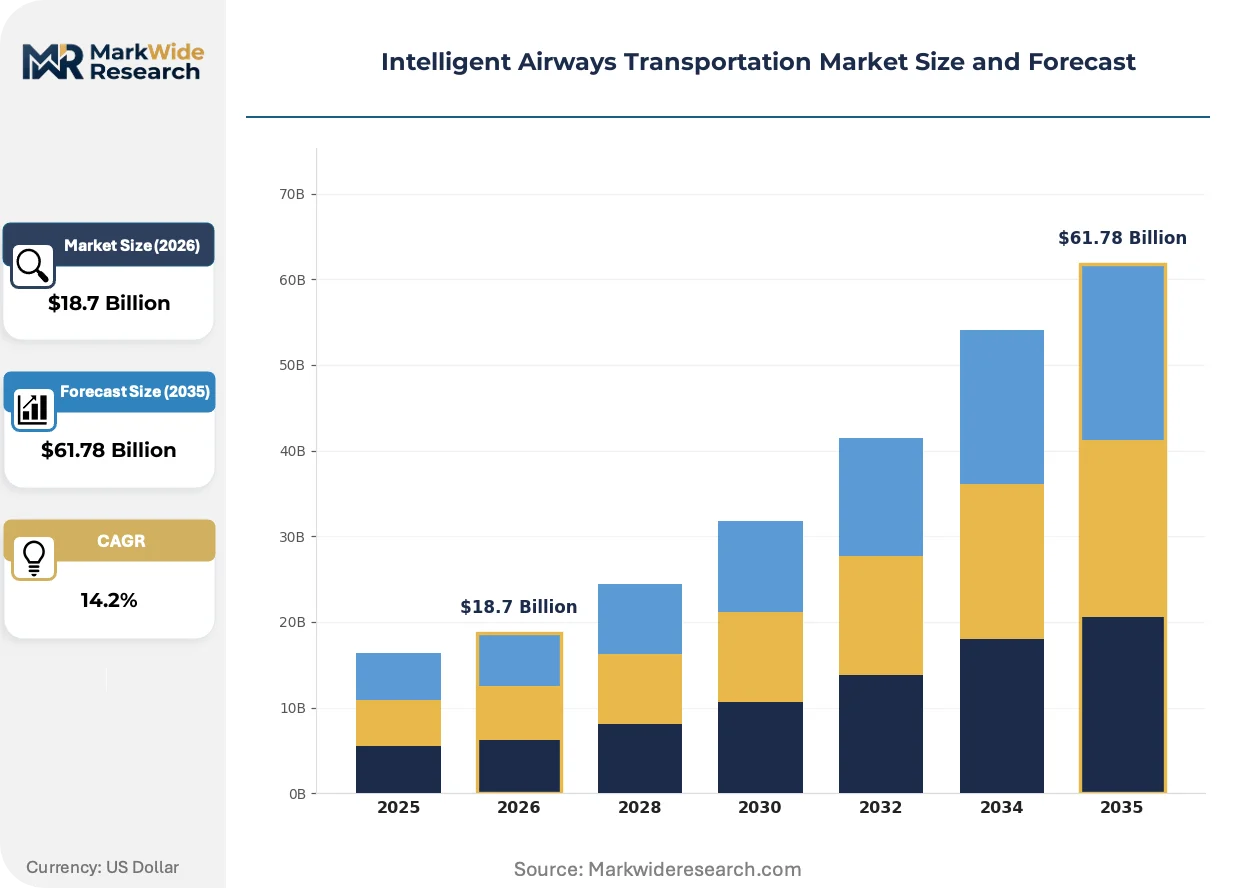
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Autonomous Systems, Artificial Intelligence, Blockchain, IoT Product Type: Drones, Advanced Air Mobility, Unmanned Aerial Vehicles, Air Traffic Management Systems Application: Parcel Delivery, Surveillance, Agricultural Monitoring, Emergency Response End User: Aviation Authorities, Logistics Providers, Agriculture Firms, Security Agencies |
| Companies Covered | International Business Machines Corporation, Amadeus IT Holding, Cisco Systems, Indra Sistemas, NEC Corporation, Rockwell Collins, SITA, Siemens AG, Honeywell Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intelligent Airways Transportation Market Strategic Shifts
Digitization of air traffic coordination is compressing the gap between sensor detection and routing decision, while regulatory frameworks struggle to match technology deployment velocity. Three developments are reshaping competitive positioning.
Artificial intelligence-driven predictive routing is displacing rule-based sequencing algorithms in high-density airspace. Major cargo carriers are adopting machine learning platforms that anticipate congestion 15 minutes ahead of human controllers. This capability is compressing arrival spacing and increasing runway throughput at capacity-constrained airports.
EASA's special condition frameworks for vertical take-off and landing aircraft are mandating redundant flight control architectures that exceed FAA Part 23 requirements. European market entry now demands redesigned avionics stacks and additional testing cycles. Manufacturers with European certification priority are capturing early operator commitments in Germany and France.
Logistics buyers are consolidating vendor relationships around integrated platform providers rather than point-solution drone operators. Parcel networks in the United States are awarding multi-year service contracts to firms owning aircraft, ground infrastructure, and traffic management software. This bundling is squeezing standalone hardware manufacturers and favoring vertically integrated service models.
Intelligent Airways Transportation Market Segmentation
Intelligent Airways Transportation demands precise segmentation because technology maturity, regulatory clearance, and buyer procurement cycles vary dramatically across aerial platforms and use cases. Channel strategies diverge sharply between hardware manufacturers selling through aviation distributors and software vendors embedding directly into airport infrastructure.
Technology:
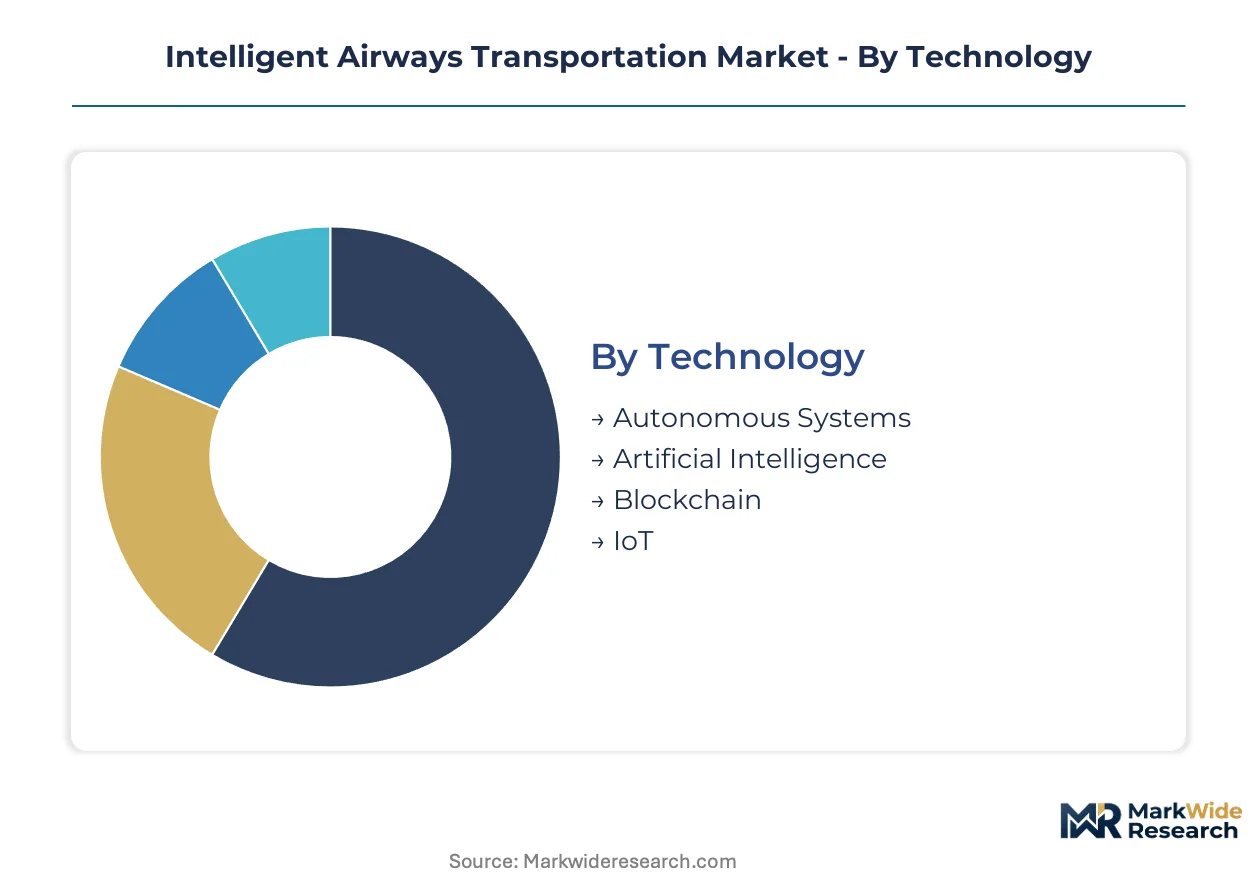
Autonomous Systems and Artificial Intelligence flow through defense contractors and logistics integrators, while Blockchain and IoT components route through telecommunications infrastructure providers and airport system vendors.
- Autonomous Systems:Hardware-software stacks enabling self-piloting aircraft without human intervention in the control loop. Demand concentrates among United States logistics providers building beyond-visual-line-of-sight parcel networks, constrained by FAA certification timelines for commercial deployment.
- Artificial Intelligence:Machine learning algorithms processing sensor fusion for predictive routing and collision avoidance. European aviation authorities are driving procurement priority ahead of EU AI Act compliance deadlines, forcing explainability module integration into traffic management platforms.
- Blockchain:Distributed ledger architectures securing flight data integrity and identity verification across multi-operator airspace.
- IoT:Networked sensor arrays providing real-time environmental and aircraft state monitoring to ground control systems.
Autonomous Systems dominates installed base. Artificial Intelligence is where expansion concentrates.
Product Type:
Cost tier stratification separates premium-certified passenger platforms from commodity surveillance hardware, with middleware traffic systems commanding recurring revenue premiums.
- Drones:Uncrewed aerial platforms under 55 pounds for commercial and recreational applications. Parcel delivery networks in Dallas and Los Angeles are piloting dedicated urban corridors, though battery supply bottlenecks are extending delivery timelines.
- Advanced Air Mobility:Electric vertical take-off and landing aircraft designed for passenger transport in metropolitan environments. EASA special condition frameworks are forcing redundant flight control architectures that exceed FAA requirements, fragmenting manufacturer development roadmaps.
- Unmanned Aerial Vehicles:Military-derived platforms adapted for civilian surveillance and agricultural spraying operations.
- Air Traffic Management Systems:Ground-based and cloud-native platforms coordinating mixed manned-unmanned airspace operations.
Drones command near-term volume leadership. Advanced Air Mobility is climbing the fastest.
Application:
Volume concentration tracks municipal infrastructure investment cycles, with emergency response applications capturing premium pricing through outcome-based contracting models.
- Parcel Delivery:Last-mile logistics networks utilizing autonomous aerial platforms for time-definite package transport. United States logistics providers are consolidating vendor relationships around integrated platform operators rather than standalone drone manufacturers.
- Emergency Response:Medical organ transport, rural hospital connectivity, and disaster relief coordination. Blood product delivery networks in the Mountain West United States are piloting dedicated air corridors with premium pricing tolerance.
- Surveillance:Border patrol, infrastructure inspection, and law enforcement monitoring deployments.
- Agricultural Monitoring:Crop health assessment and precision spraying operations over farmland.
Parcel Delivery dominates procurement volume. Emergency Response is gaining share fastest.
End User:
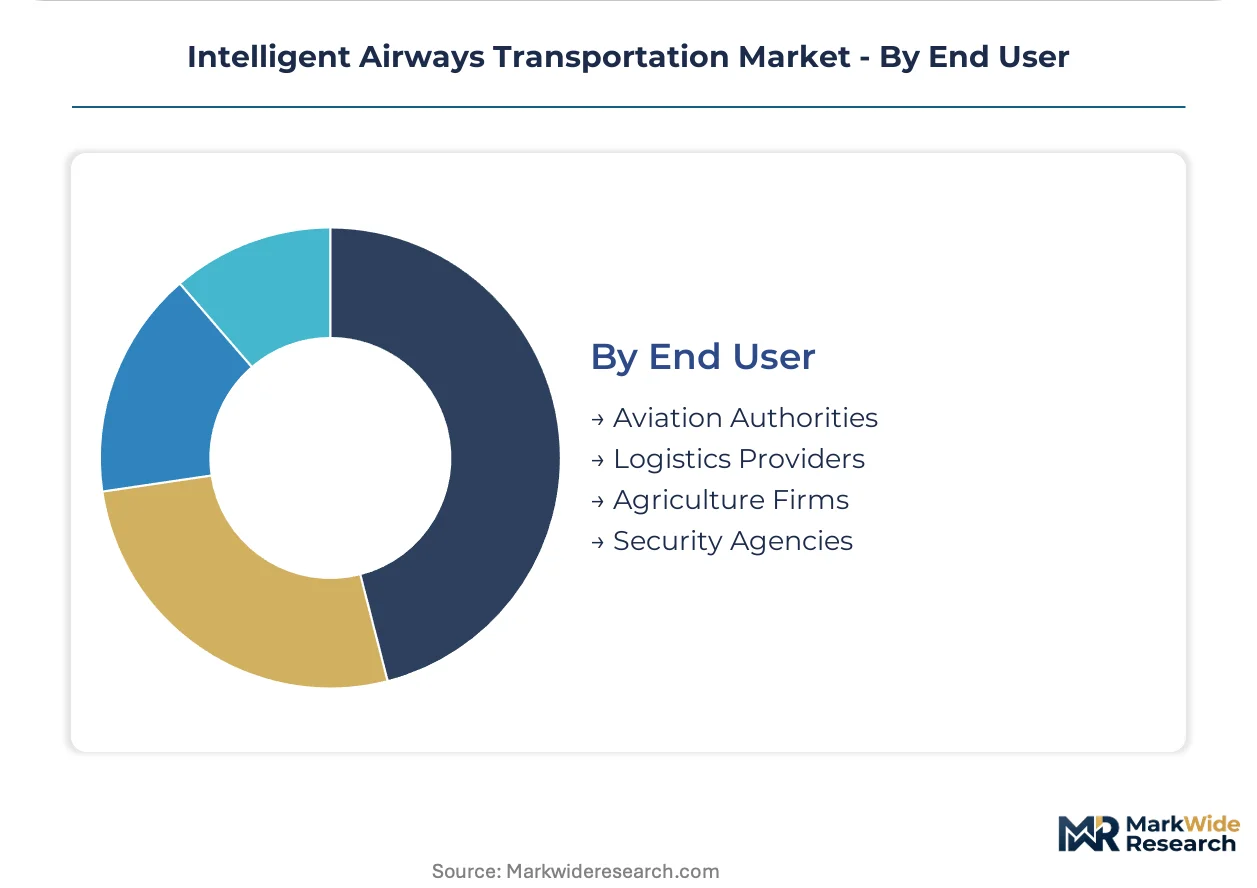
Customer type determines procurement authority, with aviation authorities mandating standards while logistics providers drive platform deployment at operational scale.
- Logistics Providers:Parcel and express delivery firms operating autonomous fleet networks. These buyers are awarding multi-year service contracts to vertically integrated vendors owning aircraft, ground infrastructure, and traffic management software.
- Aviation Authorities:FAA and EASA regulators establishing certification pathways and airspace integration standards. Dual compliance burdens for cross-border operators are reshaping partnership structures and platform development roadmaps.
- Security Agencies:Law enforcement and defense organizations deploying surveillance and counter-drone systems.
- Agriculture Firms:Large-scale farming operations utilizing aerial platforms for crop monitoring and treatment application.
Logistics Providers dominate near-term demand. Aviation Authorities is where regulatory leverage concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German avionics exports flow into United States advanced air mobility programs, while Chinese battery cell manufacturers supply Korean and Japanese eVTOL assemblers. Trade corridors concentrate component flows between regulatory jurisdictions with divergent certification timelines.
United States
Logistics providers in Dallas and Los Angeles are procuring autonomous systems for dedicated urban air mobility corridors. FAA Part 107 waivers for beyond-visual-line-of-sight operations are reshaping commercial drone fleet deployment schedules. Vertiport infrastructure investments in Texas and California are creating localized demand clusters for integrated platform operators.
Germany
EASA special condition frameworks for vertical take-off and landing aircraft are mandating redundant flight control architectures. The EU AI Act is accelerating procurement of explainability modules for traffic management platforms. Industrial clusters in Bavaria and Baden-Württemberg are hosting avionics redesign programs for European market entry.
China
Cathode material processing concentrates domestic supply for lithium-ion battery cell production. MIIT standards for uncrewed aerial vehicle traffic management are advancing separate from Western regulatory frameworks. Manufacturing bases in Shenzhen and Guangzhou are extending delivery timelines for international eVTOL manufacturers.
Japan
METI is coordinating public-private partnerships for urban air mobility demonstration projects. Domestic simulator-based training programs lack standardized curricula for mixed-traffic scenario management. The Kanto region around Tokyo is piloting 5G network slicing for command-and-control handoffs between ground stations and airborne platforms.
United Kingdom
Civil Aviation Authority pathways for uncrewed traffic integration are diverging from post-Brexit EU alignment. London airspace congestion is driving demand for predictive routing algorithms that anticipate controller workload. The Southeast corridor is hosting blood product delivery pilots for rural hospital connectivity networks.
Intelligent Airways Transportation Market Competitive Environment
Listed leaders compete with private specialists across certification track access and municipal infrastructure partnerships. The vendor base organizes around three tiers: diversified technology conglomerates with avionics heritage, telecommunications infrastructure providers with network slicing capabilities, and vertically integrated service operators bundling aircraft with ground systems. Dominant competitive moves include strategic partnerships with aviation authorities for regulatory pre-positioning and geographic expansion through multi-year logistics service contracts.
Among diversified technology conglomerates, International Business Machines Corporation and Cisco Systems exemplify the infrastructure-software archetype anchoring network and data fusion layers. Siemens AG occupies a position within the industrial automation tier serving ground infrastructure requirements. SITA represents the aviation-specialist archetype leveraging passenger processing heritage for air traffic management digitization. Honeywell Corporation anchors the avionics integration tier for advanced air mobility platforms.
| Leading Market Players |
|---|
| International Business Machines Corporation |
| Amadeus IT Holding |
| Cisco Systems |
| Indra Sistemas |
| NEC Corporation |
| Rockwell Collins |
| SITA |
| Siemens AG |
| Honeywell Corporation |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at Chinese cathode processing facilities is running above 85 percent, compressing input cost floors for battery-electric propulsion systems while elevating price leverage for vertically integrated eVTOL assemblers. This scale concentration simultaneously tightens margin structures for standalone hardware vendors and rewards operators with captive cell supply.
Pricing Analysis
Next-generation autonomous traffic management platforms command 40-60 percent premiums over legacy rule-based sequencing systems, while current-generation drone hardware faces commoditization pressure from Shenzhen manufacturing clusters. Three-tier pricing structure across FAA-certified premium, CE-marked standard, and uncertified economy levels separates logistics providers from surveillance operators. Cost compression in commodity UAV tiers is intensifying because Shenzhen cell manufacturers are extending delivery timelines for international buyers. Parcel delivery networks exhibit lowest price sensitivity due to outcome-based contracting, while agricultural spraying operators negotiate aggressively on per-acre service rates.
Supply Chain Analysis
Port congestion at Los Angeles-Long Beach and Rotterdam-Antwerp corridors is extending inbound logistics cycles for European avionics components destined for United States advanced air mobility programs. Lithium-ion cell production concentrates in China, South Korea, and Japan, with cathode material processing drawing from Sichuan and Jiangxi province refining capacity. Supply chain risk centers on single-source dependency for high-nickel cathode chemistries subject to export licensing variability. Distribution runs through aviation-certified distributors for hardware tiers and direct SaaS embedding for traffic management platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Intelligent Airways Transportation sits in early-cycle expansion, with FAA Part 107 waiver velocity outpacing prior regulatory bottlenecks and unlocking commercial deployment at operational scale.
For Market Incumbents: Fortify certification moats by accelerating EASA special condition compliance ahead of European market entry deadlines. Incumbent avionics vendors should deepen backward integration into sensor fusion software to counter emerging platform operators bundling aircraft with ground infrastructure. Priority leverage rests on middleware layer control that bridges 1980s-era FAA automation with cloud-native traffic systems. For New Entrants and Emerging Players: FAA Part 107 fast-track pathways for beyond-visual-line-of-sight operations offer the most penetrable entry wedge for logistics-focused service operators. Blood product delivery networks in the Mountain West United States represent undercontracted white space with premium pricing tolerance. Go-to-market execution should anchor on multi-year service contracts bundling aircraft, vertiport access, and traffic management software rather than standalone hardware sales. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated platform operators owning traffic management software layers, with SaaS-tiered airspace coordination fees generating predictable cash flows against lumpy aircraft sales. Long-term viability favors acquisition targets with dual FAA-EASA certification progress and municipal infrastructure partnerships in Dallas or Los Angeles corridor development. Signal to monitor: EASA special condition framework finalization timing as inflection point for European operator commitment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Vertiport Infrastructure Partnership | Municipal anchor contracts in Dallas and Los Angeles corridors lock in exclusive airspace access for integrated operators. |
| Dual Certification Investment | Parallel FAA-EASA track access fragments development roadmaps but captures early European operator commitments. |
| 5G Network Slicing Integration | Ultra-reliable low-latency links enable command-and-control handoffs, creating telecommunications-aviation convergence value. |
| Explainability Module Development | EU AI Act compliance pre-positioning accelerates procurement priority for European traffic management platforms. |
| Hydrogen Fuel Cell Propulsion | Inflation Reduction Act tax credits subsidize clean aviation technology, reshaping supplier location decisions toward domestic manufacturing. |
Study Parameters
A spread of perspectives from FAA certification officers, logistics fleet procurement directors, eVTOL platform engineers, and air traffic management software architects converged on the working assumptions driving this analysis. Primary field engagement with these stakeholders was cross-validated against FAA Part 107 waiver databases, EASA special condition publication records, and municipal vertiport investment disclosures. Bottom-up triangulation across individual program announcements and top-down reconciliation with aviation authority budget appropriations anchored volume estimates.
Segmentation dimensions modeled span technology stack (autonomous systems, artificial intelligence, IoT, blockchain), product tier (drones, advanced air mobility, air traffic management systems), application use case, and end-user procurement authority. CAGRs were derived from adoption curve analysis calibrated to regulatory clearance velocity and infrastructure investment cycles across the projection horizon. Forecast inputs incorporated battery cell delivery timeline assumptions and FAA-EASA regulatory divergence scenarios.
Underlying assumptions cover FAA Part 107 waiver grant velocity and EASA special condition implementation timelines, with deviation risk concentrated in lithium-ion supply interruptions and air traffic controller training pipeline bottlenecks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Automotive V2X Market
Smart Transportation Solutions
North America IoT Transportation Market
Smart Transportation Solutions
Monorail System Market
Smart Transportation Solutions
Personal Transporter Market
Smart Transportation Solutions
Mobility Technologies Market
Smart Transportation Solutions
Automated Parking Systems Market
Smart Transportation Solutions
Platform Screen Doors Market
Smart Transportation Solutions
Car E-Hailing Market
Smart Transportation Solutions
Europe Electronic Toll Collection Market
Smart Transportation Solutions
Contactless Ticketing Market
Smart Transportation Solutions
Traffic Management System Market
Smart Transportation Solutions
Bike Sharing Market
Smart Transportation Solutions
Shared Mobility Market
Smart Transportation Solutions
New Energy Vehicle Sweeper Market
Smart Transportation Solutions
5G in Automotive and Smart Transportation Market
Smart Transportation Solutions
Rail Internet of Things (IoT) Market