
 Global Robotics Market | 2026-2036
Global Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Robotics Market Outlook
Modular robot arm configurations with swappable end-effectors is recalibrating how manufacturers evaluate total cost of ownership against fixed automation lines. Fanuc Corporation leverages its captive servo motor production to control component lead times across Asian supply chains. ABB Ltd. anchors its European installed base through predictive maintenance software bundled with hardware contracts. KUKA AG competes on automotive line integration depth, particularly in German OEM paint and assembly halls.
Robotics encompasses programmable electromechanical systems with specified repeatability tolerances, payload capacities, and axis configurations designed to execute physical tasks with minimal human intervention. Industrial robots dominate current revenue pools due to mature automotive and electronics manufacturing demand, while collaborative robots represent the fastest-expanding product category as SMEs adopt fenceless automation. Machine learning integration within computer vision systems is displacing rule-based programming in quality inspection applications across logistics and electronics end users.
The EU AI Act, ISO 10218 safety standards, and FDA device regulations for surgical systems collectively determine market access conditions and product liability frameworks for robotics vendors. China's SAMR enforces GB standards for industrial automation equipment entering domestic manufacturing facilities. Stakeholders must monitor how divergent safety certification requirements between European CE marking and American OSHA interpretations affect platform development roadmaps and regional go-to-market sequencing.
Market Dynamics
The robotics sector is restructuring around modular hardware architectures that decouple mechanical platforms from software control layers, forcing vendors to choose between proprietary ecosystem lock-in or interoperability investments.
Growth Catalysts
- EU AI Act compliance mandates:European manufacturers must certify autonomous systems for safety-critical applications, creating certified-system demand across automotive and logistics end uses.
- Electronics contract manufacturing scale:Shenzhen and Dongguan industrial corridors deploy collaborative robots for micro-assembly tasks previously requiring manual dexterity.
- Machine learning vision integration:Defect detection algorithms reduce programming time for quality inspection stations in semiconductor packaging facilities.
Market Restraints
- Rare earth magnet supply concentration:Neodymium and dysprosium sourcing dependencies constrain high-torque servo motor production timelines.
- ISO 10218-1 certification timelines:Safety validation protocols for collaborative robots extend product launch cycles by eight to fourteen months.
- Technical workforce scarcity:Mechatronics engineering programs graduate insufficient talent to support SME automation deployments.
Strategic Opportunities
- Indian pharmaceutical manufacturing:CDSCO medical device regulations are harmonizing with ISO standards, enabling surgical robot system approvals.
- Food processing automation:USDA FSMA traceability requirements drive robotic handling investments in protein packaging operations.
- Battery cell assembly:Gigafactory construction in Nevada and Thuringia creates demand for precision electrode stacking equipment.
Industry Challenges
- Legacy PLC integration complexity:Brownfield facilities require protocol translation layers between modern robotic controllers and existing automation infrastructure.
- Cyber-physical security certification:IEC 62443 compliance for networked industrial robots demands specialized security engineering capabilities most vendors lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Robotics Market |
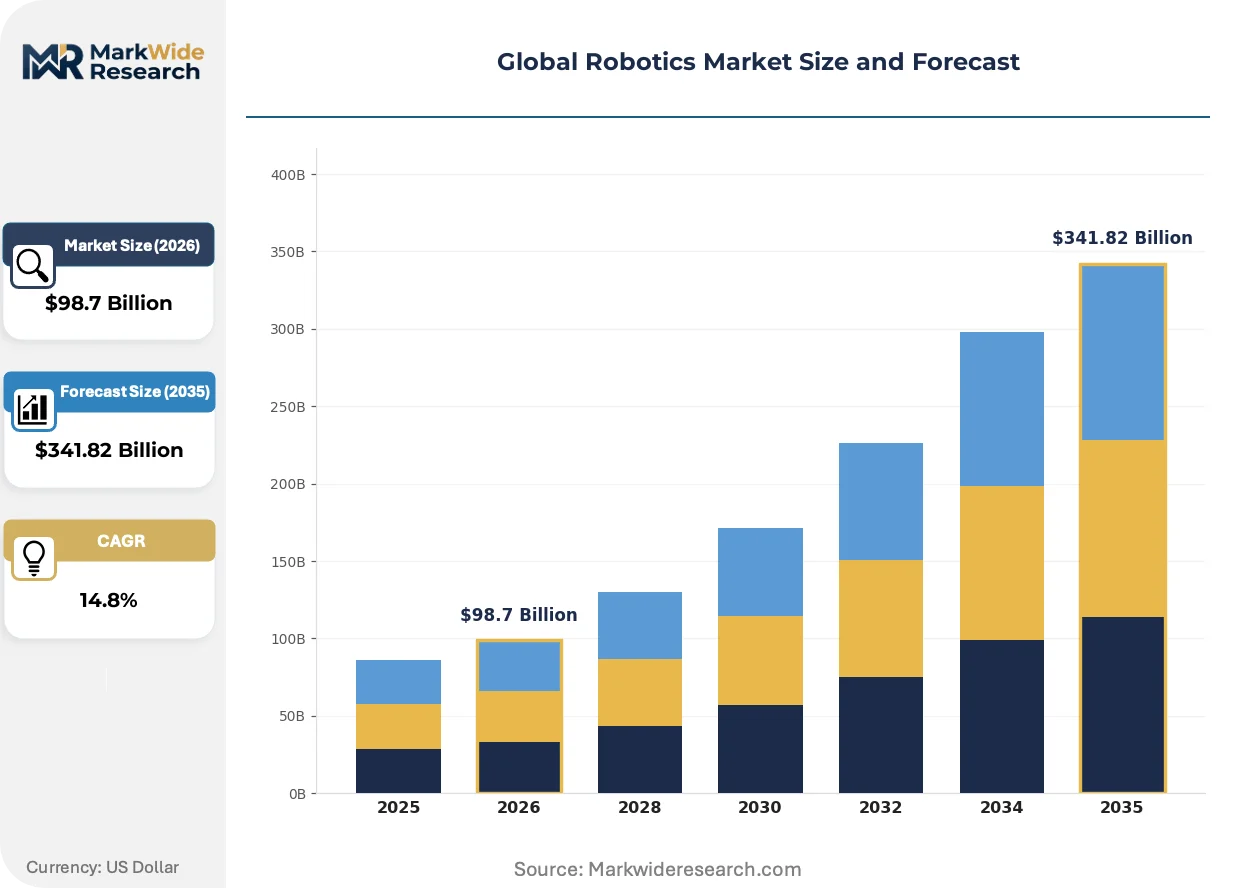
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $341.82 Billion |
| CAGR (2026 – 2036) | 14.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Robots, Service Robots, Collaborative Robots, Humanoid Robots Technology: Machine Learning, Computer Vision, Artificial Intelligence, Automation Application: Manufacturing, Healthcare, Logistics, Agriculture End User: Aerospace, Automotive, Electronics, Retail |
| Companies Covered | ABB Ltd., Fanuc Corporation, Yaskawa Electric Corporation, KUKA AG, Epson, Kawasaki Heavy Industries Ltd, Universal Robots, Denso Corporation, Intuitive Surgical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Robotics Market Strategic Shifts
Edge computing architectures are redistributing computational load from centralized servers to robot-mounted processors, altering how motion planning and sensor fusion workloads get allocated across manufacturing networks.
Computer vision systems are integrating transformer-based neural networks for real-time object pose estimation without pre-programmed part models. Tier-one automotive suppliers in Stuttgart and Toyota City are piloting these systems for bin-picking unstructured components. This compression of deployment timelines is integrating machine learning expertise directly into system integrator service offerings.
REACH substance restrictions on PFAS lubricants and flame-retardant plastics are forcing redesigns of cable assemblies and gearbox seals across European-sold robot lines. Vendors must reformulate material specifications or risk market exclusion. Collaborative robot segments face the steepest reformulation costs due to extensive human-contact surface areas.
Small and medium manufacturers are consolidating vendor relationships around platform ecosystems that bundle hardware, software licenses, and maintenance into single-contract structures. System integrators in Michigan and Bavaria report compressed evaluation cycles as buyers prioritize interoperability over best-of-breed component selection. This concentration is most pronounced among contract electronics manufacturers operating below five hundred employee thresholds.
Global Robotics Market Segmentation
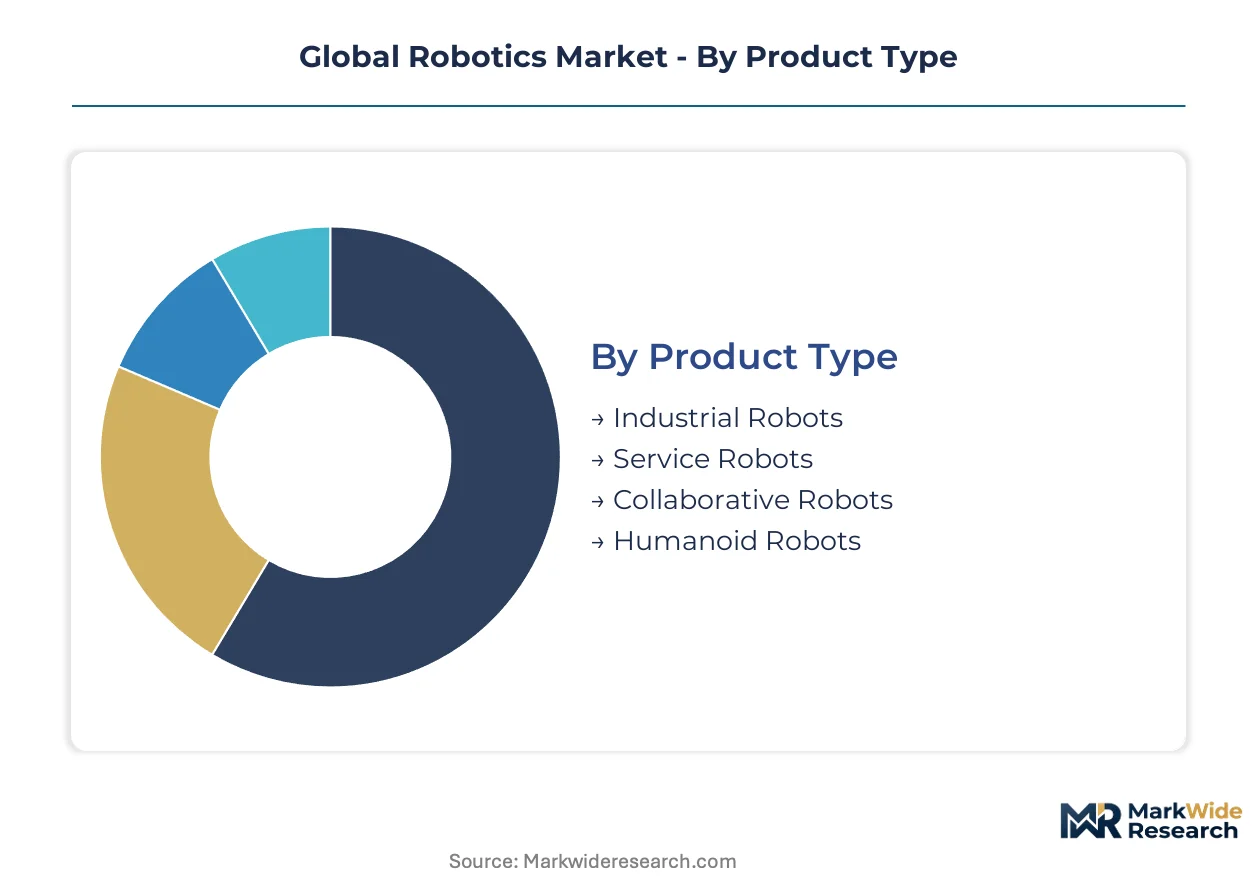
Robotics procurement decisions diverge sharply across buyer profiles, with capital-intensive manufacturers prioritizing payload precision while service operators weight human-robot interaction safety ratings. Understanding these segment boundaries clarifies why vendors maintain parallel engineering roadmaps rather than unified product architectures.
Product Type:
Buyers in this category separate by facility automation maturity and capital deployment timelines, with established manufacturers favoring proven repeatability over experimental humanoid platforms.
- Industrial Robots:Six-axis articulated arms and SCARA configurations deliver sub-millimeter repeatability tolerances for high-volume welding and material handling operations. German automotive OEMs in Stuttgart and Wolfsburg specify these systems for paint shop and body-in-white lines where ISO 10218-1 certification is mandatory.
- Collaborative Robots:Force-limited joints and speed-reduced operating modes enable fenceless deployment alongside human workers without physical guarding. Electronics contract manufacturers in Shenzhen and Dongguan deploy these for micro-assembly tasks where manual dexterity previously dominated, driven by tightening EU AI Act compliance requirements for exported goods.
- Service Robots:Autonomous mobile platforms and cleaning systems operate in semi-structured environments with LiDAR-based navigation.
- Humanoid Robots:Bipedal locomotion and dual-arm manipulation remain experimental for logistics and inspection applications.
Industrial robots lead volumes today; collaborative robots are gaining share fastest.
Technology:
Adoption patterns here track engineering talent availability, with computer vision spreading fastest where machine learning expertise concentrates regionally.
- Computer Vision:Transformer-based neural networks enable real-time object pose estimation without pre-programmed part models, compressing deployment timelines for bin-picking applications. Tier-one automotive suppliers in Toyota City pilot these systems for unstructured component handling.
- Machine Learning:Reinforcement learning algorithms optimize motion planning trajectories beyond traditional kinematic programming, reducing cycle times in semiconductor packaging facilities.
- Artificial Intelligence:Natural language interfaces and predictive maintenance models differentiate premium system offerings.
- Automation:Traditional PLC-based control architectures persist in brownfield facility upgrades.
Automation anchors installed base; computer vision is climbing the fastest.
Application:
Regulatory intensity varies dramatically across these use cases, with healthcare and aerospace demanding certification depth that manufacturing buyers rarely require.
- Manufacturing:Robotic welding, assembly, and quality inspection systems dominate current revenue pools due to mature automotive and electronics demand. Battery cell assembly lines in Nevada and Thuringia gigafactories create precision electrode stacking equipment demand.
- Logistics:Automated storage and retrieval systems plus sortation robots address labor scarcity in e-commerce fulfillment networks.
- Healthcare:Surgical systems and rehabilitation robots face FDA and EMA device regulations that extend approval timelines.
- Agriculture:Precision spraying and harvesting robots operate under variable field conditions with limited standardization.
Manufacturing dominates current deployment; logistics shows steepest expansion trajectory.
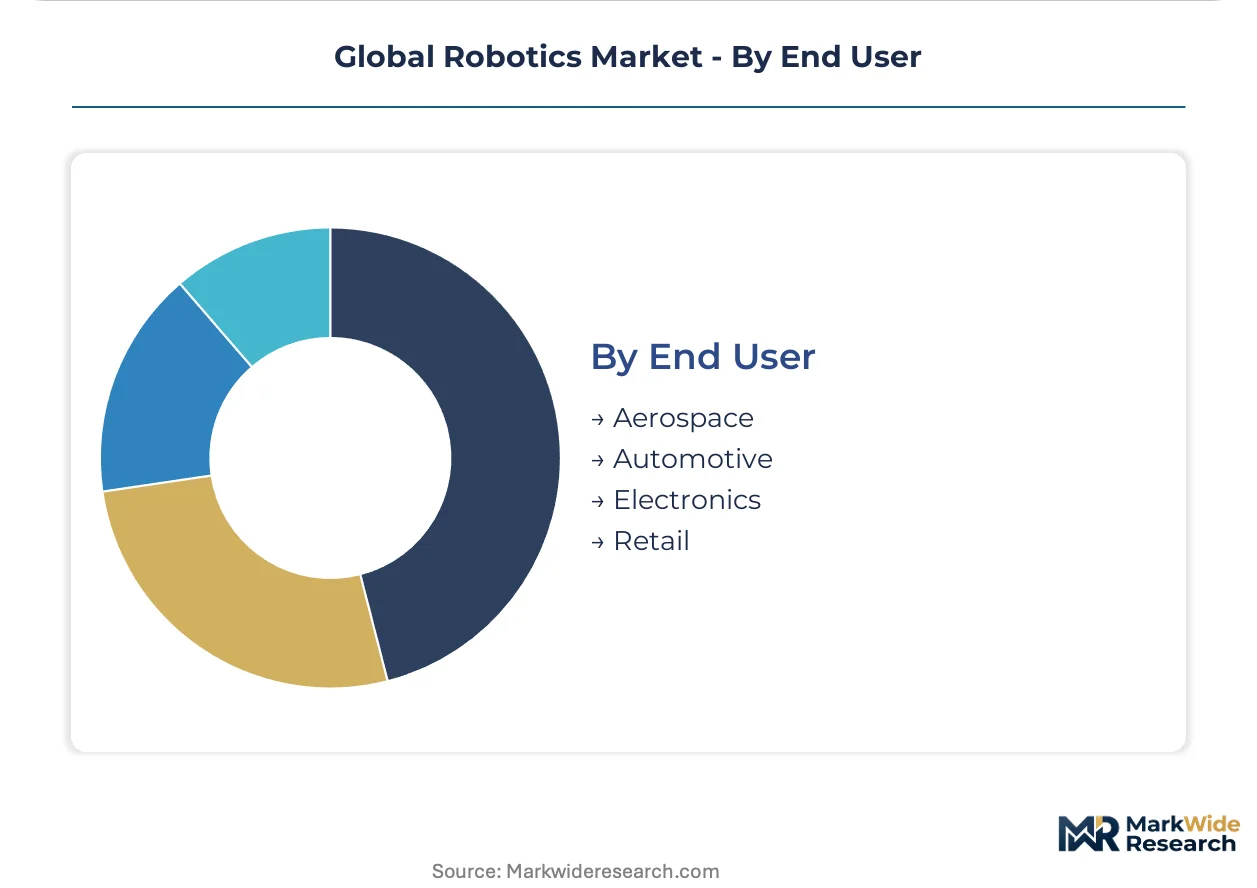
End User:
Volume concentration and margin structure diverge, with aerospace accepting premium pricing for certified systems while retail prioritizes rapid payback periods.
- Automotive:Paint and assembly hall automation represents the deepest installed base, with German OEMs specifying KUKA and ABB systems for line integration. EU AI Act safety certification is becoming mandatory for autonomous material transport.
- Electronics:Contract manufacturers operate at scale in China's industrial corridor cities, deploying collaborative robots for PCB assembly and semiconductor packaging where REACH substance restrictions on PFAS lubricants force material redesigns.
- Aerospace:Precision drilling and composite layup applications demand specialized end-effectors and extended validation protocols.
- Retail:Inventory scanning and customer service robots face compressed evaluation cycles and interoperability requirements.
Automotive leads segment revenue; electronics is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The robotics industry traces its industrial lineage to Japan's post-war automation push and Germany's automotive manufacturing scale-up, with both countries establishing the foundational engineering standards that still govern precision motion control and safety certification protocols today.
China
Electronics contract manufacturers in Shenzhen and Dongguan industrial corridors deploy collaborative robots for micro-assembly tasks at massive scale. SAMR enforces GB standards for industrial automation equipment entering domestic manufacturing facilities. The Yangtze River Delta battery gigafactories create concentrated demand for precision electrode stacking equipment.
Germany
Automotive OEMs in Stuttgart and Wolfsburg specify six-axis articulated systems for paint shop and body-in-white lines. EU AI Act compliance mandates now require safety certification for autonomous material transport systems. Bavaria's industrial automation cluster anchors European installed base through predictive maintenance software bundling.
United States
Battery cell assembly lines in Nevada gigafactories drive precision automation demand alongside logistics robotics for e-commerce fulfillment networks. FDA device regulations govern surgical system approvals while OSHA interpretations affect collaborative robot deployment standards. Michigan system integrators report compressed evaluation cycles as SMEs prioritize platform ecosystems.
Japan
Tier-one automotive suppliers in Toyota City pilot transformer-based computer vision systems for unstructured component bin-picking. METI industrial policy supports next-generation manufacturing technology adoption. The Nagoya industrial corridor maintains deep integration between robot manufacturers and captive servo motor supply chains.
South Korea
Semiconductor packaging facilities in the Seoul Capital Area deploy machine learning vision systems for defect detection algorithms. MFDS medical device regulations align with international standards for surgical robot approvals. The Busan-Ulsan manufacturing belt concentrates electronics automation demand alongside shipbuilding robotics applications.
Global Robotics Market Competitive Environment
The competitive structure tilts toward diversified industrial conglomerates with captive component production and software bundling capabilities. Market concentration remains moderate with clear tiering between full-line automation providers and specialized collaborative robot vendors. Two dominant archetypes emerge: integrated platform vendors controlling upstream servo motor supply, and software-centric players differentiating through predictive maintenance and computer vision integration. Competitive moves center on strategic partnerships for edge computing architectures and selective backward integration into rare earth magnet sourcing.
Within the integrated platform tier, Fanuc Corporation and ABB Ltd. exemplify divergent geographic anchoring strategies, with the former leveraging Asian supply chain control and the latter bundling software with European hardware contracts. KUKA AG occupies a position emphasizing automotive line integration depth. Among these archetypes, each represents a distinct approach to modular hardware architectures versus proprietary ecosystem lock-in.
| Leading Market Players |
|---|
| ABB Ltd. |
| Fanuc Corporation |
| Yaskawa Electric Corporation |
| KUKA AG |
| Epson |
| Kawasaki Heavy Industries Ltd |
| Universal Robots |
| Denso Corporation |
| Intuitive Surgical |
| Others |
Value Chain & Pricing Dynamics
EU AI Act safety certification mandates for autonomous material transport systems are forcing manufacturers to absorb validation costs upstream, compressing margins on collaborative robot lines sold into European automotive and logistics end uses while shifting procurement toward bundled hardware-software contracts that amortize compliance investment across multi-year service terms.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates robotics procurement, with premium tiers commanding spreads based on ISO 10218-1 certification depth and predictive maintenance software bundling. Price differentiation separates automotive OEM specifications from SME electronics contract manufacturer budgets, with the latter segment exhibiting acute sensitivity to total cost of ownership calculations. Pricing pressure stems from rare earth magnet cost volatility feeding into servo motor production, eroding margins at the economy tier where buyers lack volume leverage to negotiate fixed-price contracts.
Supply Chain Analysis
China's GB standards enforcement and India's phased manufacturing program are reshaping component sourcing, compelling vendors to establish localized assembly capacity or forfeit public procurement eligibility. Rare earth magnet production concentrates in China, with secondary refining capacity in Japan and Malaysia, while high-torque servo motor manufacturing anchors in Japan and Germany. Supply chain risk centers on single-source neodymium dependencies, with distribution running through regional system integrators in Michigan, Bavaria, and the Yangtze River Delta who bundle installation and aftermarket service.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where automotive OEM procurement committees now prioritize EU AI Act compliance depth and predictive maintenance integration over unit cost minimization, favoring vendors with captive software development and certified safety architectures.
For Market Incumbents: Lock in automotive line integration contracts through predictive maintenance software bundling and ISO 10218-1 certification pre-validation, while deepening upstream control over rare earth magnet supply channels to insulate margin structures from commodity volatility that threatens economy-tier positioning against emerging Asian competitors. For New Entrants and Emerging Players: System integrators in India's pharmaceutical manufacturing corridor represent the most penetrable channel partner type, offering white-space entry through CDSCO surgical robot approval pathways and food processing automation where USDA FSMA traceability requirements displace incumbent legacy systems lacking modern vision integration. For Investors and Strategic Acquirers: Asymmetric upside sits with software-centric robotics vendors possessing transformer-based computer vision IP and established edge computing partnerships, given long-term viability hinges on displacing rule-based programming in quality inspection applications; watch for inflection when tier-one automotive suppliers in Toyota City and Stuttgart expand bin-picking pilot programs to full production deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Magnet Sourcing | Secures neodymium supply channels against SAMR export licensing volatility affecting Chinese material flows. |
| Predictive Maintenance Software Bundling | ABB Ltd. and Fanuc Corporation use service contracts to anchor European and Asian installed base retention. |
| EU AI Act Pre-Certification Investment | Accelerates market access for autonomous material transport systems in German automotive OEM paint halls. |
| Edge Computing Architecture Partnerships | Redistributes motion planning workloads from centralized servers to robot-mounted processors in Nevada gigafactories. |
| Pharmaceutical Manufacturing Geographic Expansion | CDSCO harmonization with ISO standards enables surgical robot approvals in Indian CDMO automation upgrades. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with robotics OEM product managers, automotive Tier 1 procurement directors, electronics contract manufacturer operations heads, and system integrators in Michigan and Bavaria with secondary validation against SEC 10-K filings, customs trade data, and SAMR GB standards documentation. Bottom-up deployment counts across China's industrial corridor cities and top-down industrial automation spend estimates were triangulated to anchor volume assumptions.
Historical reference periods spanning pre-pandemic baseline through recent supply chain normalization established the forecast anchor, with growth trajectories modeled across product type, technology adoption curve, application intensity, and end-user vertical with additional segmentation by regional regulatory cluster and certification tier. CAGRs were derived from installed base replacement cycles and greenfield automation penetration patterns, incorporating machine learning vision integration timelines and EU AI Act compliance phase-in schedules as robotics-specific demand shapers.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to rare earth export licensing shifts, REACH substance restriction expansion, and semiconductor packaging facility automation saturation in the Seoul Capital Area. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Robotic Flexible Washer Market
Robotics and Automation
Industrial Robot Controllers Market
Robotics and Automation
Modular Robotics Market
Robotics and Automation
LAMEA Waste Sorting Robots Market
Robotics and Automation
Southeast Asia Industrial and Service Robot Market
Robotics and Automation
North America Automated Liquid Handling Market
Robotics and Automation
Autonomous Navigation Robots Market
Robotics and Automation
Firefighting Robots Market
Robotics and Automation
Robot Market
Robotics and Automation
Autonomous Security Robots Market
Robotics and Automation
Short-Range Drone Package Delivery Market
Robotics and Automation
Europe Underwater Robotics Market
Robotics and Automation
China Autonomous Mobile Robot Market
Robotics and Automation
Nano Robots Market
Robotics and Automation
Global Molecular Robotics Market
Robotics and Automation
Robot Charging Station Market