
 Portable Gas Detection Equipment Market | 2026-2036
Portable Gas Detection Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Gas Detection Equipment Market Intelligence
Industrial facility managers is unwinding legacy single-detector contracts in favor of connected multi-gas platforms. MSA Safety Incorporated dominates North American fire and rescue channel supply through captive distribution networks. Drägerwerk AG & Co. KGaA anchors European demand with electrochemical sensor R&D intensity at its Lübeck headquarters. Honeywell International Inc. extends its position across Middle Eastern oil and gas sites through localized calibration service infrastructure.
Portable gas detection equipment comprises battery-powered, wearable or handheld instruments that sample ambient air through electrochemical, infrared, or catalytic bead sensors to identify toxic, combustible, or oxygen-deficient atmospheres in real time. These devices transmit threshold alarms via Bluetooth or mesh radio to central safety systems, enabling immediate evacuation or ventilation response in hazardous work environments. Multi gas detector configurations command the strongest margin pools as buyers consolidate from single-function units to reduce device count and training overhead. Photoionization technology is displacing legacy methods in environmental monitoring applications where volatile organic compound detection at parts-per-billion resolution has become standard. Electrochemical sensors retain cost advantages in mining operations and utility maintenance, where hydrogen sulfide and carbon monoxide specificity remain paramount.
OSHA permissible exposure limits and EPA emissions monitoring mandates in the United States compel quarterly calibration cycles and data logging retention, directly expanding aftermarket service revenue. EU ATEX directives and IECEx certification schemes govern intrinsic safety design standards, creating compliance barriers for non-certified manufacturers seeking European market access. China's GB standards and MIIT equipment certification requirements impose additional testing protocols for wireless-enabled detectors. Stakeholders must weigh sensor modularity against total cost of ownership as regulatory data-integrity requirements intensify across major industrial economies.
Market Dynamics
Multi-gas platform consolidation is compressing procurement cycles as industrial buyers abandon single-function units, while wireless telemetry integration is rewriting aftermarket service economics across hazardous work environments.
Growth Catalysts
- OSHA confined space standards:Tighter permissible exposure limits in the United States are compelling oil and gas site operators to upgrade from legacy detectors to connected multi-gas systems with real-time data logging.
- Photoionization detection:Parts-per-billion volatile organic compound resolution is displacing legacy methods in environmental monitoring applications where regulatory thresholds continue tightening.
- Fixed-plus-portable hybrid deployments:China, Germany, and India are concentrating capital investment in integrated safety architectures that merge perimeter monitoring with personal protective equipment.
Market Restraints
- Electrochemical sensor supply concentration:Specialty membrane and electrolyte manufacturing clusters in East Asia create single-source vulnerability for manufacturers dependent on just-in-time component flows.
- ATEX certification costs:EU intrinsic safety design standards impose testing and documentation burdens that freeze out smaller manufacturers seeking European market entry.
- Calibration service infrastructure:Quarterly calibration cycles mandated by OSHA and EPA protocols require localized technical labor pools that remain thin in secondary industrial corridors.
Strategic Opportunities
- India's industrial safety modernization:Factory compliance deadlines under domestic occupational health frameworks are accelerating first-time detector adoption in metal processing and chemical manufacturing.
- Bluetooth-to-mesh radio convergence:Integration of personal wearables with site-wide safety networks opens subscription revenue streams for fleet management and predictive maintenance analytics.
- EU Green Deal emissions monitoring:Fugitive methane detection mandates at petrochemical facilities are expanding addressable demand for high-sensitivity portable analyzers.
Industry Challenges
- Cross-trained calibration technician scarcity:Electrochemical, infrared, and photoionization sensor platforms each demand distinct troubleshooting competencies that strain field service workforce development.
- Legacy system integration friction:Hardwired 4-20mA output protocols in existing distributed control systems resist seamless incorporation of wireless-enabled smart detectors without costly gateway retrofits.
- IECEx certification timeline variability:Divergent national interpretation of explosion protection standards stretches product approval cycles and delays revenue recognition across export markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Gas Detection Equipment Market |
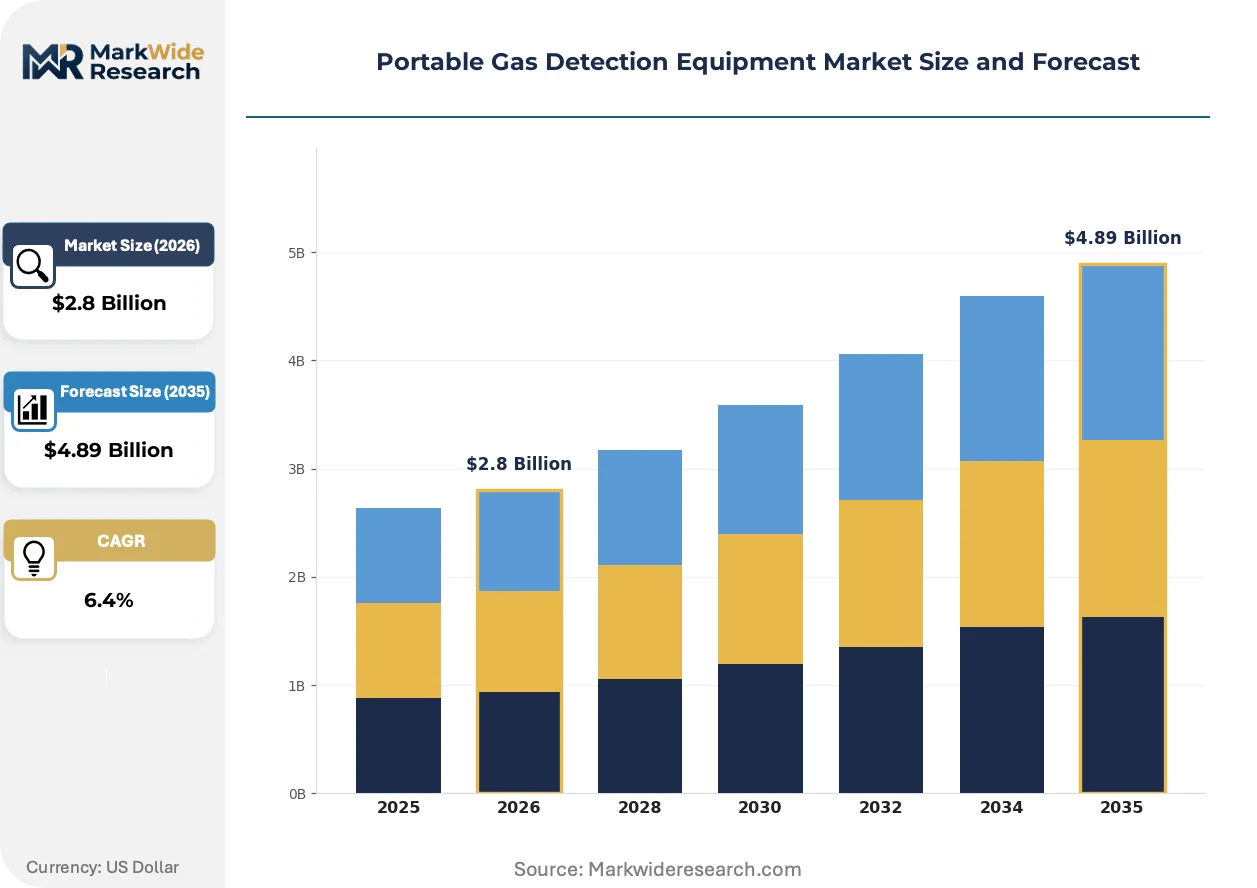
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Gas Detector, Multi Gas Detector, Gas Leak Detector, Combustible Gas Detector Technology: Electrochemical, Infrared, Catalytic Bead, Photoionization Application: Fire & Rescue, Confined Space Monitoring, Oil & Gas Sites, Environmental Monitoring End User: Mining Operations, Chemical Processing, Utility Maintenance, Construction Projects |
| Companies Covered | Honeywell International Inc., MSA Safety Incorporated, Drägerwerk AG & Co. KGaA, Industrial Scientific Corporation, Emerson Electric, Thermo Fisher Scientific Inc., Riken Keiki, Halma plc, Det-Tronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Gas Detection Equipment Market Strategic Shifts & Innovations
Sensor miniaturization and cloud connectivity are collapsing the boundary between personal protective equipment and industrial internet-of-things infrastructure, reshaping how safety data flows from the field to enterprise risk management systems.
Photoionization detection technology is fragmenting application-specific sensor portfolios as volatile organic compound monitoring at parts-per-billion thresholds becomes standard in environmental remediation and hazmat response. Environmental contractors and industrial hygienists are adopting handheld units that previously required laboratory-grade instrumentation. This capability compression is eroding the price premium historically commanded by specialized ambient air monitoring stations.
REACH chemical authorization procedures and EU F-Gas Regulation phase-down schedules are forcing sensor manufacturers to reformulate electrolyte chemistries and infrared source materials. Industrial consequence includes accelerated R&D cycles and supplier qualification costs that favor scaled producers with dedicated regulatory affairs teams. Gas detection OEMs serving European process industries are responding by consolidating component sourcing under ATEX-certified sub-suppliers with established substance compliance documentation.
Buyer preference is pivoting toward subscription-based fleet management contracts that bundle hardware, calibration, and data analytics into per-device monthly fees. Traditional distributor channels that transacted unit sales with sporadic service attachments are losing ground to manufacturer-direct safety-as-a-service programs. This restructuring is most visible in United States oil and gas operations where capital discipline favors operational expenditure treatment for personal protective equipment.
Portable Gas Detection Equipment Market Segmentation
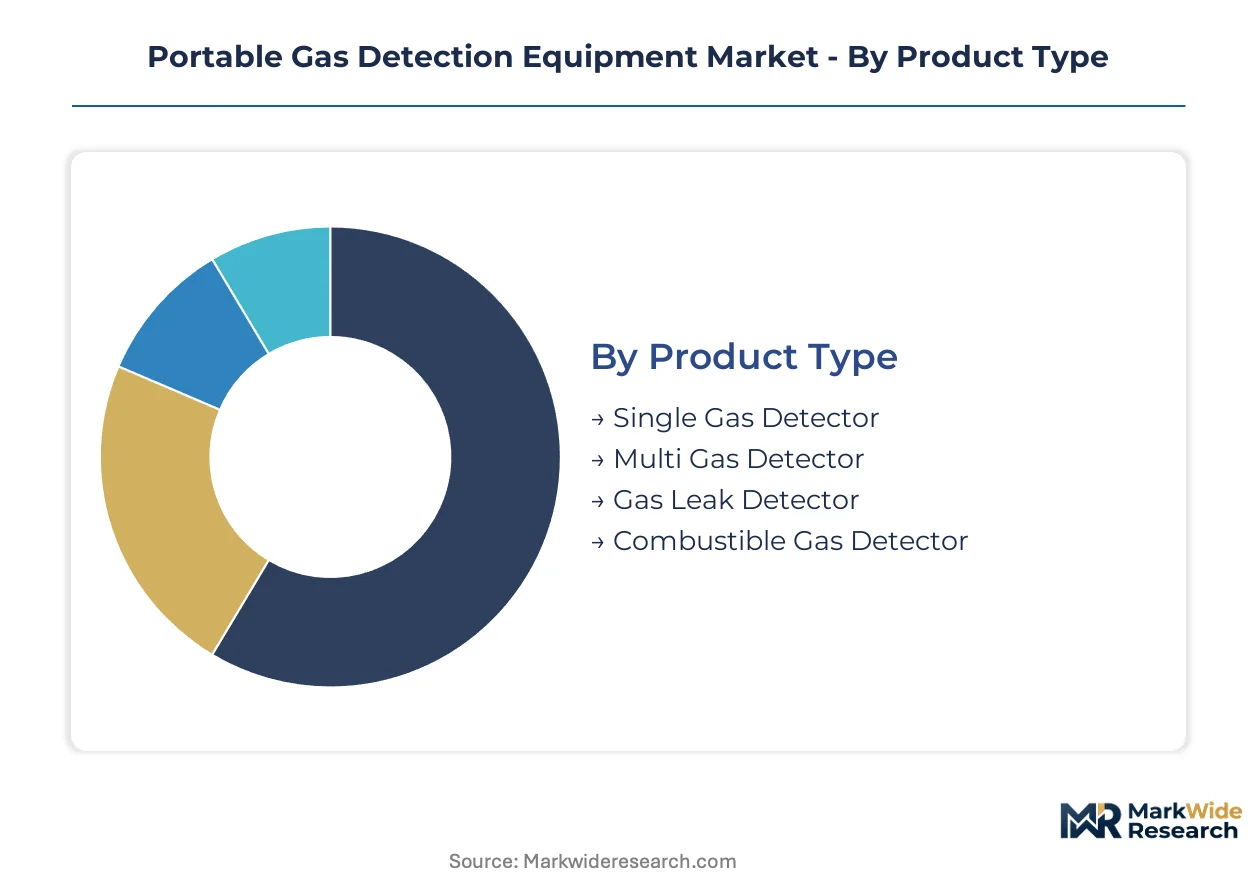
Segmentation in portable gas detection equipment reveals distinct margin architectures across product configurations and technology platforms. Buyers consolidate procurement around multi-sensor platforms while sensor chemistry choices determine aftermarket service economics and regulatory compliance pathways.
Product Type:
Margin pools concentrate in multi-sensor configurations as buyers abandon single-function units to reduce device count and training overhead across hazardous work sites.
- Multi Gas Detector:Battery-powered platforms simultaneously monitor four to six gas species through modular sensor cartridges. Oil and gas site operators in Texas and North Dakota are standardizing on these units as OSHA confined space standards mandate real-time data logging for hydrogen sulfide, carbon monoxide, oxygen, and combustible gas thresholds.
- Single Gas Detector:Dedicated instruments optimized for one hazard class—typically hydrogen sulfide or oxygen deficiency—at unit price points below multi-sensor alternatives. Mining operations in West Virginia and Kentucky retain procurement preference for these devices where workforce rotation and simple alarm protocols reduce training complexity.
- Gas Leak Detector:Handheld units with gooseneck probes for pinpoint source identification in pressurized systems. Chemical processing facilities deploy these for maintenance turnaround inspections.
- Combustible Gas Detector:Catalytic bead or infrared platforms calibrated for lower explosive limit percentage readings. Utility maintenance crews favor these for natural gas distribution line surveys.
Multi Gas Detector holds installed capacity. Gas Leak Detector is rotating up the share rankings.
Technology:
Technology selection determines sensor replacement cycles and calibration labor intensity, with electrochemical platforms dominating unit volume and photoionization commanding application-specific premiums.
- Electrochemical:Amperometric cells with specialty membranes and liquid electrolytes deliver parts-per-million resolution for toxic gases at sub-hundred-dollar sensor replacement cost. Mining operations and utility maintenance fleets in the United States standardize on this chemistry where hydrogen sulfide and carbon monoxide specificity remain paramount.
- Photoionization:Ultraviolet lamp ionization chambers detect volatile organic compounds at parts-per-billion resolution. Environmental remediation contractors in California and New Jersey are displacing laboratory-grade ambient air monitoring with handheld units as EPA regional thresholds tighten.
- Infrared:Non-dispersive absorption spectroscopy for combustible hydrocarbon detection without oxygen dependency. Oil and gas processing sites deploy these in inerted vessels.
- Catalytic Bead:Wheatstone bridge oxidation sensors for general combustible gas indication. Construction projects specify these for excavation pre-checks.
Electrochemical dominates unit shipments. Photoionization is climbing the fastest on environmental monitoring demand.
Application:
Application segmentation tracks regulatory enforcement intensity, with confined space monitoring and oil and gas site operations driving replacement cycles through mandated calibration protocols.
- Confined Space Monitoring:Pre-entry atmospheric testing and continuous wearables deployment for tank, vessel, and sewer maintenance. OSHA enforcement actions in the United States are compelling municipal utilities and petrochemical terminals to upgrade from spot-check protocols to connected multi-gas systems with man-down alarms.
- Oil & Gas Sites:Permian Basin and Gulf Coast operators deploy fixed-plus-portable hybrid architectures where perimeter monitors trigger personal protective equipment escalation. EPA fugitive emissions monitoring mandates are expanding procurement of high-sensitivity portable analyzers for methane leak detection.
- Fire & Rescue:Hazmat response teams require five-gas-plus radiation detection in ruggedized enclosures. Urban search and rescue units prioritize intrinsically safe certifications.
- Environmental Monitoring:Industrial hygienists and remediation contractors perform soil vapor intrusion and indoor air quality assessments. State-level volatile organic compound regulations in California and Massachusetts drive instrument refresh.
Oil & Gas Sites holds installed capacity. Environmental Monitoring is rotating up the share rankings.
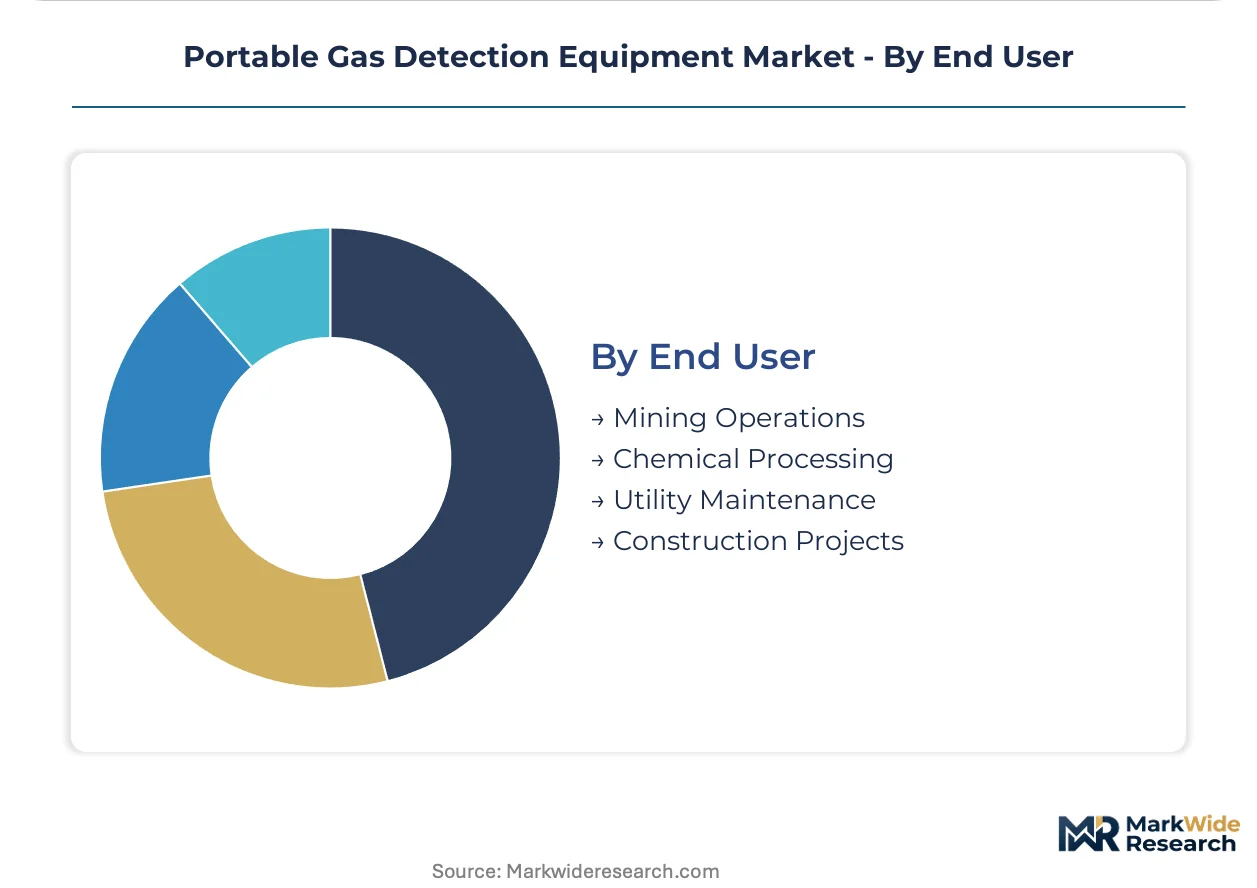
End User:
End user segmentation reflects divergent procurement sophistication, with chemical processing and mining operations consolidating fleet management under manufacturer-direct service contracts.
- Mining Operations:Underground coal and metal mines deploy personal multi-gas units with real-time location tracking through mesh radio networks. MSHA enforcement patterns in Appalachia and the Mountain West are accelerating replacement of legacy single-gas beepers with data-logging platforms.
- Chemical Processing:Gulf Coast and Ohio River Valley petrochemical complexes operate captive calibration laboratories with certified reference gas mixtures. These facilities favor subscription-based fleet management contracts bundling hardware, quarterly calibration, and predictive maintenance analytics.
- Utility Maintenance:Natural gas distribution and electric power generation crews perform leak survey and transformer vault entry with dedicated combustible and oxygen-deficiency instruments. Workforce rotation drives preference for simplified user interfaces.
- Construction Projects:General contractors and excavation subcontractors conduct pre-entry atmospheric testing for trench and foundation work. Project-based procurement favors rental and lease arrangements over capital purchase.
Chemical Processing holds installed capacity. Mining Operations is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German electrochemical sensor exports supply calibration laboratories across the Permian Basin and Gulf Coast, while Chinese GB-certified manufacturers penetrate Southeast Asian industrial safety procurement.
United States
OSHA confined space enforcement drives multi-gas detector procurement in Texas and North Dakota oilfields. EPA quarterly calibration mandates expand aftermarket service revenue pools. Houston petrochemical terminals deploy fixed-plus-portable hybrid architectures for perimeter-to-personnel safety integration.
Germany
EU ATEX directives govern intrinsic safety design standards for export-bound equipment. REACH chemical authorization forces electrolyte chemistry reformulation at Lübeck R&D clusters. Ruhr Valley chemical processing complexes consolidate fleet management under manufacturer-direct subscription contracts.
China
MIIT wireless equipment certification and GB standards impose testing protocols for mesh-radio detectors. Yangtze River Delta manufacturing bases supply specialty membranes to global electrochemical sensor assemblers. Sichuan-Chongqing mining belts accelerate personal multi-gas unit deployment under tightening occupational health frameworks.
India
Factory compliance deadlines under domestic occupational health regulations accelerate first-time detector adoption. Gujarat and Maharashtra metal processing hubs standardize on multi-sensor platforms to reduce training overhead. Central Pollution Control Board emissions monitoring directives expand environmental contractor procurement.
Saudi Arabia
SABIC-affiliated petrochemical complexes in Jubail Industrial City specify IECEx-certified portable analyzers for methane leak detection. Saudi Aramco procurement standards mandate localized calibration service infrastructure. Western Region construction projects favor rental arrangements over capital purchase for excavation pre-check protocols.
Portable Gas Detection Equipment Market Key Industry Players
Player mix skews toward diversified industrial conglomerates with captive safety divisions. Market structure concentrates around three to five vertically integrated manufacturers controlling North American and European distribution channels. Archetypes include electrochemical sensor specialists, fire-rescue channel incumbents, and diversified automation conglomerates. Dominant competitive moves encompass strategic partnerships for wireless telemetry integration and geographic expansion through localized calibration service infrastructure.
Within the diversified conglomerate tier, Honeywell International Inc. and Emerson Electric exemplify scale-driven positioning through Middle Eastern oilfield service networks and process automation integration. MSA Safety Incorporated occupies a distinct channel-control archetype through North American fire and rescue captive distribution. Drägerwerk AG & Co. KGaA anchors European demand concentration through Lübeck-based electrochemical R&D intensity. These three manufacturers represent divergent strategic postures: automation-platform integration, vertical channel ownership, and sensor-technology specialization.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| MSA Safety Incorporated |
| Drägerwerk AG & Co. KGaA |
| Industrial Scientific Corporation |
| Emerson Electric |
| Thermo Fisher Scientific Inc. |
| Riken Keiki |
| Halma plc |
| Det-Tronics |
| Others |
Cost & Logistics Intelligence
Subscription-based fleet management contracts now lock in multi-year supply access for oil and gas operators while compressing upfront capital outlays into predictable operational expenditure streams. This contract-structure shift binds buyers to manufacturer-direct calibration networks and sensor replacement programs, embedding price visibility through bundled per-device monthly fees rather than transactional unit pricing.
Pricing Analysis
Current-generation multi-gas platforms with Bluetooth-to-mesh radio convergence command substantial premiums over prior-generation single-function units, while next-generation photoionization detectors for parts-per-billion volatile organic compound resolution sit at the apex of the price hierarchy. The dominant pricing structure stratifies across premium certified-intrinsically-safe tiers, standard multi-sensor configurations, and economy single-gas alternatives, with differentiation driven by ATEX certification grade and after-sales service bundling. Pricing pressure stems from electrochemical sensor supply concentration in East Asia, where specialty membrane manufacturing bottlenecks compress margins for assemblers without captive component sourcing. Mining operations and construction project contractors exhibit the highest price sensitivity, favoring rental arrangements and simplified single-gas units, whereas chemical processing facilities under EPA quarterly calibration mandates show lowest sensitivity due to compliance-driven procurement rigidity.
Supply Chain Analysis
Inventory cycles for electrochemical sensor cartridges stretch to sixteen weeks as specialty electrolyte and membrane production clusters in China, Japan, and South Korea absorb capacity constraints from REACH chemical authorization reformulations. Portable gas detection equipment draws from catalytic bead manufacturing in Germany, infrared source materials in the United States, and printed circuit board assembly across the Yangtze River Delta. Single-source vulnerability concentrates in East Asian specialty membrane suppliers, where just-in-time component flows face disruption from divergent national IECEx certification timelines. Distribution runs through captive fire-rescue channel networks in North America and manufacturer-direct service contracts in European process industries, with secondary industrial corridors in India and Saudi Arabia dependent on third-party calibration infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a defensive moat anchored in regulatory entrenchment: ATEX, IECEx, and OSHA certification requirements create switching costs that freeze out unqualified competitors and embed incumbents within buyer procurement workflows.
For Market Incumbents: Shield market position by deepening backward integration into electrochemical sensor component production, capturing margin pools currently absorbed by East Asian specialty membrane suppliers. Accelerate certification investment in emerging GB standards and MIIT wireless protocols to preempt Chinese manufacturer expansion into Southeast Asian export markets. Channel control through captive fire-rescue distribution networks remains the critical lever against direct-to-site subscription competitors.
For New Entrants and Emerging Players: Anchor in India's industrial safety modernization wave, where factory compliance deadlines under domestic occupational health frameworks accelerate first-time detector adoption without entrenched incumbent relationships. Target environmental monitoring applications in California and Massachusetts, where state-level volatile organic compound regulations outpace national standards and photoionization technology gaps persist. A calibration-service-first go-to-market angle bypasses capital-intensive hardware manufacturing while building sticky recurring revenue foundations.
For Investors and Strategic Acquirers: Capital is best deployed toward sensor-technology specialists with established ATEX-certified sub-supplier networks and documented REACH compliance documentation, as regulatory data-integrity requirements intensify across major industrial economies. Long-term viability over the coming decade hinges on wireless telemetry integration capabilities and predictive maintenance analytics platforms. The signal to watch is Bluetooth-to-mesh radio adoption rates in United States oil and gas operations, where capital discipline favors operational expenditure treatment and subscription contract penetration indicates structural procurement shift.
| Strategic Initiative | Industry Significance |
|---|---|
| Wireless Telemetry Integration | Bluetooth-to-mesh radio convergence opens subscription revenue streams for fleet management analytics. |
| Backward Integration | Captive electrochemical sensor production insulates margins from East Asian membrane supply bottlenecks. |
| Certification Investment | ATEX and IECEx pre-qualification accelerates revenue recognition across European and Middle Eastern export markets. |
| Localized Calibration Infrastructure | Houston and Jubail service hubs capture EPA and Saudi Aramco quarterly calibration mandates. |
| Sensor Modularity Platforms | Modular sensor cartridges reduce total cost of ownership as OSHA data-logging requirements intensify. |
Research Approach
The analysis maps multi-gas detector configurations, electrochemical and photoionization technology platforms, and confined space monitoring applications, each validated through safety equipment procurement managers, plant maintenance directors, and aftermarket service heads at oil and gas operators, chemical processing facilities, and mining operations. Primary interview intelligence triangulates against secondary sources including OSHA enforcement databases, EPA emissions monitoring filings, EU ATEX certification registries, and customs trade data for electrochemical sensor component flows. Bottom-up unit shipment estimates and top-down market value reconstructions cross-validate through manufacturer revenue disclosures and distributor channel audits.
Consistency checks against external benchmarks confirm analytical framework outputs across the projection horizon, with segmentation dimensions spanning product type, sensor technology chemistry, application environment, and end-user procurement sophistication. CAGRs derive from regression analysis of historical replacement cycles, regulatory enforcement intensity trajectories, and wireless telemetry adoption curves. Industry-specific forecast inputs incorporate MSHA enforcement patterns in Appalachian mining belts and EU Green Deal fugitive methane detection mandate implementation timelines.
Material uncertainties — electrochemical sensor supply disruptions, divergent national IECEx certification interpretations, and REACH electrolyte chemistry reformulation delays — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding OSHA confined space standard enforcement continuity and oil and gas capital expenditure discipline. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Household Smart Safe Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Respiratory Protection Equipment (RPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Hazardous Disposal Bag Market
Safety Equipment and Personal Protective Equipment (PPE)
Flu Protection Kits Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Safety and Eyewash Shower Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Process Safety Services Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Protective Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Face Shield Market
Safety Equipment and Personal Protective Equipment (PPE)
Asia-Pacific Fall Protection Market
Safety Equipment and Personal Protective Equipment (PPE)
Bicycle Safety Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Machine Safeguarding Solution Market
Safety Equipment and Personal Protective Equipment (PPE)
United States Safes and Vaults Market
Safety Equipment and Personal Protective Equipment (PPE)
Outdoor Safety Lock Market
Safety Equipment and Personal Protective Equipment (PPE)
Household Eye Protection Lamp Market
Safety Equipment and Personal Protective Equipment (PPE)
Industrial Protective Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Process Safety Services Market