
 Ethernet Test Equipment Market | 2026-2036
Ethernet Test Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Ethernet Test Equipment Market Analysis
400G-to-800G Ethernet migration is rewriting how test equipment architectures handle signal integrity and protocol validation at higher baud rates. Keysight Technologies leverages deep calibration IP for PAM4 modulation analysis across semiconductor and systems customers. Anritsu Corporation anchors its position through integrated bit-error-rate testers that span R&D through production environments. Spirent Communications differentiates via software-defined test platforms that scale from lab validation to live network emulation.
Ethernet test equipment comprises instruments that verify physical-layer signal integrity, measure packet-level throughput and latency, and validate compliance with IEEE 802.3 standards across copper and fiber media. These systems employ real-time oscilloscopes with bandwidth exceeding 100 GHz, pattern generators, and protocol analyzers to characterize jitter, eye diagrams, and forward-error-correction performance in multi-gigabit links. Packet Analyzers command the largest revenue share as network equipment manufacturers debug complex switch fabrics before deployment. Network Performance Monitors represent the fastest-expanding category because cloud operators require continuous visibility into east-west traffic patterns within virtualized data centers. Fiber Optic technology segments pull premium pricing due to the specialized optical-to-electrical conversion modules and precision alignment fixtures required for coherent DSP validation.
FCC equipment authorization rules shape how test vendors certify electromagnetic compatibility for instruments sold into US telecommunications infrastructure. ETSI and IEEE standards in Europe mandate interoperability testing that expands addressable demand for protocol-conformance systems. NIST traceability requirements for federal procurement channel revenue toward vendors with accredited calibration laboratories. Stakeholders must monitor how Open Compute Project specifications and Telecom Infra Project disaggregation initiatives redefine which test functions reside in hardware versus software.
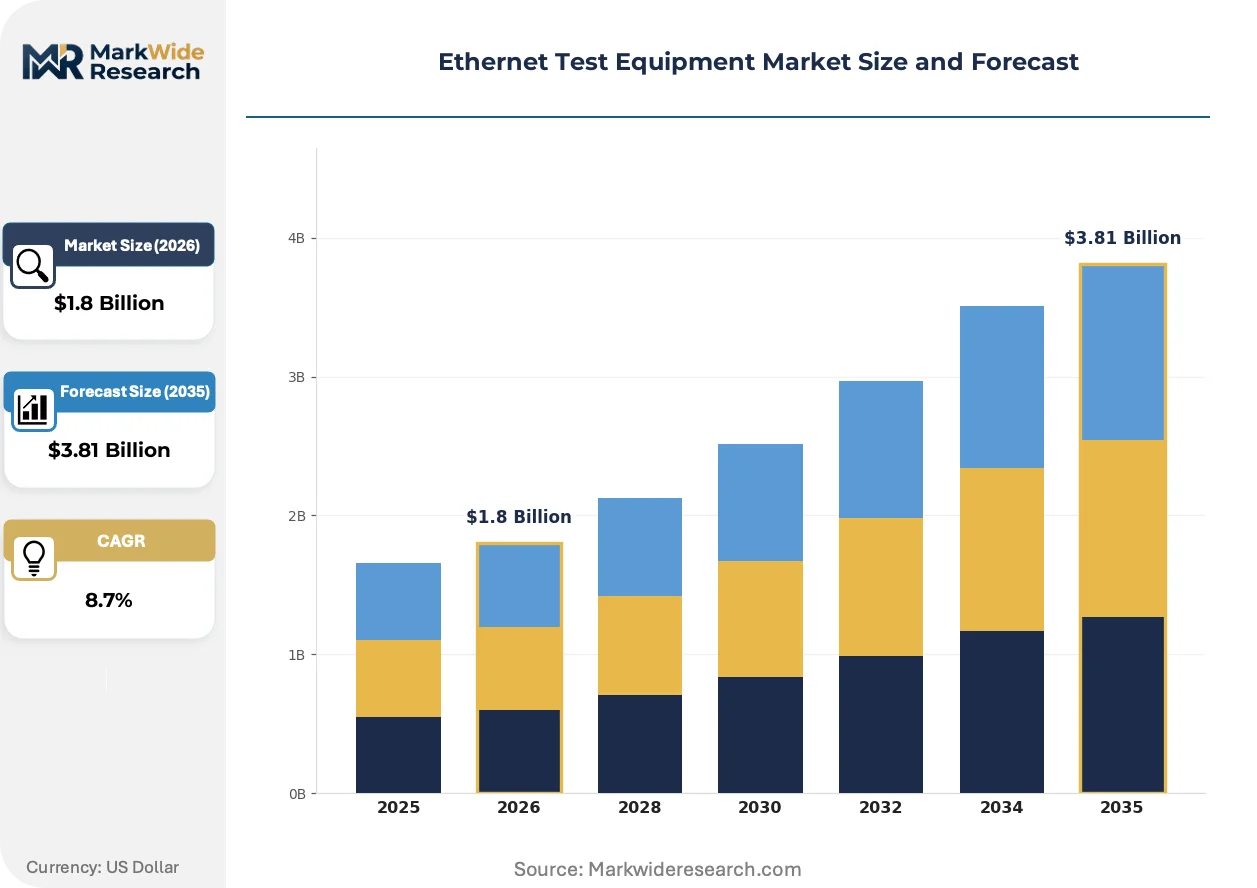
Market Dynamics
The migration from 400G to 800G and 1.6T Ethernet is collapsing traditional test equipment refresh cycles, forcing network equipment manufacturers and hyperscale operators to replace instruments before depreciation schedules complete.
Growth Catalysts
- IEEE 802.3ck standardization:The ratification of 800G electrical interfaces creates mandatory compliance testing demand across switch silicon vendors and cable assembly manufacturers.
- Hyperscale data center buildouts:United States cloud operators expanding carrier-neutral facilities in Northern Virginia and Dallas-Fort Worth are procuring multi-gigabit test systems in volume.
- China domestic cloud expansion:Baidu, Alibaba, and Tencent constructing proprietary data centers in Guizhou and Inner Mongolia are driving localized procurement of protocol analyzers.
Market Restraints
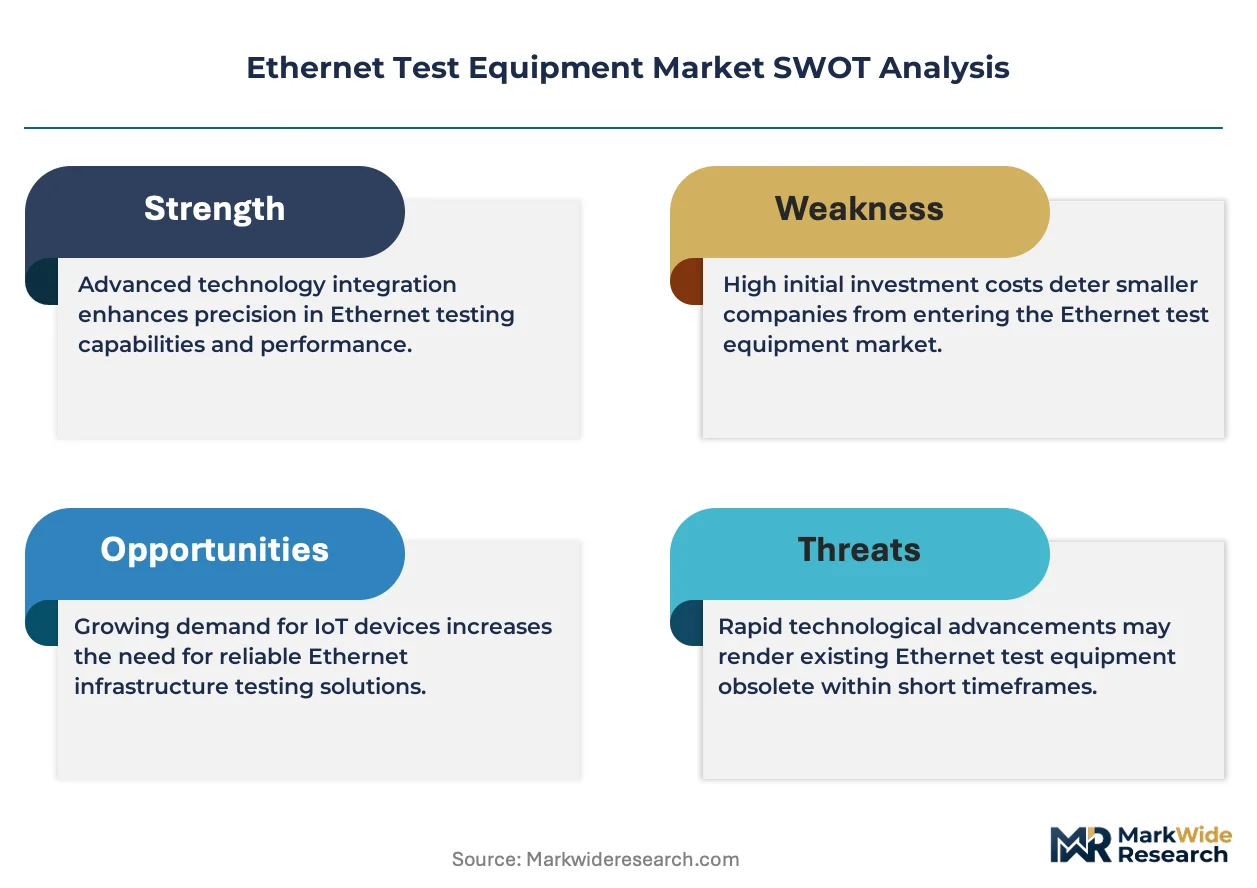
- Indium phosphide component scarcity:Specialized optical-to-electrical conversion modules for coherent DSP validation face supply concentration from Japanese and Taiwanese foundries.
- Capital intensity of 100+ GHz oscilloscopes:Real-time bandwidth expansion requires semiconductor probe stations costing multiples of legacy 50 GHz systems.
- FCC equipment authorization complexity:Electromagnetic compatibility certification timelines for instruments sold into US telecommunications infrastructure extend 6-12 months beyond historical norms.
Strategic Opportunities
- India data center emergence:Navi Mumbai and Chennai hyperscale clusters under construction by domestic and foreign operators represent underpenetrated demand for packet-level validation systems.
- Open Compute Project disaggregation:Hardware-software decoupling in switch architectures creates white space for software-defined test platforms that emulate disaggregated network functions.
- EU Green Deal alignment:Energy efficiency mandates for network infrastructure create certification-driven demand for power consumption validation during active traffic testing.
Industry Challenges
- PAM4 signal integrity expertise gap:The transition from NRZ to PAM4 modulation schemes requires analog designers capable of jitter decomposition at 56+ Gbaud, a skill set concentrated among semiconductor veterans.
- Multi-vendor interoperability certification:Forward-error-correction validation across switch ASICs from different suppliers demands test houses maintain expensive reference platform libraries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ethernet Test Equipment Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Packet Analyzers, Cable Testers, Network Performance Monitors, Tap Devices Application: Data Communication, Telecommunications, Network Security, Quality Assurance End User: Telecom Companies, Data Centers, Managed Service Providers, Enterprises Technology: Fiber Optic, Copper, Wireless, Multi-Gigabit |
| Companies Covered | Keysight Technologies, Anritsu Corporation, Spirent Communications, EXFO Inc., VIAVI Solutions Inc., Teledyne LeCroy, Rohde & Schwarz, Yokogawa Electric Corporation, VeEX Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ethernet Test Equipment Market Emerging Trajectories
Test instrumentation architectures are fragmenting along hardware-software boundaries as disaggregation initiatives redefine which validation functions require dedicated physical layer equipment versus virtualized emulation.
Real-time oscilloscope bandwidth expansion is collapsing the distinction between R&D characterization and production test. Instruments exceeding 100 GHz now serve both silicon bring-up and high-volume cable assembly screening. Keysight and Tektronix customers in switch ASIC design are compressing two previously separate capital equipment budgets into single procurement decisions.
ETSI interoperability mandates in Europe are forcing protocol conformance investments that exceed North American requirements. Network equipment manufacturers selling into Deutsche Telekom and Orange must maintain accredited test houses for IEEE 802.3 clause-by-clause validation. This regulatory friction is diverting engineering resources from feature development toward compliance documentation.
Cloud operators are unbundling after-sales calibration contracts from initial equipment purchases. Amazon Web Services and Microsoft Azure procurement teams now negotiate separate multi-year service agreements with third-party metrology providers accredited to NIST traceability standards. This behavioral shift is compressing vendor margins on initial system sales while expanding addressable revenue for independent calibration laboratories in Oregon and Bavaria.
Ethernet Test Equipment Market Segmentation
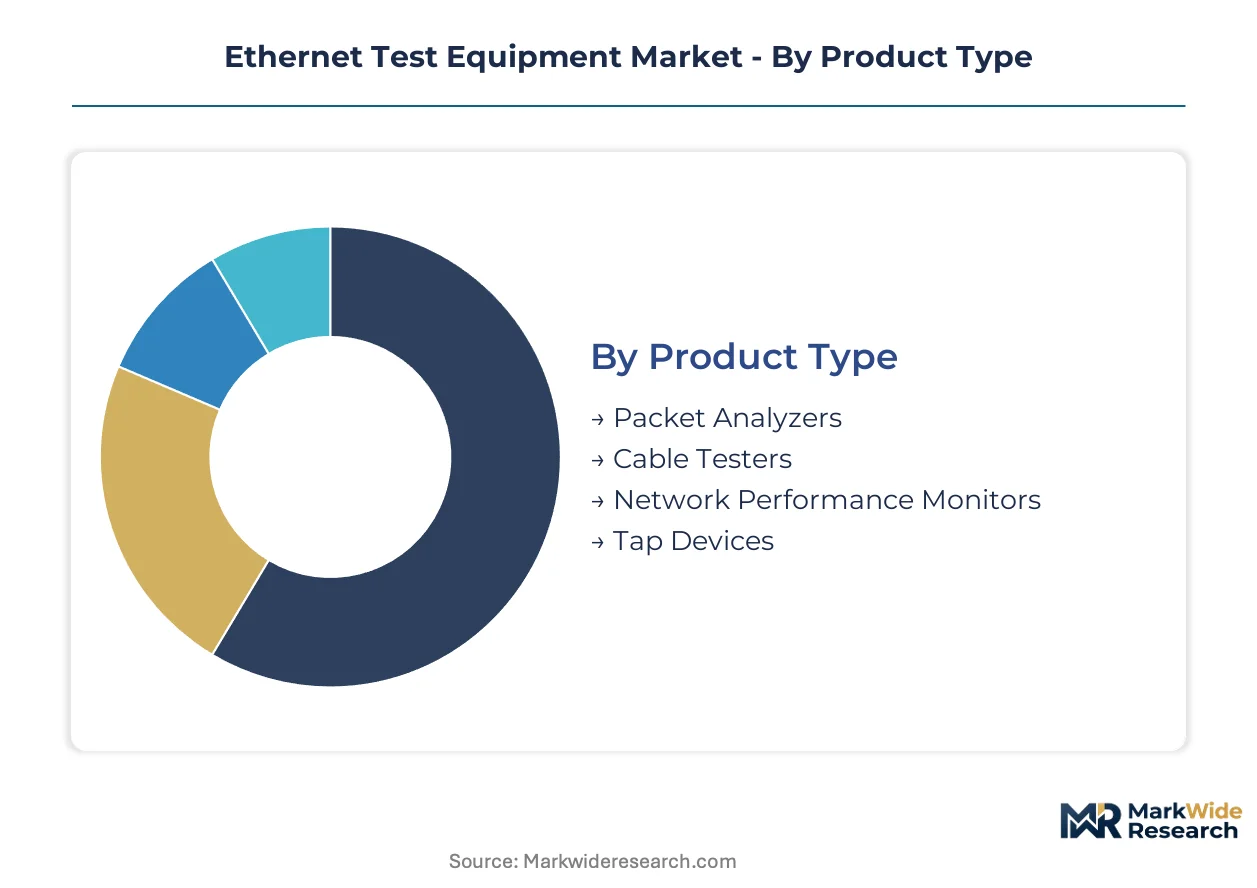
Ethernet test equipment segments reflect divergent technology maturity across physical layer validation, protocol analysis, and network performance monitoring. Each category carries distinct procurement patterns, pricing architectures, and replacement cycles that shape vendor positioning strategies.
Product Type:
Mature instrumentation categories coexist with emerging software-defined platforms in this segmentation, reflecting the market's transition from hardware-centric to virtualized validation architectures.
- Packet Analyzers:Deep-packet inspection systems decode protocol headers at line rate to diagnose switch fabric congestion and forwarding anomalies. Network equipment manufacturers in the United States deploy these for pre-deployment debugging of 400G and 800G switch ASICs. IEEE 802.3ck compliance mandates sustain replacement demand even amid budget compression.
- Network Performance Monitors:Continuous traffic visibility platforms measure east-west latency and throughput within virtualized data center fabrics. Hyperscale operators in Northern Virginia and Dallas-Fort Worth procure these in volume to monitor carrier-neutral facility interconnects. Cloud-native observability requirements displace traditional SNMP polling architectures.
- Cable Testers:Handheld or rack-mounted instruments verify copper and fiber assembly continuity, insertion loss, and crosstalk.
- Tap Devices:Passive optical or electrical splitters enable non-intrusive traffic monitoring without introducing probe-induced latency.
Packet Analyzers retain volume leadership; Network Performance Monitors hold the steepest expansion curve.
Application:
Application segments stratify by regulatory intensity, with compliance-driven procurement in telecommunications contrasting against performance-optimized purchasing in data communications.
- Data Communication:Switch and router validation for hyperscale data centers demands multi-gigabit throughput testing with PAM4 signal integrity analysis. Cloud operators in China expanding facilities in Guizhou and Inner Mongolia drive localized procurement of high-baud-rate test systems. IEEE 802.3 standards evolution forces equipment refresh ahead of depreciation schedules.
- Telecommunications:Carrier network certification requires protocol conformance validation against ETSI and IEEE interoperability mandates. Equipment sold into Deutsche Telekom and Orange networks must pass clause-by-clause IEEE 802.3 validation at accredited test houses. This regulatory friction diverts engineering resources toward compliance documentation.
- Network Security:Penetration testing and traffic anomaly detection applications employ test equipment to simulate attack vectors and validate firewall throughput under load.
- Quality Assurance:Manufacturing test environments screen cable assemblies and transceivers for parametric compliance before shipment.
Data Communication commands the largest revenue base; Network Security is climbing the fastest.
End User:
End user categories separate by capital deployment scale, with hyperscale data centers operating on compressed procurement cycles compared to enterprise IT departments.
- Data Centers:Hyperscale and colocation facilities validate optical interconnects and switch fabrics at 400G, 800G, and emerging 1.6T line rates. Amazon Web Services and Microsoft Azure procurement teams unbundle calibration contracts from initial equipment purchases, compressing vendor margins. NIST traceability requirements channel revenue toward vendors with accredited metrology laboratories.
- Telecom Companies:Incumbent carriers and mobile network operators test radio access network fronthaul and core network Ethernet backhaul. FCC equipment authorization rules shape electromagnetic compatibility certification timelines for instruments deployed in US telecommunications infrastructure. These timelines extend six to twelve months beyond historical norms.
- Managed Service Providers:Outsourced network operations teams procure portable test equipment for customer premise troubleshooting and service activation.
- Enterprises:Corporate IT departments validate campus and branch office network upgrades with mid-range protocol analyzers and cable certification tools.
Data Centers retain volume leadership; Managed Service Providers hold the steepest expansion curve.
Technology:
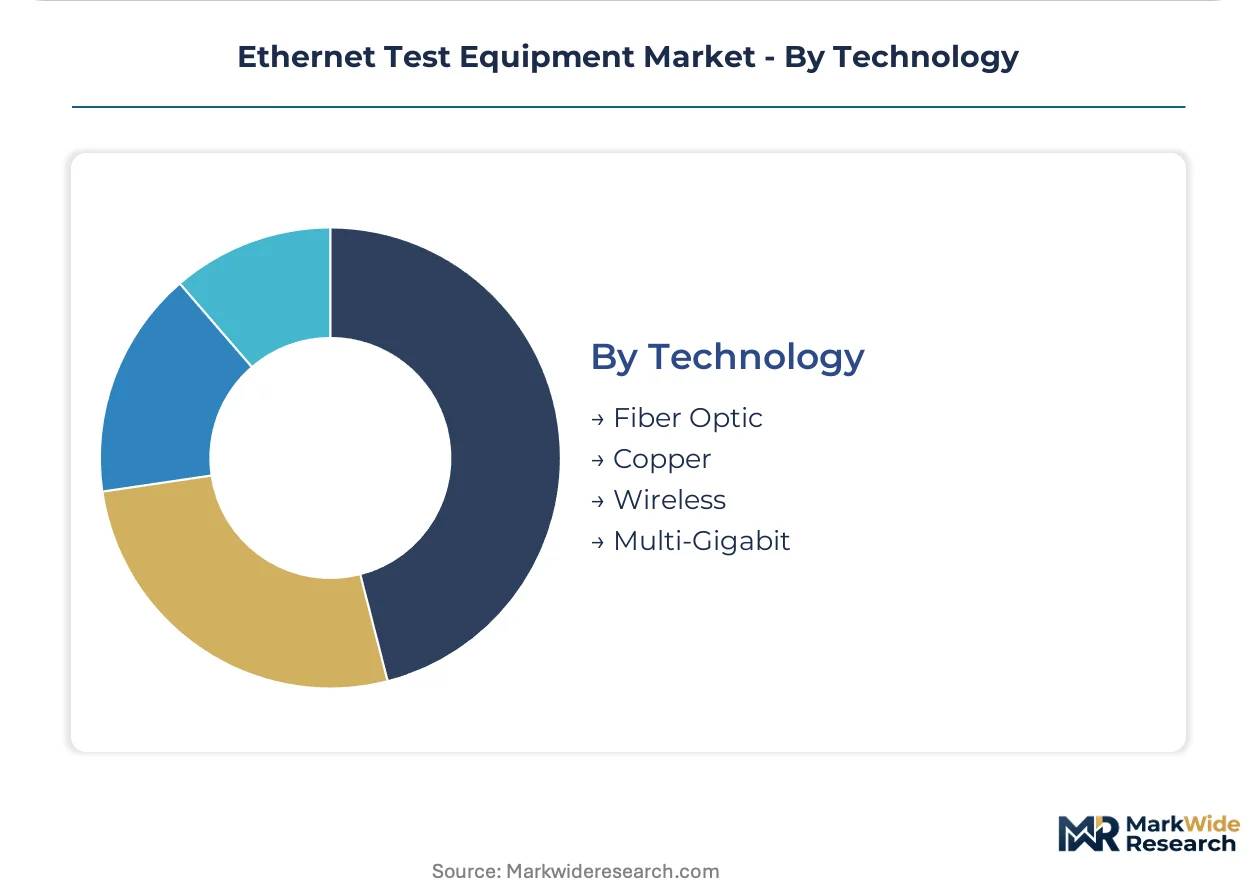
Technology segments diverge by component cost structure, with fiber optic systems requiring specialized optical-to-electrical conversion modules that face supply concentration from Japanese and Taiwanese foundries.
- Fiber Optic:Coherent DSP validation and optical-to-electrical conversion testing demand precision alignment fixtures and indium phosphide components. Indium phosphide scarcity from concentrated foundry supply creates procurement risk for test vendors. These systems command premium pricing due to specialized module requirements.
- Multi-Gigabit:Unified test platforms span 10G through 400G and 800G electrical interfaces with software-defined bandwidth scaling. Keysight Technologies and Anritsu Corporation compete on deep calibration IP for PAM4 modulation analysis. Real-time oscilloscope bandwidth expansion now serves both R&D characterization and production screening.
- Copper:Twisted-pair and twinax cable validation for short-reach data center interconnects and enterprise cabling.
- Wireless:Ethernet-over-wireless test applications for Wi-Fi 6/7 backhaul and private 5G network validation.
Fiber Optic retains volume leadership; Multi-Gigabit holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese and Taiwanese foundries export indium phosphide components to test equipment manufacturers in the United States and Germany, sustaining the optical-to-electrical conversion supply chain for coherent DSP validation systems.
United States
FCC equipment authorization rules extend electromagnetic compatibility certification timelines six to twelve months beyond historical norms for instruments deployed in telecommunications infrastructure. Hyperscale operators in Northern Virginia and Dallas-Fort Worth procure multi-gigabit test systems in volume for carrier-neutral facility expansion. NIST traceability requirements channel federal procurement toward vendors with accredited calibration laboratories.
China
Domestic cloud providers Baidu, Alibaba, and Tencent drive localized procurement of protocol analyzers for proprietary data centers in Guizhou and Inner Mongolia. MIIT standards for 800G electrical interfaces mandate compliance testing across switch silicon vendors and cable assembly manufacturers. Yangtze River Delta test houses maintain reference platform libraries for multi-vendor interoperability certification.
Germany
ETSI interoperability mandates force network equipment manufacturers to maintain accredited test houses for IEEE 802.3 clause-by-clause validation. Deutsche Telekom procurement requires protocol conformance documentation that diverts engineering resources from feature development. Bavarian calibration laboratories accredited to EU metrology standards capture unbundled service contracts from cloud operators.
Japan
METI industrial policy supports domestic foundry capacity for indium phosphide components used in coherent optical test modules. Specialized optical-to-electrical conversion faces supply concentration risk from concentrated semiconductor manufacturing. Tokyo-based test equipment vendors leverage deep calibration IP for PAM4 modulation analysis serving R&D and production environments.
India
Navi Mumbai and Chennai hyperscale clusters under construction by domestic and foreign operators represent underpenetrated demand for packet-level validation systems. TRAI infrastructure guidelines shape electromagnetic compatibility requirements for telecommunications equipment deployment. Maharashtra data center operators procure software-defined test platforms for east-west traffic monitoring within virtualized fabrics.
Ethernet Test Equipment Market Vendor Landscape
On the supply side, the industry is moderately consolidated around instrumentation specialists with deep calibration intellectual property and semiconductor probe station capabilities. Three strategic archetypes dominate: oscilloscope-centric measurement houses with bandwidth expansion roadmaps, software-defined test platform vendors, and optical component specialists with indium phosphide module expertise. Competitive moves concentrate on strategic partnerships for reference platform libraries and geographic expansion through accredited calibration laboratory networks.
Within the measurement instrumentation tier, Keysight Technologies and Anritsu Corporation exemplify archetypes built on deep calibration IP for signal integrity analysis. Spirent Communications occupies a position representing software-defined test platforms that scale from lab validation to live network emulation. These three anchors illustrate how vendor positioning stratifies between hardware-centric physical layer validation and virtualized emulation architectures.
| Leading Market Players |
|---|
| Keysight Technologies |
| Anritsu Corporation |
| Spirent Communications |
| EXFO Inc. |
| VIAVI Solutions Inc. |
| Teledyne LeCroy |
| Rohde & Schwarz |
| Yokogawa Electric Corporation |
| VeEX Inc. |
| Others |
Supply Flow & Price Mechanics
Undercapacity in Japanese indium phosphide foundries is compressing supplier margins while elevating pricing power for coherent optical module vendors serving 800G test equipment demand. This utilization squeeze forces test equipment manufacturers to absorb component premiums or pass costs to hyperscale buyers with limited alternative sourcing.
Pricing Analysis
800G-to-400G pricing gaps exceed three-to-one multiples as next-generation PAM4 modulation analysis demands 100+ GHz oscilloscope bandwidth that prior-generation NRZ systems cannot address. Three-tier pricing structure across premium calibration-bundled, standard warranty-included, and economy bare-metal tiers separates NIST-traceable systems from third-party calibrated alternatives. Pricing pressure stems from cloud procurement teams unbundling multi-year service contracts from initial capital purchases. Enterprise IT departments exhibit highest price sensitivity, while hyperscale operators prioritize specification compliance over unit cost.
Supply Chain Analysis
Tariff exposure between United States and China dominates supply chain risk planning for test equipment vendors assembling instruments from Asian component streams. Indium phosphide substrates draw from Japanese and Taiwanese foundries, precision alignment fixtures rest on German machining centers, and semiconductor probe stations hinge on South Korean capital equipment. Single-source vulnerability concentrates in coherent optical-to-electrical conversion modules. Distribution runs through direct sales teams for hyperscale accounts and authorized channel partners for enterprise segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating around hyperscale procurement teams at Amazon Web Services and Microsoft Azure, compressing vendor margins through unbundled calibration contracts and volume concentration.
For Market Incumbents: Build calibration IP moats through NIST-accredited laboratory networks in Oregon and Bavaria. Acquire specialized indium phosphide module suppliers to secure coherent DSP validation capacity. Invest in software-defined test platforms to counter emerging virtualized emulation entrants threatening hardware-centric revenue streams. For New Entrants and Emerging Players: Establish a beachhead in India's Navi Mumbai and Chennai hyperscale clusters where incumbent presence remains thin. Target software-defined network emulation for Open Compute Project disaggregated switch architectures. Pursue partnership-led go-to-market with regional system integrators lacking IEEE 802.3ck compliance expertise. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vendors with unbundled calibration service contracts and multi-year hyperscale maintenance agreements. Long-term viability favors test houses with accredited metrology infrastructure and reference platform libraries for multi-vendor interoperability certification. Acquisition targets should demonstrate PAM4 signal integrity expertise concentrated among semiconductor veterans. Monitor IEEE 802.3 standards ratification timelines as inflection indicators for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Laboratory Network Expansion | NIST-accredited facilities in Oregon and Bavaria capture unbundled service contracts from AWS and Azure procurement teams. |
| Software-Defined Test Platform Development | Virtualized emulation architectures address Open Compute Project disaggregation and compress R&D-to-production validation cycles. |
| Indium Phosphide Supply Integration | Backward integration into Japanese and Taiwanese foundry capacity mitigates component scarcity for coherent optical modules. |
| India Market Entry Partnership | Regional system integrators in Navi Mumbai and Chennai provide channel access to underpenetrated hyperscale construction activity. |
| ETSI Interoperability Certification Investment | Accredited test houses for Deutsche Telekom and Orange procurement requirements sustain European market access. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of IEEE 802.3 standards documentation, FCC equipment authorization filings, and hyperscaler capital expenditure disclosures. Primary interviews engaged test equipment R&D directors, hyperscale data center procurement managers, semiconductor probe station engineers, and accredited metrology laboratory operators. Secondary sources included ETSI interoperability mandate texts, NIST calibration procedure specifications, and Open Compute Project technical specifications. Bottom-up instrumentation shipment data triangulated against top-down capital expenditure modeling across cloud operator infrastructure budgets.
Forecast inputs encompass product type segmentation across packet analyzers and network performance monitors, technology tiers spanning fiber optic and multi-gigabit platforms, and end-user categories separating hyperscale data centers from enterprise IT departments. CAGRs derive from replacement cycle compression analysis tied to IEEE 802.3ck standardization timelines and PAM4 modulation adoption curves. Industry-specific inputs include indium phosphide foundry capacity utilization and cloud operator carrier-neutral facility construction pipelines.
Sensitivities concentrate around IEEE 802.3 standards ratification delays, indium phosphide foundry supply disruptions, and hyperscale procurement contract unbundling acceleration. Forecasts reflect assumptions regarding technology migration timelines and component supply stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Capacitance Meter Market
Test and Measurement
Global General Purpose Test Equipment (GPTE) Market
Test and Measurement
Global Bench Scale Market
Test and Measurement
Digital Moisture Meters Market
Test and Measurement
Online Weld Seam Quality Monitoring Test Systems for Steel Pipelines Market
Test and Measurement
Handheld Digital Multimeter Market
Test and Measurement
Radiation Tester Market
Test and Measurement
Surface Vision and Inspection Equipment Market
Test and Measurement
Voltage Calibrator Market
Test and Measurement
Global Reflux Testing Products Market
Test and Measurement
NIR Moisture Analyzers Sales Market
Test and Measurement
Whiteness Meter Market
Test and Measurement
Photometer and Calorimeter Market
Test and Measurement
Environmental Test Chambers Market
Test and Measurement
Flow Meter Calibration Market
Test and Measurement
Production Testing Market