
 Roughness Tester Market | 2026-2036
Roughness Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Roughness Tester Market Analytics
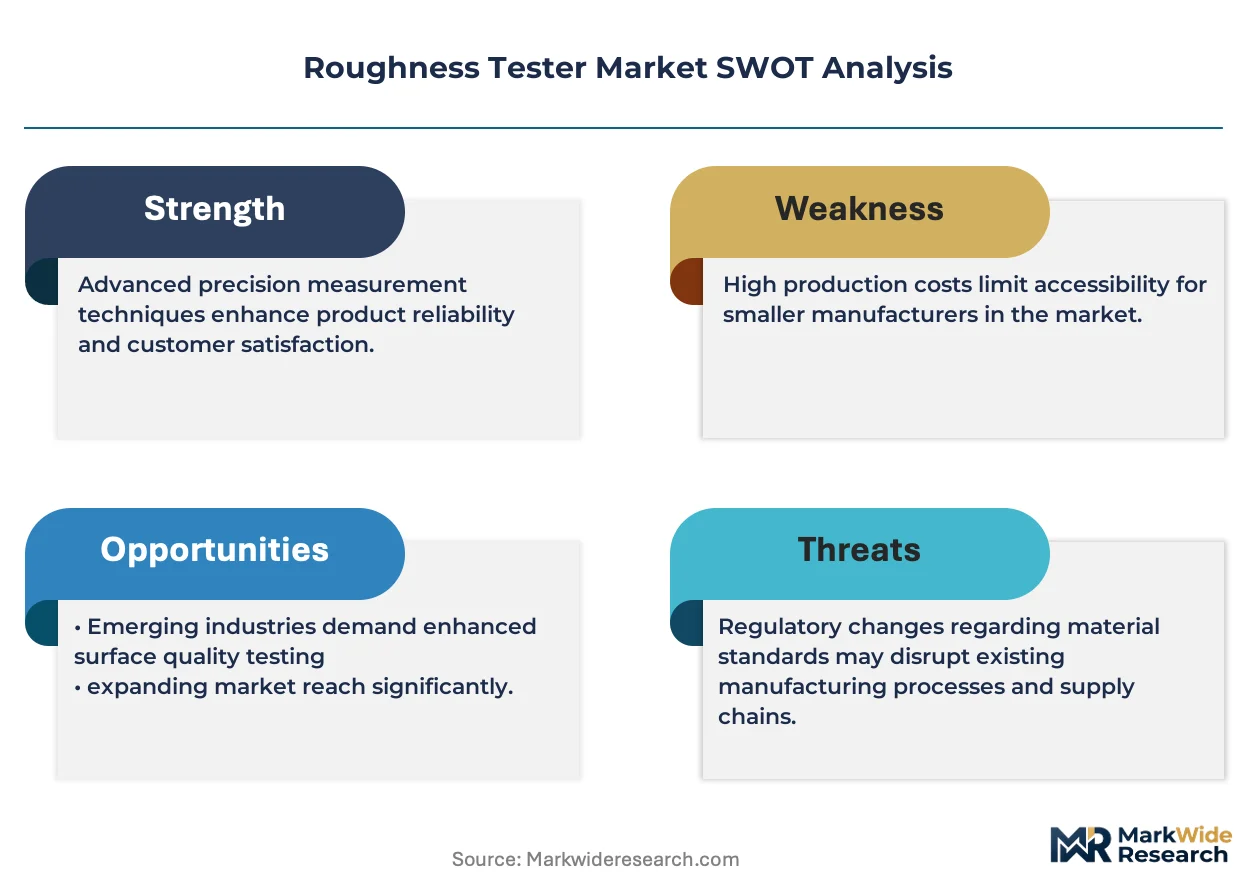
ISO 21920 surface texture standards are redrawing competitive boundaries for roughness tester suppliers. Mitutoyo Corporation leverages its JIS certification depth to anchor position in Asian manufacturing hubs. Taylor Hobson sustains dominance in optical interferometry through captive lens fabrication. Mahr GmbH differentiates via stylus profilometry systems calibrated to German automotive OEM protocols.
A roughness tester quantifies surface texture parameters including Ra, Rz, and Rq values through mechanical stylus contact or non-contact optical methods, serving quality verification across precision manufacturing. Non-contact roughness testers lead growth as semiconductor wafer and optical component producers reject stylus-induced surface damage. Stylus profilometry retains margin concentration in aerospace landing gear and crankshaft inspection where traceable mechanical contact remains mandatory. Portable roughness testers occupy expanding share in metal processing shops requiring shop-floor deployment without climate-controlled laboratory infrastructure.
ISO governs international surface texture measurement protocols while FDA enforces medical device finish requirements that shape tester specifications in orthopedic implant manufacturing. Germany's national metrology institute maintains primary roughness standards that propagate through PTB-traceable calibration chains. Stakeholders must monitor NIST's advancing research on areal surface topography standards to anticipate displacement of profile-based measurement architectures.
Market Dynamics
Optical interferometry is compressing stylus profilometry's installed base as semiconductor fabs and precision optics manufacturers eliminate contact-induced surface damage from quality protocols. This displacement is restructuring supplier revenue mixes and forcing calibration service networks to retool.
Growth Catalysts
- ISO 21920 implementation:Harmonized surface texture standards across European and Asian manufacturing hubs are mandating upgraded metrology equipment. Automotive tier-1 suppliers in Germany and Japan are replacing legacy testers to maintain OEM qualification status.
- Additive manufacturing post-processing:Metal 3D-printed components require validated surface finish verification before aerospace and medical device deployment. Roughness testers are becoming standard equipment in print-to-finish workflows.
- Electric vehicle drivetrain precision:Motor shaft and bearing surface specifications are tightening beyond legacy automotive tolerances. Chinese and South Korean battery gigafactories are embedding inline roughness inspection stations.
Market Restraints
- Helium supply concentration:Optical interferometry systems require helium-neon laser sources. Qatar and the United States control over 75% of global helium refining capacity, creating input cost volatility for non-contact instrument manufacturers.
- Stylus diamond tip supply:Single-crystal diamond indenters for contact profilometry concentrate in Russian and Belarusian processing facilities. Western sanctions are disrupting replacement part availability and calibration traceability.
- Reference standard scarcity:National metrology institutes in Germany, Japan, and the United States maintain limited stocks of certified roughness specimens. Lead times for PTB-traceable calibration artifacts now exceed 16 weeks.
Strategic Opportunities
- India precision manufacturing corridors:Tamil Nadu and Gujarat industrial zones are attracting medical device and aerospace component producers. BIS certification requirements for surface measurement equipment are creating first-mover advantages for suppliers establishing local calibration partnerships.
- AI-assisted surface classification:Machine learning algorithms trained on areal topography data are enabling predictive quality control. Convergence of optical sensors with edge computing platforms is opening subscription-based analytics revenue streams.
- Portable shop-floor deployment:Metal processing job shops in the United States Midwest are rejecting climate-controlled lab dependency. Battery-powered handheld units with wireless data transmission are penetrating small and mid-size machine shop segments.
Industry Challenges
- Areal topography skill gap:ISO 25178 surface texture standards require interpretation of 3D parameter sets beyond traditional 2D profile analysis. Metrology technicians trained in Ra-Rz-Rq fundamentals need retraining on Sa-Sz-Sq nomenclature and filtering protocols.
- Multi-sensor integration complexity:Hybrid systems combining tactile stylus and optical measurement modes require software harmonization. Aerospace OEMs are rejecting vendor-locked data formats that impede cross-platform quality database construction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Roughness Tester Market |
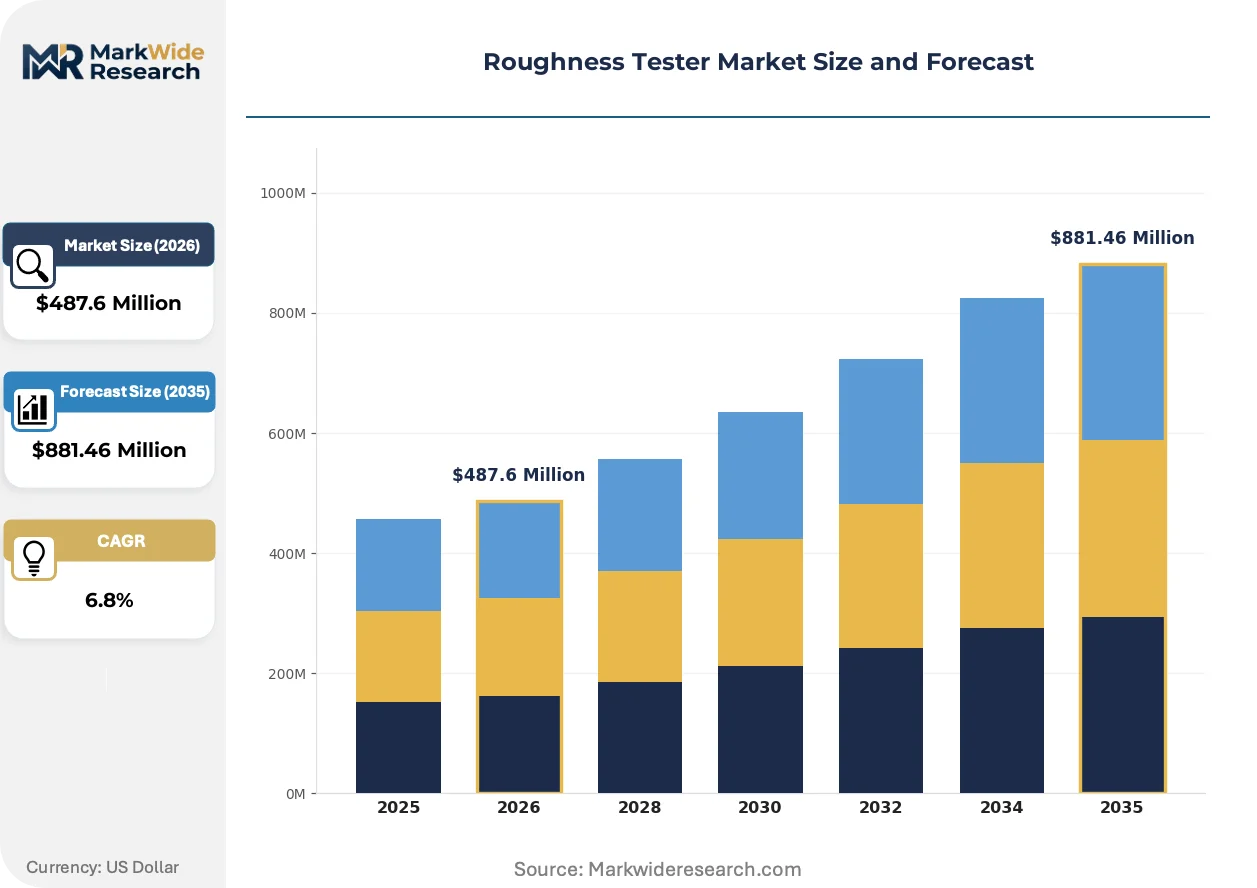
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Contact Roughness Testers, Non-Contact Roughness Testers, Portable Roughness Testers, Bench Top Roughness Testers Technology: Optical Measurement, Laser Scanning, Stylus Profilometry, Ultrasonic Testing End User: Aerospace, Automotive Manufacturing, Electronics, Metal Processing Usage Type: Laboratory Testing, On-Site Inspection, Quality Control, Research and Development |
| Companies Covered | Mitutoyo Corporation, Taylor Hobson, Mahr GmbH, Keyence Corporation, Carl Zeiss AG, Hexagon AB, Zeiss Group, Kosaka Laboratory, PCE Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Roughness Tester Market Evolving Landscape
Measurement architectures are bifurcating between high-throughput optical systems for delicate surfaces and ruggedized portable units for production-floor deployment. This divergence is fragmenting R&D budgets and reshaping service network requirements.
Confocal chromatic sensor technology is miniaturizing into probe formats compatible with coordinate measuring machine integration. Medical device manufacturers in Switzerland and Germany are embedding these sensors directly into automated orthopedic implant inspection cells. The form factor reduction is eliminating standalone roughness tester purchases for integrated quality stations.
REACH substance restrictions on hexavalent chromium plating are forcing automotive suppliers to validate alternative surface finishes. European coating applicators are investing in roughness measurement capability to document equivalence of trivalent chromium and thin-film dense chrome alternatives. German automotive OEMs are rewriting surface specification sheets to accommodate these material transitions.
Service contract unbundling is separating hardware ownership from calibration and software maintenance. Japanese precision manufacturers are purchasing instruments while outsourcing traceability verification to accredited third-party laboratories. This decoupling is compressing initial equipment margins while expanding recurring revenue pools for metrology service providers in Osaka and Nagoya industrial clusters.
Roughness Tester Market Segmentation
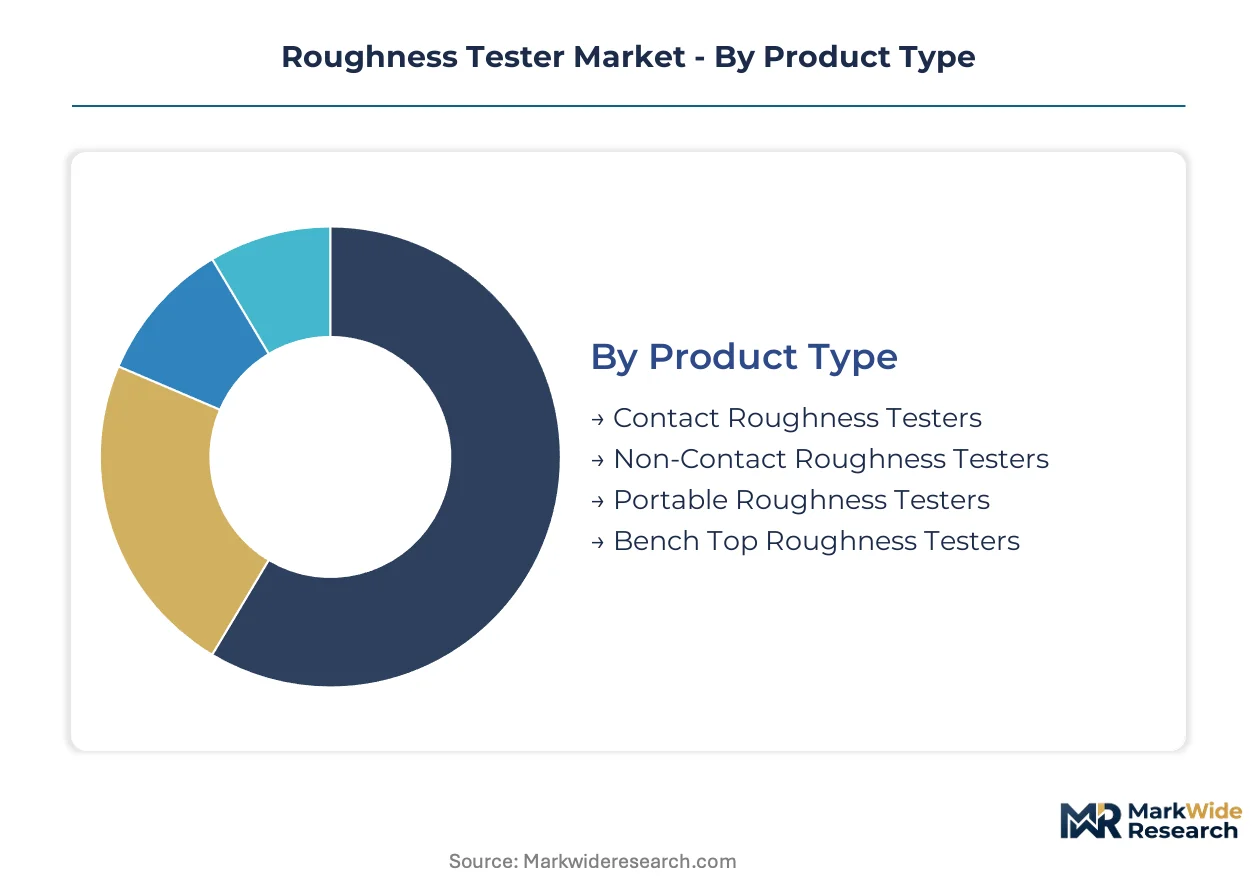
Roughness tester procurement patterns diverge sharply between export-oriented precision manufacturers and domestic metal processing shops. Segment boundaries are hardening as optical systems displace stylus methods in semiconductor and medical device corridors while portable units penetrate job-shop floors.
Product Type:
Contact roughness testers dominate German and Japanese domestic OEM supply chains, while non-contact systems flow disproportionately to export-led precision optics and semiconductor manufacturers in Taiwan and South Korea.
- Contact Roughness Testers:Mechanical stylus systems with diamond-tipped indenters trace surface profiles to quantify Ra, Rz, and Rq parameters. Aerospace landing gear and crankshaft inspection in the United States and Germany retain mandatory contact protocols for traceable mechanical verification.
- Non-Contact Roughness Testers:Optical interferometry and confocal chromatic sensors eliminate surface damage risk during measurement. Semiconductor wafer manufacturers in Hsinchu and optical component producers in Jena are eliminating stylus contact from quality protocols entirely.
- Portable Roughness Testers:Battery-powered handheld units with wireless data transmission serve Midwestern US metal job shops without climate-controlled laboratory infrastructure.
- Bench Top Roughness Testers:Climate-stabilized laboratory instruments anchor metrology departments at automotive tier-1 suppliers in Stuttgart and Toyota City.
Contact roughness testers hold the largest share; momentum sits with non-contact roughness testers.
Technology:
Cost tiers separate premium optical interferometry from mid-range laser scanning and economy stylus systems, with ultrasonic methods occupying niche penetration testing roles.
- Optical Measurement:White-light interferometry and confocal microscopy capture areal surface topography without physical contact. Swiss orthopedic implant manufacturers in Biel and Solothurn embed these sensors directly into automated inspection cells.
- Laser Scanning:Triangulation and confocal chromatic sensors enable high-speed line scanning for production-line integration. Chinese battery gigafactories in Ningbo and Shenzhen deploy laser scanning for inline motor shaft verification.
- Stylus Profilometry:Diamond-tipped mechanical tracing remains mandatory for aerospace traceability chains. Russian diamond processing disruptions are constraining tip supply for Western calibration laboratories.
- Ultrasonic Testing:Surface wave propagation methods assess subsurface integrity alongside roughness parameters. German railway wheel manufacturers employ ultrasonic roughness correlation for predictive maintenance scheduling.
Stylus profilometry retains the largest installed base; optical measurement is climbing the fastest.
End User:
Application requirements dictate sensor selection, with medical-adjacent electronics and aerospace demanding non-contact precision while metal processing tolerates ruggedized contact methods.
- Aerospace:Landing gear, turbine blade, and structural component inspection mandates traceable mechanical contact for FAA certification compliance. Boeing and Airbus supply chains in Wichita and Toulouse maintain stylus-based quality stations.
- Automotive Manufacturing:EV drivetrain components require tighter surface tolerances than legacy internal combustion systems. South Korean and Chinese battery producers are embedding inline roughness stations for motor shaft verification.
- Electronics:Semiconductor wafer and optical substrate producers reject any surface damage risk. Hsinchu Science Park fabs have completed transition to all-optical measurement protocols.
- Metal Processing:Job shops and primary metal processors prioritize shop-floor portability over laboratory precision. Midwestern US fabricators are adopting battery-powered handheld units for incoming material verification.
Automotive manufacturing holds the largest share; electronics is gaining share fastest.
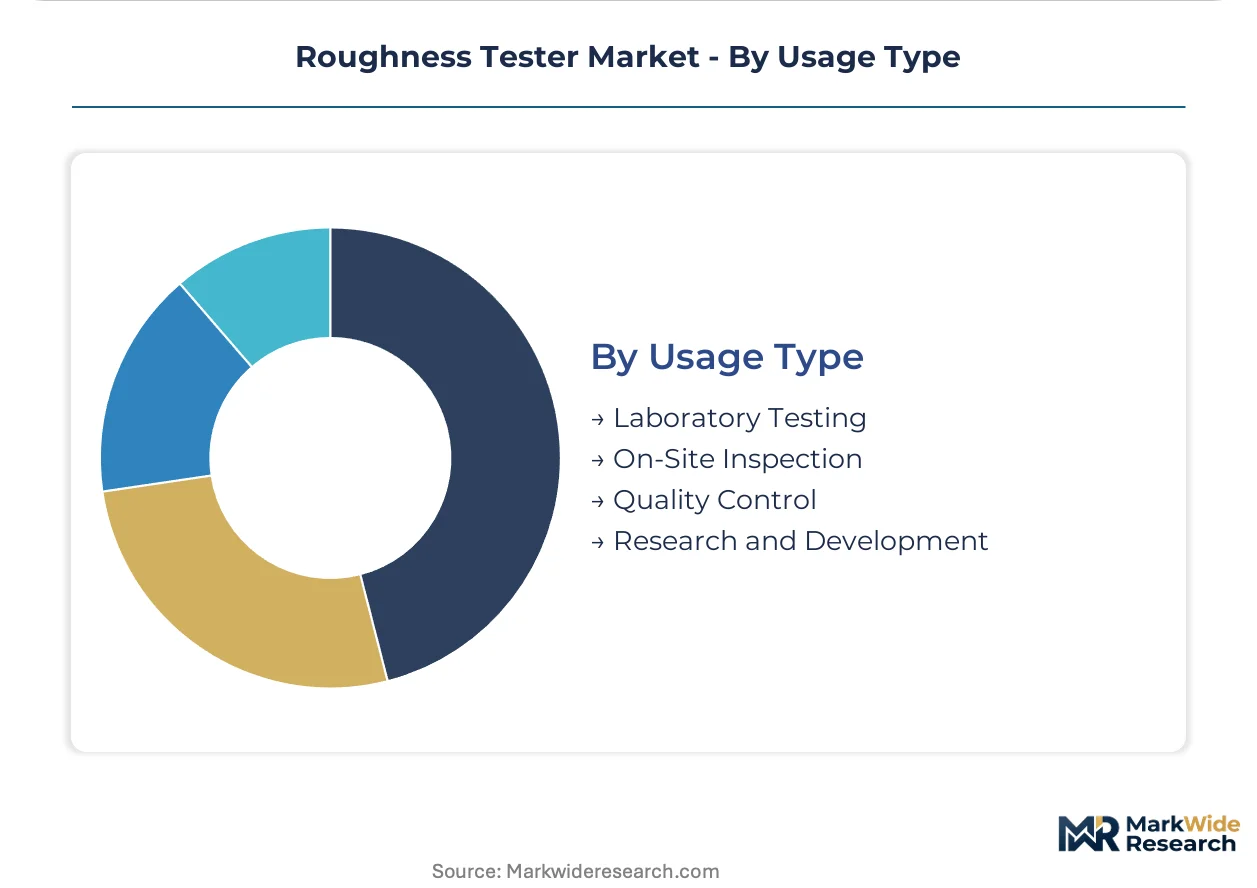
Usage Type:
Customer type stratification separates capital-intensive laboratory installations from operational expenditure-driven on-site deployment, with R&D representing discretionary budget exposure.
- Laboratory Testing:Climate-controlled metrology laboratories with vibration isolation and thermal stability anchor certification workflows. Germany's PTB-traceable calibration chains propagate through these facilities.
- On-Site Inspection:Production-floor deployment without environmental control demands ruggedized portable instrumentation. Japanese precision manufacturers in Osaka industrial clusters are unbundling hardware ownership from calibration services.
- Quality Control:Statistical process control integration requires automated data capture and MES connectivity. Automotive tier-1 suppliers are rejecting vendor-locked data formats that impede cross-platform quality databases.
- Research and Development:Areal topography method development and new surface finish validation occupy national metrology institutes and university laboratories. NIST's advancing research on ISO 25178 standards propagates through this segment.
Quality control holds the largest share; on-site inspection shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ISO 21920 harmonization is redirecting procurement budgets toward certified metrology equipment in precision manufacturing corridors. National metrology institutes in Germany, Japan, and the United States anchor calibration traceability chains that propagate through regional industrial clusters. Automotive electrification and semiconductor expansion are concentrating demand in specific metropolitan manufacturing zones.
United States
FAA certification mandates for aerospace landing gear sustain stylus-based inspection protocols at Wichita suppliers. NIST advancing research on areal surface topography standards is reshaping laboratory equipment specifications. Midwestern metal job shops in Ohio and Michigan are adopting battery-powered portable units for shop-floor deployment without climate control infrastructure.
Germany
Automotive OEM surface specification rewrites for hexavalent chromium alternatives are forcing coating applicators to invest in roughness verification capability. PTB-traceable calibration chains propagate through Stuttgart and Wolfsburg tier-1 supplier networks. Bavarian precision optics manufacturers in Jena are completing transitions to all-optical measurement protocols for delicate substrates.
Japan
JIS certification depth anchors metrology equipment procurement in Osaka and Nagoya industrial clusters. METI industrial standards harmonization is accelerating tester replacement cycles at precision manufacturers. Toyota City automotive suppliers are embedding inline roughness stations for EV drivetrain component verification.
China
Battery gigafactories in Ningbo and Shenzhen are deploying laser scanning systems for inline motor shaft surface verification. GB standards alignment with ISO 21920 is mandating equipment upgrades at export-oriented manufacturers. Yangtze River Delta semiconductor fabs are eliminating stylus contact from wafer quality protocols entirely.
India
BIS certification requirements for surface measurement equipment are creating first-mover advantages for suppliers establishing local calibration partnerships. Tamil Nadu and Gujarat medical device corridors are attracting orthopedic implant producers requiring validated finish verification. Precision manufacturing zones in Pune and Chennai are embedding roughness testers into print-to-finish additive manufacturing workflows.
Roughness Tester Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and captive manufacturing capability. The vendor base stratifies between optical interferometry specialists, stylus profilometry incumbents, and portable unit fabricators serving job-shop segments. Three archetypes dominate: integrated metrology conglomerates with captive lens fabrication, precision instrument specialists with JIS or PTB certification anchoring, and regional fabricators competing on service proximity. Competitive moves center on calibration network expansion and unbundled service contract structures separating hardware ownership from traceability verification.
Among Japanese precision instrument specialists, Mitutoyo Corporation and Kosaka Laboratory exemplify certification-anchored positioning in Asian manufacturing hubs. German metrology fabricators including Mahr GmbH occupy positions tied to automotive OEM protocol calibration. Taylor Hobson represents the optical interferometry archetype where captive lens manufacturing sustains measurement system differentiation.
| Leading Market Players |
|---|
| Mitutoyo Corporation |
| Taylor Hobson |
| Mahr GmbH |
| Keyence Corporation |
| Carl Zeiss AG |
| Hexagon AB |
| Zeiss Group |
| Kosaka Laboratory |
| PCE Instruments |
| Others |
Value Network & Pricing Analysis
Long-term calibration service contracts lock in both helium-neon laser source access and price visibility for optical interferometry manufacturers, insulating them from Qatar and United States helium refining concentration while exposing stylus profilometry suppliers to Russian diamond tip supply disruptions.
Pricing Analysis
Certification level (ISO/PTB/JIS-grade) creates the primary spread between premium optical systems and economy portable units. Three-tier pricing structure across premium, standard, and economy levels reflects traceability depth, with laboratory-grade interferometry commanding substantial premiums over shop-floor handheld devices. Cost compression in mid-range stylus profilometry is intensifying because Western sanctions constrain single-crystal diamond indenter replacement availability. Metal processing job shops in the United States Midwest exhibit highest price sensitivity, while German automotive tier-1 suppliers demonstrate lowest sensitivity due to OEM-mandated specification compliance.
Supply Chain Analysis
Helium refining concentration in Qatar and the United States underwrites optical interferometry laser source availability, while single-crystal diamond processing in Russian and Belarusian facilities anchors stylus profilometry tip supply. Critical inputs include helium-neon laser tubes, single-crystal diamond indenters, and PTB-traceable calibration artifacts. Single-source vulnerability in diamond tip supply chains threatens Western calibration laboratory operations. Distribution runs through accredited metrology service networks in Stuttgart, Osaka, and Nagoya industrial clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around ISO 21920 and national metrology institute traceability chains creates substantial defensive moats for established roughness tester suppliers, as automotive and aerospace OEMs resist switching costs associated with recalibrating quality protocols.
For Market Incumbents: Secure captive lens fabrication capabilities to sustain optical interferometry differentiation against emerging confocal chromatic sensor competitors. Deepen upstream control over helium-neon laser source inventories to mitigate Qatar supply concentration risk. Invest in AI-assisted surface classification software layers to capture recurring analytics revenue streams before platform entrants establish subscription footholds. For New Entrants and Emerging Players: Anchor in Tamil Nadu and Gujarat medical device corridors where BIS certification requirements create first-mover advantages for calibration service partnerships. Target portable roughness tester segments in Midwestern United States metal job shops rejecting climate-controlled laboratory dependency. Pursue unbundled hardware-ownership-plus-service-contract structures that Japanese precision manufacturers increasingly favor over capital-intensive equipment purchases. For Investors and Strategic Acquirers: Capital is best deployed toward optical interferometry specialists with captive manufacturing capabilities and established PTB/JIS/NIST calibration network access. The five-to-ten year viability window favors suppliers positioned for semiconductor wafer and EV drivetrain inspection demand expansion. Watch NIST areal surface topography standard advancement as the critical signal for displacement of profile-based measurement architectures and associated equipment obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Network Expansion | PTB-traceable service partnerships in Stuttgart and Wolfsburg secure automotive OEM qualification status. |
| Optical Sensor Miniaturization | Confocal chromatic probe formats enable CMM integration and eliminate standalone tester purchases. |
| AI-Assisted Surface Analytics | Machine learning algorithms trained on areal topography data open subscription revenue streams. |
| Helium Supply Diversification | Alternative laser source development reduces dependency on Qatar and United States refining concentration. |
| Portable Unit Ruggedization | Battery-powered handheld systems penetrate Midwestern US job shops without climate control infrastructure. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with metrology equipment procurement managers, calibration laboratory directors, and automotive tier-1 supplier quality engineers; and secondary validation through ISO standard documentation, PTB calibration artifact records, SEC filings of listed precision instrument manufacturers, and semiconductor fab capital expenditure disclosures. Bottom-up equipment shipment estimates triangulated against top-down manufacturing value-added projections across precision manufacturing corridors.
Across the projection horizon, the analytical framework modeled segmentation dimensions including product type (contact, non-contact, portable, bench-top), technology architecture (optical interferometry, laser scanning, stylus profilometry, ultrasonic), end-user industry (aerospace, automotive, electronics, metal processing), and usage context (laboratory, on-site inspection, quality control, R&D). CAGRs derived from equipment replacement cycle analysis, additive manufacturing adoption curves, and EV drivetrain surface specification tightening trajectories.
Material uncertainties — helium supply disruption, diamond tip trade restriction extension, and areal topography standard acceleration — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as NIST ISO 25178 research progresses and Western sanctions on Russian processing facilities evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Hour Meter Market
Test and Measurement
Optical Wafer Inspection Systems Market
Test and Measurement
Data Center Testing Market
Test and Measurement
LCR Meter Market
Test and Measurement
Gauss Meter Market
Test and Measurement
Electric Vehicle Edrive Test System Market
Test and Measurement
Calibration Services Market
Test and Measurement
Metrology Software Market
Test and Measurement
Test and Measurement Equipment Market
Test and Measurement
Test and Measurement Sensors Market
Test and Measurement
Scratch Testers Market
Test and Measurement
Industrial Metrology Market
Test and Measurement
Shape Measuring Devices Market
Test and Measurement
AI Inference Hardware Performance Benchmarking Test Systems Market
Test and Measurement
Digital Moisture Meters Market
Test and Measurement
Non-Destructive Testing (NDT) Software Market