
 Cigarette Market | 2026-2036
Cigarette Market Size, Share, and Industry Trends Forecast 2026-2036
Cigarette Market Intelligence
Buyer concentration among duty-free operators and airport retailers is pivoting toward fragmented online channels and convenience-store networks. Philip Morris International leverages heated-tobacco R&D intensity to offset traditional cigarette volume pressure. British American Tobacco anchors its position through manufacturing scale across Sub-Saharan Africa and Southeast Asia. China National Tobacco Corporation dominates its home market through state-mandated distribution control and captive leaf supply.
A cigarette is a cylindrical roll of cured tobacco leaf wrapped in paper, typically containing 10-12 mg of tar and 0.8-1.0 mg of nicotine per unit, designed for combustion inhalation and recreational nicotine delivery. Filtered products sustain the largest revenue pool globally, though menthol variants face accelerating regulatory pressure from the FDA and EU flavor bans. The duty-free channel retains premium margin concentration despite travel-volume volatility, while retail stores occupy the dominant volume position across emerging markets. Online distribution competes for share where regulatory frameworks permit direct-to-consumer sales.
The FDA enforces premarket authorization under the Family Smoking Prevention and Tobacco Control Act, while the WHO Framework Convention on Tobacco Control mandates packaging and advertising restrictions across ratifying nations. The EU Tobacco Products Directive and FCTC compliance requirements shape product standards, warning-label mandates, and cross-border trade access. Stakeholders must monitor evolving heat-not-burn classification debates and synthetic nicotine regulatory gaps to anticipate portfolio-restructuring decisions.
Market Dynamics
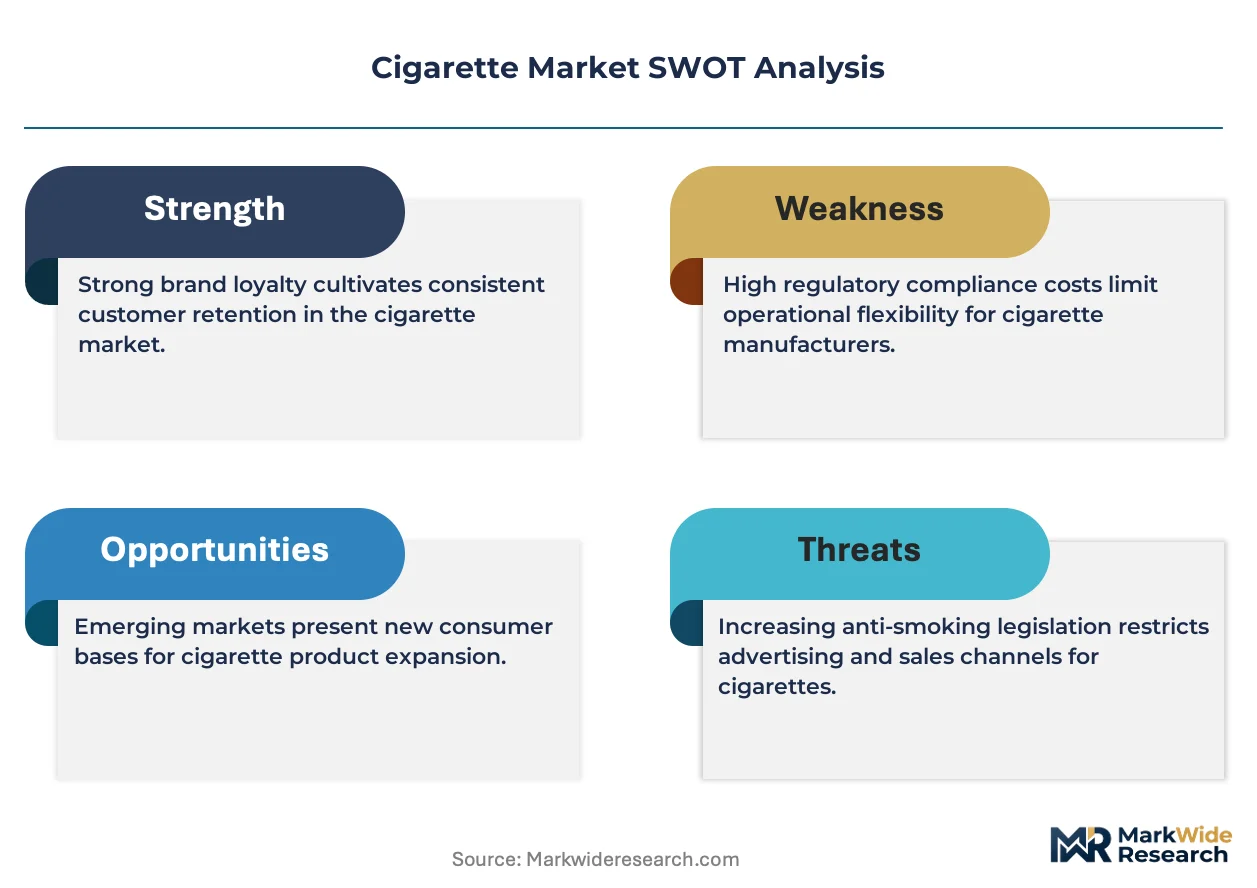
Heat-not-burn technology and synthetic nicotine classification debates are fragmenting regulatory frameworks faster than incumbents can restructure portfolios, forcing simultaneous investment in combustion alternatives and legal defense of legacy formats.
Growth Catalysts
- Adult smoker retention in emerging economies:Volume consumption persists in markets where enforcement of WHO Framework Convention on Tobacco Control packaging mandates remains uneven.
- Heated-tobacco R&D pipelines:Product development intensity targets smokers seeking reduced-risk perception without full cessation.
- Duty-free channel margin concentration:Airport retailers capture premium pricing power from transient high-income buyers.
Market Restraints
- Leaf supply concentration:Tobacco cultivation concentrates in subtropical belts vulnerable to climate volatility and water access disputes.
- FDA premarket authorization timelines:The Family Smoking Prevention and Tobacco Control Act creates multi-year product approval bottlenecks.
- Flavor prohibition expansion:EU menthol bans and FDA enforcement against characterizing flavors eliminate differentiation tools.
Strategic Opportunities
- Sub-Saharan Africa distribution gaps:Underdeveloped retail infrastructure in Nigeria and Kenya offers first-mover network advantages.
- Synthetic nicotine regulatory arbitrage:Jurisdictional classification uncertainty creates temporary product positioning windows.
- Convenience-store channel expansion:Urban proximity retail formats capture impulse purchase frequency in Southeast Asian megacities.
Industry Challenges
- Heat-not-burn manufacturing retooling:Combustion-optimized production lines require capital-intensive conversion for reduced-risk device assembly.
- Cross-border tax enforcement:Illicit trade detection capabilities lag behind e-commerce and postal distribution innovations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cigarette Market |
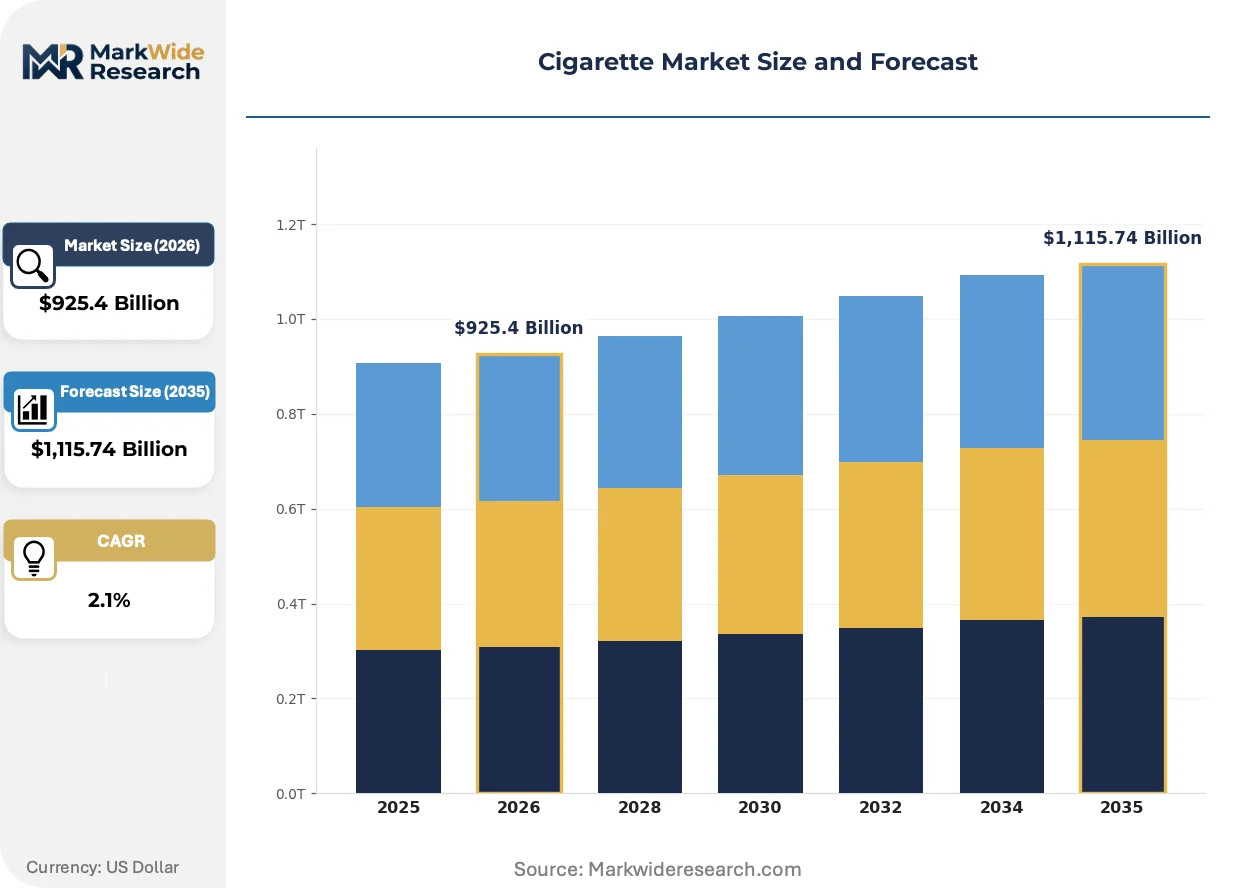
| Market Size in 2026 | $925.4 Billion |
| Market Size in 2035 | $1,115.74 Billion |
| CAGR (2026 – 2036) | 2.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filtered, Unfiltered, Menthol, Light End User: Adult Smokers, Young Adults, Quitters, Occasional Smokers Distribution Channel: Retail Stores, Online, Vending Machines, Duty-Free Packing Type: Packs, Cartons, Tins, Loose |
| Companies Covered | Japan Tobacco, Inc., Imperial Brands plc, Philip Morris International Inc., KT&G Corporation, China National Tobacco Corporation, British American Tobacco plc, ITC Limited, Smoore International Holdings Ltd, Altria Group, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cigarette Market Strategic Shifts & Innovations
Product format diversification and channel digitization are splitting the traditional cigarette value chain into modular components, with nicotine delivery separating from combustion infrastructure and retail access fragmenting across physical and virtual touchpoints.
Heated-tobacco devices are decentralizing nicotine consumption from fixed smoking locations to workplace and domestic environments previously restricted by secondhand smoke regulations. Early adopters in Japanese and South Korean urban centers demonstrate daily-use substitution rates that compress traditional cigarette occasion frequency. The technology is decentralizing consumption occasion control away from social ritual toward individual dosing precision.
The EU Tobacco Products Directive's track-and-trace serialization mandates are forcing supply chain transparency investments that reshape cost structures for mid-tier manufacturers. Implementation deadlines in Germany and France require hardware and software integration that smaller exporters struggle to fund. Filtered and capsule-variant producers face the steepest compliance cost escalation as batch-level authentication becomes mandatory.
Airport retail dependence is collapsing as post-pandemic business travel recovery lags leisure volume, forcing brand portfolios toward domestic convenience and online channels where permissible. Duty-free operators in Dubai and Singapore are renegotiating slotting fees as passenger mix shifts toward price-sensitive leisure segments. China and Indonesia demonstrate the strongest channel rotation momentum, with provincial e-commerce platforms capturing share from traditional tobacco monopoly retail.
Cigarette Market Segmentation
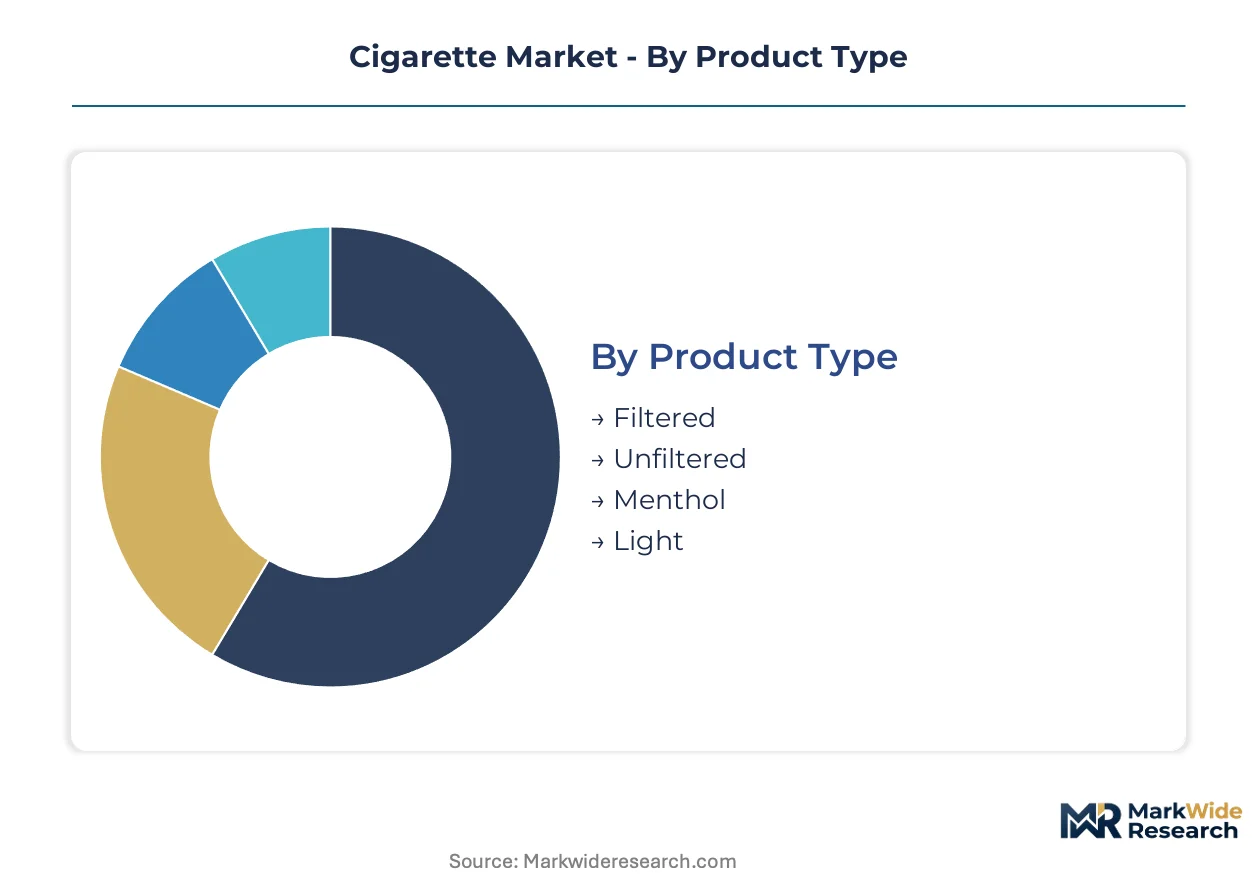
Cigarette manufacturers structure portfolios around combustion specifications, nicotine delivery preferences, and channel access constraints. Segmentation decisions determine regulatory exposure, tax liability, and manufacturing asset allocation across global markets.
Product Type:
Buyer differentiation hinges on tar content tolerance, flavor preference, and perceived health risk mitigation.
- Filtered:Cellulose acetate or charcoal filtration reduces particulate matter intake by approximately 30-50% versus unfiltered alternatives. Demand concentrates in the European Union and North America where the EU Tobacco Products Directive mandates maximum tar yields and Germany enforces strict emissions testing protocols.
- Menthol:Crystallized menthol or synthetic analogs create cooling sensations that mask throat irritation and extend inhalation depth. Regulatory pressure from the FDA's flavor enforcement priorities and EU-wide prohibitions are compressing manufacturing volumes in jurisdictions with active bans while sustaining demand in Asia-Pacific markets where flavor restrictions remain unenforced.
- Unfiltered:Traditional paper-wrapped tobacco without filtration retains highest tar and nicotine delivery per unit. Russia and parts of Eastern Europe sustain volume concentration among price-sensitive smokers seeking maximum nicotine efficiency.
- Light:Ventilated filters and expanded tobacco reduce machine-measured yields, though compensatory smoking behavior often negates intended exposure reduction. Japan and South Korea demonstrate declining per-capita consumption as heated-tobacco alternatives capture occasion migration.
Volume sits with Filtered; growth tilts toward heated-tobacco hybrids that occupy regulatory gray zones between combustion and reduced-risk categories.
End User:
Consumption frequency and cessation intent separate addressable populations from declining cohorts.
- Adult Smokers:Daily users over legal age thresholds consuming ten or more units daily represent the core revenue base. China and Indonesia anchor global volume through state-controlled distribution networks and deep rural penetration where WHO Framework Convention on Tobacco Control packaging mandates face implementation gaps.
- Young Adults:Consumers aged 18-25 demonstrate highest brand-switching elasticity and social-occasion-driven purchase patterns. Brazil and Nigeria exhibit expanding cohorts where marketing restrictions lag population growth and urbanization rates.
- Quitters:Former daily smokers attempting cessation through nicotine replacement or gradual reduction. Pharmaceutical nicotine competitors and behavioral intervention apps capture expenditure that previously flowed to combustible products.
- Occasional Smokers:Non-daily consumers motivated by social ritual rather than physical dependency. Premium positioning and limited-edition packaging sustain margin extraction despite low purchase frequency.
Revenue concentrates with Adult Smokers; portfolio investment shifts toward Young Adults in markets with favorable demographic trajectories.
Distribution Channel:
Channel selection determines tax compliance burden, age-verification enforcement, and margin capture mechanics.
- Retail Stores:Licensed tobacco shops, convenience stores, and supermarkets with point-of-sale display restrictions. Southeast Asian megacities demonstrate channel densification as urban proximity retail formats capture impulse purchase frequency.
- Duty-Free:Airport and border retail exempt from domestic excise taxation, historically capturing premium pricing from business travelers. Dubai and Singapore operators renegotiate slotting fees as passenger mix shifts toward price-sensitive leisure segments and post-pandemic business travel recovery lags.
- Online:Direct-to-consumer and marketplace sales where jurisdictional frameworks permit age verification and excise collection. Provincial e-commerce platforms in China capture share from traditional tobacco monopoly retail through delivery convenience.
- Vending Machines:Automated dispensing with token or card-based age verification, concentrated in Japan and select European markets with robust compliance infrastructure.
Volume dominance remains with Retail Stores; margin expansion targets Duty-Free recovery and Online penetration where regulatory arbitrage permits.
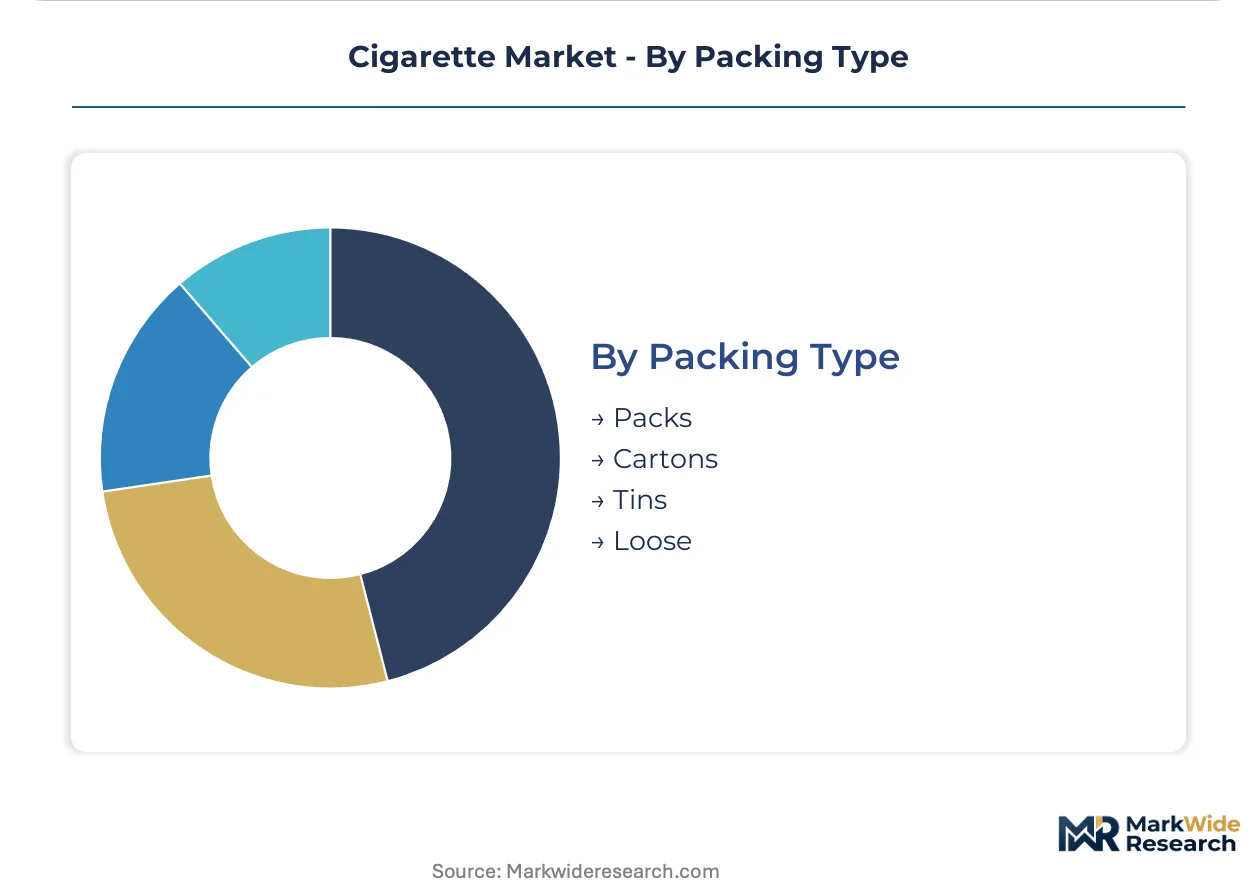
Packing Type:
Packaging format influences consumption occasion control, tax stamp application, and supply chain handling economics.
- Packs:Standard twenty-unit paperboard containers with mandated health warnings and track-and-trace serialization. EU Tobacco Products Directive implementation in Germany and France requires batch-level authentication hardware that reshapes cost structures for mid-tier manufacturers.
- Cartons:Ten-pack aggregations for volume purchasers and wholesale distribution. Price-sensitive smokers in emerging economies favor carton purchasing to minimize per-unit excise incidence.
- Tins:Metal or rigid plastic containers for loose tobacco or specialty formats, concentrated in Scandinavian and Middle Eastern markets with moisture-preservation requirements.
- Loose:Bulk tobacco for hand-rolling or pipe use, subject to differential taxation in jurisdictions distinguishing manufactured from non-manufactured products.
Unit economics favor Packs for manufacturer margin; Cartons expand most quickly in markets with excise escalation driving bulk purchasing behavior.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates over two-fifths of global cigarette consumption through state-controlled distribution networks and deep rural penetration. Volume retention in emerging economies contrasts with structural decline across Western markets where regulatory enforcement tightens.
China
China National Tobacco Corporation maintains vertical control over cultivation, manufacturing, and retail through provincial monopoly networks. The State Tobacco Monopoly Administration enforces production quotas and price controls that insulate domestic volume from international trade pressures. Hunan and Yunnan provinces anchor leaf cultivation and manufacturing clusters where state-directed investment sustains capacity expansion.
United States
Adult smoker retention concentrates in rural and lower-income demographics where menthol variants sustain brand loyalty despite FDA flavor enforcement priorities. The Family Smoking Prevention and Tobacco Control Act mandates premarket authorization timelines that compress new product introduction cycles. North Carolina and Kentucky maintain tobacco belt cultivation concentration though manufacturing employment migrates toward reduced-risk device assembly.
Indonesia
Kretek cigarette consumption persists among adult smokers where clove-flavored products retain cultural occasion dominance and limited WHO Framework Convention on Tobacco Control packaging enforcement. The national excise tax structure favors hand-rolled production over machine-made alternatives. Java island concentrates manufacturing in Surabaya and Malang where family-owned kretek houses supply domestic and regional export markets.
Germany
Filtered cigarette demand concentrates among older adult cohorts while heated-tobacco adoption accelerates in urban centers seeking reduced-risk alternatives. The EU Tobacco Products Directive mandates track-and-trace serialization that elevates compliance costs for mid-tier importers. Bavaria and Baden-Württemberg host distribution hubs where wholesale concentration faces margin pressure from cross-border e-commerce arbitrage.
Brazil
Young adult smoker cohorts expand in São Paulo and Rio de Janeiro metropolitan areas where marketing restrictions lag population growth and urbanization rates. ANVISA enforces advertising limitations that channel competition toward point-of-sale display and packaging differentiation. The southern states of Rio Grande do Sul and Santa Catarina sustain leaf cultivation concentration for export-oriented processing.
Cigarette Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue heated-tobacco and synthetic nicotine positioning outside combustion-centric portfolios. The market consolidates around state-controlled national champions and multinational tobacco conglomerates with manufacturing scale across multiple continents. Three archetypes dominate: vertically integrated state monopolies with captive distribution, multinational reduced-risk innovators with R&D-intensive pipelines, and regional leaf-integrated specialists with export processing advantages. Competitive moves center on portfolio diversification toward non-combustion formats and geographic expansion into underenforced emerging markets.
Within the multinational tier, Philip Morris International Inc., British American Tobacco plc, and Japan Tobacco, Inc. exemplify divergent strategic postures. Philip Morris International occupies a position emphasizing heated-tobacco device penetration and reduced-risk product pipelines. British American Tobacco represents manufacturing scale diversification across Sub-Saharan Africa and Southeast Asia with dual focus on combustion and emerging format portfolios. Japan Tobacco anchors a position balancing domestic state-influenced market protection with international expansion through acquisition-led growth. These three entities collectively illustrate the competitive tension between defending legacy combustion margins and accelerating transition capital allocation.
| Leading Market Players |
|---|
| Japan Tobacco, Inc. |
| Imperial Brands plc |
| Philip Morris International Inc. |
| KT&G Corporation |
| China National Tobacco Corporation |
| British American Tobacco plc |
| ITC Limited |
| Smoore International Holdings Ltd |
| Altria Group, Inc. |
| Others |
Cost & Logistics Intelligence
Duty-free operators and airport retailers historically commanded premium pricing power through transient high-income buyer concentration, though post-pandemic business travel compression is forcing portfolio rotation toward domestic convenience and online channels where excise incidence and age-verification costs reshape margin structures.
Pricing Analysis
Volume sits with filtered variants in emerging economies where per-unit excise escalation drives bulk carton purchasing among price-sensitive smokers; premium positioning concentrates in duty-free channels and heated-tobacco hybrids occupying regulatory gray zones. Price differentiation hinges on flavor variant availability and track-and-trace compliance certification tiers mandated by the EU Tobacco Products Directive. Pricing pressure stems from menthol prohibition expansion across FDA enforcement zones and EU member states, compressing differentiation tools. Young adult cohorts in Brazil and Nigeria demonstrate highest price elasticity, while adult smokers in China and Indonesia sustain lowest sensitivity through state-controlled price floors.
Supply Chain Analysis
Domestic-content mandates in China and Indonesia require state-controlled or locally registered entities to handle cultivation, manufacturing, and distribution, reshaping sourcing patterns for multinational entrants seeking market access. Leaf supply concentrates in Brazil, Malawi, and Zimbabwe for flue-cured varieties, with Indonesia and India anchoring dark-fired and oriental tobacco dependencies. Raw material sourcing draws from subtropical belts vulnerable to climate volatility and water access disputes, with curing fuel costs and fertilizer price swings amplifying input uncertainty. Single-source vulnerability concentrates in China National Tobacco Corporation's captive leaf procurement networks. Distribution runs through provincial monopoly retail in China, licensed convenience-store networks in Southeast Asian megacities, and renegotiating duty-free slotting arrangements in Dubai and Singapore.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation around heat-not-burn classification and synthetic nicotine jurisdiction is accelerating consolidation, forcing sub-scale combustion-dependent manufacturers toward distressed exits or acquisition by reduced-risk portfolios with R&D intensity.
For Market Incumbents: Cement manufacturing scale advantages in Sub-Saharan Africa and Southeast Asia through backward integration into leaf processing and provincial distribution licensing. Prioritize heated-tobacco device assembly capacity in Germany and Japan where urban adoption compresses traditional cigarette occasion frequency. Defend against synthetic nicotine entrants by accelerating premarket authorization filings with FDA under the Family Smoking Prevention and Tobacco Control Act.
For New Entrants and Emerging Players: Provincial e-commerce platforms in China and Indonesia offer the most penetrable channel white-space, capturing share from traditional tobacco monopoly retail through delivery convenience and age-verified direct-to-consumer models. Target convenience-store network gaps in Nigerian and Kenyan urban corridors where underdeveloped retail infrastructure permits first-mover slotting fee negotiation. Pursue regulatory arbitrage positioning in synthetic nicotine classification jurisdictions before harmonization closes temporary windows.
For Investors and Strategic Acquirers: Distressed-cycle entries favor regional leaf-integrated specialists with export processing advantages in Brazil and southern Africa, where manufacturing employment migrates toward reduced-risk device assembly and combustion assets trade at compressed multiples. Long-term viability hinges on portfolio diversification toward non-combustion formats and geographic expansion into underenforced emerging markets. Watch FDA premarket authorization timelines as the critical inflection signal for portfolio-restructuring decisions.
| Strategic Initiative | Industry Significance |
|---|---|
| Heated-Tobacco Device Launch | Captures occasion migration in Japanese and South Korean urban centers seeking reduced-risk alternatives. |
| Provincial Distribution Licensing | Secures channel access in China and Indonesia where state-controlled networks dominate volume. |
| Track-and-Trace Compliance Investment | Meets EU Tobacco Products Directive mandates in Germany and France that reshape mid-tier cost structures. |
| Synthetic Nicotine Product Positioning | Exploits jurisdictional classification uncertainty before regulatory harmonization closes temporary windows. |
| Convenience-Store Network Expansion | Captures impulse purchase frequency in Southeast Asian megacities with urban proximity retail formats. |
Research Approach
Document review covered customs and trade databases, SEC 10-K filings, FDA premarket authorization records, and WHO Framework Convention on Tobacco Control implementation reports, complemented by interviews with regulatory affairs leads at multinational tobacco conglomerates, provincial distribution managers at state monopoly networks, and convenience-store category buyers in Southeast Asian markets. Secondary validation drew from EU Tobacco Products Directive compliance filings, State Tobacco Monopoly Administration production quota disclosures, and airport retail operator slotting fee renegotiation announcements. Bottom-up volume modeling and top-down value triangulation anchored the analytical framework.
Segmentation outputs reflect disaggregation across product type, end-user cohort, distribution channel, and packing format dimensions over the projection horizon. CAGRs were derived from historical volume trajectories adjusted for regulatory enforcement intensity and heat-not-burn substitution elasticities. Forecast inputs incorporated leaf supply concentration risks in subtropical cultivation belts and cross-border tax enforcement capabilities lagging e-commerce distribution innovations.
Caveats apply where FDA flavor enforcement priorities, EU menthol prohibition expansion, or climate-induced leaf yield volatility could materially shift the outlook beyond modeled scenarios. Forecasts reflect assumptions around adult smoker retention persistence in emerging economies and heated-tobacco regulatory classification stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tobacco Products
United States E-Cigarette Market
Tobacco Products
Handmade Cigars Market
Tobacco Products
Smokeless Cigarettes Market
Tobacco Products
Global E-Cigarettes Market
Tobacco Products
Tobacco Pouch Market
Tobacco Products
Heat-Not-Burn Tobacco Products Market
Tobacco Products
Cigarettes Filter Market
Tobacco Products
Latin America E-Cigarette Market
Tobacco Products
US E-Cigarette and Vape Market
Tobacco Products
Premium Tobacco Products Market
Tobacco Products
Heated Tobacco Products Market
Tobacco Products
GCC Cigarette Lighter Market
Tobacco Products
E-Cigarettes and Vaporizer Market
Tobacco Products
Middle East and Africa E-Cigarettes Market
Tobacco Products
Europe Cigarette Vending Machine Market
Tobacco Products
Premium Cigarette Market