
 Middle East and Africa E-Cigarettes Market | 2026-2036
Middle East and Africa E-Cigarettes Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa E-Cigarettes Market Foresight
The Middle East and Africa e-cigarettes category is consolidating around a sharp split between premium closed-system pods and low-cost disposable devices. British American Tobacco leverages its heated-tobacco infrastructure to anchor premium positioning across Gulf retail networks. Philip Morris International competes through IQOS device ecosystems and dedicated boutique stores in Dubai and Riyadh. Joyetech Group sustains volume play via open-tank systems priced for price-sensitive consumers in Egypt and Nigeria.
An e-cigarette is a battery-powered inhalation device that vaporizes a liquid solution—typically containing propylene glycol, vegetable glycerin, nicotine, and flavoring agents—into an aerosol for user inhalation. Devices range from cylindrical vape pens with refillable tanks to compact pod systems with pre-filled cartridges, all regulated by maximum nicotine concentration thresholds in multiple jurisdictions. Pod systems command the fastest growth trajectory due to convenience and youth-oriented design, while disposable devices dominate trial purchases and tourism channels. E-liquids generate recurring revenue streams that specialty stores exploit through flavor customization services and loyalty programs.
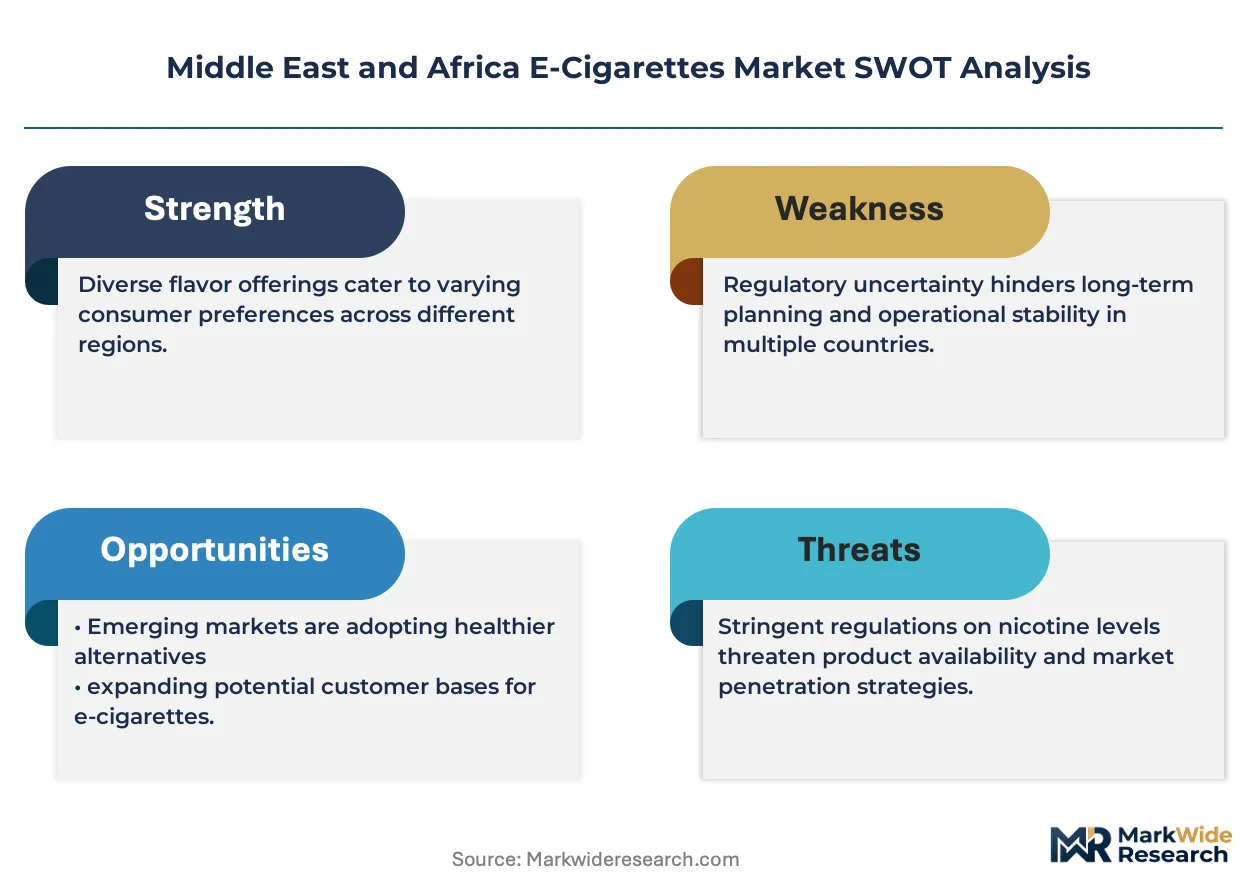
Emirates Authority for Standardization and Metrology mandates product registration and emission testing for all vaping imports into the UAE. South Africa's National Department of Health advances tobacco control amendments that would classify e-cigarettes as tobacco products subject to advertising bans and public-use restrictions. Saudi Food and Drug Authority enforces nicotine caps and packaging standards that filter out unregistered suppliers. Stakeholders must monitor regulatory divergence between Gulf harmonization efforts and sub-Saharan enforcement gaps when allocating compliance resources and distribution partnerships.
Market Dynamics
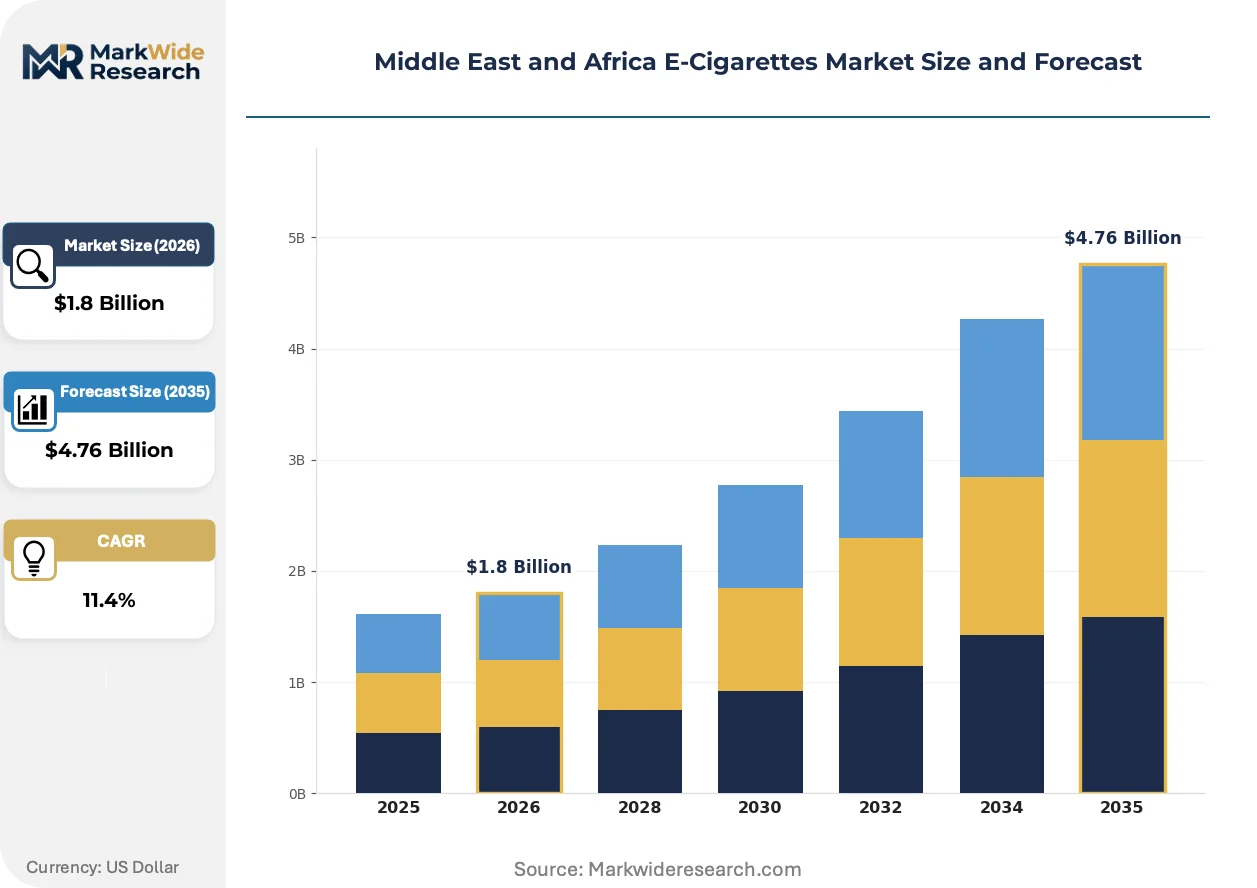
Pod system technology is compressing the Middle East and Africa e-cigarettes competitive landscape by collapsing the barrier between trial and repeat purchase, while regulatory divergence between Gulf harmonization and sub-Saharan enforcement gaps fragments compliance investment.
Growth Catalysts
- Flavor customization infrastructure:Specialty retailers in Dubai and Riyadh deploy on-site mixing stations that convert single-device buyers into recurring e-liquid subscribers. Mall-based boutique formats exploit this service layer to defend against online price competition.
- Emirates Authority for Standardization and Metrology registration pathways:Formalized product testing and emission certification for UAE imports creates legitimate supply corridors that displace grey-market disposable inflows. Registered suppliers gain preferential retail placement in duty-free and mall channels.
- Young adult nicotine migration:Urban consumers aged 18-29 across South Africa and Gulf states are rotating from combustible tobacco toward closed-system pods, accelerating category normalization and social acceptability in entertainment venues.
Market Restraints
- South Africa's tobacco control amendment friction:Proposed classification of e-cigarettes as tobacco products threatens advertising bans and public-use restrictions that would compress brand-building channels and trial conversion rates.
- Propylene glycol and vegetable glycerin import concentration:E-liquid base ingredient supply clusters through Indian and Chinese chemical exporters, exposing formulators to freight cost volatility and currency fluctuation risk.
- Nicotine salt technical ceiling:Current formulation chemistry limits smoothness-to-concentration ratios at thresholds below combustible satisfaction for heavy smokers, constraining switching efficacy in the premium segment.
Strategic Opportunities
- Nigeria's underpenetrated open-tank segment:Price-sensitive consumers in Lagos and Abuja remain underserved by closed-system premium positioning, creating volume play potential for refillable device ecosystems with localized flavor profiles.
- Saudi Food and Drug Authority nicotine cap compliance:Registration and packaging standard enforcement filters unregistered competitors, opening shelf space for compliant suppliers willing to absorb certification timelines and testing costs.
- Heat-not-burn convergence with e-cigarette retail:Heated-tobacco device boutiques in Dubai and Riyadh are cross-merchandising pod systems, leveraging shared consumer education infrastructure and mall-based foot traffic.
Industry Challenges
- Emission testing laboratory capacity:Gulf product registration requirements outpace accredited local testing facility availability, extending time-to-market for new SKUs and compressing product refresh cycles.
- Flavor chemist talent scarcity:Formulation expertise for region-specific taste profiles concentrates in European and Asian hubs, forcing Middle East and Africa operations to rely on remote technical support or expatriate hiring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa E-Cigarettes Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vape Pens, E-Liquids, Pod Systems, Disposable Devices Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Convenience Stores Customer Type: Adult Smokers, Former Smokers, Young Adults, New Users Flavor Profile: Tobacco, Menthol, Fruit, Dessert |
| Companies Covered | Japan Tobacco International, Joyetech Group, British American Tobacco, VIP Electronic Cigarettes, Innokin Technology, Philip Morris International, Imperial Brands, KangerTech, Aspire Global, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa E-Cigarettes Market Shifts & Advancements
Technology convergence between pod system miniaturization and synthetic nicotine chemistry is restructuring product development priorities across Middle East and Africa manufacturing and import channels.
Mesh coil heating elements are expanding into premium pod architectures by delivering more consistent aerosol density across battery depletion curves. Young adult consumers in UAE mall channels adopt these devices at replacement cycles compressed to under 90 days. The technology is expanding into disposable formats previously limited to wick-and-coil construction, eroding the performance gap between single-use and rechargeable systems.
Saudi Food and Drug Authority packaging standard enforcement mandates child-resistant closures and pictorial health warnings that reshape labeling production workflows. Industrial consequence includes accelerated obsolescence of pre-printed inventory and forced migration to regional printing partnerships. The closed-system pod segment bears disproportionate compliance cost due to smaller per-unit surface area requiring design reconfiguration.
Subscription-based e-liquid replenishment is displacing episodic retail purchase among established vapers in South Africa's metropolitan cores. Dedicated online platforms and WhatsApp-enabled ordering systems disintermediate traditional vape shop foot traffic. This behavioral shift concentrates most visibly in Cape Town and Johannesburg, where logistics infrastructure supports same-day or next-day delivery expectations.
Middle East and Africa E-Cigarettes Market Segmentation
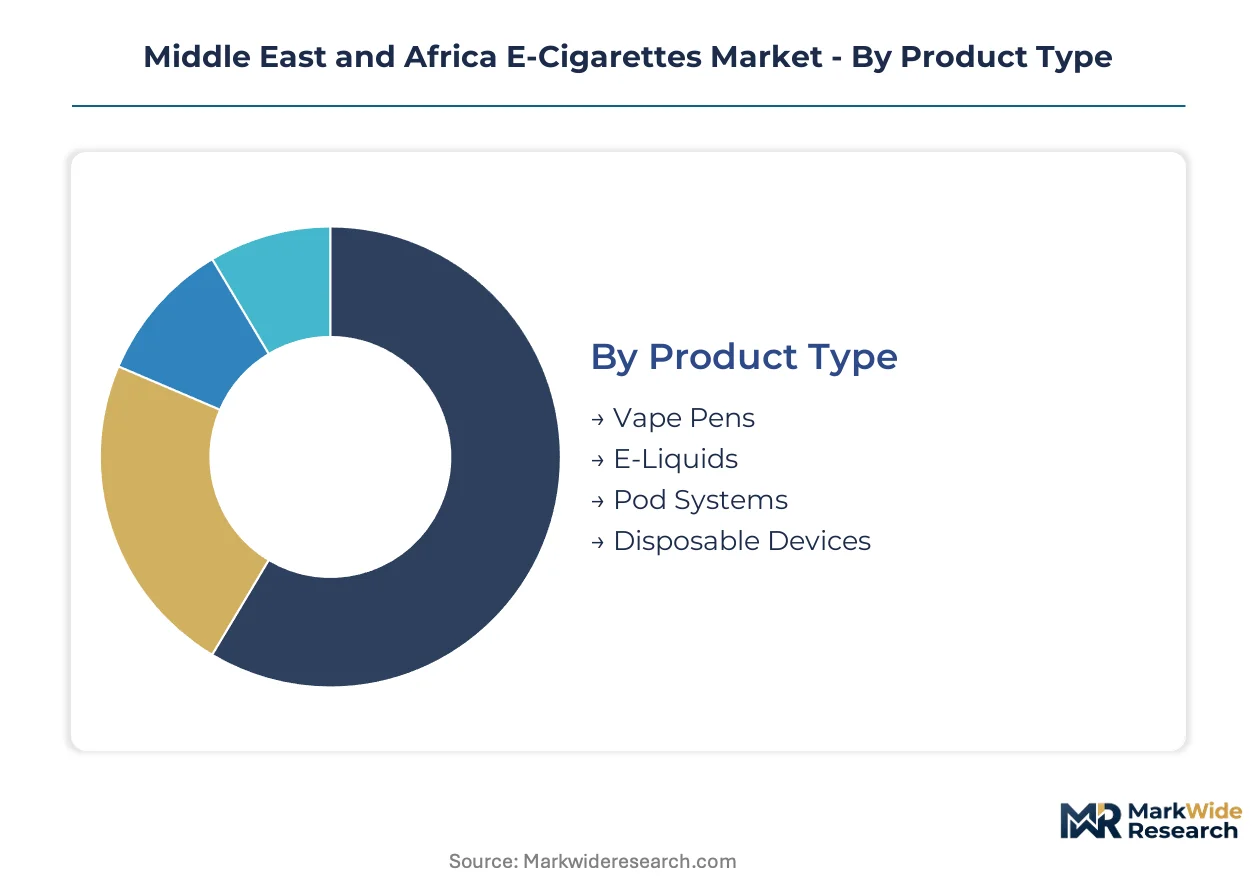
Segmentation across the Middle East and Africa e-cigarettes market reveals divergent upgrade cycles between closed-system pods and disposable trial devices. Replacement frequency, distribution access, and regulatory exposure vary sharply by product architecture and customer migration path.
Product Type:
Replacement cycles compress as consumers migrate from open-tank systems toward sealed pod architectures with proprietary cartridge formats.
- Pod Systems:Closed-system devices with pre-filled nicotine salt cartridges deliver consistent aerosol density through mesh coil heating elements. Demand clusters in Dubai and Riyadh mall channels where young adult consumers accept 60-90 day hardware replacement cadences paired with recurring cartridge purchases.
- Disposable Devices:Single-use units with integrated batteries and fixed e-liquid reservoirs dominate trial purchases and tourism corridors. Grey-market inflows from unregistered suppliers persist despite Emirates Authority for Standardization and Metrology registration requirements, compressing margins for compliant importers.
- Vape Pens:Cylindrical refillable devices with tank reservoirs and replaceable coils serve price-sensitive consumers in Egypt and Nigeria through open-system flexibility.
- E-Liquids:Propylene glycol and vegetable glycerin solutions with variable nicotine concentrations generate recurring revenue through specialty retail mixing stations and subscription replenishment platforms.
Volume placements concentrate in Disposable Devices; the faster expansion belongs to Pod Systems.
Distribution Channel:
Channel selection directly shapes customer acquisition costs and regulatory compliance burdens across divergent national enforcement environments.
- Specialty Stores:Mall-based boutiques in Dubai and Riyadh combine device sales with on-site flavor customization and loyalty program enrollment. These formats absorb elevated rent burdens to defend against online price competition through service differentiation and immediate product education.
- Online Retail:WhatsApp-enabled ordering and dedicated e-commerce platforms disintermediate traditional retail in South Africa's metropolitan cores, with same-day delivery infrastructure concentrating in Cape Town and Johannesburg.
- Convenience Stores:High-frequency urban locations in Lagos and Abuja move low-margin disposable units to transient consumers with minimal staff interaction.
- Supermarkets:Mass retail placement remains limited by shelf-space competition and restrictive tobacco-adjacent merchandising policies in Gulf jurisdictions.
Revenue contribution tilts toward Specialty Stores; customer acquisition efficiency climbs fastest in Online Retail.
Customer Type:
Migration patterns from combustible tobacco determine device format preferences and lifetime value calculations across national markets.
- Young Adults:Consumers aged 18-29 across South Africa and Gulf states rotate from cigarettes toward closed-system pods, accelerating social normalization in entertainment venues and driving compressed replacement cycles.
- Former Smokers:Individuals transitioning away from combustible products seek nicotine satisfaction parity through higher-concentration salt formulations, constraining switching efficacy where technical ceilings limit smoothness ratios.
- Adult Smokers:Current tobacco users represent the largest addressable population but require targeted education on device operation and maintenance to overcome adoption friction.
- New Users:Nicotine-naive entrants typically initiate through flavored disposable devices in social contexts, presenting distinct regulatory exposure under proposed advertising restrictions.
Addressable population mass resides with Adult Smokers; steepest expansion trajectory tracks Young Adults.
Flavor Profile:
Formulation chemistry and regional taste preferences dictate manufacturing location and import routing decisions.
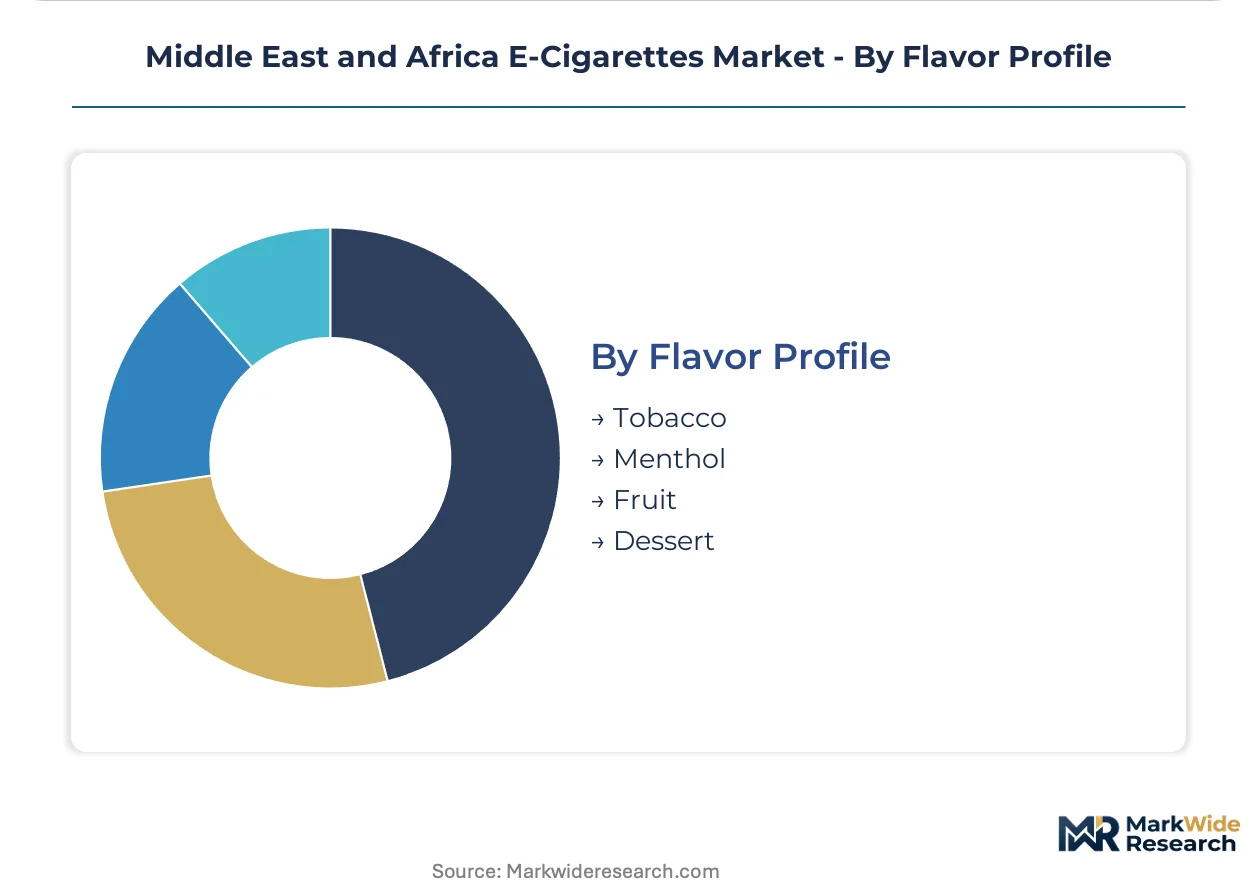
- Fruit:Berry and tropical flavor concentrates dominate youth-oriented pod cartridges and disposable lines, with formulation expertise concentrated in European and Asian chemical hubs requiring remote technical support for Middle East operations.
- Tobacco:Combustible-mimicking profiles serve former smoker conversion in Saudi Arabia and UAE, where palate familiarity supports premium pricing for verified emission-compliant products.
- Menthol:Cooling agents face variable regulatory treatment across national jurisdictions, with some markets restricting characterizing flavors while permitting mint derivatives.
- Dessert:Custard and bakery profiles attract established vapers seeking variety rotation, driving subscription replenishment volumes in South Africa's metropolitan cores.
Shipment volume concentrates in Tobacco; flavor innovation velocity peaks in Fruit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai anchors e-cigarette distribution across the Middle East and Africa, with mall-based specialty retail and duty-free corridors channeling registered imports throughout Gulf Cooperation Council states. Lagos and Johannesburg concentrate open-system demand in sub-Saharan corridors where price sensitivity shapes device format preferences.
United Arab Emirates
Emirates Authority for Standardization and Metrology registration requirements filter grey-market disposable inflows while legitimizing compliant supply corridors. Dubai's mall-based boutique networks exploit on-site flavor customization to defend against online price competition. Abu Dhabi duty-free channels serve as transit nodes for registered pod systems entering Saudi Arabia and Qatar.
Saudi Arabia
Saudi Food and Drug Authority nicotine caps and packaging standards displace unregistered suppliers from retail shelf space. Riyadh's entertainment venue clusters accelerate young adult migration from combustible tobacco toward closed-system pods. Jeddah commercial districts concentrate heat-not-burn cross-merchandising with e-cigarette retail formats.
South Africa
National Department of Health tobacco control amendments threaten advertising bans that would compress brand-building channels in Cape Town and Johannesburg. WhatsApp-enabled ordering platforms disintermediate traditional vape shop foot traffic through same-day delivery infrastructure. Metropolitan cores drive subscription-based e-liquid replenishment among established vapers.
Egypt
Open-tank vape pens serve price-sensitive consumers through refillable device flexibility unavailable in sealed pod architectures. Cairo's informal retail networks move cylindrical devices with minimal regulatory enforcement compared to Gulf registration regimes. Alexandria port corridors channel Chinese-manufactured hardware with limited emission testing requirements.
Nigeria
Lagos and Abuja remain underpenetrated by closed-system premium positioning, creating volume play potential for refillable ecosystems with localized flavor profiles. Convenience store channels dominate disposable unit distribution to transient consumers. Currency fluctuation risk concentrates e-liquid base ingredient procurement through Indian chemical exporters.
Middle East and Africa E-Cigarettes Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent technology vectors in the Middle East and Africa e-cigarettes market. Heated-tobacco infrastructure owners anchor premium positioning through dedicated boutique networks, while open-system specialists capture price-sensitive volume in sub-Saharan corridors. Three archetypes dominate: multinational tobacco conglomerates with heat-not-burn convergence strategies, Chinese manufacturing specialists with disposable and open-tank volume plays, and regional import distributors with registration compliance expertise. Competitive moves concentrate on cross-merchandising heat-not-burn with pod systems, and on absorbing Emirates Authority for Standardization and Metrology certification timelines to displace grey-market competitors.
Within the multinational conglomerate tier, British American Tobacco and Philip Morris International exemplify premium positioning through Gulf retail network control. Joyetech Group occupies a position among volume-oriented specialists serving refillable device demand in Egypt and Nigeria. These three anchors represent divergent strategic bets: heat-not-burn infrastructure leverage, closed-system pod ecosystem investment, and open-tank price-point penetration.
| Leading Market Players |
|---|
| Japan Tobacco International |
| Joyetech Group |
| British American Tobacco |
| VIP Electronic Cigarettes |
| Innokin Technology |
| Philip Morris International |
| Imperial Brands |
| KangerTech |
| Aspire Global |
| Others |
Supply & Pricing Matrix
Mesh coil miniaturization across pod system architectures is compressing manufacturing cost curves while concentrating component sourcing among Shenzhen and Dongguan electronics clusters. This technology transition simultaneously erodes the price-performance gap between disposable and rechargeable formats, reshaping how Emirates Authority for Standardization and Metrology compliance costs flow through final retail pricing.
Pricing Analysis
Value-based pricing anchored to nicotine satisfaction parity with combustible tobacco dominates premium closed-system pods in Dubai and Riyadh mall channels. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and after-sales service bundling. Cost compression in the disposable tier intensifies because grey-market inflows from unregistered suppliers undercut compliant import margins. Price-sensitive consumers in Egypt and Nigeria gravitate toward open-tank systems, while Gulf young adults accept premium pod pricing for convenience and social signaling.
Supply Chain Analysis
Freight cost volatility from Indian and Chinese chemical exporters to regional formulation hubs in South Africa and Nigeria is compressing e-liquid base ingredient margins. Propylene glycol and vegetable glycerin supply draws from Mumbai and Guangzhou chemical clusters, with hardware assembly concentrated in Shenzhen and Dongguan. Single-source vulnerability persists in mesh coil heating element supply. Distribution runs through Dubai's duty-free corridors for Gulf Cooperation Council transit, while Lagos and Johannesburg serve as sub-Saharan consolidation nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory divergence between Gulf harmonization and sub-Saharan enforcement gaps is forcing capital-constrained distributors toward acquisition or exit, consolidating market control among compliance-heavy incumbents with certification infrastructure.
For Market Incumbents: Hedge against South Africa's tobacco control amendment passage by diversifying revenue toward subscription-based e-liquid replenishment platforms that bypass advertising restrictions. Absorb extended Emirates Authority for Standardization and Metrology certification timelines to displace grey-market competitors from duty-free and mall channels. Vertical integration into regional printing partnerships for Saudi Food and Drug Authority packaging compliance reduces obsolescence risk from pre-printed inventory. For New Entrants and Emerging Players: Launch via WhatsApp-enabled ordering systems targeting South Africa's metropolitan cores, where same-day delivery infrastructure disintermediates traditional vape shop foot traffic. Nigeria's underpenetrated open-tank segment offers volume play potential for refillable device ecosystems with localized flavor profiles. Partner with Indian chemical exporters to secure propylene glycol and vegetable glycerin supply on flexible terms that absorb currency fluctuation risk. For Investors and Strategic Acquirers: Exit pathways concentrate in regional import distributors with registration compliance expertise and established Emirates Authority for Standardization and Metrology product portfolios. Long-term viability hinges on heat-not-burn convergence strategies that leverage shared retail infrastructure across pod systems and heated-tobacco devices. Monitor Saudi Food and Drug Authority enforcement intensity as the signal to watch for shelf-space reallocation toward compliant suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Emirates Authority for Standardization and Metrology Product Registration | Legitimizes supply corridors and secures preferential placement in Dubai mall channels. |
| Heat-Not-Burn Retail Convergence | Cross-merchandising pod systems in IQOS boutiques leverages shared consumer education infrastructure. |
| Subscription-Based E-Liquid Replenishment | WhatsApp-enabled platforms in Cape Town and Johannesburg disintermediate traditional retail foot traffic. |
| Regional Printing Partnership Migration | Local packaging production absorbs Saudi Food and Drug Authority labeling standard changes without inventory write-offs. |
| Mesh Coil Disposable Format Expansion | Erodes performance gap with rechargeable systems and compresses replacement cycles below 90 days. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with vape shop operators, e-liquid formulators, mall-based retail managers, and import compliance specialists. Bottom-up and top-down triangulation cross-validated volume estimates against Emirates Authority for Standardization and Metrology registration databases, Saudi Food and Drug Authority product listings, and South African National Department of Health amendment tracking.
Product type, distribution channel, customer migration path, and flavor profile were modeled at the country level across the analysis window, with replacement frequency and regulatory exposure varying by national enforcement environment. CAGRs were derived from segment-level growth trajectory synthesis. Forecast inputs incorporated nicotine salt formulation chemistry ceilings, emission testing laboratory capacity constraints, and flavor chemist talent scarcity in regional hubs.
Regulatory reversal, laboratory accreditation delays, and currency fluctuation in e-liquid base ingredient procurement are the dominant revision risks that could alter trajectory assumptions. Stakeholders should weight assumptions against their own operating context and compliance resource allocation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tobacco Products
Global Flavor Capsule Cigarette Market
Tobacco Products
Cigarette Market
Tobacco Products
Liquor Flavored Cigars Market
Tobacco Products
Flavored Cigar Market
Tobacco Products
Africa Tobacco Products Market
Tobacco Products
United States Pipe Tobacco Market
Tobacco Products
Smokeless Cigarettes Market
Tobacco Products
Handmade Cigars Market
Tobacco Products
Premium Tobacco Products Market
Tobacco Products
Homemade Cigars Market
Tobacco Products
Global E-Cigarettes Market
Tobacco Products
Premium Cigarette Market
Tobacco Products
Heat-Not-Burn Tobacco Products Market
Tobacco Products
Europe E-Cigarettes Market
Tobacco Products
Menthol Cigarette Market
Tobacco Products
Disposable E-Cigarettes Market