
 Heat-Not-Burn Tobacco Products Market | 2026-2036
Heat-Not-Burn Tobacco Products Market Size, Share, and Industry Trends Forecast 2026-2036
Heat-Not-Burn Tobacco Products Market Foresight
Aftermarket consumable revenue is tilting toward heatable sticks and replacement accessories as the primary margin pool. Philip Morris International leverages its IQOS ecosystem to sustain recurring stick sales across licensed markets. British American Tobacco PLC anchors its glo platform in European retail channels with aggressive device subsidy programs. Japan Tobacco Inc. competes through Ploom TECH variants optimized for domestic flavor preferences.
Heat-not-burn tobacco products are electronic or carbon-heated systems that warm processed tobacco to approximately 300-350°C without combustion, releasing nicotine-containing aerosol with reduced harmful constituent levels compared to conventional cigarette smoke. The primary commercial purpose centers on delivering a cigarette-like experience with lower toxicant exposure for adult smokers unwilling or unable to quit entirely. Devices and heatable sticks command the dominant value share, with conduction heating technology leading installed bases while hybrid heating systems attract premium-tier buyers seeking enhanced temperature precision. The material dimension shows tobacco blend sticks generating the majority of unit volumes, though herbal mix variants gain traction in markets with strict nicotine advertising constraints.
The FDA's modified risk tobacco product pathway determines market access for reduced-harm claims in the United States, while the EU Tobacco Products Directive and national implementations across Germany, Italy, and Poland govern labeling and cross-border sales within Europe. Japan's Ministry of Health, Labour and Welfare maintains distinct pharmaceutical-style oversight that enables broader reduced-risk messaging than most jurisdictions permit. Stakeholders must monitor evolving science-based regulatory frameworks that increasingly differentiate between combustion-free and traditional tobacco products when allocating R&D and market entry investments.
Market Dynamics
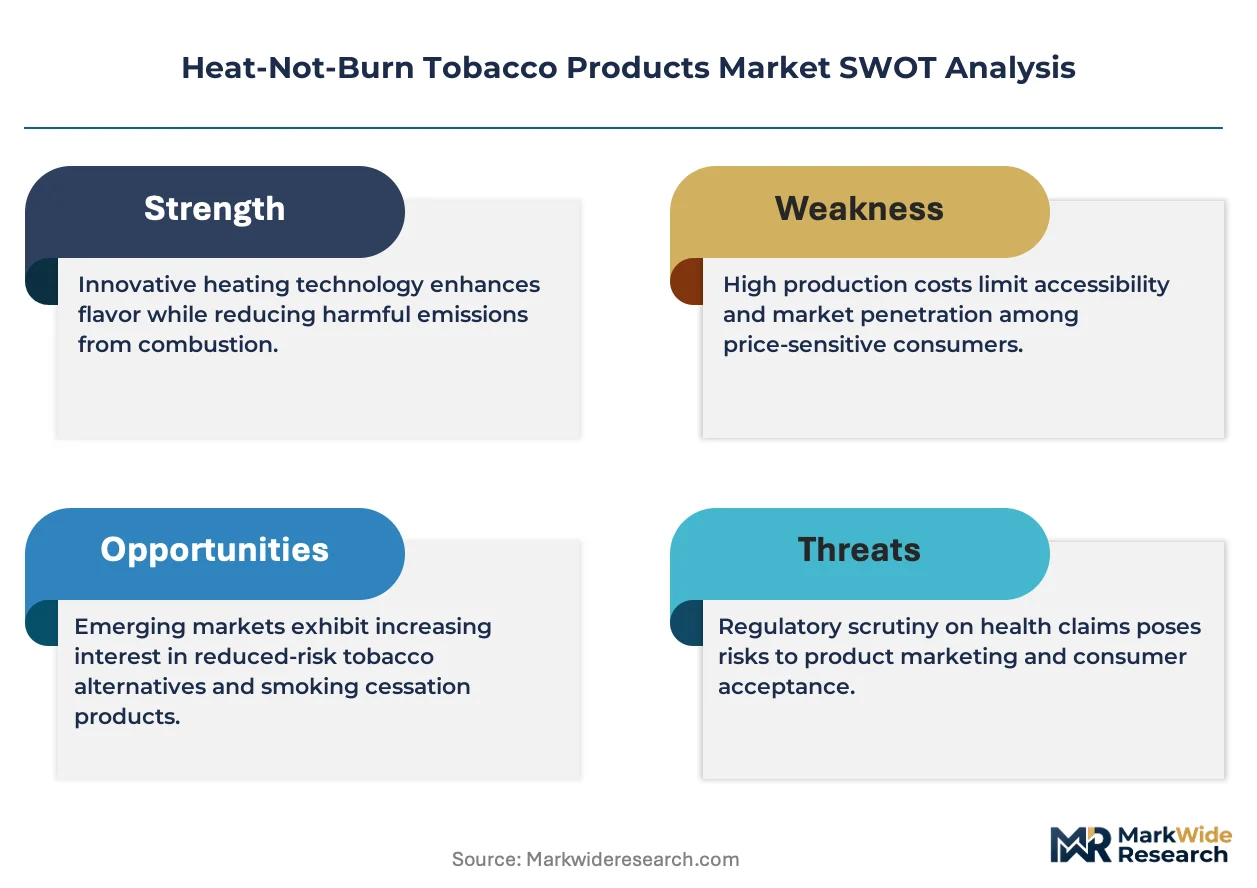
The heat-not-burn tobacco market pivots on regulatory differentiation between combustion-free and traditional tobacco products, with science-based authorization pathways determining where reduced-harm claims can legally anchor consumer messaging and device adoption curves.
Growth Catalysts
- FDA Modified Risk Tobacco Product pathway:The United States authorization framework creates legal space for reduced-exposure claims, enabling adult smokers to access verified lower-toxicant alternatives through regulated channels.
- East Asian metropolitan demand concentration:Adult smokers in Tokyo, Seoul, and Osaka demonstrate sustained willingness to switch from combustible cigarettes to heated tobacco systems when retail access and flavor variety align.
- Conduction heating technology maturation:Temperature precision improvements in ceramic blade and pin systems deliver consistent aerosol delivery that satisfies nicotine absorption expectations among former cigarette users.
Market Restraints
- EU Tobacco Products Directive labeling constraints:Cross-border sales restrictions and standardized warning requirements limit reduced-harm messaging flexibility in Germany, Italy, and Poland retail environments.
- Tobacco leaf input cost volatility:Flue-cured and burley tobacco price fluctuations compress margin pools on consumable sticks, particularly for manufacturers without captive leaf supply arrangements.
- Pharmaceutical-style oversight in Japan:Ministry of Health, Labour and Welfare requirements for clinical evidence submission extend product variant approval timelines beyond standard tobacco product registration periods.
Strategic Opportunities
- Herbal mix variant expansion:Nicotine-free heated consumables circumvent strict advertising constraints in markets where tobacco-derived products face promotional prohibitions, opening incremental shelf space in convenience retail.
- Hybrid heating system premium tier:Induction-conduction combination devices attract temperature-control-sensitive users in South Korea and Switzerland willing to pay for precision-engineered aerosol consistency.
- United Kingdom pharmacy channel pilot programs:National Health Service smoking cessation referral pathways create potential distribution access points beyond traditional tobacco retail for authorized reduced-risk products.
Industry Challenges
- Aerosol toxicology certification timelines:Independent laboratory validation of harmful constituent reduction claims requires 18-36 month study protocols that delay market entry in jurisdictions with stringent evidence requirements.
- Device-stick ecosystem lock-in engineering:Proprietary heating blade geometries and stick dimensions complicate aftermarket accessory sourcing and create consumer switching friction when migrating between competing platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heat-Not-Burn Tobacco Products Market |
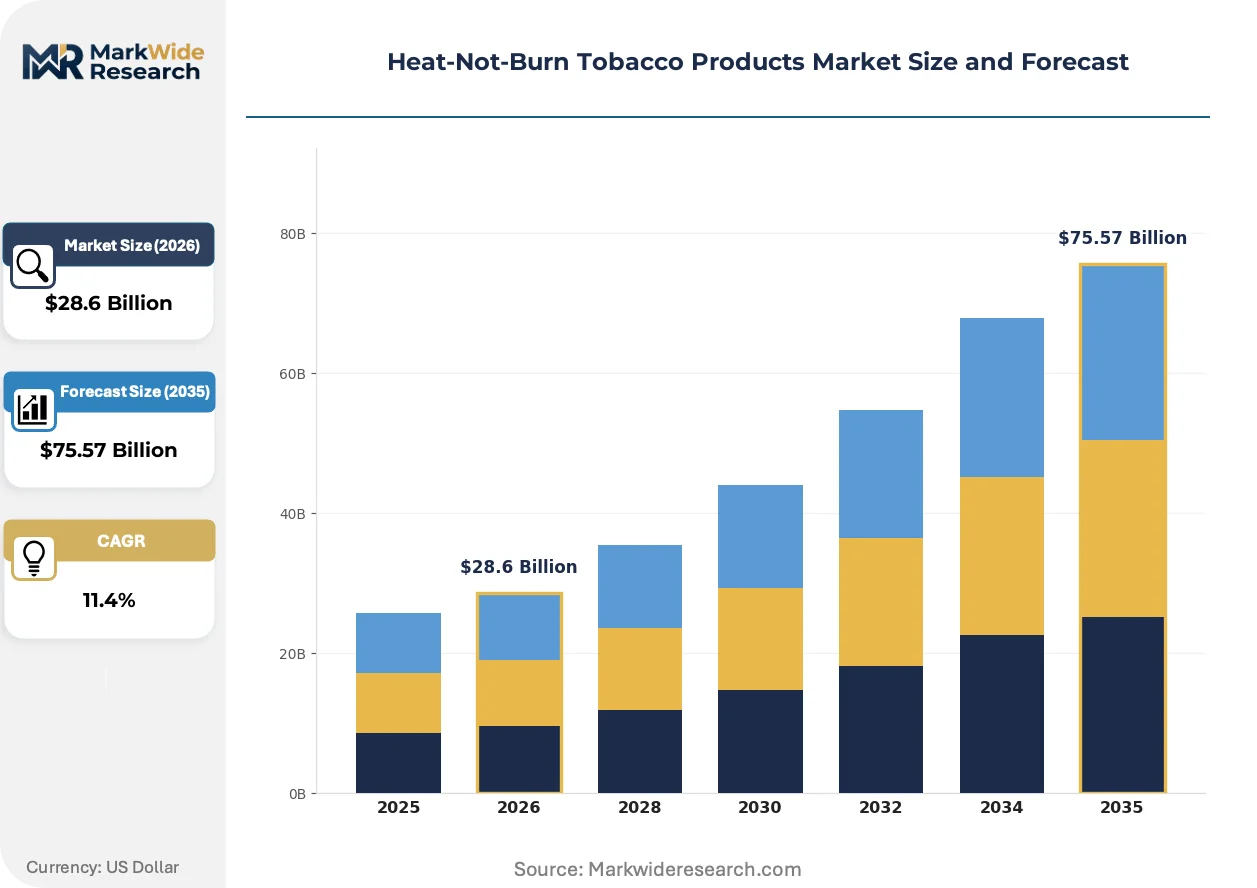
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Devices, Heatable Sticks, Accessories, Cleaning Tools End User: Individual Consumers, Retail Chains, Online Shops, Wholesale Distributors Technology: Conduction Heating, Convection Heating, Hybrid Heating, Innovative Cooling Material: Tobacco Blend, Herbal Mix, Nicotine Salts, Biomass |
| Companies Covered | KT&G Corporation, Altria Group, Inc., Philip Morris International, Smoore International Holdings Limited, China National Tobacco Corporation, British American Tobacco PLC, Imperial Brands PLC, HEECHI Group, Japan Tobacco Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heat-Not-Burn Tobacco Products Market Shifts & Advancements
Technology convergence between precision heating control and consumable formulation science is compressing product development cycles while regulatory science frameworks mature to distinguish combustion-free systems from legacy tobacco categories.
Hybrid induction-conduction heating architectures are collapsing the performance gap between carbon-heated and fully electronic systems. Premium-tier buyers in Seoul and Zurich now access temperature profiles within 5°C variance across the stick consumption cycle. This precision is collapsing consumer skepticism about heated tobacco's ability to replicate cigarette satisfaction metrics.
Japan's pharmaceutical-style oversight framework is reshaping evidentiary standards for reduced-harm claims across Asia-Pacific markets. Clinical biomarker studies submitted to PMDA-equivalent regulators now influence authorization decisions in neighboring jurisdictions. Heat-not-burn manufacturers targeting South Korea and Taiwan must align toxicology dossiers with Japanese precedent to accelerate regulatory review timelines.
After-sales service unbundling is fragmenting traditional device-stick bundling models in European retail. Specialist vape shops and tobacconists in London and Berlin now offer blade replacement and deep-cleaning services separate from consumable purchases. This service separation is most visible among adult smokers aged 35-50 who prioritize device longevity over promotional stick volume discounts.
Heat-Not-Burn Tobacco Products Market Segmentation
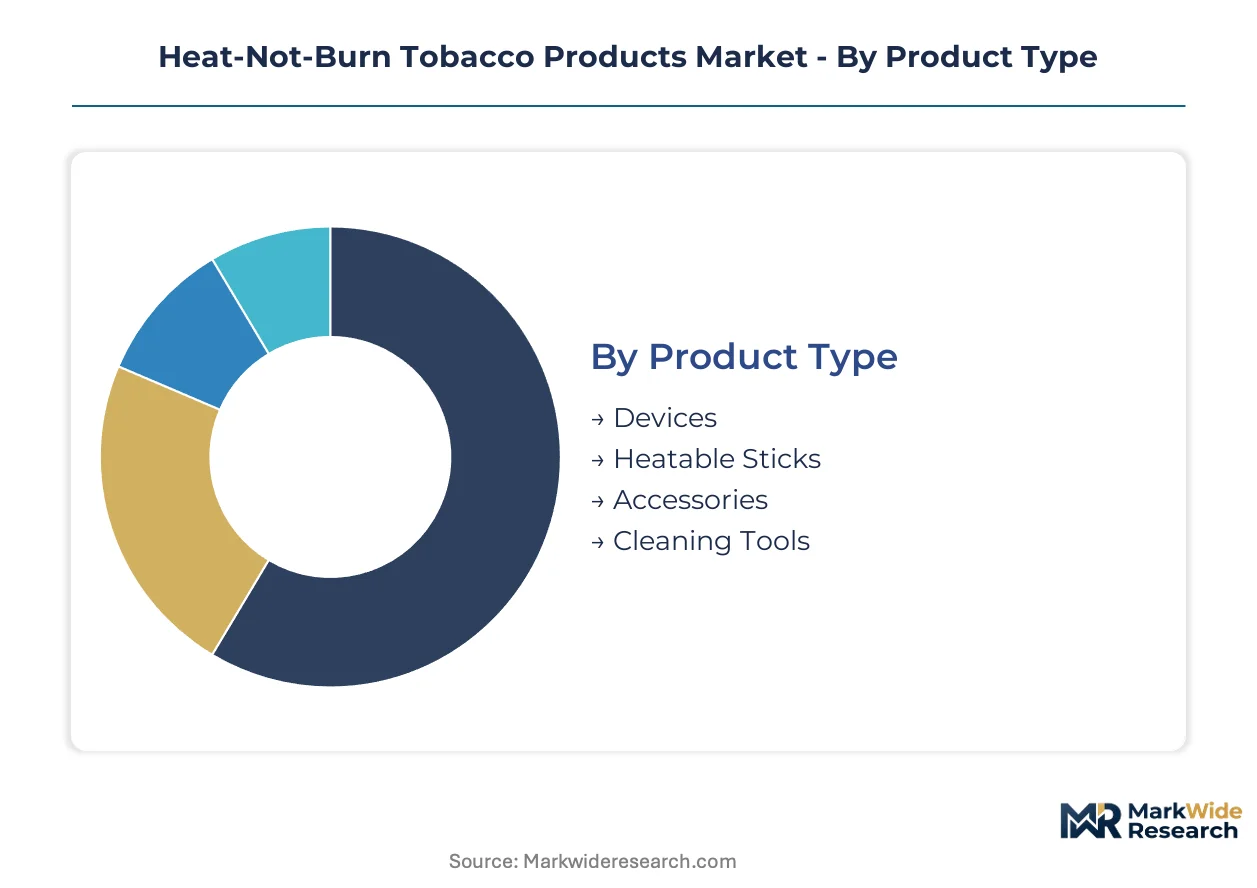
Segmentation in heat-not-burn tobacco products reveals divergent margin architectures across hardware and consumable categories. Service intensity, replacement frequency, and ecosystem lock-in create distinct competitive battlegrounds that manufacturers exploit through platform-specific consumable strategies.
Product Type:
After-sales service intensity varies sharply across this category, with blade replacement and cleaning protocols driving recurring revenue attachment rates.
- Devices:Electronic or carbon-heated hardware systems featuring ceramic blades or pin-style heating elements. Demand clusters in Tokyo, Seoul, and Osaka where adult smokers prioritize cigarette-like ritual replication. Philip Morris International's IQOS and British American Tobacco's glo dominate installed bases through subsidized hardware entry pricing.
- Heatable Sticks:Proprietary tobacco or herbal consumables engineered for specific heating geometries. Retail chains in Germany and Italy generate volume through bundled multi-pack promotions. Recurring stick purchases sustain manufacturer margins long after device subsidy recovery.
- Accessories:Charging docks, carrying cases, and protective sleeves. Online shops in the United Kingdom capture incremental attach rates through checkout bundling algorithms.
- Cleaning Tools:Specialized swabs, blade brushes, and descaling solutions. Wholesale distributors in South Korea push these as margin-enhancing add-ons to device retailers.
By volume, Heatable Sticks leads. By growth pace, Accessories is expanding most quickly as unbundled after-sales service models proliferate.
End User:
Cost tier differentiation separates premium direct-to-consumer channels from high-volume wholesale arrangements.
- Individual Consumers:Adult smokers aged 25-45 seeking reduced-risk alternatives through pharmacy, convenience, or specialty retail. Japan's Ministry of Health, Labour and Welfare oversight enables broader reduced-harm messaging than FDA or EU Tobacco Products Directive frameworks permit.
- Retail Chains:Convenience store networks and tobacconists in the United Kingdom, Italy, and Poland. These channels depend on promotional stick volume discounts and device display allowances from manufacturers competing for shelf space.
- Online Shops:E-commerce platforms circumventing traditional tobacco retail restrictions in jurisdictions with strict point-of-sale regulations. Swiss and South Korean consumers access hybrid heating devices through this channel.
- Wholesale Distributors:Regional logistics operators supplying independent retailers across Germany's federal state system. These intermediaries concentrate procurement leverage through multi-brand portfolio aggregation.
By revenue concentration, Retail Chains dominates. By margin expansion, Online Shops is climbing the fastest as direct-to-consumer regulatory arbitrage opportunities emerge.
Technology:
Application-specific performance requirements segment buyers between ritual fidelity and temperature precision priorities.
- Conduction Heating:Ceramic blade or pin systems warming tobacco through direct surface contact. This mature technology commands the largest installed base across Japan and European metropolitan markets due to manufacturing scale and consumable compatibility standardization.
- Convection Heating:Forced-air systems circulating heated air through tobacco chambers. Niche adoption in Switzerland and premium-tier segments where users prioritize reduced device cleaning frequency.
- Hybrid Heating:Induction-conduction combination architectures delivering temperature variance within 5°C across stick consumption cycles. South Korean buyers in Seoul demonstrate willingness to pay premium pricing for this precision-engineered aerosol consistency.
- Innovative Cooling:Advanced heat sink and airflow management systems reducing external device temperature. Emerging deployments in climate-sensitive Middle Eastern markets where device surface heat affects user experience.
By installed base, Conduction Heating leads. By technology substitution momentum, Hybrid Heating is gaining share fastest among temperature-control-sensitive user segments.
Material:
Customer type segmentation separates nicotine-dependent users from regulatory-avoidance seekers.
- Tobacco Blend:Flue-cured and burley tobacco formulations processed for optimal aerosol release at 300-350°C. Japan Tobacco Inc.'s Ploom TECH variants optimize domestic flavor preferences through proprietary blend ratios.
- Herbal Mix:Nicotine-free botanical formulations circumventing strict advertising constraints in markets with tobacco-derived product promotional prohibitions. Convenience retail in the United Kingdom trials these for incremental shelf space.
- Nicotine Salts:Laboratory-synthesized nicotine formulations enabling precise dosing control. Regulatory scrutiny from FDA and EU scientific committees constrains authorization timelines.
- Biomass:Cellulose-based carrier materials with or without nicotine infusion. Experimental deployments in carbon-neutral positioning strategies by European manufacturers.
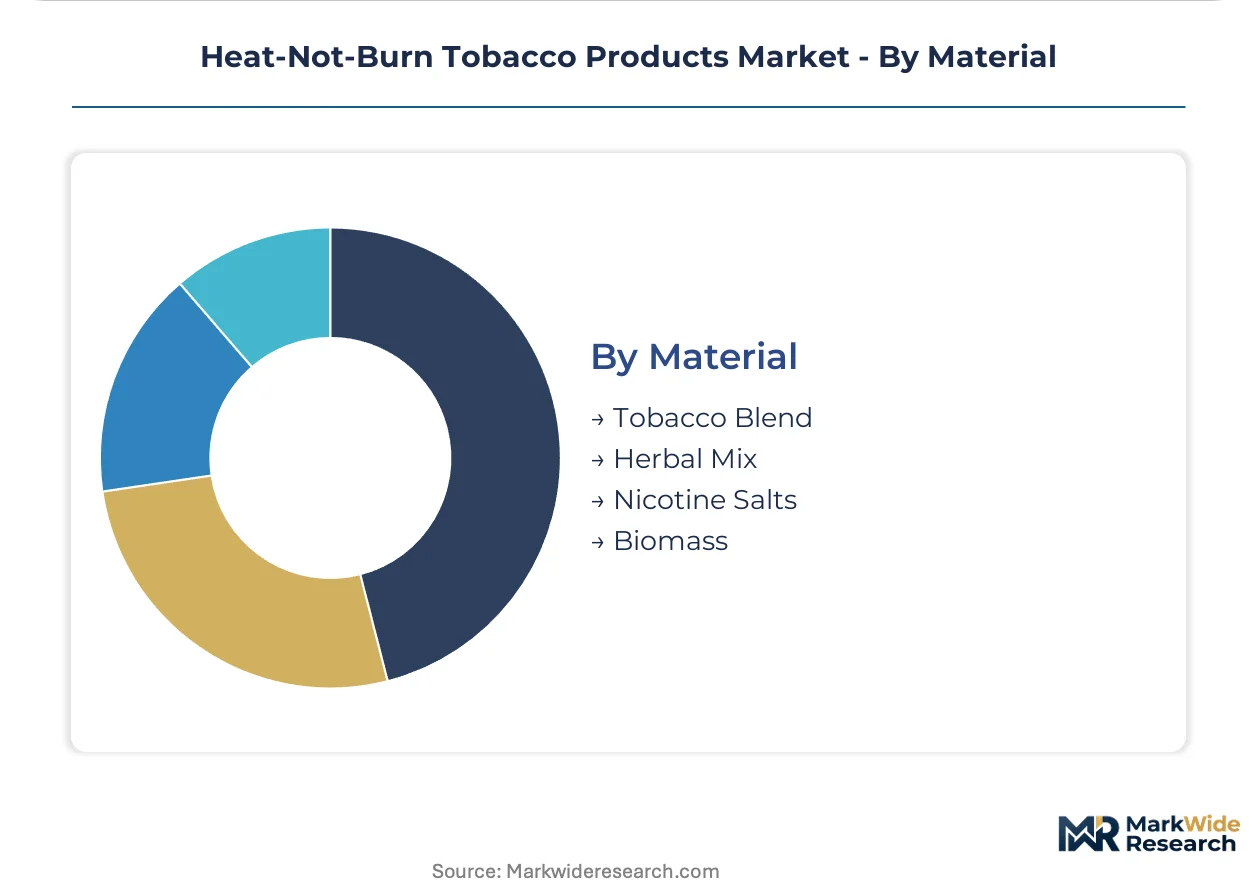
By unit volume, Tobacco Blend leads. By regulatory arbitrage opportunity, Herbal Mix is expanding most quickly in advertising-restricted jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan consumes heat-not-burn products as cigarette replacements with pharmacy-style retail access, while South Korean buyers prioritize device precision and temperature control. European markets treat these as smoking cessation aids with stricter labeling constraints. United States adoption hinges on FDA authorization pathways that limit reduced-harm messaging.
Japan
Adult smokers in Tokyo and Osaka drive consumable stick volumes through convenience store networks with flavor-optimized domestic variants. The Ministry of Health, Labour and Welfare maintains pharmaceutical-style oversight enabling broader reduced-risk claims than most jurisdictions. Metropolitan retail clusters in Kanto and Kansai regions sustain the highest per-capita device penetration globally.
South Korea
Seoul's temperature-control-sensitive users pay premium pricing for hybrid heating precision within 5°C variance across consumption cycles. The MFDS regulates reduced-risk claims through clinical evidence submission requirements. Daegu-Gyeongbuk industrial corridors host manufacturing facilities supplying domestic and export markets.
United Kingdom
Adult smokers aged 35-50 in London prioritize device longevity through unbundled after-sales service models at specialist vape shops. The Medicines and Healthcare products Regulatory Agency oversees pharmacy channel pilot programs for smoking cessation referrals. Midlands and North England retail chains generate volume through promotional stick bundling.
Germany
Wholesale distributors across federal states aggregate multi-brand procurement leverage for independent retailers in Berlin and Munich. The EU Tobacco Products Directive imposes standardized warning requirements limiting reduced-harm messaging flexibility. Bavaria and North Rhine-Westphalia concentrate retail display allowances from competing manufacturers.
Italy
Cross-border sales restrictions from EU Tobacco Products Directive implementations constrain promotional flexibility in Rome and Milan retail environments. Adult smokers access devices through tobacconist networks with bundled multi-pack promotions. Northern industrial regions supply aftermarket accessories to Central European distribution networks.
Heat-Not-Burn Tobacco Products Market Competitive Landscape
Capability concentration sits with technology-integrated conglomerates; scale advantage sits with national tobacco monopolies and diversified multinationals. The market structures around three tiers: platform ecosystem owners with recurring consumable revenue, device manufacturers supplying private-label hardware, and component specialists focused on heating element precision. Competitive moves center on ecosystem lock-in engineering through proprietary stick geometries and aggressive device subsidy programs to capture installed base.
Within the platform ecosystem tier, Philip Morris International and British American Tobacco PLC exemplify integrated hardware-consumable strategies. KT&G Corporation occupies a position bridging domestic market specialization with regional export expansion. These three represent divergent archetypes: the first anchors premium-tier temperature precision, the second leverages European retail channel density, and the third concentrates on flavor localization for East Asian metropolitan demand.
| Leading Market Players |
|---|
| KT&G Corporation |
| Altria Group, Inc. |
| Philip Morris International |
| Smoore International Holdings Limited |
| China National Tobacco Corporation |
| British American Tobacco PLC |
| Imperial Brands PLC |
| HEECHI Group |
| Japan Tobacco Inc. |
| Others |
Supply & Pricing Matrix
Regulatory chokepoint exposure at national authorization gateways determines both three-tier pricing spreads across premium, standard, and economy device tiers and supply chain regionalization strategies. Tobacco leaf input cost volatility and proprietary heating blade sourcing constraints compress margin pools differently across conduction and hybrid heating architectures.
Pricing Analysis
Long-term offtake contracts between manufacturers and flue-cured tobacco suppliers anchor consumable stick pricing, while spot-market ceramic blade procurement creates variance in device tier positioning. Price differentiation separates FDA-authorized premium platforms with clinical evidence packages from standard-tier EU-compliant systems and economy devices lacking reduced-harm certification. Pricing pressure stems from aggressive hardware subsidy programs in Tokyo and Seoul that delay consumable margin recovery. Retail chains in Germany and Italy demonstrate highest price sensitivity due to standardized warning requirements limiting promotional flexibility, while pharmacy channel buyers in the United Kingdom accept premium positioning for smoking cessation referral legitimacy.
Supply Chain Analysis
Export-control regimes on precision ceramic heating elements and induction coil technology limit component flows from Japanese and South Korean suppliers to assembly facilities in China and Vietnam. Manufacturing concentration centers on Japan, South Korea, and China for device assembly, with Italy and Poland serving European consumable stick production. Raw material dependencies include flue-cured tobacco from Brazil and Zimbabwe, ceramic substrates from Japanese specialty manufacturers, and lithium-ion cells for device power management. Single-source vulnerability in ceramic blade geometry tooling creates supply disruption risk for ecosystem-locked consumable formats. Distribution runs through wholesale distributors in Germany's federal state system, convenience retail networks in Japan, and direct-to-consumer e-commerce platforms in Switzerland and South Korea.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Heat-not-burn tobacco represents a high-growth disruption anchored by FDA modified risk authorization pathways that differentiate combustion-free systems from legacy cigarette categories. Temperature precision improvements and pharmaceutical-style regulatory frameworks are compressing product development cycles while expanding addressable smoker populations.
For Market Incumbents: Entrench ecosystem lock-in through proprietary heating blade geometries that complicate cross-platform consumable compatibility. Philip Morris International and British American Tobacco PLC should deepen captive tobacco leaf supply arrangements to offset flue-cured price volatility compressing stick margins. Defensive patent clustering around hybrid induction-conduction architectures protects against emerging temperature-control specialists in South Korea.
For New Entrants and Emerging Players: Southeast Asian markets outside Japan and South Korea offer underpenetrated demand where regulatory frameworks remain unsettled and local flavor preferences are underserved. Herbal mix variants circumvent advertising prohibitions in strict jurisdictions, creating shelf space access without competing directly against established tobacco-blend ecosystems. A pharmacy-channel pilot strategy in the United Kingdom leverages National Health Service smoking cessation referral credibility to bypass convenience retail gatekeeping.
For Investors and Strategic Acquirers: The market sits at a platform consolidation phase that favors consumable-recurring-revenue models with demonstrated regulatory authorization track records. Long-term viability over the next decade hinges on science-based reduced-harm claim durability rather than device hardware differentiation alone. Acquisition targets should demonstrate PMDA-equivalent regulatory dossier alignment and temperature precision IP portfolios. The signal to watch is MFDS and Taiwan FDA authorization timeline acceleration following Japanese clinical biomarker precedent.
| Strategic Initiative | Industry Significance |
|---|---|
| Modified Risk Authorization Pathway | FDA clearance enables legal reduced-exposure claims that differentiate platforms in pharmacy and convenience channels. |
| Hybrid Heating System Development | Induction-conduction precision within 5°C variance commands premium pricing in Seoul and Zurich metropolitan markets. |
| Herbal Mix Variant Expansion | Nicotine-free formulations circumvent EU Tobacco Products Directive advertising constraints in promotional-restricted jurisdictions. |
| Captive Tobacco Leaf Supply | Backward integration into Brazilian and Zimbabwean flue-cured sourcing insulates margin pools from commodity volatility. |
| Pharmacy Channel Pilot Programs | National Health Service smoking cessation referrals create distribution access beyond traditional tobacco retail gatekeepers. |
Research Methodology
A standing panel of regulatory affairs directors at heat-not-burn manufacturers, convenience retail category buyers in Tokyo and London, and Ministry of Health, Labour and Welfare compliance specialists provided ongoing calibration throughout the study period. Primary interviews with ceramic heating element engineers, tobacco blend formulation scientists, and wholesale distributors across Germany's federal state system combined with secondary validation from FDA modified risk tobacco product filings, EU Tobacco Products Directive national implementation texts, and MFDS clinical evidence submission guidelines. Bottom-up device and consumable volume builds triangulated against top-down manufacturer revenue disclosures and customs trade data for heatable stick components.
Scenario-bracketing around regulatory authorization timeline variance and temperature precision technology substitution rates anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, heating technology architecture, material composition, and end-user channel with geographic regulatory cluster overlays. CAGRs derived from installed base growth curves, consumable attachment rate trajectories, and authorized market expansion assumptions. Forecast inputs incorporated pharmaceutical-style oversight evidentiary requirements in Japan and South Korea, plus EU labeling constraint impacts on promotional elasticity.
Practitioners should monitor FDA authorization pathway expansion decisions, MFDS clinical biomarker study precedent adoption, and EU Tobacco Products Directive revision timelines for early signals requiring forecast reassessment. Material shifts in science-based regulatory differentiation between combustion-free and traditional tobacco products would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tobacco Products
Philippines E-Cigarette and Vape Market
Tobacco Products
E-Cigarette and Vaping Market
Tobacco Products
Japan Heated Tobacco Products Market
Tobacco Products
Middle East and Africa E-Cigarettes Market
Tobacco Products
E-Cigarettes and Vaporizer Market
Tobacco Products
Tobacco Products Market
Tobacco Products
Latin America E-Cigarette Market
Tobacco Products
Flavored Cigar Market
Tobacco Products
Europe E-Cigarettes Market
Tobacco Products
Smokeless Cigarettes Market
Tobacco Products
Luxury Cigarette Market
Tobacco Products
United States E-Cigarette Market
Tobacco Products
Cigarette Market
Tobacco Products
Handmade Cigars Market
Tobacco Products
US E-Cigarette and Vape Market
Tobacco Products
Global Flavor Capsule Cigarette Market