
 Handmade Cigars Market | 2026-2036
Handmade Cigars Market Size, Share, and Industry Trends Forecast 2026-2036
Handmade Cigars Market Insights
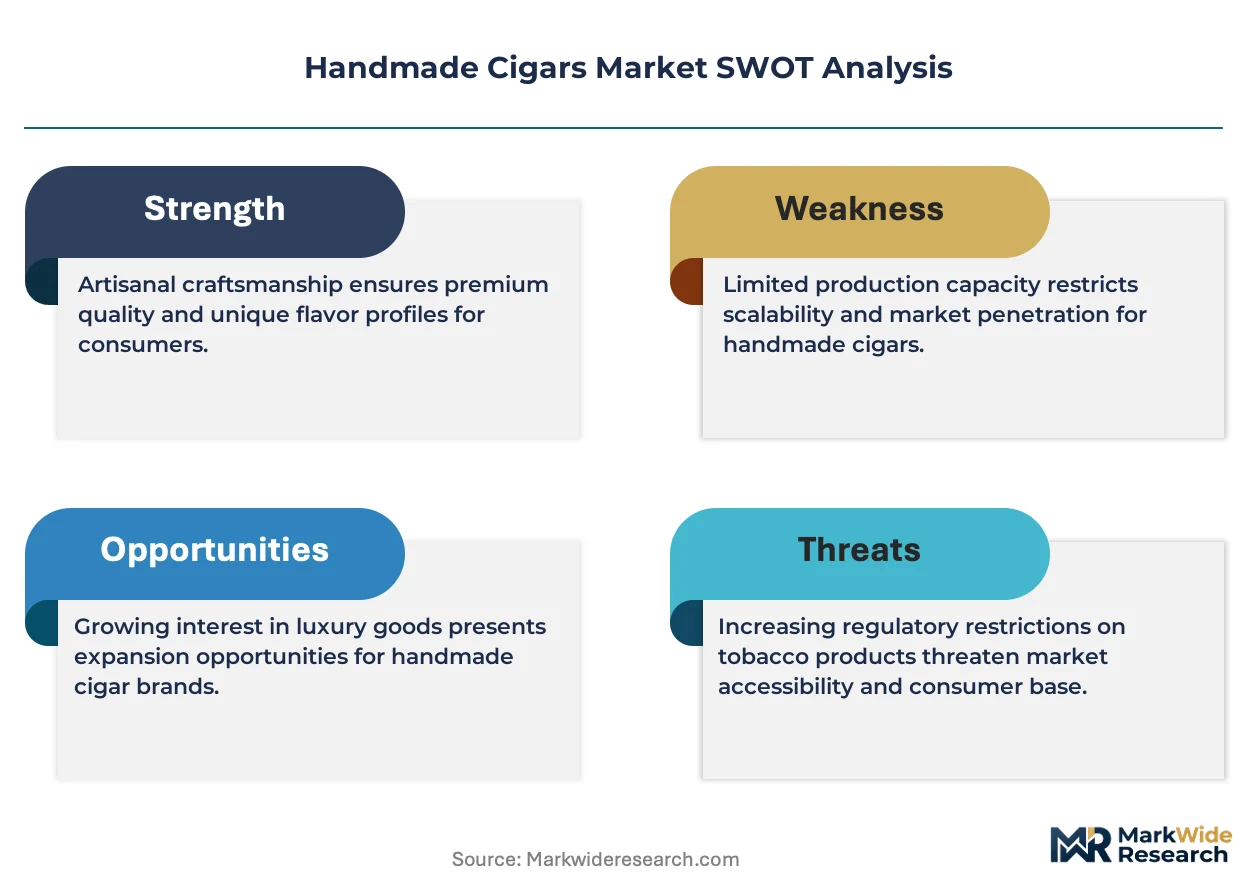
Specialty tobacco shop networks is fragmenting as online retailers and direct-to-consumer platforms capture share from traditional brick-and-mortar channels. Habanos leverages its state-controlled vertical structure to sustain exclusive geographic access for Cuban-origin products. Scandinavian Tobacco Group anchors its position through broad portfolio breadth across multiple price tiers and wrapper origins. Rocky Patel Premium Cigars differentiates via boutique positioning and limited-edition releases targeted at collector segments.
Handmade cigars consist of whole tobacco leaves selected, fermented, and rolled entirely by hand into a finished smoking product, with long-filler construction requiring binder and wrapper leaves that meet specific elasticity and combustion standards. The primary commercial purpose centers on premium consumption occasions where provenance, aging, and craftsmanship command price premiums. Long filler products dominate margin pools due to labor intensity and perceived authenticity, while Habano wrapper varieties capture growing share among enthusiasts seeking fuller-bodied flavor profiles. Specialty tobacco shops remain the structural anchor for discovery and brand education, though online retailers represent the fastest-growing access point for repeat purchases.
FDA tobacco product regulations impose substantial compliance burdens on new product introductions and manufacturing facility registrations for US-market participants. The EU Tobacco Products Directive and REACH frameworks govern labeling, ingredient disclosure, and cross-border sales channels for European distribution. Stakeholders must monitor evolving flavor restriction proposals and track how duty-free channel policies respond to shifting international travel patterns.
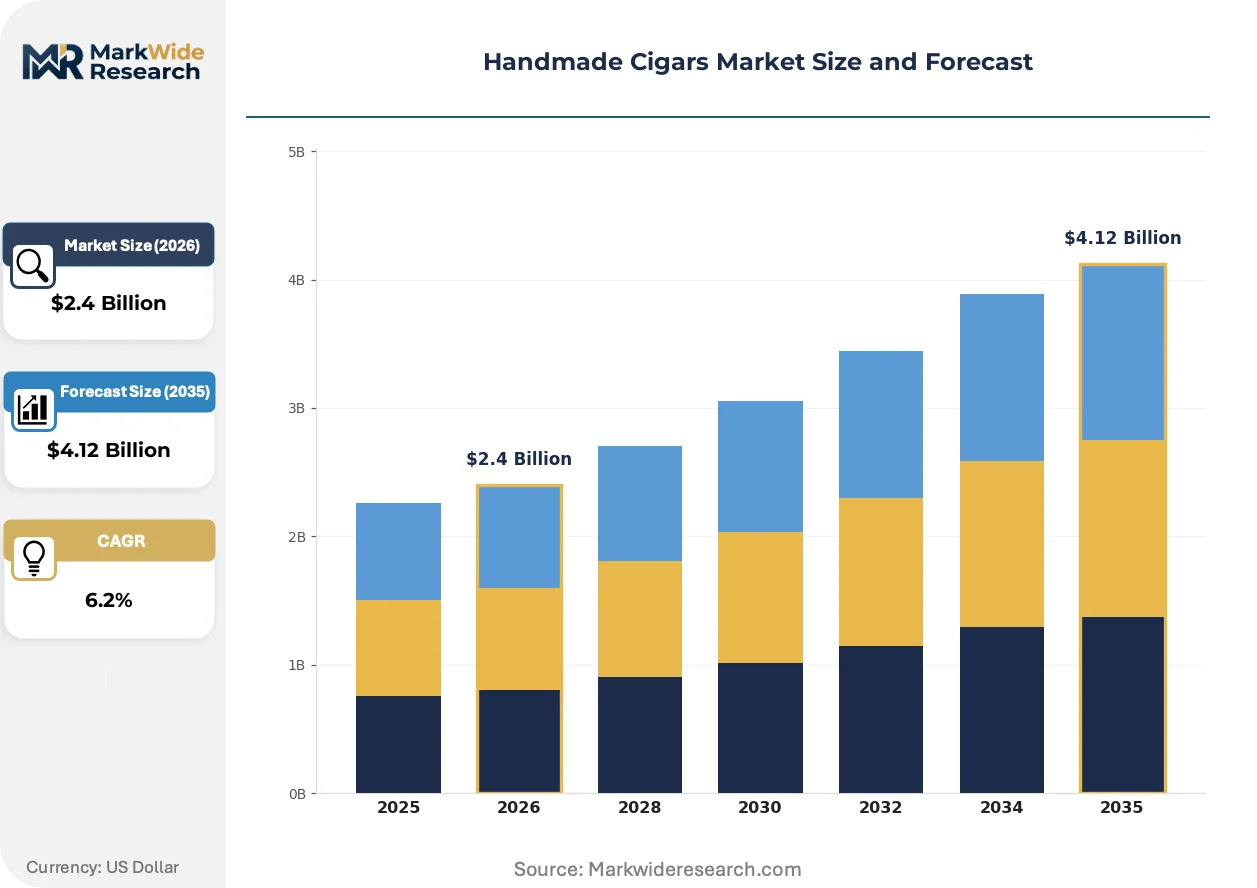
Market Dynamics
Volcanic soil concentration in Nicaragua's Estelí region anchors wrapper leaf supply, while FDA deeming rule compliance costs reshape product registration economics for US-market participants.
Growth Catalysts
- Estelí wrapper cultivation:Volcanic soil conditions in Nicaragua's primary growing zone sustain distinctive leaf characteristics that command collector premiums.
- EU Tobacco Products Directive:Standardized labeling and ingredient disclosure frameworks create regulatory clarity for cross-border distribution expansion.
- Premium lounge culture:North American hospitality venues cultivate high-frequency consumption occasions and direct brand education access.
Market Restraints
- Wrapper leaf supply concentration:Dependence on Estelí-region volcanic soil conditions creates single-point vulnerability for premium-grade binder and wrapper sourcing.
- FDA facility registration costs:Deeming rule compliance imposes substantial capital requirements on new manufacturing entrants and product line extensions.
- Combustible tobacco substitution:Heat-not-burn and vapor products capture occasion share among younger demographic cohorts seeking reduced-harm alternatives.
Strategic Opportunities
- Direct-to-consumer platforms:E-commerce channels bypass fragmented specialty retail networks to capture repeat purchase economics.
- REACH framework alignment:EU chemical compliance infrastructure enables standardized ingredient disclosure for premium export positioning.
- Aging cellar services:Humidity-controlled storage subscriptions extend collector engagement beyond initial purchase transactions.
Industry Challenges
- Master roller talent scarcity:Long-filler construction expertise requires multi-year apprenticeship pipelines that resist rapid workforce scaling.
- FDA product authorization timelines:Premarket tobacco application reviews extend 18-24 months, compressing innovation cycle returns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Handmade Cigars Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.12 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Long Filler, Short Filler, Hand Rolled, Machine Made Wrapper Type: Connecticut Shade, Habano, Maduro, Sumatra Distribution Channel: Specialty Tobacco Shops, Online Retailers, Convenience Stores, Duty-Free Shops Customer Segment: Cigar Enthusiasts, Casual Smokers, Collectors, Gifting |
| Companies Covered | Scandinavian Tobacco Group, Imperial Brands, Habanos, Altria Group, Swisher International, General Cigar Company, Arturo Fuente Cigar Company, Oliva Cigar, Rocky Patel Premium Cigars, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Handmade Cigars Market Trends and Innovations
Digital infrastructure is compressing traditional channel hierarchies while regulatory disclosure mandates and consumption occasion fragmentation reshape competitive positioning.
Sensor-enabled humidification systems is virtualizing traditional climate control for private collectors. High-net-worth enthusiasts in Miami and Dubai deploy IoT-enabled storage units that automate temperature and moisture regulation. This technology is virtualizing the role of brick-and-mortar lounge infrastructure for aging and preservation services.
REACH ingredient disclosure requirements are forcing granular supply chain documentation across European distribution channels. Manufacturers must map wrapper leaf fermentation additives and binder adhesives through tier-three suppliers. Small-batch producers in Nicaragua face disproportionate compliance burden relative to integrated conglomerates with captive laboratory resources.
Collector segmentation is fragmenting procurement patterns across auction-based and subscription channels. Limited-edition release allocations now bypass traditional specialty retailers through direct membership programs. This behavioral shift concentrates most visibly in California and Texas metropolitan markets where enthusiast density supports dedicated allocation models.
Handmade Cigars Market Segmentation
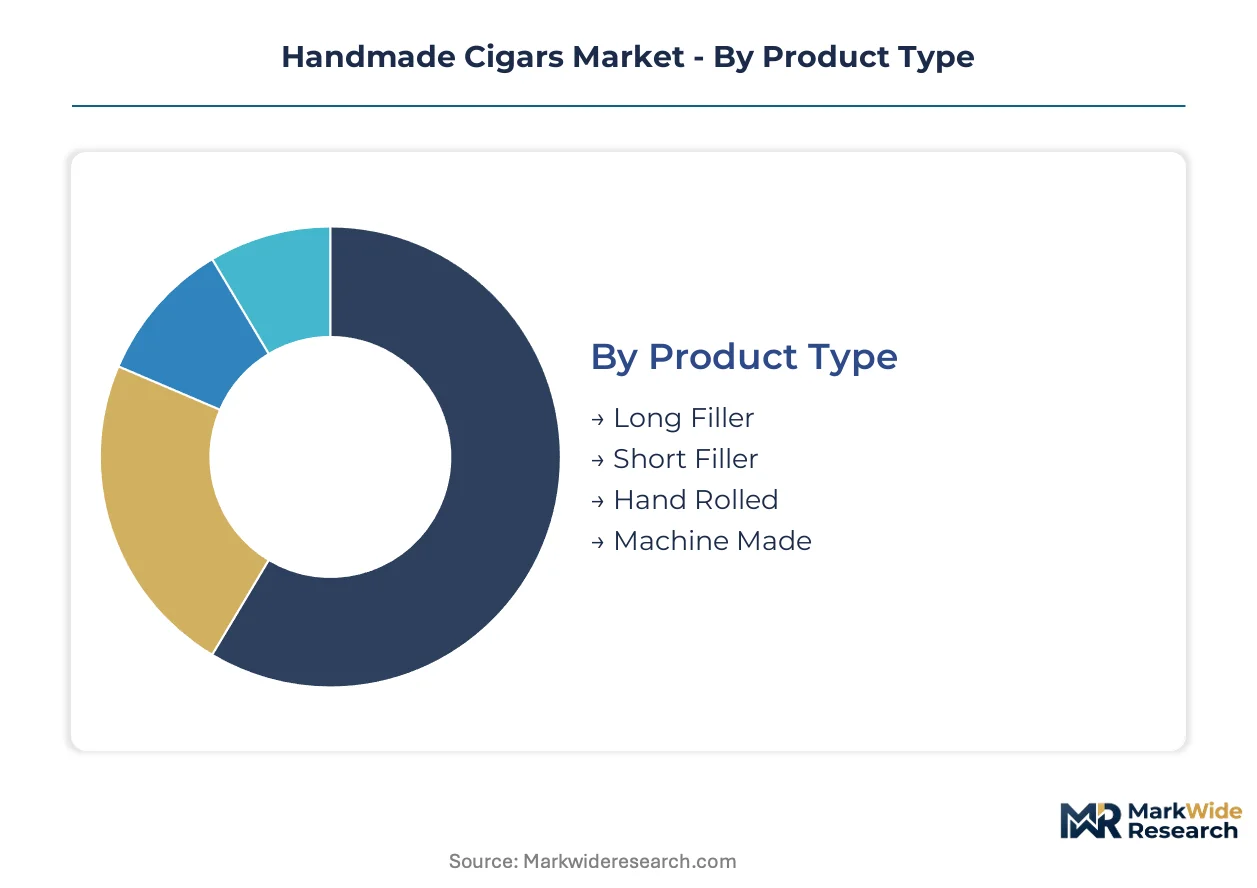
Segmentation in handmade cigars reveals how construction method, leaf origin, and purchase context stratify pricing power and customer lifetime value. Each dimension carries distinct inventory velocity profiles and margin structures that shape portfolio architecture decisions.
Product Type:
Cycle times vary dramatically across construction methods, with long-filler products aging for years while machine-made variants turn inventory weekly.
- Long Filler:Whole tobacco leaves run the full length of the cigar, requiring skilled hand-rolling and extended fermentation. Collector demand concentrates in Miami and Dubai lounges where aging programs justify price premiums above standard releases.
- Short Filler:Chopped tobacco scraps fill the body, enabling faster production and lower price points. Convenience store distribution in Texas and Florida drives volume turnover for impulse purchase occasions.
- Hand Rolled:Construction relies entirely on manual labor without mechanized assistance. Nicaragua's Estelí workshops supply the majority of skilled rollers for this labor-intensive category.
- Machine Made:Automated production delivers consistency at scale for price-sensitive segments. Duty-free channels in international airports capture traveler demand for standardized gift purchases.
Long Filler dominates installed base value. Short Filler is where expansion concentrates for accessible price-tier penetration.
Wrapper Type:
Leaf provenance drives cost tier stratification, with shade-grown varieties commanding cultivation premiums over sun-exposed alternatives.
- Connecticut Shade:Grown under cheesecloth tents to produce mild, smooth flavor profiles. New England collector circles favor this wrapper for morning smoking occasions and pairing with coffee.
- Habano:Cuban-seed varieties grown in Nicaragua's Jalapa Valley deliver full-bodied intensity. California metropolitan markets show strongest preference for this robust flavor profile among enthusiast segments.
- Maduro:Extended fermentation darkens the leaf and concentrates sweetness. Texas humidor subscriptions feature Maduro-forward curation for experienced palates seeking complexity.
- Sumatra:Indonesian-origin wrapper provides spicy, aromatic characteristics distinct from New World varieties. European distribution channels source this variety for flavor diversification in blended portfolios.
Connecticut Shade anchors premium-mid pricing tiers. Habano is climbing the fastest among collector segments seeking provenance differentiation.
Distribution Channel:
Channel selection determines customer acquisition cost and repeat purchase predictability across the ownership lifecycle.
- Specialty Tobacco Shops:Staff expertise enables discovery and education for new enthusiasts. These physical locations sustain brand relationships through lounge access and event programming in Chicago and Houston.
- Online Retailers:E-commerce platforms bypass geographic constraints to capture subscription and bulk purchase economics. Inventory breadth and price transparency attract repeat buyers with established preferences.
- Convenience Stores:Impulse accessibility drives trial for machine-made and short-filler products. Florida's tourist corridors generate high foot traffic for travel-sized formats.
- Duty-Free Shops:International airport locations capture gifting demand from business travelers. REACH labeling compliance enables standardized European packaging for cross-border consistency.
Specialty Tobacco Shops dominate high-value customer relationships. Online Retailers is where expansion concentrates for scalable repeat purchase capture.
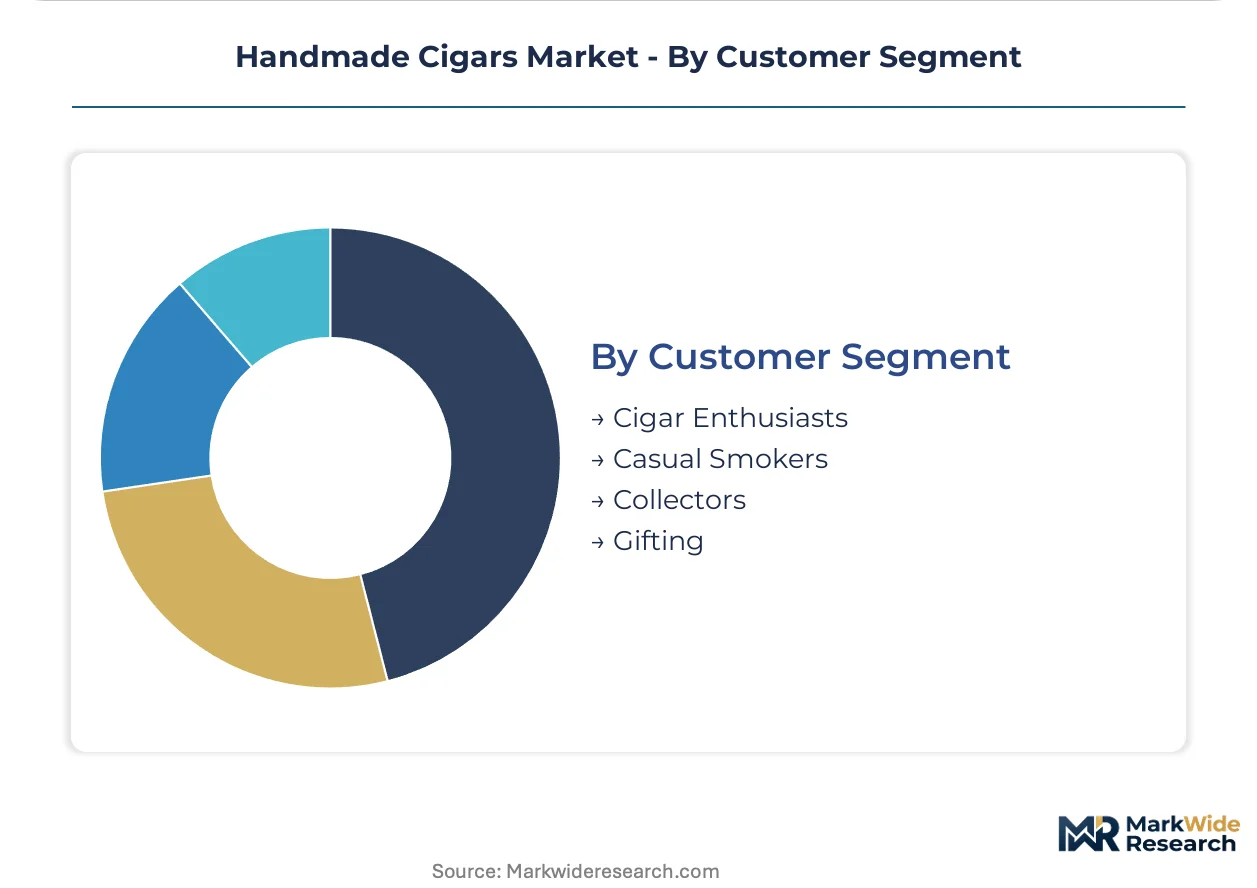
Customer Segment:
Behavioral differentiation in purchase frequency and price sensitivity shapes targeted service model investments.
- Cigar Enthusiasts:High-knowledge consumers pursue limited releases and vintage acquisitions. Aging cellar services and direct allocation programs secure loyalty among this high-spending cohort.
- Casual Smokers:Occasional consumption drives preference for accessible price points and reliable availability. Convenience-oriented channels capture this segment's lower engagement requirements.
- Collectors:Speculative acquisition of rare and limited editions treats cigars as appreciating assets. Auction platforms and private membership programs serve this investment-motivated behavior.
- Gifting:Purchase decisions prioritize presentation and brand recognition over personal taste knowledge. Holiday seasons and corporate occasions concentrate demand in premium packaging formats.
Cigar Enthusiasts dominate current revenue contribution. Collectors is where expansion concentrates for highest-margin transaction growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price premiums in Miami lounges exceed equivalent transactions in Madrid by 40-60%, reflecting divergent taxation regimes and collector density asymmetries between US and European consumption nodes.
United States
Premium lounge culture concentrates in Miami, Los Angeles, and Houston, where aging programs and private membership clubs sustain collector price premiums. FDA deeming rule compliance costs reshape product registration economics, with premarket tobacco application timelines extending 18-24 months. Estelí-sourced Habano wrappers dominate California metropolitan markets, where enthusiast density supports direct allocation bypassing traditional retail.
Germany
Specialty tobacco shop networks in Hamburg and Cologne anchor continental European discovery and brand education infrastructure. EU Tobacco Products Directive labeling mandates and REACH chemical disclosure frameworks govern cross-border distribution compliance. Bavaria's affluent consumer base drives premium-mid segment concentration, with Maduro-forward curation gaining share among experienced palates.
Spain
Andalusian and Madrid-based lounges cultivate high-frequency consumption occasions, leveraging proximity to North African sourcing corridors. ECHA registration requirements for wrapper leaf fermentation additives impose documentation burdens on Nicaraguan import channels. Barcelona's hospitality sector experiments with sensor-enabled humidification systems for private collector cellars.
United Arab Emirates
Dubai's duty-free channel captures business traveler gifting demand, with standardized packaging formats optimized for international airport retail. MOHAP tobacco product standards govern import authorization and ingredient disclosure for premium positioning. The emirate's luxury hospitality sector deploys IoT-enabled climate control for high-net-worth enthusiast aging programs.
Switzerland
Geneva and Zurich specialty retailers serve as cross-border access points for EU collector segments seeking Swissmedic-compliant product variants. REACH framework alignment enables standardized ingredient documentation for premium export positioning. The country's private banking infrastructure supports speculative cigar acquisitions as alternative asset class allocations.
Handmade Cigars Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in wrapper cultivation and master roller talent pools. The vendor base organizes around three archetypes: state-controlled verticals with exclusive geographic access, diversified conglomerates spanning multiple price tiers and wrapper origins, and boutique specialists targeting collector segments through limited-edition releases. Consolidation pressure operates through strategic partnerships with Estelí-region cultivation operations and direct-to-consumer platform development rather than horizontal merger activity.
Within the state-controlled vertical tier, Habanos occupies a position exemplifying exclusive geographic access architecture for Cuban-origin products. Scandinavian Tobacco Group anchors diversified portfolio breadth across multiple price tiers and wrapper origins. Rocky Patel Premium Cigars represents boutique specialist positioning, targeting collector segments through limited-edition release strategies. These three archetypes illustrate how competitive differentiation maps to supply chain control depth versus market access breadth tradeoffs.
| Leading Market Players |
|---|
| Scandinavian Tobacco Group |
| Imperial Brands |
| Habanos |
| Altria Group |
| Swisher International |
| General Cigar Company |
| Arturo Fuente Cigar Company |
| Oliva Cigar |
| Rocky Patel Premium Cigars |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Nicaragua's master roller workforce constrains premium long-filler output, forcing manufacturers to ration limited-edition allocations while elevating configured-to-order pricing premiums above standard releases. This labor bottleneck cascades through distributor markups and collector auction dynamics.
Pricing Analysis
The customization-premium spread between configured-to-order limited editions and standard catalog releases now exceeds three-to-one in Miami and Dubai lounge markets. Three-tier pricing structure across premium, standard, and economy levels stratifies by wrapper provenance and aging duration, with Habano-wrapper collector editions commanding the widest spreads. Cost compression in the standard tier is intensifying because FDA facility registration fees amortize poorly across lower-volume product lines. Casual smokers show highest price sensitivity, while collectors treat allocation scarcity as an asset-appreciation signal.
Supply Chain Analysis
Supplier-financing terms from Estelí-region tobacco growers now extend to 120 days for boutique manufacturers lacking captive working capital. Geographic supply concentration in Nicaragua, Honduras, and the Dominican Republic draws from volcanic soil corridors and established fermentation infrastructure. Binder leaf, wrapper seed stock, and cedar aging boxes constitute critical input dependencies. Single-source vulnerability in Estelí wrapper cultivation threatens continuity during climate disruption years. Distribution runs through fragmented specialty retail networks, direct-to-consumer platforms, and duty-free airport channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Master roller apprenticeship pipelines require seven-year development cycles, creating a structural bottleneck that rewards firms securing talent early and punishing late entrants. This scarcity dynamic favors incumbents with established training infrastructure.
For Market Incumbents: Harden master roller retention through captive apprenticeship programs in Estelí and Jalapa Valley workshops. Deepen backward integration into wrapper leaf fermentation facilities to secure supply continuity against climate volatility. Channel control through direct-to-consumer platforms defends margin position against online retailer price transparency. For New Entrants and Emerging Players: Pursue aging cellar subscription services as a white-space target, where humidity-controlled storage contracts convert one-time buyers into recurring revenue streams. The most penetrable segment sits among Texas and California enthusiasts seeking provenance documentation without lounge membership overhead. A go-to-market angle pairing sensor-enabled humidification hardware with curated leaf sourcing bypasses traditional retail gatekeepers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among boutique specialists with established direct allocation programs and aging cellar subscriptions. Long-term viability over the five-to-ten year horizon hinges on regulatory navigation capacity and Estelí-region cultivation access. Acquisition targets should demonstrate FDA premarket tobacco application experience and REACH compliance infrastructure. The signal to watch is FDA product authorization timeline compression or expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Master Roller Apprenticeship Expansion | Seven-year training pipelines in Estelí secure long-filler construction expertise against talent scarcity. |
| Direct-to-Consumer Platform Launch | Bypasses fragmented specialty retail networks to capture repeat purchase economics and customer data. |
| Aging Cellar Subscription Service | Humidity-controlled storage contracts extend collector engagement beyond initial transaction value. |
| REACH Compliance Infrastructure Investment | Granular supply chain documentation enables standardized European export positioning under ECHA frameworks. |
| Wrapper Leaf Fermentation Facility Acquisition | Captive processing capacity insulates against single-source vulnerability in Estelí volcanic soil corridors. |
Research Methodology
A standing panel of master rollers, specialty tobacco shop proprietors, import compliance officers, and collector community organizers provided ongoing calibration throughout the study. Primary interviews with Nicaraguan cultivation operations and US-based lounge operators combined with secondary validation from FDA premarket tobacco application databases, ECHA REACH registration filings, and customs import records. Bottom-up volume estimates from Estelí-region production capacity triangulated against top-down demand modeling from specialty retail point-of-sale data.
Scenario-bracketing framed the analytical approach, with baseline, upside, and downside cases tested across the projection horizon. Segmentation dimensions modeled include construction method, wrapper origin, distribution channel, and customer behavioral archetype. CAGRs derived from elasticity-adjusted demand curves incorporating collector price sensitivity and regulatory compliance cost pass-through assumptions. Industry-specific forecast inputs encompass master roller workforce development rates and FDA product authorization queue lengths.
Macroeconomic conditions sit as an overlay; deviation in discretionary luxury spending indices, international travel recovery patterns, or tobacco excise tax trajectories would shift the trajectory. Forecasts reflect documented assumptions about regulatory stability and climate patterns in Central American growing regions. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tobacco Products
Global Flavor Capsule Cigarette Market
Tobacco Products
Africa Tobacco Products Market
Tobacco Products
Roll-Your-Own Tobacco Products Market
Tobacco Products
United States E-Cigarette Market
Tobacco Products
Tobacco Pouch Market
Tobacco Products
Heat-Not-Burn Tobacco Products Market
Tobacco Products
Homemade Cigars Market
Tobacco Products
Latin America E-Cigarette Market
Tobacco Products
Premium Cigarette Market
Tobacco Products
Europe E-Cigarettes Market
Tobacco Products
Global Cigarette Vending Machine Market
Tobacco Products
Cigar Tubes Market
Tobacco Products
Premium Tobacco Products Market
Tobacco Products
Global Smokeless Tobacco Market
Tobacco Products
West Africa Cigarettes Market
Tobacco Products
Liquor Flavored Cigars Market