
 Cricket Bowling Machine Market | 2026-2036
Cricket Bowling Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Cricket Bowling Machine Market Analysis
CE marking under the EU Machinery Directive is decoupling entry costs for European vendors from low-cost Asian competitors. Bola Manufacturing Limited leverages in-house casting capabilities to sustain margin control across its pneumatic machine range. Leverage Science and Technologies Limited anchors its position through sensor-based digital systems that compete on programmable delivery variation rather than price alone.
A cricket bowling machine is an electromechanical or fully automated device designed to propel cricket balls at calibrated speeds, spin rates, and trajectories for batting practice, typically employing pneumatic wheels, spring-loaded arms, or motorized throwing mechanisms. Electric machines occupy the dominant revenue tier due to their programmable speed and swing parameters, while portable units represent the fastest-growing configuration as academies and schools prioritize transportable training infrastructure. Digital technology segments command premium positioning through app-integrated analytics, whereas analog mechanized variants retain volume share in price-sensitive institutional procurement across South Asia and the Caribbean.
BIS certification requirements in India and CE marking obligations in Europe collectively elevate compliance expenditure for new entrants, effectively filtering substandard imports from informal supply channels. The UK's Health and Safety Executive and Australia's state-level workplace safety regulators enforce operational guarding standards that shape machine enclosure design and motor housing specifications. Stakeholders must monitor evolving sensor calibration protocols and emerging AI-driven ball-tracking integrations that will determine next-generation product differentiation.
Market Dynamics
Sensor-based digital bowling machines are compressing replacement cycles as academies discard analog pneumatic units for programmable systems with ball-tracking analytics. This technology displacement is restructuring procurement priorities across institutional buyers in South Asia and Australia.
Growth Catalysts
- Franchise league infrastructure investment:Indian Premier League and Big Bash League franchises are funding academy upgrades with mechanized training equipment, creating sustained institutional demand for premium digital machines.
- BIS certification enforcement:India's Bureau of Indian Standards mandatory compliance for sports equipment imports is filtering substandard competitors and elevating quality thresholds for formal procurement channels.
- Pneumatic wheel advancement:Improved polyurethane composite wheel materials now deliver spin variation accuracy within 3% tolerance, matching professional match conditions for elite player development programs.
Market Restraints
- Aluminum alloy input volatility:Casting-grade aluminum price swings directly compress machine housing production margins, particularly affecting pneumatic wheel chassis manufacturing.
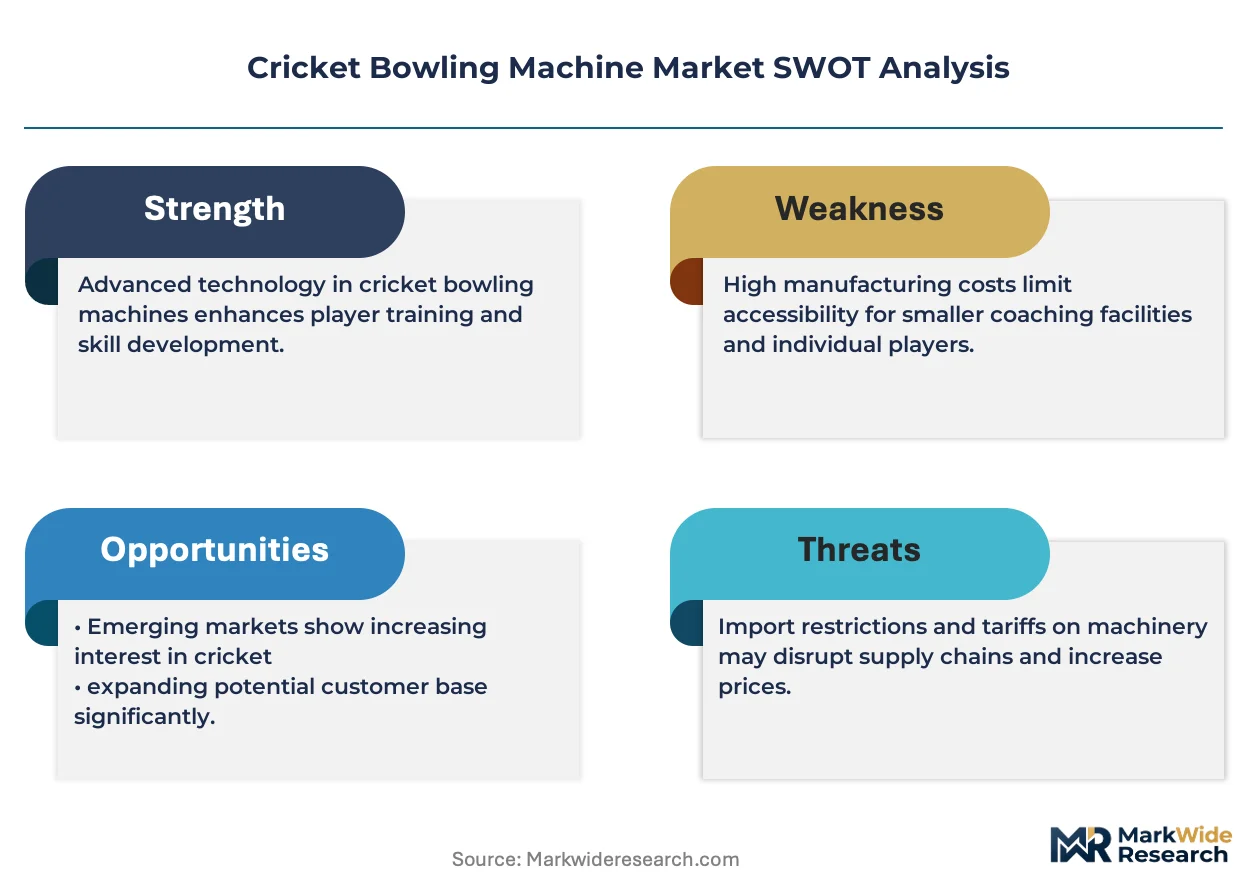
- CE marking compliance burden:European Machinery Directive certification costs exceed $15,000 per SKU variant, blocking informal Asian manufacturers from EU institutional tenders.
- Manual thrower substitution:Human bowling partners remain prevalent in Caribbean and African markets where labor costs undercut mechanized capital expenditure.
Strategic Opportunities
- Tier-2 Indian city penetration:Nagpur, Indore, and Jaipur cricket academies currently operate below 15% mechanization rates, presenting whitespace for mid-range electric machine deployment.
- AI-ball tracking convergence:Integration of Hawk-Eye trajectory analysis with machine programming enables personalized batting drill customization, commanding 40% price premiums over base digital units.
- Rental channel emergence:Equipment-as-a-service models through regional sports distributors are lowering upfront barriers for school and club buyers in Bangladesh and Sri Lanka.
Industry Challenges
- Sensor calibration technician scarcity:Digital machine maintenance requires specialized electro-mechanical skills that training institutes in South Asia have not yet scaled to match installation volumes.
- Legacy analog inventory stranding:Academy operators face write-down pressure on pre-2020 pneumatic machines with limited software upgrade paths, complicating trade-in program design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cricket Bowling Machine Market |
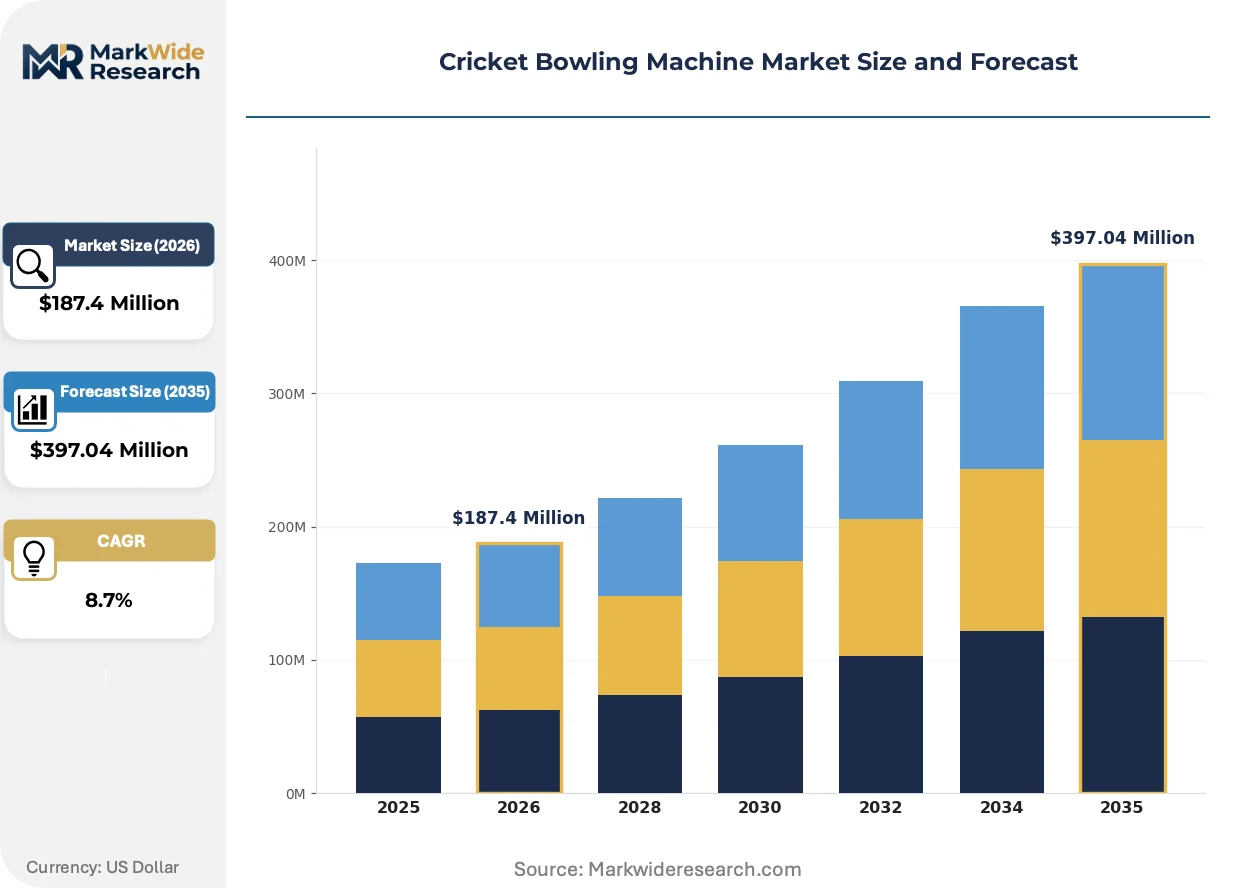
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Machines, Manual Machines, Portable Machines, Full-Automatic Machines Technology: Analog, Digital, Sensor-Based, Mechanized End User: Academies, Professional Teams, Recreational Players, Schools Distribution Channel: Online Retail, Offline Stores, Direct Sales, Distributors |
| Companies Covered | Dimension Sport UK Limited, Flicx, Bola Manufacturing Limited, Ajaib Enterprises LLP, Ha-Ko Group, Leverage Science and Technologies Limited, Keith Dudgeon Cricket Specialist, Kanon Cricket & Tennis Ball Machines, JUGS Sports, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cricket Bowling Machine Market Emerging Trajectories
Machine intelligence and connected analytics are displacing standalone mechanical units as the baseline expectation in professional training environments. This shift is redefining vendor capability requirements and buyer evaluation criteria simultaneously.
Computer vision ball-tracking is automating swing and seam delivery programming by analyzing release point data in real-time. Elite academies in Mumbai and Sydney are adopting these systems within 18-month replacement windows. The technology is automating coach intervention in drill design, compressing the skill transfer timeline from machine operator to batsman.
Australia's state-level workplace safety regulators are mandating enclosed ball-feed guarding and emergency stop integration under updated machinery operation codes. This elevates enclosure engineering costs for all market entrants. Portable machine configurations face the steepest redesign burden, as compact form factors complicate guard integration without weight penalties.
Academy procurement committees now unbundle after-sales service from equipment purchase, negotiating separate multi-year maintenance contracts with third-party technical providers. This fragments the traditional single-vendor relationship model. The practice is most visible in England's county cricket network, where centralized purchasing consortia drive service commoditization.
Cricket Bowling Machine Market Segmentation
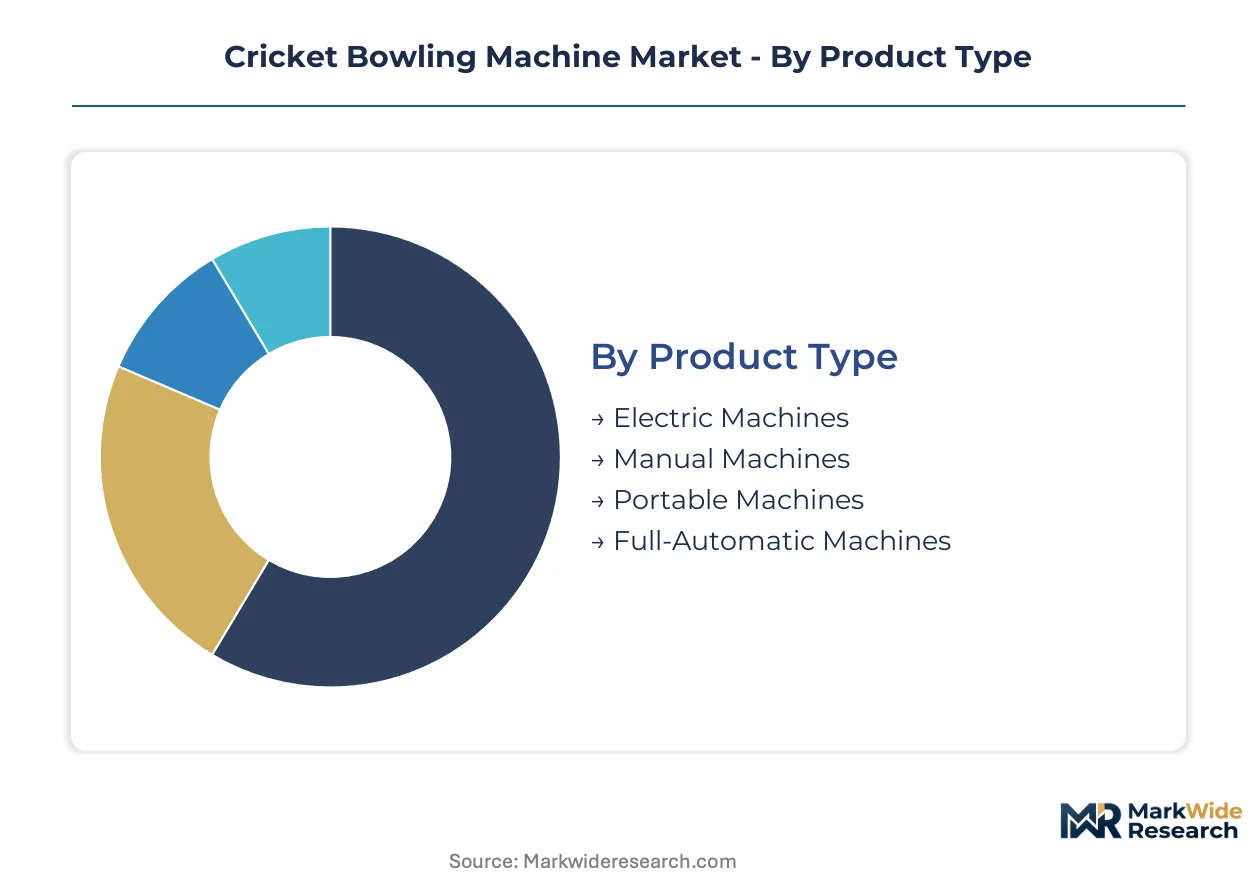
Cricket bowling machine procurement splits sharply across certification tiers, with BIS-mandated segments commanding formal channel premiums while uncertified analog variants circulate through informal supply routes. Machine intelligence and portability are redefining how academies, schools, and recreational buyers allocate capital across training infrastructure.
Product Type:
BIS certification in India and CE marking in Europe impose divergent compliance burdens across product categories, filtering entry for pneumatic chassis designs while accelerating digital electric variants through formal procurement channels.
- Electric Machines:Programmable speed and swing parameters define this segment through motorized wheel or pneumatic propulsion systems. Indian Premier League franchise academies and Cricket Australia high-performance centers concentrate procurement here, driven by programmable delivery variation requirements for elite player development.
- Portable Machines:Compact form factors with collapsible frames and battery power options enable transport between training venues. Schools in Bangladesh and Sri Lanka prioritize this configuration as rental channel penetration lowers upfront capital barriers for institutional buyers.
- Manual Machines:Spring-loaded or lever-operated mechanisms without electrical components. Recreational players and budget-constrained clubs in Caribbean markets favor these units where labor costs undercut mechanized alternatives.
- Full-Automatic Machines:Integrated ball-feed systems with programmable sequence delivery. Elite academies in Mumbai and Sydney deploy these for unsupervised batting drill automation.
Electric machines sit at the top of the volume ranking, with portable machines climbing the fastest.
Technology:
Cost stratification across technology tiers mirrors the capability gap between legacy mechanical systems and connected analytics platforms, with sensor calibration requirements driving maintenance contract bundling.
- Sensor-Based:Real-time ball-tracking integration with programmable trajectory adjustment. Australian state academies and Indian franchise facilities are displacing analog units within compressed replacement cycles, compelled by Hawk-Eye convergence for personalized drill customization.
- Digital:App-integrated control interfaces with stored delivery profiles. Mid-tier academies in Nagpur, Indore, and Jaipur represent concentrated demand as mechanization rates in these cities remain below penetration thresholds.
- Analog:Mechanical speed and angle adjustment without software interface. Price-sensitive institutional procurement across South Asia and the Caribbean retains volume share here despite limited upgrade paths.
- Mechanized:Motorized propulsion without digital programming capability. Legacy inventory in pre-2020 installations faces write-down pressure as academies confront stranded asset risk.
Sensor-based systems command the premium tier, while digital platforms are expanding most quickly through mid-market academy procurement.
End User:
Application intensity varies dramatically across user categories, with professional programs demanding programmable variation while schools prioritize durability and simplified operation protocols.
- Academies:Structured training facilities with dedicated coaching staff and scheduled player development programs. BIS-certified equipment procurement dominates here as formal channel compliance filters substandard imports from institutional tenders.
- Professional Teams:Franchise-owned high-performance centers with sports science integration. These buyers unbundle after-sales service from equipment purchase, negotiating separate multi-year maintenance contracts with third-party technical providers.
- Schools:Physical education departments and extracurricular cricket programs. Rental channel emergence through regional sports distributors is lowering upfront barriers for this buyer segment in Bangladesh and Sri Lanka.
- Recreational Players:Individual enthusiasts and informal club arrangements. Manual thrower substitution remains prevalent here where capital expenditure constraints exceed mechanized training value perception.
Academies generate the dominant procurement volume, with professional teams driving the steepest technology upgrade trajectory.
Distribution Channel:
Channel selection correlates directly with buyer sophistication and service requirements, fragmenting the traditional single-vendor relationship model across institutional procurement.
- Direct Sales:Manufacturer-led engagement with academy procurement committees and franchise technical directors. England's county cricket network exemplifies this channel through centralized purchasing consortia.
- Distributors:Regional sports equipment specialists with technical service capabilities. These intermediaries are capturing equipment-as-a-service model growth in emerging South Asian markets.
- Online Retail:E-commerce platforms with standardized product listings and limited technical consultation. Recreational players and small clubs access entry-level portable units through this channel.
- Offline Stores:Physical retail with demonstration and basic maintenance support. Schools and municipal buyers in tier-2 Indian cities rely on tactile evaluation before capital commitment.
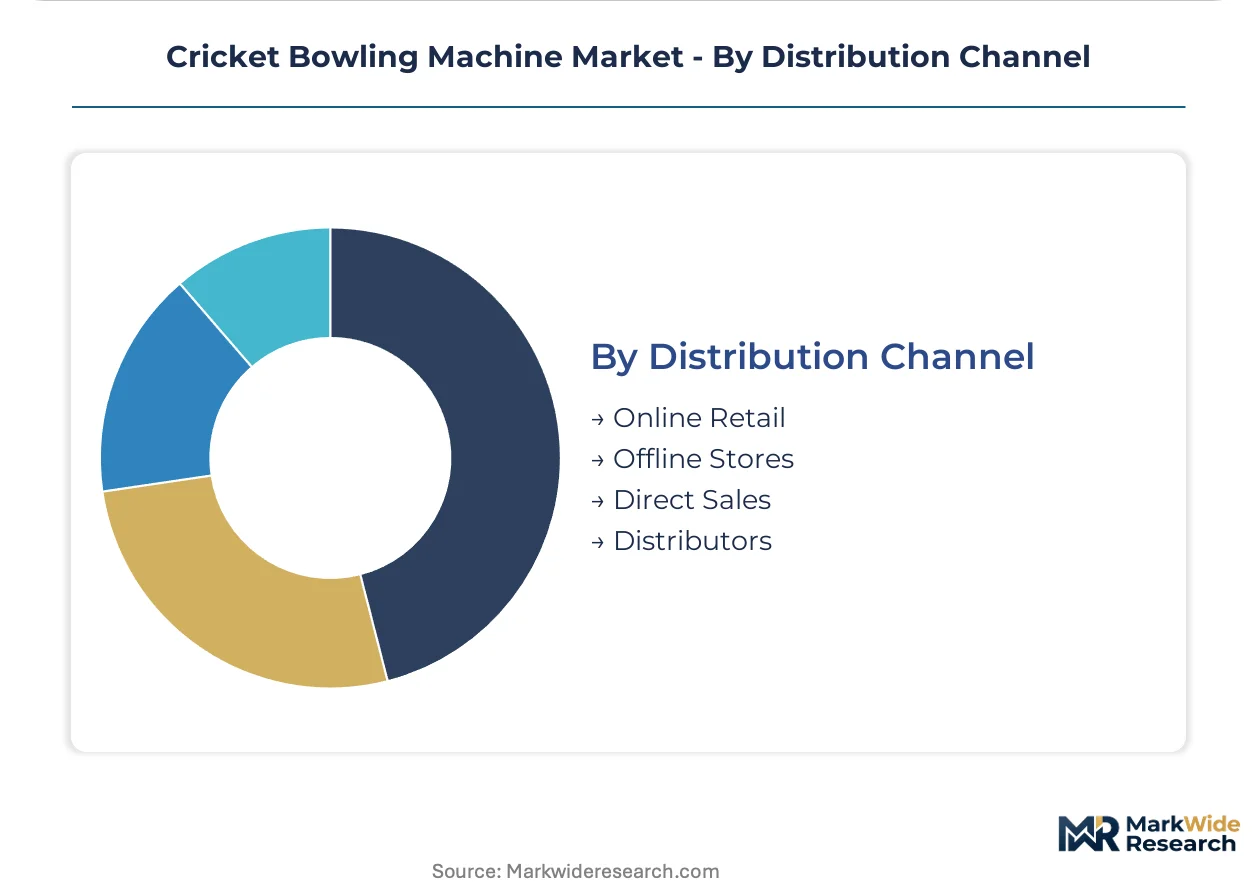
Direct sales anchor the revenue ranking, with distributor networks gaining share fastest through service-integrated positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coaching talent clusters in India and Australia anchor regional demand concentration, with academy networks in both countries driving mechanized training infrastructure procurement. European markets filter entry through CE marking compliance, while South Asian franchise leagues fund facility upgrades that reshape equipment specifications. Sub-regional variations reflect divergent certification burdens and institutional buyer sophistication.
India
Franchise league academies in Mumbai and Delhi-NCR deploy sensor-based systems for elite player development, compressing replacement cycles for legacy pneumatic units. BIS certification enforcement under the Bureau of Indian Standards mandatory compliance regime filters substandard imports from formal procurement channels. Nagpur, Indore, and Jaipur cricket academies operate below mechanization thresholds, presenting whitespace for mid-range electric machine penetration.
Australia
State-level workplace safety regulators mandate enclosed ball-feed guarding and emergency stop integration under updated machinery operation codes. Cricket Australia high-performance centers concentrate procurement in programmable digital systems with Hawk-Eye trajectory convergence. Sydney and Melbourne academies adopt computer vision ball-tracking within 18-month replacement windows, automating coach intervention in drill design.
United Kingdom
County cricket network centralized purchasing consortia unbundle after-sales service from equipment acquisition, negotiating separate multi-year maintenance contracts. CE marking under the EU Machinery Directive elevates enclosure engineering costs for all market entrants. England's academy infrastructure prioritizes portable configurations with collapsible frames for transport between training venues.
Bangladesh
School physical education departments drive rental channel emergence through regional sports distributors lowering upfront capital barriers. Equipment-as-a-service models penetrate institutional buyer segments previously excluded from mechanized procurement. Dhaka-based academy operators balance durability requirements against simplified operation protocols for non-specialized coaching staff.
Sri Lanka
Colombo cricket academies prioritize battery-powered portable units enabling transport between municipal training grounds. Regional distributor networks capture service-integrated positioning through technical capability investments. Galle and Kandy sub-regional markets remain underpenetrated relative to capital concentration in the Western Province corridor.
Cricket Bowling Machine Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across certification-tiered market strata. The vendor base separates into three strategic archetypes: in-house casting specialists controlling pneumatic chassis production, sensor-integrated digital platform developers, and regional assembly operations serving price-sensitive institutional procurement. Competitive moves concentrate on geographic expansion through distributor partnerships and portfolio diversification into rental service models.
Among UK-based fabricators, Dimension Sport UK Limited and Bola Manufacturing Limited exemplify the casting-capability archetype, while Leverage Science and Technologies Limited anchors the sensor-based digital systems tier. These three entities occupy positions spanning pneumatic heritage and programmable analytics convergence, reflecting the technology displacement restructuring procurement priorities across South Asian and Australian academy networks.
| Leading Market Players |
|---|
| Dimension Sport UK Limited |
| Flicx |
| Bola Manufacturing Limited |
| Ajaib Enterprises LLP |
| Ha-Ko Group |
| Leverage Science and Technologies Limited |
| Keith Dudgeon Cricket Specialist |
| Kanon Cricket & Tennis Ball Machines |
| JUGS Sports |
| Others |
Supply Flow & Price Mechanics
Sensor-based digital bowling machine adoption simultaneously compresses replacement cycles and concentrates supply power among vendors with in-house calibration capabilities. This technology transition elevates cost structures for polyurethane composite wheel sourcing while filtering price-sensitive competitors from formal procurement channels in India and Australia.
Pricing Analysis
The bundled-vs-unbundled service split now defines transaction architecture across institutional procurement. Three-tier pricing structure across premium, standard, and economy levels separates sensor-integrated systems with Hawk-Eye convergence from programmable digital units and legacy analog variants. Price differentiation hinges on certification grade—BIS-mandated equipment commands 15-25% premiums over uncertified alternatives—and after-sales service bundling. Pricing pressure stems from aluminum alloy input volatility compressing pneumatic chassis margins. Schools and municipal buyers in Bangladesh and Sri Lanka exhibit highest price sensitivity, while Indian Premier League franchise academies prioritize programmable variation over unit cost.
Supply Chain Analysis
Direct-to-academy channels handle franchise and high-performance center demand, while regional distributor networks serve school and club segments. Manufacturing concentrates in India, the United Kingdom, and Australia, with casting-grade aluminum and polyurethane composite wheels as critical component inputs. Supply chain risk centers on single-source vulnerability for sensor calibration modules sourced from specialized electro-mechanical suppliers. Distribution runs through equipment-as-a-service models emerging in South Asian markets, fragmenting traditional single-vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in sensor-integrated premium tiers where programmable delivery variation commands sustained price premiums. Cost compression in analog manufacturing simultaneously pressures legacy competitors without digital upgrade paths.
For Market Incumbents: Deepen in-house casting capabilities to sustain margin control across pneumatic machine ranges as aluminum alloy volatility intensifies. Invest in sensor calibration technician training programs to address scarcity constraining digital machine deployment. Anchor positions through multi-year maintenance contract structures that resist third-party service commoditization in England's county cricket network.
For New Entrants and Emerging Players: BIS certification enforcement in India opens a window for compliant mid-range electric machine penetration in Nagpur, Indore, and Jaipur academies operating below mechanization thresholds. Target rental channel partnerships with regional sports distributors in Bangladesh and Sri Lanka to bypass upfront capital barriers. Pursue portable machine configurations with collapsible frames and battery power options for school physical education departments prioritizing transportability.
For Investors and Strategic Acquirers: Valuations sit cheapest among analog mechanized specialists facing stranded asset risk from compressed replacement cycles. Long-term viability favors vendors with converged sensor-platform capabilities and captive service networks. Monitor AI-ball tracking integration adoption rates in Mumbai and Sydney academies as inflection indicator for next-generation product differentiation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Calibration Technician Training Programs | Addresses electro-mechanical skills scarcity constraining digital machine installation volumes across South Asia. |
| Equipment-as-a-Service Model Launch | Lowers upfront capital barriers for school and club buyers in Bangladesh and Sri Lanka through rental channel penetration. |
| Hawk-Eye Trajectory Convergence Integration | Enables personalized batting drill customization commanding premium positioning over base digital units in Australian state academies. |
| Multi-Year Maintenance Contract Structuring | Resists third-party service commoditization driven by England's county cricket centralized purchasing consortia. |
| Tier-2 Indian City Distributor Partnerships | Captures whitespace in Nagpur, Indore, and Jaipur academies operating below 15% mechanization rates. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary engagement with academy procurement committees, franchise technical directors, sensor calibration technicians, and regional sports equipment distributors alongside secondary validation. Primary sources included Cricket Australia high-performance center operators, BIS-certified equipment importers, and polyurethane wheel composite suppliers. Secondary data drew from Bureau of Indian Standards certification records, state-level workplace safety regulator filings in Australia, and customs trade data for casting-grade aluminum flows. Bottom-up installation tracking across tier-1 and tier-2 Indian cities triangulated against top-down franchise league infrastructure investment disclosures.
Segment-weighting approaches modeled product type splits across electric, portable, manual, and full-automatic configurations, technology tiers spanning sensor-based, digital, analog, and mechanized variants, and end-user categories including academies, professional teams, schools, and recreational players. CAGRs derived from replacement cycle compression analysis and mechanization rate penetration curves across South Asian markets. Forecast inputs incorporated BIS certification enforcement timelines and Hawk-Eye convergence adoption rates in elite training facilities.
Revisions become necessary when aluminum alloy price volatility exceeds historical bands or when sensor calibration technician training output fails to match installation volumes across the analysis window. Forecasts reflect documented assumptions regarding franchise league infrastructure investment continuity and regulatory compliance pathway stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sportswear
Casual Sportswear Market
Sportswear
North America Dancewear Market
Sportswear
Bicycle Apparels Market
Sportswear
Athleisure Wear Market
Sportswear
Europe Dancewear Market
Sportswear
Global Women Active Wear Market
Sportswear
Cycling Wear Market
Sportswear
Billiards and Snooker Equipment Market
Sportswear
Athleisure Market
Sportswear
Activewear Market
Sportswear
Workout Clothes Market
Sportswear
Cycling Apparel Market
Sportswear
Skateboard Grip Tapes Market
Sportswear
Sports Socks for Children Market