
 Tobacco Pouch Market | 2026-2036
Tobacco Pouch Market Size, Share, and Industry Trends Forecast 2026-2036
Tobacco Pouch Market Analytics
Smokeless tobacco consumption in convenience retail and specialty channels is repositioning the core demand architecture for pouch packaging. Swedish Match leverages its Scandinavian manufacturing heritage to sustain premium-positioned supply relationships across Northern Europe. British American Tobacco competes through integrated polymer-to-paper material transitions that respond to evolving substrate regulations. Philip Morris International anchors its pouch portfolio within broader reduced-risk product strategies, extending format compatibility across multiple oral nicotine platforms.
A tobacco pouch is a sealed or resealable flexible container engineered to preserve moisture content, block oxygen ingress, and maintain flavor stability in smokeless and rolling tobacco products, typically constructed from multi-layer laminates or single-polymer films with tear-notch or zip-lock closure systems. The primary commercial purpose centers on shelf-life extension, portability, and regulatory compliance for health-warning display and child-resistant features. Plastic material formats dominate current volume due to barrier performance and cost efficiency, though paper substrates are gaining fastest growth as REACH-compliant and F-Gas Regulation-aligned sustainability mandates intensify across European supply chains. Rolling tobacco applications lead absolute demand, while snuff and chewing tobacco segments concentrate margin pools in specialized barrier-film configurations and premium closure systems.
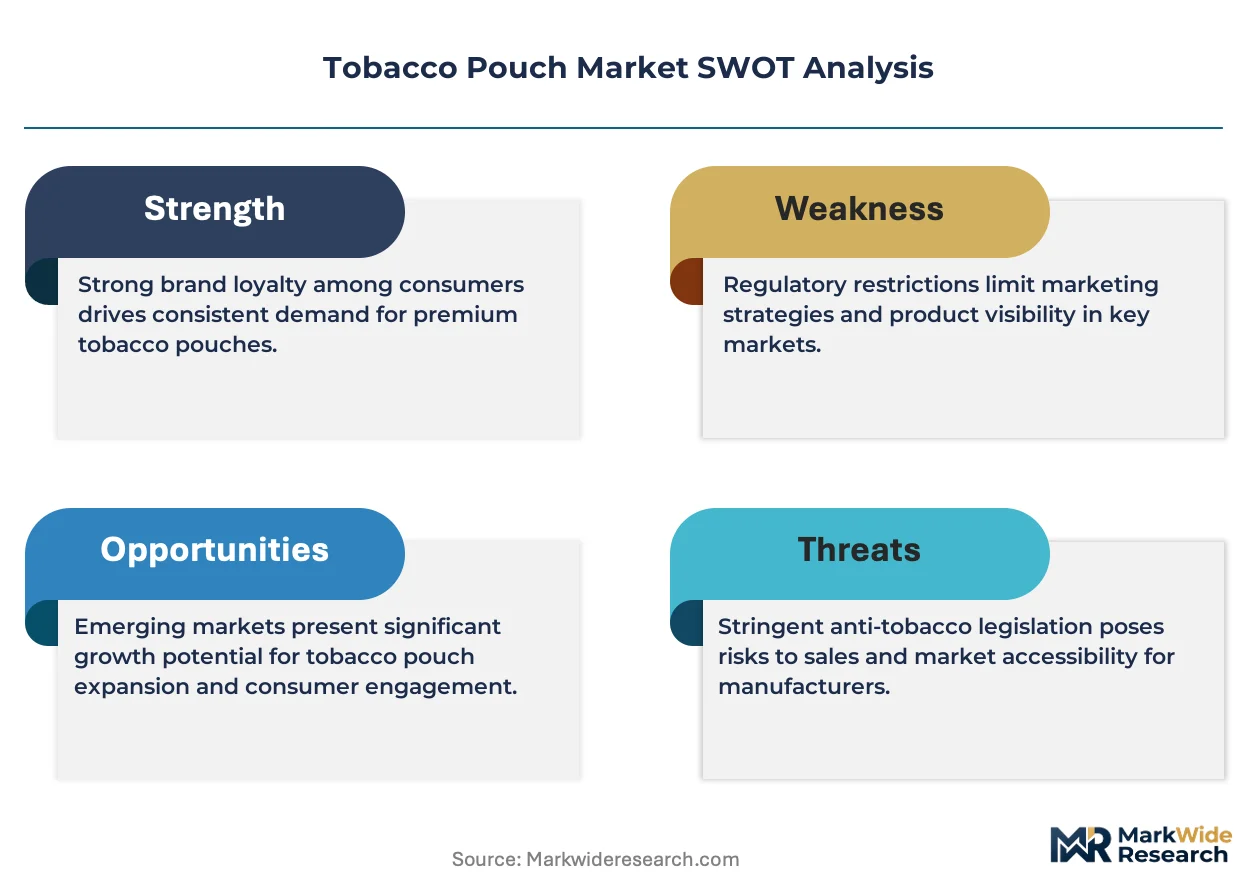
The European Chemicals Agency enforces REACH substance restrictions that directly limit certain polymer additives in tobacco-contact materials, while the EU Packaging and Packaging Waste Directive shapes recyclability quotas that manufacturers must integrate into new pouch designs. The U.S. Food and Drug Administration oversees modified-risk tobacco product pathways that influence labeling specifications and pouch format submissions for oral products. Stakeholders must monitor material certification timelines and regional polymer substitution trajectories to align capacity investments with compliance deadlines and shifting substrate preferences.
Market Dynamics
Polymer-to-paper substrate transitions are compressing legacy supply chains as REACH-compliant material certification becomes mandatory for European market access. Manufacturers must retool laminating equipment and requalify barrier-performance specifications simultaneously.
Growth Catalysts
- REACH substance restrictions:ECHA's evolving polymer additive limits are accelerating compliant material R&D investments among flexible packaging converters serving Northern European tobacco brands.
- Snuff and chewing tobacco formats:Oral smokeless segments in Germany and Scandinavia require specialized high-barrier films with premium closure systems, creating margin-rich demand pockets.
- India convenience retail expansion:Modern trade penetration in tier-2 and tier-3 cities is standardizing resealable pouch specifications for rolling tobacco distribution.
Market Restraints
- Aluminum oxide coating cost volatility:High-barrier metallized substrates depend on aluminum supply fluctuations that squeeze converter margins during price spikes.
- European polymer concentration:Specialty barrier film supply clusters in Germany and Benelux create geographic vulnerability to regional energy cost shocks.
- Recyclability-quota compliance:EU Packaging and Packaging Waste Directive targets force simultaneous performance maintenance and material simplification that technical teams struggle to reconcile.
Strategic Opportunities
- United States modified-risk pathway:FDA's MRTP labeling specifications for oral products create first-mover advantage for pouch formats engineered to display reduced-risk claims prominently.
- Cellulose nanofiber barrier convergence:Bio-based film technology paired with mechanical recycling streams opens premium positioning for sustainability-certified tobacco lines.
- India oral tobacco modernization:Traditional khaini and gutka users migrating to packaged snus formats represent unconverted volume for moisture-stable pouch designs.
Industry Challenges
- Migration testing expertise scarcity:ECHA-compliant substance migration analysis requires specialized analytical chemists that flexible packaging firms compete to recruit.
- Dual certification timeline compression:Child-resistant closure validation and food-contact material approval must run parallel for nicotine pouch expansion, straining regulatory affairs bandwidth.
- Legacy heat-seal equipment incompatibility:Paper substrate adoption demands infrared or ultrasonic sealing retrofits that disrupt running production schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tobacco Pouch Market |
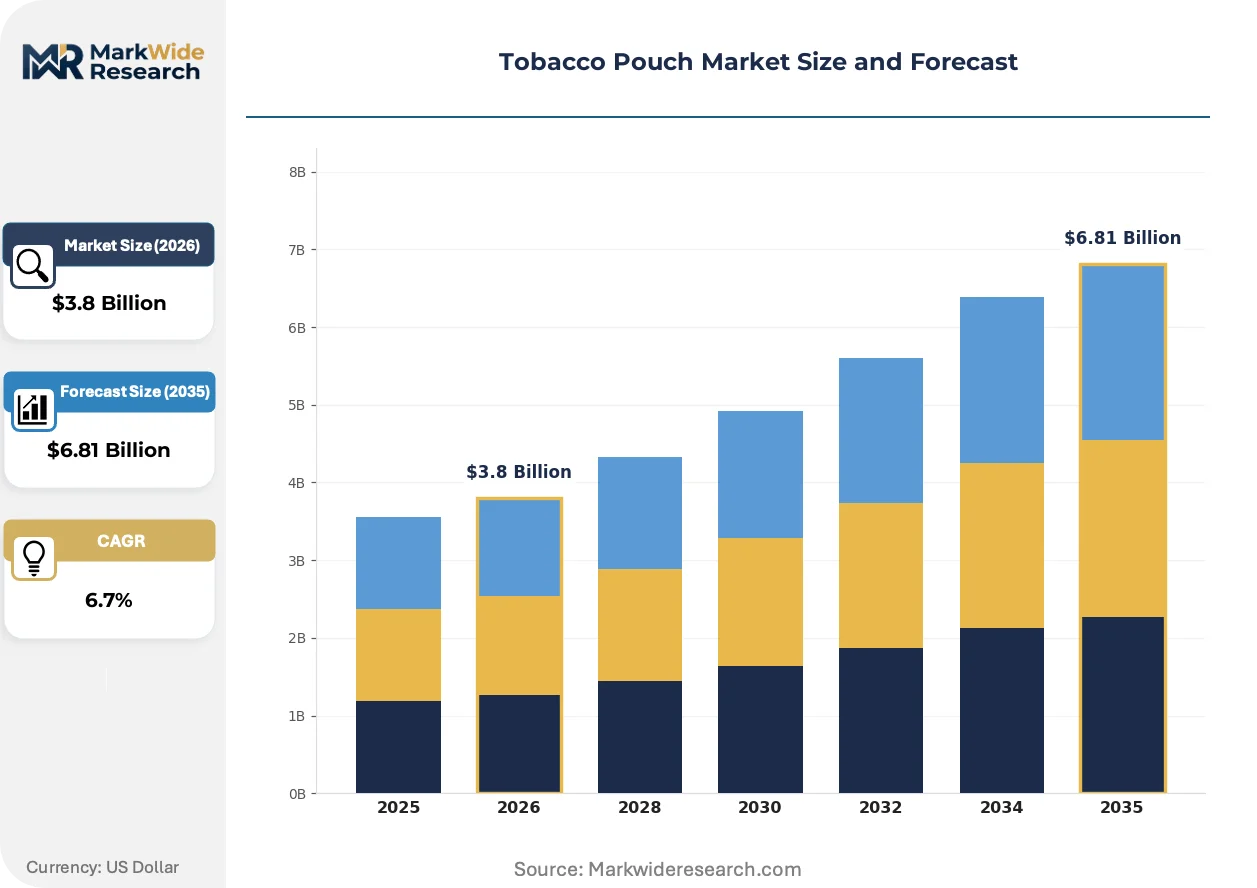
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rolling Tobacco, Chewing Tobacco, Snuff, Herbal Tobacco Material: Plastic, Paper, Aluminium, Silicone End User: Retail Consumers, Wholesale Distributors, Manufacturers, Importers Distribution Channel: Online Stores, Supermarkets, Convenience Stores, Specialty Shops |
| Companies Covered | Philip Morris International, British American Tobacco, Altria Group, Swedish Match, Imperial Brands, Japan Tobacco International, Rogue Holdings, GN Tobacco Sweden AB, Turning Point Brands, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tobacco Pouch Market Evolving Landscape
Material science convergence with regulatory compliance timelines is compressing product development cycles. Packaging engineers must now integrate barrier performance, recyclability, and health-warning display requirements into single design iterations.
Multi-layer paper laminates with bio-based moisture barriers are unifying sustainability credentials with functional performance. Scandinavian rolling tobacco brands are specifying these substrates for premium lines ahead of formal mandates. This unifying technology is collapsing the historical trade-off between environmental positioning and shelf-life extension that previously segmented the market.
F-Gas Regulation phase-down schedules are eliminating hydrofluorocarbon-based barrier coatings from European supply chains. Converters are pivoting to plasma-enhanced chemical vapor deposition alternatives that maintain oxygen transmission rates. Oral nicotine pouch formats in Germany and Sweden face the steepest reformulation deadlines given their reliance on ultra-high barrier specifications.
Specialty convenience retailers are consolidating pouch procurement through direct manufacturer agreements that bypass traditional wholesale distributors. German and US tobacco chains now specify custom closure geometries and health-warning panel dimensions as standard terms. This concentration is most visible in urban metro markets where shelf-space optimization drives format standardization.
Tobacco Pouch Market Segmentation
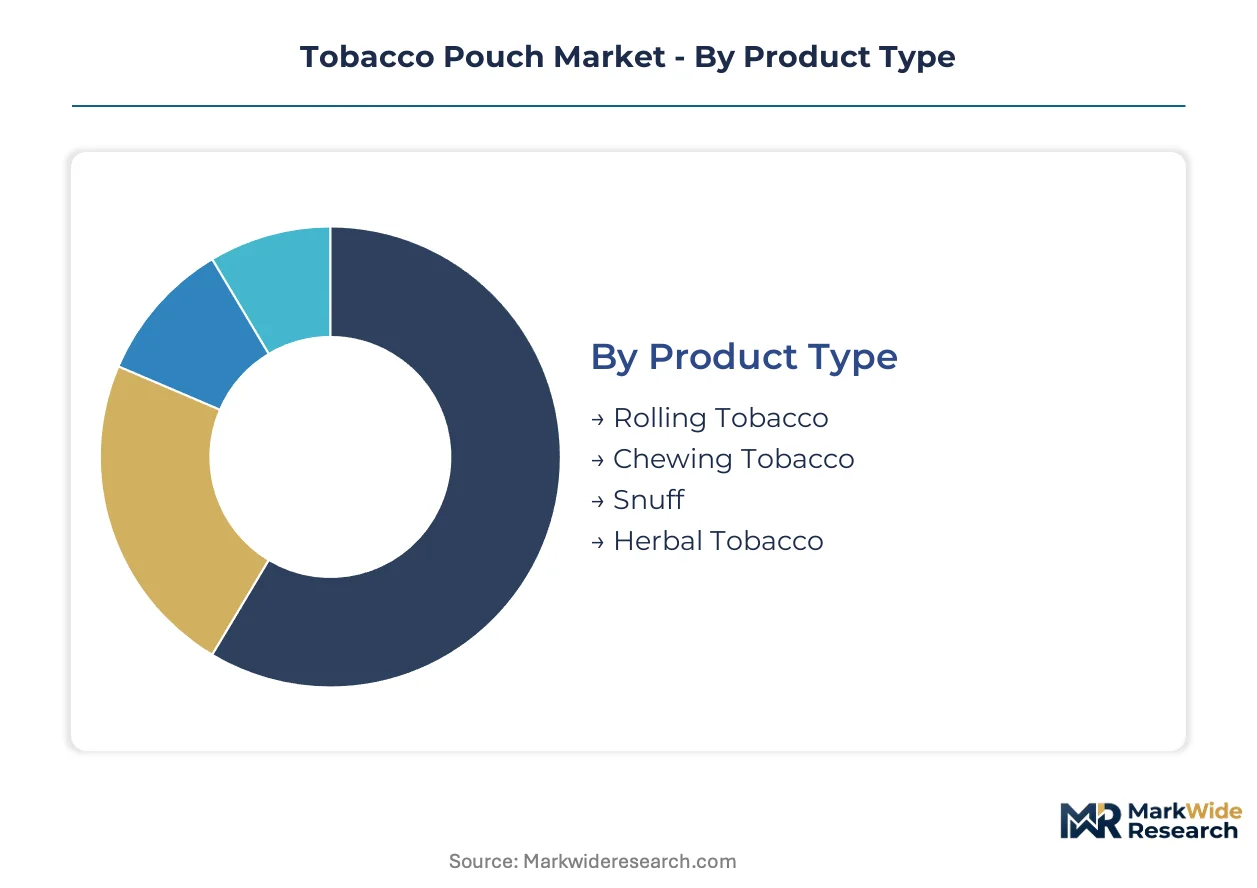
Tobacco pouch segmentation reveals how substrate regulations, moisture-barrier requirements, and channel-specific packaging standards fragment demand across incompatible technical specifications. Manufacturers must qualify separate material certifications for each product-material combination to maintain market access.
Product Type:
Moisture sensitivity and oxygen exposure tolerance drive product-specific pouch engineering decisions across oral and combustible formats.
- Rolling Tobacco:Multi-layer laminates with medium barrier properties preserve humidity without premium closure costs. German and Indian retail chains specify standardized resealable formats for shelf-space efficiency in high-turnover convenience locations.
- Chewing Tobacco:High-moisture content demands metallized or aluminum oxide-coated films with zip-lock systems to prevent desiccation. Scandinavian manufacturers source specialized barrier configurations that command margin premiums due to technical complexity.
- Snuff:Portion-packed formats require individual moisture-stable sachets with precise oxygen transmission control.
- Herbal Tobacco:Lower regulatory burden permits simpler paper-based substrates with basic heat-seal closures.
Rolling Tobacco leads on scale; Snuff leads on momentum.
Material:
REACH compliance timelines and F-Gas Regulation phase-downs are forcing simultaneous substrate transitions across European converter operations.
- Plastic:Polyethylene and polypropylene laminates dominate current volume through proven barrier performance and heat-seal compatibility. German flexible packaging converters face ECHA additive restrictions that require reformulation of legacy polymer grades.
- Paper:Bio-based moisture barriers and cellulose nanofiber coatings enable mechanical recycling compliance under EU Packaging and Packaging Waste Directive targets. Swedish Match and British American Tobacco specify these substrates for premium positioning ahead of formal mandates.
- Aluminium:Metallized films provide ultra-high barrier specifications for moisture-critical oral products.
- Silicone:Specialized closure systems and gasketing components enhance reseal functionality in premium formats.
Plastic maintains volume leadership; Paper gains share fastest.
End User:
Procurement scale and technical specification authority determine whether pouch designs prioritize cost efficiency or performance optimization.
- Retail Consumers:Individual purchase decisions favor portability and reseal convenience over barrier sophistication. Convenience retail in India and Germany drives standardization of tear-notch and zip-lock formats.
- Wholesale Distributors:Bulk procurement concentrates negotiating leverage for custom closure geometries and health-warning panel dimensions. US tobacco chains specify direct manufacturer agreements that bypass traditional distribution tiers.
- Manufacturers:Integrated tobacco companies control substrate selection for brand differentiation and regulatory alignment.
- Importers:Cross-border operations face dual certification requirements for child-resistant closures and food-contact material approvals.
Wholesale Distributors concentrate purchasing power; Retail Consumers drive format innovation.
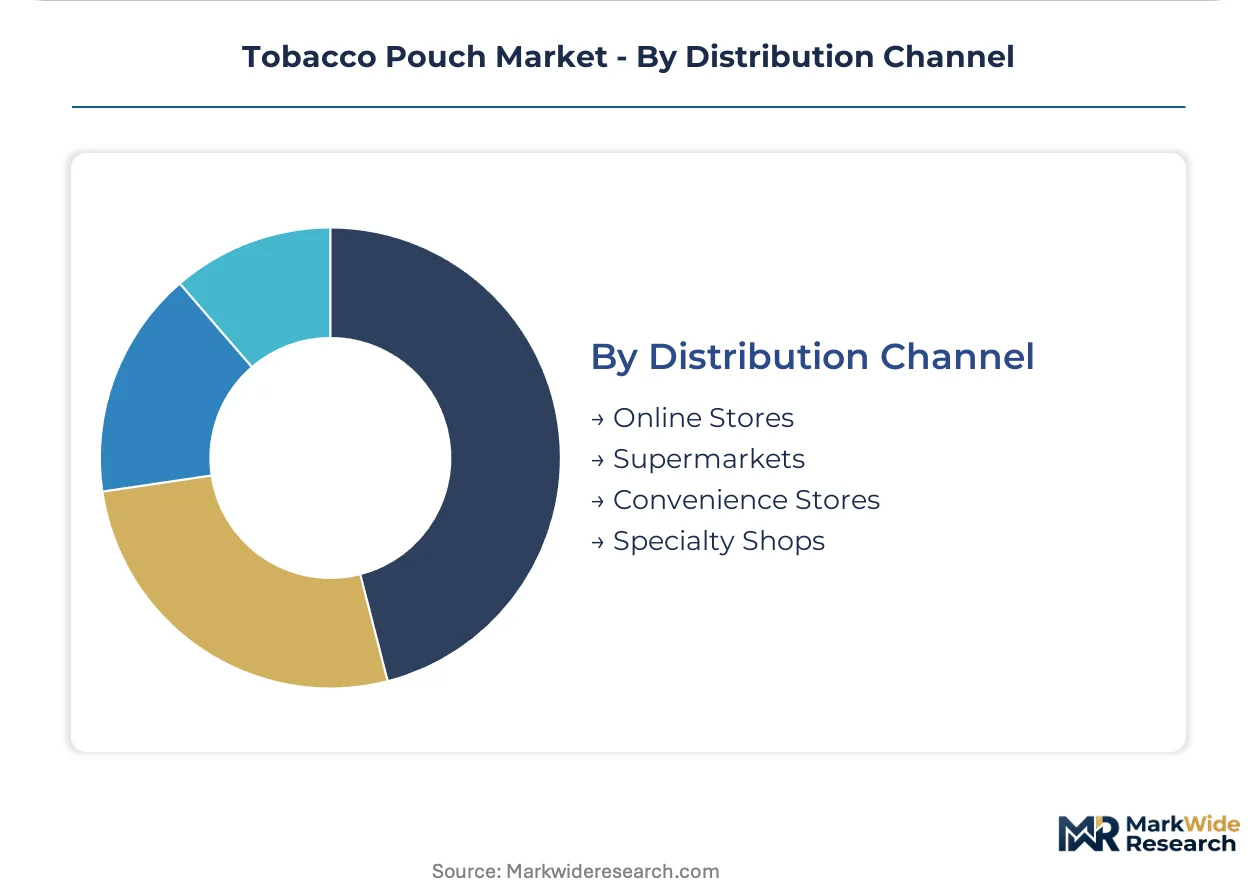
Distribution Channel:
Channel-specific shelf-space constraints and consumer interaction patterns shape pouch dimension and closure system specifications.
- Online Stores:Shipping durability requirements favor reinforced seals and puncture-resistant laminates. E-commerce penetration in Germany and the United States demands packaging engineered for last-mile handling stress.
- Supermarkets:Planogram standardization forces uniform pouch dimensions across competing brands. Health-warning display regulations in the European Union mandate specific panel sizing that constrains design flexibility.
- Convenience Stores:High-velocity turnover prioritizes tear-notch accessibility and single-hand opening.
- Specialty Shops:Premium positioning permits complex closure systems and specialty substrates with sustainability certifications.
Convenience Stores anchor volume throughput; Specialty Shops command margin premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing converter capacity toward jurisdictions with lower compliance burdens. Manufacturers in Germany and Sweden face REACH additive restrictions that elevate material certification costs, while Indian and US operations capture volume from delayed enforcement timelines.
Germany
Snuff and chewing tobacco consumption in Bavaria and North Rhine-Westphalia sustains demand for high-barrier metallized films. ECHA substance restrictions under REACH compel polymer reformulation across flexible packaging operations in the Ruhr industrial cluster. Stuttgart-based converters are retooling laminating equipment to accommodate paper substrate transitions ahead of formal mandates.
United States
Modified-risk tobacco product pathways through FDA are standardizing pouch format specifications for oral nicotine lines. Convenience retail chains in Texas and Florida specify direct manufacturer agreements with custom closure geometries. Chicago-area distributors concentrate negotiating leverage for health-warning panel dimensions across wholesale procurement.
India
Rolling tobacco modernization in Maharashtra and Gujarat drives resealable pouch standardization through tier-2 and tier-3 convenience retail expansion. BIS certification requirements for food-contact materials are compressing dual approval timelines for child-resistant closures. Mumbai-based importers face cross-border compliance complexity for polymer additive specifications.
Sweden
Scandinavian oral tobacco traditions sustain premium-positioned demand for portion-packed sachets with precise oxygen transmission control. F-Gas Regulation phase-downs are eliminating hydrofluorocarbon-based barrier coatings from Stockholm and Gothenburg converter operations. Lund technical clusters pioneer plasma-enhanced chemical vapor deposition alternatives for ultra-high barrier specifications.
Tobacco Pouch Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated tobacco companies controlling substrate selection for regulatory alignment while flexible packaging converters serve wholesale distributor specifications. The structure concentrates around three archetypes: multinational tobacco firms with captive pouch operations, regional flexible packaging specialists with ECHA-compliant certification, and contract manufacturers serving private-label convenience retail lines. M&A activity targets REACH-certified converter capacity, while capacity expansion clusters in India and the US to exploit compliance timeline gaps.
Among Scandinavian-heritage specialists, Swedish Match and GN Tobacco Sweden AB occupy positions within premium oral tobacco packaging tiers, exemplifying manufacturing heritage leveraged for barrier-film specification authority. British American Tobacco sits within the integrated multinational archetype, representing polymer-to-paper transition capabilities across Northern European supply chains. These three anchors demonstrate how regulatory compliance timelines and substrate certification credentials determine competitive positioning in converter procurement decisions.
| Leading Market Players |
|---|
| Philip Morris International |
| British American Tobacco |
| Altria Group |
| Swedish Match |
| Imperial Brands |
| Japan Tobacco International |
| Rogue Holdings |
| GN Tobacco Sweden AB |
| Turning Point Brands |
| Others |
Value Network & Pricing Analysis
Wholesale distributor concentration in Germany and the United States anchors contract-based pricing with volume-scaled discounts, while specialty retail procurement in Scandinavia sustains premium positioning through specification premiums for barrier-film performance.
Pricing Analysis
Distributor margin compression runs through European supply chains as REACH-compliant material certification costs pass through converter quotations. Three-tier pricing structure across premium, standard, and economy levels stratifies by barrier specification and closure complexity, with polymer-to-paper transitions commanding specification premiums. Price erosion in rolling tobacco pouches reflects Indian convenience retail standardization, while moisture-critical oral formats in Germany maintain pricing power. Small-scale importers exhibit highest price sensitivity; integrated tobacco manufacturers show lowest.
Supply Chain Analysis
Freight cost volatility from energy price shocks in the Ruhr industrial cluster and Benelux converter regions is compressing margin buffers for metallized film shipments. Supply concentrates in Germany, India, and Sweden, with raw material dependencies spanning aluminum oxide coatings, cellulose nanofiber substrates, and REACH-certified polymer additives. Single-source vulnerability to ECHA substance restriction timelines threatens European capacity. Distribution runs through direct manufacturer agreements with convenience retail chains, bypassing traditional wholesale tiers in urban metro markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tobacco pouch market functions as a stable compounder, with regulatory-driven material transitions sustaining replacement demand and specification upgrades across European and North American supply chains.
For Market Incumbents: Lock in ECHA-compliant converter capacity ahead of certification deadline compression, particularly for paper substrate laminating equipment in the Ruhr cluster. Secure backward integration into cellulose nanofiber barrier film production to defend margin position against aluminum oxide cost volatility. Prioritize child-resistant closure validation parallel to food-contact approvals for nicotine pouch expansion. For New Entrants and Emerging Players: Tier-2 Indian convenience retailers represent the most penetrable buyer archetype, with standardized resealable specifications creating volume entry points without premium barrier complexity. Target US modified-risk tobacco product pathway submissions for oral nicotine formats, leveraging FDA labeling specification windows. Pursue contract manufacturing relationships with Scandinavian heritage brands seeking second-source flexibility. For Investors and Strategic Acquirers: Integrated tobacco companies with captive pouch operations are the most active acquirers in this space, targeting REACH-certified European converter capacity. The 5-10 year viability window favors substrate-transition-ready assets over legacy polymer-dependent operations. Watch ECHA substance restriction enforcement timelines as the critical inflection signal for capacity repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Polymer-to-Paper Substrate Transition | REACH compliance mandates in Germany and Sweden are eliminating legacy polymer grades from tobacco-contact materials. |
| Child-Resistant Closure Certification | FDA modified-risk pathway requirements for oral nicotine pouches demand parallel validation with food-contact approvals. |
| Direct Retail Procurement Agreements | US and German convenience chains are bypassing wholesale distributors for custom format specifications. |
| Plasma-Enhanced Barrier Deposition | F-Gas Regulation phase-downs in Sweden are eliminating hydrofluorocarbon coatings from ultra-high barrier specifications. |
| India Tier-2 Distribution Expansion | Maharashtra and Gujarat retail modernization is standardizing resealable pouch formats for rolling tobacco. |
Research Methodology
Coverage spans Germany, the United States, India, and Sweden, with primary inputs from each market cluster combining interviews with flexible packaging converters, tobacco company procurement directors, regulatory affairs specialists, and convenience retail category managers with secondary validation. Sources include ECHA substance restriction databases, FDA modified-risk tobacco product filings, EU Packaging and Packaging Waste Directive implementation reports, and BIS food-contact material certifications. Bottom-up volume modeling triangulates against top-down industry value estimates.
Granularity extends to substrate material, product format, and distribution channel dimensions across the projection horizon, with separate modeling for rolling tobacco, chewing tobacco, snuff, and herbal tobacco segments. CAGRs derive from trend extrapolation against regulatory deadline impacts and material substitution trajectories. Industry-specific inputs include ECHA compliance timeline probability weightings and F-Gas Regulation phase-down schedules.
Inputs from converter operations and regulatory filings were available through the study window; gaps in real-time aluminum oxide pricing data and polymer additive migration testing capacity introduce uncertainty bands around margin forecasts. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tobacco Products
E-Cigarettes and Vaporizer Market
Tobacco Products
Asia-Pacific E Cigarettes Market
Tobacco Products
Europe Cigarette Vending Machine Market
Tobacco Products
Handmade Cigars Market
Tobacco Products
Disposable E-Cigarettes Market
Tobacco Products
Nicotine Pouches Market
Tobacco Products
Luxury Cigarette Market
Tobacco Products
Heat-Not-Burn Tobacco Products Market
Tobacco Products
Electronic Cigarette Atomizer Market
Tobacco Products
Cigar Tubes Market
Tobacco Products
Philippines E-Cigarette and Vape Market
Tobacco Products
Flavored Cigar Market
Tobacco Products
Menthol Cigarette Market
Tobacco Products
Cigarette Market
Tobacco Products
US E-Cigarette and Vape Market
Tobacco Products
Global E-Cigarettes Market