
 Cigarettes Filter Market | 2026-2036
Cigarettes Filter Market Size, Share, and Industry Trends Forecast 2026-2036
Cigarettes Filter Market Analysis
The capital-intensity divergence between integrated resin producers and standalone filter converters is redrawing competitive boundaries in the cigarettes filter supply chain. Celanese Corporation leverages its captive cellulose acetate flake capacity to secure raw material margins that converters cannot replicate. Essentra plc anchors its position through specialized tipping and filtration solutions tailored to brand-owner specifications. Daicel Corporation differentiates via advanced tow production technology that yields consistent denier control for premium filter rods.
Cigarettes filters are cylindrical mouthpiece attachments constructed primarily from cellulose acetate tow—bundles of crimped filaments typically measuring 2.5 to 6.0 denier per filament—that trap particulate matter and reduce tar delivery during combustion. Their primary commercial purpose is to serve as a standardized component in manufactured cigarettes, enabling brand differentiation while meeting regulatory emissions thresholds. Cellulose acetate tow commands the dominant material position due to established manufacturing infrastructure and predictable filtration performance, though activated carbon segments are gaining structural attention as tar-reduction specifications tighten across multiple jurisdictions. Standard filter designs retain volume leadership, while slim and mentholated variants capture disproportionate margin pools in premium product tiers.
The US FDA exercises authority over modified risk tobacco product claims that directly influence filter innovation pathways and marketing permissions. REACH in Europe governs chemical migration limits from filter materials into smoke streams, compelling reformulation investments by tow suppliers. China's national standards body sets GB specifications for filter rod dimensional and performance consistency that all domestic manufacturers must satisfy. Stakeholders must monitor how biodegradable material mandates in multiple jurisdictions reshape cellulose acetate's long-term viability against paper and biopolymer alternatives.
Market Dynamics
Filter rod manufacturers face a structural squeeze between tightening GB standards in China and accelerating biodegradable mandates across EU member states, forcing dual-track R&D investments that strain mid-tier converters without captive resin supply.
Growth Catalysts
- Activated carbon filtration:Premium cigarette brands in Germany and Japan are embedding carbon segments to meet tar-reduction thresholds set by Health Canada and Japan's Ministry of Health, Labour and Welfare.
- China's GB compliance wave:Domestic filter rod producers must retool to satisfy dimensional consistency standards, creating equipment replacement cycles for tow crimping and rod forming machinery.
- REACH migration limits:ECHA-enforced caps on chemical leaching from filter materials into smoke streams are compelling reformulation of cellulose acetate plasticizers, opening specification windows for alternative binders.
Market Restraints
- Cellulose acetate flake concentration:Three integrated resin producers control over 70 percent of global flake supply, exposing standalone converters to allocation risk during petrochemical feedstock volatility.
- Biopolymer performance gaps:Polylactic acid and starch-based alternatives lack the crimp retention and pressure-drop predictability that machine-made cigarette production lines require.
- Dual carbon policy friction:China's MEE enforcement of emissions intensity targets conflicts with filter production expansion plans in Shandong and Yunnan provinces.
Strategic Opportunities
- Indonesia's unregulated filter segment:Kretek cigarette manufacturers still use unfiltered or rudimentary paper mouthpieces, presenting a conversion opportunity as excise tax structures evolve.
- Carbon-capsule tipping:Crushable capsule technology that releases flavor or cooling agents is miniaturizing into slim and super-slim filter formats for Southeast Asian premium tiers.
- EU Green Deal biodegradability mandates:Proposed single-use plastics directives targeting cigarette butt litter are accelerating development of paper and hemp-based filter substrates in Netherlands and France.
Industry Challenges
- Tow denier control expertise:Consistent 2.5-6.0 denier filament production requires polymer science specialization that aging workforces in US and European manufacturing clusters struggle to replenish.
- Cross-border certification timelines:Filter rod suppliers seeking FDA modified risk tobacco product qualification face 18-24 month review cycles that freeze formulation iterations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cigarettes Filter Market |
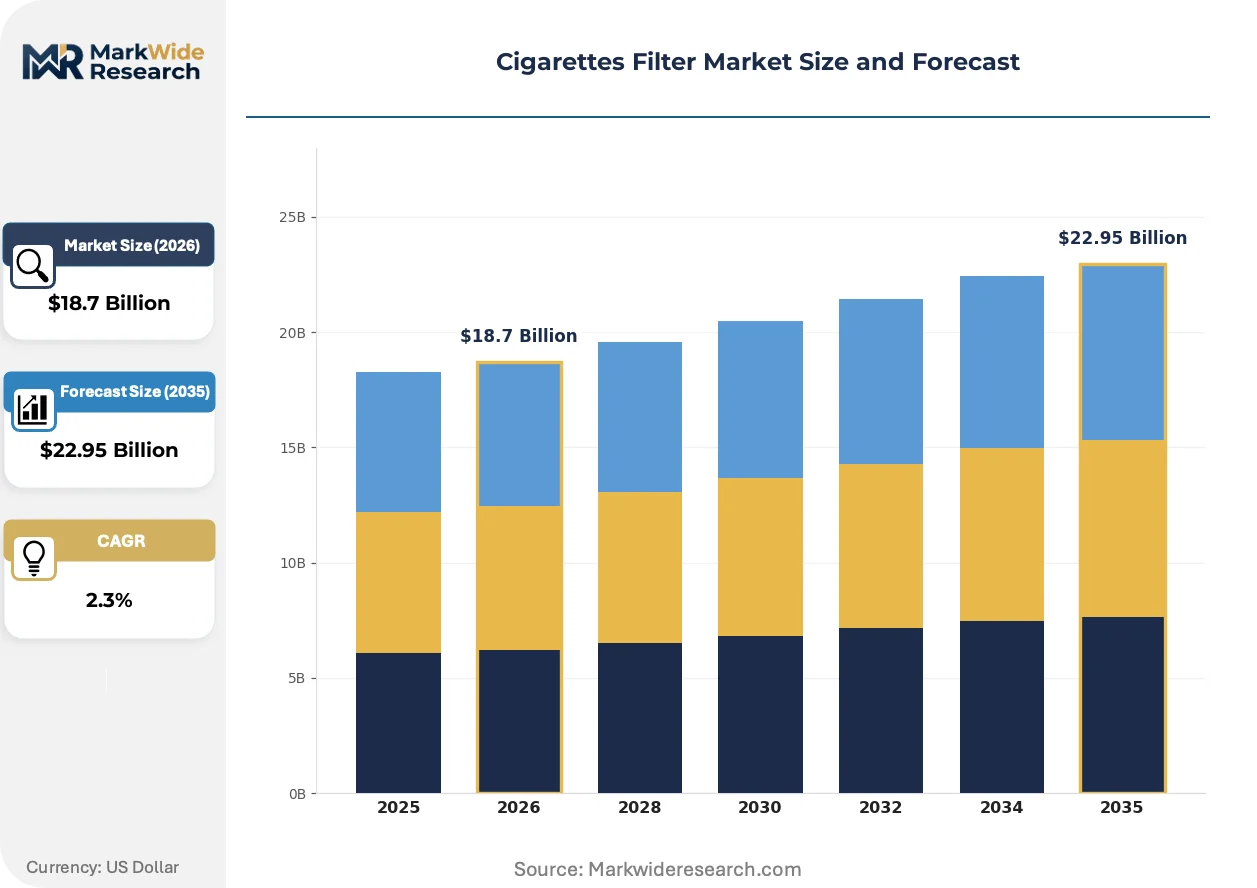
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 2.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cellulose Acetate, Paper, Foam, Activated Carbon Filter Design: Standard, Slim, Mentholated, Flavored End User: Individual Consumers, Retailers, Distributors, Manufacturers Distribution Channel: Online, Supermarkets, Convenience Stores, Tobacco Shops |
| Companies Covered | Cerdia International GmbH, Essentra plc, Celanese Corporation, Solvay S.A., Mitsubishi Chemical Corporation, Daicel Corporation, SWM International, Rayonier Advanced Materials, Eastman Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cigarettes Filter Market Emerging Trajectories
Filter technology is bifurcating between precision-engineered premium segments and cost-optimized standard rods, with material science investments concentrating on biodegradable alternatives that preserve manufacturing line compatibility.
Multi-segment filter architecture is miniaturizing into increasingly compact formats without sacrificing functional performance. Japanese and South Korean tobacco manufacturers are embedding two or three distinct filtration zones—acetate tow, activated carbon, and flavor capsules—into diameters below 17mm. This compression is enabling brand differentiation in super-slim and nano cigarette categories where tar delivery must still meet regulatory ceilings.
REACH Annex XVII restrictions on microplastic shedding are forcing filter producers to document biodegradability pathways for cellulose acetate tow sold into EU markets. ECHA's 2023-2025 evaluation window for synthetic polymer fibers is compelling suppliers to submit dissolution test data under marine and soil conditions. German and French filter converters are responding by piloting paper-based alternatives that maintain pressure-drop specifications through controlled porosity engineering.
Brand owners are consolidating supplier relationships to secure dedicated production lines for proprietary filter designs. British American Tobacco and Japan Tobacco International are signing multi-year offtake agreements that lock in capacity at specific rod-forming facilities in Poland and Malaysia. This concentration is squeezing independent converters in Spain and Italy who lack the scale to justify dedicated line investments for single-customer volumes.
Cigarettes Filter Market Segmentation
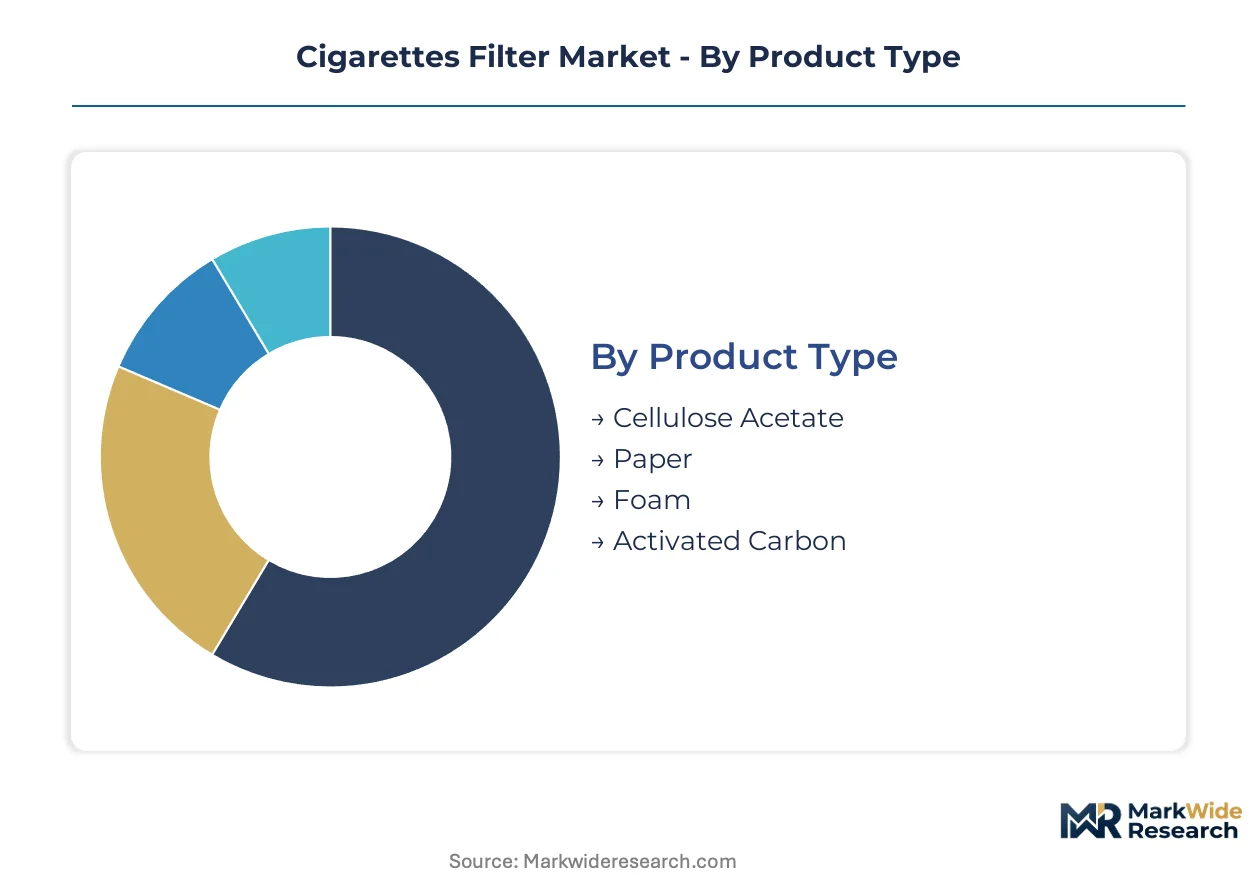
Filter material selection and design architecture determine manufacturing compatibility, regulatory compliance pathways, and brand differentiation potential across cigarette portfolios. Segmentation reveals where biodegradable substitutes threaten incumbent technologies and where premium formats command disproportionate margin capture.
Product Type:
Cellulose acetate faces the most acute substitution pressure as EU biodegradability mandates and marine litter regulations challenge its synthetic polymer classification.
- Cellulose Acetate:Crimped filament bundles of 2.5-6.0 denier deliver predictable pressure-drop performance and tar retention. Demand concentrates in China where GB standards enforce dimensional consistency, though REACH Annex XVII documentation requirements are forcing reformulation of plasticizer chemistry.
- Activated Carbon:Porous carbon segments embedded in multi-chamber designs adsorb vapor-phase constituents and enable tar reduction claims. Japanese and German premium brands are specifying carbon-loaded configurations to satisfy Health Canada and Japan Ministry of Health thresholds.
- Paper:Compressed fiber matrices offer biodegradability compliance but struggle with crimp retention and moisture stability. Dutch and French converters are piloting controlled-porosity engineering to meet EU Green Deal single-use plastics directives.
- Foam:Polyurethane or polyester foam structures provide alternative mouthfeel and filtration density. Limited adoption in Southeast Asian kretek conversions where cost sensitivity dominates material selection.
Cellulose acetate anchors the volume base while activated carbon gains share at the steepest rate.
Filter Design:
Cost tier stratification separates precision-engineered premium formats from commodity standard rods, with flavor integration driving the widest price spreads.
- Standard:Conventional cylindrical rods of 20-25mm length dominate machine-made cigarette production lines. Volume concentrates in mass-market brands across Indonesia and Eastern Europe where manufacturing throughput prioritizes format consistency.
- Slim:Diameters below 17mm require compressed multi-segment architecture without sacrificing filtration efficiency. South Korean and Japanese manufacturers are embedding dual and triple filtration zones into super-slim categories.
- Mentholated:Flavor-impregnated tow or capsule-release systems deliver cooling sensation. Regulatory scrutiny from FDA modified risk tobacco product pathways is constraining new product introduction timelines.
- Flavored:Crushable capsule technology miniaturizing into filter tips releases cooling or fruit agents on demand. Southeast Asian premium tiers are adopting carbon-capsule hybrid formats for brand differentiation.
Standard designs retain the installed manufacturing base while slim formats are expanding most quickly in East Asian premium segments.
End User:
Customer type determines order scale, specification complexity, and supplier relationship intensity across the value chain.
- Individual Consumers:End smokers experience filter performance through draw resistance and mouthfeel characteristics. Preference data from Germany and Japan indicates rising specification of carbon-segment and capsule-integrated products.
- Retailers:Point-of-sale inventory management favors standardized filter formats with predictable turnover velocity. Convenience store chains in Poland and Malaysia are consolidating supplier relationships to secure dedicated production lines.
- Distributors:Wholesale intermediaries manage bulk logistics between rod-forming facilities and cigarette manufacturing plants. Regional distributors in Spain and Italy face margin compression from brand-owner direct contracting.
- Manufacturers:Tobacco companies specify proprietary designs and lock in multi-year offtake agreements. British American Tobacco and Japan Tobacco International are signing capacity reservations at dedicated facilities.
Manufacturers command the deepest supplier integration while retailers are gaining procurement leverage through format standardization.
Distribution Channel:
Channel selection reflects regulatory access restrictions, product age-verification requirements, and geographic coverage intensity.
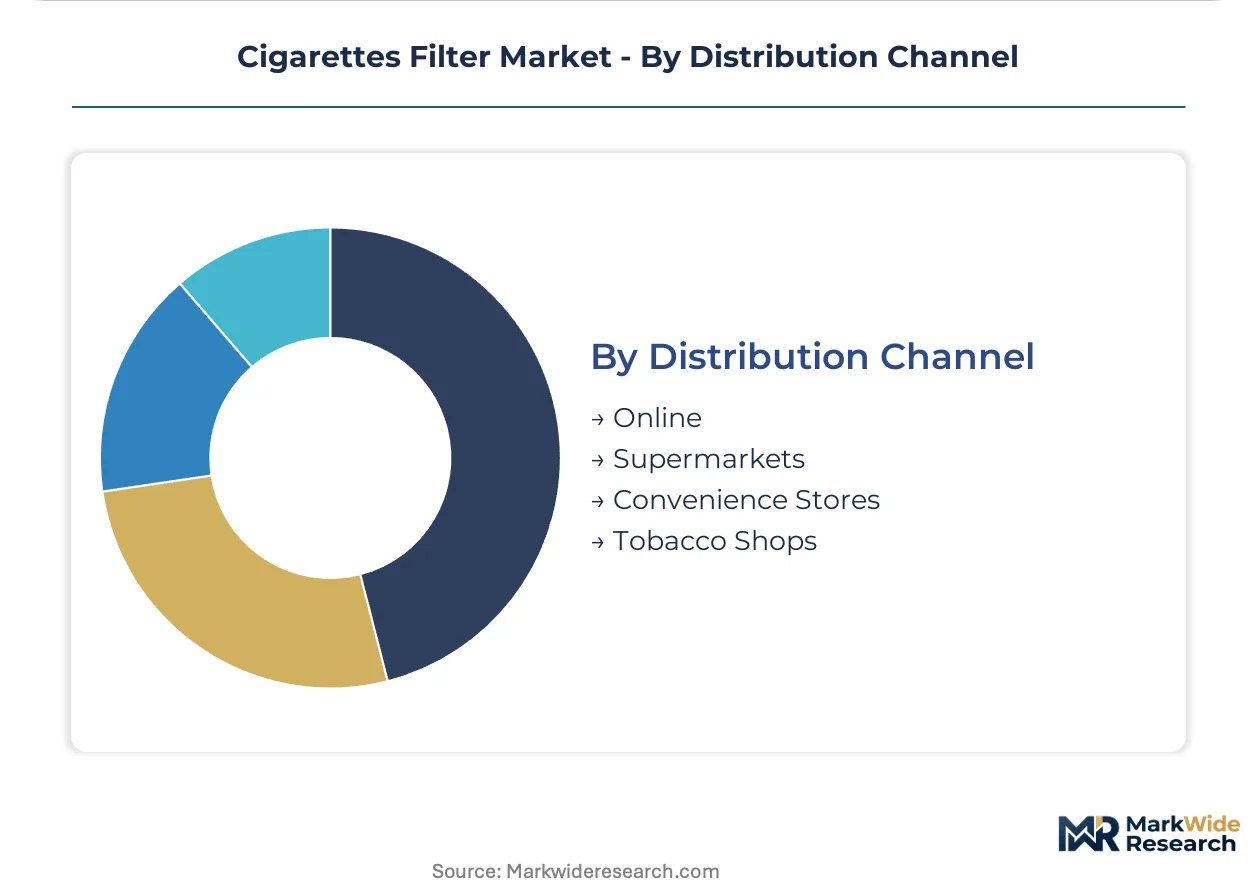
- Online:E-commerce platforms face strict age-gating and shipping regulations across EU member states. Limited penetration for filter components due to bulk shipment economics and excise tracking requirements.
- Supermarkets:Mass retail chains stock finished cigarettes rather than standalone filters. Filter rod sales through this channel remain negligible outside specialized industrial supply contexts.
- Convenience Stores:High-frequency outlets dominate finished cigarette availability in urban clusters. Filter component distribution bypasses this channel in favor of direct manufacturer-to-integrator supply.
- Tobacco Shops:Specialized retailers focus on premium and artisanal finished products. Limited relevance for industrial filter rod procurement.
Direct manufacturer supply anchors the volume base while specialized industrial distributors are climbing the fastest in emerging market expansions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across cigarette filter markets. Indonesia and Eastern Europe exhibit high sensitivity to tow cost fluctuations, while Japanese and German buyers absorb premiums for carbon-segment and capsule-integrated configurations without volume erosion.
China
Domestic filter rod producers face mandatory retooling cycles as GB standards tighten dimensional consistency requirements. The Ministry of Ecology and Environment enforces dual carbon intensity targets that constrain expansion in Shandong and Yunnan provinces. Manufacturing clusters in Kunming and Qingdao are upgrading crimping and rod-forming machinery to satisfy compliance deadlines.
United States
FDA modified risk tobacco product pathways freeze formulation iterations for 18-24 month review cycles, compressing innovation timelines for filter suppliers. The agency's authority over emissions claims directly shapes carbon-segment adoption in premium tiers. Production concentrates in North Carolina and Virginia tobacco belt corridors where cigarette manufacturers maintain integrated supply relationships.
Germany
ECHA's REACH Annex XVII evaluation of synthetic polymer fibers compels suppliers to submit marine and soil biodegradability documentation for cellulose acetate tow. Premium brands specify carbon-loaded configurations to satisfy tar-reduction thresholds. Filter converters in Hamburg and Munich are piloting paper-based alternatives through controlled-porosity engineering.
Japan
The Ministry of Health, Labour and Welfare maintains strict tar delivery ceilings that drive specification of multi-segment filtration in super-slim formats. Tobacco manufacturers embed dual and triple filtration zones into diameters below 17mm. Manufacturing concentrates in Osaka and Nagoya industrial corridors where precision tow denier control expertise resides.
Indonesia
Kretek cigarette manufacturers still deploy unfiltered or rudimentary paper mouthpieces across mass-market segments. Excise tax structures are evolving toward filter-mandate parity with international standards. Conversion opportunities concentrate in Java-based production clusters where equipment modernization lags regional competitors.
Cigarettes Filter Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the cigarettes filter supply chain. Integrated resin producers command raw material margins through captive cellulose acetate flake capacity, while standalone converters compete on rod-forming precision and brand-owner relationship depth. Three archetypes dominate: upstream chemical conglomerates with polymer science specialization, mid-tier converters with regional equipment footprints, and niche specialists in carbon-impregnated or capsule-integrated configurations. Competitive moves center on multi-year offtake agreements that lock in dedicated production lines and backward integration into tow manufacturing to secure flake supply allocation.
Among integrated chemical producers, Celanese Corporation and Eastman Chemical Company occupy positions anchored by captive resin supply chains. Daicel Corporation exemplifies the precision-specialist archetype through advanced tow production technology. These three entities represent distinct competitive vectors: scale-driven raw material security, formulation chemistry expertise, and manufacturing process control respectively.
| Leading Market Players |
|---|
| Cerdia International GmbH |
| Essentra plc |
| Celanese Corporation |
| Solvay S.A. |
| Mitsubishi Chemical Corporation |
| Daicel Corporation |
| SWM International |
| Rayonier Advanced Materials |
| Eastman Chemical Company |
| Others |
Supply Flow & Price Mechanics
REACH Annex XVII documentation requirements for synthetic polymer fibers simultaneously gate EU market access and stratify supplier pricing tiers, forcing cellulose acetate producers to absorb compliance costs while carbon-segment specialists capture premium positioning.
Pricing Analysis
After-sales technical service contracts and multi-year equipment maintenance agreements drive lifetime value for filter rod machinery suppliers. Contract-based long-term offtake agreements dominate, with pricing stratifying across premium, standard, and economy tiers based on tow denier precision and carbon-impregnation complexity. Cost compression in standard acetate rods is intensifying because flake supply allocation constraints favor integrated resin producers. Indonesian kretek manufacturers exhibit highest price sensitivity, while Japanese premium brands absorb carbon-segment premiums without volume erosion.
Supply Chain Analysis
Strategic stockpiling of cellulose acetate flake prevails among integrated producers, while standalone converters operate on just-in-time tow deliveries that expose them to petrochemical feedstock volatility. Supply concentrates in China, the United States, and Japan, with raw material flows drawing from wood pulp derivatives, acetic anhydride, and activated carbon feedstocks. Single-source vulnerability in flake supply creates allocation risk during upstream chemical plant outages. Distribution runs through direct manufacturer-to-integrator supply chains, bypassing retail intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense imperative as paper and hemp-based filter substrates gain regulatory traction under EU Green Deal biodegradability mandates.
For Market Incumbents: Fortify raw material security through backward integration into tow manufacturing or captive flake supply agreements. Secure dedicated production line commitments from British American Tobacco and Japan Tobacco International through multi-year offtake structures. Prioritize carbon-capsule miniaturization R&D to defend premium positioning against biopolymer alternatives.
For New Entrants and Emerging Players: Post-sales technical training and rapid equipment commissioning services represent underserved white space where aging workforces struggle with tow denier control expertise. Target Indonesia's kretek conversion opportunity as excise tax structures evolve toward filter mandates. Pursue equipment financing partnerships to lower capital barriers for mid-tier converters.
For Investors and Strategic Acquirers: ECHA's 2023-2025 synthetic polymer fiber evaluation reshapes the acquisition landscape toward biodegradability-compliant asset portfolios. Five-to-ten-year viability hinges on successful paper-based alternative commercialization. Target precision tow producers with established denier control expertise. Watch for EU single-use plastics directive enforcement timelines as inflection indicators.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Flake Production | Celanese Corporation and Eastman Chemical Company secure raw material margins that standalone converters cannot replicate. |
| Carbon-Capsule Miniaturization R&D | Japanese and South Korean manufacturers embed triple filtration zones into sub-17mm diameters for super-slim categories. |
| Multi-Year Offtake Agreement | British American Tobacco locks dedicated capacity at Polish rod-forming facilities, squeezing independent Spanish converters. |
| Paper-Based Alternative Piloting | Dutch and French converters engineer controlled porosity to satisfy EU Green Deal single-use plastics directives. |
| Precision Denier Control Technology Acquisition | Daicel Corporation's advanced tow production expertise commands premium positioning in Japanese Ministry of Health compliance tiers. |
Methodological Framework
Operator-level perspectives from filter rod plant managers, cigarette manufacturer procurement leads, cellulose acetate R&D directors, and tipping equipment service engineers anchored the qualitative base. Primary interviews combined with secondary validation from customs trade data, SEC chemical company filings, GB standards documentation, and ECHA REACH registration databases. Bottom-up capacity modeling and top-down demand triangulation cross-verified volume estimates.
Sensitivity analysis tested forecast robustness across flake supply disruption scenarios and biodegradable mandate acceleration timelines. Segmentation dimensions modeled include material type, filter design architecture, end-user category, and regional regulatory cluster. CAGRs were derived from installed equipment base depreciation cycles and brand-owner capacity expansion announcements. Industry-specific inputs incorporated GB compliance equipment replacement waves and FDA modified risk tobacco product review cycle durations.
Forecasts assume regulatory continuity in REACH Annex XVII enforcement and China's GB standards implementation; material policy shifts would require re-modeling. Specific risks include ECHA biopolymer reclassification, Indonesia excise tax restructuring, and cellulose acetate marine biodegradability finding revisions. Revision becomes warranted when EU single-use plastics directive enforcement thresholds cross statutory implementation deadlines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tobacco Products
Global Flavor Capsule Cigarette Market
Tobacco Products
E-Cigarettes and Vaporizer Market
Tobacco Products
Flavored Cigar Market
Tobacco Products
Europe Cigarette Market
Tobacco Products
Europe E-Cigarettes Market
Tobacco Products
Roll-Your-Own Tobacco Products Market
Tobacco Products
Handmade Cigars Market
Tobacco Products
United States E-Cigarette Market
Tobacco Products
Tobacco Products Market
Tobacco Products
Japan Heated Tobacco Products Market
Tobacco Products
Middle East and Africa E-Cigarettes Market
Tobacco Products
Premium Cigarette Market
Tobacco Products
Disposable E-Cigarettes Market
Tobacco Products
Cigarette Market
Tobacco Products
GCC Cigarette Lighter Market
Tobacco Products
West Africa Cigarettes Market