
 US E-Cigarette and Vape Market | 2026-2036
US E-Cigarette and Vape Market Size, Share, and Industry Trends Forecast 2026-2036
US E-Cigarette and Vape Market Intelligence
Asset-light leasing models for retail vape shop fixtures and consignment inventory programs is rewriting capital requirements for new entrants. Altria Group leverages its smokeless product infrastructure to sustain shelf presence across convenience channels. Juul Labs anchors its position through R&D intensity in nicotine salt formulation technology. NJOY competes on regulatory preparedness, having secured FDA marketing authorization for multiple device and pod configurations.
E-cigarettes and vape products comprise battery-powered electronic nicotine delivery systems that heat e-liquid solutions—typically containing propylene glycol, vegetable glycerin, flavorings, and nicotine—into inhalable aerosol for recreational or smoking-cessation purposes. Pod systems now lead unit volume due to portability and discrete form factors, while mods retain the premium margin pool through customization and coil-building enthusiast demand. Fruit and menthol flavor categories drive the fastest growth in cartridge replenishment cycles, though tobacco flavors dominate in channels serving older adult smokers transitioning from combustibles.
FDA Center for Tobacco Products enforces premarket authorization under the Family Smoking Prevention and Tobacco Control Act, while state attorneys general in New York, Massachusetts, and Rhode Island impose additional flavor restrictions and licensing moratoria. These overlapping compliance layers elevate barriers for unauthorized imports and reshape retail geography toward states with lighter local ordinances. Stakeholders must monitor pending FDA decisions on synthetic nicotine classification and state preemption battles that could abruptly redraw market access maps.
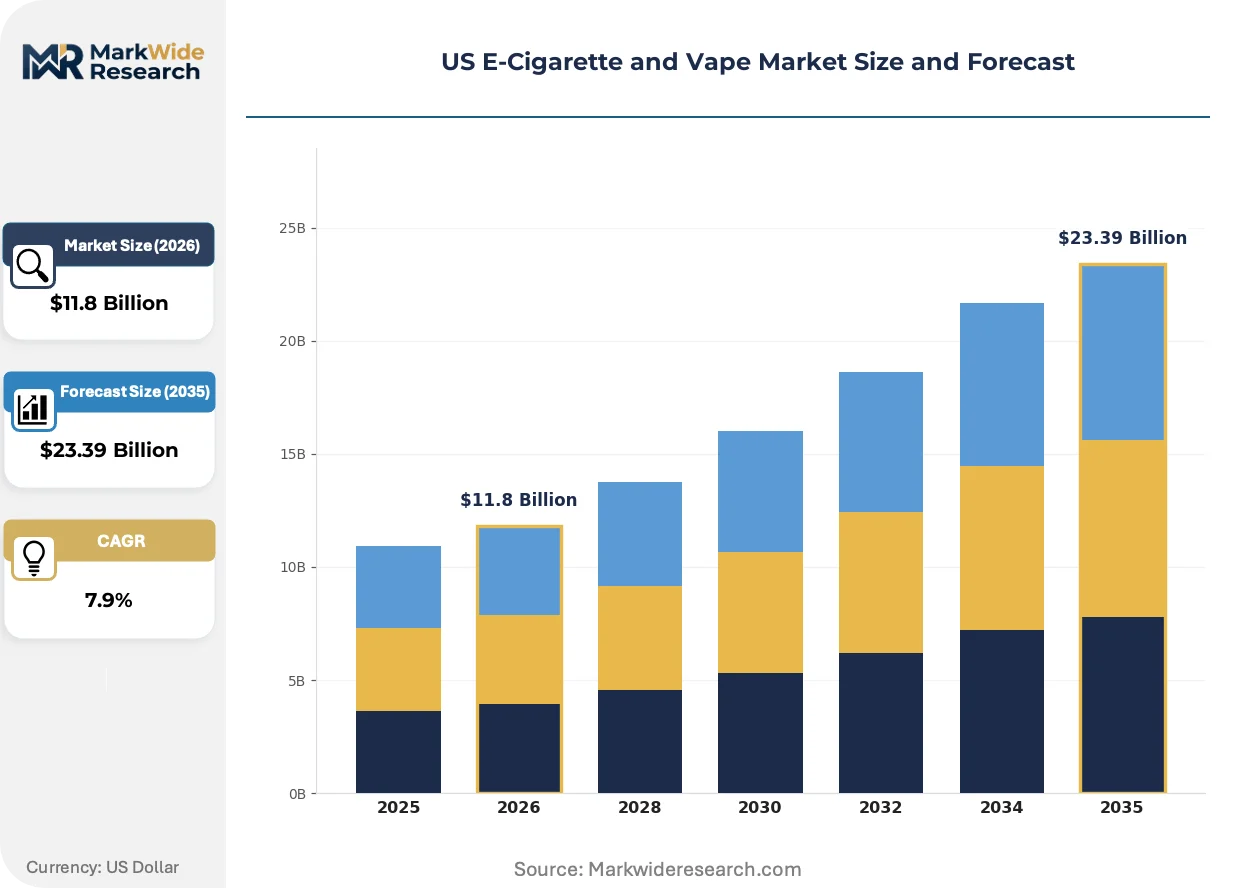
Market Dynamics
FDA premarket tobacco product application enforcement and state-level flavor licensing moratoria are compressing competitive access while adult smokers switching from combustibles drive volume concentration in permissive jurisdictions.
Growth Catalysts
- Adult smoker transition:Former combustible cigarette users in California, Texas, and Florida represent the largest expanding buyer segment as they seek reduced-harm alternatives.
- Nicotine salt formulation advances:Higher bioavailability delivery systems enable lower-volume consumption with equivalent satisfaction, accelerating pod system adoption.
- Consignment inventory programs:Asset-light retail fixture leasing reduces capital barriers for new vape shop entrants in high-density metropolitan clusters.
Market Restraints
- FDA authorization backlog:Premarket tobacco product application review timelines extend 12-18 months, freezing product pipeline expansion for unauthorized manufacturers.
- Propylene glycol supply concentration:Pharmaceutical-grade solvent production clusters with three domestic chemical processors, creating input vulnerability.
- Flavor ban geographic fragmentation:Massachusetts and Rhode Island ordinances force inventory segmentation, raising working capital requirements for multi-state operators.
Strategic Opportunities
- Synthetic nicotine classification clarity:Pending FDA determinations on non-tobacco-derived nicotine sources could open regulatory pathways for novel product categories.
- Closed-loop recycling infrastructure:Lithium-ion battery recovery programs in partnership with municipal waste systems address environmental liability while securing raw material streams.
- Telehealth cessation integration:Partnerships with digital health platforms create reimbursement pathways for vape products prescribed as smoking cessation aids.
Industry Challenges
- Premarket authorization documentation:FDA requires longitudinal toxicological studies and behavioral data that demand specialized regulatory affairs talent scarce outside Washington DC consulting corridors.
- State preemption litigation:Conflicting municipal and state ordinances force operators to maintain parallel compliance systems, elevating legal expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US E-Cigarette and Vape Market |
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $23.39 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cigalikes, Vape Pens, Pod Systems, Mods Flavor Category: Tobacco, Menthol, Fruit, Dessert Distribution Channel: Online Retail, Convenience Stores, Vape Shops, Supermarkets Customer Type: Adult Smokers, Young Adults, Health-Conscious Users, Recreational Users |
| Companies Covered | Reynolds American Inc., Altria Group, Inc., Juul Labs, Inc., British American Tobacco, Imperial Brands, Japan Tobacco Inc., NJOY, Elf Bar, International Vapor Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US E-Cigarette and Vape Market Strategic Shifts & Innovations
Product architecture and distribution infrastructure are converging around discrete form factors and direct fulfillment models that reduce physical retail dependency while intensifying regulatory scrutiny on youth access controls.
Ceramic coil heating elements are migrating from premium mod systems into mid-tier pod devices. Enthusiast builders in online communities pioneered porous alumina substrates for temperature stability. Mainstream manufacturers now integrate these components to reduce dry-hit incidence and extend coil lifespan, compressing the performance gap between customizable and closed systems.
FDA Center for Tobacco Products is escalating enforcement against synthetic nicotine products marketed without premarket authorization. The agency's enforcement discretion letters have targeted disposable devices using laboratory-derived nicotine analogues. Manufacturers in states without parallel state-level restrictions are accelerating toxicology submissions to secure marketing orders before potential classification rulings.
Subscription-based cartridge replenishment is replacing single-transaction vape shop visits among heavy users. Direct-to-consumer platforms with age-verification APIs capture recurring revenue from adult smokers in Florida and Texas while bypassing municipal licensing caps. California operators face additional complications from state excise tax collection requirements on shipped products.
US E-Cigarette and Vape Market Segmentation
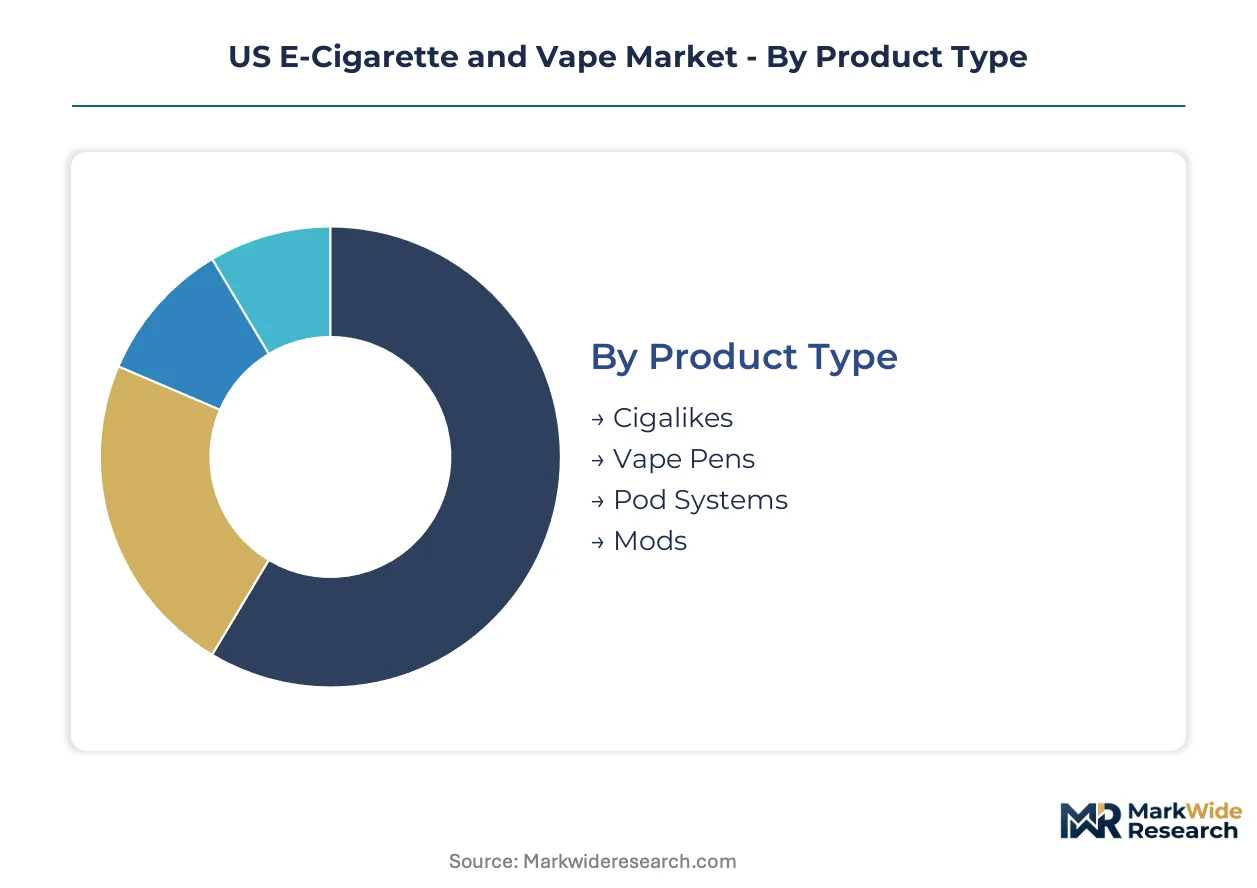
Segmentation in the US E-Cigarette and Vape Market reveals how regulatory pressure and user migration patterns split demand across hardware formats, sensory preferences, and purchase occasions. Manufacturers must align product portfolios with the distinct compliance burdens and margin structures governing each category.
Product Type:
The maturity spectrum spans legacy formats nearing commoditization against emerging systems capturing switching smokers through convenience engineering.
- Pod Systems:Compact, pre-filled or refillable cartridge devices utilizing nicotine salt formulations for rapid absorption. Adult smokers in Texas and Florida drive replenishment velocity through subscription direct-to-consumer channels, constrained by FDA premarket authorization delays for new pod configurations.
- Mods:Customizable, high-wattage devices with rebuildable atomizers and variable voltage control. Coil-building enthusiasts in California metropolitan clusters sustain premium pricing through component aftermarket demand, though municipal flavor bans compress local retail access.
- Vape Pens:Cylindrical, mid-capacity devices bridging disposable convenience with limited customization. Health-conscious users favor these for tobacco-liquid compatibility in channels with stricter age-verification protocols.
- Cigalikes:First-generation devices mimicking combustible cigarette dimensions and draw resistance. Older adult smokers transitioning from traditional cigarettes retain residual demand through convenience store distribution.
Pod Systems retain volume leadership; Mods hold the steepest expansion curve among enthusiast demographics.
Flavor Category:
Cost tier stratification separates premium formulation R&D investments from economy-grade flavor house catalog selections.
- Fruit:Berry, tropical, and orchard profiles utilizing natural and artificial flavorant blends. Young adults in Florida drive the steepest cartridge replenishment rates through online retail, though Massachusetts and Rhode Island ordinances force inventory segmentation for multi-state operators.
- Menthol:Cooling agents combined with mint or tobacco bases for throat-hit mitigation. Adult smokers seeking combustible alternatives concentrate demand in Texas and California, where menthol cigarette restrictions accelerate vape substitution.
- Tobacco:Cured leaf replication through pyrazine and maillard reaction compounds. Convenience store channels serving older demographics sustain baseline volume despite slower growth relative to non-tobacco profiles.
- Dessert:Custard, bakery, and confectionary profiles requiring complex vanillin and lactone formulations. Recreational users in permissive jurisdictions sustain niche premium positioning through specialty vape shop channels.
Fruit flavors command the highest replenishment frequency; Menthol gains share fastest among combustible switchers.
Distribution Channel:
Volume concentration patterns reflect geographic licensing density and age-verification infrastructure maturity.
- Online Retail:Direct-to-consumer platforms with third-party age-verification APIs and excise tax collection systems. Heavy users in Texas and Florida sustain recurring revenue through subscription cartridge replenishment, navigating California's stringent shipment tax compliance.
- Vape Shops:Specialized retail with in-person age verification and coil-building services. California, Texas, and Florida clusters concentrate independent operators leveraging asset-light fixture leasing models.
- Convenience Stores:Mass-market tobacco-alternative placement with limited flavor variety. Adult smokers seeking immediate combustible substitutes drive transaction velocity in states without flavor licensing moratoria.
- Supermarkets:Big-box retail with restricted product lines behind-counter. Health-conscious users favor these channels for perceived legitimacy and standardized age protocols.
Online Retail captures the steepest expansion trajectory; Vape Shops retain margin leadership through service differentiation.
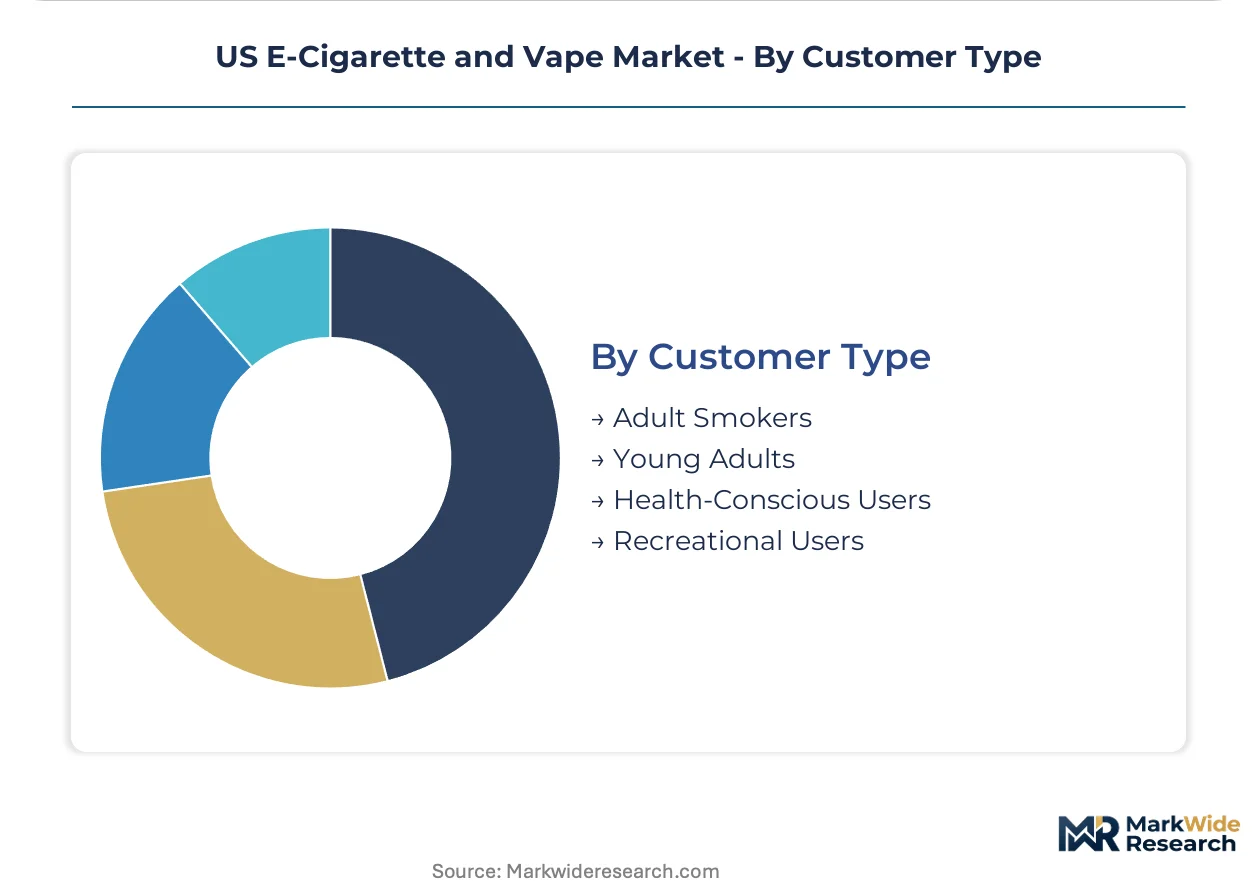
Customer Type:
Application-based segmentation aligns product positioning with cessation intent versus recreational use occasions.
- Adult Smokers:Former combustible users seeking reduced-harm nicotine delivery. California, Texas, and Florida represent the largest expanding buyer segment, prioritizing tobacco and menthol compatibility.
- Young Adults:Demographic cohort favoring discrete form factors and fruit flavor variety. Florida and Texas direct-to-consumer platforms capture this segment through social media-integrated age verification.
- Health-Conscious Users:Consumers prioritizing pharmaceutical-grade ingredients and transparent labeling. Supermarket and pharmacy-adjacent channels serve this segment with propylene glycol and vegetable glycerin purity certifications.
- Recreational Users:Enthusiasts pursuing flavor experimentation and coil customization. California vape shop density and online community engagement sustain this segment despite municipal restrictions.
Adult Smokers retain volume leadership; Young Adults expand most quickly through digital-native purchase behaviors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA premarket tobacco product application requirements and state-level flavor licensing moratoria are compressing competitive access while concentrating demand in permissive jurisdictions with established vape shop infrastructure and direct-to-consumer fulfillment capabilities.
California
Adult smokers transitioning from combustible cigarettes drive the largest buyer segment in Los Angeles and San Francisco metropolitan clusters. The state's flavor ban and excise tax collection requirements on shipped products force inventory segmentation and elevate working capital burdens for multi-state operators. San Diego and Orange County sustain independent vape shop density through asset-light fixture leasing models despite municipal restrictions.
Texas
Heavy users in Houston and Dallas-Fort Worth sustain recurring revenue through subscription-based cartridge replenishment via direct-to-consumer platforms with age-verification APIs. The absence of state-level flavor restrictions permits broader product variety in convenience store and vape shop channels. Austin and San Antonio clusters concentrate coil-building enthusiasts and premium mod aftermarket demand.
Florida
Young adults favoring discrete form factors and fruit flavor variety drive the steepest cartridge replenishment rates through online retail channels in Miami and Tampa metropolitan areas. Social media-integrated age verification captures this demographic segment. Orlando and Jacksonville sustain vape shop density through service differentiation and in-person coil-building communities.
New York
State attorneys general impose additional flavor restrictions and licensing moratoria that reshape retail geography toward permissive neighboring jurisdictions. Adult smokers in New York City metro concentrate demand for tobacco and menthol compatibility through convenience store channels with standardized age protocols. Buffalo and Rochester clusters face compressed local retail access under municipal ordinances.
Massachusetts
Flavor ban ordinances force inventory segmentation and elevate legal expenditure for operators maintaining parallel compliance systems. Boston metropolitan area adult smokers seeking reduced-harm alternatives navigate restricted retail access through cross-border purchasing patterns. Worcester and Springfield clusters experience diminished vape shop density under state-level licensing constraints.
US E-Cigarette and Vape Market Key Industry Players
Channel-controlling players compete with product-specialist players across tiered market positions defined by regulatory preparedness and nicotine delivery technology differentiation. Altria Group leverages smokeless product infrastructure to sustain shelf presence across convenience channels while Juul Labs anchors position through R&D intensity in nicotine salt formulation technology. NJOY competes on regulatory preparedness having secured FDA marketing authorization for multiple device and pod configurations. Strategic moves concentrate on premarket authorization documentation and state preemption litigation defense.
Among large-cap tobacco conglomerates, Reynolds American Inc., Altria Group, Inc., and British American Tobacco occupy positions spanning combustible-to-vapor transition portfolios. These entities exemplify channel-control archetypes leveraging existing distribution infrastructure and regulatory affairs capabilities. Juul Labs and NJOY represent product-specialist archetypes competing through formulation technology and marketing authorization status respectively. The competitive dynamic pits scale-driven regulatory endurance against nimble innovation in nicotine delivery systems.
| Leading Market Players |
|---|
| Reynolds American Inc. |
| Altria Group, Inc. |
| Juul Labs, Inc. |
| British American Tobacco |
| Imperial Brands |
| Japan Tobacco Inc. |
| NJOY |
| Elf Bar |
| International Vapor Group |
| Others |
Cost & Logistics Intelligence
FDA premarket authorization chokepoints determine both pricing tier spreads and supply chain shape by freezing product pipelines for unauthorized manufacturers while concentrating margin capture among authorized incumbents. Pharmaceutical-grade propylene glycol supply concentration with three domestic chemical processors creates input vulnerability that compresses margins for mid-tier pod system assemblers.
Pricing Analysis
FDA marketing authorization status creates the primary spread between premium authorized devices and gray-market alternatives. Three-tier pricing structure across authorized premium, pending-approval standard, and unauthorized economy levels segments buyer willingness-to-pay. Cost compression in the economy tier intensifies because unauthorized imports face escalating enforcement actions. Adult smokers switching from combustibles demonstrate lowest price sensitivity, while young adult recreational users gravitate toward economy disposables.
Supply Chain Analysis
Extended payment terms from Chinese battery cell and ceramic coil substrate suppliers dominate upstream financing arrangements for domestic device assemblers. Manufacturing concentration in China, Malaysia, and Indonesia for lithium-ion cells and heating elements feeds into US final assembly operations. Single-source vulnerability concentrates in pharmaceutical-grade nicotine extraction and propylene glycol refining. Distribution runs through direct-to-consumer platforms with age-verification APIs alongside vape shop and convenience store channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a regulatory cyclical recovery as FDA authorization backlogs gradually clear and adult smoker transition demand stabilizes volume foundations.
For Market Incumbents: Harden regulatory affairs capabilities through specialized toxicological study investments and longitudinal behavioral data collection. Deepen vertical integration into nicotine salt formulation R&D to defend against synthetic nicotine classification disruptions. Secure shelf presence across convenience channels before state-level flavor licensing moratoria expand. For New Entrants and Emerging Players: Asset-light fixture leasing programs in Texas and Florida metropolitan clusters represent the most penetrable entry point for independent vape shop operators. Subscription-based cartridge replenishment platforms with third-party age-verification APIs offer a direct-to-consumer angle bypassing municipal licensing caps. Target coil-building enthusiast communities in Austin and San Antonio for premium mod aftermarket positioning. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors product-specialist archetypes with FDA marketing authorization status. Long-term viability hinges on regulatory endurance rather than formulation innovation alone. Watch pending FDA determinations on synthetic nicotine classification as the inflection indicator for portfolio reallocation between tobacco-derived and laboratory-derived nicotine exposure.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Authorization Pursuit | Marketing orders from FDA Center for Tobacco Products unlock convenience channel distribution and insulate against enforcement actions. |
| Nicotine Salt Formulation R&D | Higher bioavailability delivery systems capture adult smoker switchers seeking combustible alternatives with equivalent satisfaction profiles. |
| Direct-to-Consumer Platform Launch | Age-verification APIs and subscription replenishment models bypass municipal licensing caps in Florida and Texas. |
| Closed-Loop Battery Recovery Partnership | Municipal waste system collaborations address environmental liability while securing lithium-ion raw material streams. |
| Telehealth Cessation Integration | Digital health platform partnerships create reimbursement pathways for vape products prescribed as smoking cessation aids. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with vape shop owners, convenience store category managers, FDA regulatory affairs consultants, and e-liquid formulation chemists. Secondary validation drew from FDA premarket tobacco product application filings, state attorney general flavor restriction ordinances, customs import records, and convenience store distribution data. Bottom-up pod system and mod unit estimates triangulated against top-down nicotine consumption models.
Calibration against historical authorization timelines and state regulatory adoption curves anchored projections across the analysis window. Segmentation dimensions modeled include product type, flavor category, distribution channel, and customer cessation intent. CAGRs derived from regression analysis of adult smoker transition rates and replenishment frequency patterns. FDA review pipeline velocity and synthetic nicotine classification uncertainty fed scenario-weighted outputs.
Macroeconomic conditions sit as an overlay; deviation in disposable income trends among adult smokers or acceleration in state-level flavor ban adoption would shift the trajectory. Forecasts reflect documented assumptions about regulatory clearance timelines and geographic licensing evolution. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tobacco Products
Europe E-Cigarettes Market
Tobacco Products
E-Cigarettes and Vaporizer Market
Tobacco Products
Cigar Tubes Market
Tobacco Products
Heated Tobacco Products Market
Tobacco Products
Global Smokeless Tobacco Market
Tobacco Products
Global E-Cigarettes Market
Tobacco Products
Asia-Pacific E Cigarettes Market
Tobacco Products
Europe Cigarette Vending Machine Market
Tobacco Products
GCC E-Cigarette Market
Tobacco Products
Tobacco Pouch Market
Tobacco Products
Cigarettes Filter Market
Tobacco Products
Smokeless Cigarettes Market
Tobacco Products
North America E-Cigarette Market
Tobacco Products
United States Pipe Tobacco Market
Tobacco Products
Premium Cigarette Market
Tobacco Products
Middle East and Africa E-Cigarettes Market