
 Global E-Cigarettes Market | 2026-2036
Global E-Cigarettes Market Size, Share, and Industry Trends Forecast 2026-2036
Global E-Cigarettes Market Analysis
Multi-source component procurement is realigning competitive economics across the e-cigarettes industry. British American Tobacco PLC leverages its integrated supply chain to secure battery and chipset volumes at scale. Philip Morris International Inc. anchors its position through heated-tobacco R&D spillover into nicotine vapor platforms. JUUL Labs Inc. competes on flavor chemistry and closed-system pod architecture rather than hardware commoditization.
An e-cigarette is a battery-powered electronic device that aerosolizes a liquid solution typically containing propylene glycol, vegetable glycerin, nicotine, and flavoring agents for inhalation. The device activates through either manual button press or draw-activated sensors, with coil resistance ranging from sub-ohm configurations for direct-lung vapor to higher-resistance builds for mouth-to-lung delivery mimicking combustible cigarettes. Pod systems command the fastest expansion trajectory due to convenience and nicotine salt formulation compatibility, while rechargeable devices sustain the largest installed base and aftermarket revenue pool. Distribution through online channels captures margin efficiency but faces escalating age-verification mandates that specialty shops navigate through face-to-face compliance protocols.
The FDA in the United States enforces premarket authorization under the Family Smoking Prevention and Tobacco Control Act, while the EU Tobacco Products Directive caps nicotine concentration and mandates health warnings across member states. China's SAMR and NMPA jointly oversee domestic manufacturing standards and cross-border sales licensing for vapor products. Stakeholders must monitor pending flavor restrictions and battery safety standards that will determine which product architectures retain market access.
Market Dynamics
Regulatory premarket authorization requirements are compressing product development cycles and forcing manufacturers to consolidate compliance infrastructure across multiple jurisdictions simultaneously.
Growth Catalysts
- Nicotine Salt Formulation:The chemistry breakthrough enables higher bioavailability at lower vapor volumes, expanding adoption among former combustible cigarette users seeking comparable satisfaction profiles.
- FDA Premarket Tobacco Product Applications:Authorized products gain shelf stability and retail access advantages that unauthorized competitors forfeit, concentrating revenue among compliant portfolios.
- United States:State-level flavor bans create geographic arbitrage opportunities for manufacturers maintaining federal authorization, redirecting distribution investment toward permissive jurisdictions.
Market Restraints
- Lithium-Ion Battery Supply:Cell production concentrates in China and South Korea, exposing manufacturers to export licensing delays and raw material cost volatility in cobalt and nickel feedstocks.
- EU Tobacco Products Directive:The 20mg/ml nicotine concentration cap and refill container size limits prevent product architecture standardization across Atlantic markets, fragmenting production runs.
- Heated Tobacco Products:IQOS and similar platforms compete for the same harm-reduction positioning with established regulatory pathways and tobacco industry marketing infrastructure.
Strategic Opportunities
- India:The absence of federal vapor product authorization creates first-mover advantage for manufacturers navigating state-level pharmaceutical and drug control interpretations.
- Closed-System Recycling Infrastructure:Pod collection and material recovery programs address emerging extended producer responsibility frameworks in Germany and France while generating aftermarket revenue streams.
- Artificial Intelligence and Sensor Fusion:Draw-pattern recognition and usage-monitoring chipsets enable personalized nicotine delivery and compliance-age verification integration.
Industry Challenges
- Toxicology Submission Expertise:FDA premarket authorization requires aerosol constituent testing and population-level health impact modeling that few manufacturers have built in-house.
- Flavor Chemistry IP:Patent thickets around heat-stable compounds and inhalation safety profiles complicate formulation freedom-to-operate assessments and licensing negotiations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global E-Cigarettes Market |
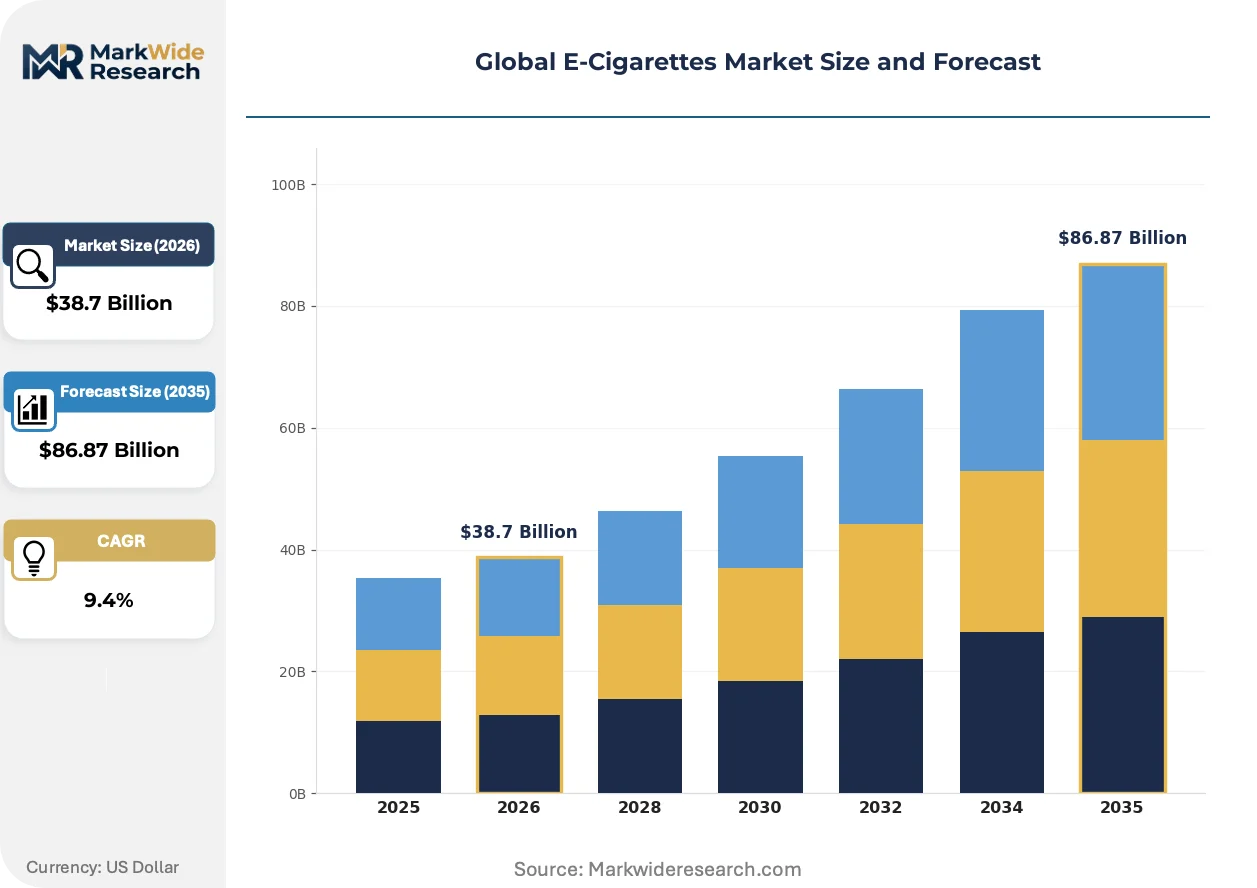
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $86.87 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Rechargeable, Pod Systems, Mods Flavor: Tobacco, Menthol, Fruit, Dessert Distribution Channel: Online, Convenience Stores, Specialty Shops, Supermarkets Consumer Age Group: 18-24, 25-34, 35-44, 45+ |
| Companies Covered | Philip Morris International Inc., Altria Group Inc., British American Tobacco PLC, Japan Tobacco International, Imperial Brands, JUUL Labs Inc., SMOK, Innokin Technology Ltd., GEEKVAPE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global E-Cigarettes Market Emerging Trajectories
Product architecture is bifurcating between disposable convenience formats and rechargeable precision devices, with chemistry and chipset differentiation replacing hardware commoditization as the primary value capture mechanism.
Ceramic coil heating elements are electrifying temperature control precision in pod systems. Young adult consumers aged 18-24 in the United Kingdom and United States are migrating toward these configurations for flavor consistency and reduced dry-hit incidence. The technology is electrifying competition away from traditional kanthal wire builds toward materials science partnerships with semiconductor foundries.
REACH chemical registration requirements in Europe are forcing reformulation of flavor compounds and carrier solvents. Manufacturers must submit full toxicological dossiers for substances above one ton annual volume, extending product development timelines by 18-24 months. Pod system producers with existing authorized portfolios are freezing flavor ranges rather than absorbing registration costs for marginal variants.
Specialty vape shops are ceding volume to convenience retail chains with automated age-verification kiosks. The channel shift concentrates purchasing power among distributors capable of integrating real-time ID scanning with state prescription monitoring databases. This transformation is most visible in California and New York, where municipal licensing density caps have accelerated independent store closures.
Global E-Cigarettes Market Segmentation
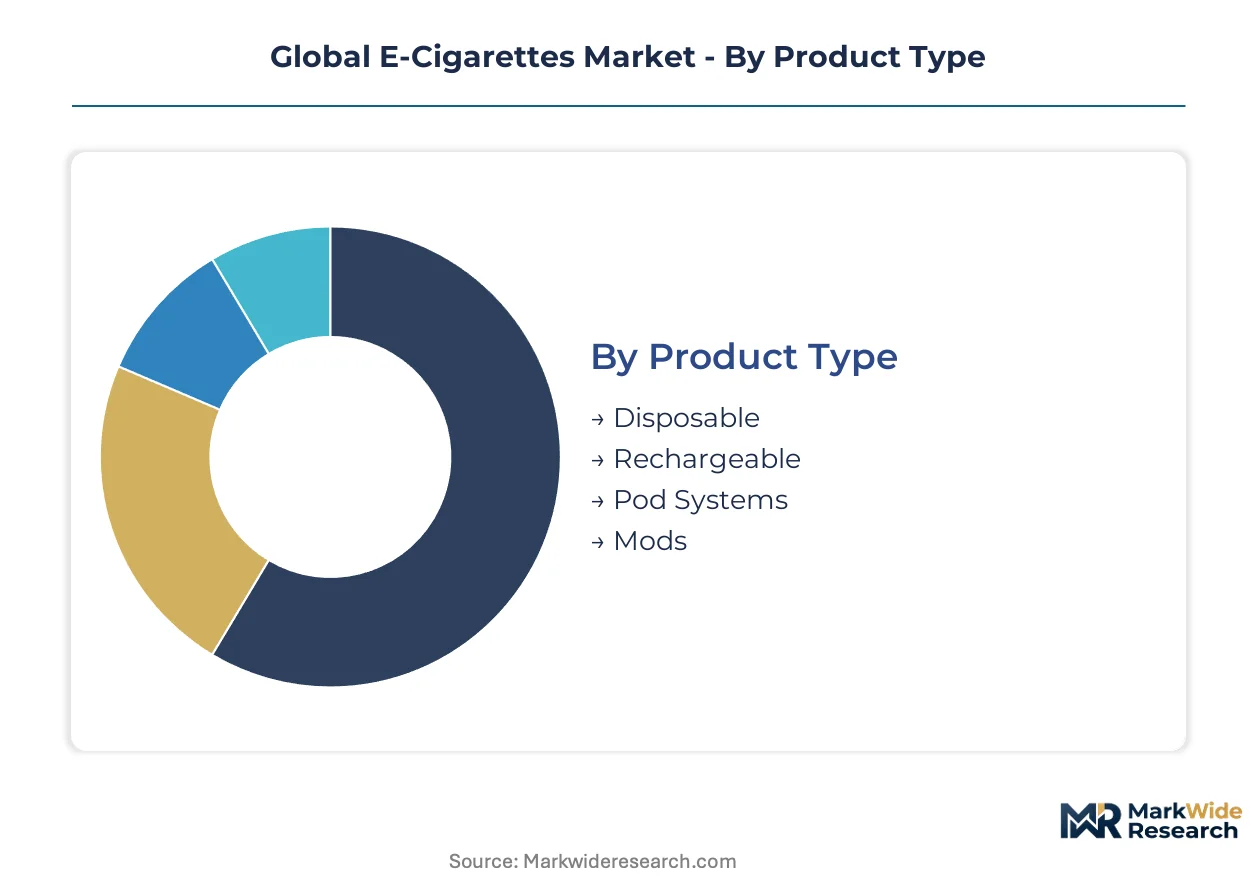
E-cigarette market segmentation reveals how regulatory compliance burdens concentrate differently across hardware formats, flavor categories, and distribution channels. Manufacturers must align product architectures with specific authorization pathways to retain market access.
Product Type:
FDA premarket tobacco product applications impose distinct toxicology submission requirements on each hardware architecture, with closed systems facing lower aerosol variability burdens than open-platform devices.
- Disposable:Single-use lithium-ion cells and pre-filled reservoirs eliminate user maintenance but trigger higher per-unit environmental compliance costs under Germany's extended producer responsibility frameworks. Demand concentrates in convenience retail channels across permissive U.S. jurisdictions where flavor bans have not taken effect.
- Pod Systems:Closed-system cartridge architecture enables precise nicotine salt dosing and temperature-controlled ceramic coil integration. United Kingdom and United States consumers aged 18-24 drive replacement pod velocity through flavor-seeking behavior.
- Rechargeable:Modular battery systems sustain the largest installed base through coil and tank aftermarket revenue. China's SAMR manufacturing standards dominate component sourcing.
- Mods:Variable-wattage open platforms appeal to enthusiast segments but face escalating battery safety certification requirements under EU directives.
Leading the category by volume: Rechargeable. Growing fastest: Pod Systems.
Flavor:
Flavor chemistry determines regulatory risk exposure, with heat-stable compound portfolios requiring REACH registration in Europe and toxicology dossiers for FDA authorization.
- Tobacco:Synthetic and extracted tobacco alkaloid formulations align with smoking cessation positioning and face lower restriction probability in flavor-ban jurisdictions.
- Menthol:Cooling agent chemistry interacts with nicotine salt bioavailability profiles. EU Tobacco Products Directive health warning placement affects packaging economics.
- Fruit:Ester-based formulations command premium pricing among young adult consumers but face municipal prohibition in California and New York localities.
- Dessert:Vanillin and lactone compounds require extended stability testing. Manufacturers freeze range expansion rather than absorb REACH registration costs.
Most defensible against regulatory rollback: Tobacco. Steepest expansion trajectory: Fruit.
Distribution Channel:
Age-verification infrastructure investments segment channel economics, with automated ID scanning capabilities determining access to state prescription monitoring database integrations.
- Online:Direct-to-consumer models capture margin efficiency but face escalating FDA enforcement against unauthorized product shipments.
- Convenience Stores:Automated kiosk verification enables volume scale in chains with real-time compliance systems.
- Specialty Shops:Face-to-face age protocols navigate municipal licensing density caps but cede volume to convenience retail.
- Supermarkets:Mass retail shelf space concentrates among manufacturers with authorized portfolios and established trade relationships.
Highest compliance infrastructure requirement: Online. Fastest channel shift: Convenience Stores.
Consumer Age Group:
Nicotine salt formulation bioavailability and draw-activation preferences segment adoption patterns across demographic cohorts.
- 18-24:Pod system preference dominates with flavor-seeking behavior and social use occasions driving product trial.
- 25-34:Former combustible cigarette users prioritize nicotine satisfaction parity and device portability.
- 35-44:Smoking cessation intent concentrates demand toward tobacco-flavored rechargeable systems with cost-per-use optimization.
- 45+:Medicalized positioning and harm-reduction messaging resonate with physician-guided adoption pathways.
Largest absolute volume: 25-34. Gaining share fastest: 18-24.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for e-cigarettes concentrates in the United States, China, and the United Kingdom, with regulatory fragmentation creating divergent product architectures across these three markets.
United States
FDA premarket tobacco product applications and state-level flavor bans drive geographic arbitrage in distribution investment. The Family Smoking Prevention and Tobacco Control Act mandates aerosol constituent testing that few manufacturers have built in-house. California and New York municipal licensing density caps accelerate independent specialty shop closures while concentrating volume in convenience retail chains with automated age-verification kiosks.
China
SAMR and NMPA jointly oversee domestic manufacturing standards and cross-border sales licensing for vapor products. The country's battery and chipset production clusters in Shenzhen and Dongguan supply component volumes to global manufacturers. Export licensing delays for lithium-ion cells expose foreign assemblers to raw material cost volatility in cobalt and nickel feedstocks.
United Kingdom
Medicines and Healthcare products Regulatory Agency pathways for licensed smoking cessation products create dual-track market access. The MHRA's 20mg/ml nicotine concentration guidance aligns with EU Tobacco Products Directive caps while permitting broader flavor ranges than U.S. jurisdictions. London and Manchester retail corridors concentrate pod system trial among consumers aged 18-24.
Germany
Extended producer responsibility frameworks under the Electrical and Electronic Equipment Act impose per-unit environmental compliance costs on disposable formats. REACH chemical registration requirements force reformulation of flavor compounds and carrier solvents, extending product development timelines by 18-24 months. Berlin and Hamburg distribution networks navigate federal pharmaceutical interpretations of nicotine-containing products.
Japan
Pharmaceutical and Medical Device Agency classification of nicotine-containing vapor products as medicinal limits retail channels to pharmacies and licensed vendors. METI standards for battery safety certification shape import requirements for rechargeable devices. Tokyo and Osaka convenience retail chains integrate real-time ID scanning with prescription monitoring databases.
Global E-Cigarettes Market Vendor Landscape
Portfolio diversification dominates the current landscape as manufacturers hedge across heated-tobacco, nicotine vapor, and synthetic nicotine platforms. The vendor base fragments between tobacco majors with integrated supply chains, independent hardware specialists, and chemistry-focused closed-system operators. Three archetypes define positioning: scale-driven integrated players, flavor-chemistry specialists, and component-assembly contract manufacturers. M&A activity and strategic partnerships concentrate compliance infrastructure across multiple jurisdictions simultaneously.
Among integrated tobacco multinationals, Philip Morris International Inc., British American Tobacco PLC, and Altria Group Inc. occupy positions that exemplify backward integration into battery and chipset procurement. These players anchor the premium-tier vector through captive supply relationships and in-house toxicology submission capabilities. Their scale enables absorption of FDA premarket authorization costs that fragment smaller competitors.
| Leading Market Players |
|---|
| Philip Morris International Inc. |
| Altria Group Inc. |
| British American Tobacco PLC |
| Japan Tobacco International |
| Imperial Brands |
| JUUL Labs Inc. |
| SMOK |
| Innokin Technology Ltd. |
| GEEKVAPE |
| Others |
Supply Flow & Price Mechanics
Convenience retail chains with automated age-verification kiosks concentrate purchasing power and enforce three-tier pricing structure across premium, standard, and economy levels. FDA premarket authorization costs and lithium-ion battery feedstock volatility feed directly into margin structures across hardware tiers.
Pricing Analysis
Warranty and after-sales service bundling separates authorized manufacturers from unauthorized competitors in the United States. Premium-tier closed-system pods with ceramic coil integration and toxicology dossier backing command pricing separation from standard-tier rechargeable devices and economy disposable formats. Pricing pressure stems from cobalt and nickel cost volatility in battery cell production. Former combustible cigarette users aged 25-34 demonstrate lowest price sensitivity due to harm-reduction positioning, while young adult flavor-seekers aged 18-24 exhibit highest elasticity.
Supply Chain Analysis
Dual-sourcing mandates from major OEMs require battery cell qualification across both Chinese and South Korean suppliers. Shenzhen and Dongguan manufacturing clusters in China anchor global component volumes, while South Korean semiconductor foundries supply temperature-control chipsets. Lithium-ion cell production draws from cobalt and nickel feedstocks concentrated in the Democratic Republic of Congo and Indonesia. Single-source vulnerability in ceramic coil materials from specific semiconductor partnerships creates qualification bottlenecks. Distribution runs through convenience retail chains with real-time ID scanning integration in California and New York.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell production capacity constraints in lithium-ion battery manufacturing prop pricing power for manufacturers with qualified supplier relationships. Component scarcity favors incumbents with existing authorization portfolios.
For Market Incumbents: Anchor market position through backward integration into ceramic coil semiconductor partnerships and captive battery cell offtake agreements. Heated tobacco product competition from IQOS platforms and synthetic nicotine entrants threatens vapor segment share. Prioritize FDA premarket authorization maintenance and state-level flavor ban navigation to defend retail access. For New Entrants and Emerging Players: Begin with white-space targeting in India's state-level pharmaceutical interpretation markets and Germany's extended producer responsibility recycling infrastructure. India's absence of federal vapor authorization creates first-mover qualification pathways. Deploy closed-system pod architectures with nicotine salt compatibility to minimize toxicology submission burdens versus open-platform alternatives. For Investors and Strategic Acquirers: The window for entry favors manufacturers with existing FDA-authorized portfolios and REACH-registered flavor chemistry libraries. Long-term viability hinges on regulatory compliance infrastructure scalability rather than hardware innovation alone. Monitor FDA enforcement actions against unauthorized product shipments as the primary inflection signal for market consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Authorization Investment | Toxicology submission capabilities concentrate revenue among compliant portfolios in the United States. |
| Ceramic Coil Semiconductor Partnership | Temperature-control precision differentiates pod systems from kanthal wire commodity builds. |
| Extended Producer Responsibility Program | Pod collection infrastructure addresses German environmental compliance while generating aftermarket revenue. |
| Nicotine Salt Formulation Patent Licensing | Heat-stable compound IP thickets restrict formulation freedom-to-operate for unauthorized competitors. |
| Automated Age-Verification Kiosk Deployment | Real-time ID scanning integration enables convenience retail volume scale in California and New York. |
Methodological Framework
Independent corroboration across regulatory filing databases, customs trade records, and retail audit panels underwrites the qualitative findings. Primary interviews with toxicology submission consultants, ceramic coil materials scientists, convenience retail procurement directors, and FDA regulatory affairs specialists combined with secondary validation from FDA premarket tobacco product application filings, ECHA REACH registration databases, SAMR manufacturing standard disclosures, and EU Tobacco Products Directive implementation reports. Bottom-up pod velocity estimates and top-down market sizing triangulate volume figures.
Comparable historical periods spanning pre- and post-TPD implementation in Europe and pre- and post-Deeming Rule enforcement in the United States anchor the forecast window. The analytical framework segments by hardware architecture, flavor chemistry category, distribution channel compliance infrastructure, and consumer age cohort nicotine delivery preference across the projection horizon. CAGRs derive from replacement pod velocity modeling and device installed base depreciation curves. Forecast inputs include battery cell production capacity expansion timelines and municipal flavor ban legislative tracking.
FDA authorization timeline delays, REACH chemical registration cost inflation, and lithium-ion export licensing disruptions are the dominant revision risks. Deviation in FDA enforcement intensity against unauthorized shipments would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tobacco Products
US E-Cigarette and Vape Market
Tobacco Products
Nicotine Pouches Market
Tobacco Products
United States Pipe Tobacco Market
Tobacco Products
North America E-Cigarette Market
Tobacco Products
Global Cigarette Vending Machine Market
Tobacco Products
Asia-Pacific E Cigarettes Market
Tobacco Products
Africa Tobacco Products Market
Tobacco Products
Tobacco Products Market
Tobacco Products
Cigarette Market
Tobacco Products
West Africa Cigarettes Market
Tobacco Products
Latin America E-Cigarette Market
Tobacco Products
Smokeless Cigarettes Market
Tobacco Products
Global Smokeless Tobacco Market
Tobacco Products
Europe Cigarette Vending Machine Market
Tobacco Products
Electronic Cigarette Atomizer Market
Tobacco Products
Europe E-Cigarettes Market