
 United States E-Cigarette Market | 2026-2036
United States E-Cigarette Market Size, Share, and Industry Trends Forecast 2026-2036
United States E-Cigarette Market Intelligence
Pod-based nicotine salt formulation is rewriting the hardware-liquid interface across the United States e-cigarette landscape. Juul Labs Inc. leverages its early nicotine salt patent position to sustain brand recognition despite regulatory headwinds. Altria Group Inc. anchors its exposure through a strategic minority stake in Juul, while British American Tobacco competes via the Vuse Alto platform with integrated supply chain control over both device and pod production.
United States e-cigarettes are battery-powered aerosolization devices that heat propylene glycol, vegetable glycerin, nicotine, and flavoring compounds to temperatures between 200°C and 350°C, producing an inhalable vapor intended to simulate smoking without combustion. The pod-based segment dominates unit economics through recurring pod purchases, while disposable formats attract trial users and younger demographics with zero-maintenance convenience. Flavor type stratification shows menthol and fruit variants driving repeat purchase frequency, though regulatory pressure on non-tobacco flavors threatens margin pools in the dessert and fruit categories.
FDA Center for Tobacco Products enforcement of premarket authorization requirements, combined with state-level flavor bans in jurisdictions like California and Massachusetts, constricts product portfolios and elevates compliance costs for market participants. The FTC monitors advertising practices targeting youth, while state attorneys general pursue litigation that shapes settlement-driven market restructuring. Stakeholders must monitor PMTA authorization outcomes and state legislative calendars to determine which product formats and flavor portfolios warrant continued manufacturing investment versus strategic abandonment.
Market Dynamics
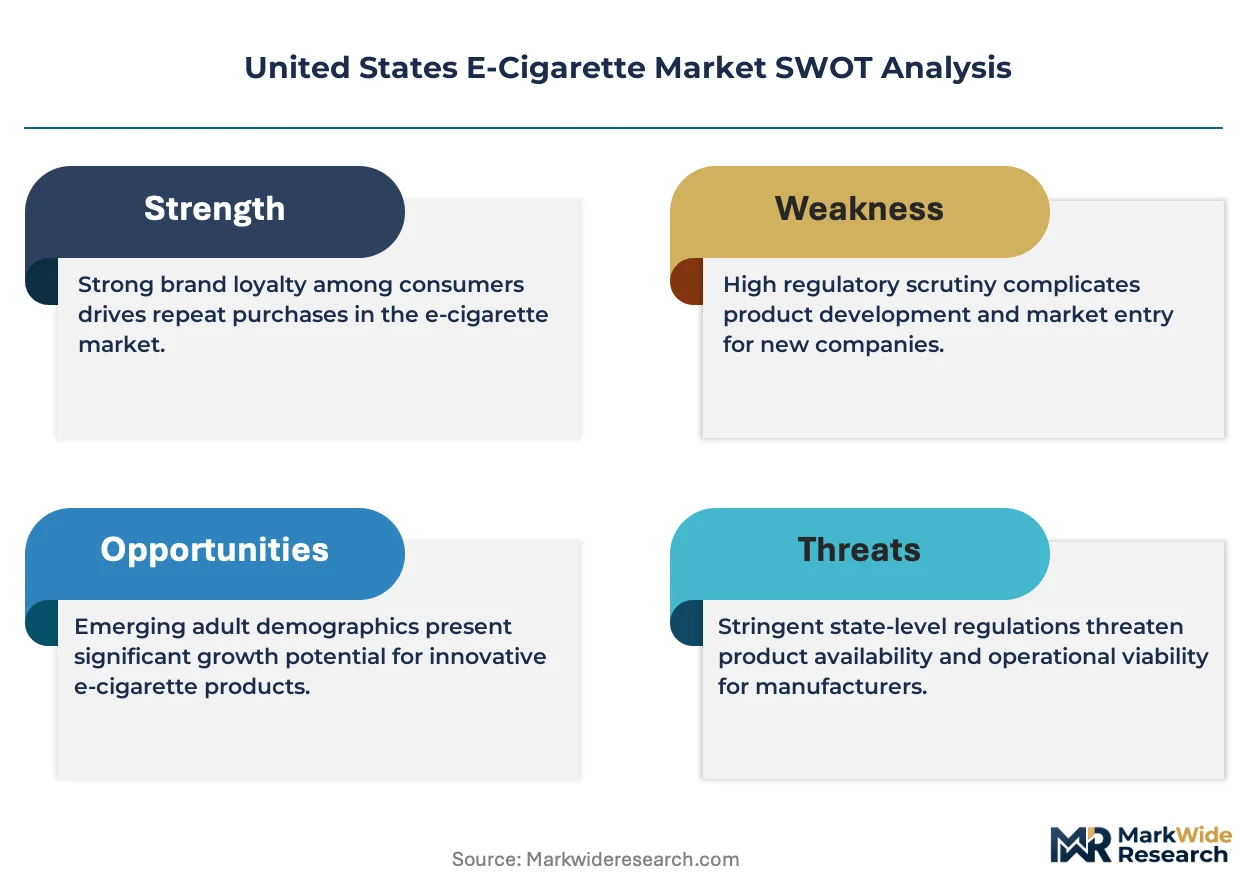
Pod-based nicotine salt systems concentrate consumer loyalty through recurring cartridge purchases while FDA premarket tobacco product application enforcement eliminates non-compliant competitors, compressing the vendor base toward authorized manufacturers with sufficient compliance infrastructure.
Growth Catalysts
- Adult Smoker Migration:Former combustible tobacco users in California, Texas, and Florida seek reduced-harm alternatives, concentrating demand in states with established vape retail networks and dense urban populations.
- PMTA Authorization Pathway:FDA Center for Tobacco Products enforcement creates a regulatory moat that rewards manufacturers with authorized product portfolios and eliminates gray-market competition.
- Nicotine Salt Chemistry:Benzoic acid formulations enable higher nicotine concentration at reduced throat irritation, expanding addressable users among adult smokers previously deterred by harsh free-base nicotine aerosols.
Market Restraints
- Flavor Portfolio Constriction:State-level prohibitions in California and Massachusetts remove fruit and dessert variants from legal commerce, compressing margin pools and forcing portfolio rationalization toward tobacco and menthol SKUs.
- Supply Chain Concentration:Domestic manufacturing of pod hardware concentrates in Shenzhen-linked contract manufacturers, exposing participants to tariff volatility and logistics disruption across Pacific shipping lanes.
- Youth Access Liability:FTC monitoring of digital advertising practices and state attorneys general litigation create settlement exposure that elevates compliance costs and restricts marketing channels.
Strategic Opportunities
- Texas and Florida Expansion:Underpenetrated metro corridors in Houston, Dallas, Miami, and Orlando offer whitespace for retail footprint expansion and localized distribution partnerships.
- Tobacco-Derived Nicotine Synthesis:Synthetic nicotine formulations fall outside certain statutory definitions, creating a regulatory arbitrage window for product architectures that bypass traditional tobacco sourcing.
- Direct-to-Consumer Subscription:Recurring auto-ship models for authorized pod refills capture lifetime value while reducing customer acquisition costs through retention economics.
Industry Challenges
- Toxicology Study Requirements:PMTA submissions demand extensive aerosol chemistry and clinical endpoint data, requiring multi-million dollar investment timelines that strain mid-tier manufacturer balance sheets.
- Retail Licensing Fragmentation:Municipal and county-level vape shop permitting varies across jurisdictions, complicating national rollout strategies and forcing location-by-location compliance verification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States E-Cigarette Market |
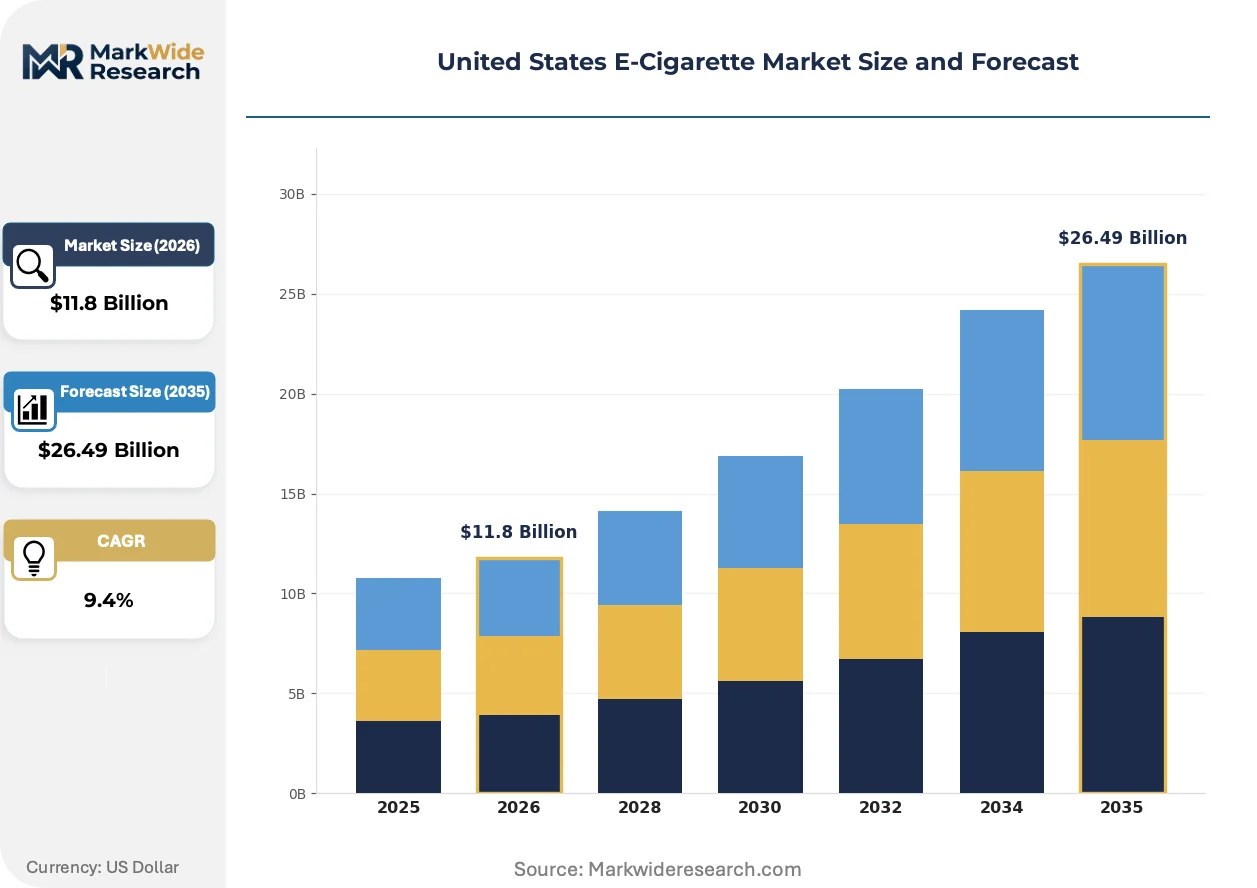
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $26.49 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Rechargeable, Pod-Based, Multi-Use Flavor Type: Tobacco, Menthol, Fruit, Dessert Distribution Channel: Online Retail, Convenience Stores, Specialty Shops, Gas Stations Consumer Segment: Teenagers, Young Adults, Adults, Former Smokers |
| Companies Covered | Vuse, Juul Labs Inc., Altria Group Inc., British American Tobacco, NJOY, Elf Bar, Breeze Smoke, Geekvape, Imperial Brands, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States E-Cigarette Market Strategic Shifts & Innovations
Hardware-liquid integration, synthetic nicotine chemistry, and channel consolidation are compressing the competitive set toward vertically controlled supply chains with regulatory authorization.
Ceramic coil heating elements are migrating from sub-ohm tank systems into pod-based architectures. Adult users seeking flavor consistency and reduced dry-hit incidence adopt ceramic wicking at accelerating rates. This thermal management improvement is migrating from premium disposable formats into refillable pod systems, enabling higher-VG formulations previously incompatible with cotton wicking.
FDA enforcement of premarket authorization deadlines eliminates non-compliant disposable and pod products from interstate commerce. Manufacturers with authorized portfolios gain shelf space and pricing power as competitors exit. The disposable segment faces the steepest contraction, with retail inventory shifts toward PMTA-authorized pod systems and tobacco-derived nicotine alternatives.
Convenience store and gas station channels displace dedicated vape shops as primary purchase points for authorized products. Adult smokers seeking substitution encounter e-cigarettes at existing tobacco retail locations rather than specialty destinations. This channel rotation concentrates volume in California, Texas, and Florida c-store networks with existing tobacco distribution infrastructure.
United States E-Cigarette Market Segmentation
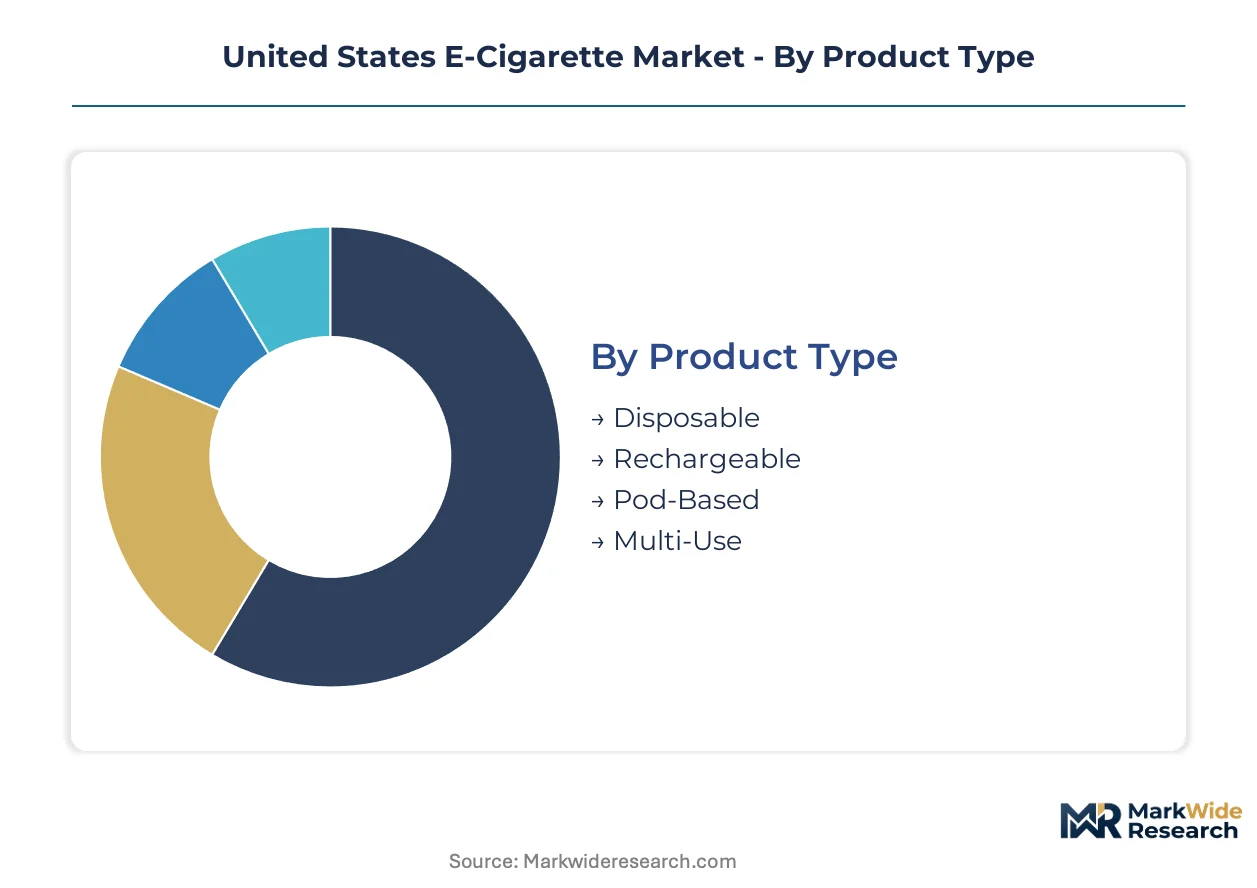
Segmentation reveals divergent replacement cycles across the United States e-cigarette landscape, with disposable formats turning over weekly while rechargeable hardware persists for months. Understanding these velocity differentials shapes inventory planning and margin capture strategies for participants across the value chain.
Product Type:
Cycle times vary dramatically from single-use disposables replaced within days to multi-use systems maintained for quarters, creating distinct working capital profiles and customer lifetime value calculations.
- Pod-Based:Closed-system cartridges containing nicotine salt formulations generate recurring revenue through proprietary pod replacements. Adult smokers in California, Texas, and Florida drive concentration where established retail networks support repeat purchase behavior despite FDA premarket authorization constraints.
- Disposable:Single-use devices with integrated batteries and pre-filled e-liquid reservoirs eliminate maintenance entirely. Trial users and younger demographics in urban corridors favor zero-commitment formats, though enforcement actions against non-PMTA-authorized inventory threaten shelf availability.
- Rechargeable:Open-tank systems with replaceable coils and refillable reservoirs appeal to enthusiast segments seeking customization control over wattage and airflow parameters.
- Multi-Use:Modular platforms accommodating both pod and tank configurations through interchangeable components serve users transitioning between convenience and control preferences.
Pod-based systems anchor the volume base while disposable formats gain share at the steepest rate among entry-level users.
Flavor Type:
Margin profiles stratify across flavor categories, with synthetic formulations commanding premium positioning against tobacco-derived alternatives facing agricultural input volatility.
- Fruit:Berry and tropical variants dominate repeat purchase frequency among adult users under 35, though California and Massachusetts state-level prohibitions remove these SKUs from legal commerce in key markets.
- Menthol:Cooling agents combined with nicotine salts sustain loyalty among former menthol cigarette smokers seeking sensory parity. Texas and Florida retail networks report sustained velocity despite regulatory scrutiny of characterizing flavors.
- Tobacco:Blended and straight tobacco profiles align with FDA-authorized product portfolios, offering compliance certainty as fruit and dessert variants face portfolio rationalization pressures.
- Dessert:Custard, vanilla, and bakery-inspired formulations attract flavor-chasing enthusiasts but confront the steepest regulatory headwinds as youth-appeal scrutiny intensifies.
Menthol and tobacco variants provide the compliance anchor while fruit flavors climb fastest in permissive jurisdictions.
Distribution Channel:
Channel economics reflect divergent foot traffic patterns and regulatory exposure, with convenience formats scaling through existing tobacco infrastructure while specialty destinations face municipal licensing fragmentation.
- Convenience Stores:C-store networks in California, Texas, and Florida leverage existing tobacco distribution relationships to capture adult smoker substitution demand. Shelf placement adjacent to combustible products drives impulse trial among target demographics.
- Gas Stations:Highway-adjacent locations with extended operating hours serve replacement purchases outside traditional retail windows, though inventory depth constraints limit format variety.
- Online Retail:Direct-to-consumer platforms face age-verification compliance costs and shipping restrictions that elevate customer acquisition expenses relative to physical channels.
- Specialty Shops:Dedicated vape retailers concentrate in urban corridors with knowledgeable staff supporting device troubleshooting and flavor sampling, though municipal permitting varies block-by-block.
Convenience stores carry the volume foundation while gas station placement expands most quickly through petroleum retail partnerships.
Consumer Segment:
User archetypes span cessation-motivated former smokers through recreational adopters, each presenting distinct regulatory risk profiles and product specification requirements.
- Former Smokers:Adults seeking reduced-harm alternatives to combustible tobacco represent the core addressable market with strongest clinical validation support and FDA authorization pathway alignment.
- Adults:Non-smoking adult adopters drive incremental category expansion, though marketing restrictions limit outreach to this segment without youth-exposure liability.
- Young Adults:Users aged 21-30 demonstrate highest flavor variety experimentation rates and social use occasion frequency, concentrating in metropolitan clusters with dense nightlife infrastructure.
- Teenagers:Underage access represents regulatory enforcement priority with FTC monitoring and state attorneys general litigation creating settlement exposure across the industry.
Former smokers constitute the stable demand base while adult non-smokers represent the expanding frontier requiring careful targeting compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Former smokers in California, Texas, and Florida drive the core demand concentration for reduced-harm alternatives, with urban density and established vape retail networks sustaining above-average per-capita consumption across these three states.
California
Adult consumers in Los Angeles and San Francisco metro corridors seek menthol and tobacco variants after state-level flavor prohibitions removed fruit and dessert SKUs from legal commerce. The California Department of Public Health enforces retail licensing requirements that elevate compliance costs for dedicated vape shops. San Diego's coastal urban cluster maintains specialized retail destinations despite municipal permitting fragmentation.
Texas
Houston and Dallas-Fort Worth metro areas present whitespace for retail footprint expansion, with convenience store networks capturing adult smoker substitution demand through existing tobacco distribution relationships. The Texas Department of State Health Services monitors youth access compliance while avoiding the flavor restrictions seen in coastal states. Austin's young adult demographic concentrates flavor experimentation behavior in nightlife corridors.
Florida
Miami and Orlando urban corridors sustain pod-based nicotine salt velocity through gas station and convenience store channels with extended operating hours. The Florida Department of Business and Professional Regulation oversees retail licensing with county-level variation that complicates statewide rollout strategies. Tampa Bay's established vape retail infrastructure supports repeat purchase behavior among former combustible tobacco users.
New York
New York City metro density supports specialty shop concentration despite municipal permitting constraints and flavor portfolio limitations. The New York State Department of Health enforces comprehensive flavor restrictions that compress margin pools toward tobacco and menthol SKUs. Buffalo and Rochester industrial corridors see convenience store channel displacement of dedicated retailers.
Illinois
Chicago metro adult smokers access authorized products through petroleum retail partnerships at highway-adjacent locations. The Illinois Department of Public Health coordinates with FDA enforcement actions to remove non-PMTA-authorized inventory from interstate commerce. Springfield and Peoria secondary markets exhibit underpenetrated convenience store networks relative to coastal demand centers.
United States E-Cigarette Market Key Industry Players
Channel-controlling players compete with product-specialist players across a bifurcated structure where FDA authorization status determines shelf access. The vendor base compresses toward authorized manufacturers with sufficient compliance infrastructure to sustain PMTA-submitted portfolios. Three archetypes dominate: legacy tobacco conglomerates with integrated supply chains, independent hardware specialists with Shenzhen manufacturing linkages, and disposable-format importers facing enforcement-driven inventory constraints. Competitive moves center on portfolio rationalization toward authorized SKUs and direct-to-consumer subscription models that capture lifetime value.
Within the legacy tobacco tier, British American Tobacco and Altria Group Inc. occupy positions anchored by strategic stakes and integrated device-pod production control. Juul Labs Inc. exemplifies the nicotine salt patent-holder archetype sustaining brand recognition despite regulatory headwinds. Among independent specialists, Geekvape represents hardware-focused fabrication with ceramic coil thermal management capabilities.
| Leading Market Players |
|---|
| Vuse |
| Juul Labs Inc. |
| Altria Group Inc. |
| British American Tobacco |
| NJOY |
| Elf Bar |
| Breeze Smoke |
| Geekvape |
| Imperial Brands |
| Others |
Cost & Logistics Intelligence
Undercapacity in Shenzhen-linked battery cell fabrication is elevating procurement premiums for pod system manufacturers while compressing margin pools across the mid-tier hardware segment. This utilization squeeze forces authorized manufacturers toward long-term offtake commitments that lock in component costs, while gray-market competitors absorb spot-price volatility that destabilizes their pricing posture.
Pricing Analysis
Cost-plus contracts with lithium-ion cell indexation dominate procurement agreements between pod system assemblers and Shenzhen contract manufacturers. Price differentiation hinges on FDA PMTA authorization status and ceramic coil thermal management certification, with authorized portfolios commanding shelf-space premiums against unauthorized alternatives. Pricing pressure intensifies downward among disposable formats facing enforcement-driven inventory liquidation. Former smokers demonstrate lowest price sensitivity due to substitution economics, while trial users in entry segments exhibit elastic demand response.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard in supply-chain finance facilities extended to Shenzhen contract manufacturers serving US pod system brands. Geographic concentration centers on China for battery cells and ceramic heating elements, Malaysia for chip assembly, and Mexico for final packaging and fulfillment. Raw material dependencies include lithium carbonate, nickel-manganese-cobalt cathode formulations, and medical-grade propylene glycol. Tariff exposure across Pacific shipping lanes threatens margin stability. Distribution runs through California, Texas, and Florida c-store networks with established tobacco distribution infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Adult smoker migration to reduced-harm alternatives represents an early-cycle expansion tailwind with sustained penetration runway ahead. FDA authorization barriers concentrate competitive returns among compliant portfolios with established retail access.
For Market Incumbents: Harden regulatory moats through PMTA portfolio expansion beyond current authorized SKUs, prioritizing synthetic nicotine formulations that bypass agricultural supply volatility. Deepen backward integration into ceramic coil fabrication to secure thermal management capabilities against specialist component suppliers. Channel control through exclusive petroleum retail partnerships in Texas and Florida defends shelf access against emerging entrants. For New Entrants and Emerging Players: Establish a beachhead in direct-to-consumer subscription models for authorized pod refills, capturing lifetime value while bypassing c-store slotting fee barriers. Target underpenetrated metro corridors in Houston, Dallas, Miami, and Orlando where convenience store networks lack dedicated vape retail competition. Synthetic nicotine chemistry offers regulatory arbitrage for product architectures without tobacco-derived supply dependencies. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across PMTA submission and toxicology study requirements, favoring balance-sheet strength over operational agility. Long-term viability over the next decade rests on FDA authorization durability and flavor portfolio resilience against state-level prohibitions. Acquisition targets with ceramic coil intellectual property and Shenzhen manufacturing relationships warrant priority evaluation. The signal to monitor is PMTA authorization velocity relative to competitor exit rates.| Strategic Initiative | Industry Significance |
|---|---|
| PMTA Portfolio Expansion | FDA authorization creates shelf access moats that eliminate non-compliant competitors from interstate commerce. |
| Synthetic Nicotine Transition | Tobacco-derived nicotine alternatives bypass agricultural input volatility and certain statutory definitions. |
| Ceramic Coil Integration | Thermal management improvements enable higher-VG formulations with reduced dry-hit incidence for flavor consistency. |
| Direct-to-Consumer Subscription | Auto-ship models capture lifetime value while reducing customer acquisition costs through retention economics. |
| Petroleum Retail Partnership | Extended-hour c-store networks in Texas and Florida displace dedicated vape shops as primary purchase points. |
Research Approach
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings in this study. Conversations with vape retail operators, convenience store category managers, FDA regulatory consultants, and pod system hardware engineers combined with FDA PMTA submission databases, FTC enforcement actions, state attorneys general litigation records, and customs import data. Bottom-up demand modeling across product type, flavor category, distribution channel, and consumer segment triangulates against top-down market sizing.
Calibration against historical authorization timelines and enforcement intensity patterns shapes the projection framework. Segmentation dimensions modeled include pod-based versus disposable versus rechargeable formats, menthol-tobacco-fruit-dessert flavor stratification, convenience store-gas station-online-specialty shop channel mix, and former smoker-adult non-smoker-young adult demographic splits. CAGRs derive from replacement cycle velocity differentials and per-capita consumption trends. Forecast inputs incorporate PMTA approval probability assessments and state-level flavor prohibition legislative tracking.
Sensitivities concentrate around FDA authorization velocity, state-level flavor ban expansion, and lithium-ion cell supply disruptions. Forecasts reflect documented assumptions regarding adult smoker substitution rates and enforcement intensity. Macroeconomic contraction affecting discretionary spending, regulatory deviation in PMTA standards, or synthetic nicotine reclassification would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tobacco Products
Global Smokeless Tobacco Market
Tobacco Products
Asia-Pacific E Cigarettes Market
Tobacco Products
Homemade Cigars Market
Tobacco Products
Premium Tobacco Products Market
Tobacco Products
Japan Heated Tobacco Products Market
Tobacco Products
Heat-Not-Burn Tobacco Products Market
Tobacco Products
Tobacco Pouch Market
Tobacco Products
GCC E-Cigarette Market
Tobacco Products
United States Pipe Tobacco Market
Tobacco Products
West Africa Cigarettes Market
Tobacco Products
Philippines E-Cigarette and Vape Market
Tobacco Products
Roll-Your-Own Tobacco Products Market
Tobacco Products
Cigarette Market
Tobacco Products
Handmade Cigars Market
Tobacco Products
Heated Tobacco Products Market
Tobacco Products
Global E-Cigarettes Market