
 Premium Cigarette Market | 2026-2036
Premium Cigarette Market Size, Share, and Industry Trends Forecast 2026-2036
Premium Cigarette Market Analytics
Heat-not-burn technology is reconfiguring manufacturing priorities across the premium cigarette supply chain. Philip Morris International leverages its IQOS platform to anchor heated tobacco leadership in regulated European markets. British American Tobacco competes through glo device deployment and specialized nicotine pouch offerings. Japan Tobacco sustains its domestic dominance while extending premium leaf sourcing networks across Southeast Asia.
Premium cigarettes denote tobacco products manufactured with select-grade flue-cured and burley leaf blends, typically featuring higher tar and nicotine thresholds than economy variants, engineered for sensory intensity and brand prestige. The full flavor and menthol product type categories occupy established margin pools in mature Western markets where brand heritage commands pricing power. The organic segment navigates regulatory pressure on synthetic additives, while gift buyers and collectors within the customer type dimension drive seasonal volume spikes in duty-free and ceremonial channels across East Asia.
The FDA exercises premarket authority over modified-risk claims and nicotine yield disclosures in the United States, while the EU Tobacco Products Directive mandates standardized packaging and ingredient transparency across member states. WHO Framework Convention protocols constrain advertising latitude and compel health warning expansions in participating jurisdictions. Stakeholders must monitor escalating flavor bans and reduced-nicotine mandates that threaten to obsolete existing product architectures faster than consumer migration timelines allow.
Market Dynamics
Heat-not-burn technology is fragmenting manufacturing priorities across the premium cigarette supply chain, forcing incumbents to dual-track combustible and heated tobacco portfolios while regulatory bodies accelerate flavor restrictions and packaging standardization mandates.
Growth Catalysts
- EU Tobacco Products Directive:Standardized packaging requirements and ingredient transparency rules are consolidating brand equity around heritage labels, concentrating consumer loyalty among established premium portfolios.
- Affluent urban cohorts in emerging economies:Rising disposable income in Chinese and Southeast Asian metropolitan centers is expanding the addressable base for sensory-intensive, prestige-positioned tobacco products.
- Heat-not-burn device proliferation:Heated tobacco platforms are capturing smokers seeking reduced-combustion alternatives without abandoning ritualistic consumption patterns entirely.
Market Restraints
- Flue-cured leaf supply concentration:Premium-grade tobacco sourcing concentrates in specific climatic belts across Brazil, Zimbabwe, and select US states, exposing manufacturers to weather-driven yield volatility and geopolitical trade friction.
- WHO Framework Convention protocols:Expanding advertising prohibitions and pictorial health warning mandates constrain brand differentiation levers and compress margin recovery from packaging investments.
- Nicotine pouch substitution:Oral nicotine delivery formats are capturing switching demand among urban professionals seeking smoke-free consumption without thermal device complexity.
Strategic Opportunities
- Duty-free channel expansion in Southeast Asia:Airport retail networks across Thailand, Vietnam, and Indonesia present underexploited volume pools for gift-format premium packaging and limited-edition releases.
- Organic certification tailwinds:Synthetic additive restrictions under evolving EU and national frameworks are creating first-mover advantages for additive-free and certified-organic leaf positioning.
- Reduced-nicotine mandate preparation:FDA exploratory rules on nicotine yield caps are incentivating R&D investment in compensatory sensory engineering and modified-risk claim substantiation.
Industry Challenges
- Dual-track manufacturing complexity:Simultaneous production of combustible cigarettes and heated tobacco consumables demands redundant quality systems and specialized thermal-processing equipment.
- Modified-risk claim substantiation timelines:Premarket authorization pathways for reduced-exposure positioning require multi-year clinical and behavioral studies with uncertain regulatory acceptance thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Premium Cigarette Market |
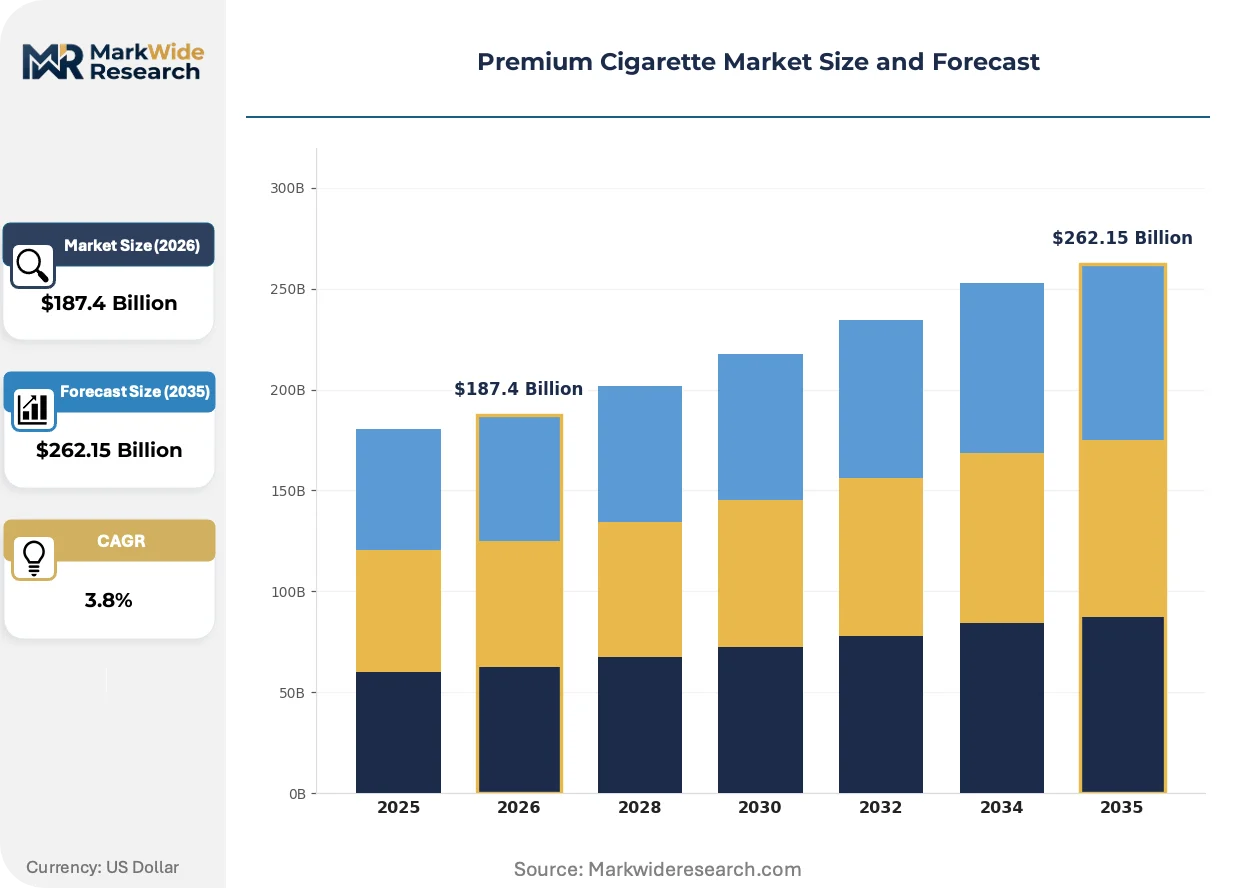
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $262.15 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Menthol, Full Flavor, Light, Organic Packaging Type: Soft Pack, Hard Pack, Carton, Custom Design Distribution Channel: Online, Supermarket, Convenience Store, Specialty Shops Customer Type: Regular Smokers, Occasional Smokers, Gift Buyers, Collectors |
| Companies Covered | Philip Morris International, Altria Group, British American Tobacco, Japan Tobacco, Imperial Brands, ITC Limited, Reynolds American, Philip Morris USA, Vector Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Premium Cigarette Market Evolving Landscape
Product architecture is bifurcating between heritage combustible formats and novel heated tobacco systems, with regulatory pressure on additives and packaging accelerating investment in sensory engineering and ritual-preserving delivery mechanisms.
Heat-not-burn technology is hybridizing combustible ritual with reduced-combustion chemistry. Smokers in Japanese and South Korean metropolitan markets are adopting heated tobacco sticks at rates that outpace initial projections. Philip Morris International's IQOS platform and competing glo devices are compressing traditional cigarette volume in these markets while creating parallel supply chains for blade-heated consumables.
REACH and RoHS frameworks in Europe are constraining synthetic additive portfolios and mandating ingredient disclosure thresholds. Manufacturers are reformulating flavor signatures around naturally derived compounds and certified-organic leaf sources. Premium menthol and full-flavor categories face the steepest compliance costs as the EU evaluates stricter flavor prohibitions.
Urban professionals in Shanghai, Seoul, and Singapore are migrating toward reduced-odor, indoor-tolerant consumption formats. Heated tobacco and oral nicotine pouches are displacing combustible cigarettes in workplace and social settings where smoke visibility carries stigma. Duty-free and ceremonial gift channels in East Asia remain combustible-dominant but are experimenting with hybrid assortment strategies.
Premium Cigarette Market Segmentation
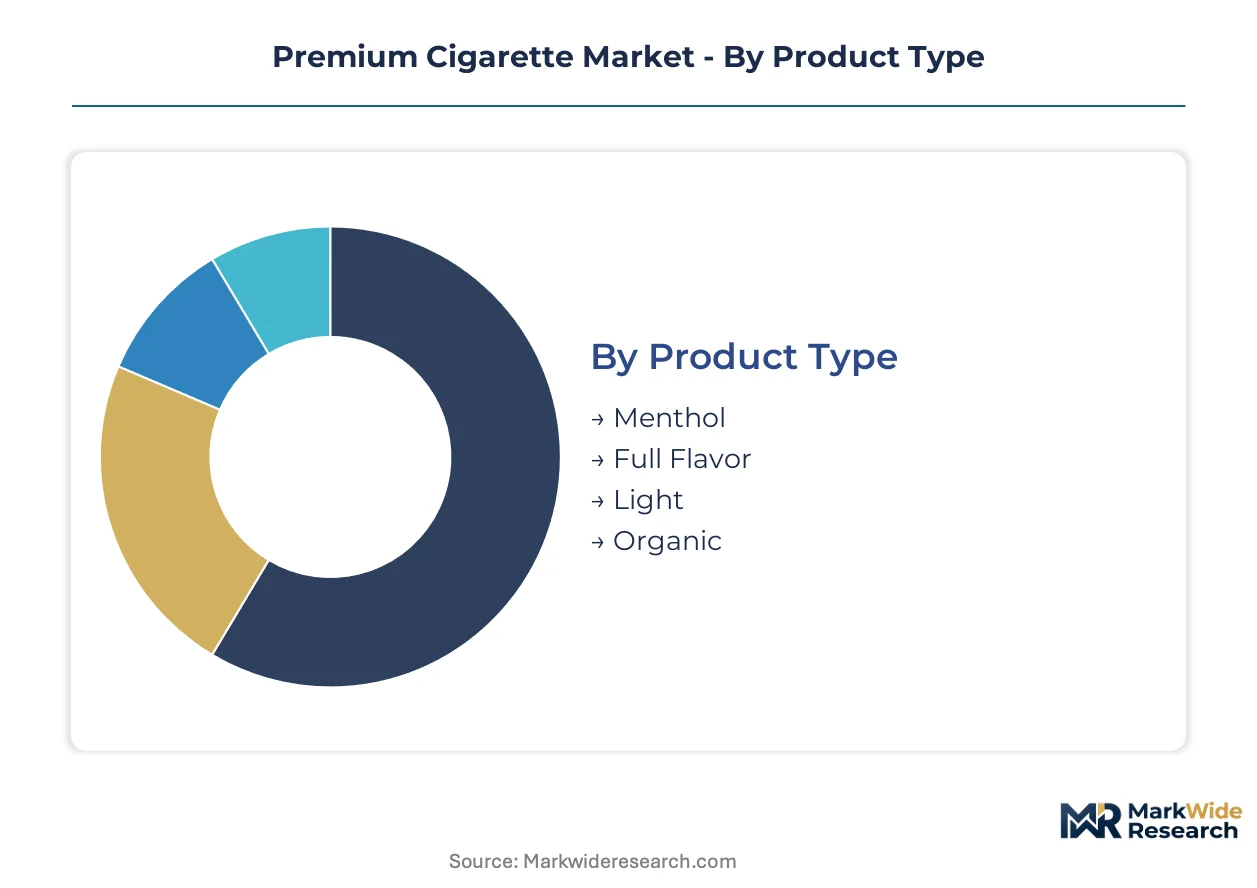
Premium cigarette segmentation reveals how manufacturers architect portfolio depth across sensory intensity, ritual occasion, and ceremonial purpose. Each dimension carries distinct margin profiles and regulatory exposure that shape resource allocation across combustible and heated tobacco platforms.
Product Type:
Use-case spectrum spans from habitual daily consumption to additive-conscious positioning, with sensory intensity and ingredient transparency defining competitive differentiation.
- Full Flavor:Engineered with higher tar and nicotine thresholds using select-grade flue-cured and burley leaf blends for maximum sensory intensity. Demand concentrates in mature Western markets where brand heritage commands pricing power, though EU flavor restrictions threaten portfolio obsolescence.
- Menthol:Delivers cooling sensory modulation through naturally derived or synthetic compounds, historically anchoring margin pools in North American and European markets. Regulatory pressure from FDA exploratory rules and EU prohibition timelines is forcing accelerated reformulation toward reduced-risk claim pathways.
- Light:Lower tar and nicotine positioning targets health-conscious urban professionals seeking reduced-intensity ritual without abandoning combustible formats entirely.
- Organic:Certified additive-free leaf sourcing navigates REACH and RoHS disclosure mandates, capturing first-mover advantage in regulatory-forward European jurisdictions.
The dominant share belongs to Full Flavor, while Organic is closing the gap fastest as synthetic additive restrictions tighten across EU member states.
Packaging Type:
Cost tier stratification separates mass-market accessibility from ceremonial premium positioning, with material investment and format durability signaling price-band intent.
- Hard Pack:Rigid cardboard construction protects product integrity during transport and extends shelf presence in retail environments. Volume concentrates in urban convenience channels across China and Southeast Asia where humidity exposure demands structural resilience.
- Soft Pack:Flexible foil-and-paper laminates reduce unit cost and enable pocket-friendly portability for high-frequency consumption occasions. Demand clusters in price-sensitive emerging markets and duty-free channels where volume efficiency outweighs premium signaling.
- Carton:Bulk-format packaging serves habitual heavy smokers and wholesale procurement, with standardized dimensions optimized for supply chain throughput.
- Custom Design:Limited-edition artwork and commemorative releases target gift buyers and collectors in East Asian ceremonial channels, with production runs calibrated to seasonal demand spikes.
Hard Pack commands the volume lead, yet Custom Design is expanding most quickly as manufacturers exploit underexploited duty-free networks across Thailand, Vietnam, and Indonesia.
Distribution Channel:
Geography of purchase determines margin recovery and regulatory compliance burden, with channel mix shifting toward controlled retail environments under advertising prohibition expansion.
- Convenience Store:High-frequency impulse purchase environment with extended operating hours capturing urban commuter traffic. Volume concentrates in Japanese and South Korean metropolitan centers where heated tobacco device compatibility drives category reset.
- Supermarket:Planned purchase setting with broader assortment visibility, though WHO Framework Convention protocols constrain promotional activity and display positioning.
- Specialty Shops:Curated environments with trained staff enabling consultative selling for premium and limited-release formats, particularly in Chinese tier-one cities.
- Online:Direct-to-consumer and marketplace platforms face escalating age-verification mandates and shipping restrictions under national tobacco control frameworks.
Convenience Store retains the dominant position, while Specialty Shops are gaining share fastest as affluent urban cohorts in Shanghai and Singapore seek differentiated purchase experiences.
Customer Type:
Maturity of consumption relationship shapes product architecture, with ritual preservation driving combustible loyalty among habitual users while occasion-based and ceremonial segments demand format innovation.
- Regular Smokers:Daily consumption cohort with established brand loyalty and price-inelastic demand patterns, anchoring volume stability in core markets.
- Gift Buyers:Ceremonial purchase occasion concentrated in East Asian duty-free and specialty retail, with packaging aesthetics and brand prestige outweighing sensory preference.
- Occasional Smokers:Social and stress-triggered consumption with higher switching propensity, increasingly migrating toward heated tobacco and oral nicotine alternatives.
- Collectors:Niche segment acquiring limited editions and vintage releases, with purchase behavior decoupled from consumption utility.
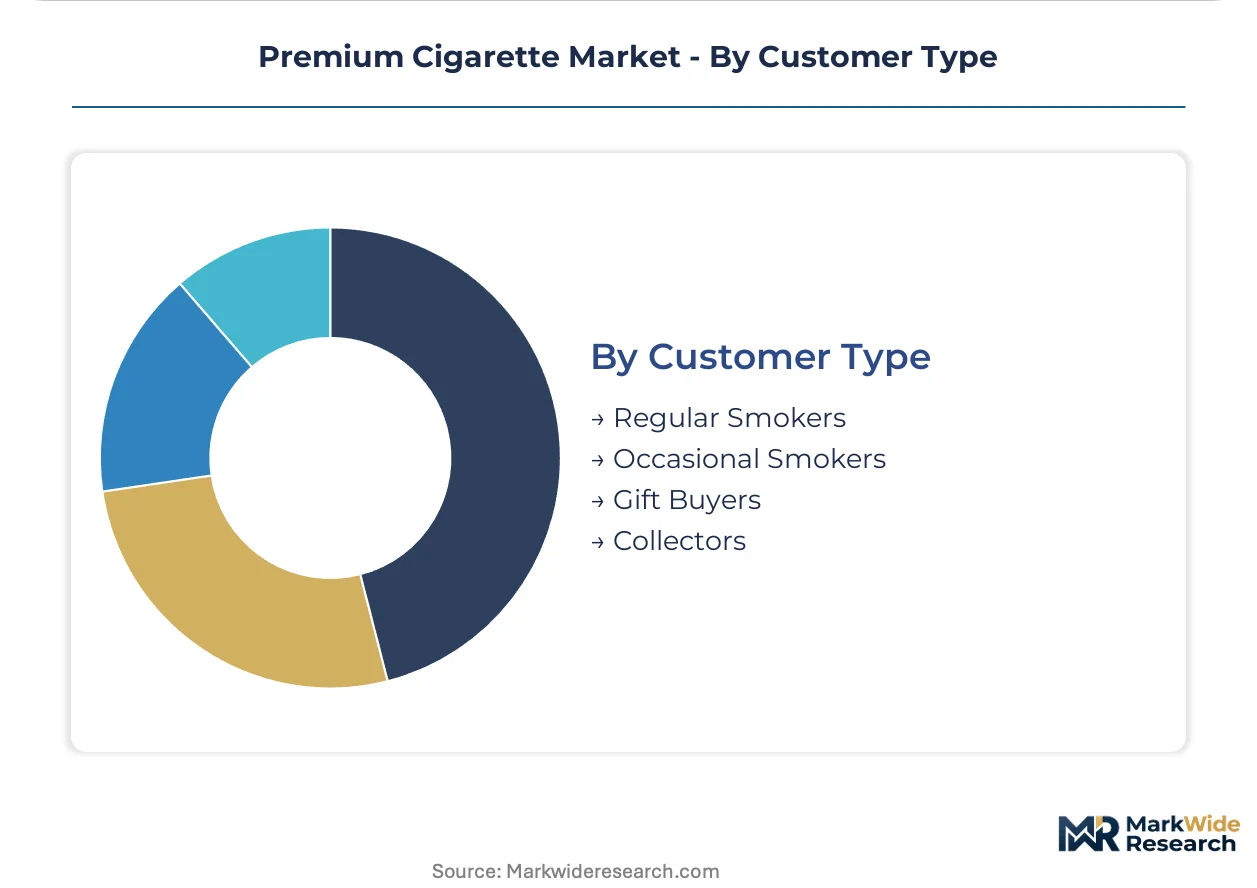
Regular Smokers hold the dominant share, while Gift Buyers are climbing the fastest as airport retail networks across Southeast Asia expand premium assortment depth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Affluent urban smokers in Shanghai, Seoul, and Singapore anchor the premium cigarette buyer archetype, with ceremonial gift purchasers and habitual brand-loyal consumers forming distinct demand clusters across metropolitan centers in China, Japan, South Korea, and Southeast Asia.
China
Tier-one city professionals drive volume for heritage combustible brands and heated tobacco alternatives alike. SAMR enforces standardized packaging mandates and ingredient disclosure rules that compress margin recovery from premium investments. Manufacturing clusters in Yunnan Province supply select-grade flue-cured leaf for domestic premium portfolios while duty-free channels in Shanghai and Beijing experiment with limited-edition ceremonial releases.
Japan
Metropolitan smokers in Tokyo and Osaka have migrated toward heated tobacco sticks at rates exceeding initial projections. METI oversees product safety standards for thermal devices while PMDA evaluates modified-risk claim submissions. Domestic leaf sourcing networks extend premium cultivation contracts across Kyushu and Shizuoka prefectures to secure supply continuity for heritage combustible lines.
South Korea
Seoul Capital Area professionals favor reduced-odor consumption formats compatible with indoor workplace norms. MFDS regulates nicotine yield disclosures and advertising restrictions across all tobacco categories. Manufacturing facilities in Busan-Ulsan produce both combustible cigarettes and heated tobacco consumables for domestic distribution and regional export.
Indonesia
Ceremonial gift buyers in Jakarta and Surabaya sustain demand for premium packaging formats during seasonal festivals. The national tobacco regulator enforces health warning expansions and promotional activity constraints. Airport retail networks across Bali and Jakarta are expanding premium assortment depth to capture transit passenger volume.
Germany
Heritage brand loyalty among mature smokers in Berlin and Munich sustains full-flavor and menthol category stability despite regulatory pressure. REACH and RoHS frameworks mandate synthetic additive restrictions and ingredient transparency thresholds. Specialized retail channels in Hamburg and Frankfurt curate premium portfolios for discerning urban consumers.
Premium Cigarette Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a consolidated structure where heritage tobacco conglomerates anchor volume leadership while heated technology platforms fragment manufacturing priorities. The competitive landscape organizes around three archetypes: integrated leaf-to-device conglomerates with dual-track combustible and heated portfolios; regional heritage brands with ceremonial positioning strength; and technology-forward specialists pursuing modified-risk claim pathways. Dominant competitive moves include strategic partnerships for thermal device distribution and portfolio diversification into oral nicotine alternatives.
Within the integrated conglomerate tier, Philip Morris International and British American Tobacco represent the archetype of dual-track manufacturers balancing heritage combustible equity with heated tobacco platform deployment. Japan Tobacco occupies a position exemplifying regional heritage strength extended through Southeast Asian sourcing networks. These three entities anchor the competitive structure without exhausting the participant base, as Altria Group and Imperial Brands sit within adjacent strategic positions focused on domestic market defense and international portfolio optimization respectively.
| Leading Market Players |
|---|
| Philip Morris International |
| Altria Group |
| British American Tobacco |
| Japan Tobacco |
| Imperial Brands |
| ITC Limited |
| Reynolds American |
| Philip Morris USA |
| Vector Group |
| Others |
Value Network & Pricing Analysis
Overcapacity in Brazilian flue-cured processing facilities is compressing leaf procurement margins while simultaneously empowering manufacturers to enforce stricter quality-tier pricing across premium cigarette portfolios. This utilization asymmetry rewards vertically integrated conglomerates with captive sourcing networks and squeezes contract-dependent processors into unfavorable indexation terms.
Pricing Analysis
Cost-plus contracts indexed to the Tobacco Merchants Association leaf price benchmarks dominate procurement arrangements across Zimbabwe, Brazil, and US state-level auctions. Price differentiation rests on flue-cured grade certification and heritage brand equity rather than manufacturing scale alone. Pricing pressure stems from EU flavor restriction compliance costs that manufacturers struggle to pass through to price-elastic economy-tier buyers. Gift buyers in East Asian ceremonial channels exhibit the lowest price sensitivity, while occasional smokers in European urban centers demonstrate acute responsiveness to per-unit increases.
Supply Chain Analysis
Export-control regimes limiting thermal-device technology flows constrain heated tobacco consumable manufacturing expansion outside established licensing jurisdictions. Premium-grade leaf supply concentrates in Brazil, Zimbabwe, and select US states including Virginia and North Carolina. Manufacturing draws from specialized blade-heating components, select-grade burley blends, and standardized packaging substrates. Single-source vulnerability pervades the flue-cured supply base where climatic disruption in any one region triggers global price volatility. Distribution runs through duty-free airport networks, controlled convenience retail, and supervised specialty channels subject to WHO Framework Convention advertising prohibitions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Premium cigarette market fragmentation is accelerating as heat-not-burn technology bifurcates demand between ritual-preserving combustible loyalists and reduced-exposure seekers, creating distinct portfolio niches that reward specialized positioning over undifferentiated scale.
For Market Incumbents: Build regulatory moats through premarket authorization investments for modified-risk claim substantiation under FDA and PMDA pathways. Secure backward integration into select-grade leaf sourcing across Kyushu and Yunnan cultivation networks to insulate against Brazilian weather volatility. Channel control through duty-free network expansion in Thailand and Vietnam counters nicotine pouch substitution threats from oral delivery specialists. For New Entrants and Emerging Players: Southeast Asian airport retail underpenetration presents the most accessible white-space target for gift-format premium packaging and limited-edition ceremonial releases. Organic certification gaps in EU member states offer second-mover positioning as REACH additive restrictions tighten. A direct-specialty retail go-to-market angle bypasses incumbent convenience channel lock-in while capturing affluent urban professionals in Singapore and Seoul. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across heated tobacco platform manufacturing as dual-track combustible and thermal-device production demands redundant quality systems. Long-term viability over the next decade favors acquisition targets with certified-organic leaf sourcing networks and pre-positioned reduced-nicotine R&D pipelines. The signal to monitor is FDA exploratory rule advancement on nicotine yield caps that would obsolete non-compliant product architectures faster than consumer migration timelines permit.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Track Manufacturing Investment | Simultaneous combustible and heated tobacco production secures portfolio optionality against regulatory bifurcation. |
| Organic Certification Program | Additive-free positioning captures REACH-compliant market share ahead of EU flavor prohibition expansion. |
| Duty-Free Network Expansion | Airport retail penetration in Thailand and Vietnam accesses underexploited gift-buyer volume pools. |
| Modified-Risk Claim Substantiation | FDA premarket authorization creates defensible positioning against reduced-nicotine mandate obsolescence. |
| Leaf Sourcing Backward Integration | Captive cultivation in Yunnan and Kyushu insulates margin from Brazilian weather-driven price spikes. |
Research Methodology
A spread of perspectives from brand portfolio directors, leaf procurement managers, regulatory affairs specialists, and duty-free channel operators converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA premarket tobacco product application filings, EU Tobacco Products Directive implementation reports, SAMR standardized packaging mandates, and customs trade data from major leaf-exporting jurisdictions. Bottom-up volume triangulation across product type, packaging format, distribution channel, and customer type segments was cross-checked against top-down macroeconomic and regulatory scenario modeling.
Demand-supply balance dynamics anchored the forecast framework across the analysis window, with segmentation dimensions spanning product architecture, packaging tier, purchase channel, and consumption occasion maturity. CAGRs were derived from trend extrapolation adjusted for regulatory intervention probabilities and technology substitution elasticities. Industry-specific forecast inputs included heated tobacco device adoption curves in Japanese and South Korean metropolitan centers and ceremonial gift purchase seasonality patterns across East Asian duty-free networks.
The forecast holds incumbent behavior within observed patterns; aggressive moves by oral nicotine pouch specialists or accelerated FDA reduced-nicotine rule implementation would shift outcomes beyond modeled ranges. Material shifts in EU flavor prohibition timelines or Brazilian climatic disruption severity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tobacco Products
United States Pipe Tobacco Market
Tobacco Products
Disposable E-Cigarettes Market
Tobacco Products
Roll-Your-Own Tobacco Products Market
Tobacco Products
GCC Cigarette Lighter Market
Tobacco Products
Europe Cigarette Market
Tobacco Products
Nicotine Pouches Market
Tobacco Products
Smokeless Cigarettes Market
Tobacco Products
Heat-Not-Burn Tobacco Products Market
Tobacco Products
Global Smokeless Tobacco Market
Tobacco Products
Electronic Cigarette Atomizer Market
Tobacco Products
Cigarette Market
Tobacco Products
Africa Tobacco Products Market
Tobacco Products
US E-Cigarette and Vape Market
Tobacco Products
Flavored Cigar Market
Tobacco Products
Global E-Cigarettes Market
Tobacco Products
Global Flavor Capsule Cigarette Market