
 Rolling Papers Market | 2026-2036
Rolling Papers Market Size, Share, and Industry Trends Forecast 2026-2036
Rolling Papers Market Outlook
Spanish flax cultivation is hardening as a critical input base for European rolling paper manufacturers. RAW leverages its unbleached hemp product line to sustain premium positioning across North American dispensary channels. OCB anchors its competitive stance through specialized rice paper formulations that dominate French and Belgian retail networks. Zig-Zag competes via extensive booklet-format distribution reach through convenience stores and smoke shops in the United States.
Rolling papers are thin sheets manufactured from wood pulp, hemp, rice, or flax fibers, typically measuring 50–110 millimeters in width and designed to combust evenly while minimizing ash residue for hand-rolled tobacco or cannabis consumption. Their primary commercial purpose centers on providing a portable, customizable consumption medium distinct from pre-manufactured cigarettes or vaporizer devices. Hemp-based materials command expanding share as consumers prioritize additive-free, sustainably sourced substrates over bleached wood pulp alternatives. Flavored product types face regulatory pressure in multiple jurisdictions, pushing margin pools toward unbleached and king size formats where certification requirements remain less restrictive.
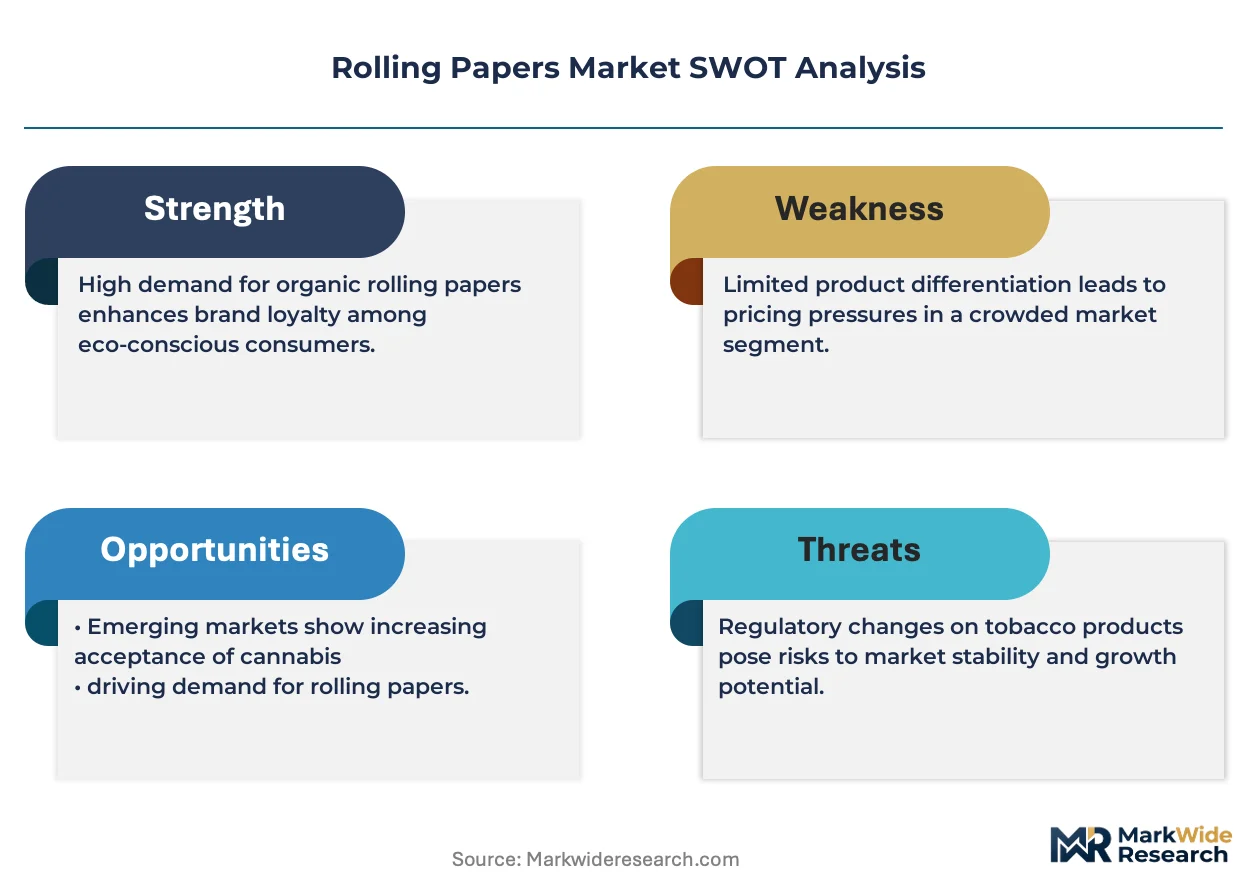
The FDA and state-level attorneys general in the United States enforce evolving ingredient transparency mandates that reshape packaging claims and retail access conditions for rolling paper brands. The EU Tobacco Products Directive and REACH frameworks impose chemical disclosure thresholds that filter non-compliant suppliers from European distribution channels. Stakeholders must monitor pending regulatory classifications that could recategorize rolling papers as tobacco accessories or standalone regulated products, fundamentally altering compliance costs and channel eligibility.
Market Dynamics
Cannabis normalization across North American and European jurisdictions is restructuring demand composition, with unbleached hemp and flax substrates displacing bleached wood pulp as the dominant material specification in premium distribution channels.
Growth Catalysts
- EU Tobacco Products Directive:Chemical disclosure mandates are filtering non-compliant suppliers from European distribution, concentrating volume among certified manufacturers.
- Recreational cannabis end-users:This segment is expanding faster than traditional tobacco consumers as jurisdiction-level legalization proliferates across Germany, Canada, and select US states.
- Spanish flax cultivation:Regional fiber production is hardening as the critical input base for European rolling paper manufacturers seeking supply security.
Market Restraints
- Flax fiber input costs:Weather-dependent agricultural yields in northern Spain and southwestern France create raw material price volatility that compresses margin pools.
- REACH chemical thresholds:Registration, Evaluation, Authorisation and Restriction of Chemicals compliance costs disproportionately burden smaller manufacturers without dedicated regulatory affairs functions.
- Pre-rolled cone substitutes:Factory-rolled formats are capturing convenience-oriented consumers who previously purchased loose papers, eroding booklet-format volume.
Strategic Opportunities
- German retail infrastructure:Federal cannabis legalization has created specialty dispensary channels where certified organic papers command premium positioning unavailable in convenience retail.
- Biodegradable gum arabic adhesives:Convergence of natural fiber substrates with plant-derived sealing agents enables compostability certifications that unlock municipal procurement contracts.
- Direct-to-consumer subscription models:Monthly paper deliveries bypass wholesale markups while capturing lifetime value through bundled grinder and accessory attachments.
Industry Challenges
- Combustion emissions testing:Laboratory certification for heavy metal and carbon monoxide release requires capital-intensive analytical equipment that smaller producers cannot access.
- Legacy packaging line retrofits:Converting foil-and-paper booklet assembly to biodegradable film and hemp card stock demands six-figure mechanical reconfiguration with extended downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rolling Papers Market |
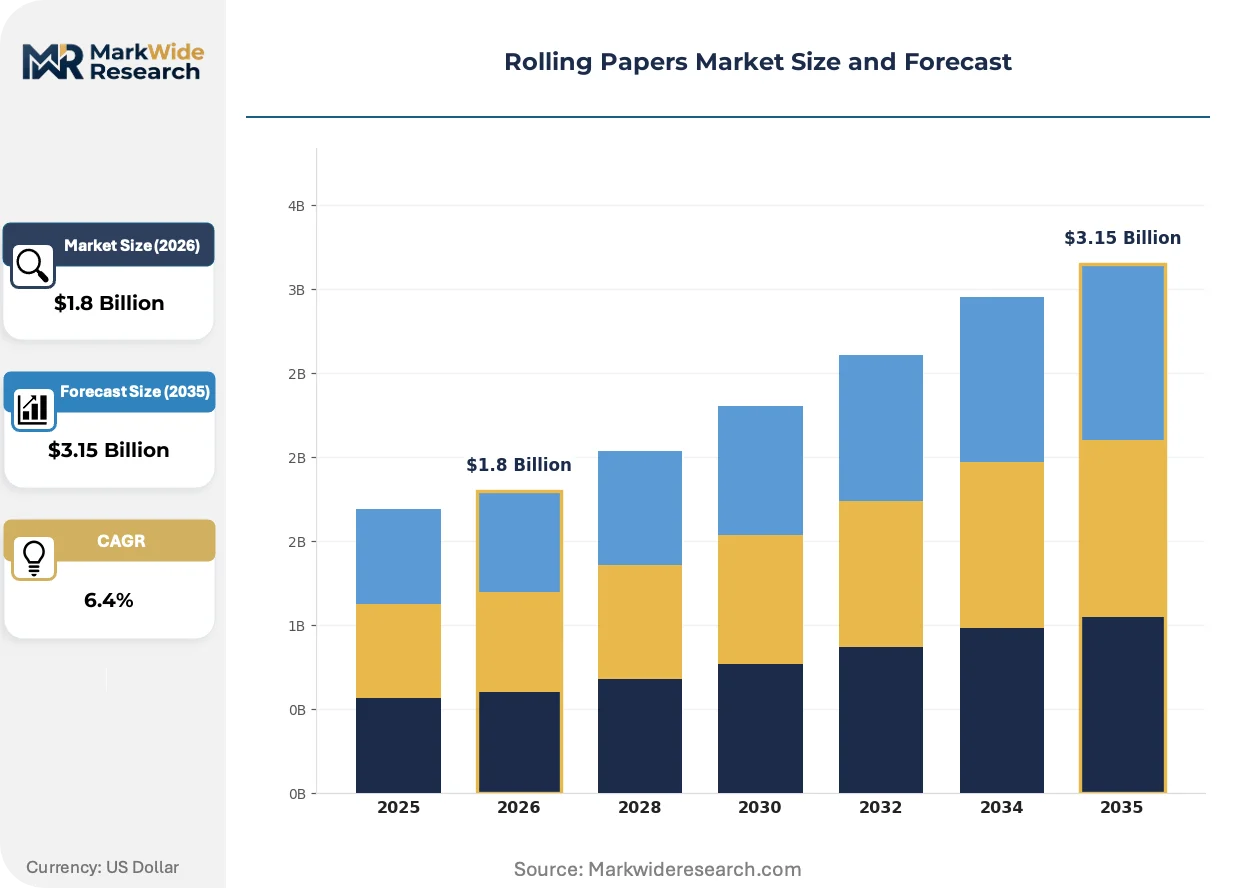
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Wood Pulp, Hemp, Rice, Flax Product Type: Unbleached, Flavored, King Size, Slim End User: Recreational Users, Medical Users, Retailers, Manufacturers Packaging Type: Booklet, Bulk, Dispensers, Single Packs |
| Companies Covered | RAW, OCB, Zig-Zag, Elements, Juicy Jay’s, Backwoods, Smoking, Rizla, Job, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rolling Papers Market Strategic Shifts
Material science advances and regulatory disclosure mandates are converging to redefine substrate specifications and packaging formats across both recreational and traditional consumption channels.
Unbleached hemp fiber is overtaking bleached wood pulp as the substrate of choice for North American dispensary channels. Recreational consumers prioritize additive-free, sustainably sourced materials that align with cannabis culture values. This material shift is compressing market share for chlorine-bleached alternatives while expanding premium price tiers.
REACH chemical disclosure thresholds are forcing reformulation of gum adhesives and flavor additives across European manufacturing operations. Industrial consequence includes supplier consolidation as only mid-cap and large manufacturers maintain dedicated regulatory compliance functions. French and Belgian retail networks are responding by delisting non-compliant flavored varieties from their core assortments.
Specialty smoke shops are losing volume to licensed cannabis dispensaries as the primary point of rolling paper access in legalized US states. Dispensary buyers demand king-size and extra-wide formats optimized for cannabis rather than tobacco fill volumes. California and Colorado represent the most visible geography for this channel displacement pattern.
Rolling Papers Market Segmentation
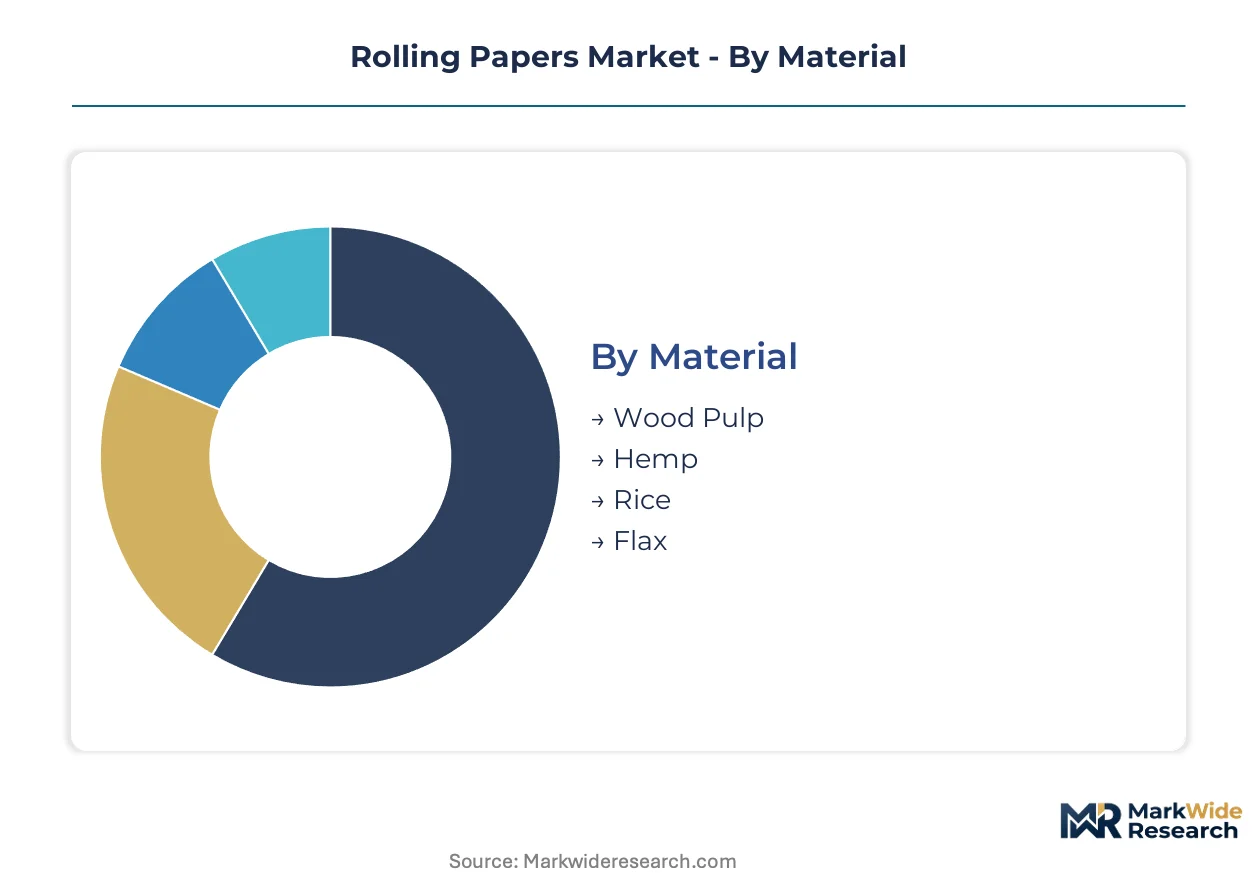
Material substrate and end-user identity are restructuring competitive boundaries in rolling papers. Recreational cannabis normalization is fragmenting demand patterns across traditional tobacco-oriented formats and dispensary-optimized specifications.
Material:
Buyers differentiate primarily by combustion purity preferences and sustainability credentials rather than price alone.
- Hemp:Unbleached hemp fibers deliver additive-free combustion with minimal ash residue. North American dispensary channels concentrate demand as cannabis consumers reject chlorine-bleached alternatives. The substrate commands premium positioning where organic certification is mandatory for shelf placement.
- Flax:Spanish and French flax cultivation supplies European manufacturers with regionally traceable fiber stocks. Specialty retailers in Barcelona and Madrid prioritize flax-based booklets for their superior burn rate consistency. Agricultural yield volatility in northern Spain creates periodic supply constraints.
- Wood Pulp:Bleached wood pulp retains cost advantage in convenience store distribution.
- Rice:Rice paper formulations dominate French and Belgian retail networks through specialized ultra-thin specifications.
Volume sits with wood pulp; growth tilts toward hemp.
Product Type:
Regulatory pressure on additives is compressing margin pools toward formats with lighter compliance burdens.
- Unbleached:Natural fiber papers bypass chlorine processing and align with additive-free positioning. King-size unbleached formats are displacing standard sizes in California and Colorado dispensaries. The format avoids flavor additive disclosure requirements that burden competing varieties.
- Flavored:Vanilla, fruit, and liquorice-infused papers face delisting under REACH chemical thresholds. French retail networks have removed non-compliant flavored varieties from core assortments. ECHA registration costs disproportionately burden smaller manufacturers.
- King Size:Extra-wide dimensions accommodate cannabis fill volumes that exceed tobacco specifications.
- Slim:Reduced-width formats retain traditional tobacco consumer preference in European convenience channels.
Unbleached captures the steepest expansion trajectory; flavored contracts under regulatory weight.
End User:
Channel access patterns are bifurcating between licensed dispensary procurement and conventional retail.
- Recreational Users:Cannabis consumers prioritize king-size hemp papers with compostable packaging. German federal legalization has created specialty dispensary channels where certified organic papers command premium positioning unavailable in convenience retail. This segment expands most quickly as jurisdiction-level normalization proliferates.
- Retailers:Smoke shops and specialty stores curate assortment depth around material origin stories and burn quality differentiation. California dispensary buyers demand extra-wide formats optimized for cannabis rather than tobacco fill volumes.
- Medical Users:Prescription cannabis patients in Germany and Canada require consistent dosing precision.
- Manufacturers:Pre-rolled cone producers purchase bulk flax and hemp substrates for in-house rolling operations.
Retailers hold current volume; recreational users drive forward momentum.
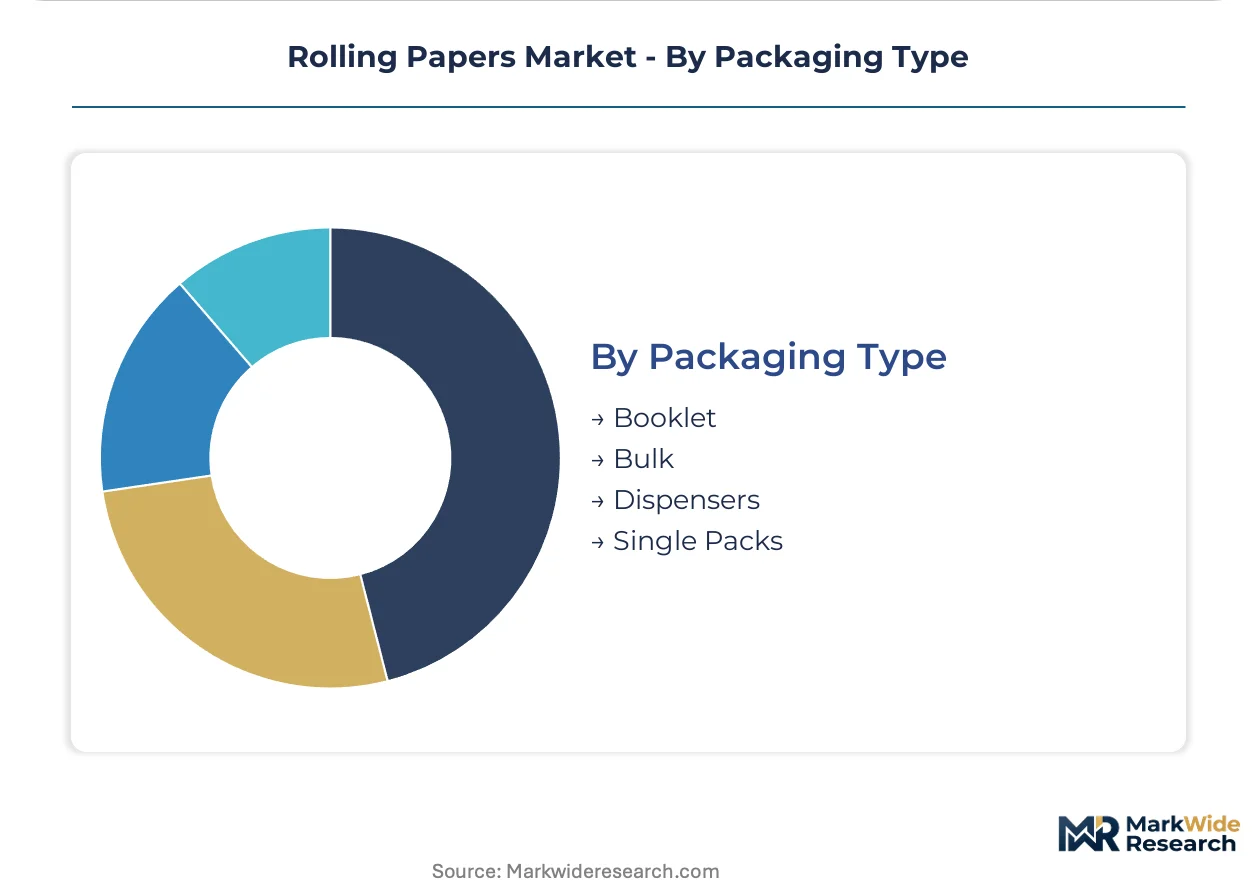
Packaging Type:
Convenience expectations are fragmenting between portability, unit economics, and retail display requirements.
- Booklet:Foil-and-paper booklet assembly dominates convenience store and smoke shop distribution. Zig-Zag competes through extensive booklet-format reach across United States retail networks. Legacy packaging line retrofits to biodegradable film demand six-figure mechanical reconfiguration.
- Single Packs:Individual paper sachets serve trial purchase and travel-use occasions in airport and hospitality retail.
- Bulk:Dispensary and pre-roll manufacturers purchase carton quantities to minimize per-unit procurement overhead.
- Dispensers:Counter-top display units support high-traffic retail environments with self-service access.
Booklet formats retain volume dominance; bulk packaging gains share in manufacturing procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spanish flax cultivation in northern Castile and León provinces anchors European substrate supply chains, while German federal cannabis policy and United States state-level normalization reshape demand geography across distinct regulatory environments.
United States
California and Colorado dispensary channels concentrate king-size hemp paper procurement as recreational cannabis consumers reject chlorine-bleached alternatives. FDA ingredient transparency mandates and state attorneys general enforcement reshape packaging claims and retail access conditions. Los Angeles and Denver host the most developed specialty retail infrastructure for unbleached product formats.
Germany
Federal cannabis legalization has created specialty dispensary channels where certified organic papers command premium positioning unavailable in convenience retail. ECHA REACH chemical disclosure thresholds filter non-compliant suppliers from national distribution networks. Berlin and Hamburg anchor the emerging procurement infrastructure for recreational end-users.
Spain
Barcelona and Madrid host Europe's most developed specialty retail infrastructure for rolling paper products, with flax-based booklets prioritized for superior burn rate consistency. EU Tobacco Products Directive chemical disclosure mandates concentrate volume among certified domestic manufacturers. Agricultural yield volatility in northern Spain creates periodic substrate supply constraints.
France
Rice paper formulations dominate French and Belgian retail networks through specialized ultra-thin specifications that retain traditional tobacco consumer preference. ECHA registration costs disproportionately burden smaller manufacturers without dedicated regulatory affairs functions. Paris and Lyon distribution centers filter non-compliant flavored varieties from core assortments.
Canada
Prescription cannabis patients require consistent dosing precision that drives demand for standardized paper specifications across medical and recreational channels. Health Canada oversight harmonizes with provincial retail frameworks that privilege additive-free substrate positioning. Toronto and Vancouver concentrate national distribution infrastructure for hemp-based formats.
Rolling Papers Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue biodegradable packaging and direct-to-consumer subscription models. The vendor base stratifies across three tiers: multinational paper conglomerates with captive fiber supply, mid-cap specialists leveraging regional substrate advantages, and niche entrants exploiting regulatory arbitrage in emerging cannabis markets. Strategic archetypes include certification-focused premium specialists, convenience-channel volume players, and pre-roll cone manufacturers integrating backward into substrate production. Dominant competitive moves encompass legacy packaging line retrofits to biodegradable materials and geographic expansion into German dispensary channels.
Within the premium unbleached tier, RAW and OCB exemplify archetype positioning through distinct substrate specializations. RAW represents North American dispensary-channel penetration anchored in hemp fiber positioning, while OCB occupies European retail network dominance through rice paper formulation heritage. Zig-Zag sits within the convenience-store volume tier, leveraging extensive booklet-format distribution reach across United States retail networks.
| Leading Market Players |
|---|
| RAW |
| OCB |
| Zig-Zag |
| Elements |
| Juicy Jay's |
| Backwoods |
| Smoking |
| Rizla |
| Job |
| Others |
Value Chain & Pricing Dynamics
Captive fiber supply arrangements among Spanish and French flax cultivators anchor both substrate security and premium pricing power for European manufacturers confronting REACH compliance burdens. This integration choice insulates certified producers from agricultural yield volatility while enabling organic certification premiums that non-integrated competitors cannot match.
Pricing Analysis
Certification bundling separates compliant from non-compliant tiers, with ECHA registration costs embedded in premium hemp and flax formats while economy wood pulp varieties compete on unbundled transactional pricing. Price differentiation hinges on organic certification grade and burn quality consistency. Cost compression in flavored segments intensifies as French retailers delist non-compliant varieties. Convenience store buyers exhibit highest price sensitivity; German dispensary procurement shows lowest sensitivity due to mandated organic specifications.
Supply Chain Analysis
Flax fiber supply rests on northern Spanish and southwestern French agricultural regions, with hemp sourcing concentrated in North American cultivation zones. Raw material dependencies span flax stalks, hemp bast fibers, and gum arabic adhesives. Single-source vulnerability in Spanish flax cultivation creates periodic supply constraints from weather-dependent yields. Distribution runs through three-channel structure: convenience retail for volume, specialty smoke shops for assortment depth, and licensed dispensaries for premium formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rolling papers market functions as a cost-of-compliance story where ECHA REACH thresholds erect barrier-to-entry moats favoring manufacturers with dedicated regulatory affairs infrastructure.
For Market Incumbents: Deploy certification investment to capture German dispensary channels before federal legalization saturates compliant supplier capacity. Secure backward integration into Spanish flax cultivation to defend margin position against agricultural yield volatility. Pre-rolled cone manufacturers represent the most credible substitution threat requiring monitoring.
For New Entrants and Emerging Players: Biodegradable packaging technology offers the most penetrable wedge for municipal procurement contracts where compostability certifications unlock institutional volume. Target direct-to-consumer subscription models in North American jurisdictions with established cannabis normalization. Lead with bundled grinder and accessory attachments to capture lifetime value beyond per-unit paper margins.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational paper conglomerates seeking captive fiber supply and dispensary channel access. Long-term viability favors mid-cap specialists with regional substrate advantages and established ECHA compliance functions. Monitor pending FDA classification decisions that could recategorize rolling papers as standalone regulated products as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Packaging Transition | Compostability certifications unlock municipal procurement contracts in EU member states. |
| Direct-to-Consumer Subscription Launch | Monthly delivery models bypass wholesale markups while capturing grinder accessory attachment revenue. |
| Organic Certification Investment | ECHA REACH compliance enables shelf placement in German federal dispensary channels. |
| Backward Integration into Flax Cultivation | Captive Spanish fiber supply insulates against agricultural yield volatility compressing margin pools. |
| King-Size Format Expansion | Extra-wide dimensions accommodate cannabis fill volumes exceeding legacy tobacco specifications. |
Study Parameters
Document review covered EU Tobacco Products Directive filings, ECHA REACH registration databases, FDA ingredient transparency guidance, and national cannabis regulatory frameworks, complemented by interviews with rolling paper procurement managers at German dispensaries, Spanish flax cultivation cooperatives, French retail category buyers, and North American smoke shop distributors. Secondary sources included customs trade data for flax and hemp fiber imports, SEC filings from paper conglomerates with disclosed rolling paper segment revenue, and provincial retail framework documents from Canadian and German jurisdictions. Bottom-up volume estimates from material substrate consumption were triangulated against top-down retail audit data.
Historical consumption patterns were cross-referenced against panel input from procurement managers to establish baseline demand across the projection horizon. Segmentation modeling incorporated material substrate, product type, end-user identity, and packaging format dimensions. CAGRs were derived from trend extrapolation adjusted for regulatory inflection points. Industry-specific forecast inputs included Spanish agricultural yield projections and pending FDA classification timelines.
Several conditions sit outside the modeled scope, including hypothetical federal cannabis rescheduling in the United States and abrupt ECHA threshold revisions. Forecasts reflect documented assumptions about jurisdictional legalization trajectories and fiber crop yield stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smoking Accessories
Japan Smoking Accessories Market
Smoking Accessories
North America Cigarette Lighter Market
Smoking Accessories
US Smoking Pipe Market
Smoking Accessories
Pocket Flask Market
Smoking Accessories
Pod Vape Market
Smoking Accessories
United States Cigarette Lighter Market
Smoking Accessories
Global Blunt Wrap Market
Smoking Accessories
Ashtray Market
Smoking Accessories
Lighter Market
Smoking Accessories
UK Smoking Pipe Market
Smoking Accessories
Smoking Accessories Market
Smoking Accessories
Wearable Tailgating Keg Market
Smoking Accessories
China Smoking Pipe Market
Smoking Accessories
Cigarette Lighter Market
Smoking Accessories
Herb Grinder Market
Smoking Accessories
Smoking Pipe Market