
 Premium Tobacco Products Market | 2026-2036
Premium Tobacco Products Market Size, Share, and Industry Trends Forecast 2026-2036
Premium Tobacco Products Market Analytics
The EU Green Deal is decoupling premium tobacco demand from conventional volume metrics by embedding sustainability reporting into supply chain contracts. Philip Morris International leverages its smoke-free transition investments to sustain premium positioning across heated tobacco lines. British American Tobacco anchors its portfolio through specialized cigar and pipe subsidiaries with distinct geographic footprints. Imperial Brands competes via controlled distribution in European specialty channels where regulatory compliance costs filter smaller competitors.
Premium tobacco products encompass high-grade cured leaf formulations, often aged or fermented, with defined tar and nicotine specifications, manufactured through hand-rolling or small-batch mechanized processes for sensory differentiation and ritual consumption. Cigars occupy the dominant margin pool due to aging premiums and limited-edition releases, while pipe tobacco retains collector-driven demand in European and Japanese markets. Online retail channels are expanding fastest among customer types as connoisseurs and collectors seek direct access to rare inventory outside taxed conventional retail.
The FDA enforces premarket authorization and ingredient listing requirements that reshape product development timelines and market access for new entrants, while REACH and the EU Tobacco Products Directive govern chemical disclosure and cross-border shipment standards within Europe. Japan's Ministry of Health, Labour and Welfare applies distinct additive regulations that filter import eligibility for non-domestic manufacturers. Stakeholders must monitor evolving heat-not-burn tax classifications and track how sustainability disclosure mandates in the EU and United States alter supplier qualification criteria for premium leaf sourcing.
Market Dynamics
Regulatory fragmentation across the United States, European Union, and Japan is forcing manufacturers to maintain parallel compliance infrastructures, diverting capital from product innovation toward legal and quality assurance functions.
Growth Catalysts
- Aged Inventory Premiumization:Collector demand for vintage cigar releases and decades-old pipe tobacco cellaring is absorbing excess liquidity from high-net-worth individuals seeking tangible alternative assets.
- REACH Chemical Disclosure:The EU's expanded substance registration requirements are advantaging established European blenders with in-house analytical capabilities over import-dependent competitors.
- Heat-Not-Burn Tax Arbitrage:Japan's Ministry of Health, Labour and Welfare maintains favorable duty treatment for heated tobacco versus combustibles, redirecting connoisseur spending toward premium device-compatible leaf formats.
Market Restraints
- Input Cost Volatility:Ecuadorian Connecticut shade wrapper leaf and Indonesian binder tobaccos face climate-driven supply interruptions, compressing margins on hand-rolled formats.
- FDA Premarket Authorization:The United States regulator's substantial equivalence pathway delays new product introductions by 18-36 months, freezing pipeline innovation for domestic manufacturers.
- Substitution by Cannabis:Legalized adult-use markets in Germany and multiple US states are capturing ritual consumption occasions previously reserved for premium cigars.
Strategic Opportunities
- Duty-Free Channel Expansion:Frankfurt, Dubai, and Singapore airport concessionaires are carving dedicated humidor spaces for ultra-premium releases, bypassing domestic excise structures.
- Sustainability Certification:The EU Green Deal's supply chain disclosure mandates are creating first-mover advantage for leaf buyers with verified carbon-accounted fermentation and curing operations.
- Direct-to-Collector Platforms:Blockchain-verified provenance systems are enabling peer-to-peer rare cigar trading outside traditional auction houses, capturing margin previously lost to intermediaries.
Industry Challenges
- Master Blender Succession:Cuban and Dominican Republic training pipelines are failing to replace retiring tobacco selectors with equivalent sensory evaluation expertise, threatening consistency in limited-edition releases.
- Legacy System Integration:European specialty retailers attempting to merge brick-and-mortar humidor management with e-commerce inventory visibility face point-of-sale architecture mismatches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Premium Tobacco Products Market |
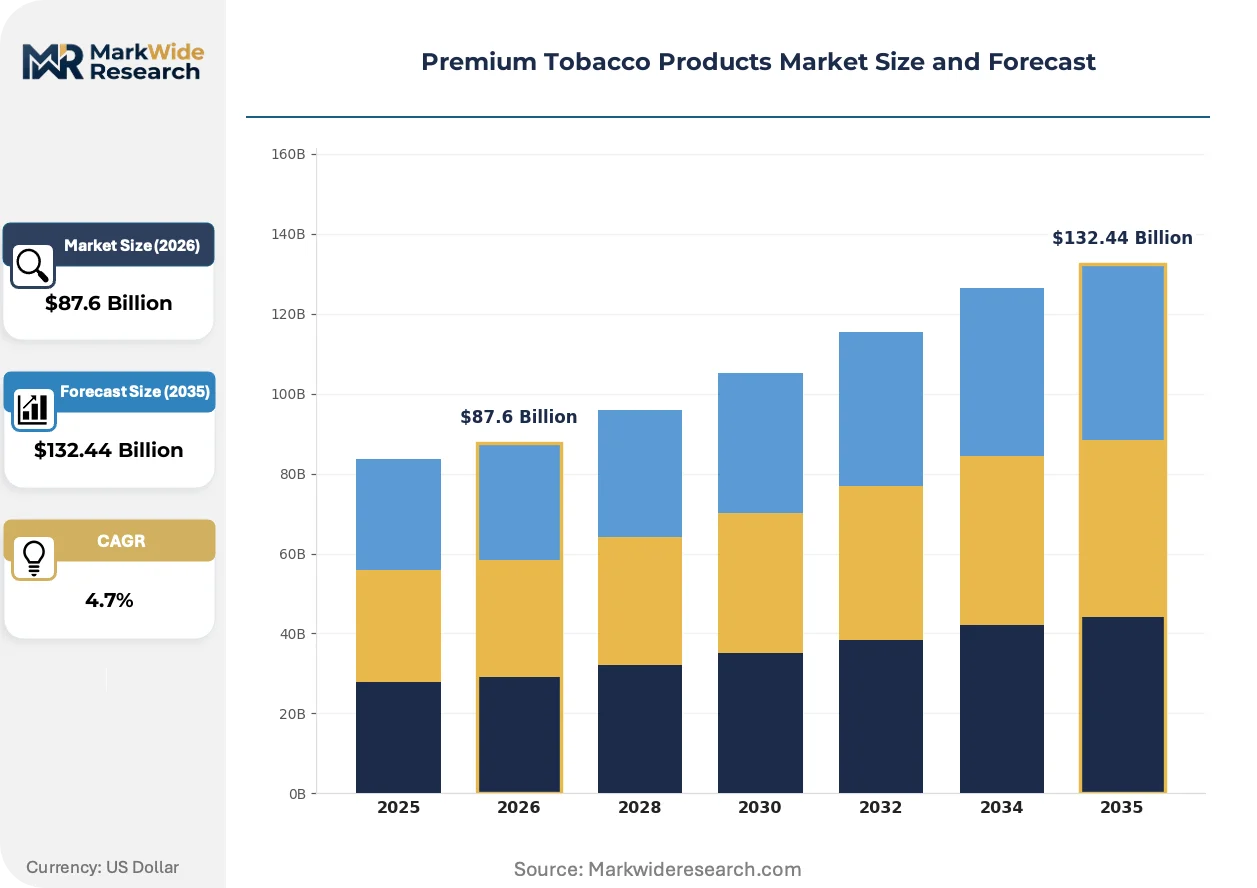
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $132.44 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cigars, Pipe Tobacco, Rolling Tobacco, Blended Tobacco Packaging Type: Tins, Boxes, Pouches, Cartons Distribution Channel: Specialty Stores, Online Retail, Supermarkets, Convenience Stores Customer Type: Casual Users, Connoisseurs, Gift Purchasers, Collectors |
| Companies Covered | Philip Morris International, British American Tobacco, Altria Group, Japan Tobacco International, Imperial Brands, SMOORE International, Arturo Fuente, Swedish Match, Ashton Cigars, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Premium Tobacco Products Market Evolving Landscape
Digital verification technologies and fermentation science advances are redefining authenticity guarantees and sensory customization in premium tobacco, while regulatory disclosure mandates reshape competitive qualification criteria.
Near-infrared spectroscopy is absorbing quality control functions previously performed by human tasters, enabling Dominican Republic and Nicaraguan manufacturers to standardize nicotine and sugar profiles across harvest years. Medium-sized cigar houses are adopting these systems fastest, using spectral fingerprinting to replicate vintage characteristics in new releases. The technology is absorbing variability premium that once justified price differentials between crop years.
The EU Tobacco Products Directive's track-and-trace serialization requirements are mandating unit-level authentication codes on all premium cigars and pipe tobacco sold in member states. Manufacturers must integrate government-certified data carriers into packaging workflows by contracted deadlines or face distribution suspension. Germany's federal customs administration is enforcing these provisions most aggressively, forcing specialty importers to reconfigure warehouse management systems.
Collector purchasing is fragmenting across single-stick acquisition platforms and fractional ownership schemes that democratize access to pre-embargo Cuban inventory. Traditional full-box retailers in Tokyo's Ginza district and London's Mayfair are losing transaction volume to mobile-native consignment marketplaces. This behavioral shift is most pronounced among collectors aged 35-50 in the United States and Japan, where authentication anxiety previously favored established dealer relationships.
Premium Tobacco Products Market Segmentation
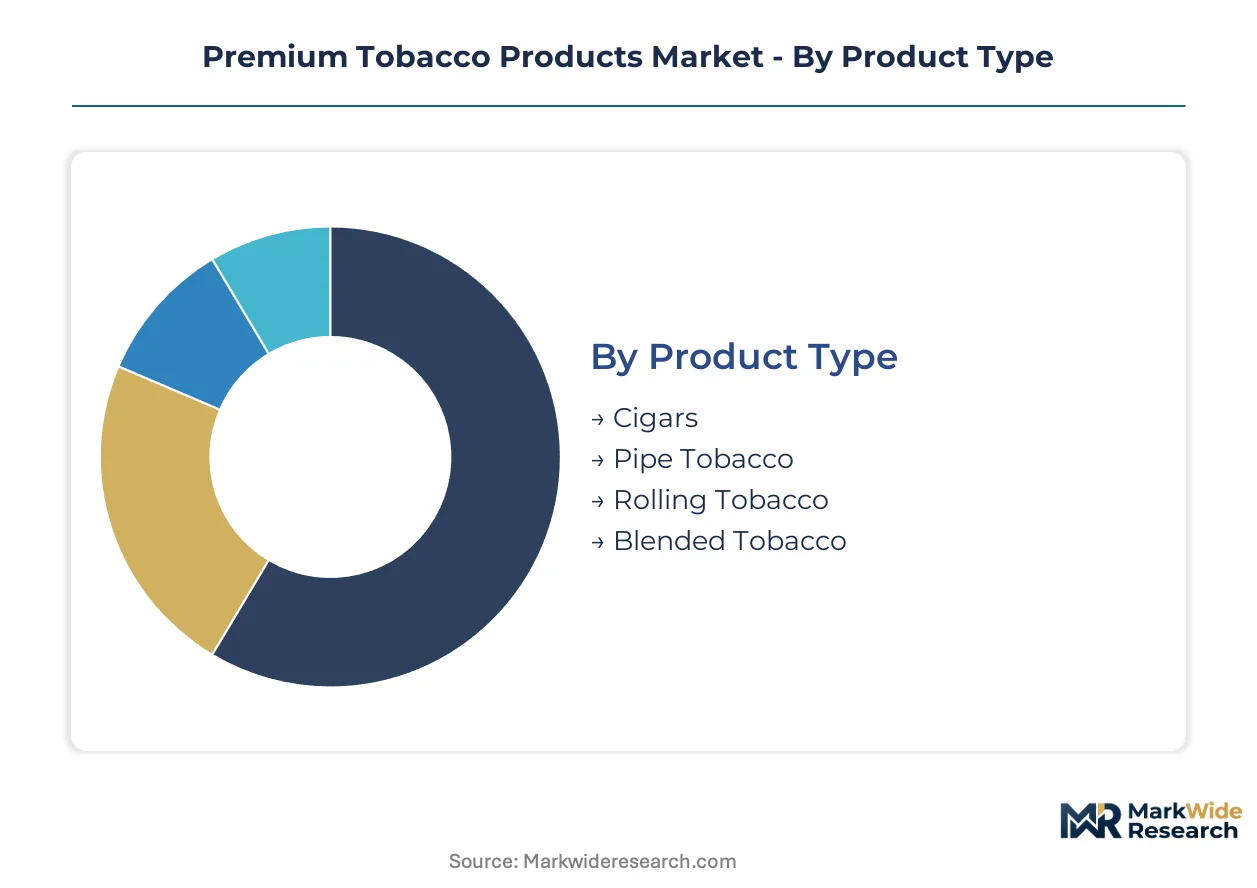
Premium tobacco segmentation reflects divergent ritual consumption patterns and purchasing contexts. Each category captures distinct margin structures and regulatory exposure profiles that reshape competitive positioning.
Product Type:
Consumption rituals and aging economics separate buyers across this category.
- Cigars:Hand-rolled formats from Nicaraguan and Dominican Republic manufacturers command aging premiums through controlled fermentation. Collector demand in the United States and Germany absorbs limited-edition releases as alternative asset allocations.
- Pipe Tobacco:Small-batch aged blends with defined moisture specifications attract European and Japanese cellaring enthusiasts. REACH chemical disclosure requirements favor established blenders with in-house analytical laboratories over import-dependent competitors.
- Rolling Tobacco:Premium cured leaf for hand-rolling maintains niche demand in German and Spanish specialty channels.
- Blended Tobacco:Curated mixing tobaccos serve connoisseur custom blending in Japanese and UK pipe communities.
Cigars lead volumes today; pipe tobacco is gaining share fastest among collector demographics.
Packaging Type:
Preservation requirements and display conventions drive format selection across retail environments.
- Tins:Airtight metal containers with vacuum seals maintain optimal humidity for pipe tobacco cellaring. Connoisseurs in Japan and Germany prioritize tin-dated releases for provenance verification.
- Boxes:Cedar-lined humidor boxes dominate ultra-premium cigar presentation. Frankfurt and Dubai airport concessionaires allocate dedicated display space for boxed limited editions.
- Pouches:Reclosable foil pouches serve convenience-oriented rolling tobacco purchasers in Spanish and Italian urban markets.
- Cartons:Multi-unit cartons support gift purchasing occasions in US and Japanese duty-free channels.
Boxes dominate revenue contribution; tins show steepest expansion trajectory among aging-focused collectors.
Distribution Channel:
Tax exposure and authentication confidence shape where transactions concentrate.
- Specialty Stores:Licensed humidor retailers in Tokyo's Ginza and London's Mayfair provide provenance verification and climate-controlled storage. Germany's federal customs administration enforces EU Tobacco Products Directive serialization most aggressively through this channel.
- Online Retail:Direct-to-collector platforms bypass domestic excise structures and enable rare inventory access. Blockchain-verified provenance systems capture margin previously lost to auction house intermediaries.
- Supermarkets:Limited premium SKU availability serves casual purchasers in US and Japanese suburban markets.
- Convenience Stores:Basic rolling tobacco and machine-made formats dominate this channel in Spanish and Italian transit locations.
Specialty stores retain the highest transaction values; online retail is expanding most quickly among authenticated rare releases.
Customer Type:
Knowledge depth and purchase motivation separate behavioral clusters.
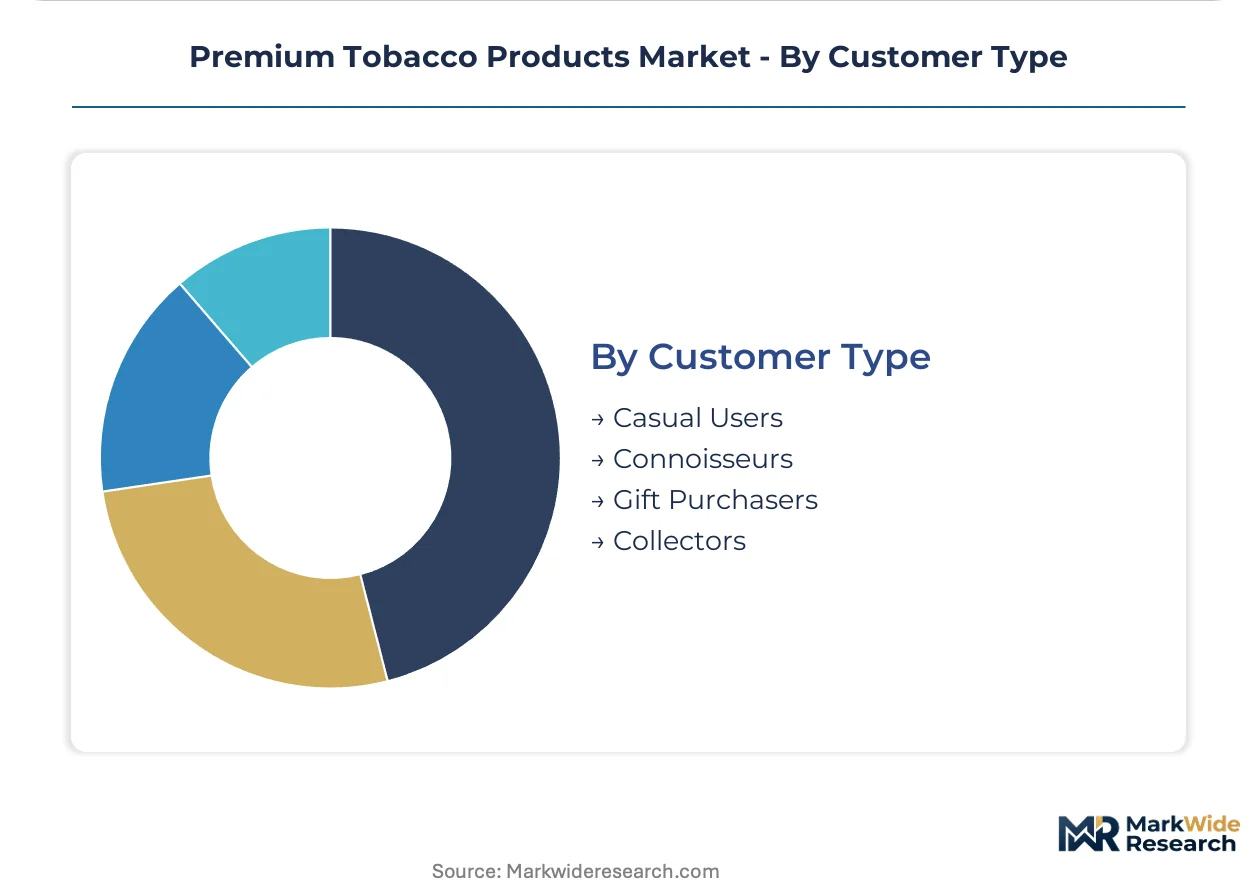
- Connoisseurs:Sensory-trained purchasers evaluate leaf origin, fermentation method, and aging potential before acquisition. FDA premarket authorization delays reshape their new product discovery timelines in US markets.
- Collectors:Inventory-focused buyers treat aged cigars and cellared pipe tobacco as tangible alternative assets. Fractional ownership schemes now democratize access to pre-embargo Cuban inventory previously locked in full-box transactions.
- Casual Users:Occasion-driven purchasers prioritize convenience and recognized brand markers over provenance depth.
- Gift Purchasers:Presentation-focused buyers respond to packaging aesthetics and brand heritage signaling in Japanese and German seasonal markets.
Connoisseurs anchor volume stability; collectors demonstrate the fastest value growth per transaction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium tobacco craftsmanship traces its commercial origins to nineteenth-century Caribbean fermentation houses and European pipe-blending ateliers. Contemporary demand concentrates where connoisseur cultures intersect with favorable tax treatment and mature specialty retail infrastructure.
United States
Collector demand for aged Nicaraguan and Dominican cigars absorbs significant high-net-worth liquidity through Miami and New York specialty humidor networks. FDA premarket authorization requirements delay new product introductions by 18-36 months, freezing pipeline innovation for domestic manufacturers. Tampa's Ybor City historic district anchors boutique cigar manufacturing with direct-to-consumer fermentation facility tours.
Germany
Pipe tobacco cellaring enthusiasts in Hamburg and Berlin sustain demand for decades-aged European blends with defined moisture specifications. REACH chemical disclosure requirements favor established blenders with in-house analytical laboratories over import-dependent competitors. Frankfurt airport concessionaires allocate dedicated humidor spaces for ultra-premium releases, bypassing domestic excise structures.
Japan
Tokyo's Ginza district specialty retailers provide provenance verification for connoisseur purchasers evaluating leaf origin and aging potential. The Ministry of Health, Labour and Welfare applies distinct additive regulations that filter import eligibility for non-domestic manufacturers. Osaka's Kansai region harbors collector communities treating aged cigars as tangible alternative assets.
Dominican Republic
Santiago de los Caballeros manufacturers deploy near-infrared spectroscopy to standardize nicotine and sugar profiles across harvest years, replicating vintage characteristics. Export-oriented fermentation houses face climate-driven supply interruptions on Ecuadorian Connecticut shade wrapper inputs. The Cibao Valley tobacco-growing region concentrates hand-rolling expertise for limited-edition releases.
United Kingdom
London's Mayfair traditional full-box retailers compete with mobile-native consignment marketplaces for collector transactions aged 35-50. EU Tobacco Products Directive serialization requirements mandate unit-level authentication codes through specialty import channels. British pipe-blending heritage sustains curated mixing tobacco demand among custom-blending communities.
Premium Tobacco Products Market Competitive Landscape
Premium-margin players sit above commodity-margin players across aging-inventory depth and provenance-verification capabilities. The vendor base stratifies between integrated leaf-to-retail houses, specialized cigar subsidiaries, and device-centric heat-not-burn platforms. Three archetypes dominate: heritage fermentation houses with master blender succession pipelines, technology-enabled authentication platforms, and diversified multinationals leveraging smoke-free transition investments. Competitive moves concentrate on duty-free channel expansion and blockchain-verified direct-to-collector platform development.
Within the heritage fermentation tier, Arturo Fuente exemplifies family-structured craftsmanship continuity, while Ashton Cigars occupies a position bridging Dominican manufacturing heritage with US market access. Philip Morris International anchors the diversified multinational archetype through heated tobacco line investments. These three entities represent distinct strategic postures: artisanal succession-dependent authenticity, transatlantic distribution-integrated positioning, and smoke-free transition capital redeployment.
| Leading Market Players |
|---|
| Philip Morris International |
| British American Tobacco |
| Altria Group |
| Japan Tobacco International |
| Imperial Brands |
| SMOORE International |
| Arturo Fuente |
| Swedish Match |
| Ashton Cigars |
| Others |
Value Network & Pricing Analysis
Family-owned fermentation houses in the Dominican Republic and Nicaragua anchor supply-side discipline through generational inventory management and selective release timing, translating crop-year scarcity into sustained premium capture across limited-edition cigar lines. Their refusal to scale mechanized output preserves artisanal pricing power against commodity-margin competitors.
Pricing Analysis
Three-tier pricing structure across ultra-premium, connoisseur-grade, and accessible premium levels segments buyers by aging depth and provenance documentation. Price differentiation rests on master blender lineage and vintage certification, with Ecuadorian Connecticut shade wrapper availability driving cost compression in hand-rolled formats. Casual users exhibit highest price sensitivity, while collectors absorb substantial premiums for pre-embargo Cuban inventory and decades-old pipe tobacco cellars.
Supply Chain Analysis
Master blender succession gaps in Santiago de los Caballeros and Estelí constrain output scaling despite near-infrared spectroscopy standardization. Supply concentrates in the Dominican Republic, Nicaragua, and Honduras for hand-rolled cigars, with Indonesian binder tobaccos and Ecuadorian wrapper leaf as critical dependencies. Climate-driven crop volatility on Connecticut shade varieties creates single-source vulnerability. Distribution runs through Frankfurt, Dubai, and Singapore duty-free concessionaires alongside authenticated direct-to-collector platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Premium tobacco functions as a stable compounder where collector demand for tangible alternative assets generates recurring revenue through aged inventory releases and cellaring subscriptions.
For Market Incumbents: Deploy blockchain-verified provenance systems to defend against fractional ownership platforms eroding traditional dealer relationships. Deepen backward integration into Ecuadorian wrapper tobacco cultivation to secure climate-exposed inputs. FDA premarket authorization delays threaten pipeline innovation; accelerate pre-submission engagement for heat-not-burn line extensions. For New Entrants and Emerging Players: EU Green Deal supply chain disclosure mandates in Europe open a window for sustainability-certified leaf brokers to capture first-mover advantage. Target German pipe tobacco cellaring enthusiasts through direct-to-consumer tin-dated releases. Build go-to-market around REACH-compliant analytical capabilities that filter import-dependent competitors. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-sized Dominican fermentation houses with unresolved succession planning. Long-term viability hinges on heat-not-burn tax arbitrage persistence and collector demographic expansion. Watch Japan's Ministry of Health, Labour and Welfare additive regulation enforcement as inflection signal for import eligibility tightening.| Strategic Initiative | Industry Significance |
|---|---|
| Master Blender Succession Programs | Cuban and Dominican training pipelines preserve sensory evaluation expertise for limited-edition consistency. |
| Blockchain Provenance Integration | Peer-to-peer authentication captures margin from auction house intermediaries in rare cigar trading. |
| Duty-Free Channel Expansion | Frankfurt and Dubai airport humidor spaces bypass domestic excise structures for ultra-premium releases. |
| Sustainability Certification Investment | EU Green Deal compliance creates supplier qualification barriers favoring carbon-accounted fermentation operations. |
| Direct-to-Collector Platform Launch | Mobile-native consignment marketplaces fragment collector purchasing away from Mayfair and Ginza traditional retailers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with master blenders, specialty humidor retailers, duty-free concessionaires, and regulatory affairs specialists at major manufacturers with secondary validation. Sources included FDA premarket tobacco product application filings, EU Tobacco Products Directive implementation guidance from Germany's federal customs administration, Japan's Ministry of Health, Labour and Welfare additive regulation notices, and trade flow data from Dominican and Nicaraguan export authorities. Bottom-up demand modeling and top-down supply capacity estimates were triangulated to cross-check volume assumptions.
Segment-weighting applied product type, packaging format, distribution channel, and customer archetype dimensions across the projection horizon. CAGRs were derived from trend extrapolation adjusted for regulatory milestone impacts. Forecast inputs incorporated aging inventory premiumization curves, heat-not-burn tax classification shifts, and collector liquidity allocation patterns toward tangible alternative assets.
Revisions become necessary when FDA deeming rule enforcement intensifies, EU serialization deadlines accelerate, or climate events disrupt Ecuadorian wrapper tobacco harvests. Forecasts reflect documented assumptions about regulatory stability and collector demand persistence. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tobacco Products
Heat-Not-Burn Tobacco Products Market
Tobacco Products
West Africa Cigarettes Market
Tobacco Products
United States E-Cigarette Market
Tobacco Products
North America E-Cigarette Market
Tobacco Products
Global Cigarette Vending Machine Market
Tobacco Products
Asia-Pacific E Cigarettes Market
Tobacco Products
Middle East and Africa E-Cigarettes Market
Tobacco Products
US E-Cigarette and Vape Market
Tobacco Products
Premium Cigarette Market
Tobacco Products
E-Cigarettes and Vaporizer Market
Tobacco Products
Cigarette Market
Tobacco Products
Disposable E-Cigarettes Market
Tobacco Products
Homemade Cigars Market
Tobacco Products
Electronic Cigarette Atomizer Market
Tobacco Products
United States Pipe Tobacco Market
Tobacco Products
Japan Heated Tobacco Products Market