
 Smokeless Cigarettes Market | 2026-2036
Smokeless Cigarettes Market Size, Share, and Industry Trends Forecast 2026-2036
Smokeless Cigarettes Market Intelligence
The miniaturization of heating elements and the development of proprietary nicotine salt formulations is rewriting product design and user experience. Philip Morris International Inc. leads in the heat-not-burn category with its significant R&D investments. British American Tobacco plc competes across multiple product formats, including vaping and nicotine pouches. Altria Group, Inc. leverages its extensive distribution network in the United States to maintain market presence.
Smokeless cigarettes encompass a category of products that deliver nicotine without combustion, typically by heating a liquid or specially processed tobacco. Heat-not-burn devices, for example, operate at temperatures below 350°C to create an aerosol instead of smoke. Within product types, heat-not-burn (HNB) and nicotine pouches represent the fastest-growing segments, offering higher margins. The core addressable market remains current smokers seeking alternatives, while uptake among non-smokers faces significant regulatory scrutiny.
Market access and product claims are governed by stringent regulatory frameworks. The U.S. Food and Drug Administration (FDA) requires premarket authorization for new products, a process that heavily influences commercial viability. In Europe, the Tobacco Products Directive (TPD) and REACH regulations impose limits on nicotine concentration and ingredient reporting. Stakeholders must navigate this complex and diverging regulatory landscape to secure market approval and build consumer trust.
Market Dynamics
The market's central dynamic is the tension between the public health mandate for harm reduction and the stringent regulatory frameworks designed to prevent youth uptake. This conflict shapes product development, market access, and commercial claims, forcing companies to navigate a complex path between innovation and compliance.
Growth Catalysts
- Regulatory Pressure:Stricter regulations on combustible cigarettes, such as potential nicotine caps by the FDA, are compelling smokers to seek out non-combustion alternatives.
- Technology Miniaturization:Advances in battery technology and heating element design enable smaller, more discreet, and user-friendly devices, broadening their appeal among adult users.
- Developed Market Demand:Consumer demand in high-income countries like Japan and the United States is focused on harm-reduction products, creating concentrated growth pockets.
Market Restraints
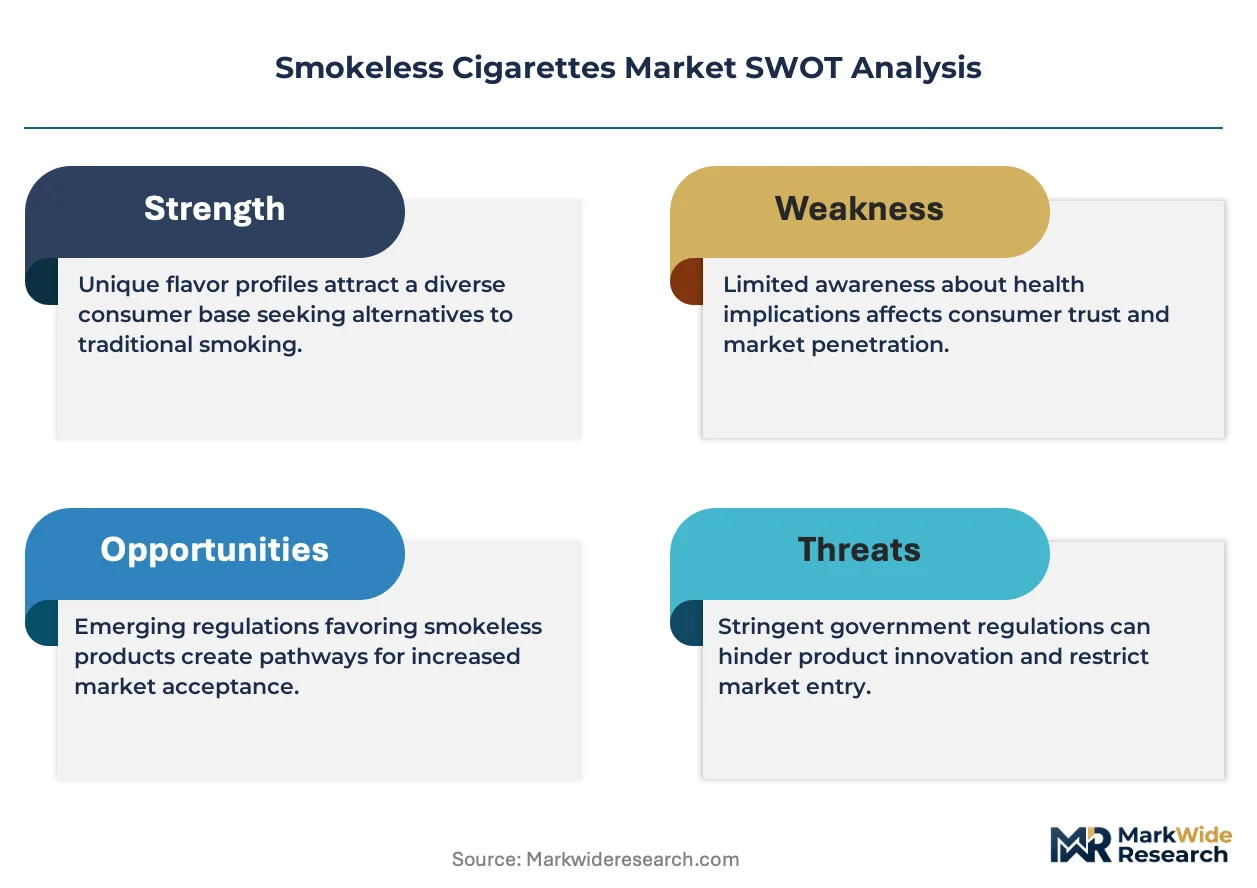
- Regulatory Barriers:The U.S. FDA’s resource-intensive Premarket Tobacco Product Application (PMTA) process acts as a significant barrier to entry for smaller innovators.
- Flavor Restrictions:Widespread flavor bans in various US states and some European countries limit product differentiation and reduce appeal for some adult smokers.
- Public Health Opposition:Coordinated campaigns from public health organizations framing smokeless products as a threat to youth create negative consumer sentiment and political pressure.
Strategic Opportunities
- Emerging Market Entry:There is a significant opportunity to introduce smokeless alternatives in large smoking markets across Eastern Europe and Southeast Asia with low current penetration.
- Device Connectivity:Integrating Bluetooth and app connectivity allows for usage tracking, personalized control, and building a direct-to-consumer digital relationship.
- MRTP Designation:Achieving a Modified Risk Tobacco Product (MRTP) order from the FDA provides a powerful, scientifically validated marketing claim that separates products from competitors.
Industry Challenges
- Component Sourcing:Managing a complex global supply chain for both specialized electronic components and proprietary tobacco or nicotine consumables introduces volatility and risk.
- Divergent Regulations:Navigating conflicting international standards, such as the EU's Tobacco Products Directive and U.S. FDA requirements, increases compliance costs.
- Intellectual Property Defense:Protecting patented heating technologies and nicotine formulations from counterfeiters and fast-followers requires constant legal vigilance and expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smokeless Cigarettes Market |
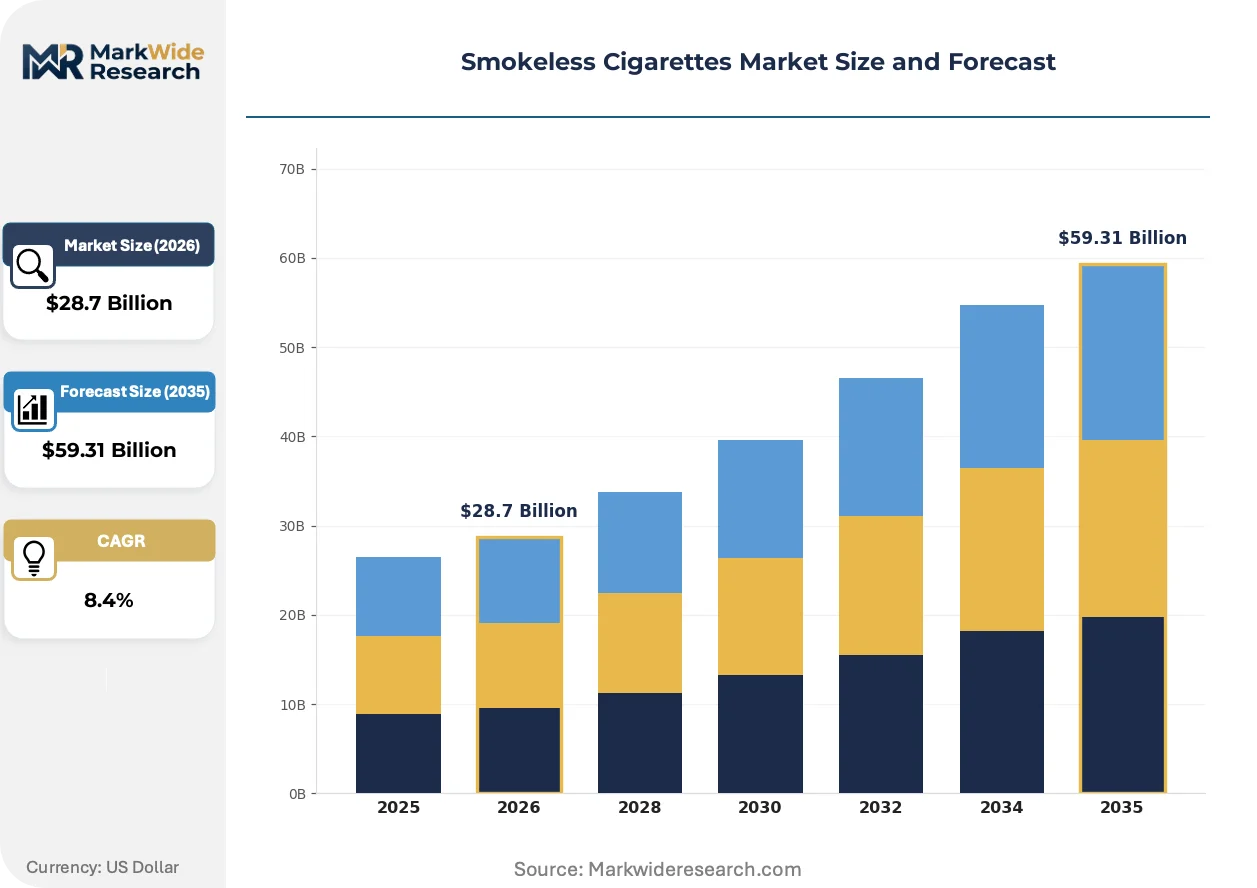
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $59.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: E-Cigarettes, Vaping Devices, HNB (Heat Not Burn), Nicotine Pouches Customer Type: Current Smokers, Former Smokers, Non-Smokers, Young Adults Distribution Channel: Online Retail, Convenience Stores, Supermarkets, Specialty Shops Flavor Profile: Tobacco, Menthol, Fruit, Dessert |
| Companies Covered | Altria Group, Inc., British American Tobacco plc, Philip Morris International Inc., Japan Tobacco Inc., Swedish Match AB, Imperial Brands plc, 22nd Century Group, Inc., Turning Point Brands, Inc., JUUL Labs, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smokeless Cigarettes Market Strategic Shifts & Innovations
Product innovation is shifting from hardware advancements to the chemistry of nicotine delivery and the digital user experience. This evolution aims to more closely replicate the satisfaction of traditional cigarettes while building ecosystems that encourage brand loyalty beyond the initial device purchase.
Proprietary nicotine salt formulations are a key material innovation, engineered to deliver nicotine more efficiently with less throat irritation. Adult smokers transitioning from combustible products are the primary adopters, seeking a more satisfying user experience. This chemical innovation is hybridizing the product category, blending the rapid nicotine uptake of traditional cigarettes with the non-combustion format of next-generation devices.
The U.S. Food and Drug Administration's Premarket Tobacco Product Application (PMTA) pathway is a defining regulatory framework for the industry. It mandates that manufacturers provide extensive scientific evidence to demonstrate a product is appropriate for public health protection. Heat-not-burn and novel nicotine products are most affected, as the process favors companies with deep scientific and financial resources.
A notable behavioral shift is the consumer move towards subscription models for the regular purchase of consumable sticks, pods, and pouches. This model disrupts traditional convenience store channels and fosters a direct-to-consumer brand relationship. This trend is most visible in digitally advanced markets like South Korea and parts of Western Europe.
Smokeless Cigarettes Market Segmentation
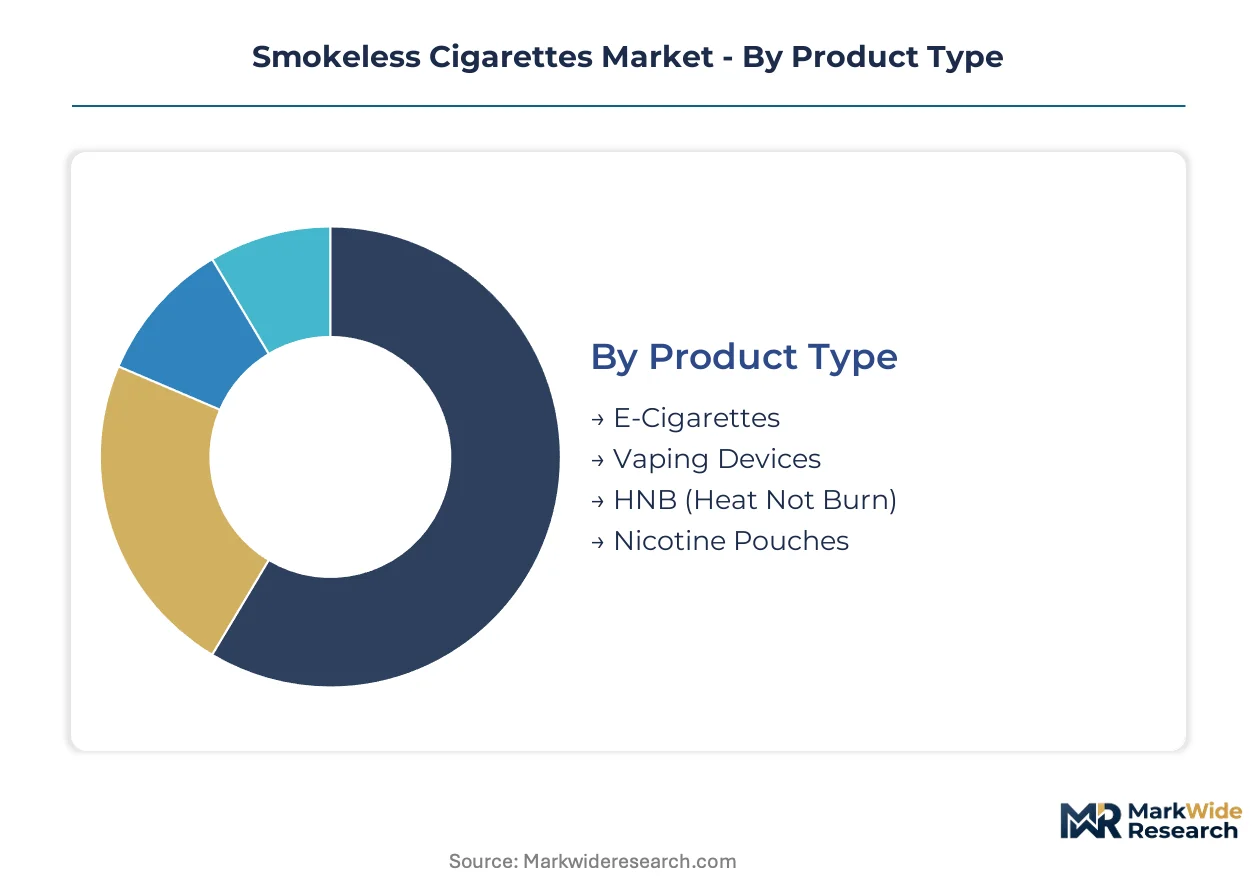
Segmentation analysis reveals the diverse product landscape and consumer base driving the smokeless cigarettes market, highlighting specific innovation pathways and targeted distribution strategies. Understanding these distinct segments is crucial for manufacturers to align product development with evolving consumer needs and navigate complex regulatory environments.
Product Type:
The use-case spectrum for smokeless nicotine delivery devices spans multiple formats, each designed for distinct user preferences and consumption patterns.
- HNB (Heat Not Burn):These devices operate below 350°C, creating an aerosol from specially processed tobacco without combustion. Demand concentrates in developed markets like Japan and Italy, driven by adult smokers seeking traditional tobacco flavor with reduced harm perception.
- Nicotine Pouches:Nicotine pouches are pre-portioned, tobacco-free oral products containing nicotine salts, plant fibers, and flavorings. Uptake is significant in Scandinavian countries and the United States, appealing to users desiring discreet, smoke-free nicotine consumption.
- E-Cigarettes:These electronic devices vaporize a liquid containing nicotine, flavorings, and other chemicals, offering a wide range of customizable experiences.
- Vaping Devices:Vaping devices encompass a broad category of electronic systems that heat e-liquids to produce an inhalable aerosol, often featuring advanced battery and coil technologies.
Established volume favors E-Cigarettes; emerging adoption favors Nicotine Pouches.
Customer Type:
Understanding user demographics defines product development and marketing strategies across the smokeless cigarette market.
- Current Smokers:This segment comprises individuals actively using combustible tobacco products who seek harm-reduction alternatives. Products are designed to mimic traditional cigarette satisfaction, often featuring higher nicotine delivery and familiar flavor profiles.
- Young Adults:This demographic segment includes individuals aged 18-25, often targeted by public health concerns regarding product initiation. Regulatory scrutiny in the United States and Europe heavily influences product availability and marketing to this group.
- Former Smokers:Individuals who have quit combustible tobacco products but continue to use nicotine, often seeking less harmful delivery methods to manage cravings.
- Non-Smokers:This group includes individuals who have never smoked or used nicotine, representing a segment where regulatory bodies aim to prevent initiation into nicotine use.
Market penetration for smokeless products is deepest among Current Smokers, while regulatory frameworks aim to mitigate uptake among Non-Smokers.
Distribution Channel:
The market's commercial reach is shaped by diverse retail pathways, each offering distinct advantages in consumer access and product visibility.
- Convenience Stores:These ubiquitous retail points offer immediate access to smokeless products, serving as a primary channel for impulse purchases and rapid replenishment. Their widespread presence supports broad market penetration, particularly for established brands.
- Online Retail:E-commerce platforms provide extensive product variety and direct-to-consumer relationships, bypassing some traditional retail restrictions. This channel is critical for subscription models and niche product launches, especially in digitally advanced markets like South Korea.
- Supermarkets:Large grocery retailers offer smokeless products alongside other consumer goods, providing a broad reach to adult consumers during regular shopping trips.
- Specialty Shops:Dedicated vape shops and tobacco stores offer expert advice, a wider selection of products, and opportunities for product trials, catering to more experienced users.
Traditional retail outlets like Convenience Stores remain foundational for volume, while Online Retail is gaining share fastest through direct engagement.
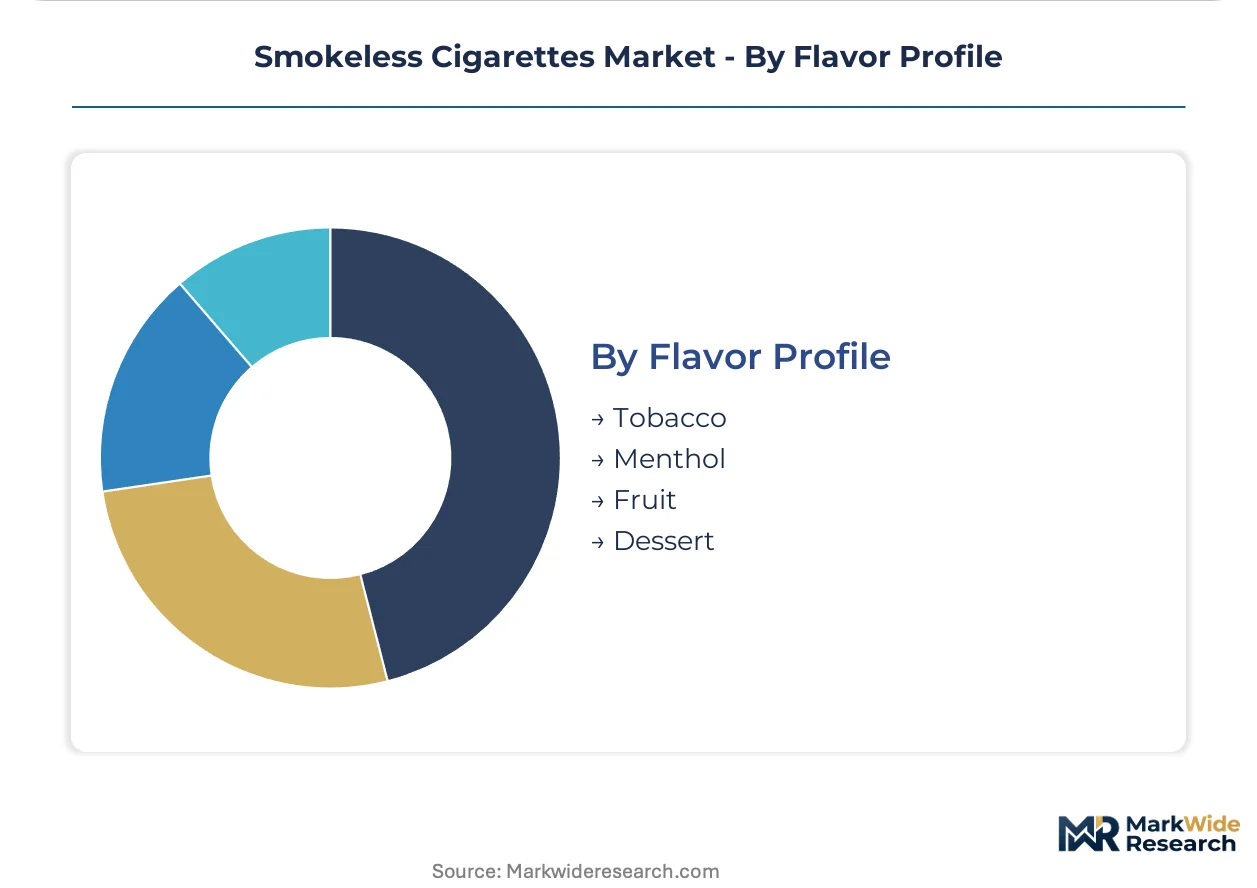
Flavor Profile:
Consumer preference for sensory experience drives innovation in the flavor profiles offered across smokeless cigarette formats.
- Tobacco:This flavor profile aims to replicate the traditional taste of combustible cigarettes, providing familiarity for transitioning adult smokers. Regulatory bodies in the United States often permit tobacco flavors while restricting others.
- Menthol:Menthol flavors offer a cooling sensation and are popular among a significant subset of adult smokers of combustible products. However, these flavors face increasing regulatory bans in various jurisdictions, including parts of the EU and some US states.
- Fruit:Fruit-flavored smokeless products offer a sweet and aromatic experience, appealing to consumers seeking alternatives to traditional tobacco tastes.
- Dessert:Dessert flavor profiles mimic popular sweet treats, providing a diverse range of indulgent options for adult nicotine users.
Core demand for smokeless products centers on Tobacco flavors, while the future of Menthol flavors faces significant regulatory headwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Current smokers seeking harm reduction products drive significant demand across developed markets, concentrating growth in regions with established regulatory frameworks and consumer awareness. These markets exhibit high adoption rates for heat-not-burn devices and nicotine pouches. Regulatory bodies actively shape market access and product innovation in these key geographies.
United States
Consumer demand for harm-reduction alternatives is particularly strong among adult smokers in the United States. The U.S. Food and Drug Administration (FDA) requires extensive premarket authorization for new smokeless products, influencing market entry. Major metropolitan areas like New York and Los Angeles show high retail penetration for diverse smokeless product formats.
Japan
Japan exhibits a high concentration of heat-not-burn product adoption, driven by early market entry and strong consumer acceptance. The Ministry of Health, Labour and Welfare oversees tobacco product regulations, including marketing restrictions. Tokyo and Osaka serve as major hubs for product launches and consumer trials of new device technologies.
Sweden
Nicotine pouch uptake is significant in Sweden, reflecting a long-standing cultural acceptance of oral tobacco alternatives. The Public Health Agency of Sweden monitors nicotine product consumption and health impacts. Stockholm and Gothenburg lead in the distribution and consumer base for tobacco-free nicotine pouches.
Germany
Demand for smokeless products in Germany is expanding as consumers seek alternatives to combustible cigarettes. The Tobacco Products Directive (TPD) in Europe, implemented by national authorities, governs product composition and labeling. Major cities like Berlin and Munich are seeing increased availability and marketing efforts for next-generation nicotine delivery systems.
South Korea
South Korea shows a strong propensity for technology adoption, including advanced smokeless cigarette devices and subscription models. The Ministry of Food and Drug Safety (MFDS) regulates nicotine products and their market introduction. Seoul and Busan are key markets for innovative device connectivity and direct-to-consumer sales channels.
Smokeless Cigarettes Market Key Industry Players
Channel-controlling players compete with product-specialist players, creating a dynamic market structure for smokeless cigarettes. The market exhibits characteristics of both consolidation among established tobacco giants and fragmentation among niche innovators. Strategic archetypes include diversified tobacco conglomerates, specialized vaping companies, and oral nicotine product manufacturers. Portfolio diversification and technology licensing represent dominant competitive moves.
Diversified tobacco conglomerates, such as Philip Morris International Inc. and British American Tobacco plc, anchor the market with extensive R&D and distribution networks. These companies occupy a position at the forefront of heat-not-burn technology and multi-format nicotine product offerings. Altria Group, Inc. exemplifies a strong regional player, leveraging its established presence in the United States to maintain market share. These firms primarily focus on transitioning adult smokers to reduced-harm products through continuous innovation and regulatory engagement.
| Leading Market Players |
|---|
| Altria Group, Inc. |
| British American Tobacco plc |
| Philip Morris International Inc. |
| Japan Tobacco Inc. |
| Swedish Match AB |
| Imperial Brands plc |
| 22nd Century Group, Inc. |
| Turning Point Brands, Inc. |
| JUUL Labs, Inc. |
| Others |
Cost & Logistics Intelligence
Shenzhen's advanced electronics manufacturing capacity underpins the smokeless cigarettes market, influencing specialized component availability and ultimately impacting device pricing for global consumers. This concentration of production capability creates both efficiencies and potential chokepoints within the supply chain.
Pricing Analysis
Cost-plus contract patterns, often indexed to commodity tobacco prices or specialized chemical inputs, define pricing for smokeless cigarette consumables. Price differentiation stems from brand premium and the achievement of Modified Risk Tobacco Product (MRTP) designations from the FDA. Pricing pressure stems from intense regulatory scrutiny on flavors and youth uptake, leading to price erosion in certain product categories. Current smokers transitioning from combustible products exhibit lower price sensitivity for satisfying alternatives, while non-smokers remain highly price-sensitive.
Supply Chain Analysis
Proprietary nicotine salt formulations and advanced heating element components form the upstream feedstock for smokeless cigarettes. Geographic supply concentration for electronic components centers in China, while specialized nicotine and flavor chemicals often source from Switzerland and the United States. The supply chain relies on specialized electronic components and high-purity nicotine, creating potential single-source vulnerabilities for proprietary ingredients. Downstream distribution runs through a hybrid model, combining traditional convenience store channels with a rapidly expanding direct-to-consumer online retail presence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smokeless cigarettes market presents an early-cycle expansion story, driven by growing consumer demand for harm-reduction alternatives among adult smokers globally.
For Market Incumbents: Harden core market positions by investing heavily in Premarket Tobacco Product Application (PMTA) submissions and securing MRTP designations from the FDA. This regulatory commitment mitigates the threat from emerging niche entrants lacking deep scientific resources. Enhance channel control through subscription models and direct-to-consumer platforms, building brand loyalty beyond the initial device purchase.
For New Entrants and Emerging Players: Establish a beachhead in emerging markets like Eastern Europe and Southeast Asia, targeting adult smokers seeking alternatives to combustible products with low current penetration. Focus on novel nicotine delivery systems or unique flavor profiles that differentiate from established players. A digital-first go-to-market strategy, leveraging online retail and social media, offers a cost-effective entry point.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified tobacco conglomerates seeking to divest non-core assets or non-compliant product lines. These assets often possess established R&D capabilities and regulatory expertise. Long-term viability over a five-to-ten-year window hinges on navigating evolving regulatory landscapes and demonstrating clear harm-reduction potential. Watch for significant FDA MRTP approvals as a key inflection indicator for market validation.
| Strategic Initiative | Industry Significance |
|---|---|
| Secure MRTP Designation | Provides a powerful, scientifically validated marketing claim, differentiating products from competitors. |
| Expand Direct-to-Consumer Channels | Fosters brand loyalty and captures higher margins by bypassing traditional retail intermediaries. |
| Invest in Next-Gen Nicotine Formulations | Delivers more efficient nicotine with less irritation, enhancing user satisfaction for transitioning smokers. |
| Target Emerging Asian Markets | Unlocks significant growth potential in large smoking populations with low current smokeless penetration. |
| Develop Device Connectivity Features | Allows for usage tracking and personalized control, building a digital ecosystem around the product. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted, including R&D directors, regulatory affairs specialists, and marketing executives from leading manufacturers. Primary interviews with industry stakeholders were validated against extensive secondary research. Secondary data sources included FDA filings, European Tobacco Products Directive (TPD) reports, and national health agency publications. Bottom-up and top-down triangulation ensured data consistency.
Calibration against historical sales data and product launch trends informed the analytical framework across the analysis window. The model segmented the market by product type, customer type, distribution channel, and flavor profile, with an additional dimension for regional regulatory frameworks. Compound annual growth rates were derived from a weighted average of segment-specific growth trajectories. Forecast inputs included evolving regulatory timelines and consumer transition rates from combustible products.
Stress conditions across regulatory changes and consumer adoption rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions concerning technological advancements and public health policy shifts. Cross-checking against national health survey data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tobacco Products
Electronic Cigarette Atomizer Market
Tobacco Products
Handmade Cigars Market
Tobacco Products
Africa Tobacco Products Market
Tobacco Products
Europe Cigarette Vending Machine Market
Tobacco Products
Menthol Cigarette Market
Tobacco Products
Global Smokeless Tobacco Market
Tobacco Products
Tobacco Pouch Market
Tobacco Products
Premium Tobacco Products Market
Tobacco Products
Cigarette Market
Tobacco Products
United States E-Cigarette Market
Tobacco Products
E-Cigarettes and Vaporizer Market
Tobacco Products
Global Flavor Capsule Cigarette Market
Tobacco Products
Cigar Tubes Market
Tobacco Products
Europe E-Cigarettes Market
Tobacco Products
Nicotine Pouches Market
Tobacco Products
Middle East and Africa E-Cigarettes Market