
 E-Cigarettes and Vaporizer Market | 2026-2036
E-Cigarettes and Vaporizer Market Size, Share, and Industry Trends Forecast 2026-2036
E-Cigarettes and Vaporizer Market Foresight
The e-cigarettes and vaporizer category is recalibrating around a widening gap between premium closed-system pods and low-cost disposable units. Philip Morris International dominates heated-tobacco positioning through its IQOS platform, while JUUL Labs navigates regulatory headwinds with its concentrated pod format. British American Tobacco leverages its Vuse brand to sustain shelf presence across multiple distribution channels.
E-cigarettes and vaporizers are battery-powered inhalation devices that heat a liquid solution—typically containing propylene glycol, vegetable glycerin, flavoring agents, and variable nicotine concentrations—into an aerosol for user inhalation. The hardware incorporates precision temperature control circuits, wicking systems, and lithium-ion power cells engineered for consistent vapor output across draw-activated or button-fired activation modes. Pod systems command the highest margin pools due to recurring cartridge purchases, while refillable box mods retain enthusiast loyalty through customization depth. Disposable units lead volume growth in convenience retail, though flavor restrictions in certain jurisdictions compress their addressable footprint.
The FDA governs market access through premarket tobacco product applications and marketing denial orders, while the EU Tobacco Products Directive caps nicotine concentration at 20 mg/mL and mandates health warning coverage. Japan's Ministry of Health, Labour and Welfare classifies nicotine-containing products as pharmaceutical items, creating a divergent regulatory architecture that favors heated-not-burn alternatives. Stakeholders must monitor evolving flavor bans, taxation schemes, and youth-access enforcement mechanisms to anticipate demand shifts and portfolio rebalancing requirements.
Market Dynamics
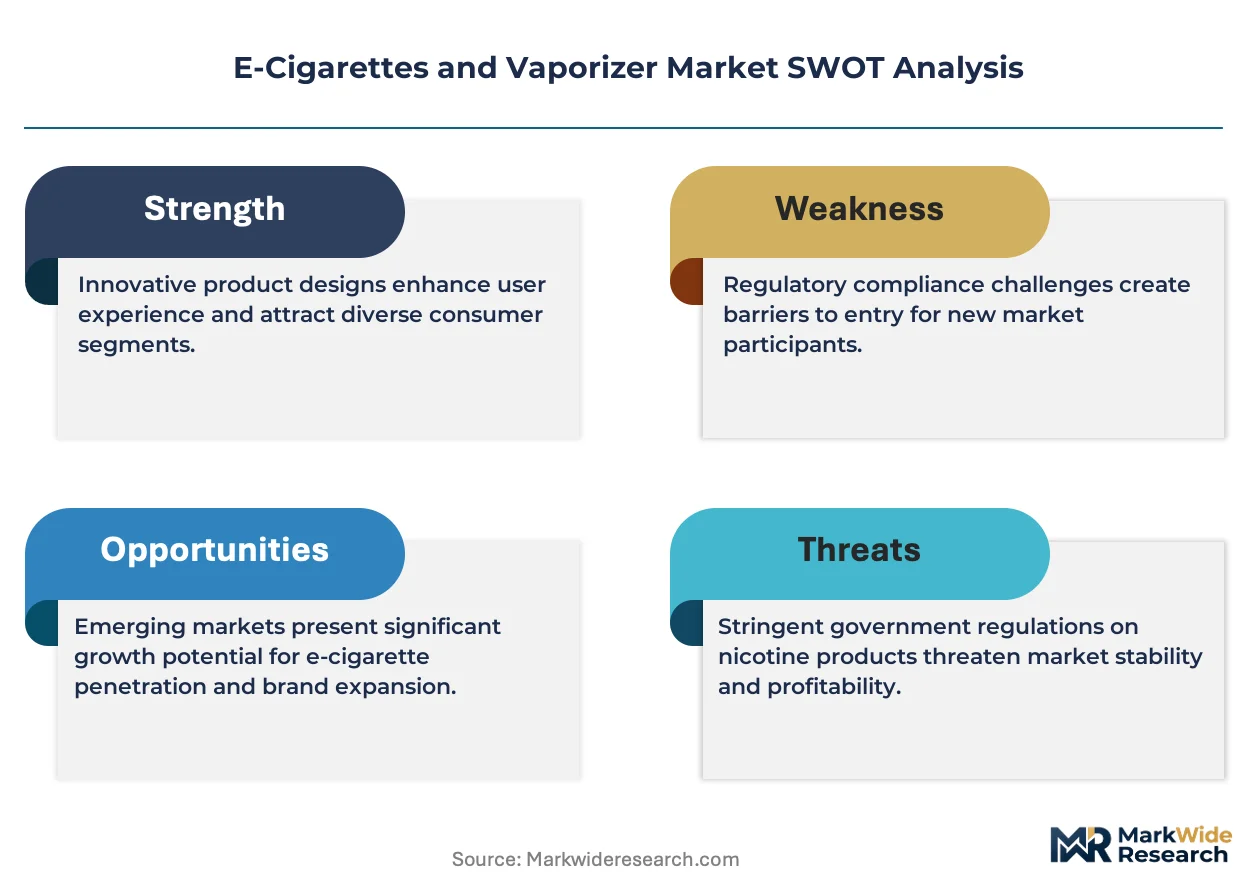
The e-cigarettes and vaporizer market is bifurcating around nicotine delivery efficiency versus flavor complexity, with ceramic coil technology and synthetic nicotine chemistry rewriting product development roadmaps while the FDA's marketing denial orders compress authorized SKU counts.
Growth Catalysts
- Pod system adoption:Young adult consumers in the United States gravitate toward closed-system formats that simplify maintenance and ensure consistent nicotine delivery. Recurring cartridge purchases generate predictable revenue streams for manufacturers.
- REACH compliance harmonization:The EU's chemical registration framework creates transparent ingredient disclosure standards that reduce cross-border market entry friction. Manufacturers leverage this clarity to standardize formulations across member states.
- Heated-tobacco positioning:Japan's pharmaceutical classification of nicotine-containing liquids channels demand toward heat-not-burn alternatives. This regulatory architecture rewards devices that aerosolize tobacco rather than liquid solutions.
Market Restraints
- Lithium-ion supply concentration:Battery cell production concentrates in East Asian manufacturing clusters, exposing hardware assemblers to input volatility and extended lead times for power management components.
- Nicotine purity standards:Synthetic nicotine sourcing faces agricultural nicotine price competition while requiring pharmaceutical-grade purification infrastructure that smaller formulators cannot economically deploy.
- Flavor additive restrictions:State-level prohibitions on characterizing flavors in California and Massachusetts eliminate entire product categories from legal distribution, forcing portfolio rationalization.
Strategic Opportunities
- Pharmaceutical channel expansion:Smoking cessation clinics in Germany and the United Kingdom present authorized distribution pathways for medically positioned nicotine replacement devices. Reimbursement frameworks in these markets subsidize hardware acquisition.
- Biometric integration:Convergence of puff-tracking sensors with smartphone health applications enables usage monitoring that appeals to controlled-consumption segments. This data layer differentiates premium hardware from commodity disposables.
- Closed-loop recycling mandates:Extended producer responsibility legislation in France and the Netherlands requires manufacturers to finance end-of-life device collection. Early compliance investments secure retail shelf access as enforcement tightens.
Industry Challenges
- Aerosol toxicology expertise:Formulation chemists with inhalation safety credentials remain scarce relative to product development pipelines, elongating preclinical testing timelines and delaying regulatory submissions.
- Premarket authorization capital intensity:The FDA's requirement for longitudinal behavioral studies and longitudinal health outcome data demands multi-million-dollar investment commitments with uncertain approval probabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Cigarettes and Vaporizer Market |
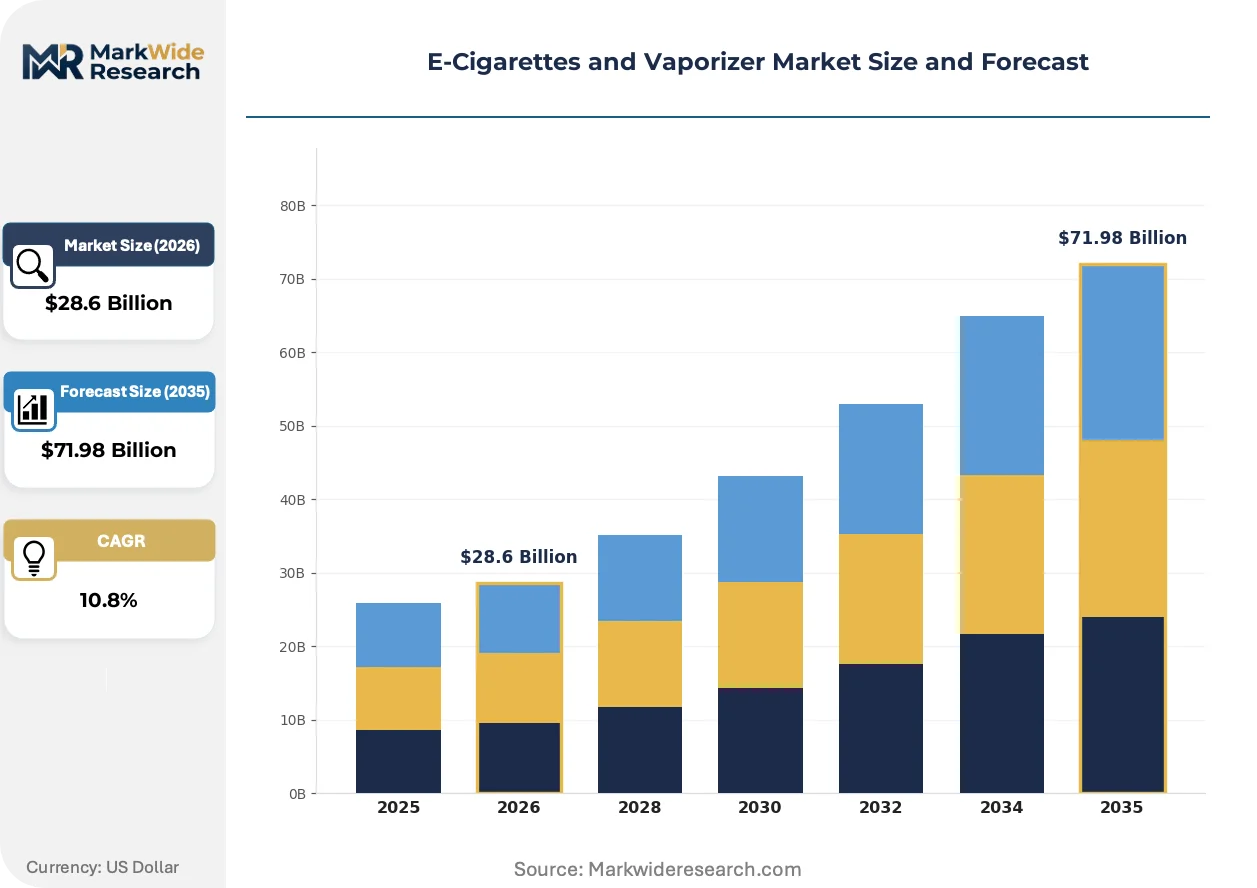
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $71.98 Billion |
| CAGR (2026 – 2036) | 10.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Refillable, Pod System, Box Mod Nicotine Content: Nicotine Free, Low Nicotine, Medium Nicotine, High Nicotine Flavor Profile: Tobacco, Menthol, Fruit, Dessert Distribution Channel: Online Retail, Convenience Stores, Vape Shops, Supermarkets |
| Companies Covered | Philip Morris International Inc., British American Tobacco, Altria Group, Inc., Imperial Brands, JUUL Labs, Inc., Japan Tobacco International, R.J. Reynolds Vapor Company, Shenzhen IVPS Technology Co., Ltd., NJOY, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Cigarettes and Vaporizer Market Shifts & Advancements
Product architecture is fragmenting along consumption occasion lines, with hardware designers optimizing for discrete portability, session duration, or customization depth rather than pursuing universal device formats.
Ceramic heating elements are expanding into premium pod systems by eliminating metallic taste transfer and enabling precise temperature curves that preserve volatile flavor compounds. Enthusiast segments in California and Texas adopt these configurations despite unit cost premiums. The technology is compressing market share for traditional kanthal wire configurations that dominate mass-market disposables.
The FDA's marketing denial order enforcement against non-tobacco flavor authorizations is restructuring competitive positioning around taste neutrality. Manufacturers pivot toward tobacco-derived flavor profiles that satisfy regulatory thresholds while maintaining sensory differentiation. Pod-based systems face the steepest reformulation burden, as their closed cartridges require complete flavor architecture redesigns rather than modular adjustments available to open-tank configurations.
Young adult purchasing patterns are rotating toward convenience retail channels that prioritize transaction velocity over product education. Gas station and pharmacy chains in Texas and Florida now represent primary trial environments, displacing dedicated vape shops that previously controlled category introduction. This channel compression rewards brands with national distribution infrastructure and packaged-goods marketing capabilities over boutique positioning.
E-Cigarettes and Vaporizer Market Segmentation
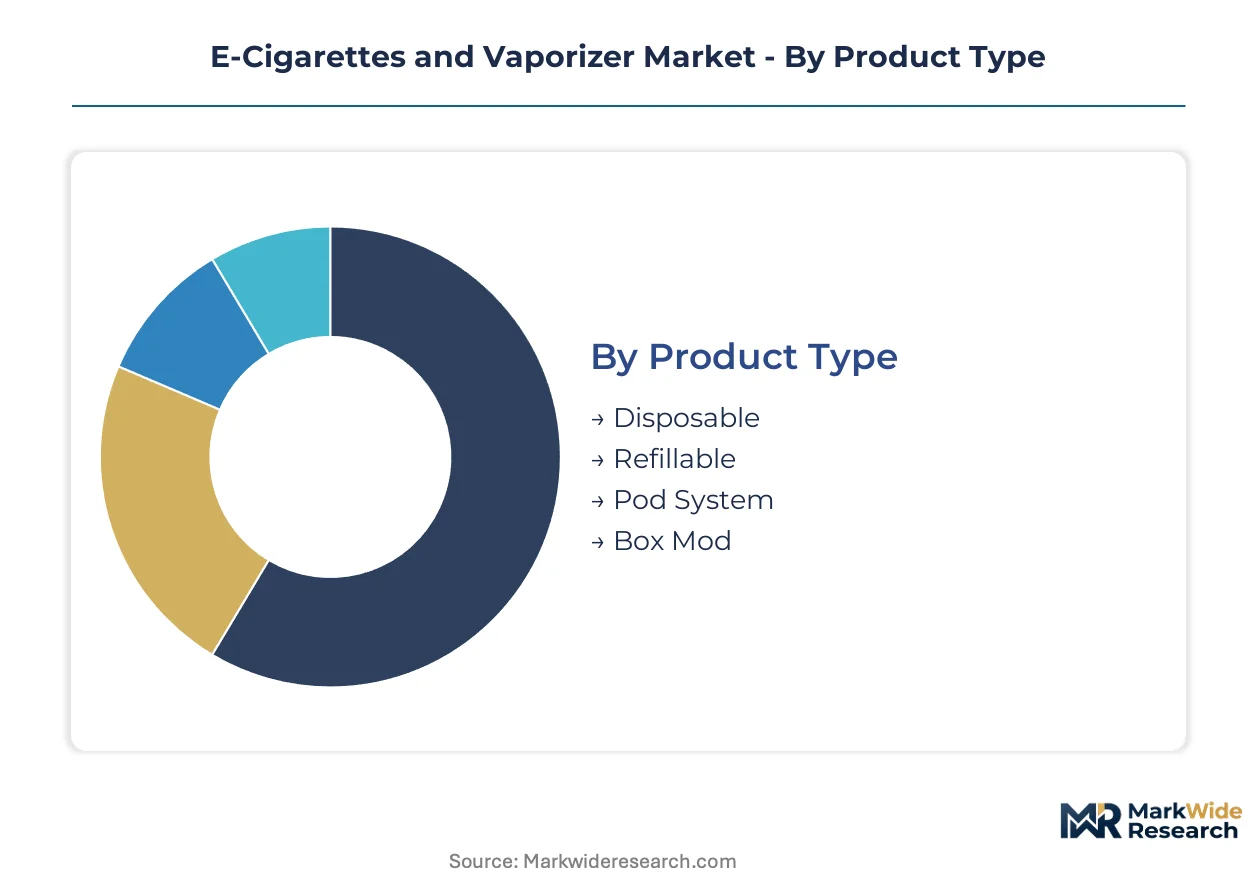
Segmentation in the e-cigarettes and vaporizer market reveals divergent margin structures and regulatory exposure across hardware formats and consumption patterns. Manufacturers calibrate portfolio depth against channel access constraints and flavor authorization risks that vary sharply by product configuration.
Product Type:
Buyers differentiate primarily by maintenance tolerance versus convenience priority, with this trade-off determining lifetime value profiles and repeat purchase cadence.
- Pod System:Closed-cartridge architectures integrate precision temperature control and draw-activated firing mechanisms within compact form factors. Demand concentrates in Texas and Florida convenience retail channels where young adult consumers prioritize discrete portability and consistent nicotine delivery without coil replacement protocols.
- Disposable:Single-use units with pre-charged lithium-ion cells and integrated e-liquid reservoirs eliminate all maintenance requirements. Volume growth accelerates in California gas station chains where transaction velocity outweighs unit economics, though flavor restrictions compress authorized SKU availability.
- Refillable:Open-tank systems enable user-controlled e-liquid selection and coil customization.
- Box Mod:High-wattage devices with interchangeable batteries and rebuildable atomizer decks serve enthusiast segments demanding granular output control.
Volume sits with Disposable units; growth tilts toward Pod System configurations.
Nicotine Content:
Regulatory thresholds and cessation positioning create distinct addressable markets based on user dependency level and pharmaceutical channel eligibility.
- High Nicotine:Concentrations exceeding 20 mg/mL deliver rapid absorption profiles through protonated nicotine salt formulations. Demand clusters in United States markets where FDA marketing authorization pathways remain navigable for tobacco-derived flavor pairings, though EU Tobacco Products Directive caps render these formulations non-compliant across member states.
- Medium Nicotine:12-20 mg/mL ranges balance satisfaction with consumption moderation goals. Adoption expands in United Kingdom smoking cessation clinics where National Health Service reimbursement frameworks subsidize medically positioned hardware.
- Low Nicotine:Sub-12 mg/mL concentrations appeal to tapering protocols and social consumption contexts.
- Nicotine Free:Zero-nicotine formulations circumvent pharmaceutical classification in Japan and enable unrestricted flavor portfolios.
Revenue concentrates in High Nicotine cartridges; steepest expansion trajectory belongs to Nicotine Free variants.
Flavor Profile:
Regulatory authorization status and sensory differentiation drive portfolio prioritization decisions amid shifting enforcement priorities.
- Tobacco:Derived from actual leaf extraction or synthetic replication, these profiles satisfy FDA marketing denial order thresholds while maintaining category access. Manufacturers in the United States pivot entire pod system architectures toward these formulations as non-tobacco characterizing flavors face systematic authorization rejection.
- Fruit:Synthetic and natural ester blends dominate disposable unit preferences in Texas and Florida where state-level bans remain absent.
- Menthol:Cooling agent formulations face concentrated regulatory scrutiny mirroring combustible tobacco restrictions.
- Dessert:Complex vanillin and lactone profiles attract enthusiast segments within open-tank configurations.
Authorization stability favors Tobacco; sensory preference momentum favors Fruit.
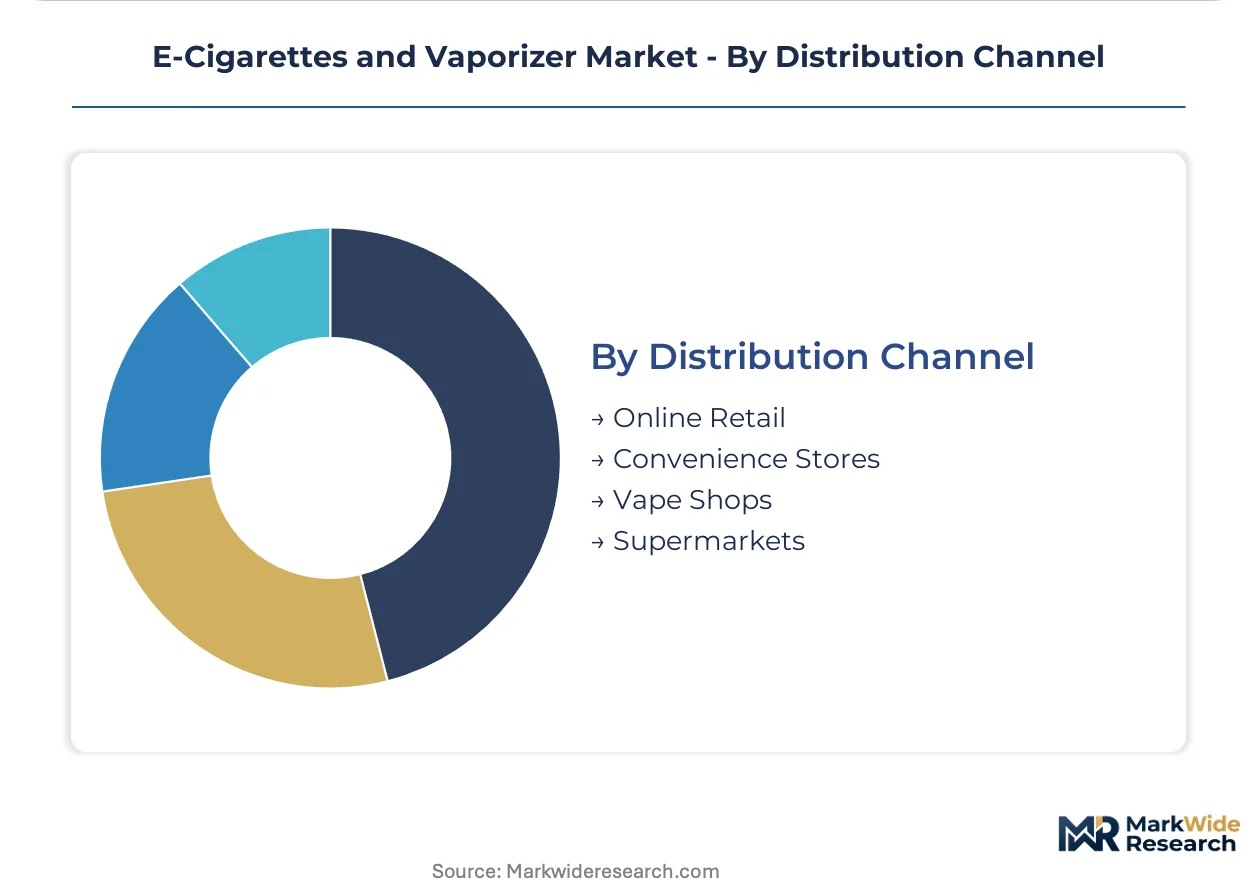
Distribution Channel:
Channel selection determines customer acquisition cost, regulatory compliance burden, and product education depth available at point of purchase.
- Convenience Stores:Gas station and pharmacy chains in Texas and Florida now represent primary trial environments for young adult consumers. National distribution infrastructure requirements favor brands with packaged-goods marketing capabilities over boutique positioning.
- Vape Shops:Specialty retailers provide coil building expertise and flavor sampling protocols that sustain enthusiast loyalty.
- Online Retail:Direct-to-consumer platforms face age verification mandates and shipping restrictions that vary by state jurisdiction.
- Supermarkets:Mass-market shelf access demands compliance with extended producer responsibility legislation in France and the Netherlands.
Transaction velocity concentrates in Convenience Stores; customer lifetime value peaks in Vape Shops.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Los Angeles anchors North American e-cigarette distribution infrastructure through its port complex and fulfillment network density, channeling hardware imports from Shenzhen manufacturing clusters into Texas and Florida retail corridors.
United States
California and Texas concentrate pod system demand through convenience retail chains where young adult consumers prioritize discrete form factors. FDA marketing denial orders systematically reject non-tobacco flavor authorizations, forcing portfolio pivots toward leaf-derived profiles. Los Angeles and Miami serve as import gateways for Shenzhen-assembled hardware entering domestic distribution.
Japan
Tokyo and Osaka metropolitan areas channel demand toward heated-tobacco devices after the Ministry of Health, Labour and Welfare classified nicotine-containing liquids as pharmaceutical items. IQOS platform adoption concentrates in Kanto region smoking lounges and designated retail. This regulatory architecture rewards aerosolized tobacco over liquid vaporization technologies.
Germany
Bavaria and North Rhine-Westphalia host smoking cessation clinics where National Health Service reimbursement frameworks subsidize medically positioned nicotine replacement hardware. REACH compliance harmonization enables standardized formulations across EU member states. Berlin serves as regulatory compliance headquarters for pan-European market access strategies.
United Kingdom
London and Manchester metropolitan areas exhibit strong pharmacy-channel penetration for medium-nicotine pod systems positioned as cessation aids. The Medicines and Healthcare products Regulatory Agency oversees pharmaceutical-grade nicotine sourcing standards. Birmingham distribution hubs handle hardware imports serving NHS reimbursement pathways.
China
Shenzhen dominates global hardware manufacturing through integrated lithium-ion cell supply chains and precision machining clusters. Export volumes concentrate through Hong Kong port facilities serving United States and European markets. Guangdong province formulators supply propylene glycol and vegetable glycerin base liquids to international brand owners.
E-Cigarettes and Vaporizer Market Competitive Landscape
Premium-margin players sit above commodity-margin players across flavor authorization status and distribution infrastructure depth. The competitive structure consolidates around three strategic archetypes: multinational tobacco conglomerates with heated-tobacco platforms, independent pod system specialists navigating FDA compliance, and Shenzhen-based hardware fabricators serving private-label demand. Dominant competitive moves include portfolio rationalization around tobacco-derived flavor profiles and vertical integration into lithium-ion power cell sourcing.
Within the multinational tier, Philip Morris International Inc. and British American Tobacco occupy positions spanning heated-tobacco and liquid vaporization categories. Shenzhen IVPS Technology Co., Ltd. anchors the hardware fabrication archetype through integrated manufacturing capabilities serving brand owners requiring original equipment production.
| Leading Market Players |
|---|
| Philip Morris International Inc. |
| British American Tobacco |
| Altria Group, Inc. |
| Imperial Brands |
| JUUL Labs, Inc. |
| Japan Tobacco International |
| R.J. Reynolds Vapor Company |
| Shenzhen IVPS Technology Co., Ltd. |
| NJOY, LLC |
| Others |
Supply & Pricing Matrix
Lithium-ion cell costs cascade through Shenzhen assembly clusters into three-tier pricing structures across premium pod systems, standard disposables, and economy refillable hardware, with ceramic coil technology commanding manufacturer margins that kanthal wire configurations cannot match.
Pricing Analysis
Value-based pricing anchored to nicotine delivery consistency and flavor preservation separates ceramic-heated pod cartridges from commodity disposables. Certification tiers—FDA marketing authorization status versus unauthorized gray-market entry—create price differentiation between compliant and non-compliant inventory. Pricing pressure stems from state-level flavor prohibitions in California and Massachusetts that eliminate premium SKU categories. Convenience retail buyers in Texas and Florida exhibit highest price sensitivity, while pharmacy-channel purchasers in the United Kingdom show lowest elasticity due to NHS reimbursement frameworks.
Supply Chain Analysis
Propylene glycol and vegetable glycerin supply rests on Guangdong province chemical processors integrated with Shenzhen hardware fabrication. Battery cell production draws from South Korean and Japanese cathode material suppliers, with final pack assembly concentrating in Guangdong. Single-source vulnerability sits with East Asian lithium-ion concentrate refining. Distribution runs through Los Angeles and Miami port gateways into Texas and Florida retail corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Players pursue captive control over lithium-ion cell supply chains to defend margin pools against input volatility and regulatory compliance costs.
For Market Incumbents: Deploy pharmaceutical-grade nicotine purification infrastructure to satisfy FDA premarket authorization requirements while synthetic nicotine entrants face agricultural price competition. Consolidate around tobacco-derived flavor portfolios as marketing denial orders systematically reject non-tobacco authorizations. Backward integration into ceramic coil manufacturing secures component supply against Shenzhen capacity constraints. For New Entrants and Emerging Players: Enter via nicotine-free formulations that circumvent pharmaceutical classification in Japan and enable unrestricted flavor development. Target Germany and United Kingdom smoking cessation clinics where NHS reimbursement frameworks subsidize medically positioned hardware. Pursue biometric-enabled pod systems with smartphone health integration as a differentiated go-to-market angle. For Investors and Strategic Acquirers: Distressed-cycle entries favor FDA-authorized pod system specialists with existing marketing granted orders in the United States. Long-term viability hinges on regulatory compliance infrastructure rather than flavor innovation capabilities. Watch FDA marketing denial order appeal outcomes as the inflection indicator for portfolio revaluation.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical Channel Expansion | NHS reimbursement in the United Kingdom and German cessation clinics subsidize hardware acquisition for medically positioned entrants. |
| Ceramic Coil Technology Integration | Premium pod systems in California and Texas adopt temperature-precise heating elements that eliminate metallic taste transfer. |
| Closed-Loop Recycling Compliance | Extended producer responsibility mandates in France and the Netherlands require manufacturer-financed end-of-life collection infrastructure. |
| Synthetic Nicotine Sourcing | Pharmaceutical-grade purification capabilities differentiate formulators from agricultural nicotine price competitors. |
| Biometric Usage Tracking | Puff-tracking sensors with smartphone health applications differentiate premium hardware from commodity disposables. |
Research Methodology
Independent corroboration across FDA premarket tobacco product application filings, EU Tobacco Products Directive compliance databases, and Japanese Ministry of Health pharmaceutical classification records underwrites the qualitative findings. Primary interviews with e-liquid formulation chemists, hardware procurement managers at convenience retail chains, regulatory affairs leads at pod system manufacturers, and smoking cessation clinic directors in Germany and the United Kingdom combined with secondary validation from customs import records, REACH registration databases, and SEC 10-K disclosures. Bottom-up SKU-level volume aggregation and top-down category spend analysis triangulate market sizing.
Comparable-period anchoring to historical FDA authorization timelines and flavor restriction implementation dates structures the forecast window across the projection horizon. Segmentation dimensions modeled include product type architecture, nicotine concentration tier, flavor authorization status, and distribution channel access. CAGRs derive from category growth rate reconciliation against demographic consumption shift assumptions. Industry-specific forecast inputs incorporate lithium-ion cell price trajectory assumptions and regulatory enforcement intensity indices.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated FDA marketing denial order enforcement or expanded state-level flavor prohibition adoption. Forecasts reflect documented assumptions regarding authorization pathway navigability and youth access enforcement mechanisms. A small set of regulatory trigger events warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tobacco Products
GCC E-Cigarette Market
Tobacco Products
North America E-Cigarette Market
Tobacco Products
Premium Cigarette Market
Tobacco Products
Europe Cigarette Market
Tobacco Products
Japan Heated Tobacco Products Market
Tobacco Products
Homemade Cigars Market
Tobacco Products
Menthol Cigarette Market
Tobacco Products
Africa Tobacco Products Market
Tobacco Products
Smokeless Cigarettes Market
Tobacco Products
West Africa Cigarettes Market
Tobacco Products
Asia-Pacific E Cigarettes Market
Tobacco Products
Tobacco Products Market
Tobacco Products
Global Flavor Capsule Cigarette Market
Tobacco Products
Cigar Tubes Market
Tobacco Products
E-Cigarette and Vape Market
Tobacco Products
Heated Tobacco Products Market