
 Global Hematology Diagnostics Market | 2026-2036
Global Hematology Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hematology Diagnostics Market Foresight
Software-defined maintenance contracts is decoupling instrument revenue from consumable pull-through in hematology diagnostics. Sysmex Corporation anchors its position through captive reagent ecosystems tied to analyzer placements. Danaher Corporation leverages its Life Sciences platform to integrate hematology workflows with broader diagnostic menus. Abbott Laboratories differentiates through point-of-care hematology systems that extend into physician office laboratories.
Hematology diagnostics encompasses the quantitative and morphological analysis of blood cellular components, employing technologies such as impedance-based cell counting with discriminators set at specific thresholds for erythrocytes, leukocytes, and platelets to generate complete blood count parameters for clinical decision-making. Automated Hematology Analyzers dominate capital expenditure budgets while Reagents & Kits capture recurring revenue streams with durable margin profiles. Point-of-Care Devices represent the fastest-expanding deployment category as health systems decentralize testing to reduce emergency department throughput times.
The FDA oversees premarket notification pathways for hematology analyzers while CLIA proficiency standards govern laboratory quality systems that shape instrument validation requirements. The EU IVDR transition is forcing manufacturers to recertify legacy hematology products under stricter clinical evidence rules, compressing market access timelines for mid-tier suppliers. Stakeholders must monitor how cloud-connected hematology platforms trigger cross-border data governance obligations under GDPR and emerging national health data frameworks.
Market Dynamics
Software-defined maintenance contracts are decoupling instrument revenue from consumable pull-through, forcing hematology diagnostics vendors to rebuild recurring revenue models around data services and predictive analytics rather than captive reagent lock-in.
Growth Catalysts
- EU IVDR Recertification Mandate:Stricter clinical evidence requirements under the EU In Vitro Diagnostic Regulation are accelerating replacement cycles for legacy analyzers as mid-tier suppliers exit, consolidating demand around compliant platforms.
- Emergency Department Decentralization:Health systems in the United States are deploying point-of-care hematology systems to reduce throughput times, expanding addressable volume beyond traditional hospital laboratories.
- Impedance-Based Cytometry:Advances in multi-angle light scatter and fluorescence flow cytometry are extending automated differential capabilities, reducing manual slide review rates and labor dependency in high-volume settings.
Market Restraints
- Reagent Supply Concentration:Captive reagent ecosystems tied to specific analyzer platforms create switching costs that limit price competition and lock laboratories into single-vendor dependencies.
- EU IVDR Compliance Burden:The transition to stricter clinical evidence rules under the EU In Vitro Diagnostic Regulation is compressing market access timelines and raising certification costs for manufacturers with legacy product portfolios.
- Fluorochrome Input Volatility:Specialized fluorescent dyes and monoclonal antibody conjugates face supply chain vulnerabilities from concentrated chemical synthesis capacity in specific Asian manufacturing clusters.
Strategic Opportunities
- Cloud-Connected Platform Expansion:Remote monitoring and AI-assisted morphology review are creating service revenue streams that decouple value capture from physical consumable shipments.
- Physician Office Laboratory Integration:Point-of-care hematology systems are penetrating ambulatory settings in Germany and Japan where reimbursement frameworks favor decentralized testing.
- Japan's Precision Medicine Infrastructure:METI-funded initiatives for genomic-hematology integration are creating demand for analyzers with enhanced sample-to-result connectivity and LIS interoperability.
Industry Challenges
- Cross-Border Data Governance:Cloud-connected hematology platforms trigger GDPR compliance obligations and emerging national health data frameworks that fragment platform architectures across jurisdictions.
- Analyzer-LIS Integration Complexity:Legacy hospital information systems require customized middleware development, extending deployment timelines and inflating professional services costs.
- Specialized Field Service Engineering:Advanced hematology analyzers demand technicians with combined optical, fluidics, and software troubleshooting skills that outpace vocational training pipeline output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hematology Diagnostics Market |
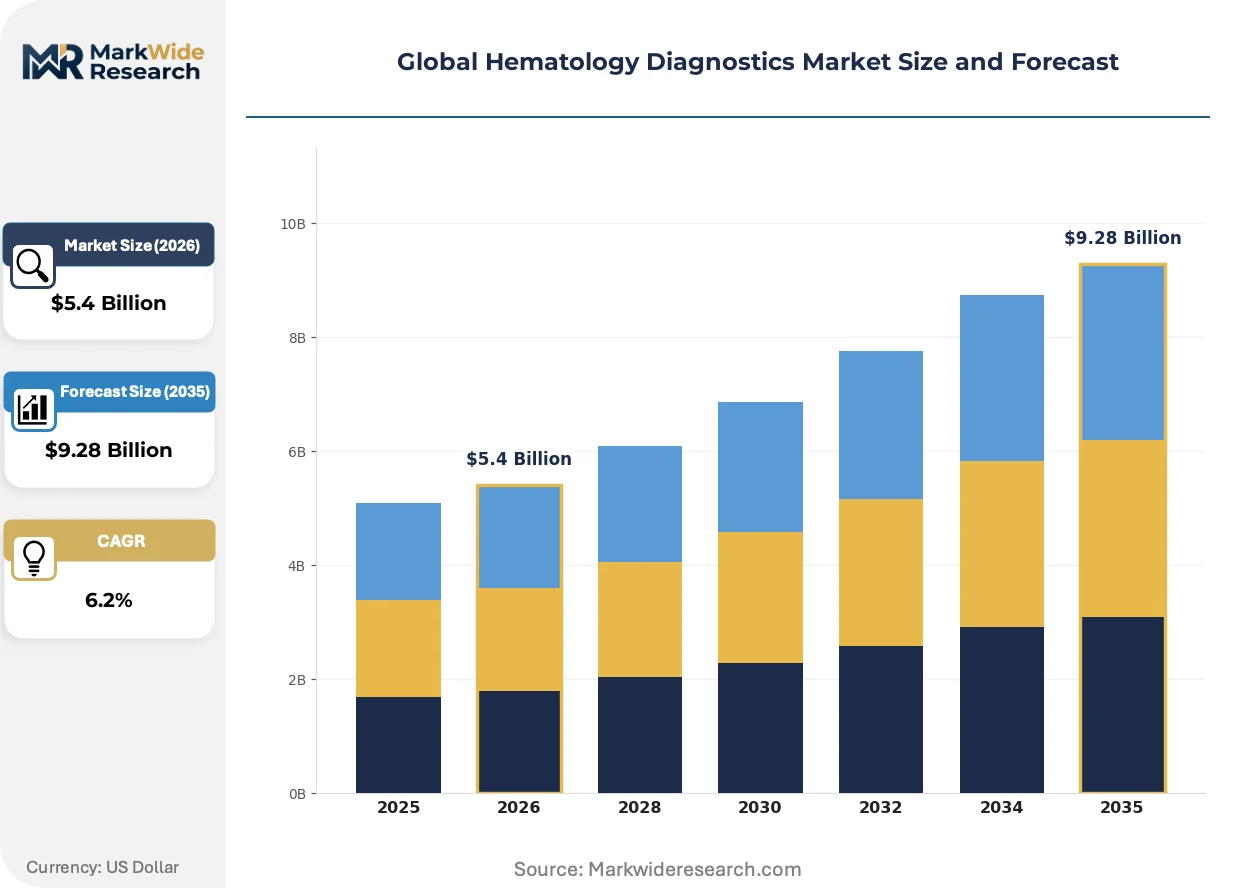
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Hematology Analyzers, Coagulation Analyzers, Reagents & Kits, Slide Stainers, Flow Cytometers Therapy Area: Leukemia, Thrombocytopenia, Anemia, Hemophilia, Lymphoma, Myeloma End User: Diagnostic Laboratories, Blood Banks, Research Institutes, Academic Centers, Specialty Clinics, Pathology Labs Deployment: Standalone Systems, Integrated Platforms, Point-of-Care Devices, Cloud-Based Solutions, On-Premise Installations |
| Companies Covered | Abbott Laboratories, Bio-Rad Laboratories, Sysmex Corporation, Mindray, HORIBA, Danaher Corporation, Nihon Kohden Corporation, Thermo Fisher Scientific, Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hematology Diagnostics Market Shifts & Advancements
Artificial intelligence-assisted morphology classification is compressing the path from raw cellular imaging to diagnostic interpretation, while regulatory frameworks on both sides of the Atlantic force simultaneous compliance investments.
Digital morphology analysis combined with convolutional neural networks is rewriting how laboratories handle manual differential reviews. Academic medical centers in the United States are piloting systems that pre-classify abnormal cells for pathologist confirmation. This technology is rewriting labor allocation models by reducing skilled technologist time per sample while maintaining diagnostic accuracy thresholds.
The EU In Vitro Diagnostic Regulation's clinical evidence requirements are forcing manufacturers to generate prospective performance data for legacy hematology parameters. Industrial consequence includes delayed market access for iterative product improvements and accelerated obsolescence of platforms lacking economic justification for recertification. Mid-tier suppliers with concentrated European revenue exposure are responding by divesting hematology portfolios or seeking strategic acquirers with compliant quality management systems.
After-sales service unbundling is gaining traction as hospital procurement departments in Germany demand itemized contracts separating warranty, preventive maintenance, and reagent supply. This pattern is displacing traditional bundled agreements that cross-subsidized instrument placement costs. The shift is most visible in integrated delivery networks where centralized procurement functions negotiate enterprise-wide diagnostics contracts.
Global Hematology Diagnostics Market Segmentation
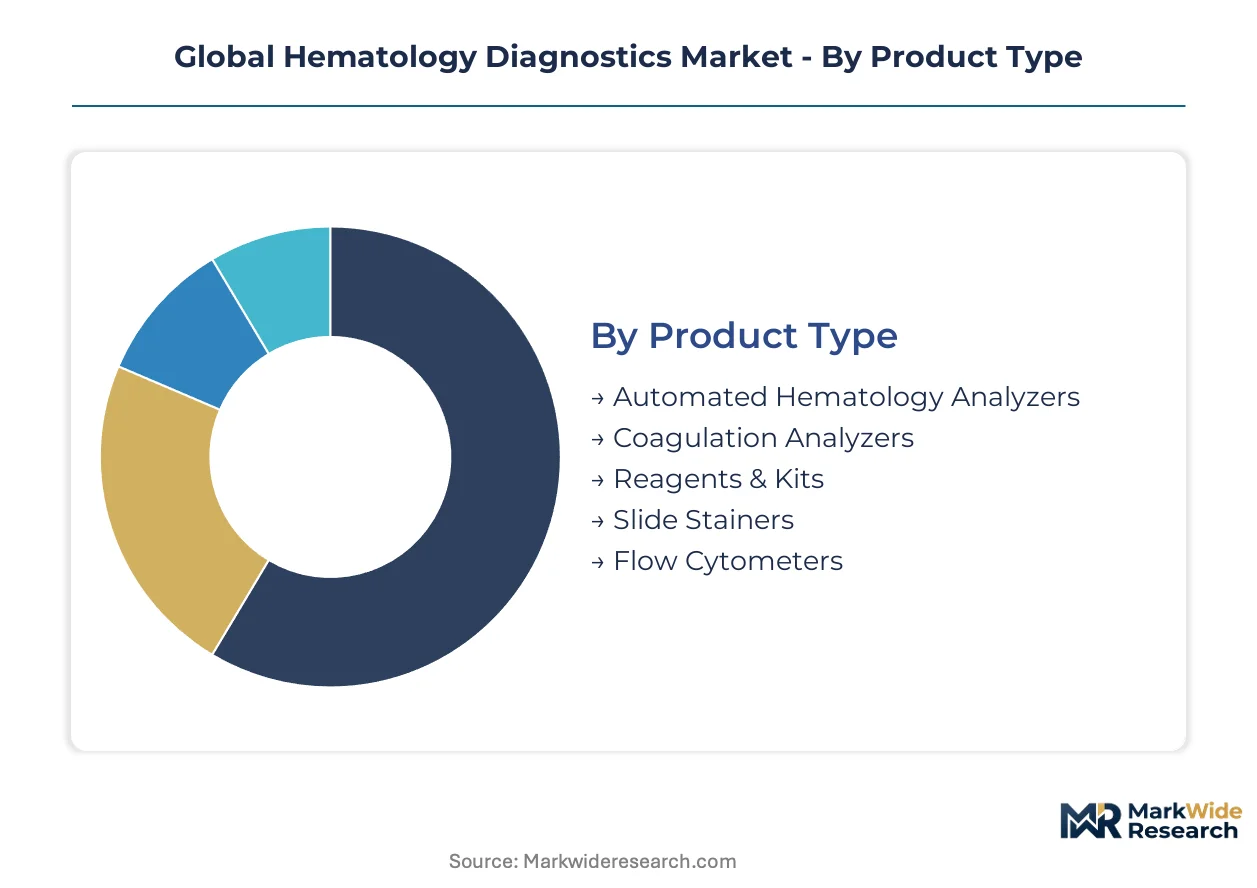
Hematology diagnostics segmentation reflects divergent capital intensity and workflow integration requirements. Automated platforms dominate hospital laboratory procurement while decentralized deployment models reshape volume distribution across care settings.
Product Type:
Standalone analyzers operate in discrete laboratory workflows whereas integrated systems embed within broader diagnostic automation architectures.
- Automated Hematology Analyzers:Multi-parameter cell counters employing impedance and light scatter technologies generate complete blood count differentials with minimal operator intervention. Demand concentrates in United States hospital laboratories where labor cost pressures drive automation adoption against staffing shortages.
- Reagents & Kits:Consumable panels including lysing reagents, diluents, and calibrator materials generate recurring revenue tied to analyzer test volumes. Germany's statutory health insurance reimbursement framework favors high-throughput platforms with locked reagent contracts, entrenching vendor-specific supply relationships.
- Coagulation Analyzers:Clot-based and chromogenic assay systems for hemostasis testing in anticoagulation monitoring.
- Slide Stainers:Automated Wright-Giemsa and Romanowsky staining systems for peripheral blood smear preparation.
- Flow Cytometers:Fluorescence-activated cell sorting instruments for immunophenotyping and rare cell detection.
Volume placements concentrate in Automated Hematology Analyzers; the faster expansion belongs to Reagents & Kits.
Therapy Area:
Diagnostic intensity varies sharply across hematologic conditions, with malignant disorders demanding comprehensive molecular and morphologic workups.
- Leukemia:Acute and chronic leukemias require integrated flow cytometry, cytogenetics, and molecular profiling for classification and minimal residual disease monitoring. Academic medical centers in Japan leverage METI-funded precision medicine infrastructure to consolidate genomic-hematology testing workflows.
- Anemia:Iron deficiency, hemolytic, and megaloblastic anemias represent high-frequency indications with established automated screening protocols. Primary care networks in Germany deploy point-of-care hemoglobin testing to reduce specialist referral volumes for nutritional deficiency workups.
- Thrombocytopenia:Immune-mediated and consumptive platelet disorders requiring specialized coagulation panels.
- Hemophilia:Congenital factor deficiencies necessitating factor activity assays and inhibitor screening.
- Lymphoma:Hodgkin and non-Hodgkin classifications requiring immunohistochemistry and flow cytometry correlation.
- Myeloma:Plasma cell dyscrasias with serum protein electrophoresis and free light chain quantification needs.
Test volumes cluster in Anemia screening; the steepest expansion trajectory sits with Leukemia molecular profiling.
End User:
Procurement authority and technical capability thresholds fragment demand across institutional categories with divergent capital access.
- Diagnostic Laboratories:High-volume reference and hospital-affiliated labs processing thousands of samples daily with full automation suites. Integrated delivery networks in the United States centralize hematology procurement through enterprise contracts that bundle instrumentation, reagents, and professional services.
- Blood Banks:Transfusion services requiring donor screening, cross-matching, and component quality testing with stringent turnaround requirements. Japanese Red Cross Blood Center networks maintain dedicated hematology lines for platelet and leukocyte counting in component preparation.
- Research Institutes:Investigational platforms for biomarker discovery and therapeutic development.
- Academic Centers:Teaching hospitals combining clinical service with training missions and protocol development.
- Specialty Clinics:Hematology-oncology and coagulation-focused ambulatory practices.
- Pathology Labs:Morphology-centric operations emphasizing manual differential confirmation.
Capital deployment concentrates in Diagnostic Laboratories; Specialty Clinics are gaining share fastest through point-of-care expansion.
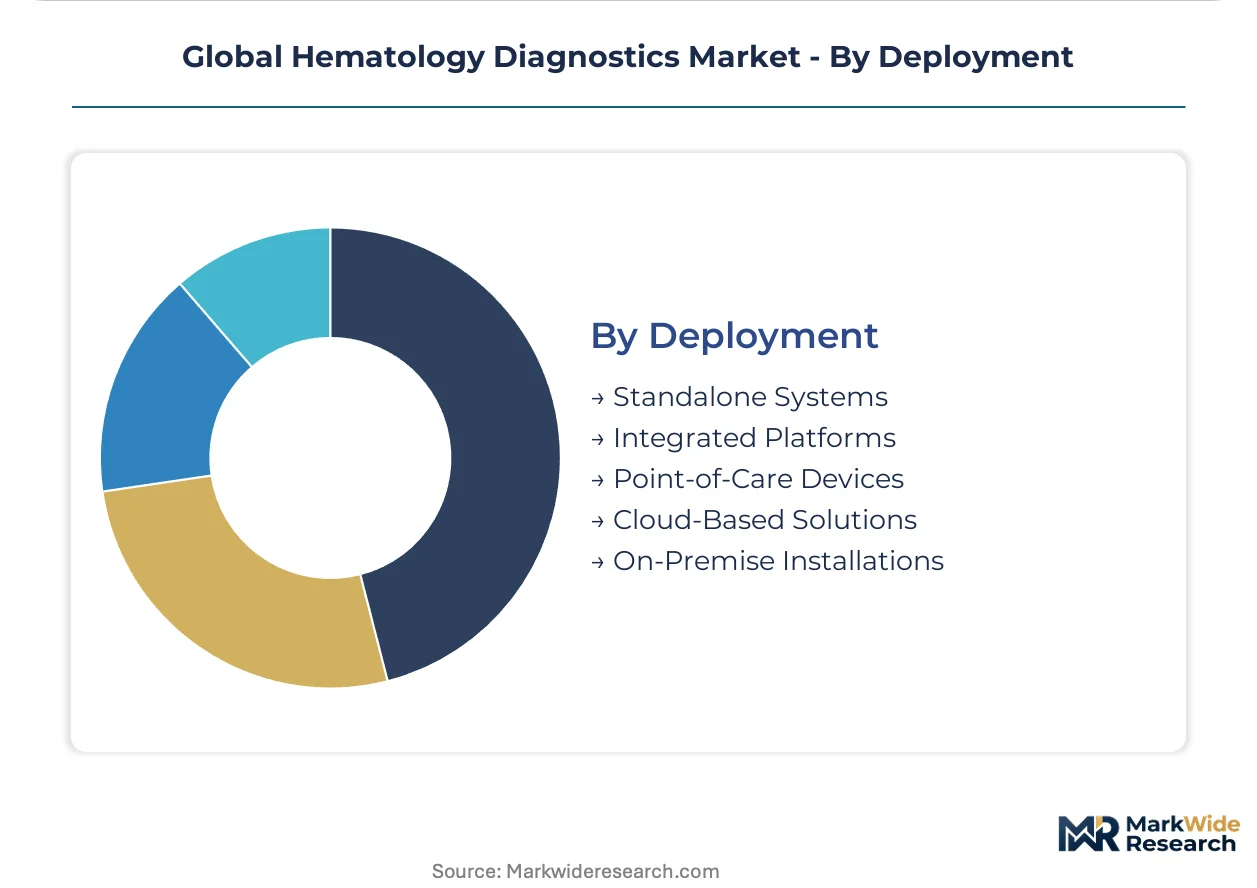
Deployment:
Physical footprint and connectivity architecture determine where each model delivers measurable workflow advantage.
- Point-of-Care Devices:Compact analyzers for capillary blood testing in emergency departments, physician offices, and resource-limited settings. Health systems across the United States deploy these in ED triage to reduce length-of-stay metrics tied to reimbursement penalties.
- Integrated Platforms:Modular systems connecting hematology, chemistry, and immunoassay modules through unified sample handling and data management. German university hospitals favor these for consolidated core laboratory designs that minimize floor space and staffing headcount.
- Standalone Systems:Discrete analyzers operating without upstream or downstream automation coupling.
- Cloud-Based Solutions:Remote result verification, AI-assisted morphology review, and predictive maintenance via internet-connected platforms.
- On-Premise Installations:Traditional locally-hosted LIS integration without external data transmission dependencies.
Installed base concentrates in Integrated Platforms; Point-of-Care Devices are climbing the fastest amid decentralization priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Instrument manufacturing clusters in Japan and Germany supply analytical platforms to consumption centers in the United States and China. Reagent production concentrates near chemical synthesis hubs in Switzerland and the Netherlands. Service revenue now exceeds hardware margins in mature markets.
United States
Emergency department decentralization and integrated delivery network consolidation drive analyzer placements. FDA premarket notification pathways govern 510(k) clearances for multi-parameter cell counters. Academic medical centers in Boston and the Research Triangle pilot AI-assisted morphology classification systems.
Germany
Statutory health insurance reimbursement frameworks favor high-throughput platforms with locked reagent contracts. EU IVDR recertification mandates compress market access timelines for legacy products. University hospitals in Bavaria and North Rhine-Westphalia deploy integrated core laboratory designs minimizing floor space.
Japan
METI-funded precision medicine infrastructure creates demand for genomic-hematology integration. PMDA oversees in vitro diagnostic approvals with emphasis on clinical evidence generation. The Kanto region around Tokyo anchors domestic analyzer production and Red Cross Blood Center networks.
China
Hospital laboratory automation upgrades proceed amid healthcare infrastructure expansion. NMPA regulates Class II and III in vitro diagnostic devices with accelerating review timelines. Manufacturing clusters in Jiangsu and Zhejiang provinces supply reagent materials to domestic and export markets.
India
Private diagnostic laboratory chains expand automated testing footprints in tier-2 and tier-3 cities. CDSCO regulates medical device imports with recent harmonization toward international standards. Hyderabad and Bengaluru clusters concentrate on hematology reagent formulation and distributed analyzer servicing.
Global Hematology Diagnostics Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the hematology diagnostics value chain. The market structure consolidates around integrated platform vendors with captive reagent ecosystems, while mid-tier suppliers face exit pressure from EU IVDR compliance burdens. Three archetypes dominate: diversified conglomerates with life sciences platforms, specialized hematology pure-plays with analyzer-reagent lock-in, and point-of-care device specialists. Competitive moves center on strategic acquisitions to secure compliant quality management systems and cloud-connected service unbundling to capture recurring revenue.
Within the diversified conglomerate tier, Danaher Corporation and Abbott Laboratories exemplify platform integration strategies spanning diagnostic menus. Sysmex Corporation anchors the specialized pure-play archetype with analyzer placements tied to reagent pull-through models. These three entities represent contrasting approaches to decoupling instrument revenue from consumable dependency through software-defined maintenance contracts and predictive analytics services.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Bio-Rad Laboratories |
| Sysmex Corporation |
| Mindray |
| HORIBA |
| Danaher Corporation |
| Nihon Kohden Corporation |
| Thermo Fisher Scientific |
| Siemens Healthineers |
| Others |
Supply & Pricing Matrix
Multi-angle light scatter technology migration is compressing manufacturing scale economies for mid-tier suppliers while concentrating procurement leverage among laboratories with volume consolidation. This shift simultaneously elevates reagent contract values as the primary pricing anchor and locks buyers into analyzer-specific consumable ecosystems that resist vendor switching.
Pricing Analysis
Margin tightening in the mid-tier analyzer segment reflects EU IVDR recertification cost absorption and accelerated obsolescence of non-compliant platforms. Three-tier pricing structure across premium, standard, and economy levels separates cloud-connected integrated platforms from standalone systems and point-of-care devices, with FDA 510(k) clearance tier commanding brand premiums. Cost compression in reagent contracts intensifies as German statutory health insurance frameworks favor locked supply relationships. Diagnostic laboratories in integrated delivery networks exhibit highest price sensitivity due to enterprise procurement leverage, while physician office laboratories show lowest sensitivity amid reimbursement-protected point-of-care placement.
Supply Chain Analysis
Dual-sourcing qualification requirements for fluorochrome dyes and monoclonal antibody conjugates are forcing manufacturers to validate secondary chemical synthesis suppliers in Switzerland and the Netherlands alongside primary Asian manufacturing clusters. Geographic supply concentration centers on Japan and Germany for analyzer production, with reagent formulation anchored in Swiss and Dutch chemical synthesis hubs. Raw material dependencies include specialized fluorescent dyes, high-purity buffer chemicals, and precision optical components. Single-source vulnerability persists for proprietary reagent formulations tied to specific analyzer platforms. Distribution runs through regional service organizations with captive field engineering capabilities rather than third-party logistics channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hematology diagnostics market is consolidating around compliant quality management systems as EU IVDR recertification burdens force mid-tier supplier exits. This consolidation dynamic favors platform vendors with captive reagent ecosystems and cloud-connected service architectures.
For Market Incumbents: Anticipate accelerated replacement cycles for legacy analyzers by pre-positioning IVDR-compliant platforms before competitor recertification timelines expire. Defensive consolidation moves should emphasize backward integration into fluorochrome dye supply to mitigate Asian manufacturing cluster concentration risk, paired with software-defined maintenance contract unbundling to capture predictive analytics revenue streams that decouple value from physical consumable shipments. For New Entrants and Emerging Players: The premium-to-economy price-point gap in point-of-care hematology systems creates white-space opportunity for compact analyzer platforms targeting emergency department decentralization in United States health systems. Most penetrable segment lies in physician office laboratories across Germany and Japan where reimbursement frameworks favor decentralized testing. Go-to-market angle should emphasize capillary blood testing workflows with rapid turnaround metrics that reduce specialist referral volumes. For Investors and Strategic Acquirers: Re-rating potential sits with specialized hematology pure-plays possessing compliant EU IVDR quality management systems given accelerated demand consolidation around recertified platforms. Long-term viability framing centers on five-to-ten year service revenue expansion as hardware margins compress. Acquisition target archetype includes mid-tier suppliers with concentrated European revenue exposure seeking compliant acquirers. Signal to watch is cloud-connected platform deployment velocity as indicator of recurring revenue transition success.| Strategic Initiative | Industry Significance |
|---|---|
| EU IVDR Recertification Pathway | Accelerates compliant platform demand as mid-tier suppliers exit under stricter clinical evidence rules. |
| Cloud-Connected Platform Development | Creates AI-assisted morphology review revenue streams decoupled from consumable pull-through. |
| Hospital System Partnership | Locks in integrated delivery network procurement through enterprise-wide diagnostics contracts. |
| Reagent Supply Backward Integration | Mitigates fluorochrome input volatility from concentrated Asian chemical synthesis capacity. |
| Point-of-Care Geographic Expansion | Captures emergency department decentralization demand in United States health systems. |
Research Methodology
Document review covered FDA 510(k) filings, EU IVDR technical documentation, and hospital procurement databases, complemented by interviews with laboratory directors, biomedical engineers, GPO contracts managers, and diagnostic platform product managers. Secondary validation drew from PMDA approval records, CMS Medicare reimbursement schedules, and hematology analyzer installation base estimates. Bottom-up instrument placement and reagent volume modeling triangulated against top-down market sizing from regulatory filing revenue disclosures.
Cross-referencing historical placement patterns against expert panel input shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type, therapy area, end user category, and deployment architecture. CAGRs were derived from instrument replacement cycle analysis and consumable pull-through coefficients. Industry-specific forecast inputs encompassed EU IVDR transition timelines and cloud-connected platform adoption curves.
Inputs from regulatory filing databases and hospital procurement systems were available through the study window; gaps in real-time reagent pricing transparency introduce uncertainty bands around consumable revenue projections. Deviation in EU IVDR enforcement stringency or fluorochrome supply chain disruption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Blood Plasma Market
Hematology
Polycythemia Vera Treatment Market
Hematology
Burkitt Lymphoma Treatment Market
Hematology
Hemoglobin Analyzer Market
Hematology
Acute Myeloid Leukemia Treatment Market
Hematology
Immune Thrombocytopenia (ITP) Market
Hematology
Warm Autoimmune Hemolytic Anemia Market
Hematology
Warm Autoimmune Hemolytic Anemia (WAIHA) Treatment Market
Hematology
Peripheral T-Cell Lymphoma Treatment Market
Hematology
Haematocrit Centrifuge Market
Hematology
Sickle-Cell Anemia Therapeutics Market
Hematology
Bleeding Disorders Therapeutics Market
Hematology
Idiopathic Thrombocytopenic Purpura Market
Hematology
Follicular Lymphoma Treatment Market
Hematology
Global Hematopoietic Stem Cell Transplantation Market
Hematology
Lymphoproliferative Disorder Treatment Market