
 Heavy Metal Testing Market | 2026-2036
Heavy Metal Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Heavy Metal Testing Market Analysis
Multi-source outsourcing of analytical services is consolidating as large pharmaceutical and food manufacturers pare down approved vendor lists. Eurofins Scientific SE leverages its pan-European laboratory network to capture recurring environmental compliance contracts. SGS S.A. anchors its position through integrated testing and certification bundles that reduce client procurement overhead. Bureau Veritas SA differentiates via marine and industrial sector specialization where regulatory inspection cycles create predictable revenue streams.
Heavy metal testing encompasses quantitative and qualitative analytical methods for detecting toxic metallic elements such as lead, cadmium, mercury, and arsenic at trace concentrations typically measured in parts per billion. These procedures employ atomic absorption spectroscopy, inductively coupled plasma mass spectrometry, and X-ray fluorescence to determine elemental composition in matrices ranging from biological tissues to geological samples. Inductively coupled plasma mass spectrometry commands the premium instrument segment due to its multi-element detection limits and throughput advantages in high-volume pharmaceutical and environmental laboratories. Food safety testing applications are expanding fastest as import screening protocols and processed food supply chain audits intensify across major economies.
The US FDA enforces heavy metal action levels in food and dietary supplements through its Total Diet Study and import alert systems, while the European EMA's ICH Q3D guideline mandates elemental impurity risk assessments for all new drug applications. China's NMPA and SAMR have aligned domestic pharmaceutical standards with ICH guidelines, creating harmonized demand for compliant testing infrastructure. Stakeholders must monitor evolving maximum residue limits in food contact materials and emerging per- and polyfluoroalkyl substance regulations that may extend testing portfolios beyond traditional metallic contaminants.
Market Dynamics
Pharmaceutical quality control budgets are expanding under ICH Q3D elemental impurity mandates, compressing testing timelines from months to weeks while elevating analytical precision requirements. Contract laboratories face capacity constraints as manufacturers consolidate vendor lists and demand integrated compliance bundles.
Growth Catalysts
- ICH Q3D Implementation:The EMA's elemental impurity guideline now covers all new drug applications, forcing reformulation screening and expanding contract testing volumes across European manufacturing clusters.
- Food Import Screening Intensification:Processed food supply chain audits in major economies are multiplying testing touchpoints, particularly for heavy metals in packaged imports and dietary supplements.
- ICP-MS Throughput Advantages:Inductively coupled plasma mass spectrometry's multi-element detection capabilities are displacing atomic absorption methods in high-volume pharmaceutical and environmental laboratories.
Market Restraints
- Instrument Capital Intensity:ICP-MS systems require seven-figure capital outlays and specialized infrastructure, concentrating advanced analytical capacity among large contract laboratory networks.
- Helium Supply Concentration:ICP-MS operations depend on helium as a plasma gas, with supply vulnerability concentrated in Qatar and the United States creating input cost volatility.
- Technical Talent Scarcity:Mass spectrometry operation and method development expertise remains concentrated in industrial clusters around Basel, Frankfurt, and Boston.
Strategic Opportunities
- India Pharmaceutical Expansion:CDSCO alignment with ICH Q3D standards creates compliant testing infrastructure demand as domestic API manufacturing scales.
- PFAS Testing Portfolio Extension:Emerging per- and polyfluoroalkyl substance regulations in the European Union and United States extend analytical service menus beyond traditional metallic contaminants.
- Portable XRF Deployment:Handheld X-ray fluorescence units enable field-based screening, opening environmental remediation and mining assay channels previously served by centralized laboratories.
Industry Challenges
- Method Validation Complexity:Matrix-specific interference suppression for biological tissues and complex drug formulations extends development timelines and strains analytical chemistry staffing.
- Multi-Jurisdiction Certification Burden:Laboratories serving pharmaceutical clients must maintain ISO 17025, GLP, and national GMP certifications simultaneously, creating audit cycle congestion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heavy Metal Testing Market |
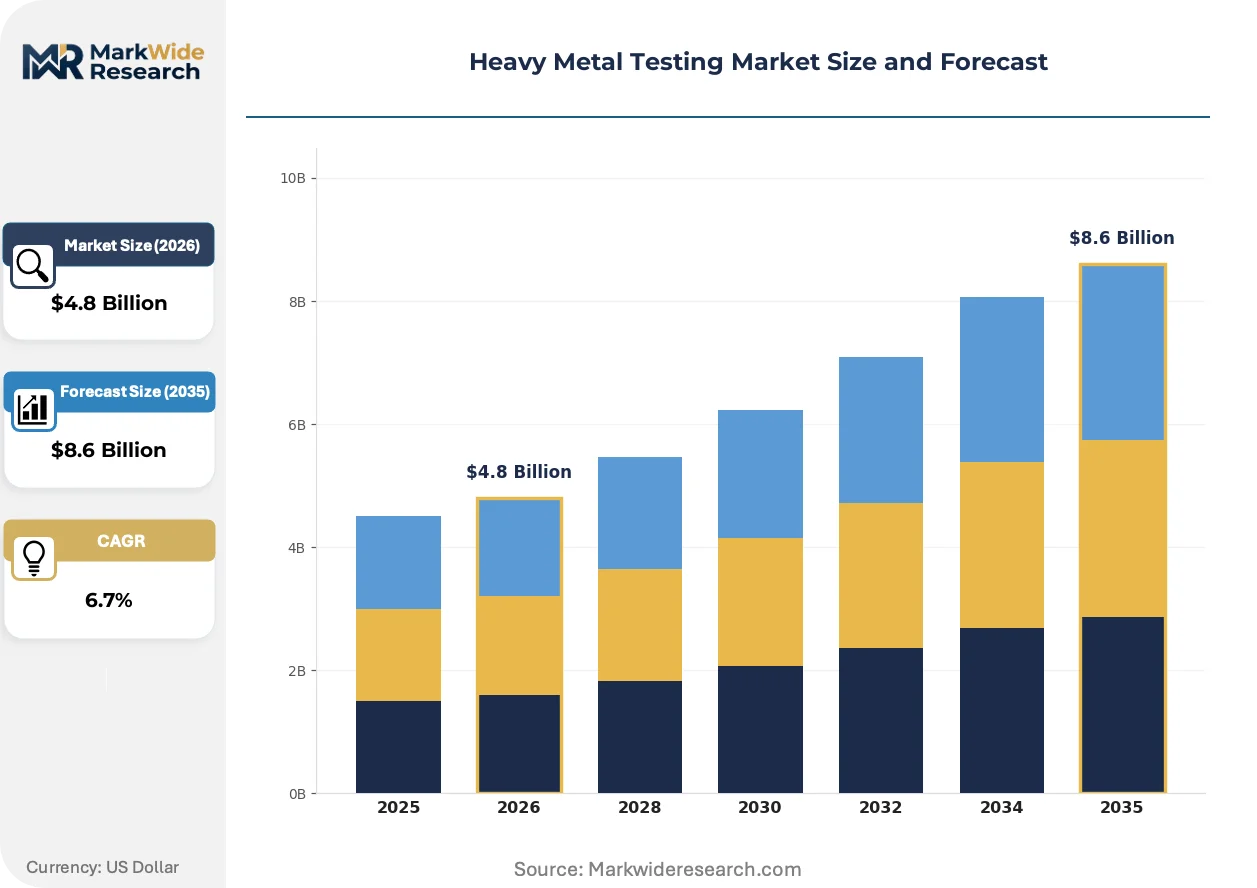
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Atomic Absorption Spectroscopy, Inductively Coupled Plasma Mass Spectrometry, X-Ray Fluorescence, Total Reflection X-Ray Fluorescence End User: Environmental Testing Labs, Food and Beverage Manufacturers, Pharmaceutical Companies, Mining Industries Application: Soil Testing, Water Quality Assessment, Material Analysis, Food Safety Testing Technology: Wet Chemistry, Spectroscopic Methods, Electrochemical Methods, Microscopy Techniques |
| Companies Covered | Merck KGaA, TÜV SÜD AG, Eurofins Scientific SE, LGC Limited, Bureau Veritas SA, SGS S.A., ALS Limited, Mérieux NutriSciences Corporation, Intertek Group PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heavy Metal Testing Market Emerging Trajectories
Automation and regulatory harmonization are compressing testing turnaround times while elevating data integrity requirements. Laboratory information management systems now integrate directly with chromatography and spectrometry platforms.
Triple quadrupole ICP-MS is consolidating its position as the reference method for ultra-trace elemental analysis in pharmaceutical matrices. Large molecule and cell therapy manufacturers are adopting this platform for extractable and leachable studies. The technology is consolidating multi-instrument workflows into single-platform configurations, reducing capital deployment and headcount per test.
China's NMPA and SAMR have aligned domestic pharmaceutical standards with ICH Q3D, eliminating redundant testing protocols for multinational submissions. This harmonization accelerates approval timelines for imported drug products. Domestic contract laboratories in Shanghai and Suzhou are upgrading ICP-MS capacity to capture compliance-driven outsourcing from international sponsors.
Multi-year testing contracts are replacing transactional project-based procurement as pharmaceutical manufacturers reduce approved vendor lists. Large food manufacturers now bundle environmental monitoring, raw material screening, and finished product release under single-provider agreements. Germany's industrial chemical clusters exhibit the most advanced consolidation, with BASF and Bayer affiliates driving integrated compliance purchasing.
Heavy Metal Testing Market Segmentation
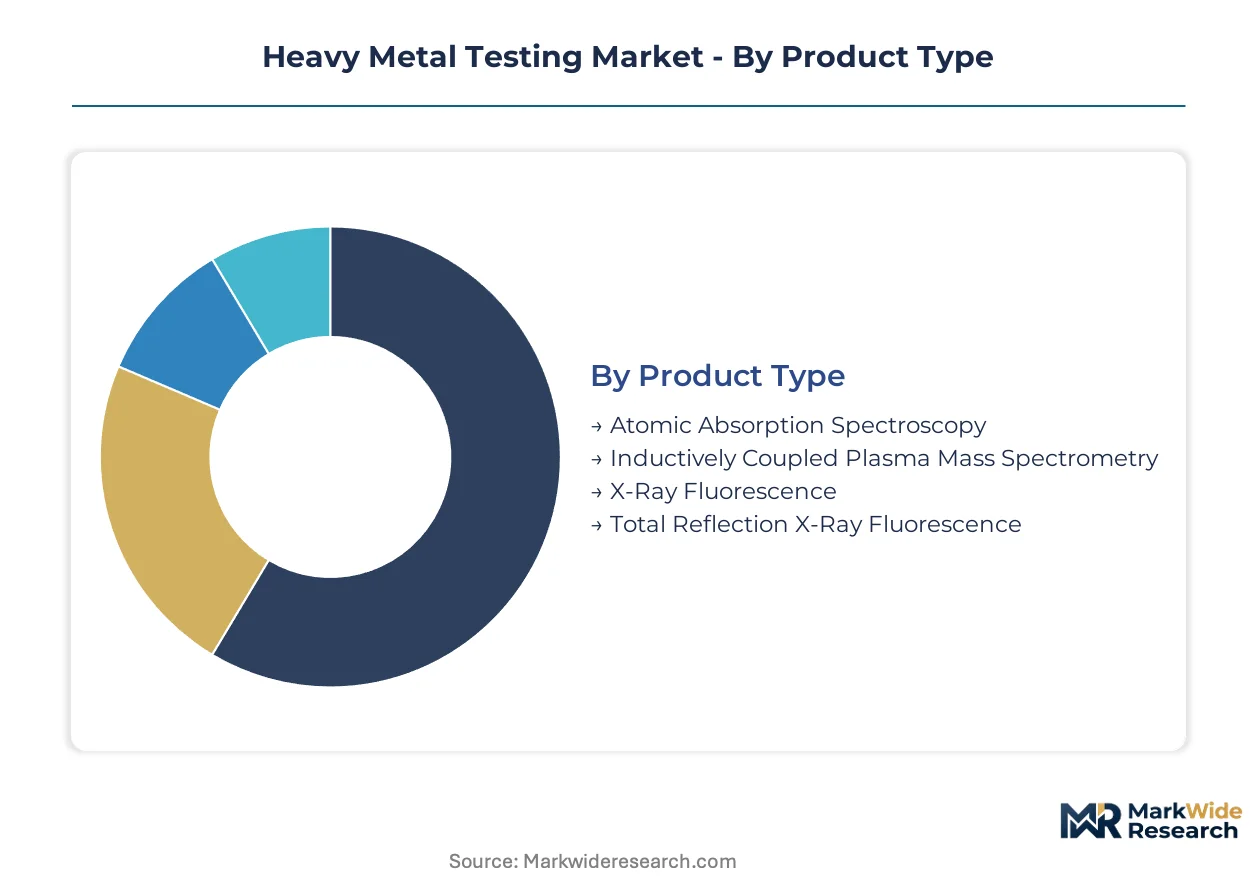
Heavy metal testing instrumentation varies dramatically in capital intensity, throughput capability, and regulatory acceptance. End-use concentration in pharmaceutical quality control and environmental compliance drives divergent purchasing patterns across segments. Application requirements dictate method selection, with food safety protocols demanding faster turnaround than geological surveys.
Product Type:
Customization spans from benchtop units for routine screening to fully automated multi-element platforms requiring dedicated infrastructure and specialized operators.
- Inductively Coupled Plasma Mass Spectrometry:Multi-element detection at parts-per-trillion sensitivity enables simultaneous quantification of arsenic, cadmium, lead, and mercury in complex pharmaceutical matrices. Demand clusters in Basel and Frankfurt manufacturing corridors where ICH Q3D compliance mandates ultra-trace capability. Helium-dependent plasma generation creates supply chain exposure concentrated in Qatar and United States sources.
- Atomic Absorption Spectroscopy:Flame and graphite furnace configurations dominate routine environmental monitoring where single-element analysis suffices. Water utilities in Germany and municipal labs across France standardize on AAS for lead and cadmium screening in drinking water distribution networks. Lower capital barriers sustain deployment in smaller contract laboratories lacking ICP-MS infrastructure.
- X-Ray Fluorescence:Non-destructive elemental screening suits mining assay and industrial alloy verification without sample preparation.
- Total Reflection X-Ray Fluorescence:Ultra-low sample volume requirements serve semiconductor wafer contamination analysis and trace residue quantification in high-purity chemicals.
Leading the category by volume: Atomic Absorption Spectroscopy. Expanding most quickly: Inductively Coupled Plasma Mass Spectrometry.
End User:
Cost tier separation distinguishes centralized pharmaceutical outsourcing from decentralized food manufacturer in-house screening.
- Pharmaceutical Companies:ICH Q3D elemental impurity risk assessments mandate validated methods with documented detection limits for all new drug submissions. Quality control budgets are compressing testing timelines while elevating precision requirements. CDSCO alignment in India and NMPA harmonization in China extend compliant infrastructure demand across manufacturing clusters in Hyderabad and Shanghai.
- Environmental Testing Labs:Eurofins and SGS networks capture recurring compliance contracts through pan-European coverage and integrated certification bundles. Soil remediation and industrial discharge monitoring generate predictable revenue streams tied to regulatory inspection cycles. Method validation complexity for biological matrices strains analytical chemistry staffing across Basel and Boston clusters.
- Food and Beverage Manufacturers:Import screening protocols and processed food supply chain audits intensify testing touchpoints for packaged goods entering United States and European Union markets.
- Mining Industries:Exploration assay and process control applications favor portable XRF units enabling field-based screening without centralized laboratory logistics.
Highest spend per test: Pharmaceutical Companies. Steepest volume expansion: Food and Beverage Manufacturers.
Application:
Geography shapes method preference, with water-stressed regions prioritizing contamination monitoring over material analysis.
- Food Safety Testing:FDA Total Diet Study and import alert systems enforce action levels for lead, cadmium, and arsenic in dietary supplements and packaged imports. Processed food supply chain audits multiply testing touchpoints across major economies. FSSAI in India and SAMR in China align domestic protocols with Codex Alimentarius standards, harmonizing demand for compliant screening infrastructure.
- Water Quality Assessment:EPA Safe Drinking Water Act mandates and European Drinking Water Directive drive recurring monitoring of distribution networks and source protection zones. Municipal utilities standardize on AAS and ICP-MS platforms depending on analyte panel breadth and capital availability. Emerging per- and polyfluoroalkyl substance regulations may extend testing portfolios beyond traditional metallic contaminants.
- Soil Testing:Agricultural land classification and brownfield remediation require standardized extraction protocols for bioavailable metal fractions.
- Material Analysis:Industrial alloy verification and electronics manufacturing quality control employ XRF for rapid non-destructive screening.
Widest method diversity: Food Safety Testing. Tightest regulatory specification: Water Quality Assessment.
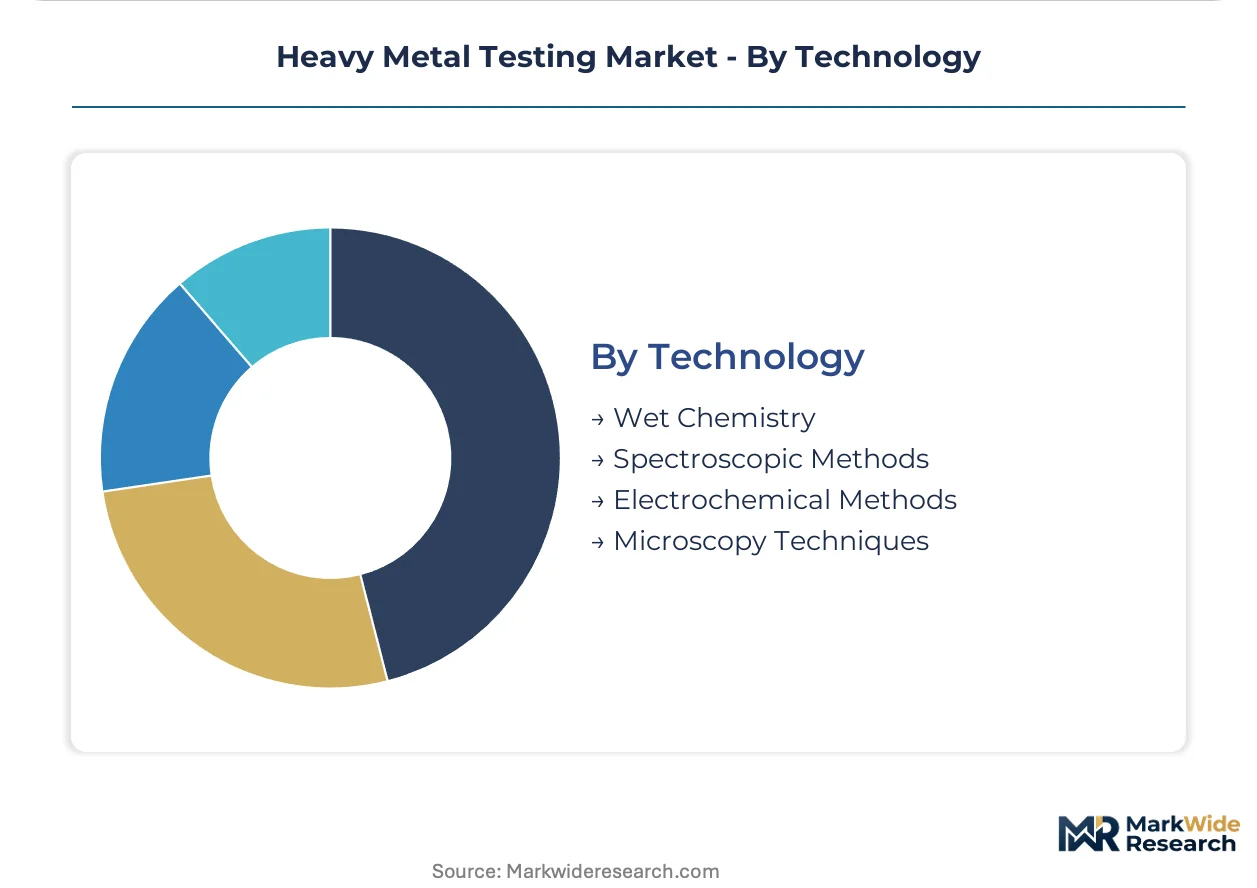
Technology:
Maturity gradient separates century-old wet chemistry from emerging automation platforms reducing headcount per test.
- Spectroscopic Methods:Atomic absorption, ICP-MS, and X-ray fluorescence consolidate as reference methods across pharmaceutical, environmental, and food compliance frameworks. Laboratory information management systems now integrate directly with chromatography and spectrometry platforms, compressing turnaround times while elevating data integrity requirements. Triple quadrupole ICP-MS configurations displace single-quadrupole systems for ultra-trace analysis in cell therapy extractable and leachable studies.
- Wet Chemistry:Colorimetric and gravimetric techniques persist in resource-constrained settings and for standardized regulatory methods lacking instrumental alternatives. Cold vapor atomic absorption for mercury and hydride generation for arsenic retain method-specific regulatory acceptance despite automation disadvantages.
- Electrochemical Methods:Anodic stripping voltammetry offers portable field deployment for heavy metal screening in environmental monitoring and occupational hygiene applications.
- Microscopy Techniques:Electron probe microanalysis and laser ablation ICP-MS enable spatially resolved elemental mapping for forensic and materials science investigations.
Dominant revenue share: Spectroscopic Methods. Gaining share fastest: Electrochemical Methods in portable configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Helium supply concentration in Qatar and the United States anchors geographic deployment of advanced ICP-MS infrastructure. Testing demand clusters around pharmaceutical manufacturing corridors and environmental compliance jurisdictions with stringent elemental impurity mandates.
United States
FDA enforcement through Total Diet Study action levels and import alert systems drives food safety screening volumes. EPA Safe Drinking Water Act mandates sustain municipal utility testing contracts across distribution networks. Boston and Research Triangle Park clusters concentrate mass spectrometry expertise serving pharmaceutical extractable and leachable studies.
Germany
Industrial chemical clusters around BASF and Bayer affiliates generate integrated compliance purchasing for environmental and pharmaceutical testing. EMA ICH Q3D guidelines enforce elemental impurity risk assessments for all new drug applications. Frankfurt and Basel manufacturing corridors concentrate contract laboratory capacity for ultra-trace analysis.
China
NMPA and SAMR alignment with ICH Q3D standards eliminates redundant testing protocols for multinational drug submissions. Domestic API manufacturing scaling in Hyderabad and Shanghai drives compliant infrastructure investment. Suzhou contract laboratories upgrade ICP-MS capacity to capture outsourcing from international sponsors.
India
CDSCO harmonization with ICH Q3D creates compliant testing demand as domestic pharmaceutical production expands. FSSAI alignment with Codex Alimentarius standards intensifies food import screening at major ports. Hyderabad and Mumbai manufacturing clusters drive contract laboratory spending for elemental impurity screening.
Switzerland
Swissmedic pharmaceutical oversight maintains stringent elemental impurity standards aligned with EMA guidelines. Basel manufacturing corridor anchors European demand for triple quadrupole ICP-MS reference methods. Specialized contract laboratories serve cell therapy and large molecule manufacturers requiring extractable and leachable validation.
Heavy Metal Testing Market Vendor Landscape
Strategic partnerships dominate the current landscape as contract laboratories bundle testing and certification services to reduce client procurement overhead. The vendor base concentrates around pan-regional networks capable of multi-jurisdiction compliance certification. Three archetypes occupy distinct positions: integrated testing-certification conglomerates, specialized pharmaceutical analytical services providers, and environmental compliance laboratories with recurring inspection-cycle contracts. M&A activity and geographic network expansion represent the primary competitive vectors as manufacturers consolidate approved vendor lists.
Within the integrated testing tier, Eurofins Scientific SE, SGS S.A., and Bureau Veritas SA exemplify the scale-driven archetype. Eurofins leverages its pan-European laboratory footprint to capture recurring environmental compliance contracts. SGS anchors its market position through bundled testing and certification offerings that streamline client procurement processes. Bureau Veritas occupies a specialized niche serving marine and industrial sectors where regulatory inspection cycles generate predictable revenue streams. These three entities represent the consolidation pressure reshaping competitive positioning as pharmaceutical and food manufacturers reduce supplier counts.
| Leading Market Players |
|---|
| Merck KGaA |
| TÜV SÜD AG |
| Eurofins Scientific SE |
| LGC Limited |
| Bureau Veritas SA |
| SGS S.A. |
| ALS Limited |
| Mérieux NutriSciences Corporation |
| Intertek Group PLC |
| Others |
Supply Flow & Price Mechanics
Large pharmaceutical manufacturers consolidating approved vendor lists command project-based pricing with bundled compliance certification, while smaller food producers face transactional per-sample rates that compress margins for standalone contract laboratories. This buyer-tier concentration creates divergent pricing power across ICP-MS capacity holders and routine screening providers.
Pricing Analysis
Extended warranty and validation support packages differentiate premium-tier ICP-MS contracts from unbundled instrument-only transactions. Three-tier pricing structure across premium, standard, and economy levels separates full-service method development from basic equipment lease arrangements. Cost compression in economy-tier atomic absorption services is intensifying because smaller environmental laboratories compete for municipal water utility contracts. Pharmaceutical quality control departments exhibit lowest price sensitivity due to ICH Q3D compliance mandates, while food import screening operations at ports demonstrate highest sensitivity to per-test costs.
Supply Chain Analysis
Mass spectrometry engineering talent pools in Boston, Basel, and Frankfurt anchor manufacturing decisions for precision instrument assembly. Germany, United States, and Japan concentrate production of ICP-MS optical components and quadrupole mass analyzers. Helium gas supply draws from Qatar and United States extraction facilities, creating single-source vulnerability for plasma generation requirements. Distribution runs through pan-regional laboratory networks rather than direct manufacturer-to-end-user channels, with Eurofins and SGS maintaining captive logistics for instrument deployment and service.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Inductively coupled plasma mass spectrometry is displacing legacy atomic absorption platforms across pharmaceutical quality control workflows, compressing the window for method-transition investment. Laboratories still operating single-element flame AAS face accelerated obsolescence as ICH Q3D mandates demand multi-element detection capabilities.
For Market Incumbents: Deploy certification bundling as the primary lever to defend against price erosion in routine environmental testing. Integrate ISO 17025 and GLP compliance documentation into standard service agreements to elevate switching costs for pharmaceutical clients. Add dedicated ICP-MS capacity in Hyderabad and Shanghai manufacturing corridors before CDSCO and NMPA alignment fully matures, preempting domestic competitor scale-up. For New Entrants and Emerging Players: Portable XRF distributors represent the most accessible channel partnership for field-based environmental remediation contracts. White-space concentration in handheld screening for mining assay and soil contamination assessment offers lower capital barriers than centralized laboratory competition. Target food safety testing at Indian and Chinese port authorities where FSSAI and SAMR import screening intensification outpaces established laboratory capacity. For Investors and Strategic Acquirers: The window for entry favors contract laboratory networks with existing multi-jurisdiction certification infrastructure and established pharmaceutical client relationships. Mid-cap European environmental testing platforms with recurring municipal utility contracts offer defensive cash flow profiles through regulatory inspection cycles. Monitor helium supply contract renegotiation announcements as inflection indicators for ICP-MS operating cost volatility and margin compression risk.| Strategic Initiative | Industry Significance |
|---|---|
| Triple Quadrupole ICP-MS Platform Deployment | Consolidates multi-instrument workflows for cell therapy extractable and leachable studies at Basel manufacturers. |
| Helium Supply Contract Diversification | Reduces plasma gas cost volatility exposure concentrated in Qatar and United States extraction sources. |
| Portable XRF Channel Partnership | Opens field-based mining assay and environmental remediation channels outside centralized laboratory networks. |
| Multi-Jurisdiction Certification Bundling | Streamlines pharmaceutical client procurement overhead across ISO 17025, GLP, and national GMP requirements. |
| PFAS Testing Portfolio Extension | Extends analytical service menus beyond metallic contaminants under emerging European Union and United States regulations. |
Methodological Framework
SEC 10-K filings, EMA regulatory submissions, and customs trade data formed the secondary backbone for instrument shipment and laboratory capacity estimation. Primary interviews with ICP-MS platform engineers, pharmaceutical quality control directors, contract laboratory procurement managers, and environmental compliance officers validated secondary findings. Bottom-up triangulation across installed instrument base and top-down cross-check against contract laboratory revenue disclosures ensured segmentation consistency.
Bottom-up modeling of ICP-MS, atomic absorption, and X-ray fluorescence unit placements across pharmaceutical, environmental, food safety, and mining applications drove volume projections. Segmentation dimensions included product type, end-user vertical, application protocol, and technology platform across the analysis window. CAGR derivation incorporated regulatory implementation timelines for ICH Q3D alignment in India and China, helium supply cost trajectories, and pharmaceutical manufacturing cluster expansion rates.
Caveats apply where helium supply disruption, accelerated PFAS regulatory expansion, or pharmaceutical vendor consolidation beyond modeled rates could materially shift the outlook. Forecasts reflect assumptions about regulatory harmonization pace and instrument replacement cycles without guaranteed realization. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Adhesive Tester Market
Testing Equipment
Laboratory Mixer Market
Testing Equipment
Automated Solid Phase Extraction Systems Market
Testing Equipment
Material Tester Market
Testing Equipment
Next-Generation Titrators Market
Testing Equipment
Chemical Reaction Monitoring Equipment Market
Testing Equipment
North America Dissolved Gas Analyzer Market
Testing Equipment
Chloride Reagents Kits Market
Testing Equipment
Hydrocarbon Tester Market
Testing Equipment
Durometers Market
Testing Equipment
Melting Point Apparatus Market
Testing Equipment
Analytical Gel Permeation Chromatography Market
Testing Equipment
Global Online Coal Ash Analyzers Market
Testing Equipment
Glass Testing Instruments Market
Testing Equipment
Brittleness Tester Market
Testing Equipment
Clean-Up Gel Permeation Chromatography Market