
 CHS (Carbon Hydrogen Sulfur) Analyzers Market | 2026-2036
CHS (Carbon Hydrogen Sulfur) Analyzers Market Size, Share, and Industry Trends Forecast 2026-2036
CHS (Carbon Hydrogen Sulfur) Analyzers Market Insights
The gap between laboratory-grade precision and field-portable economy is repositioning how vendors structure their product lines. Thermo Fisher Scientific leverages its combustion technology heritage to dominate high-throughput refinery installations. PerkinElmer anchors its position through specialized infrared detection modules for sulfur speciation. Horiba competes aggressively in the Asian environmental compliance segment with localized service networks.
CHS analyzers are elemental analysis instruments that quantify carbon, hydrogen, and sulfur content in organic and inorganic samples through high-temperature combustion followed by infrared or thermal conductivity detection, with detection thresholds typically reaching parts-per-million sensitivity for sulfur. These systems serve critical quality control functions in petroleum refining, where sulfur content directly determines product grade and regulatory compliance. Laboratory analyzers occupy the largest revenue pool due to their precision and throughput advantages in central testing facilities, while portable analyzers represent the fastest-expanding category as field-based screening protocols expand across pipeline networks and remote production sites. Online analyzers sustain steady demand from continuous process monitoring in chemical manufacturing, though their narrower customization scope limits margin expansion relative to configurable benchtop units.
EPA Tier 3 gasoline sulfur regulations and the EU F-Gas Regulation shape analyzer demand by mandating tighter measurement tolerances and certified calibration protocols for emissions verification. Japan's METI enforces comparable precision standards through JIS-certified reference methods, creating a tripartite compliance architecture across North America, Europe, and East Asia. Stakeholders must monitor how evolving carbon border adjustment mechanisms redefine traceability requirements for cross-border fuel certification.
Market Dynamics
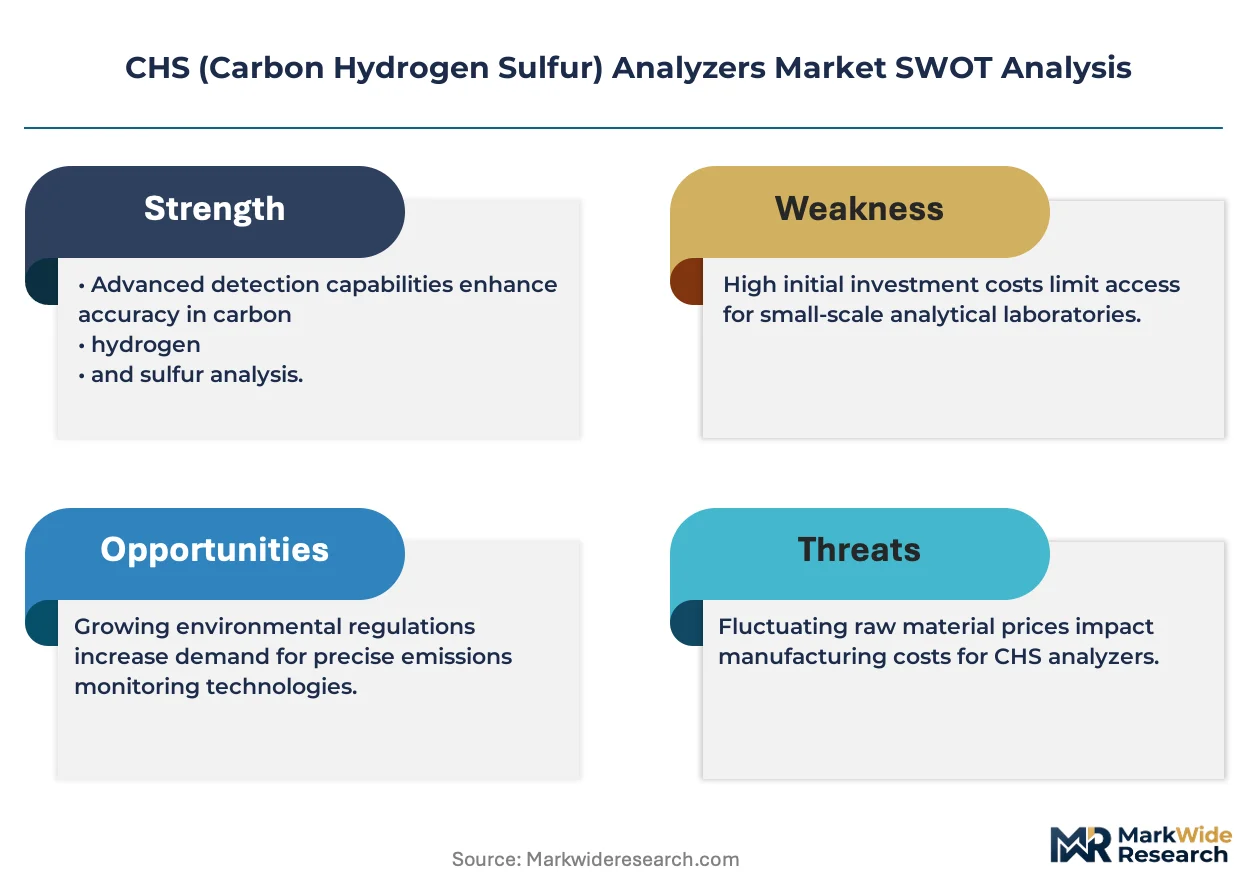
EPA Tier 3 sulfur mandates and the EU F-Gas Regulation are compressing detection tolerance thresholds, forcing analyzer vendors to recalibrate combustion and infrared architectures for sub-10 ppm precision in refinery and environmental monitoring applications.
Growth Catalysts
- EPA Tier 3 gasoline standards:US refineries must verify sulfur content below 10 ppm, sustaining replacement demand for high-precision combustion analyzers in Gulf Coast processing facilities.
- Carbon border adjustment mechanisms:Cross-border fuel certification in the EU requires traceable sulfur documentation, expanding analyzer deployment at import terminals and blending facilities.
- Shale oil processing intensity:Variable sulfur content in domestic crude streams drives continuous monitoring investments at US midstream storage and pipeline injection points.
Market Restraints
- Platinum catalyst cost volatility:Combustion analyzer consumables depend on platinum-group metals, exposing OEM margins to London Metal Exchange price swings.
- Detector supply concentration:Thermal conductivity and infrared detector manufacturing clusters in Germany and Japan create single-source vulnerability for tier-two analyzer assemblers.
- Calibration gas scarcity:Certified reference materials with traceable sulfur concentrations face production bottlenecks at national metrology institutes.
Strategic Opportunities
- India refining expansion:Reliance Industries and Indian Oil Corporation are building world-scale complexes requiring analyzer fleets for Euro-VI-equivalent diesel production.
- Biomass sulfur characterization:Biofuel certification protocols need CHS analyzers adapted for oxygen-rich matrices, opening application engineering contracts.
- Digital twin integration:Analyzer data feeds into refinery simulation platforms, creating recurring software revenue streams beyond hardware sales.
Industry Challenges
- Combustion method specialist scarcity:Technicians trained in high-temperature oxidation chemistry and infrared spectroscopy command premium wages in Houston and Rotterdam.
- Multi-standard certification complexity:Simultaneous EPA, EU F-Gas, and JIS compliance extends product validation timelines by 8-14 months.
- Legacy DCS integration friction:Analyzer output protocols must map to decades-old distributed control systems at established refineries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CHS (Carbon Hydrogen Sulfur) Analyzers Market |
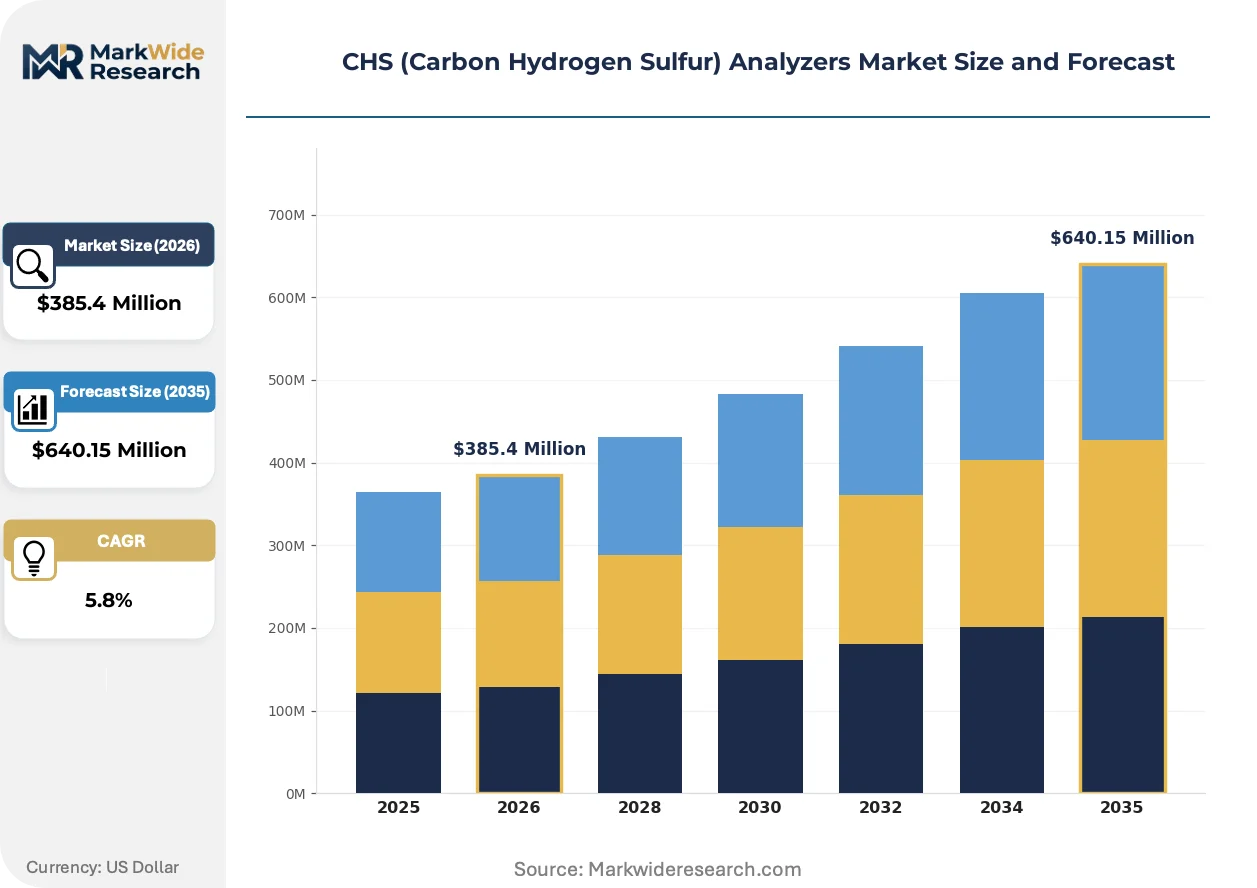
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laboratory Analyzers, Portable Analyzers, Online Analyzers, Benchtop Analyzers End User: Petroleum Refineries, Chemical Manufacturing, Environmental Testing, Academic Institutions Technology: Combustion, Infrared, Gravimetric, Flash Method Application: Quality Control, Research & Development, Compliance Testing, Production Monitoring |
| Companies Covered | Thermo Fisher Scientific, PerkinElmer, Horiba, Elementar, Agilent Technologies, ELTRA, LECO Corporation, Bruker, Ajay, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CHS (Carbon Hydrogen Sulfur) Analyzers Market Trends and Innovations
Analyzer architectures are fragmenting between centralized laboratory precision and distributed field portability, with software-defined detection and service unbundling emerging as parallel vectors of vendor differentiation.
Microcombustion cell technology is modularizing. These miniaturized high-temperature oxidation chambers enable sulfur quantification in battery-powered handheld units. Pipeline operators in Alberta and Kazakhstan are deploying them for rapid field screening of crude batches. The shift is modularizing the traditional laboratory-to-field value chain, allowing decentralized testing networks to replace centralized lab queues.
REACH Annex XVII restrictions on fluorinated greenhouse gases are phasing out certain infrared detector coolants. European analyzer OEMs are redesigning thermal management systems to accommodate alternative refrigerants or solid-state cooling. Environmental monitoring agencies in Germany and the Netherlands are accelerating procurement of compliant systems ahead of 2027 deadlines.
Service contracts are unbundling from hardware sales. Refinery procurement teams in Texas and Singapore are negotiating calibration, maintenance, and data analytics as separate line items. This purchasing behavior is compressing upfront capital commitments while extending vendor revenue duration through multi-year consumable and service agreements.
CHS (Carbon Hydrogen Sulfur) Analyzers Market Segmentation
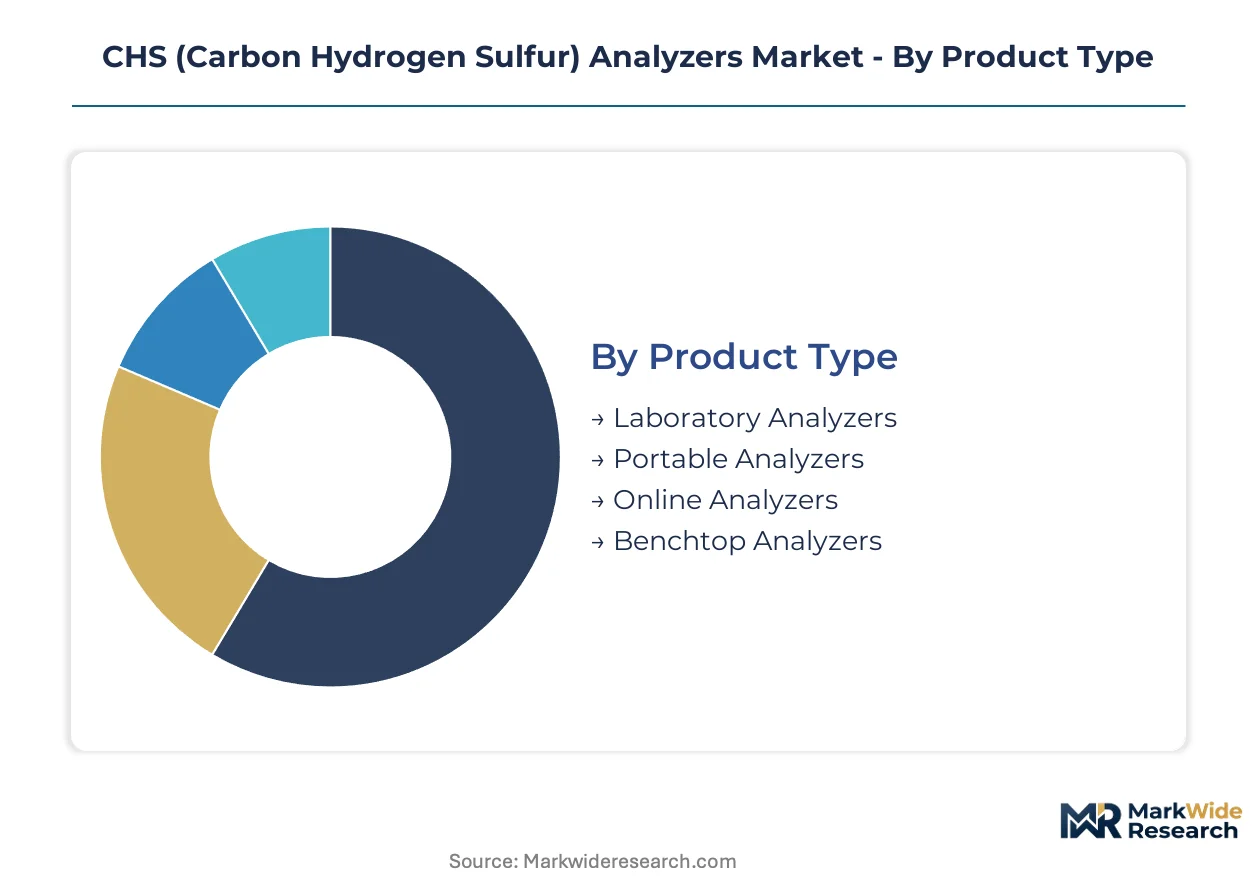
CHS analyzer procurement patterns diverge sharply between precision-critical laboratory installations and field-deployable screening units. Vendors structure product architectures around four distinct technical axes that reshape competitive positioning.
Product Type:
Detection sensitivity and throughput specifications determine capital allocation across installation environments.
- Laboratory Analyzers:These systems achieve parts-per-million sulfur detection through high-temperature combustion coupled with infrared or thermal conductivity detection. Gulf Coast petroleum refineries in Texas and Louisiana deploy centralized laboratory fleets to verify EPA Tier 3 compliance across gasoline and diesel streams, with procurement concentrated in facilities processing over 250,000 barrels per day.
- Portable Analyzers:Battery-powered microcombustion cells enable rapid field screening without sample transport delays. Pipeline operators across Alberta's oil sands and Kazakhstan's CPC pipeline network are expanding deployment for crude batch verification at remote injection points, driven by variable sulfur content in blended feedstocks.
- Online Analyzers:Continuous process monitoring systems integrate directly into refinery distributed control systems for real-time sulfur tracking.
- Benchtop Analyzers:Configurable units bridge laboratory precision with moderate throughput for mid-scale testing facilities.
Mature deployment sits with laboratory analyzers. Newer deployment is concentrated in portable analyzers.
End User:
Regulatory stringency and batch variability create divergent procurement rhythms across customer categories.
- Petroleum Refineries:These facilities operate the largest installed base, with sulfur content verification mandated at every production stage from crude receipt to finished product certification. US refineries under EPA Tier 3 and EU facilities under F-Gas Regulation drive replacement cycles for sub-10 ppm detection capability.
- Chemical Manufacturing:Continuous process monitoring demands sustain steady analyzer procurement for feedstock quality verification and catalyst protection. German chemical complexes along the Rhine corridor represent concentrated demand for infrared-based systems with rapid cycle times.
- Environmental Testing:Commercial laboratories serving regulatory compliance testing require certified calibration protocols and traceable reference materials.
- Academic Institutions:Research-focused procurement emphasizes configurability and method development flexibility over throughput.
Revenue concentration favors petroleum refineries. Procurement expansion is accelerating in environmental testing laboratories.
Technology:
Detection chemistry and thermal management architectures define performance boundaries and maintenance economics.
- Combustion:High-temperature oxidation at 1,350°C converts sulfur to sulfur dioxide for infrared or thermal conductivity quantification. This method dominates refinery installations in Japan under METI-certified JIS reference protocols, where precision requirements exceed alternative techniques.
- Infrared:Non-dispersive infrared detection enables rapid sulfur speciation without combustion consumables. PerkinElmer and European OEMs concentrate development here for environmental monitoring applications facing REACH Annex XVII coolant restrictions.
- Gravimetric:Classical precipitation methods persist in national metrology institutes for certified reference material production.
- Flash Method:Rapid pyrolysis techniques serve specialized applications in polymer and biomass sulfur characterization.
Combustion retains the largest installed base. Infrared is gaining share fastest in environmental compliance segments.
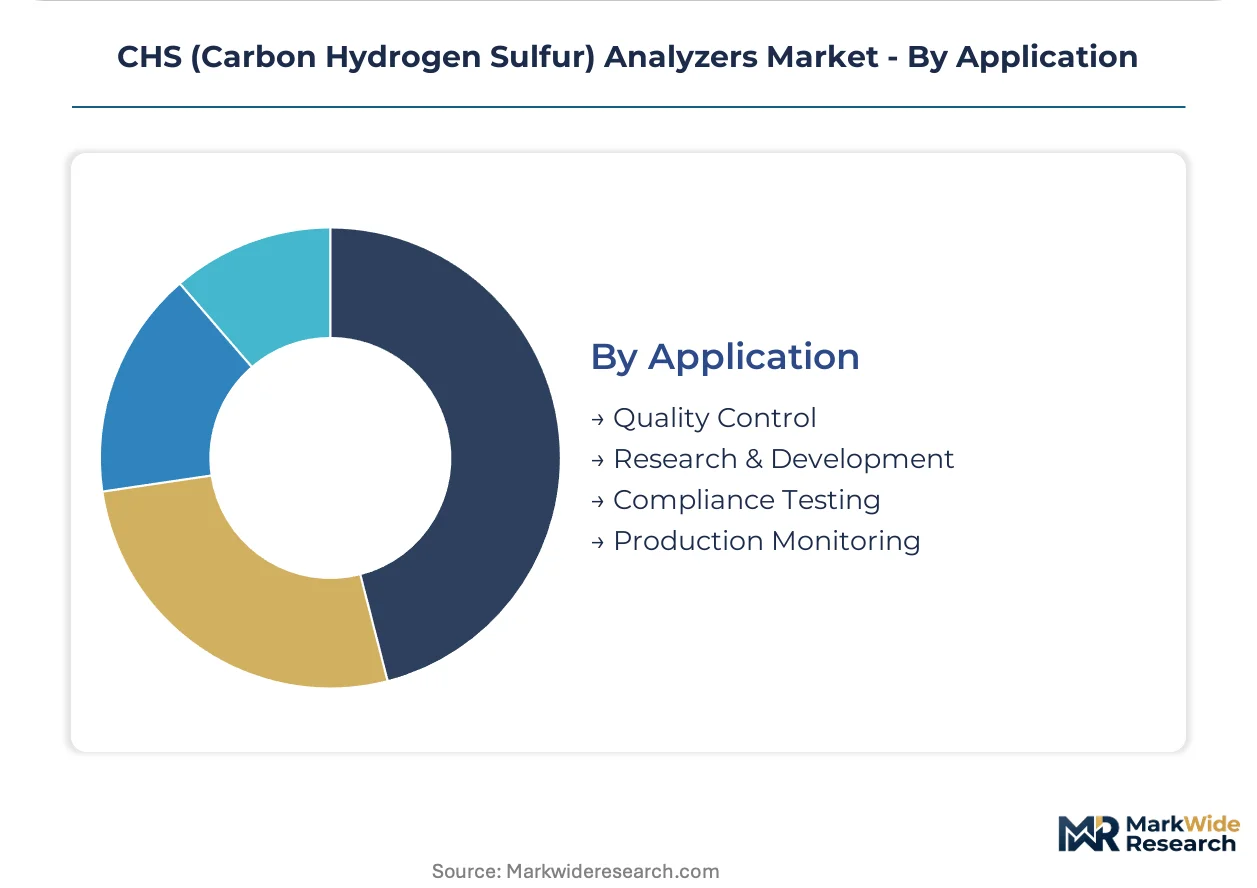
Application:
Testing frequency and documentation requirements segment demand by operational criticality.
- Quality Control:High-throughput verification at production scale demands automated sample handling and direct LIMS integration. Refinery laboratories in Singapore and Rotterdam operate round-the-clock quality control protocols with sub-5 ppm detection thresholds for bunker fuel certification.
- Research & Development:Method development and new matrix characterization require configurable combustion parameters and alternative detection modes. Biomass sulfur characterization for biofuel certification protocols is emerging as a specialized R&D application in Nordic research institutes.
- Compliance Testing:Regulatory verification demands certified calibration traceability and audit-ready documentation.
- Production Monitoring:Continuous analyzer integration into process control loops enables real-time sulfur adjustment.
Quality control commands the largest capital allocation. Research and development shows the steepest expansion trajectory in alternative fuel characterization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston anchors the largest concentration of CHS analyzer deployment, with Gulf Coast petroleum refineries operating centralized laboratory fleets to verify EPA Tier 3 sulfur compliance across gasoline and diesel streams.
United States
EPA Tier 3 mandates drive replacement cycles for sub-10 ppm detection capability at Gulf Coast refineries. Shale oil variability sustains continuous monitoring investments at midstream storage terminals. Texas and Louisiana facilities processing over 250,000 barrels per day dominate procurement volume.
Germany
Rhine corridor chemical complexes sustain concentrated demand for infrared-based systems with rapid cycle times. REACH Annex XVII restrictions on fluorinated greenhouse gases accelerate procurement of redesigned thermal management systems ahead of 2027 deadlines. Environmental monitoring agencies in the Netherlands and Germany lead compliant system adoption.
Japan
METI-enforced JIS-certified reference methods create precision requirements exceeding alternative techniques. Combustion-based systems dominate refinery installations under these protocols. Nagoya and Osaka industrial clusters maintain steady replacement demand for high-throughput laboratory analyzers.
India
Reliance Industries and Indian Oil Corporation are building world-scale refining complexes requiring analyzer fleets for Euro-VI-equivalent diesel production. The country's national petroleum regulator mandates tighter sulfur documentation for import terminals. Gujarat and Maharashtra coastal refining zones concentrate new procurement.
Singapore
Bunker fuel certification for maritime compliance drives round-the-clock quality control protocols with sub-5 ppm detection thresholds. The port city serves as regional calibration hub for Southeast Asian analyzer networks. Jurong Island petrochemical complexes sustain premium-tier equipment demand.
CHS (Carbon Hydrogen Sulfur) Analyzers Market Competitive Landscape
Premium-margin players sit above commodity-margin players across detection precision and service bundling dimensions. The vendor base organizes into three tiers: combustion technology specialists with refinery heritage, infrared detection module providers for environmental segments, and regional assemblers serving price-sensitive procurement. Consolidation pressure concentrates among mid-scale participants facing detector supply bottlenecks. Dominant competitive moves include strategic partnerships for localized service networks and portfolio diversification into portable microcombustion architectures.
Within the technology heritage tier, Thermo Fisher Scientific and PerkinElmer exemplify divergent specialization strategies. Thermo Fisher leverages its combustion technology lineage to anchor high-throughput refinery installations, while PerkinElmer occupies a position centered on infrared detection modules for sulfur speciation. Horiba represents the regional service network archetype, with its geographic naming signaling Japanese origin and environmental compliance focus. These three entities collectively illustrate how vendor positioning fragments across detection chemistry, geographic service density, and end-use application.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| PerkinElmer |
| Horiba |
| Elementar |
| Agilent Technologies |
| ELTRA |
| LECO Corporation |
| Bruker |
| Ajay |
| Others |
Pricing and Supply Chain Analysis
Refinery procurement teams in Texas and Singapore unbundling service contracts from hardware purchases are forcing analyzer vendors to restructure revenue models around recurring calibration and consumable streams rather than upfront capital premiums. This shift compresses initial equipment margins while extending customer lifetime value through multi-year service agreements.
Pricing Analysis
Outcome-based pricing tied to detection uptime and calibration certification accuracy anchors premium tiers in refinery installations. Three-tier pricing structure across premium, standard, and economy levels separates EPA Tier 3-compliant systems with JIS traceability from mid-tier environmental monitoring units and basic laboratory configurations. Cost compression in the economy tier is intensifying because regional assemblers in India and Southeast Asia source non-certified detector modules from secondary suppliers. Petroleum refineries demonstrate the lowest price sensitivity due to regulatory non-compliance penalties, while academic institutions and small environmental testing laboratories exhibit the highest sensitivity to capital expenditure thresholds.
Supply Chain Analysis
Specialized technician scarcity in high-temperature oxidation chemistry across Germany and Japan constrains manufacturing scale-up for precision combustion cells. Detector manufacturing concentrates in Germany and Japan, with platinum-group metal consumables drawing from South African and Russian mining operations. Single-source vulnerability persists for thermal conductivity detector substrates sourced from specialized Japanese ceramics producers. Distribution runs through authorized service networks rather than direct OEM sales, with regional calibration hubs in Houston, Rotterdam, and Singapore managing downstream logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as vendors pursue captive production of platinum-group metal catalysts to insulate margins from London Metal Exchange volatility.
For Market Incumbents: To counter detector supply bottlenecks from German and Japanese ceramics specialists, Thermo Fisher and PerkinElmer should deepen backward integration into thermal conductivity substrate manufacturing and secure long-term offtake agreements with South African platinum refiners. Certification investment in simultaneous EPA, EU F-Gas, and JIS compliance protocols creates switching costs that protect installed base revenue. For New Entrants and Emerging Players: Begin with portable microcombustion architectures for pipeline field screening in Kazakhstan and Alberta, where incumbent service networks remain underdeveloped. Biomass sulfur characterization for biofuel certification protocols represents the most penetrable application white-space. A go-to-market angle anchored to battery-powered handheld units with localized calibration partnerships bypasses capital-intensive laboratory analyzer competition. For Investors and Strategic Acquirers: The window for entry favors mid-scale infrared detection module specialists with established European environmental agency relationships. Long-term viability hinges on software-defined detection capabilities and digital twin integration revenue streams. Watch for carbon border adjustment mechanism implementation timelines as the inflection signal triggering accelerated analyzer deployment at EU import terminals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Catalyst Production | Captive platinum-group metal supply insulates margins from LME price swings. |
| Multi-Standard Certification Investment | Simultaneous EPA, EU F-Gas, and JIS compliance extends product validation timelines but creates customer lock-in. |
| Portable Microcombustion Development | Battery-powered handheld units open field screening applications in remote pipeline networks. |
| Digital Twin Integration | Analyzer data feeds into refinery simulation platforms, creating recurring software revenue beyond hardware. |
| Regional Calibration Hub Expansion | Localized service networks in Singapore and Rotterdam reduce downtime penalties for maritime bunker fuel certification. |
Research Methodology
Document review covered EPA enforcement data, EU ECHA regulatory filings, and JIS standard documentation, complemented by interviews with refinery laboratory directors, environmental compliance officers at chemical manufacturers, and procurement leads at national petroleum regulators. Primary fieldwork included discussions with analyzer OEM technical sales teams and aftermarket service managers. Secondary validation drew from customs trade records for analyzer imports, SEC 10-K disclosures from listed instrument manufacturers, and national metrology institute calibration certification databases. Bottom-up unit shipment estimates triangulated against top-down refinery capital expenditure tracking.
Segment-level revenue outputs across the projection horizon reflect modeled deployment rates by analyzer type, technology chemistry, and end-use vertical. The analytical framework incorporated petroleum refining throughput capacity additions, chemical manufacturing process control upgrade cycles, and environmental monitoring agency procurement budgets. CAGRs were derived from regression analysis of historical replacement demand patterns and regulatory mandate implementation schedules. Industry-specific inputs included EPA Tier 3 compliance deadline phasing and REACH Annex XVII coolant restriction timelines.
Underlying measurement precision varies by segment; laboratory analyzers with certified reference material traceability carry tighter precision than portable field-screening units. Forecasts reflect assumptions around platinum price stability, detector manufacturing capacity expansion, and regulatory enforcement continuity. Material deviation in carbon border adjustment mechanism adoption rates or JIS standard revision schedules warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Chemical Reaction Monitoring Equipment Market
Testing Equipment
Total Reflection X Ray Fluorescence (TXRF) Spectrometer Market
Testing Equipment
Cone Calorimeter Market
Testing Equipment
Steel Testing Equipment Market
Testing Equipment
Flammability Tester Market
Testing Equipment
Hydrogen Peroxide Measurement Market
Testing Equipment
Ultrasonic Testing Market
Testing Equipment
Paper Moisture Meter Market
Testing Equipment
Mud Sediment Tester Market
Testing Equipment
Pellistor Bead Chemical Sensor Market
Testing Equipment
Global Circular Dichroism (CD) Spectrometers Market
Testing Equipment
Hydrometer Market
Testing Equipment
Material Testing Market
Testing Equipment
Benchtop Density Meter for Solids Market
Testing Equipment
Gas Calorimeter Market
Testing Equipment
Global Silica Analyzer Market