
 Global Isononanoic Acid Market | 2026-2036
Global Isononanoic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Global Isononanoic Acid Market Foresight
German oxo-chemical producers is expanding isononanoic acid capacity to serve European synthetic ester demand. BASF SE leverages backward integration into C4 feedstock streams to secure margin control. Evonik Industries AG specializes in high-purity grades for personal care and lubricant additive applications. OQ Chemicals GmbH anchors supply reliability through its integrated oxo-alcohol platform.
Isononanoic acid is a branched C9 carboxylic acid produced via oxo-synthesis of octenes, typically exhibiting a purity threshold above 99% for cosmetic and food-grade certifications. It functions primarily as a precursor for synthetic esters used in lubricants, plasticizers, and surfactant systems. Technical grade material dominates volume flows into plasticizer and lubricant additive channels, where cost efficiency outweighs certification overhead. Cosmetic grade commands premium positioning within personal care formulations, reflecting tighter impurity limits and specialized handling protocols.
EPA industrial chemical regulations in the United States and REACH registration requirements in Europe constrain market access for uncertified producers, elevating compliance costs. China's MEE environmental standards and GB quality specifications shape import eligibility and domestic production licensing. Manufacturers must monitor regulatory divergence between jurisdictions to optimize grade-mix strategies and avoid stranded inventory positions.
Market Dynamics
Synthetic ester demand from Germany's automotive sector and China's eastern chemical corridor is compressing supply chains, forcing producers to secure captive C4 feedstock positions and accelerate high-purity grade certification timelines.
Growth Catalysts
- REACH purity mandates:European lubricant formulators now require cosmetic-grade certification thresholds for industrial applications, expanding addressable premium volume.
- China's esterification buildout:Domestic capacity surges in Jiangsu and Zhejiang provinces are absorbing technical-grade flows and reducing import dependency.
- EPA industrial chemical standards:Tightening volatility and toxicity specifications in North America are disqualifying uncertified suppliers and consolidating qualified vendor pools.
Market Restraints
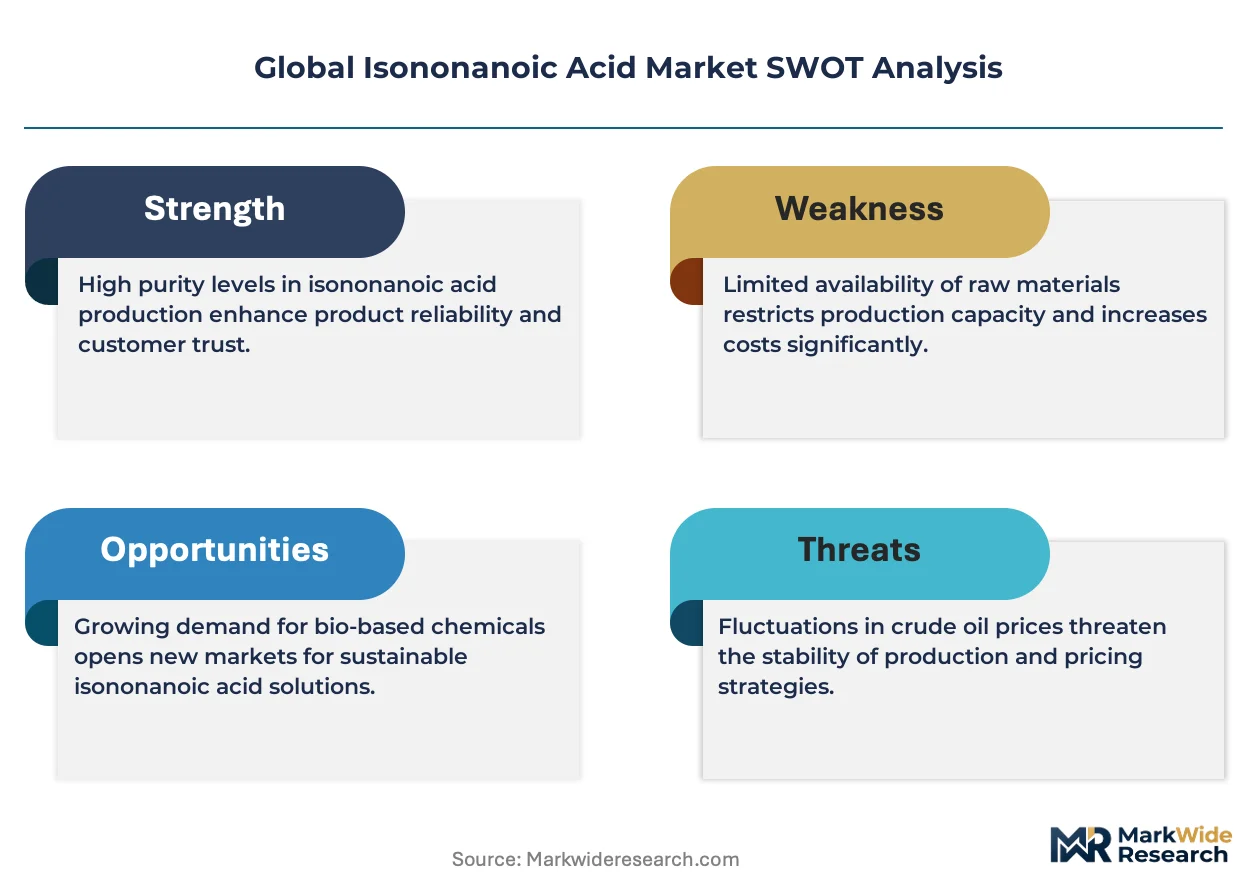
- Propylene oligomer volatility:C4 feedstock costs fluctuate with naphtha-cracking economics, squeezing oxo-synthesis margins without long-term supply contracts.
- German supply concentration:Three integrated oxo-chemical platforms control European high-purity output, creating single-source vulnerability for specialized ester producers.
- Biobased C9 acid substitution:Renewable fatty acid derivatives from palm kernel and coconut oil are penetrating cosmetic applications where carbon intensity disclosure matters.
Strategic Opportunities
- India's lubricant additive gap:Domestic synthetic ester production remains underdeveloped, creating first-mover positioning for certified acid suppliers.
- Japan's METI carbon neutrality roadmap:Fuel efficiency mandates for industrial machinery are accelerating demand for high-performance synthetic lubricants.
- Direct-to-compounder distribution:Bypassing traditional distributor networks in China's Yangtze River Delta reduces working capital cycles and improves specification control.
Industry Challenges
- REACH registration timelines:Full substance dossier completion for isononanoic acid derivatives extends 18-24 months, freezing product launch schedules.
- Legacy plasticizer integration:Substituting isononanoate esters for phthalate-based alternatives requires reformulation of PVC processing equipment and temperature profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Isononanoic Acid Market |
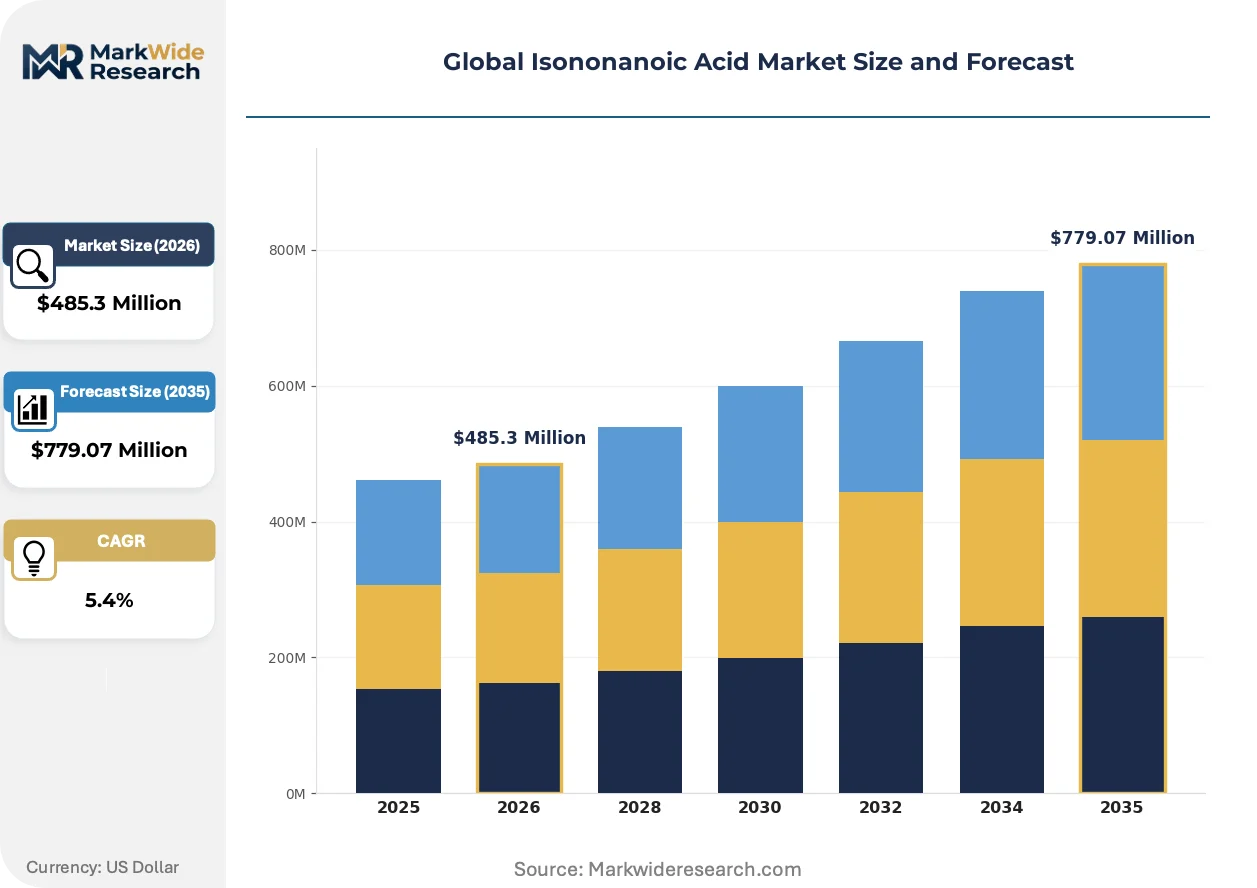
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $779.07 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Technical Grade, Food Grade, Cosmetic Grade, Industrial Grade Application: Plasticizers, Lubricant Additives, Surfactants, Corrosion Inhibitors, Adhesives End User Industry: Paint & Coatings, Personal Care, Chemical Manufacturing, Automotive Suppliers, Textile Treatment Packaging Type: Drums, Bulk Containers, Intermediate Bulk Containers, Totes |
| Companies Covered | OQ Chemicals GmbH, BASF SE, KH Neochem Co. Ltd., Evonik Industries AG, TotalEnergies, Croda International plc, Dow, INEOS, ExxonMobil, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Isononanoic Acid Market Shifts & Advancements
Process intensification in oxo-synthesis and regulatory pressure on carbon disclosure are reshaping how producers compete on specification breadth and supply chain transparency rather than unit economics alone.
Membrane separation technology for final-stage acid purification is electrifying the competitive landscape for cosmetic-grade material. Specialty chemical distributors in France and Switzerland are adopting these systems to bypass traditional distillation bottlenecks. The technology is compressing qualification timelines from 12 months to under 6 months for new supply relationships.
REACH's updated restriction roadmap for persistent organic pollutants is forcing reformulation across European personal care applications. Manufacturers must now document impurity profiles below 0.1% for specific branched isomers previously considered benign. German and Dutch formulators are accelerating supplier audits to preempt 2025 enforcement windows.
Specification-driven procurement contracts are displacing spot-market purchasing among North American synthetic lubricant blenders. Buyers now require certificate-of-analysis continuity across 24-month supply agreements rather than batch-level verification. This pattern is most pronounced in Pennsylvania and Ohio, where automotive OEM tier-one suppliers dominate volume allocation.
Global Isononanoic Acid Market Segmentation
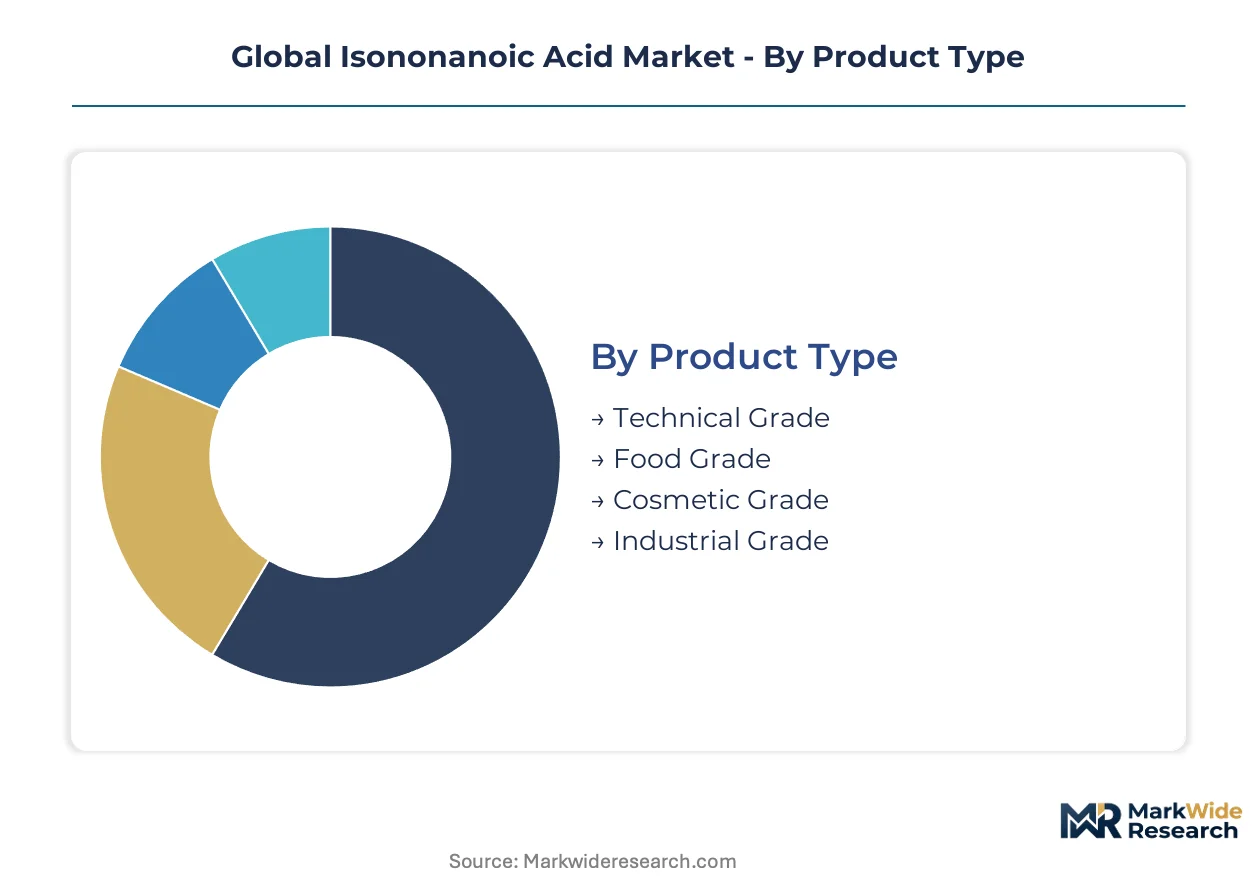
Specification tiers in isononanoic acid determine pricing power and regulatory compliance burden. Formulators select grades based on end-use certification requirements and supply chain reliability rather than unit cost alone.
Product Type:
Supply concentration among German oxo-chemical platforms favors integrated producers with captive C4 feedstock positions.
- Technical Grade:Material exhibiting 95-98% purity serves plasticizer and general lubricant additive channels. Demand concentrates in China's Jiangsu province esterification facilities, where domestic capacity expansion is absorbing regional flows and compressing import windows.
- Cosmetic Grade:Purity thresholds exceeding 99.5% with documented impurity profiles below 0.1% for specific branched isomers command premium positioning. REACH's updated persistent organic pollutant restrictions are forcing European personal care formulators to accelerate supplier audits and tighten qualification timelines.
- Food Grade:Certification under FDA and EFSA frameworks enables food packaging and processing equipment applications.
- Industrial Grade:Intermediate specification material serves corrosion inhibitor and adhesive precursor markets.
Technical grade absorbs the bulk of installed capacity; cosmetic grade is expanding most quickly.
Application:
Cost tier differentiation separates high-performance synthetic esters from commodity plasticizer replacements.
- Plasticizers:Isononanoate esters substitute for phthalate-based alternatives in flexible PVC applications. Legacy equipment reformulation requirements in European processing facilities are slowing substitution rates despite regulatory pressure.
- Lubricant Additives:Synthetic ester base stocks for automotive and industrial lubricants demand cosmetic-grade certification thresholds even for industrial applications. Japan's METI carbon neutrality roadmap is accelerating demand for high-performance synthetic lubricants in industrial machinery.
- Surfactants:Branched C9 acid precursors enable mild surfactant systems for personal care formulations.
- Corrosion Inhibitors:Metalworking fluid applications tolerate technical-grade material with broader isomer distribution.
- Adhesives:Pressure-sensitive and structural adhesive formulations utilize esterified derivatives for tack and flexibility control.
Plasticizers dominate current volume allocation; lubricant additives are climbing the fastest.
End User Industry:
Customer type fragmentation requires producers to maintain parallel certification dossiers for cosmetic, food-contact, and industrial channels.
- Automotive Suppliers:Synthetic lubricant blenders in Pennsylvania and Ohio now require certificate-of-analysis continuity across 24-month supply agreements. Specification-driven procurement contracts are displacing spot-market purchasing among North American tier-one suppliers.
- Personal Care:Formulators in France and Switzerland are adopting membrane separation technology to bypass traditional distillation bottlenecks and compress qualification timelines. REACH compliance documentation for branched isomer impurity profiles is becoming a non-negotiable entry requirement.
- Chemical Manufacturing:Domestic esterification capacity in China's Zhejiang province is reducing import dependency for technical-grade acid.
- Paint & Coatings:Coalescing agent and modifier applications favor cost-optimized technical-grade material.
- Textile Treatment:Softener and finishing agent formulations represent niche volume with specialized handling protocols.
Automotive suppliers absorb the bulk of high-purity output; personal care is gaining share fastest.
Packaging Type:
Volume scale determines packaging economics, with direct-to-compounder distribution in China's Yangtze River Delta reducing working capital cycles.
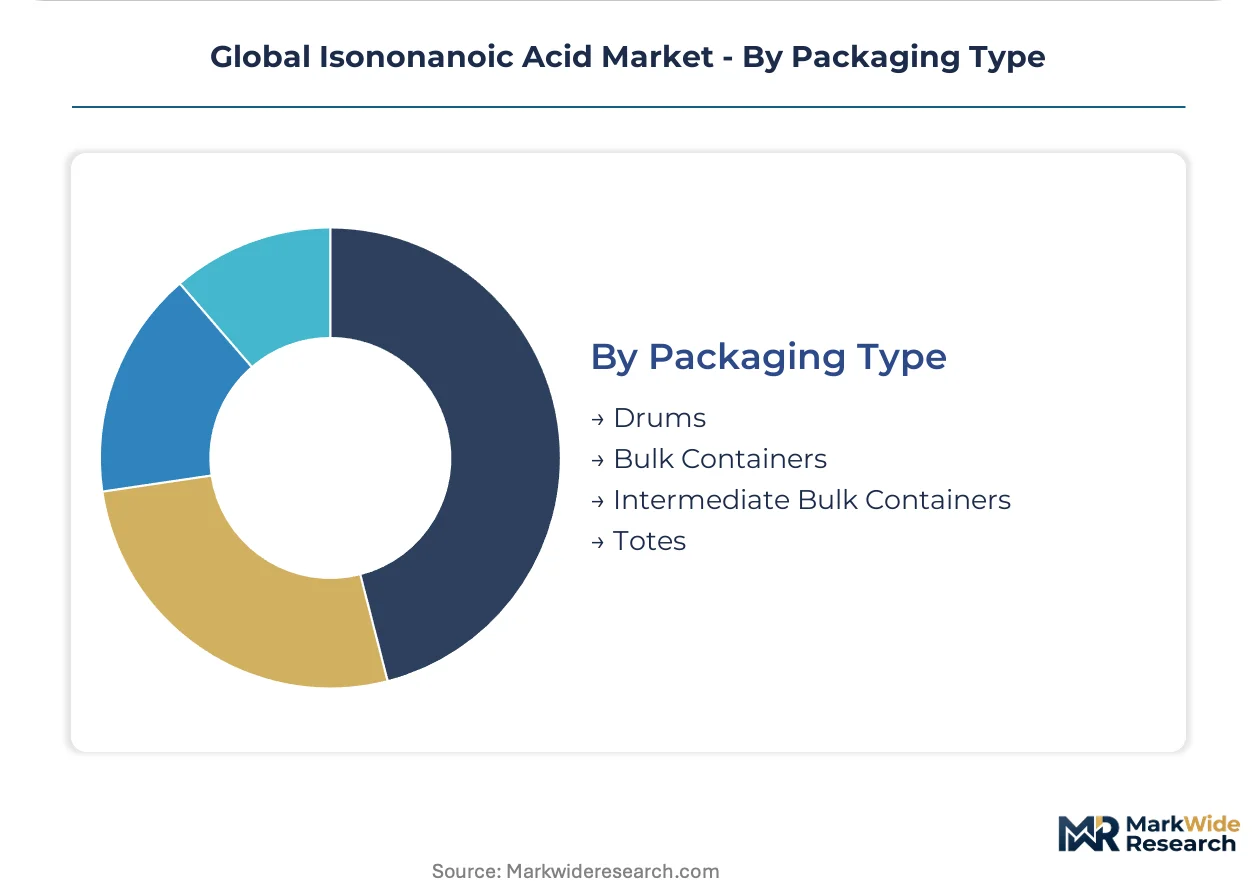
- Bulk Containers:Rail and vessel-scale shipments serve integrated esterification facilities with dedicated unloading infrastructure. Jiangsu and Zhejiang province chemical corridors favor bulk delivery to minimize handling costs.
- Intermediate Bulk Containers:Flexible intermediate bulk containers enable just-in-time delivery for mid-scale compounders without fixed storage tanks.
- Drums:Standard 200-liter steel drums serve specialty chemical distributors and small-batch formulators.
- Totes:Intermediate volume containment bridges drum-scale and bulk-scale economics for regional blenders.
Bulk containers absorb the bulk of seaborne trade; intermediate bulk containers are expanding most quickly in regional distribution networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
C4 feedstock availability in the US Gulf Coast and German Rhineland anchors isononanoic acid production economics. Demand dispersion across automotive lubricant hubs and personal care formulation centers creates distinct procurement patterns by geography.
United States
Synthetic lubricant blenders in Pennsylvania and Ohio now mandate certificate-of-analysis continuity across 24-month supply agreements. EPA industrial chemical standards are disqualifying uncertified suppliers and consolidating qualified vendor pools. The Gulf Coast petrochemical corridor provides captive C4 feedstock integration for oxo-synthesis operations.
Germany
REACH purity mandates now require cosmetic-grade certification thresholds even for industrial lubricant applications. ECHA's updated persistent organic pollutant restrictions are forcing accelerated supplier audits ahead of 2025 enforcement windows. The Rhineland oxo-chemical cluster hosts integrated producers with backward integration into C4 feedstock streams.
China
Domestic esterification capacity surges in Jiangsu and Zhejiang provinces are absorbing technical-grade flows and reducing import dependency. MEE environmental standards and GB quality specifications shape import eligibility and domestic production licensing. The Yangtze River Delta chemical corridor favors direct-to-compounder distribution to compress working capital cycles.
Japan
METI's carbon neutrality roadmap for industrial machinery is accelerating demand for high-performance synthetic lubricants. Fuel efficiency mandates are pushing automotive OEMs toward synthetic ester base stocks with documented carbon intensity profiles. The Kansai and Chubu industrial regions concentrate lubricant formulation and metalworking fluid demand.
India
Domestic synthetic ester production remains underdeveloped, creating positioning opportunities for certified acid suppliers entering the lubricant additive market. BIS quality specifications and DGFT import frameworks govern market access for specialty chemical grades. Maharashtra and Gujarat host the primary automotive manufacturing and lubricant blending infrastructure.
Global Isononanoic Acid Market Competitive Landscape
Global majors compete with regional champions across feedstock integration and certification breadth. The vendor base stratifies into three tiers: integrated petrochemical platforms with captive C4 supply, specialty chemical houses with membrane purification capabilities, and regional distributors with qualification acceleration services. Strategic moves center on backward integration into octene feedstocks and membrane technology licensing for cosmetic-grade certification compression.
Within the integrated petrochemical tier, BASF SE and OQ Chemicals GmbH exemplify producers with Rhineland-based oxo-synthesis platforms and captive C4 positioning. Evonik Industries AG occupies the specialty chemical archetype, representing high-purity grade specialization for personal care and lubricant additive channels. These three German entities anchor European supply reliability through integrated oxo-alcohol production systems.
| Leading Market Players |
|---|
| OQ Chemicals GmbH |
| BASF SE |
| KH Neochem Co. Ltd. |
| Evonik Industries AG |
| TotalEnergies |
| Croda International plc |
| Dow |
| INEOS |
| ExxonMobil |
| Others |
Supply & Pricing Matrix
REACH's updated persistent organic pollutant restrictions are forcing European personal care formulators to accelerate supplier audits and compress qualification timelines, compelling producers to invest in membrane purification systems and secure captive C4 positions that elevate cost structures across cosmetic-grade tiers.
Pricing Analysis
Certificate-of-analysis continuity across 24-month supply agreements now bundles specification compliance with base material pricing, unbundling traditional spot-market flexibility. Three-tier pricing structure across premium, standard, and economy levels separates cosmetic-grade certified material from technical-grade volume and food-grade niche applications. Price differentiation rests on REACH dossier completeness and membrane purification capability rather than feedstock scale alone. Cost compression in technical-grade channels is intensifying because domestic esterification capacity in Jiangsu province is absorbing regional flows and shortening import windows. Mid-scale compounders exhibit highest price sensitivity, while automotive tier-one suppliers in Pennsylvania and Ohio prioritize specification continuity over unit cost.
Supply Chain Analysis
Regional distribution centers in the Yangtze River Delta and Rhineland chemical corridor anchor hub-and-spoke patterns for drum-scale and bulk deliveries. Supply concentrates in Germany, China, and the United States Gulf Coast, where integrated oxo-chemical platforms draw from captive C4 feedstock streams. Raw material dependencies hinge on propylene oligomer availability, naphtha-cracking economics, and octene oxo-synthesis catalyst supply. Single-source vulnerability for high-purity grades persists because three German platforms control European cosmetic-grade output. Distribution runs through direct-to-compounder channels in China's eastern chemical corridor and specialty chemical distributors in France and Switzerland for membrane-purified material.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH registration timelines and ECHA enforcement windows have erected a cost-of-compliance moat that favors incumbent producers with completed substance dossiers and qualified vendor status, marginalizing uncertified competitors.
For Market Incumbents: Hedge against biobased C9 acid substitution in cosmetic channels by accelerating carbon intensity disclosure capabilities and securing renewable feedstock offtake options. Expand membrane purification capacity in the Rhineland to compress qualification timelines below six months. Defend margin position through backward integration into C4 streams rather than distributor network acquisition. For New Entrants and Emerging Players: Capture India's underdeveloped synthetic ester market by establishing certified acid supply relationships with Maharashtra and Gujarat lubricant blenders before domestic capacity emerges. Target direct-to-compounder distribution in the Yangtze River Delta to bypass established distributor markups. Lead with REACH dossier completion services bundled with material supply to differentiate from uncertified regional traders. For Investors and Strategic Acquirers: The window for entry favors specialty chemical houses with membrane technology licensing and qualification acceleration capabilities rather than commodity-scale producers. Long-term viability centers on regulatory compliance infrastructure rather than feedstock scale across the analysis window. Monitor ECHA enforcement actions against branched isomer impurity profiles as the inflection signal for vendor consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into C4 Feedstock | BASF SE and OQ Chemicals GmbH secure margin control through Rhineland-based oxo-alcohol platforms. |
| Membrane Purification Technology Licensing | Specialty distributors in France and Switzerland compress cosmetic-grade qualification timelines below six months. |
| REACH Dossier Completion Services | Documentation support bundled with material supply locks in European personal care formulator relationships. |
| Direct-to-Compounder Distribution | Yangtze River Delta bypass reduces working capital cycles for Jiangsu and Zhejiang esterification facilities. |
| Carbon Intensity Disclosure Programs | Documented low-carbon profiles preempt biobased substitution in Japan's METI-mandated fuel efficiency applications. |
Research Methodology
Independent corroboration across plant managers at integrated oxo-chemical platforms, procurement leads at synthetic lubricant blenders, and distribution channel partners in specialty chemical networks underwrites the qualitative findings. Technical R&D directors at membrane separation technology providers supplied process economics and qualification timeline benchmarks. Secondary validation draws from customs and trade data, Cefic sector reports, SEC 10-K filings from disclosed chemical producers, and ECHA registration dossiers. Bottom-up volume estimates from esterification capacity buildouts triangulate against top-down demand projections from automotive OEM specification changes.
Rate-of-change decomposition across the projection horizon segments volume and value by grade tier, end-use industry, packaging format, and regional production hub. CAGRs derive from feedstock cost trajectory modeling, capacity utilization assumptions, and regulatory compliance cost pass-through elasticity. Industry-specific forecast inputs include naphtha-cracking margin spreads and REACH enforcement probability weightings.
The model holds under stable C4 feedstock supply and incremental regulatory enforcement; deviation in propylene oligomer volatility or accelerated ECHA restriction timelines would shift grade-mix strategies and regional demand allocation. Forecasts reflect documented assumptions on capacity expansion schedules and certification completion rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Cold Flow Improvers Market
Additives
Bromine Derivatives Market
Additives
Silage Additives Market
Additives
Green Polymer Additive Market
Additives
Glycol Acetate Market
Additives
Potassium Nitrate Market
Additives
Antiknock Agents Market
Additives
Global Dicalcium Phosphate (Feed Grade) Market
Additives
Phthalic Anhydride Derivatives Market
Additives
Dishwashing Additives Market
Additives
Feed Additive Nosiheptide Premix Market
Additives
Global Cement and Concrete Additives Market
Additives
Iso-Butyric Acid Market
Additives
Canada Water Enhancer Market
Additives
Polyethylene Terephthalate Additives Market
Additives
Dipotassium Guanylate Market