
 Spain Alcohol E-Commerce Market | 2026-2036
Spain Alcohol E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Alcohol E-Commerce Market Insights
Multi-sourced platform procurement is broadening as Spanish alcohol e-commerce operators diversify beyond single-retailer dependencies. Heineken N.V. leverages its established Iberian distribution network to secure direct-to-consumer channel control. Mercadona anchors its position through integrated logistics infrastructure spanning regional fulfillment centers. Pernod Ricard SA differentiates via specialized spirits portfolios targeting premium online segments.
Spain alcohol e-commerce denotes digital retail platforms facilitating the sale and home delivery of fermented and distilled beverages with alcohol-by-volume content ranging from 4% to 40%+, subject to temperature-controlled logistics and age-verification protocols at point of delivery. The category serves commercial and residential buyers seeking convenience-driven replenishment and discovery-driven purchasing outside traditional brick-and-mortar channels. Wine dominates transaction volumes reflecting Spain's entrenched viticultural heritage and consumer familiarity with regional denominaciones de origen. Same-day delivery models capture the fastest expansion trajectory as urban density in Barcelona and Madrid supports route economics. Subscription services concentrate margin pools through predictable recurring revenue and inventory pre-commitment mechanisms.
Spain's national health ministry and regional autonomous community regulators enforce Ley General de Sanidad Sanitaria provisions restricting alcohol promotion to minors and limiting cross-border digital sales volumes. The country's central food safety authority mandates traceability documentation for temperature-sensitive shipments affecting last-mile provider certification requirements. Stakeholders must monitor evolving autonomous community enforcement disparities and delivery-time restriction proposals that could reshape fulfillment network economics.
Market Dynamics
Same-day delivery infrastructure is compressing fulfillment timelines across Spain's alcohol e-commerce sector, forcing operators to reconfigure last-mile networks around Madrid and Barcelona urban corridors while navigating autonomous community enforcement disparities.
Growth Catalysts
- Urban density corridors:Barcelona and Madrid metropolitan zones generate route economics that sustain sub-two-hour delivery windows. Population concentration in these corridors enables batch optimization algorithms that reduce per-drop costs.
- Ley General de Sanidad Sanitaria advertising restrictions:Digital platforms capture marketing spend displaced from traditional broadcast channels. Compliance-driven budget reallocation favors owned-channel investments in e-commerce infrastructure.
- Temperature-controlled logistics maturation:Refrigerated last-mile fleets achieve certification standards required by Spain's central food safety authority. Expanded cold-chain coverage unlocks premium wine and spirits segments previously constrained by spoilage risk.
Market Restraints
- Autonomous community enforcement fragmentation:Seventeen regional regulators interpret Ley General de Sanidad Sanitaria provisions inconsistently. Operators face compliance cost multiplication when scaling across Andalusia, Catalonia, and Basque Country jurisdictions.
- Last-mile labor cost escalation:Delivery driver wage pressures in Madrid and Barcelona compress platform margins. Same-day service promises require staffing ratios that erode unit economics outside dense urban cores.
- Cross-border digital sales volume caps:National health ministry restrictions limit inbound shipments from Portuguese and French e-commerce competitors. Domestic incumbents benefit from import friction but face reciprocal constraints on outbound expansion.
Strategic Opportunities
- Subscription service penetration:Recurring revenue models concentrate margin pools through inventory pre-commitment mechanisms. Young urban professionals in Madrid demonstrate willingness to automate replenishment for preferred denominaciones de origen.
- Andalusian corridor expansion:Seville and Málaga urban agglomerations remain underpenetrated relative to capital-region density. Route economics in these secondary metros are approaching viability thresholds for same-day deployment.
- Blockchain traceability integration:Convergence of distributed ledger technology with temperature logging addresses documentation requirements from Spain's central food safety authority. Premium segment buyers gain provenance verification that justifies price premiums.
Industry Challenges
- Age-verification protocol standardization:Point-of-delivery identity checks lack interoperable technical standards across carrier networks. Platform operators must integrate multiple verification systems, increasing integration complexity with legacy order management infrastructure.
- Refrigerated fleet capex intensity:Electric vehicle transition timelines for temperature-controlled delivery vans require capital deployment ahead of demand certainty. Operators face stranded asset risk if autonomous community delivery-time restrictions reshape route planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Alcohol E-Commerce Market |
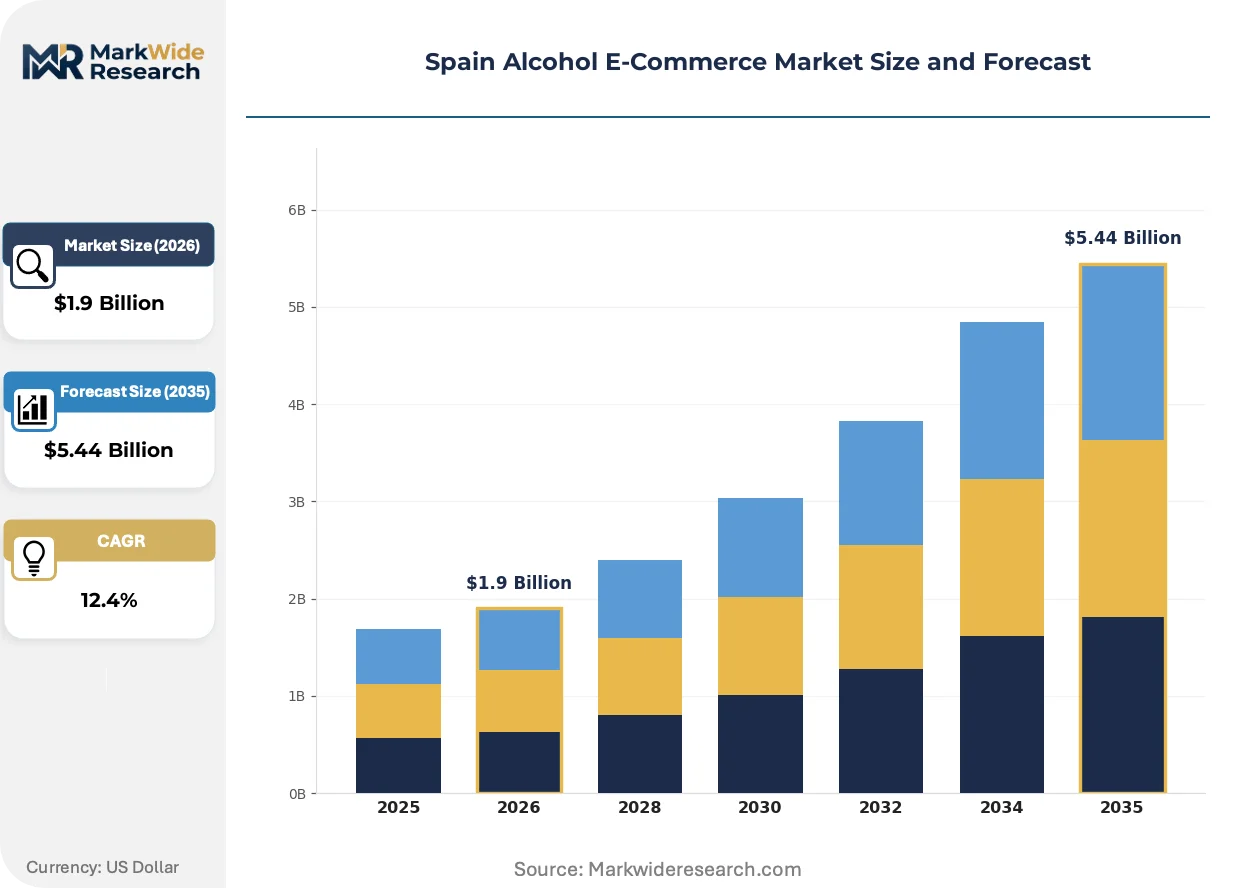
| Market Size in 2026 | $1.9 Billion |
| Market Size in 2035 | $5.44 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spirits, Wine, Beer, Cider Sales Channel: Direct-to-Consumer, Marketplace, Subscription Service, B2B Sales Customer Type: Individual Consumers, Restaurants, Retailers, Event Planners Delivery Model: Home Delivery, Click & Collect, Same-Day Delivery, Scheduled Delivery |
| Companies Covered | Diageo plc, Heineken N.V., Mercadona, Vivino Inc., Anheuser-Busch InBev SA/NV, Carrefour, Pernod Ricard SA, Wine.com LLC, AliExpress, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Alcohol E-Commerce Market Trends and Innovations
Artificial intelligence is reshaping demand forecasting and inventory positioning across Spanish alcohol e-commerce platforms, compressing the gap between discovery-driven purchasing patterns and fulfillment readiness.
Machine learning algorithms trained on regional denominaciones de origen preference data are rewriting how platforms anticipate restocking needs. Madrid-based operators deploy predictive models that correlate weather patterns with sparkling wine demand spikes. The structural consequence is a shift from reactive procurement to pre-positioned inventory, reducing stockout rates during peak consumption windows.
Spain's updated Ley General de Sanidad Sanitaria provisions on digital alcohol promotion are tightening platform content moderation obligations. The industrial consequence is accelerated investment in automated age-gating and geofencing technologies. Premium spirits segments face the highest compliance burden, with operators deploying manual review layers for influencer partnership content.
Discovery-driven purchasing is displacing replenishment-only behavior among Barcelona's young professional cohort. Subscription curation services and algorithmic recommendation engines are capturing share from static category browsing. This behavioral shift concentrates most visibly in natural wine and craft spirits verticals, where unfamiliar producers rely on platform editorial content to overcome brand recognition deficits.
Spain Alcohol E-Commerce Market Segmentation
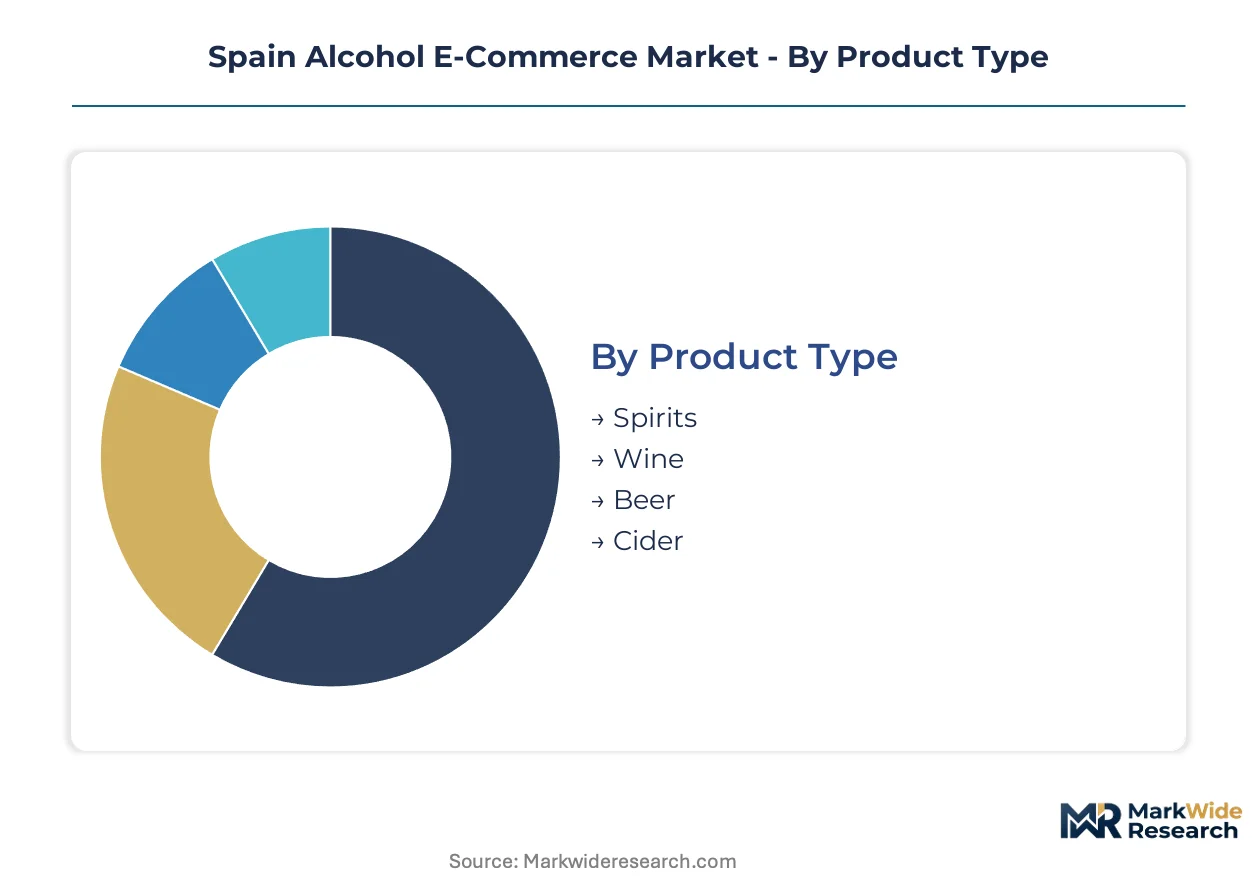
Segmentation reveals how capital deployment and regulatory compliance costs concentrate across Spain's alcohol e-commerce value chain. Product handling requirements, customer verification protocols, and delivery infrastructure investments vary dramatically by category, shaping platform specialization strategies.
Product Type:
Wine and spirits demand the heaviest upfront investment in temperature-controlled warehousing and traceability systems mandated by Spain's central food safety authority.
- Wine:Denominaciones de origen protection requires blockchain-enabled provenance documentation for premium vintages. Madrid and Barcelona urban professionals drive demand for same-day chilled delivery of Ribera del Duero and Priorat labels, though regional fulfillment center capex limits coverage.
- Spirits:Higher alcohol-by-volume content triggers stricter Ley General de Sanidad Sanitaria advertising restrictions and age-verification protocols. Premium whiskey and gin segments attract subscription curation services targeting Barcelona's young professional cohort with discovery-driven purchasing.
- Beer:Volume leadership in transaction frequency supports batch-optimized route economics across Madrid metropolitan delivery corridors.
- Cider:Asturian and Basque regional specialties command niche positioning with lower refrigerated fleet utilization.
Most installed capacity flows through Wine. Expansion is steepest in Spirits.
Sales Channel:
Channel selection determines margin structure and customer acquisition cost exposure, with direct control trading off against reach scalability.
- Direct-to-Consumer:Brand-owned platforms capture full margin but absorb compliance and logistics integration burdens. Heineken's Iberian distribution network demonstrates how captive channels bypass marketplace fee structures.
- Marketplace:Aggregator platforms spread fixed technology costs across multiple seller bases. Mercadona's integrated logistics infrastructure anchors this channel with regional fulfillment center coverage.
- Subscription Service:Recurring revenue models concentrate margin pools through inventory pre-commitment mechanisms among Madrid's young urban professionals.
- B2B Sales:Restaurant and hospitality procurement volumes justify dedicated account management and negotiated delivery windows outside peak residential demand periods.
Marketplace channels carry the broadest SKU exposure. Subscription services are climbing the fastest as automation penetrates repeat purchasing behavior.
Customer Type:
Verification intensity and order pattern predictability split capital allocation between residential last-mile density and commercial account infrastructure.
- Individual Consumers:Point-of-delivery age checks require carrier network integration with multiple verification systems. Discovery-driven purchasing in Barcelona's natural wine vertical demands algorithmic recommendation engine investment.
- Restaurants:Predictable volume patterns support scheduled delivery optimization with lower per-drop verification overhead.
- Retailers:Replenishment-driven ordering aligns with batch procurement economics and palletized logistics.
- Event Planners:Spike demand around seasonal consumption windows strains same-day capacity in Madrid and Barcelona corridors.
Individual consumer volume dominates transaction counts. Restaurant segment expansion is gaining share fastest as platform B2B capabilities mature.
Delivery Model:
Speed-tier differentiation separates premium service investments from cost-optimized fulfillment infrastructure.
- Same-Day Delivery:Sub-two-hour promises require electric refrigerated fleet deployment ahead of demand certainty. Madrid and Barcelona urban density sustains route economics that secondary metros cannot yet match.
- Scheduled Delivery:Consolidated drop windows maximize vehicle utilization and minimize per-unit labor cost exposure.
- Home Delivery:Standard residential service anchors baseline coverage with flexible timing tolerance.
- Click & Collect:Locker and pickup point networks reduce last-mile labor intensity for cost-sensitive orders.
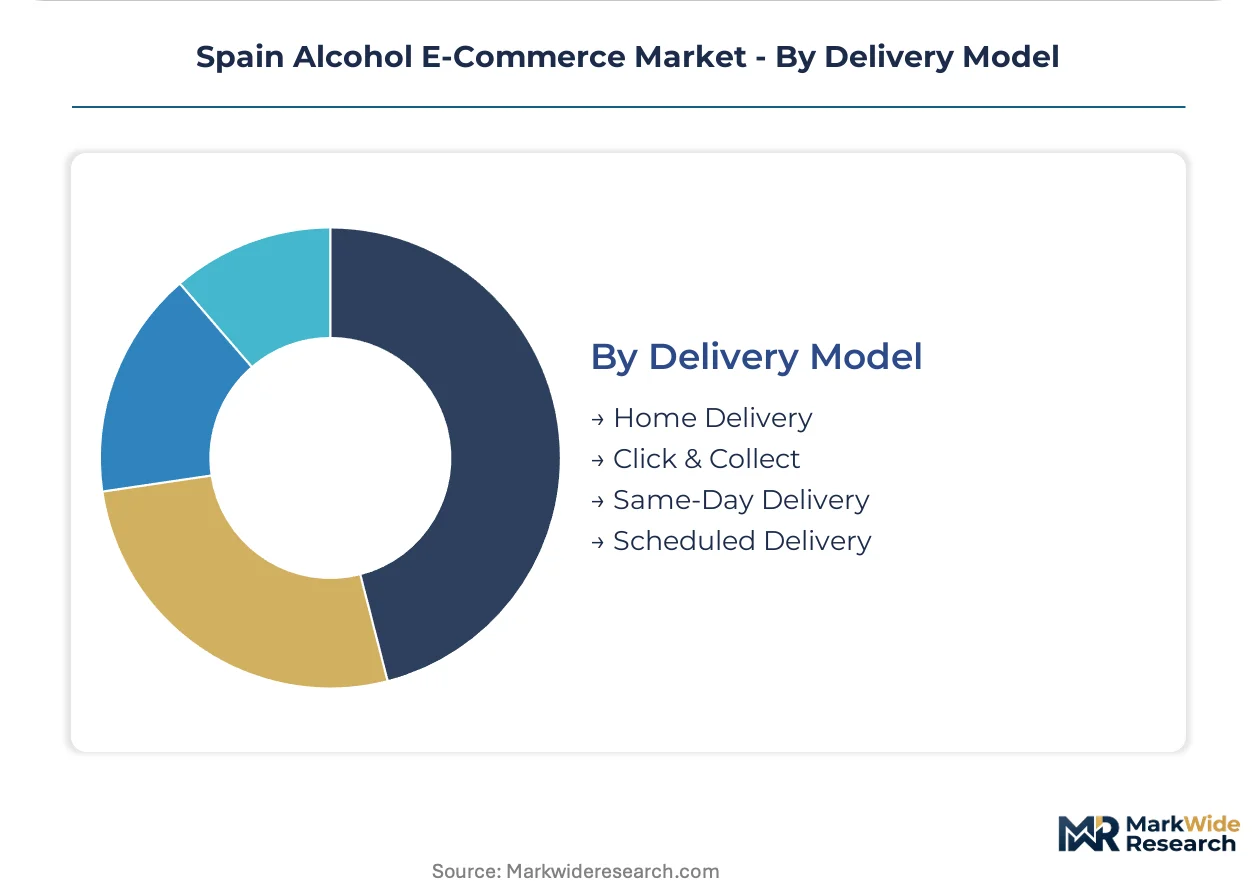
Home delivery infrastructure represents the most deployed capacity. Same-day services are expanding most quickly as autonomous community delivery-time restrictions reshape competitive positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Madrid and Barcelona metropolitan corridors anchor Spain's alcohol e-commerce infrastructure, with autonomous community regulatory fragmentation shaping expansion economics across secondary urban agglomerations.
Madrid
Young urban professionals drive same-day delivery demand for Ribera del Duero and premium spirits. The national health ministry enforces Ley General de Sanidad Sanitaria advertising restrictions that redirect marketing spend toward owned digital channels. Temperature-controlled fulfillment centers in the capital corridor sustain sub-two-hour delivery windows through batch-optimized route algorithms.
Catalonia
Barcelona's density supports the fastest subscription service adoption among Spain's autonomous communities. Regional regulators interpret alcohol promotion rules with stricter point-of-delivery verification standards than national baselines. The Priorat and Penedès wine clusters feed discovery-driven purchasing through platform editorial content targeting natural wine segments.
Basque Country
Cider specialists and craft spirits producers leverage underpenetrated same-day delivery corridors relative to capital-region saturation. Local enforcement of age-verification protocols exceeds minimum Ley General de Sanidad Sanitaria requirements. San Sebastián and Bilbao urban cores demonstrate emerging viability for refrigerated fleet deployment.
Andalusia
Seville and Málaga agglomerations approach route economics thresholds for same-day service expansion. Andalusian autonomous community regulators maintain distinct documentation requirements for cross-border digital shipments from Portuguese competitors. Sherry denomination producers in Jerez de la Frontera anchor B2B procurement volumes for restaurant and hospitality channels.
Valencia
The Levante corridor exhibits lower per-capita alcohol e-commerce penetration despite comparable urban density metrics. Regional fulfillment center gaps force longer scheduled delivery windows that compress platform margins. Valencia city logistics networks remain optimized for traditional retail distribution rather than chilled last-mile infrastructure.
Spain Alcohol E-Commerce Market Competitive Landscape
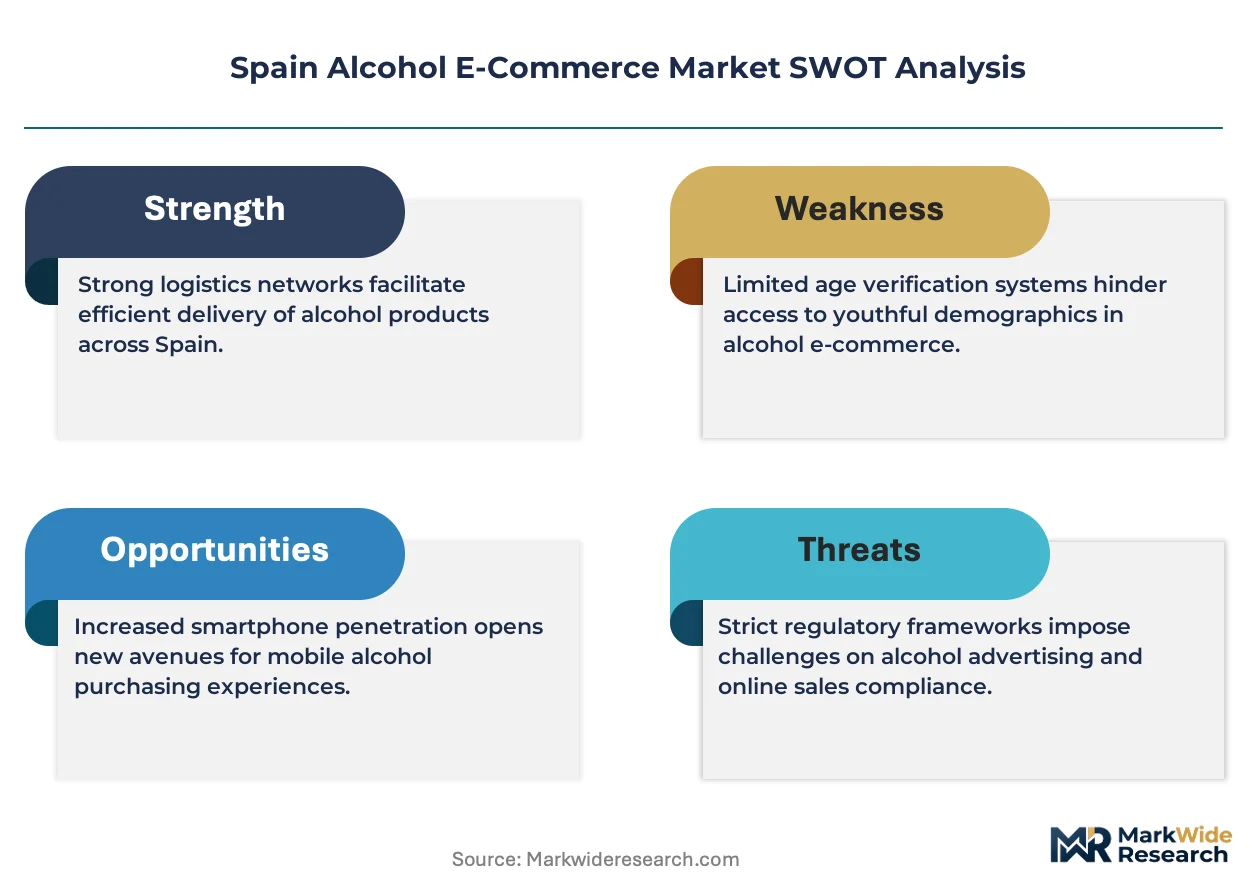
Established producers occupy the standard tier; emerging entrants pursue subscription curation and same-day delivery specialization. The market structure concentrates around integrated retail platforms with captive logistics networks and brand-owned direct-to-consumer channels bypassing marketplace fee structures. Three archetypes dominate: multinational beverage conglomerates with Iberian distribution control, domestic supermarket operators with regional fulfillment density, and specialized wine platforms with discovery-driven recommendation engines. Competitive moves center on refrigerated fleet capex deployment and automated age-verification technology integration.
Within the multinational tier, Heineken N.V. and Diageo plc exemplify beverage conglomerates leveraging established distribution infrastructure for channel control. Pernod Ricard SA occupies a position among spirits specialists targeting premium online segments through curated portfolio positioning. Among domestic retail platforms, Mercadona anchors integrated logistics capabilities spanning regional fulfillment centers. Vivino Inc. and Wine.com LLC represent discovery-oriented platforms where algorithmic recommendation engines capture share from static category browsing.
| Leading Market Players |
|---|
| Diageo plc |
| Heineken N.V. |
| Mercadona |
| Vivino Inc. |
| Anheuser-Busch InBev SA/NV |
| Carrefour |
| Pernod Ricard SA |
| Wine.com LLC |
| AliExpress |
| Others |
Pricing and Supply Chain Analysis
Delivery driver concentration in Madrid and Barcelona metropolitan corridors feeds labor-cost differentials that widen pricing-tier spreads between same-day premium service and scheduled economy delivery across Spain's alcohol e-commerce sector.
Pricing Analysis
Input-cost pass-through from refrigerated fleet operations and age-verification technology investments shapes pricing stratification across premium, standard, and economy tiers. Price differentiation rests on delivery speed guarantees and temperature-control certification levels, with same-day chilled service commanding widest spreads. Pricing pressure stems from driver wage escalation in capital-region corridors compressing platform margins. Individual consumers in secondary metros exhibit highest price sensitivity; young urban professionals in Madrid demonstrate lowest sensitivity for discovery-driven premium spirits purchases.
Supply Chain Analysis
Warehouse-distribution layer concentration in Madrid and Barcelona regional fulfillment centers anchors hub-and-spoke patterns radiating toward secondary urban agglomerations. Geographic supply concentration draws from Spain's domestic denominaciones de origen wine clusters, Portuguese fortified wine producers, and French spirits distillers. Raw material dependencies encompass temperature-controlled packaging materials, electric refrigerated vehicle fleets, and blockchain-enabled traceability systems. Supply chain risk centers on single-source vulnerability for specialized cold-chain equipment subject to Ley General de Sanidad Sanitaria certification requirements. Distribution runs through integrated retail platforms with captive logistics networks alongside third-party last-mile providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's alcohol e-commerce market functions as a geographic-arbitrage play where autonomous community enforcement fragmentation creates compliance-cost differentials between Madrid's national health ministry baseline and Catalonia's stricter point-of-delivery verification standards.
For Market Incumbents: Lock in regional fulfillment center density around Madrid and Barcelona corridors before secondary metro route economics mature. Secure captive cold-chain fleet capacity to defend against emerging same-day specialists. Prioritize automated age-verification technology integration to preempt Catalonia's escalating point-of-delivery protocol requirements.
For New Entrants and Emerging Players: Subscription curation specialists represent the most penetrable white-space target among Madrid's young urban professional cohort with automated replenishment willingness. Andalusian corridor expansion into Seville and Málaga offers underpenetrated density relative to capital-region saturation. Pursue partnership-led entry with regional denominaciones de origen producers seeking direct-to-consumer channel bypass of marketplace fee structures.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized wine platforms with discovery-driven recommendation engines but limited refrigerated logistics infrastructure. Long-term viability across the analysis window favors acquisition targets with integrated cold-chain certification and autonomous community compliance expertise. Monitor blockchain traceability integration adoption rates among premium segment buyers as inflection indicator for provenance-verification monetization potential.
| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerated Fleet Electrification | Electric vehicle deployment in Madrid corridors addresses Ley General de Sanidad Sanitaria delivery-time restriction compliance ahead of regulatory enforcement. |
| Subscription Curation Launch | Recurring revenue models capture inventory pre-commitment from young urban professionals seeking automated denominaciones de origen replenishment. |
| Blockchain Traceability Integration | Distributed ledger convergence with temperature logging satisfies Spain's central food safety authority documentation mandates for premium wine segments. |
| Andalusian Corridor Expansion | Seville and Málaga deployment extends same-day coverage into secondary metros approaching route economics viability thresholds. |
| Automated Age-Verification Deployment | Geofencing and age-gating technology investments preempt Catalonia's stricter regional interpretation of digital alcohol promotion restrictions. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with platform operations directors, cold-chain logistics managers, regulatory compliance officers at autonomous community health ministries, and procurement leads at denominaciones de origen consortiums with secondary validation against Spain's central food safety authority certification databases, Ley General de Sanidad Sanitaria enforcement bulletins, customs records for cross-border digital shipments, and refrigerated fleet operator registration filings. Bottom-up segment sizing and top-down macroeconomic anchoring provided triangulation checks.
Segment-weighting approach distributed value and volume projections across product type, sales channel, customer archetype, and delivery speed tier dimensions throughout the forecast period. CAGRs derived from logistic curve fitting to adoption penetration patterns, with inputs incorporating urban density corridor expansion timelines, electric refrigerated fleet deployment schedules, and autonomous community regulatory enforcement variance assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to autonomous community delivery-time restriction proposals and cross-border digital sales volume cap adjustments. Outputs reflect documented assumptions around labor cost trajectories and cold-chain technology maturation curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Orange Wine Market
Alcoholic Beverages
Apple Wine Market
Alcoholic Beverages
Alcoholic Tea Market
Alcoholic Beverages
United States Tequila Market
Alcoholic Beverages
Sake and Plum Wine Market
Alcoholic Beverages
RTD Bottled Cocktails Market
Alcoholic Beverages
Pre-Mixed/RTD Alcoholic Drinks Market
Alcoholic Beverages
Pineapple Beer Market
Alcoholic Beverages
UAE Alcohol E-Commerce Market
Alcoholic Beverages
Germany Tequila Market
Alcoholic Beverages
Distilled Spirits Market
Alcoholic Beverages
Tonic Wine Market
Alcoholic Beverages
Global Malt Market
Alcoholic Beverages
Puncheon Barrel Market
Alcoholic Beverages
Japan Tequila Market
Alcoholic Beverages
Middle East and Africa Beer Market