
 China Tequila Market | 2026-2036
China Tequila Market Size, Share, and Industry Trends Forecast 2026-2036
China Tequila Market Insights
The price gap between premium aged tequilas and unaged silver expressions is hardening as Chinese consumers develop more sophisticated palates. Jose Cuervo leverages its mass-market distribution network to sustain volume leadership in retail channels. Patron Spirits Company anchors the super-premium tier through positioning in high-end bars and duty-free retail. Brown-Forman differentiates via its portfolio depth across reposado and añejo expressions.
Tequila is a distilled spirit produced from the fermented sugars of blue agave (Agave tequilana Weber), with Mexican regulations mandating minimum agave content and specific origin denominations for classification. The spirit serves primarily as a base for cocktails and as a sipping spirit in premium hospitality settings. Silver tequila dominates retail volume due to lower price points and versatility in mixed drinks, while extra añejo commands the highest margins in on-premise channels. Online sales are expanding fastest among distribution formats as e-commerce platforms improve cold-chain logistics for imported alcohol.
SAMR enforces labeling and food safety standards for imported spirits entering China, while NMPA oversees health claims and additive disclosures on alcoholic beverages. The country's national standards body applies GB standards for alcohol content measurement and contaminant limits, creating compliance costs that favor larger importers with dedicated regulatory affairs teams. Stakeholders must monitor potential revisions to cross-border e-commerce rules that could reshape how premium tequila reaches consumers outside tier-one cities.
Market Dynamics
China's tequila market pivots on the tension between SAMR's evolving food safety standards and the rapid maturation of tier-one city drinking culture, where mixology sophistication now outpaces regulatory adaptation speed.
Growth Catalysts
- Mixology Culture Maturation:Premium cocktail bars in Shanghai and Beijing are normalizing aged tequila as a sipping spirit, creating pull-through demand for reposado and añejo expressions previously confined to Western markets.
- E-commerce Logistics Modernization:Cold-chain improvements on platforms like Tmall and JD.com are collapsing distribution timelines for imported spirits, enabling direct-to-consumer reach beyond traditional on-premise channels.
- GB Standards Harmonization:China's national standards body is aligning alcohol content measurement protocols with international norms, reducing technical barriers for Mexican exporters seeking market entry.
Market Restraints
- Agave Supply Concentration:Blue agave cultivation remains geographically locked to Jalisco and limited Mexican states, exposing Chinese importers to weather-driven harvest volatility and price spikes.
- SAMR Certification Friction:China's State Administration for Market Regulation imposes additive disclosure requirements that extend product registration timelines by 8-14 months versus other spirits categories.
- Baijiu Substitution Threat:China's indigenous grain spirit dominates domestic premium alcohol occasions, with established gifting rituals and cultural cachet that tequila struggles to displace in tier-two and tier-three cities.
Strategic Opportunities
- Cross-border E-commerce Expansion:Revisions to China's CBEC (cross-border e-commerce) rules could unlock duty-advantaged pathways for premium tequila into Hangzhou, Chengdu, and Shenzhen consumer bases.
- Western Dining Format Proliferation:Steakhouse and fine-dining chains in Guangzhou and Shenzhen are expanding tequila pairing programs, creating new on-premise volume anchors outside Beijing-Shanghai dominance.
- Dual Carbon Policy Alignment:China's MEE (Ministry of Ecology and Environment) sustainability incentives favor importers with verified carbon-neutral shipping and packaging, rewarding early compliance investments.
Industry Challenges
- Regulatory Affairs Talent Scarcity:Qualified professionals capable of navigating SAMR-NMPA interface requirements for alcoholic beverage labeling remain concentrated in Shanghai, creating bottlenecks for regional market expansion.
- Legacy Distribution Integration:Established baijiu wholesalers lack cold-storage infrastructure and brand storytelling capability for premium agave spirits, forcing tequila brands to build parallel channel structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Tequila Market |
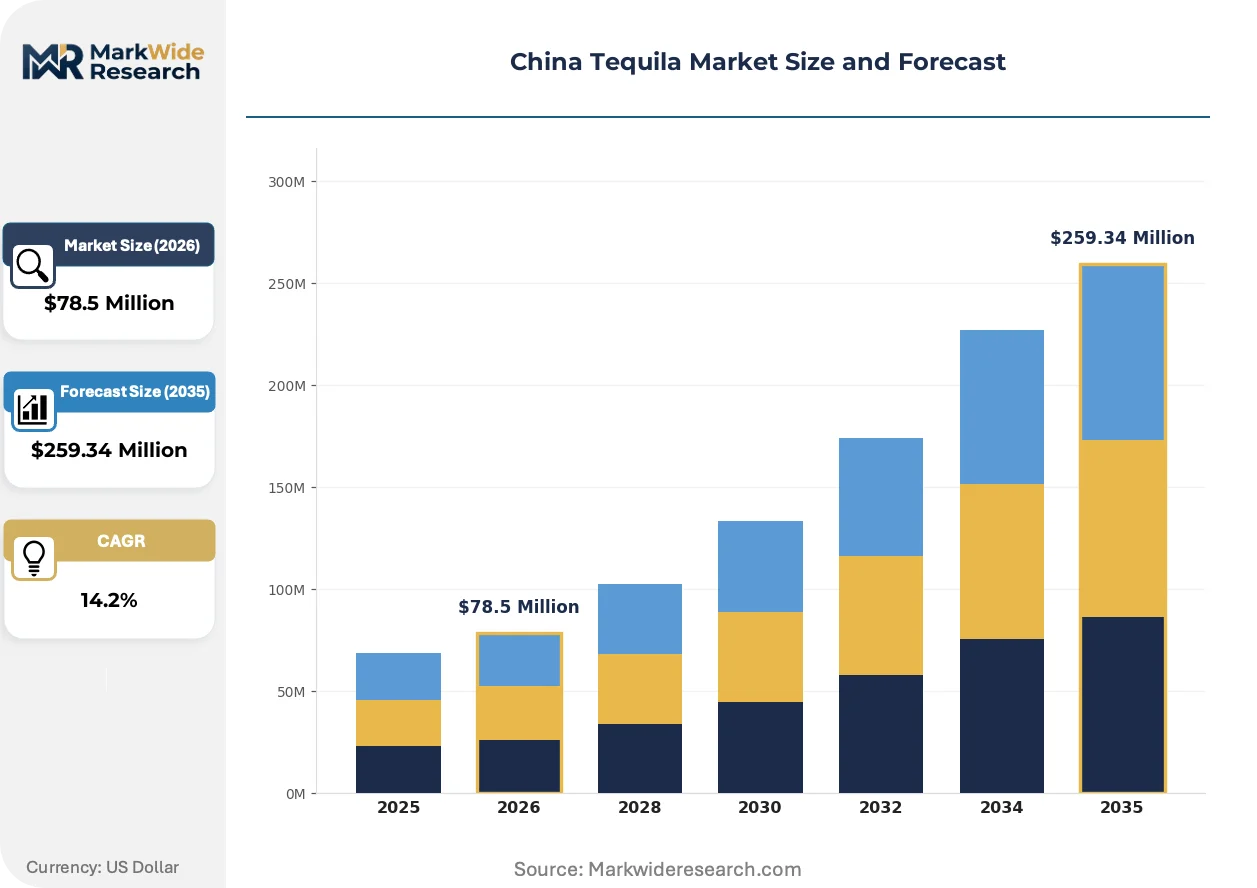
| Market Size in 2026 | $78.5 Million |
| Market Size in 2035 | $259.34 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silver, Reposado, Añejo, Extra Añejo Sales Channel: Retail, Online, Bars, Restaurants Pricing Tier: Premium, Super Premium, Value, Standard Consumption Occasion: Celebrations, Social Gatherings, Casual Drinking, Mixology |
| Companies Covered | Pernod Ricard, Campari Group, Jose Cuervo, Don Julio, Sauza Tequila, Patron Spirits Company, Brown-Forman, Becle, Diageo, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Tequila Market Trends and Innovations
Digital traceability systems and consumption occasion engineering are redefining how premium tequila builds authenticity and occasion-share in China's contested spirits landscape.
Blockchain-based provenance verification is consolidating trust architecture for high-value extra añejo expressions. Luxury hospitality groups in Shanghai are mandating QR-linked agave field documentation for back-bar placement. This technology is compressing the traditional brand-building timeline by substituting transparent supply chain narrative for decades of market presence.
SAMR's 2023 additive disclosure amendments are forcing reformulation of flavored and mixto tequilas bound for China. The regulation mandates explicit labeling of glycerin, caramel color, and oak extract, eliminating opacity that previously masked production shortcuts. Premium 100% agave exporters are leveraging this friction to differentiate against lower-tier competitors dependent on additive masking.
Home bartending equipment purchases on Xiaohongshu and Douyin are rotating demand toward versatile silver expressions. Young professionals in tier-one cities are building personal cocktail stations, substituting at-home experimentation for nightclub expenditure. This behavioral pivot is most visible in Beijing, where apartment size constraints favor compact bar tools and multi-purpose base spirits over specialized sipping collections.
China Tequila Market Segmentation
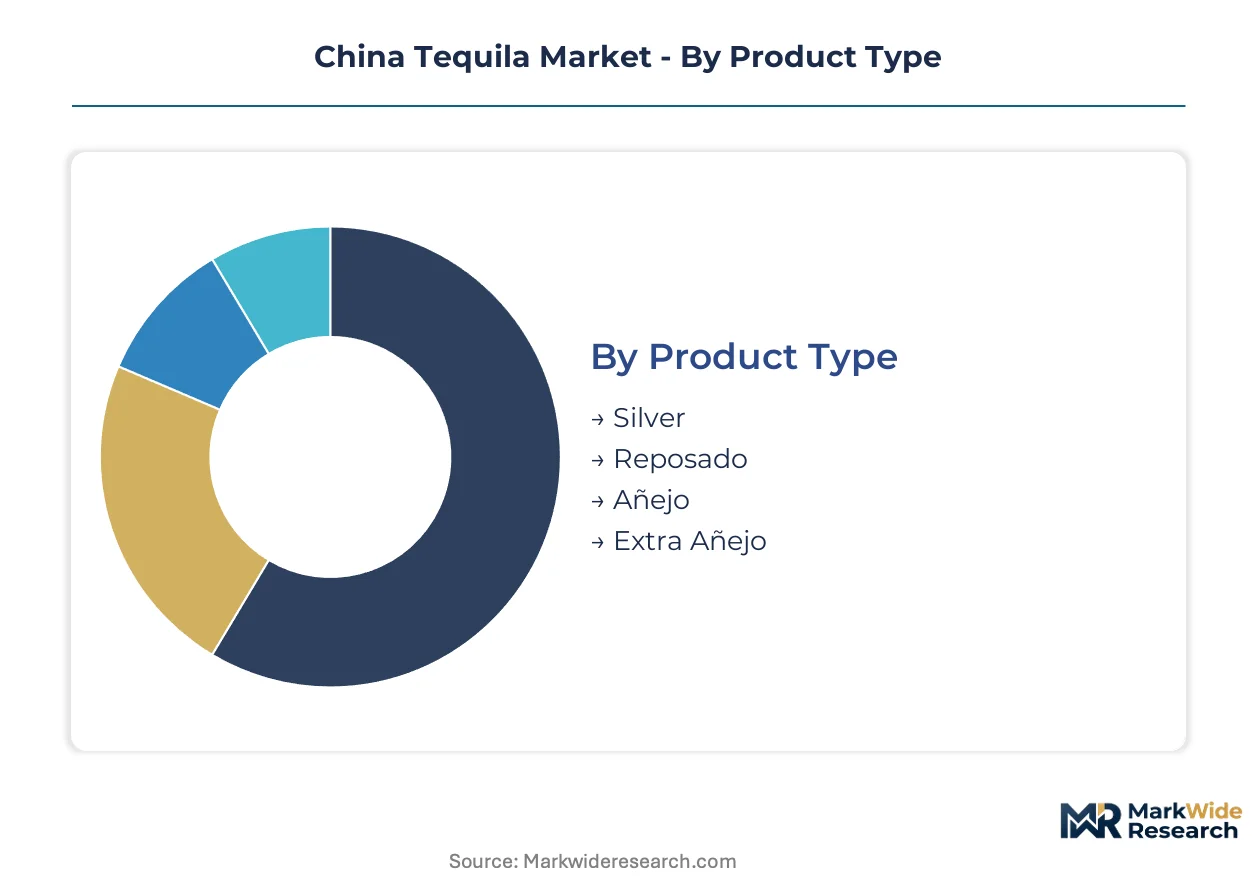
China's tequila market segments reveal distinct upgrade pathways as consumers migrate from entry-level mixers toward aged sipping expressions. Each dimension captures a different lens on how Mexican agave spirits penetrate a market historically dominated by indigenous grain alcohols.
Product Type:
Upgrade cycles in Chinese spirits consumption favor products that reward palate development with measurable quality differentiation.
- Silver:Unaged tequila bottled immediately after distillation, preserving raw agave vegetal notes and peppery finish. Volume concentrates in Beijing and Shanghai home bartending scenes, where Xiaohongshu tutorials drive demand for versatile cocktail bases that tolerate recipe experimentation.
- Reposado:Rested two months to one year in oak barrels, developing vanilla and caramel mid-palate complexity. Premium cocktail bars in Shanghai's former French Concession are normalizing reposado as a standalone sipping spirit, displacing blended Scotch in highball preparations.
- Añejo:Aged one to three years, delivering concentrated oak tannins and dried fruit depth. Duty-free retail at Shanghai Pudong International Airport captures outbound affluent travelers seeking giftable luxury formats.
- Extra Añejo:Matured beyond three years in limited oak casks, commanding the highest per-liter margins. Blockchain traceability systems now document agave field provenance for back-bar placement at hospitality groups mandating supply chain transparency.
Silver sits at the top of the volume ranking, with extra añejo climbing the fastest as tier-one city collectors build vertical agave portfolios.
Sales Channel:
Channel strategy in China must account for fragmented cold-chain maturity and divergent consumer education requirements across touchpoints.
- Retail:Supermarkets and specialty liquor stores in Shanghai and Beijing stock predominantly silver and value-tier reposado. SAMR labeling compliance creates shelf-space advantages for importers with dedicated regulatory affairs teams.
- Online:Tmall and JD.com platforms leverage improved cold-chain logistics to collapse delivery timelines for temperature-sensitive agave spirits. Direct-to-consumer reach now extends beyond tier-one cities into Chengdu and Hangzhou.
- Bars:Premium cocktail venues in Beijing's Sanlitun district anchor super-premium volume through back-bar visibility and bartender education programs. Mixology competitions rotate toward aged expressions as judges reward complexity.
- Restaurants:Western steakhouse chains in Guangzhou and Shenzhen deploy tequila pairing menus to differentiate from baijiu-dominated fine dining. Sommelier certification programs now include agave spirits modules.
Retail maintains volume leadership, though online channels are gaining share fastest as e-commerce platforms improve last-mile cold storage.
Pricing Tier:
Price stratification reflects supply chain control depth and certification rigor rather than simple ingredient cost accounting.
- Premium:100% agave tequilas with CRT denomination of origin certification. Tier-one city professionals purchase these for home consumption occasions where baijiu gifting rituals do not apply.
- Super Premium:Extended-aged expressions with verified additive-free production. High-end bars in Shanghai mandate these for back-bar placement to satisfy mixology competition judging criteria.
- Value:Mixto tequilas with minimum 51% agave content. Price-sensitive consumers in tier-two cities purchase these for casual social gatherings where brand recognition matters less than accessibility.
- Standard:Entry-level 100% agave expressions targeting first-time buyers. Retail shelf placement competes directly with flavored vodka and rum in the sub-premium white spirits corridor.
Value commands the highest unit volume, while super premium exhibits the steepest expansion trajectory as aged expressions penetrate gifting occasions.
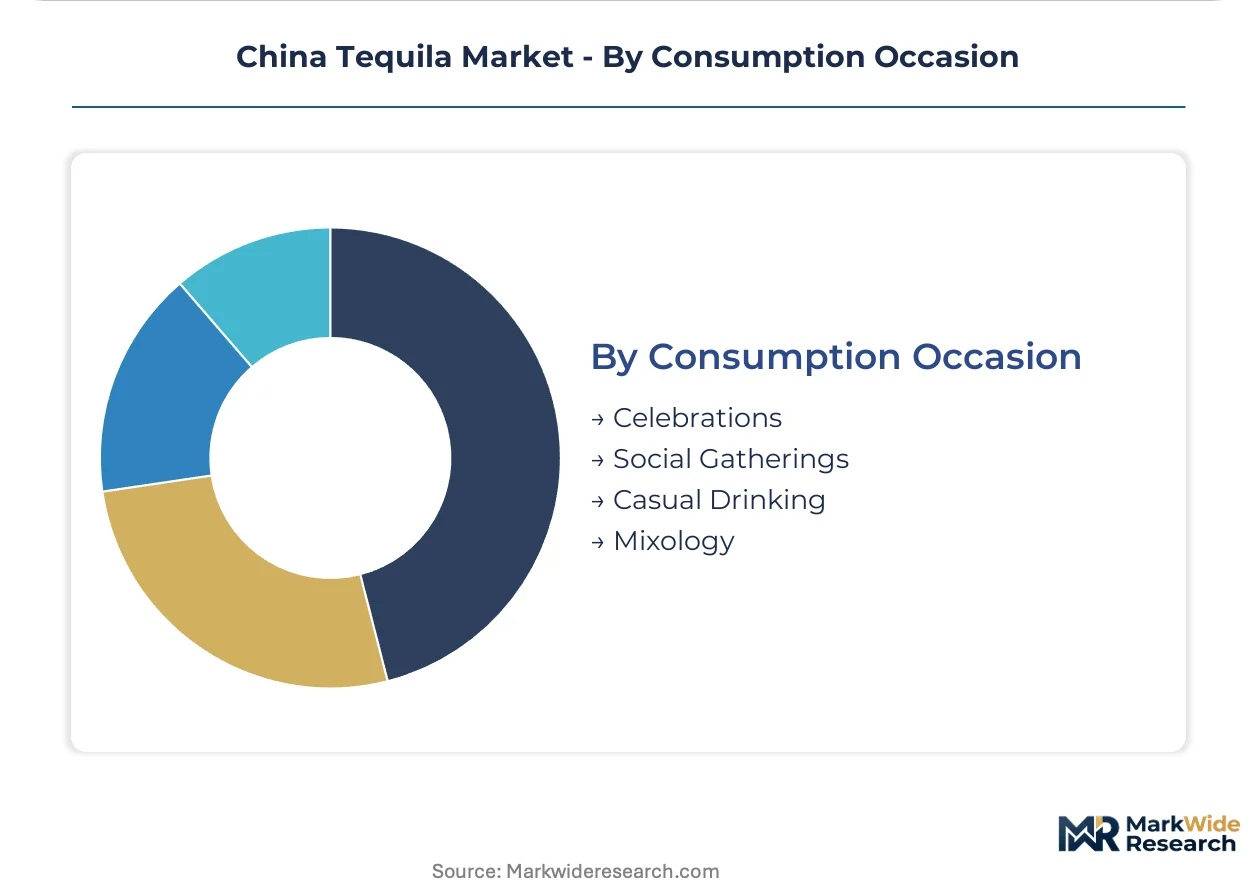
Consumption Occasion:
Occasion engineering determines whether tequila displaces incumbent spirits or remains confined to niche Western-format venues.
- Celebrations:Lunar New Year and corporate banquet gifting opportunities where baijiu dominates. Tequila brands struggle to replicate the cultural cachet of Maotai in tier-two and tier-three cities.
- Social Gatherings:Informal dining and karaoke occasions favoring shareable bottle formats. Young professionals in Beijing substitute tequila for beer in mixed-group settings to signal cosmopolitan taste.
- Casual Drinking:At-home consumption driven by Xiaohongshu cocktail tutorials. Apartment size constraints in Shanghai favor compact bar tools and multi-purpose base spirits over specialized collections.
- Mixology:Craft cocktail bar visits where bartender recommendations drive trial. Competition judging panels now reward agave complexity, rotating demand toward reposado and añejo expressions.
Social gatherings generate the highest occasion frequency, with mixology-driven consumption expanding most quickly as bar culture matures in Shenzhen and Chengdu.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized regulatory affairs talent clusters in Shanghai anchor tequila import operations, creating geographic concentration that shapes market expansion patterns across Chinese sub-regions.
Shanghai and Yangtze River Delta
Premium cocktail bars in Shanghai's former French Concession drive reposado adoption through back-bar visibility and bartender education programs. SAMR certification specialists concentrate here, reducing product registration timelines for importers with dedicated compliance teams. Cold-chain logistics hubs in Pudong connect directly to duty-free retail at Shanghai Pudong International Airport.
Beijing and Beijing-Tianjin-Hebei
Home bartending culture flourishes among young professionals building personal cocktail stations in compact apartments. NMPA oversight of health claims and additive disclosures creates compliance friction that favors established importers with in-house regulatory capacity. Mixology competitions in Sanlitun district rotate judging criteria toward aged agave complexity.
Guangdong and Pearl River Delta
Western steakhouse chains in Guangzhou and Shenzhen deploy tequila pairing menus to differentiate from baijiu-dominated fine dining. GB standards for alcohol content measurement apply uniformly across the province, harmonizing with international protocols. Sommelier certification programs in Shenzhen now include dedicated agave spirits modules.
Sichuan-Chongqing
Cross-border e-commerce platforms target Chengdu's emerging consumer base as CBEC rule revisions create duty-advantaged pathways. MEE sustainability incentives favor importers with verified carbon-neutral shipping documentation. Local distributors lack cold-storage infrastructure, forcing parallel channel construction by premium brands.
China Tequila Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across China's tequila import landscape. The market structure consolidates around three strategic tiers: mass-market volume leaders with established retail networks, super-premium specialists anchored in high-end hospitality, and portfolio diversifiers spanning multiple aged expressions. Dominant competitive moves include e-commerce platform partnerships and regulatory compliance investments that extend market access timelines.
Within the super-premium tier, Patron Spirits Company and Brown-Forman occupy positions defined by mixology channel penetration and aged expression depth. Jose Cuervo anchors mass-market volume through retail distribution scale. These three exemplify how archetype differentiation—premium hospitality focus versus portfolio breadth versus mass accessibility—determines competitive positioning in a market where SAMR certification creates structural barriers to rapid expansion.
| Leading Market Players |
|---|
| Pernod Ricard |
| Campari Group |
| Jose Cuervo |
| Don Julio |
| Sauza Tequila |
| Patron Spirits Company |
| Brown-Forman |
| Becle |
| Diageo |
| Others |
Pricing and Supply Chain Analysis
Super-premium additive-free certification against commodity mixto tiering creates a bifurcated pricing architecture that simultaneously rewards CRT-compliant exporters with margin expansion and exposes lower-tier competitors to SAMR-driven cost compression. This divergence manifests in supply chain configurations where premium brands bypass legacy baijiu wholesalers entirely, while value-tier importers remain tethered to fragmented cold-storage deficient distribution networks.
Pricing Analysis
Certification-bundled versus unbundled service splits dominate tequila pricing in China, with super-premium brands packaging SAMR compliance consulting and bartender education into landed costs while value-tier competitors strip these services to hit price points. Price differentiation rests on CRT denomination verification and additive-free production documentation, with the former commanding 3-4x per-liter premiums over mixto alternatives. Pricing pressure stems from baijiu substitution in tier-two gifting occasions, compressing margins for entrants lacking brand heritage. Home bartending segments in Beijing exhibit highest price sensitivity, while duty-free collectors at Shanghai Pudong show lowest elasticity.
Supply Chain Analysis
Agave harvesting workforce availability in Jalisco and limited Mexican states constrains production scaling for Chinese-bound exports, with jimador labor pools already stretched across multiple international markets. Geographic supply concentrates in Mexico's Denominación de Origen regions, with secondary bottling operations in China proper for value-tier products. Raw material dependencies include blue agave piñas, American and French oak casks, and copper still components. Single-source vulnerability runs through Jalisco's weather-exposed harvest cycles. Distribution runs through parallel channel structures: premium brands build dedicated cold-chain partnerships with Tmall and JD.com, while mass-market players rely on fragmented regional liquor wholesalers lacking temperature control infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's tequila market reads as a late-cycle quality story where mixology sophistication in tier-one cities is rotating demand toward aged sipping expressions and away from entry-level silver mixers. This demand-shift toward premium specifications rewards early compliance investments and punishes commodity positioning.
For Market Incumbents: Deepen vertical control over agave field relationships to secure harvest priority during weather-stressed vintages, insulating margin structure from input volatility. Fortify SAMR regulatory affairs capacity in Shanghai to compress product registration timelines as additive disclosure requirements tighten. Baijiu wholesalers' inability to execute cold-chain logistics presents both threat and opportunity—incumbents must build parallel distribution or risk channel capture by beverage conglomerates with existing infrastructure.
For New Entrants and Emerging Players: Tier-two city sommelier programs represent an underserved buyer archetype with penetrable white-space, as Western steakhouse chains in Guangzhou and Shenzhen expand agave education modules faster than established brands can deploy training resources. Chengdu's cross-border e-commerce consumer base offers second-mover advantage as CBEC rule revisions create duty-advantaged pathways outside Beijing-Shanghai dominance. A go-to-market angle anchored in carbon-neutral shipping documentation aligns with MEE sustainability incentives and differentiates against legacy importers.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier portfolio diversifiers possessing aged expression depth but lacking dedicated China regulatory capacity, as SAMR certification friction creates acquisition targets with compressed valuations relative to intrinsic brand equity. Long-term viability over a 5-10 year window hinges on mixology channel penetration rather than retail volume scale. The signal to watch is bartender competition judging criteria—sustained rotation toward agave complexity indicates durable premium-tier expansion, while reversion to Scotch and Japanese whisky dominance suggests category ceiling.
| Strategic Initiative | Industry Significance |
|---|---|
| Cross-Border E-Commerce Platform Partnership | CBEC rule revisions unlock duty-advantaged reach into Chengdu and Hangzhou consumer bases. |
| Carbon-Neutral Shipping Certification | MEE sustainability incentives reward verified documentation with preferential customs treatment. |
| Bartender Education Program Expansion | Mixology competition judging criteria now reward agave complexity, rotating demand toward aged expressions. |
| Blockchain Provenance Implementation | Luxury hospitality groups in Shanghai mandate QR-linked agave field documentation for back-bar placement. |
| Parallel Cold-Chain Distribution Buildout | Legacy baijiu wholesalers lack temperature control infrastructure, forcing direct channel construction. |
Research Methodology
Coverage spans China's tier-one cities, Yangtze River Delta, Pearl River Delta, and Sichuan-Chongqing corridor, with primary inputs from each sub-region informing demand calibration. The analysis combines structured interviews with brand managers at import houses, regulatory affairs specialists navigating SAMR-NMPA interface requirements, beverage directors at premium hospitality groups, and procurement leads at cross-border e-commerce platforms. Secondary validation draws from customs import records, SAMR additive disclosure amendments, CRT denomination of origin registries, and cold-chain logistics disclosures by Tmall and JD.com. Bottom-up channel volume estimates and top-down market sizing triangulate to produce coherent demand figures.
Granularity-level framing applies distinct modeling resolution across segmentation dimensions: product type splits (silver, reposado, añejo, extra añejo) carry full projection detail, sales channel dynamics (retail, online, bars, restaurants) incorporate platform-specific growth rates, and pricing tier movements reflect certification compliance cost differentials. CAGRs emerge from segment-level trajectory blending rather than single-point extrapolation. Industry-specific forecast inputs include agave harvest cycle volatility patterns and mixology competition judging trend analysis.
Underlying measurement precision varies by segment; tier-one city on-premise channels carry tighter precision than tier-two retail estimates due to data availability asymmetries. Forecasts reflect assumptions regarding SAMR regulatory stability, agave supply continuity, and baijiu competitive response intensity. Material deviation in cross-border e-commerce rule implementation, Jalisco weather patterns, or MEE sustainability incentive enforcement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
North America Mezcal Market
Alcoholic Beverages
Edible Alcohol Market
Alcoholic Beverages
Global Malted Barley Market
Alcoholic Beverages
Apple Wine Market
Alcoholic Beverages
UAE Alcohol E-Commerce Market
Alcoholic Beverages
Roasted Malt Market
Alcoholic Beverages
RTD Bottled Cocktails Market
Alcoholic Beverages
Premix Bottled Cocktails Market
Alcoholic Beverages
Bottled Craft Beer Market
Alcoholic Beverages
Australia Alcohol E-Commerce Market
Alcoholic Beverages
Global Bourbon Market
Alcoholic Beverages
North America Soju Market
Alcoholic Beverages
Russia Tequila Market
Alcoholic Beverages
Low Alcohol Beverages Market
Alcoholic Beverages
Wine Enzymes Market
Alcoholic Beverages
Global Distillation System Market