
 Pentanedione Market | 2026-2036
Pentanedione Market Size, Share, and Industry Trends Forecast 2026-2036
Pentanedione Market Analytics
REACH compliance is realigning the cost-of-entry calculus for European pentanedione suppliers, forcing purification upgrades that favor capital-rich producers. BASF SE leverages its integrated Ludwigshafen complex to sustain high-purity acetylacetone output under tightening ECHA thresholds. Eastman Chemical Company anchors North American supply through Kingsport manufacturing scale, while Wacker Chemie AG dominates silicone-crosslinker applications with specialized 2,4-pentanedione grades.
Pentanedione refers to dialkyl ketones with two carbonyl groups separated by a single methylene unit, where 2,4-pentanedione (acetylacetone) exhibits a boiling point of 140°C and enol content exceeding 80% in neat form, serving primarily as a bidentate ligand for metal chelation and as a synthetic intermediate in heterocyclic chemistry. Acetylacetone leads product type revenue due to its unmatched versatility across pharmaceutical metal coordination and catalyst precursors, while 3-pentanedione represents the fastest-growing flavoring agent segment as clean-label dairy and butter notes displace synthetic alternatives in food and beverages. Coatings applications concentrate margin pools in high-performance automotive refinish formulations where diketone solvency controls flash time and film clarity.
EPA oversight under TSCA governs pentanedione manufacturing thresholds and emission controls in the United States, while ECHA's REACH Annex XVII restrictions limit residual solvent content in consumer-facing formulations across Europe. China's MEE enforces GB standards on volatile organic compound emissions from diketone production facilities in Shandong and Jiangsu provinces. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether centralized or regionalized purification investments offer superior risk-adjusted returns.
Market Dynamics
REACH Annex XVII solvent restrictions are compressing European production margins while China's Shandong province concentrates diketone supply chains, creating a bifurcated cost structure between compliance-heavy and volume-driven manufacturing zones.
Growth Catalysts
- Pharmaceutical metal chelation therapies:Acetylacetone demand from oncology and diagnostic imaging formulators is pulling high-purity grades into clinical-scale production pipelines.
- REACH solvent purity mandates:ECHA thresholds for residual diketones in consumer formulations are locking in premium pricing for certified European suppliers.
- Shandong chemical cluster expansion:Bulk acetylacetone output from China's provincial industrial zones is feeding agrochemical formulators across East Asia.
Market Restraints
- Acetone feedstock volatility:Crude acetone pricing swings directly compress diketone producer margins, with no viable alternative feedstock at scale.
- Shandong supply concentration:Overreliance on China's eastern coastal chemical parks exposes buyers to regional environmental shutdowns and logistics bottlenecks.
- Enol tautomer instability:Acetylacetone's equilibrium-sensitive chemistry limits long-haul shipping distances and storage durations without stabilization investments.
Strategic Opportunities
- India agrochemical formulators:CDSCO registration pathways for metal-complex crop protection intermediates remain underpenetrated by established diketone suppliers.
- Silicone crosslinker grade specialization:2,4-pentanedione purity tiers above 99.5% for electronics-grade silicone curing command technical premiums in semiconductor fabrication.
- EU Green Deal bio-based solvents:ECHA recognition of fermentation-derived diketone alternatives opens regulatory-fast-tracked positioning for sustainable chemistry investments.
Industry Challenges
- Specialized chemical engineering talent:Keto-enol equilibrium process control expertise is scarce, slowing capacity ramp-ups at new production facilities.
- Multi-jurisdiction certification timelines:Parallel EPA TSCA pre-manufacture notifications and ECHA REACH dossier preparations extend product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pentanedione Market |
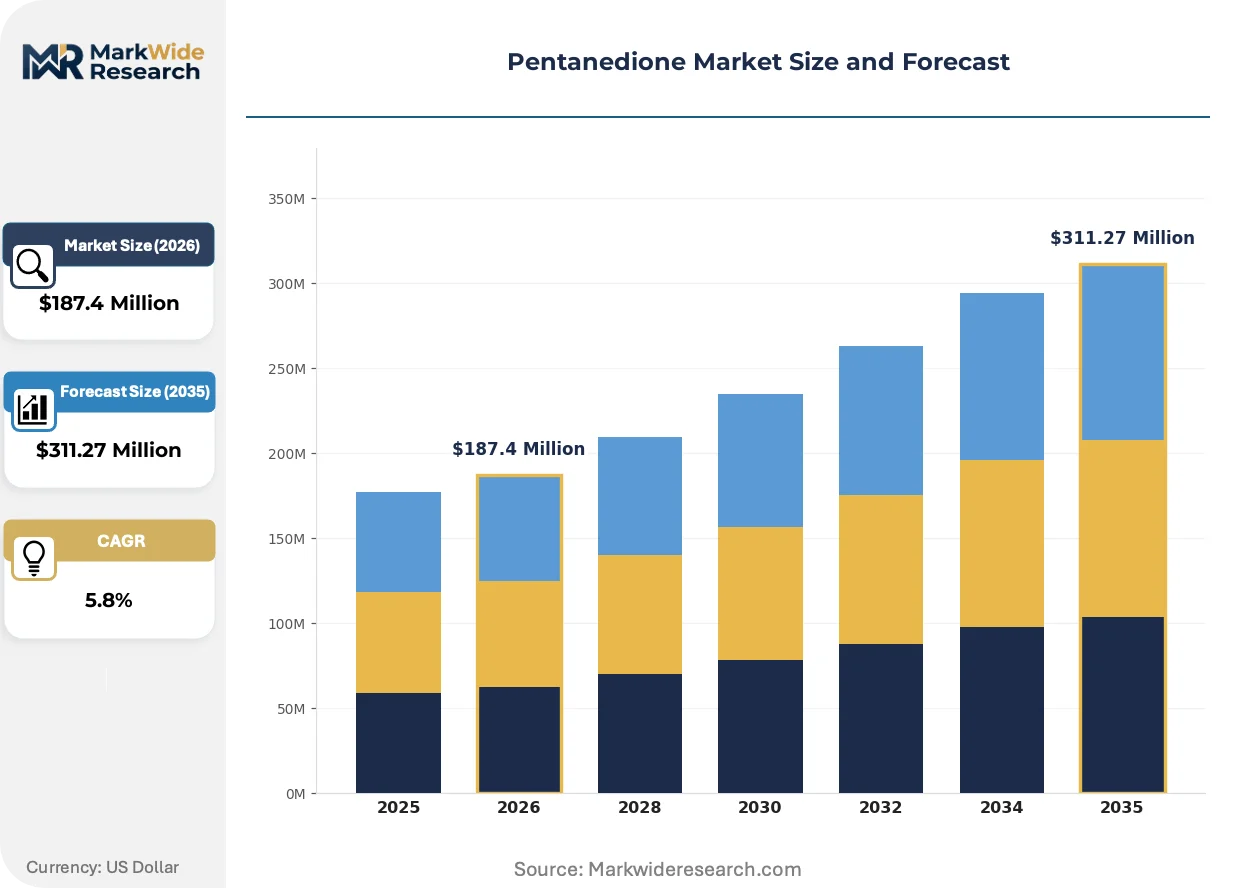
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acetylacetone, 3-Pentanedione, 2-Pentanone, 4-Pentanone End Use Industry: Pharmaceuticals, Agrochemicals, Food & Beverages, Coatings Distribution Channel: Online Retail, Distributors, Direct Sales, Wholesale Application: Solvent, Intermediate, Flavoring Agent, Ligand |
| Companies Covered | Anhui Fubore Pharmaceutical & Chemical, Eastman Chemical Company, Wacker Chemie AG, Dow Inc., BASF SE, Nouryon, Anhui Wotu Chemical, Arkema S.A., Anmol Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pentanedione Market Evolving Landscape
Process intensification and regulatory chemistry are restructuring how pentanedione is manufactured, purified, and specified across pharmaceutical, coatings, and electronics supply chains.
Continuous flow reactor technology for acetylacetone synthesis is modularizing production economics, enabling pharmaceutical-grade manufacturers to downscale batch volumes without sacrificing purity consistency. Specialty chemical producers in Germany and Switzerland are piloting these systems for on-demand metal chelator output. The technology is compressing minimum efficient scale thresholds and allowing regionalized supply hubs to serve fragmented pharmaceutical demand.
ECHA's 2023 updates to REACH Annex XVII residual solvent limits are forcing reformulation of consumer-facing coatings and adhesives, with diketone content caps tightening in skin-contact applications. Automotive refinish formulators in France and Italy are accelerating substitution testing for flash-time control solvents. The regulatory pressure is segmenting the market into industrial-grade and consumer-grade purity tiers with diverging certification requirements.
Specification-driven procurement is consolidating buyer power among large pharmaceutical and agrochemical formulators, with annual contract volumes replacing spot-market purchases for acetylacetone supply security. Distributors in the Netherlands and Singapore are losing intermediation share to direct manufacturer relationships. This concentration is most visible in North American and European pharmaceutical procurement, where qualified supplier lists have narrowed to three-to-four approved vendors per major formulator.
Pentanedione Market Segmentation
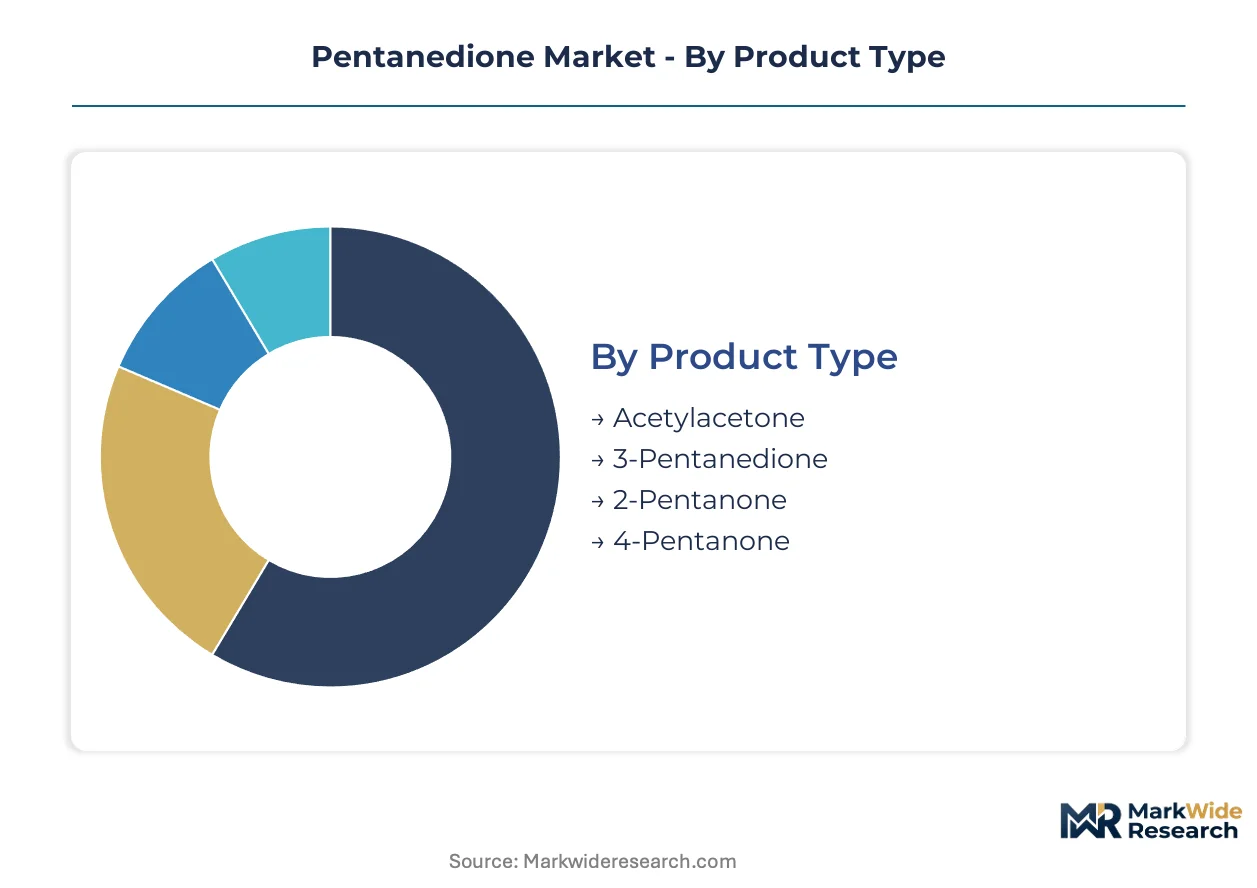
Pentanedione chemistry fragments into distinct specification tiers, each commanding divergent purity premiums and regulatory certification burdens. Pharmaceutical formulators and agrochemical producers source from entirely different supply pools based on metal chelation performance versus bulk solvent economics.
Product Type:
Specification purity and enol stability separate commercial grades, with pharmaceutical ligand applications demanding sub-ppm impurity thresholds that general industrial solvents cannot satisfy.
- Acetylacetone:This 2,4-diketone exists as an equilibrium mixture exceeding 80% enol tautomer in neat form, delivering bidentate coordination geometry essential for platinum-group catalyst precursors. Oncology metal chelation therapies in Ludwigshafen and Basel manufacturing clusters pull pharmaceutical-grade output under tightening ECHA residual solvent mandates.
- 3-Pentanedione:The symmetric 2,3-diketone structure produces clean-label butter and dairy flavor notes without synthetic additive classification. Clean-label beverage reformulations in France and Italy are climbing the fastest as FSSAI and FDA natural flavoring recognition expands addressable formulation space.
- 2-Pentanone:This methyl ketone serves as a lower-cost co-solvent in industrial coatings where flash-time control requirements are less stringent.
- 4-Pentanone:The dialkyl ketone finds niche use in specialty adhesive formulations requiring intermediate volatility between acetone and higher diketones.
Acetylacetone leads on scale; 3-pentanedione leads on momentum.
End Use Industry:
Customer procurement patterns split between qualified-supplier pharmaceutical protocols and spot-market agrochemical purchasing, creating divergent margin architectures across end-use segments.
- Pharmaceuticals:Metal chelation therapies for diagnostic imaging and oncology require 99.5%+ purity grades with full EMA and FDA Drug Master File documentation. BASF SE and Eastman Chemical Company anchor qualified supplier lists through dedicated pharmaceutical-grade production lines.
- Agrochemicals:Shandong province bulk chemical clusters supply metal-complex intermediates for fungicide and herbicide formulators across East Asia under MEE GB emission standards.
- Food & Beverages:Natural flavoring agent demand concentrates in European dairy and confectionery applications where EFSA clean-label recognition drives substitution from synthetic alternatives.
- Coatings:Automotive refinish formulations in Germany and Japan specify diketone solvency for controlled flash time and optical clarity in premium clearcoat systems.
Pharmaceuticals command the steepest purity premiums; agrochemicals drive absolute volume throughput.
Distribution Channel:
Channel selection tracks shipment scale and certification complexity, with direct relationships displacing intermediaries where technical documentation requirements are most intensive.
- Direct Sales:Pharmaceutical and electronics-grade silicone crosslinker customers mandate batch-specific certificates of analysis and stability data. Manufacturers in Germany and Switzerland maintain dedicated technical service teams for qualified account management.
- Distributors:Regional chemical distributors in the Netherlands and Singapore aggregate fragmented coatings and agrochemical demand, though their intermediation share is compressing under specification-driven procurement consolidation.
- Online Retail:Laboratory-scale quantities for research institutions and pilot-scale pharmaceutical development move through specialized chemical e-commerce platforms with hazardous material shipping compliance.
- Wholesale:Bulk industrial-grade pentanedione for coatings and adhesive formulators transacts through commodity chemical wholesalers with volume-based pricing tiers.
Direct sales capture the highest technical-margin accounts; wholesale channels dominate tonnage movement.
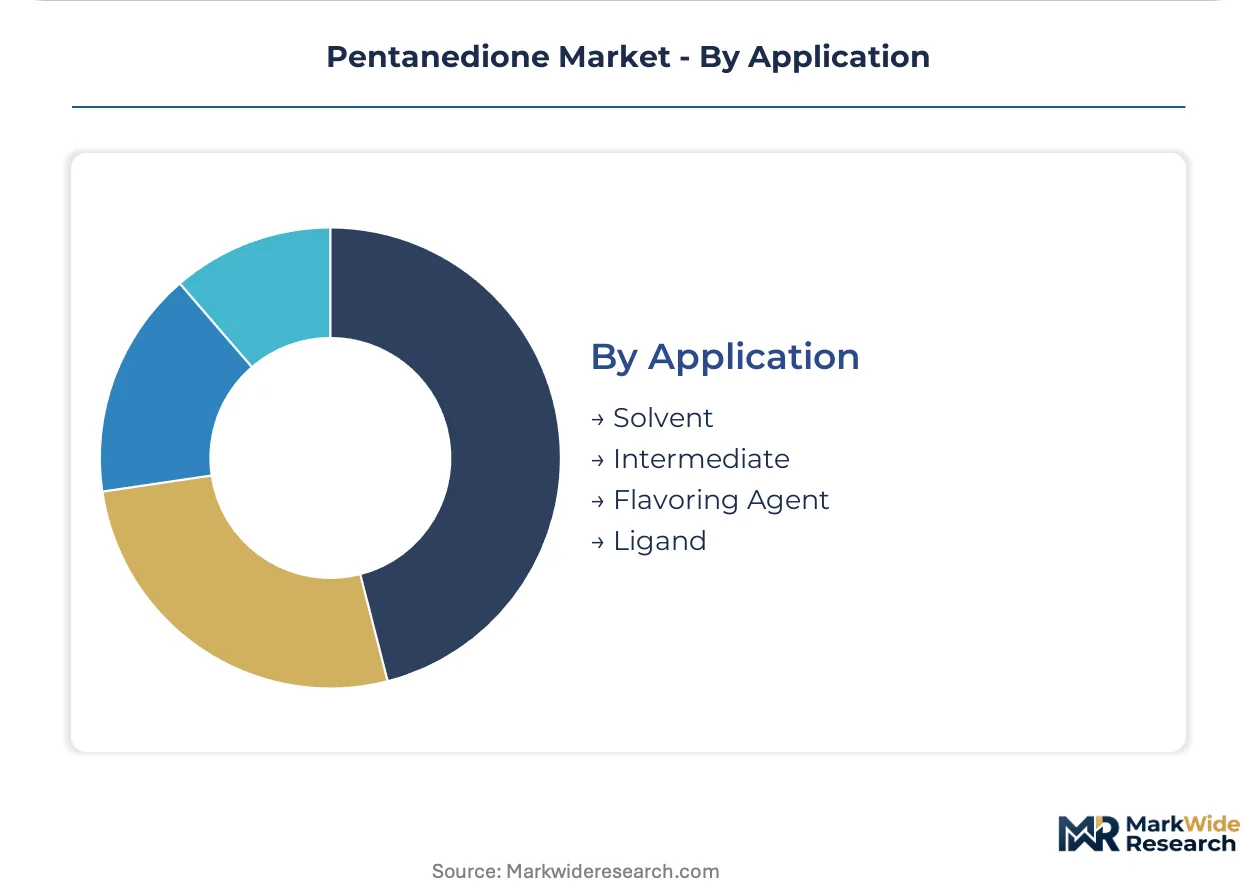
Application:
Functional role determines purity specification and regulatory pathway, with ligand applications facing the most stringent metal content and residual impurity thresholds.
- Ligand:Bidentate coordination chemistry for MRI contrast agents and platinum anticancer drugs demands sub-ppm transition metal contamination limits. EMA and FDA chemistry, manufacturing, and controls documentation requirements extend qualification timelines.
- Intermediate:Heterocyclic synthesis feedstock for pyrazole and pyrimidine agrochemical actives operates under less stringent purity protocols, with Shandong bulk producers satisfying cost-sensitive procurement.
- Solvent:Coatings and adhesive formulations utilize diketone solvency for controlled evaporation profiles, though REACH Annex XVII and TSCA emission controls are forcing reformulation testing in skin-contact applications.
- Flavoring Agent:3-pentanedione natural flavoring status under EFSA and FDA regulations positions the segment for clean-label expansion, with fermentation-derived alternatives gaining EU Green Deal regulatory preference.
Ligand applications command the steepest certification barriers; flavoring agent deployment is expanding most quickly through natural product positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized chemical engineering talent concentrates in Germany's Rhine corridor and China's Shandong province, anchoring divergent manufacturing philosophies across compliance-heavy and volume-driven zones.
United States
Pharmaceutical metal chelation demand from oncology and diagnostic imaging formulators pulls high-purity acetylacetone into clinical-scale production. EPA oversight under TSCA governs manufacturing thresholds and emission controls for diketone facilities. The Kingsport manufacturing cluster in Tennessee anchors North American supply through dedicated pharmaceutical-grade production lines.
Germany
REACH Annex XVII solvent restrictions compress margins while locking in premium pricing for certified suppliers meeting ECHA residual diketone thresholds. The Ludwigshafen chemical complex sustains high-purity acetylacetone output through integrated production economics. BASF SE leverages this infrastructure to serve qualified supplier lists for EMA-documented pharmaceutical formulators.
China
Bulk acetylacetone output from Shandong province feeds agrochemical formulators across East Asia under MEE GB emission standards. The province's chemical clusters concentrate diketone supply chains, exposing buyers to regional environmental shutdown risks. Shandong bulk producers satisfy cost-sensitive procurement for metal-complex fungicide and herbicide intermediates.
India
CDSCO registration pathways for metal-complex crop protection intermediates remain underpenetrated by established diketone suppliers. FSSAI recognition of 3-pentanedione natural flavoring status expands addressable formulation space for clean-label dairy applications. Maharashtra and Gujarat pharmaceutical clusters generate qualified-supplier demand for documented acetylacetone ligand supply.
Switzerland
Specialty chemical producers pilot continuous flow reactor technology for on-demand pharmaceutical-grade output. Swissmedic documentation requirements align with EMA chemistry, manufacturing, and controls standards for metal chelation therapies. Basel manufacturing clusters pull sub-ppm purity grades for platinum-group catalyst precursors in oncology applications.
Pentanedione Market Competitive Landscape
The competitive structure tilts toward integrated chemical conglomerates with captive acetone feedstock and dedicated pharmaceutical-grade purification assets. Three tiers separate capital-rich European suppliers from Shandong bulk producers and specialty silicone-crosslinker specialists. Dominant competitive moves include backward integration into acetone supply and geographic expansion through qualified supplier list penetration.
Within the integrated conglomerate tier, BASF SE and Eastman Chemical Company exemplify archetypes of compliance-heavy and scale-driven manufacturing philosophies respectively. Wacker Chemie AG occupies a specialized position in electronics-grade silicone crosslinker applications. Among China-based producers, Anhui Fubore Pharmaceutical & Chemical and Anhui Wotu Chemical represent the Shandong province bulk chemical cluster model serving regional agrochemical formulators.
| Leading Market Players |
|---|
| Anhui Fubore Pharmaceutical & Chemical |
| Eastman Chemical Company |
| Wacker Chemie AG |
| Dow Inc. |
| BASF SE |
| Nouryon |
| Anhui Wotu Chemical |
| Arkema S.A. |
| Anmol Chemicals |
| Others |
Value Network & Pricing Analysis
Pharmaceutical-grade versus industrial-grade purity bifurcation splits pentanedione pricing into disconnected tiers, with ECHA-certified acetylacetone commanding technical premiums while Shandong bulk output feeds spot-market agrochemical procurement. This divergence concentrates pricing power among Ludwigshafen and Basel producers who control qualified supplier list access, while acetone feedstock volatility compresses margins for volume-driven manufacturers lacking captive raw material supply.
Pricing Analysis
Bundled technical service contracts dominate pharmaceutical-grade procurement, where batch-specific certificates of analysis and stability documentation justify premium positioning over unbundled commodity spot transactions. Three-tier pricing structure across pharmaceutical, industrial, and flavoring grades tracks certification burden and enol stability requirements. Cost compression in industrial coatings solvents intensifies as REACH Annex XVII reformulation testing accelerates substitution evaluation. Agrochemical formulators exhibit highest price sensitivity, while oncology metal chelation therapy developers accept steep premiums for documented purity.
Supply Chain Analysis
Reverse-logistics considerations are minimal for pentanedione given its chemical instability, though enol tautomer degradation drives just-in-time delivery requirements that reshape inventory positioning. Supply concentrates in Germany, China, and the United States, with Shandong province chemical clusters anchoring bulk agrochemical feedstock output. Production draws from crude acetone and diketene intermediates, with no viable alternative feedstock at commercial scale. Single-source vulnerability concentrates in Shandong environmental compliance shutdowns. Distribution runs through direct manufacturer relationships for pharmaceutical grades and regional chemical distributors for industrial volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pentanedione demand functions as a regulatory compounder where ECHA REACH Annex XVII residual solvent mandates lock in premium pricing for certified European suppliers and accelerate substitution testing across consumer-facing formulations.
For Market Incumbents: Anchor qualified supplier list positions through dedicated pharmaceutical-grade production lines and EMA Drug Master File documentation investments. BASF SE's Ludwigshafen integration exemplifies defensive positioning against Shandong bulk producer price pressure. Backward integration into acetone supply secures margin control against feedstock volatility. Certification investment in silicone crosslinker grades above 99.5% purity defends technical premium capture in semiconductor fabrication applications. For New Entrants and Emerging Players: CDSCO-registered agrochemical formulators in India represent an underserved buyer archetype with limited established diketone supplier penetration. Fermentation-derived bio-based alternatives for EU Green Deal regulatory preference offer white-space positioning in sustainable chemistry. Direct technical service relationships with Maharashtra and Gujarat pharmaceutical clusters provide the most penetrable go-to-market angle against entrenched European qualified supplier lists. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH compliance investments favor capital-rich producers with integrated purification assets over standalone Shandong bulk operators. Long-term viability favors pharmaceutical-grade specialists with EMA and FDA documentation capabilities and captive acetone supply. Acquisition target archetype: mid-cap European producers with underutilized pharmaceutical-grade capacity and established qualified supplier relationships. Monitor ECHA solvent restriction expansion timelines as inflection indicator for premium tier demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acetone Supply | Captive feedstock secures margin control against crude acetone price volatility for Ludwigshafen-scale producers. |
| Pharmaceutical-Grade Purification Investment | Sub-ppm metal contamination limits unlock EMA-qualified supplier list access for oncology ligand applications. |
| Continuous Flow Reactor Deployment | Modular production economics enable regionalized pharmaceutical-grade supply hubs without batch scale sacrifice. |
| Silicone Crosslinker Grade Specialization | Electronics-grade 99.5%+ purity tiers command technical premiums in semiconductor fabrication curing applications. |
| Bio-Based Fermentation Pathway Development | EU Green Deal regulatory preference accelerates positioning for sustainable diketone alternatives in consumer formulations. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with pharmaceutical procurement managers, agrochemical formulators, coatings R&D directors, and chemical distribution channel partners with secondary validation from ECHA REACH dossier filings, FDA Drug Master File databases, customs trade data, and SEC 10-K disclosures from listed chemical producers. Bottom-up volume modeling and top-down value reconciliation triangulated segment outputs.
Segment-weighting approaches distributed pentanedione demand across purity grade tiers, end-use industry verticals, and regional production hub clusters throughout the forecast period. CAGRs derived from historical trajectory analysis and regulatory demand elasticity modeling incorporated acetone feedstock price correlation, REACH compliance cost pass-through coefficients, and Shandong capacity utilization assumptions.
Underlying measurement precision varies by segment; pharmaceutical-grade volumes carry tighter precision than agrochemical spot-market estimates given qualified supplier list visibility. Forecasts reflect documented assumptions on ECHA regulatory expansion timelines and Shandong environmental enforcement intensity. Practitioners should monitor ECHA Annex XVII solvent restriction updates and Shandong province MEE inspection schedules for early demand shift signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Aerosol Insecticides Market
Chemicals
Global P-Phenylenediamine Market
Chemicals
Lanthanum Nitrate Market
Chemicals
Potassium Iodide Market
Chemicals
Natural Fatty Alcohols Market
Chemicals
Asia Pacific Waterproofing Chemicals Market
Chemicals
Africa Sodium Cyanide Market
Chemicals
Deicing Fluid Market
Chemicals
Sodium Cyanide Market
Chemicals
Diethylenetriamine (DETA) Market
Chemicals
Power Plant Chemicals Market
Chemicals
Leather Tanning Chemicals Market
Chemicals
(S)-(+)-2-Amino-1-Propanol Market
Chemicals
Aluminum Phosphide Market
Chemicals
SLS and LABSA Market
Chemicals
Phosphorus Pentasulfide (P2S5) Market