
 China Vegetable Seed Market | 2026-2036
China Vegetable Seed Market Size, Share, and Industry Trends Forecast 2026-2036
China Vegetable Seed Market Analysis
The seed distribution channel is rewriting competitive access across China's vegetable belt. Syngenta Group leverages its global breeding network to supply hybrid tomato and pepper varieties to commercial farms. Yuan Longping High-Tech Agriculture anchors domestic research with its rice-breeding heritage now extending into vegetable germplasm. Beidahuang Kenfeng Seed Co Ltd dominates northern supply chains through its Heilongjiang production base and state-farm relationships.
China vegetable seed comprises genetically stable or hybridized propagules bred for specific agronomic traits including disease resistance, uniformity, and yield potential, with hybrid seeds requiring controlled pollination between inbred parental lines to exploit heterosis for commercial field performance. The hybrid segment leads value capture due to farmer willingness to pay for performance consistency, while open-pollinated varieties retain share in home garden and subsistence channels where seed-saving reduces input costs. Leafy greens command the largest crop category volume as bok choy and spinach rotation intensity rises in protected cultivation systems across the Yangtze Delta.
China's Ministry of Agriculture and Rural Affairs enforces GB standards for seed germination rates and genetic purity, while NMPA regulates biotech trait approvals and import quarantine protocols for foreign germplasm. These frameworks elevate compliance costs for offshore breeders but create protected terrain for domestic players with established variety registration portfolios. Stakeholders must monitor how China's seed law revisions and dual carbon goals for agriculture reshape R&D incentives and cross-border licensing terms.
Market Dynamics
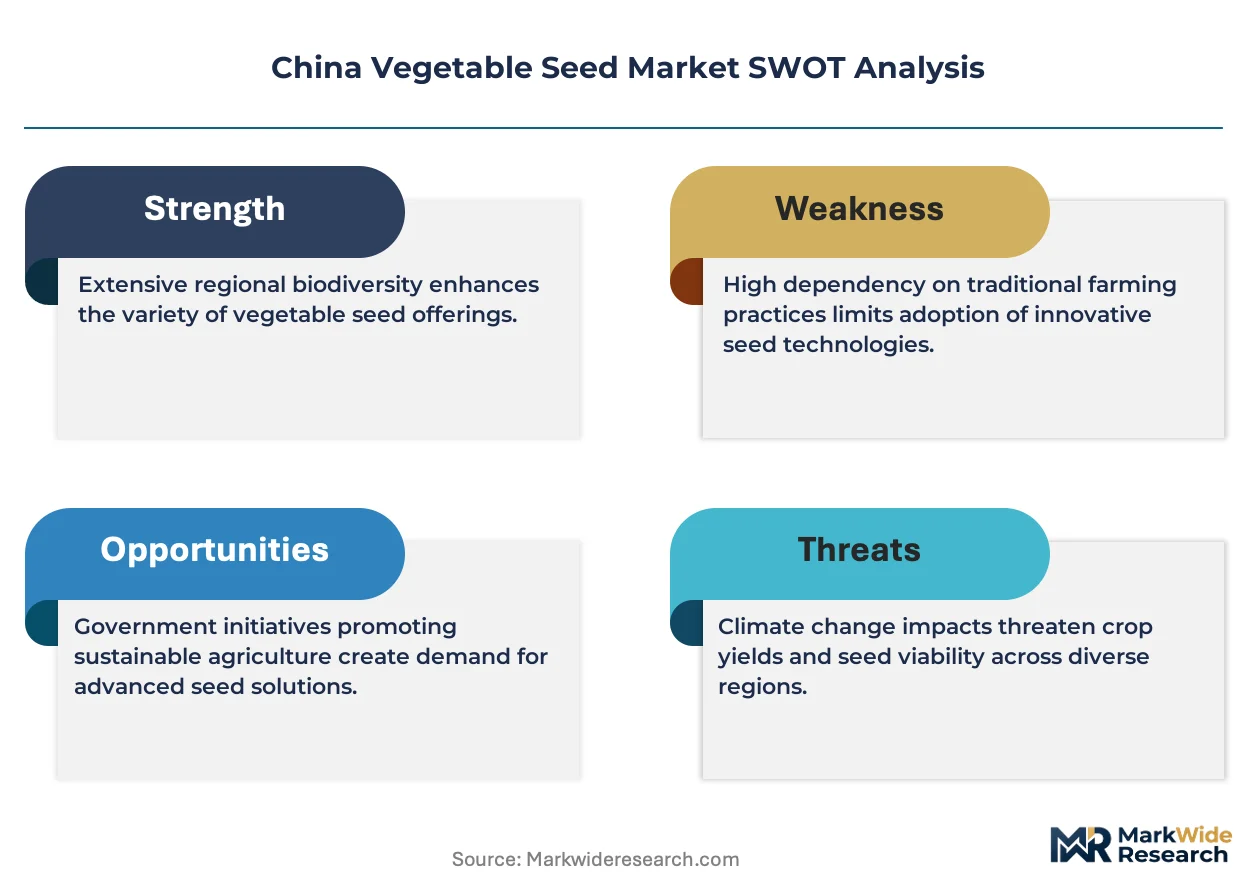
China's vegetable seed market is restructuring around the tension between NMPA's tightening germplasm import quarantine protocols and domestic breeders' push to capture commercial greenhouse procurement. State-farm consolidation and protected cultivation expansion are compressing traditional distribution layers.
Growth Catalysts
- Dual carbon goals for agriculture:Beijing's emission-reduction mandates for intensive farming are accelerating demand for climate-adaptive hybrid varieties with improved water-use efficiency and reduced fertilizer dependency.
- Commercial greenhouse expansion:Shandong Province's intensive vegetable production belt is driving procurement of disease-resistant hybrid tomato and pepper seeds as operators scale protected cultivation acreage.
- GB standards enforcement:China's national seed quality standards are elevating germination rate and genetic purity requirements, forcing market exit of substandard suppliers and concentrating volume with compliant domestic and foreign breeders.
Market Restraints
- Import quarantine friction:NMPA's extended approval timelines for foreign germplasm introduction are creating supply bottlenecks for offshore breeders seeking to introduce novel traits into China.
- Parental line concentration:Hybrid seed production depends on concentrated sourcing of inbred parental lines from specific temperate breeding zones, exposing supply chains to climatic and geopolitical disruption.
- Substitution by farm-saved seed:Open-pollinated varieties in home garden and subsistence channels retain share as seed-saving practices reduce recurring input costs for smallholders.
Strategic Opportunities
- Western China expansion:Underpenetrated protected cultivation development in Sichuan and Yunnan provinces offers whitespace for hybrid vegetable seed distribution as infrastructure investment accelerates.
- Biotech trait convergence:Stacking of disease resistance and abiotic stress tolerance traits through marker-assisted selection is creating premium product tiers for commercial farm procurement.
- Direct-to-farm digital channels:E-commerce platforms and agricultural service apps are disintermediating traditional county-level seed distributors, enabling breeder-farmer relationships and variety performance data exchange.
Industry Challenges
- Variety registration backlog:MARA's field trial and DUS testing requirements are extending time-to-market for new hybrids, compressing effective commercial lifecycles before trait obsolescence.
- Skilled breeder scarcity:Domestic talent pipelines in quantitative genetics and molecular breeding are insufficient to match R&D expansion targets of state-backed seed enterprises.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Vegetable Seed Market |
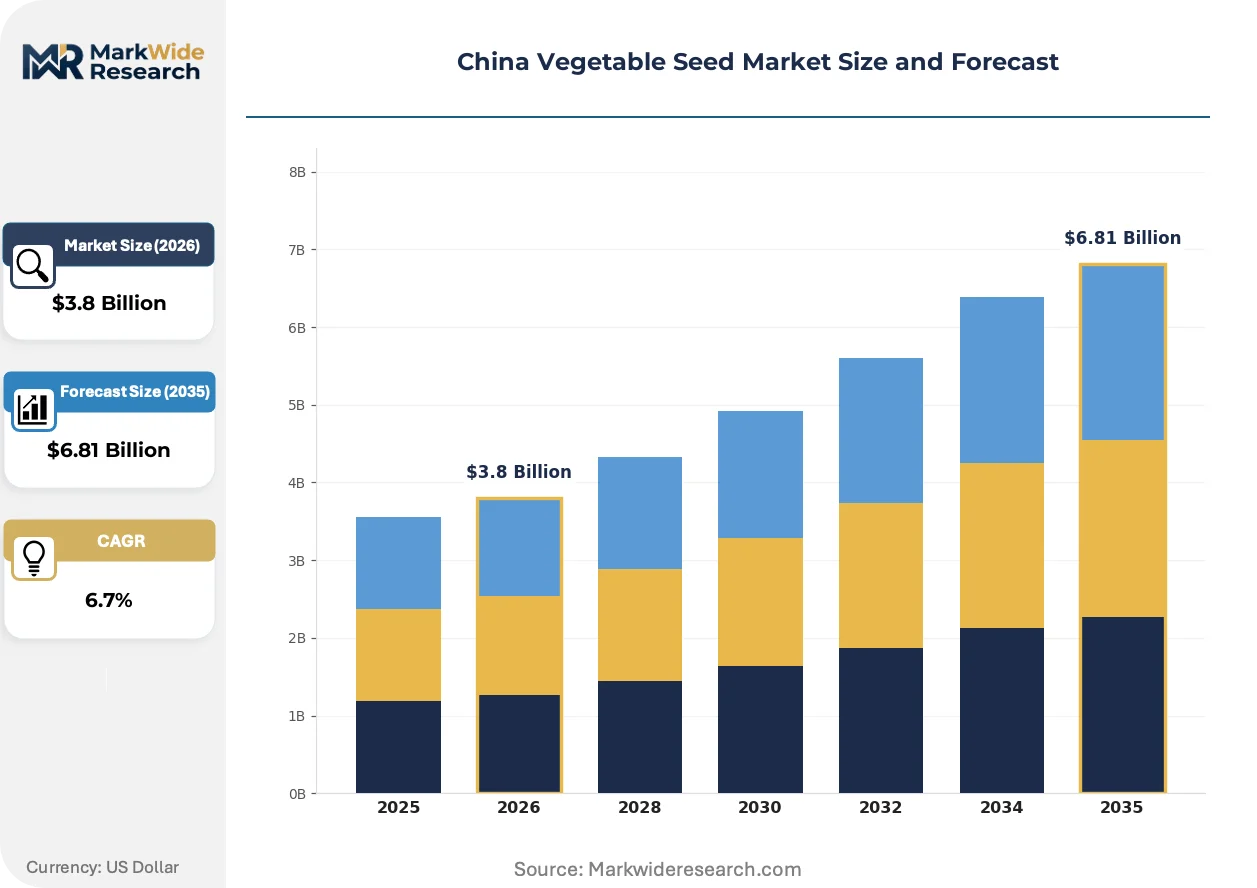
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Seed Type: Hybrid, Open-Pollinated, Heirloom, GMO End Use: Commercial, Home Garden, Research, Export Distribution Channel: Online, Retail, Wholesale, Direct Sales Crop Category: Leafy Greens, Root Vegetables, Legumes, Others |
| Companies Covered | Beidahuang Kenfeng Seed Co Ltd, Rijk Zwaan Zaadteelt en Zaadhandel BV, Syngenta Group, Bejo Zaden BV, Sakata Seeds Corporation, Groupe Limagrain, Anhui Tsuen Yin Hi-Tech Seed Industry Co Ltd, East-West Seed, Yuan Longping High-Tech Agriculture, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Vegetable Seed Market Emerging Trajectories
Biotechnology integration and regulatory recalibration are compressing traditional breeding timelines while digital infrastructure rewires how commercial farms access genetic material. Three developments are restructuring competitive positioning.
Marker-assisted selection is migrating from research stations to commercial breeding programs, enabling rapid pyramiding of quantitative trait loci for disease resistance and yield stability. Shandong and Hebei greenhouse operators are demanding varieties bred through these platforms. The technology is compressing the gap between trait discovery and field deployment.
NMPA's implementation of biotech crop trait approval frameworks is reshaping R&D investment patterns. Offshore breeders face elevated compliance costs for environmental release trials. Domestic players with established variety registration portfolios are capturing protected terrain as foreign germplasm introduction slows.
Commercial farm procurement is consolidating around performance-guaranteed supply contracts rather than spot-market seed purchases. Large greenhouse operators in the Yangtze Delta are negotiating direct breeding service agreements with seed companies. This behavior is most visible in tomato and pepper categories where uniformity premiums justify long-term supplier relationships.
China Vegetable Seed Market Segmentation
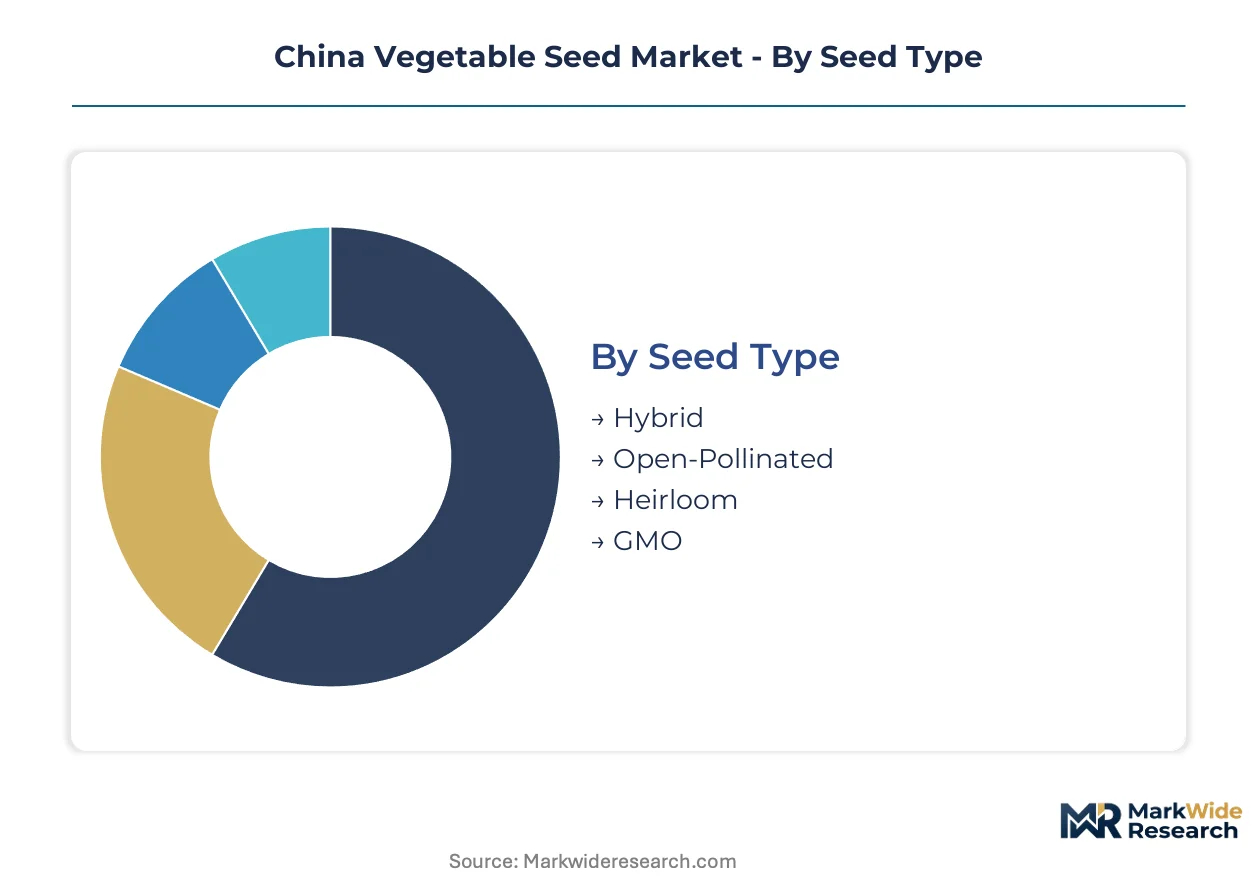
China's vegetable seed market segments along four critical dimensions that determine pricing power, regulatory exposure, and channel strategy. Breeders must align product portfolios with the divergent requirements of commercial greenhouse operators versus subsistence farmers, while navigating NMPA's trait-specific approval pathways.
Seed Type:
Commercial farms demand performance-optimized propagules across the full use-case spectrum from intensive protected cultivation to open-field rotation systems.
- Hybrid:Controlled pollination between inbred parental lines exploits heterosis for disease resistance and yield uniformity. Shandong Province's greenhouse belt drives procurement of hybrid tomato and pepper varieties as operators scale protected cultivation acreage.
- Open-Pollinated:Genetically stable varieties propagated through natural pollination enable farmer seed-saving and reduce recurring input costs. Smallholders in subsistence channels favor these propagules where capital constraints limit hybrid adoption.
- Heirloom:Traditional landrace varieties preserved for regional culinary preferences and genetic diversity. Specialty restaurant supply chains and heritage crop programs in Jiangsu and Zhejiang sustain niche demand.
- GMO:Biotech-enhanced seeds with stacked traits for pest resistance and abiotic stress tolerance. NMPA's extended environmental release trial timelines constrain commercial deployment despite R&D investment.
The dominant share belongs to Hybrid, while GMO is closing the gap fastest pending regulatory pathway clarification.
End Use:
Customer archetypes span capital-intensive commercial operations to research institutions developing climate-adaptive germplasm.
- Commercial:Large-scale greenhouse and open-field operators purchasing performance-guaranteed supply contracts. Yangtze Delta vegetable producers negotiate direct breeding service agreements for tomato and pepper uniformity premiums.
- Home Garden:Urban and peri-urban cultivators selecting open-pollinated varieties for seed-saving economics. E-commerce platforms are disintermediating traditional county-level distributors for this segment.
- Research:Agricultural universities and state-backed breeding institutes conducting germplasm characterization and trait introgression. MARA's field trial requirements extend time-to-market for hybrids developed through these programs.
- Export:Seed companies supplying neighboring markets in Southeast Asia and Central Asia. Heilongjiang production bases leverage state-farm relationships for cross-border distribution.
Commercial procurement commands the largest value pool, though Research channels show the steepest expansion trajectory as domestic breeding capacity scales.
Distribution Channel:
Channel economics reflect the tension between traditional agricultural input networks and platform-based disintermediation.
- Online:Agricultural service apps and e-commerce platforms enabling breeder-farmer direct relationships. Performance data exchange and variety comparison tools accelerate adoption in younger farmer demographics.
- Retail:County-level agricultural supply stores and cooperative distribution points. These channels retain importance for smallholder access in remote production zones.
- Wholesale:Volume procurement by greenhouse consortiums and state-farm aggregators. Shandong and Hebei operators leverage collective bargaining for hybrid seed pricing.
- Direct Sales:Breeder-to-farm contracts with performance guarantees and technical support. Large Yangtze Delta greenhouse operators prefer this channel for high-value tomato and pepper varieties.
Wholesale dominates transaction volume, yet Online is gaining share fastest among commercial farms under forty hectares.
Crop Category:
Rotation intensity and protected cultivation suitability determine category-specific demand patterns across China's vegetable belt.
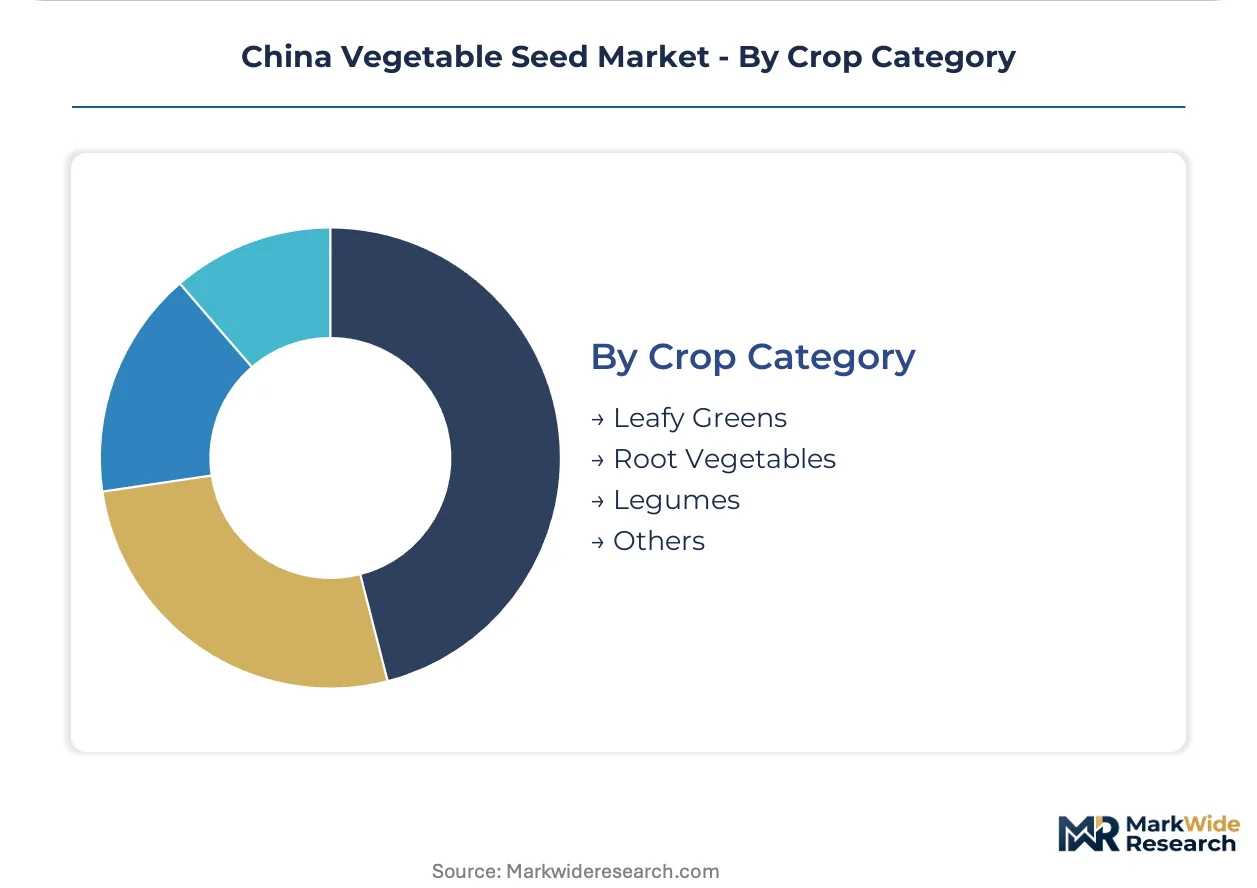
- Leafy Greens:Bok choy, spinach, and amaranth varieties bred for rapid cycling in protected systems. Yangtze Delta greenhouse operators drive volume as rotation frequency intensifies.
- Root Vegetables:Carrot, radish, and turnip seeds optimized for uniform sizing and storage durability. Northern plains production zones favor these for mechanized harvest compatibility.
- Legumes:Bean and pea varieties with nitrogen-fixation traits for soil health integration. Crop rotation programs in Sichuan and Yunnan sustain steady procurement.
- Others:Solanaceous and cucurbit crops including tomato, pepper, and cucumber. These high-value categories justify premium hybrid pricing in commercial greenhouse operations.
Leafy Greens holds the largest volume position, though Others is expanding most quickly as greenhouse tomato and pepper acreage scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Shandong Province's greenhouse belt while western provinces absorb input cost premiums. Yangtze Delta operators negotiate direct breeder contracts unavailable to Sichuan and Yunnan farms. This asymmetry shapes procurement patterns across China's vegetable seed landscape.
Shandong Province
Commercial greenhouse operators in Weifang and Qingdao drive hybrid tomato and pepper seed procurement at volume discounts. GB standards enforcement by MARA elevates germination rate requirements for suppliers serving this cluster. The Shandong Peninsula's protected cultivation belt anchors national pricing benchmarks for high-value solanaceous crops.
Yangtze River Delta
Rotation-intensive bok choy and spinach production in Jiangsu and Zhejiang sustains steady demand for rapid-cycling leafy green varieties. NMPA's variety registration requirements extend time-to-market for new hybrids developed through regional research stations. Shanghai's logistics infrastructure enables just-in-time seed delivery to peri-urban greenhouse complexes.
Sichuan-Chongqing
Emerging protected cultivation development in Chengdu's agricultural satellite counties creates whitespace for hybrid vegetable seed distribution. Provincial infrastructure investment lags coastal benchmarks, elevating logistics costs for breeders. The region's legume rotation programs sustain open-pollinated variety demand among smallholders.
Heilongjiang
State-farm consolidation in the northern plains compresses traditional distribution layers for root vegetable seeds. Beidahuang Kenfeng Seed Co Ltd leverages production base proximity to supply mechanized harvest-compatible carrot and radish varieties. Cross-border distribution into Central Asian markets utilizes established rail corridors through Manzhouli.
Western China
Yunnan's high-altitude greenhouse zones attract disease-resistant hybrid trials for abiotic stress tolerance validation. Dual carbon goals for agriculture accelerate climate-adaptive variety demand in underpenetrated production areas. Kunming's seed testing facilities support regional germplasm characterization programs.
China Vegetable Seed Market Vendor Landscape
Global breeding networks and domestic state-backed enterprises split the market into complementary competitive spheres. Foreign players with established variety registration portfolios navigate NMPA's extended approval timelines while capturing premium greenhouse contracts. Domestic specialists leverage production base proximity and state-farm relationships for volume positioning. Consolidation pressures concentrate around direct-to-farm digital channels and performance-guaranteed supply contracts.
Within the multinational tier, Syngenta Group and Rijk Zwaan Zaadteelt en Zaadhandel BV occupy positions defined by global germplasm access and hybrid development platforms. Yuan Longping High-Tech Agriculture anchors domestic research capacity with rice-breeding heritage extending into vegetable germplasm. Beidahuang Kenfeng Seed Co Ltd exemplifies state-farm-integrated supply chain control through its Heilongjiang production base. These three represent the archetype spectrum from global technology access to domestic distribution dominance.
| Leading Market Players |
|---|
| Beidahuang Kenfeng Seed Co Ltd |
| Rijk Zwaan Zaadteelt en Zaadhandel BV |
| Syngenta Group |
| Bejo Zaden BV |
| Sakata Seeds Corporation |
| Groupe Limagrain |
| Anhui Tsuen Yin Hi-Tech Seed Industry Co Ltd |
| East-West Seed |
| Yuan Longping High-Tech Agriculture |
| Others |
Supply Flow & Price Mechanics
The Beijing-Manzhouli rail corridor's freight cost dynamics compress margins for hybrid seed shipments from Heilongjiang production bases while amplifying price differentiation between coastal greenhouse operators and western inland buyers. NMPA's extended germplasm quarantine timelines concentrate supply leverage with domestic breeders holding registered variety portfolios, forcing offshore competitors to absorb compliance premiums or cede volume in Shandong's procurement clusters.
Pricing Analysis
The customization-premium spread between direct breeder contracts and spot-market procurement runs wide in China's vegetable seed trade. Commercial greenhouse operators in the Yangtze Delta negotiate performance-guaranteed supply agreements with embedded technical support, while smallholders in Sichuan and Yunnan purchase open-pollinated varieties through county-level retail channels at lower unit economics. Price differentiation hinges on genetic purity certification under GB standards and volume scale thresholds that trigger collective bargaining power. Pricing pressure intensifies as domestic breeders expand hybrid production capacity, compressing import-dependent premium tiers. Research institutions show least price sensitivity due to grant-funded procurement, while subsistence farmers exhibit highest elasticity to input cost fluctuations.
Supply Chain Analysis
Export-control regimes on advanced biotech germplasm restrict flows from Dutch and Japanese breeding networks into China, elevating domestic R&D investment as a supply chain hedge. Parental line production concentrates in the Netherlands, Japan, and China's Heilongjiang corridor, with climatic suitability dictating inbred sourcing geography. Raw material dependencies include controlled-environment greenhouse infrastructure, precision pollination labor pools, and molecular marker laboratory capacity. Single-source vulnerability concentrates around temperate-zone parental line multiplication sites exposed to extreme weather disruption. Distribution runs through state-farm aggregators and emerging agricultural service apps that disintermediate traditional county-level seed cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's vegetable seed market constitutes a high-growth disruption as NMPA's biotech trait approval frameworks recalibrate competitive access and compress breeding-to-market timelines for domestic players.
For Market Incumbents: Pre-empt regulatory capture by accelerating variety registration portfolio expansion ahead of seed law revisions. Deepen backward integration into parental line production across Heilongjiang and Shandong breeding stations to reduce import dependency exposure. Lock in direct-to-farm digital channel partnerships with greenhouse consortiums before platform-based disintermediation consolidates. For New Entrants and Emerging Players: Pursue whitespace in Sichuan and Yunnan protected cultivation development where infrastructure investment lags coastal benchmarks but provincial subsidy programs accelerate adoption. Target legume rotation programs and high-altitude abiotic stress tolerance trials as underpenetrated entry points. Deploy agricultural service app integration as primary go-to-market vector to bypass entrenched county-level distributor networks. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors domestic breeders with established NMPA registration portfolios and molecular breeding platform deployment. Long-term viability centers on entities capable of stacking disease resistance and climate-adaptive traits through marker-assisted selection. Acquisition targets should demonstrate field trial execution speed and state-farm relationship depth. Watch NMPA's environmental release trial timeline compression as the critical inflection signal for foreign germplasm re-entry feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Parental Line Production Expansion | Captive inbred sourcing reduces exposure to NMPA import quarantine friction and climatic disruption in temperate breeding zones. |
| Direct-to-Farm Digital Channel Development | Agricultural service apps enable breeder-farmer data exchange that accelerates variety performance validation and procurement consolidation. |
| Marker-Assisted Selection Platform Investment | Rapid trait pyramiding compresses time-to-market for disease-resistant hybrids demanded by Shandong greenhouse operators. |
| Western China Distribution Infrastructure | Sichuan and Yunnan whitespace capture depends on logistics investment ahead of provincial protected cultivation scaling. |
| Biotech Trait Registration Pipeline | NMPA approval pathway navigation determines competitive access to premium greenhouse contracts as regulatory frameworks mature. |
Methodological Framework
A standing panel of commercial greenhouse operators, seed company breeding directors, agricultural extension officers, and NMPA regulatory affairs specialists provided ongoing calibration across the primary research phase. This practitioner input was cross-referenced with secondary validation from MARA variety registration databases, GB standards documentation, customs germplasm import records, and provincial agricultural statistical yearbooks. Bottom-up triangulation across distributor shipment records and top-down reconciliation with greenhouse acreage expansion data anchored volume estimates.
Scenario-bracketing around NMPA approval timeline variants and dual carbon policy implementation intensity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include seed type, crop category, distribution channel, and end-use archetype, with regional production cluster differentiation as an industry-specific overlay. CAGRs were derived from trend extrapolation of breeder capacity expansion, greenhouse infrastructure investment pipelines, and farmer willingness-to-pay evolution for hybrid performance premiums. Forecast inputs incorporated parental line multiplication yield volatility and provincial subsidy program disbursement trajectories.
Sensitivities concentrate around NMPA regulatory recalibration, extreme weather disruption in temperate parental line zones, and acceleration of farm-saved seed substitution in smallholder channels. Forecasts reflect assumptions on germplasm import pathway stability and state-farm consolidation velocity. Material shifts in biotech trait approval timelines or provincial infrastructure investment commitments would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Asia-Pacific Rice Seed Market
Seeds
Celery Seed Oil Market
Seeds
Psyllium Seed Market
Seeds
Punnet Market
Seeds
Sweet Corn Seeds Market
Seeds
Cucumber Seeds Market
Seeds
Philippines Hybrid Rice Seed Market
Seeds
Europe Seed Market
Seeds
Vegetable Seed Protein Market
Seeds
Europe Quinoa Seed Market
Seeds
Bangladesh Seed Market
Seeds
Europe Vegetable Seed Market
Seeds
Global Vegetable Seed Market
Seeds
Europe Grain Seed Market
Seeds
Global Forage Seeds Market
Seeds
Morocco Seed Market