
 Cucumber Seeds Market | 2026-2036
Cucumber Seeds Market Size, Share, and Industry Trends Forecast 2026-2036
Cucumber Seeds Market Insights
Modular seed pack sizing is decoupling volume commitments from smallholder budgets across emerging growing regions. Bayer Crop Science leverages its trait integration pipeline to anchor premium hybrid offerings in protected-culture systems. Sakata Seed Corporation specializes in parthenocarpic lines that dominate greenhouse supply chains. Rijk Zwaan Zaadteelt en Zaadhandel B.V. competes through varietal breadth that spans continental climate zones.
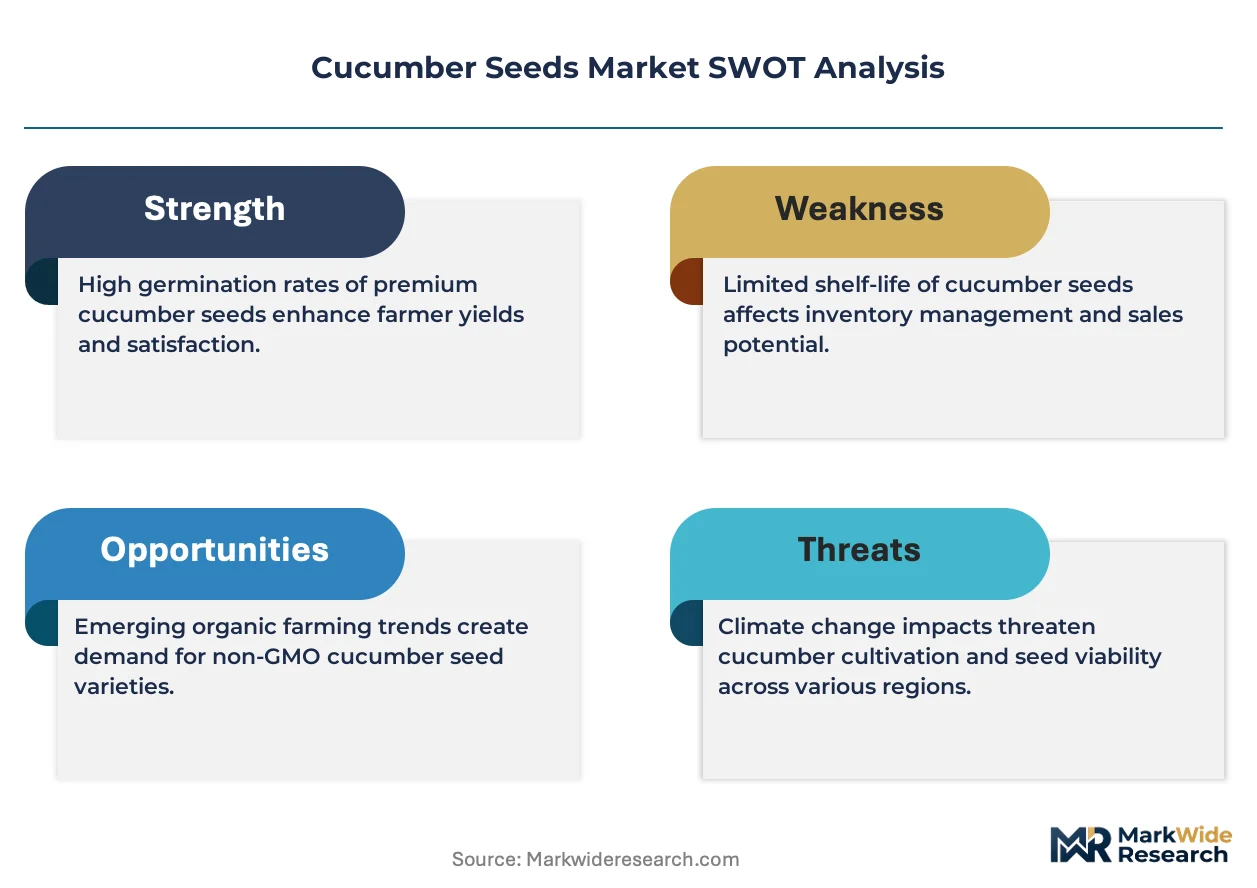
Cucumber seeds are botanically classified as Cucumis sativus propagules, typically ranging from 3-6 millimeters in length with moisture content below 8% for commercial storage viability, bred for determinate or indeterminate growth habits suited to open-field or trellised production environments. Hybrid varieties command the dominant margin pool due to intellectual property protection and yield consistency, while organic-certified seed lines represent the fastest-expanding channel as certification programs tighten allowable inputs. Open-pollinated types sustain heirloom and home-garden segments where seed-saving practices reduce repeat purchase frequency.
EU seed marketing directives enforced by national variety listing authorities shape commercial access, while OECD seed certification schemes govern cross-border quality standards for hybrid lots. The USDA's Plant Variety Protection Office and EPA's pesticide tolerance frameworks jointly influence trait development priorities for North American breeders. Stakeholders must monitor evolving phytosanitary protocols for cross-continental germplasm movement and align R&D portfolios with shifting water-use regulations in drought-prone production zones.
Market Dynamics
Controlled-environment agriculture expansion is restructuring procurement patterns as greenhouse operators consolidate seed purchasing around performance-guaranteed hybrid genetics, compressing open-pollinated varieties into niche home-garden channels.
Growth Catalysts
- EU F-Gas Regulation:Phasedown of hydrofluorocarbon refrigerants accelerates greenhouse infrastructure retrofit cycles, triggering synchronized seed variety upgrades for climate-optimized cultivars.
- Parthenocarpic trait penetration:Seedless cucumber demand in fresh-cut processing chains pulls protected-culture operators toward specialized breeding lines with guaranteed fruit set without pollination.
- Dutch horticulture cluster density:Concentration of glasshouse expertise around Westland and Aalsmeer creates knowledge spillovers that elevate seed quality benchmarks across adjacent Belgian and German growing zones.
Market Restraints
- Hybrid seed cost structure:Parent line maintenance and hand-pollination labor embed 40-60% cost premiums versus open-pollinated alternatives, squeezing smallholder adoption in price-sensitive growing regions.
- Germplasm concentration risk:Narrow genetic bases in commercial hybrid pools increase vulnerability to emerging cucumber downy mildew races, threatening yield stability across Mediterranean and Middle Eastern production belts.
- OECD certification friction:Cross-border seed lot documentation requirements create customs delays for multi-origin breeding programs, particularly affecting just-in-time greenhouse planting schedules.
Strategic Opportunities
- India protected-culture buildout:Subsidy schemes for polyhouse construction under horticulture mission programs create first-mover openings for heat-tolerant parthenocarpic variety introductions.
- Organic certification tailwind:EU Organic Regulation tightening on allowable inputs pushes certified greenhouse operators toward organic-compliant seed lines with documented non-GMO pedigree chains.
- Direct-to-grower digital channels:E-commerce platforms connecting breeders with mid-scale greenhouse operators bypass traditional distributor markups, capturing margin in fragmented Eastern European markets.
Industry Challenges
- Trait integration timelines:Stacking disease resistance with parthenocarpic fruiting extends breeding cycles to 8-12 years, compressing royalty capture windows before varietal obsolescence.
- Phytosanitary documentation complexity:Evolving seed health testing protocols for cucumber green mottle mosaic virus strain differentiation delay shipment releases from multiplication fields.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cucumber Seeds Market |
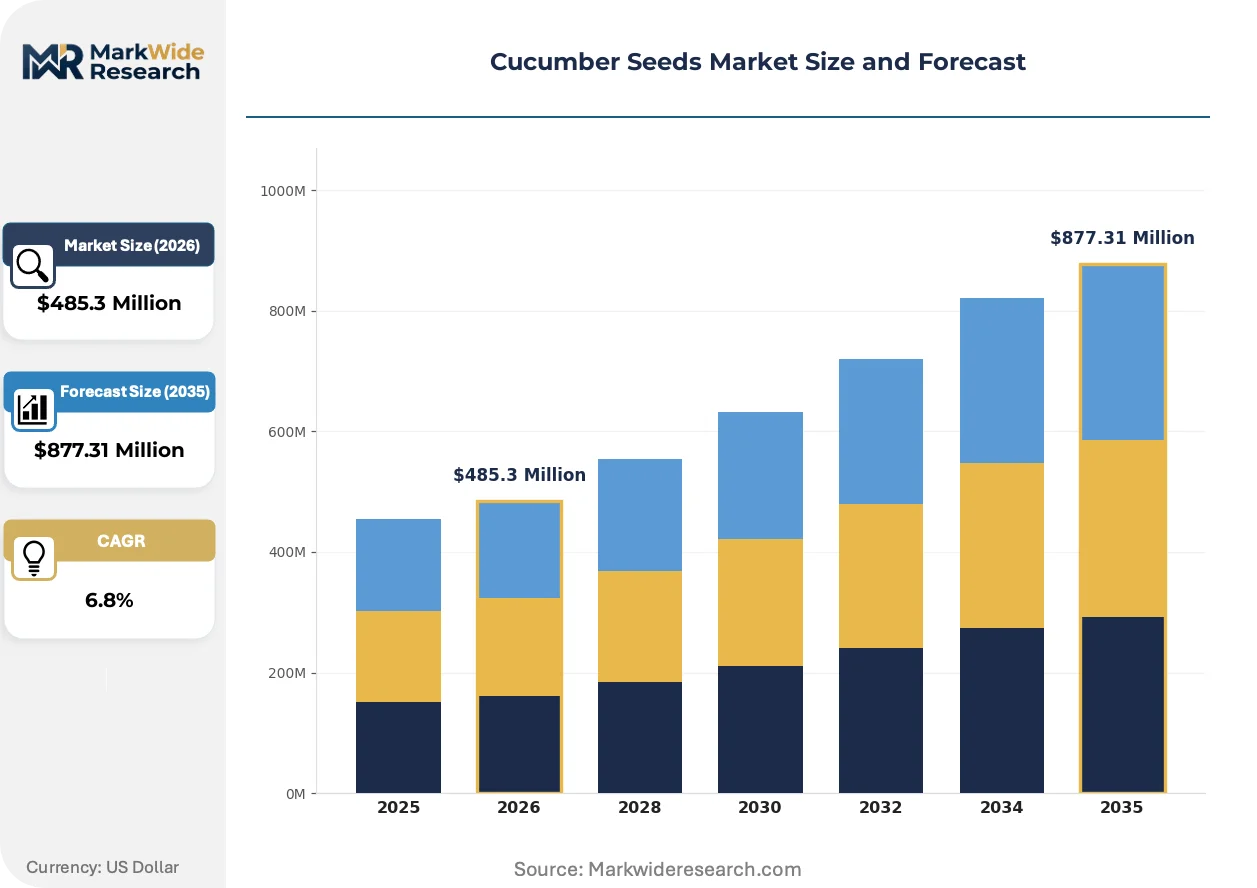
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $877.31 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hybrid, Open-Pollinated, Organic, Conventional End Use: Home Gardens, Greenhouses, Commercial Farms, Crop Production Distribution Channel: Online Retailers, Agricultural Stores, Wholesale Distributors, Direct Sales Packaging Type: Bags, Pouches, Bulk, Packs |
| Companies Covered | Syngenta AG, Bayer Crop Science, Sakata Seed Corporation, Rijk Zwaan Zaadteelt en Zaadhandel B.V., Groupe Limagrain, Enza Zaden B.V., Hazera Seeds B.V., Vilmorin & Cie, Johnny’s Selected Seeds, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cucumber Seeds Market Trends and Innovations
Precision phenotyping platforms and climate-adaptive breeding pipelines are compressing variety development cycles while regulatory pressure on input chemistry reshapes trait prioritization across seed portfolios.
Hyperspectral imaging in breeding nurseries is automating early-stage selection for powdery mildew resistance and uniform fruit shape, accelerating genetic gain timelines. Large-scale greenhouse operators in the Netherlands and Canada deploy these systems to reduce manual scoring labor by 60-70%. Trait discovery pipelines compress from 18 months to 6 months, enabling faster response to pathogen race shifts.
REACH restrictions on candidate list substances are forcing seed treatment reformulations, eliminating neonicotinoid-based priming for emerging cucumber shoots. European breeders pivot to biological seed coatings with Trichoderma inoculants and chitosan polymers. Protected-culture operators in Spain and Italy face 90-day registration delays for novel treatment chemistries, pushing adoption toward pre-certified organic-compliant alternatives.
Consolidated buying cooperatives among mid-scale Polish and Romanian greenhouse operators displace independent distributor relationships, aggregating volume for direct breeder negotiations. These purchasing pools demand performance guarantees on fruit count per square meter, shifting risk from grower to seed supplier. Contract structures now incorporate clawback clauses for yield shortfalls below specified thresholds, visible across 200+ hectare operations in Southeast European growing belts.
Cucumber Seeds Market Segmentation
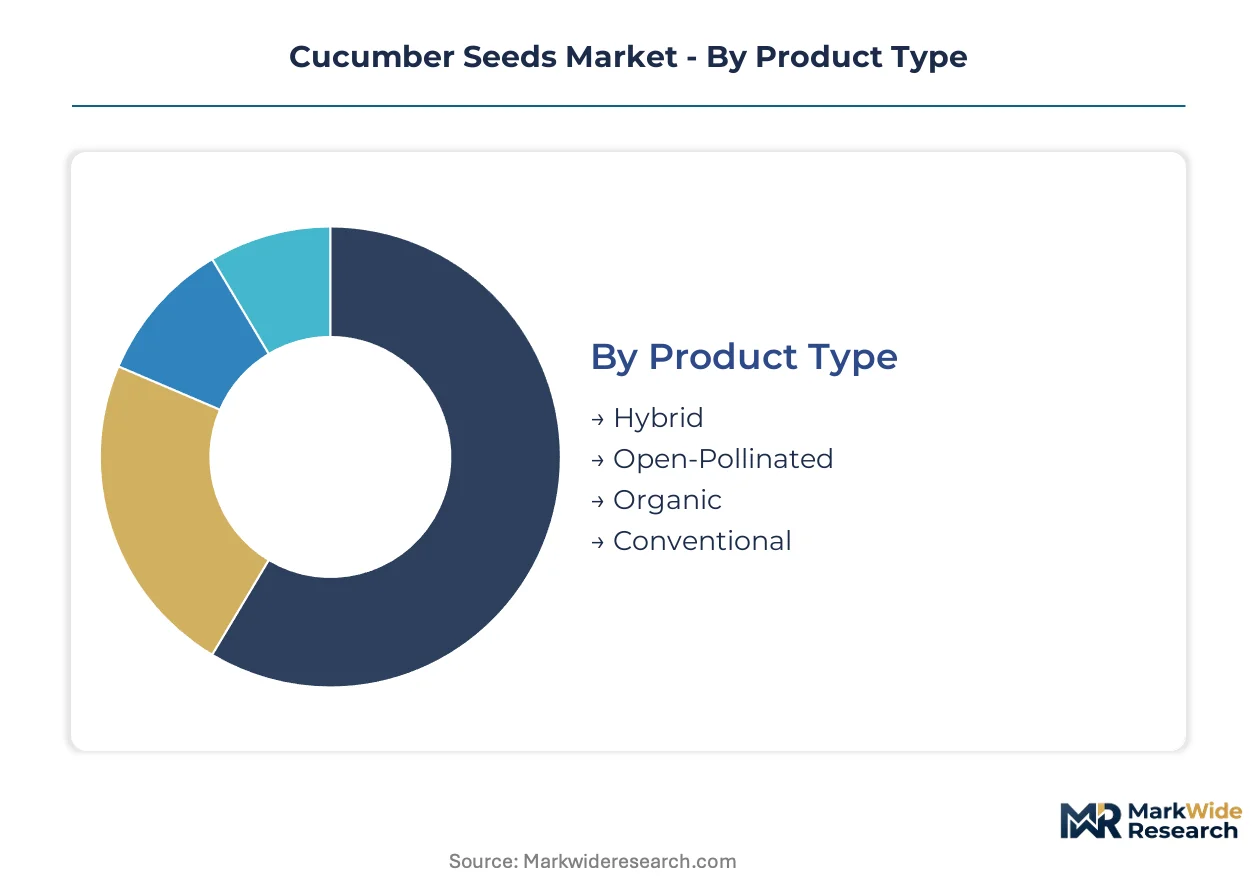
Seed variety selection determines yield consistency, disease resilience, and market access for growers across protected-culture and open-field systems. Segmentation reveals how breeding investments concentrate around hybrid genetics while distribution infrastructure adapts to consolidated greenhouse procurement and fragmented smallholder channels.
Product Type:
Upgrade cycles accelerate as greenhouse operators replace open-pollinated stocks with performance-guaranteed hybrid genetics, compressing varietal turnover timelines across Mediterranean and Northern European growing belts.
- Hybrid:Cross-pollinated F1 lines deliver uniformity in fruit size, disease resistance stacking, and parthenocarpic fruit set without pollination. Dutch glasshouse operators around Westland and Aalsmeer anchor procurement volume here, driven by EU F-Gas Regulation retrofit cycles that synchronize infrastructure and seed variety upgrades.
- Open-Pollinated:Self-fertile varieties allow seed-saving practices that reduce repeat purchase frequency. Heirloom and home-garden segments in Poland and Romania sustain demand, constrained by yield variability that excludes these lines from processor contracts specifying brix and dimensional tolerances.
- Organic:Certified non-GMO pedigree chains with documented input histories meet tightening EU Organic Regulation allowable substance lists.
- Conventional:Standard-treated seeds with synthetic fungicide coatings dominate price-sensitive open-field production in Turkey and Egypt.
Hybrid sits at the top of the volume ranking, with Organic climbing the fastest.
End Use:
Cost tier differentiation separates capital-intensive protected-culture systems from input-flexible open-field operations, with seed pricing spreading across three performance levels.
- Greenhouses:Controlled-environment agriculture demands parthenocarpic cultivars optimized for artificial light spectra and CO2 enrichment protocols. Canadian large-scale operators in Leamington and Dutch clusters drive specification tightening around fruit count per square meter guarantees.
- Commercial Farms:Open-field mechanized harvesting requires determinate bush types with concentrated fruit set windows. Spanish Almeria province and Italian Sicily concentrate procurement of heat-tolerant slicing cucumber lines.
- Home Gardens:Small-scale cultivation favors compact vining types with visual appeal and flavor intensity over yield metrics.
- Crop Production:Contract farming arrangements for processing chains specify pickle-grade gherkin types with uniform diameter and spine density for brining efficiency.
Greenhouses command the premium tier by margin, with Commercial Farms generating the highest absolute volume throughput.
Distribution Channel:
Customer type fragmentation—consolidated buying cooperatives versus independent smallholders—reshapes route-to-market economics and working capital requirements.
- Wholesale Distributors:Traditional agricultural supply houses maintain inventory depth for just-in-time greenhouse planting schedules. Southeast European networks face 90-day registration delays for novel seed treatment chemistries, pushing operators toward pre-certified organic-compliant alternatives.
- Direct Sales:Breeder-to-grower relationships bypass distributor markups for mid-scale Polish and Romanian cooperative purchasing pools. These aggregations demand performance guarantees with clawback clauses for yield shortfalls below specified thresholds.
- Online Retailers:E-commerce platforms capture home-garden and smallholder segments with modular pack sizing that decouples volume commitments from limited budgets.
- Agricultural Stores:Brick-and-mortar rural supply points serve last-minute replanting needs and emergency disease-resistance variety switches.
Wholesale Distributors retain the largest transaction volume, with Direct Sales expanding most quickly through cooperative consolidation.
Packaging Type:
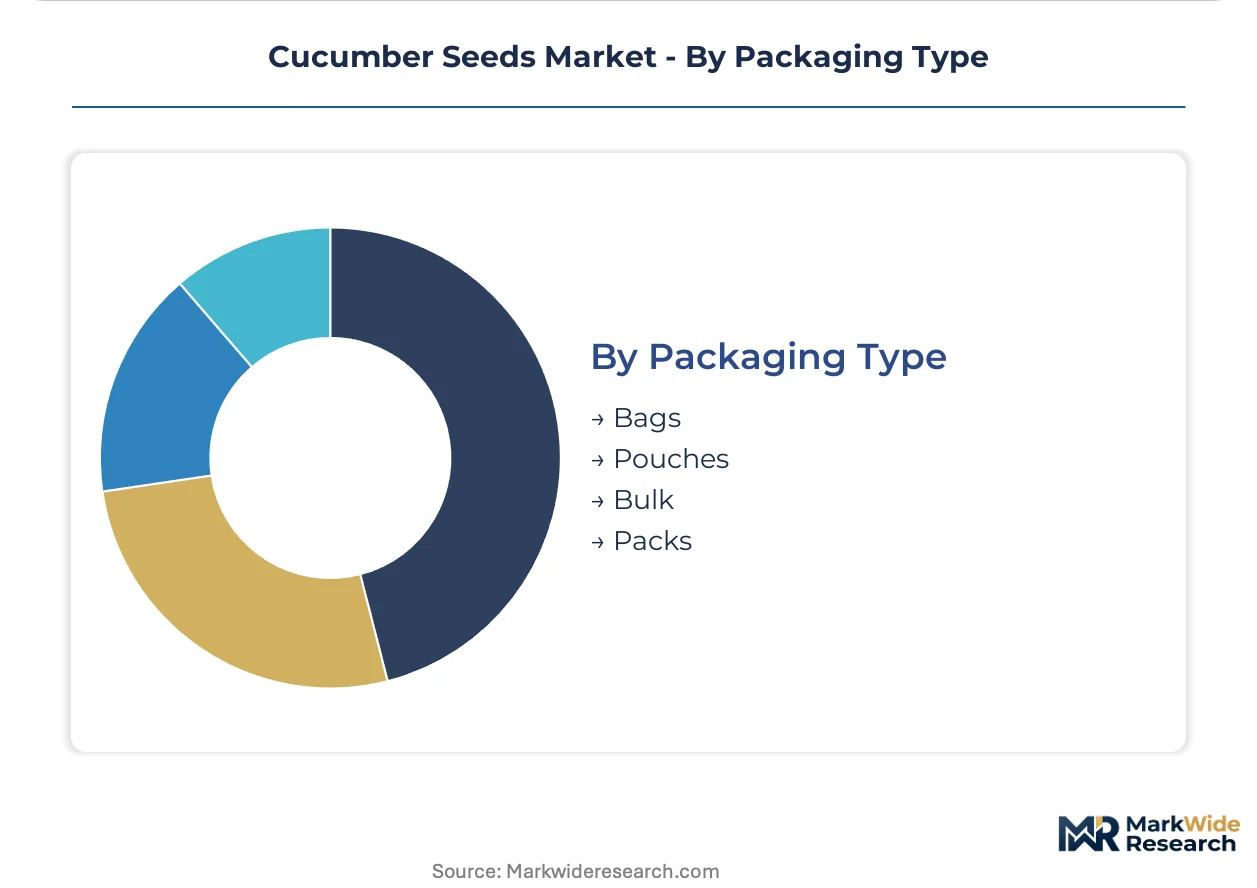
Supply concentration in breeder multiplication fields dictates lot sizing and packaging configurations, with phytosanitary documentation complexity favoring bulk formats for cross-border movement.
- Bulk:Unpackaged seed lots in metric-ton quantities serve large greenhouse operators with on-site treatment and priming capabilities. OECD certification schemes govern quality standards for these hybrid lots crossing Netherlands-Germany-Belgium growing zones.
- Packs:Pre-measured unit quantities with printed cultivation protocols target smallholder literacy barriers in emerging protected-culture markets.
- Bags:Standard woven polypropylene containers with moisture barriers protect viability during tropical storage conditions.
- Pouches:Laminated foil sachets with desiccant inserts extend shelf life for retail garden center channels.
Bulk formats dominate value concentration, with Pouches gaining share fastest in direct-to-consumer digital channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dutch horticulture clusters pioneered modern greenhouse cucumber cultivation during the 1960s, establishing varietal benchmarks that now propagate across protected-culture zones worldwide. The Netherlands remains the nucleus of hybrid seed innovation, with knowledge spillovers reshaping procurement standards in adjacent growing belts.
Netherlands
Westland and Aalsmeer glasshouse complexes drive premium hybrid seed demand as operators synchronize infrastructure retrofits with EU F-Gas Regulation compliance timelines. The Dutch Food and Consumer Product Safety Authority enforces strict phytosanitary protocols for germplasm movement. Knowledge spillovers from Wageningen University research clusters elevate seed quality benchmarks across Belgian and German border zones.
Spain
Almeria province concentrates open-field mechanized harvesting of heat-tolerant slicing cucumber lines for European fresh produce supply chains. Spain's Ministry of Agriculture mandates integrated pest management documentation for seed treatment imports. Andalusian growing cooperatives negotiate volume-based procurement contracts with direct breeder relationships.
United States
Leamington, Ontario-adjacent greenhouse operators in Michigan and Ohio deploy parthenocarpic cultivars optimized for artificial light spectra and CO2 enrichment protocols. The USDA Plant Variety Protection Office shapes trait development priorities through intellectual property frameworks. Protected-culture expansion in the Great Lakes region concentrates demand for performance-guaranteed hybrid genetics.
India
Maharashtra and Karnataka polyhouse construction under National Horticulture Mission subsidy schemes creates first-mover openings for heat-tolerant variety introductions. The Directorate of Plant Protection, Quarantine & Storage regulates seed health certification for imported germplasm. Nashik and Pune clusters aggregate mid-scale greenhouse operator purchasing pools for direct breeder negotiations.
Canada
Leamington greenhouse corridor operators specify fruit count per square meter guarantees in seed procurement contracts, shifting yield risk to suppliers. Health Canada's Pest Management Regulatory Agency governs allowable seed treatment chemistries for protected-culture systems. Ontario-based buying cooperatives displace traditional distributor relationships through consolidated volume aggregation.
Cucumber Seeds Market Competitive Landscape
Premium-margin players sit above commodity-margin players across intellectual property protection and trait integration depth. The vendor base organizes into three tiers: multinational agrochemical conglomerates with captive breeding pipelines, specialized vegetable seed houses with regional varietal depth, and niche organic-certified suppliers serving certification-constrained channels. Strategic moves concentrate on trait licensing agreements and direct-to-grower digital channel buildout.
Within the multinational tier, Bayer Crop Science and Syngenta AG occupy positions anchored by broad trait integration capabilities and global distribution infrastructure. Specialized houses including Sakata Seed Corporation and Rijk Zwaan Zaadteelt en Zaadhandel B.V. exemplify regional expertise models concentrated on protected-culture genetics. Enza Zaden B.V. and Hazera Seeds B.V. represent mid-scale specialists with varietal breadth spanning continental climate zones.
| Leading Market Players |
|---|
| Syngenta AG |
| Bayer Crop Science |
| Sakata Seed Corporation |
| Rijk Zwaan Zaadteelt en Zaadhandel B.V. |
| Groupe Limagrain |
| Enza Zaden B.V. |
| Hazera Seeds B.V. |
| Vilmorin & Cie |
| Johnny's Selected Seeds |
| Others |
Pricing and Supply Chain Analysis
Hand-pollination labor concentration in Dutch breeding stations anchors cost premiums across hybrid seed tiers, with wage differentials between Netherlands-based parent-line maintenance and outsourced multiplication in Turkey and Egypt driving spreads between premium greenhouse genetics and economy open-field lines.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments procurement by performance guarantee intensity and intellectual property depth. Price differentiation rests on parthenocarpic trait stacking and OECD certification tier, with Dutch glasshouse operators absorbing premiums for fruit-count guarantees while Egyptian smallholders face cost compression in untreated conventional lines. Pricing pressure stems from consolidated buying cooperatives in Poland and Romania demanding clawback clauses for yield shortfalls. Smallholder home-garden segments exhibit highest price sensitivity; large-scale protected-culture operators show lowest sensitivity due to yield-risk transfer contracts.
Supply Chain Analysis
Skilled breeder workforce availability concentrates in Netherlands, Japan, and USA, with parent-line development anchored at Wageningen-cluster research stations and Sakata's Japanese R&D facilities. Raw material dependencies center on germplasm repositories, synthetic fungicide coatings for conventional treatments, and biological inoculants for organic-compliant alternatives. Supply chain risk manifests as phytosanitary documentation complexity for cucumber green mottle mosaic virus strain differentiation, delaying releases from multiplication fields. Distribution runs through wholesale agricultural supply houses maintaining inventory depth for just-in-time greenhouse planting schedules, with direct breeder-to-grower channels expanding through cooperative purchasing pools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a geographic-arbitrage play: EU F-Gas Regulation retrofit cycles compress seed variety upgrade timelines in Netherlands and Germany while Indian polyhouse subsidy schemes create parallel demand windows with lower regulatory compliance burdens.
For Market Incumbents: Deploy trait licensing agreements to capture royalty streams without breeding cycle capital intensity. Consolidate germplasm repositories against emerging cucumber downy mildew race vulnerabilities. Deepen backward integration into parent-line maintenance facilities in Netherlands to protect margin position from outsourced multiplication cost volatility.
For New Entrants and Emerging Players: Mid-scale Polish and Romanian greenhouse cooperatives represent underserved buyer archetypes with fragmented distributor relationships and appetite for performance-guaranteed direct contracts. Target India's protected-culture buildout under National Horticulture Mission subsidies for heat-tolerant parthenocarpic introductions. Establish e-commerce platforms with modular pack sizing to bypass traditional agricultural supply house markups.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized vegetable seed houses with regional varietal depth but limited trait integration pipelines. Long-term viability hinges on intellectual property protection durability and climate-adaptive breeding acceleration. Watch for inflection signals in EU Organic Regulation tightening timelines that would re-rate organic-certified seed line premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Trait Licensing Agreement | Bayer Crop Science leverages its integration pipeline to anchor premium hybrid offerings in protected-culture systems. |
| Direct-to-Grower Digital Channel | E-commerce platforms connect breeders with mid-scale greenhouse operators, capturing margin in fragmented Eastern European markets. |
| Backward Integration into Parent-Line Maintenance | Dutch specialists secure captive supply of germplasm against outsourced multiplication cost volatility and quality drift. |
| Organic Certification Program | EU Organic Regulation tightening pushes certified greenhouse operators toward documented non-GMO pedigree chains. |
| Climate-Adaptive Breeding Pipeline | Hyperspectral imaging accelerates powdery mildew resistance selection, compressing genetic gain timelines from 18 months to 6 months. |
Research Methodology
Direct dialogue with greenhouse operators, breeding program directors, agricultural supply distributors, and seed certification authorities grounded qualitative insights in operational reality. Secondary validation drew from EU seed marketing directives, OECD certification scheme documentation, USDA Plant Variety Protection Office filings, and national variety listing authority registries. Bottom-up variety-level demand estimates triangulated against top-down greenhouse acreage expansion data across Netherlands, Spain, Canada, and India.
Segmented outputs across product type, end use, distribution channel, and packaging format dimensions fed into analytical framework spanning the projection horizon. CAGRs were derived from breeder shipment data, greenhouse operator procurement surveys, and protected-culture infrastructure investment tracking. Industry-specific inputs included EU F-Gas Regulation compliance timelines, National Horticulture Mission subsidy disbursement rates, and phytosanitary protocol evolution for cucumber green mottle mosaic virus strain differentiation.
Inputs from greenhouse operator interviews and seed certification authority documentation were available through the study window; gaps in real-time breeder inventory data and proprietary parent-line cost structures introduce uncertainty bands around margin compression estimates. Forecasts reflect documented assumptions on subsidy scheme continuity and regulatory enforcement intensity. Material deviation in EU F-Gas Regulation phase-down pace or Indian polyhouse construction acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Chamomile Seeds Market
Seeds
South Africa Seed Market
Seeds
Garden Seeds Market
Seeds
Asia-Pacific Onion Seed Market
Seeds
Sprouted Grains and Seeds Market
Seeds
Mustard Seeds Market
Seeds
Field Crop Seeds Market
Seeds
Safflower Seeds Market
Seeds
Asia-Pacific Vegetable Seed Market
Seeds
Grass Seed Market
Seeds
Thailand Vegetable Seed Market
Seeds
Philippines Hybrid Rice Seed Market
Seeds
South and Southeast Asia Seed Market
Seeds
Global Soybean Seed Market
Seeds
Punnet Market
Seeds
Native Grass Seeds Market