
 Europe Seed Market | 2026-2036
Europe Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Seed Market Foresight
Specialty vegetable growers is reorganizing demand patterns across European seed procurement, displacing commodity grain farmers as the priority buyer archetype for premium germplasm. Bayer AG leverages its trait pipeline to dominate corn and oilseed genetics in Eastern European breadbaskets. KWS SAAT SE & Co. KGaA anchors sugar beet and cereal seed supply through deep breeding station networks in Germany and France. Rijk Zwaan specializes in greenhouse tomato and pepper varieties, controlling proprietary germplasm that commands loyalty from Dutch and Spanish glasshouse operators.
Europe seeds comprise sexually or vegetatively propagated plant material bred for genetic uniformity, disease resistance, and yield stability, typically meeting OECD seed certification schemes for varietal purity and germination rates above specified thresholds. Their primary purpose is to establish commercial crops and managed turf with predictable agronomic performance under diverse climatic and soil conditions. Hybrid seeds occupy the dominant value pool in cereals and vegetables, while organic seeds represent the fastest-expanding category as EU subsidy rules and retailer procurement codes tighten permitted input lists. Open-pollinated varieties retain structural importance in marginal farming zones where farmer seed-saving persists, though GM seeds remain restricted to limited maize approvals under national opt-out clauses.
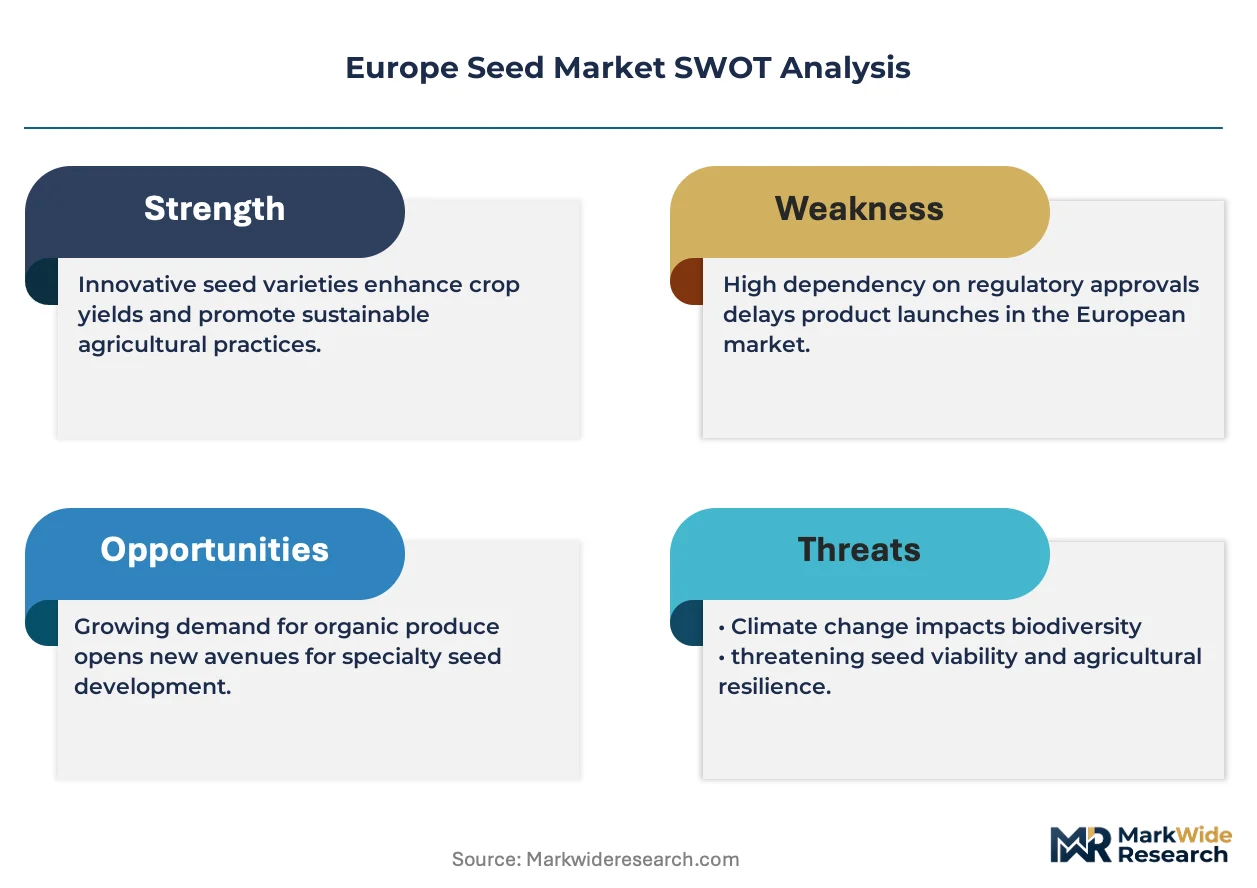
The EU Green Deal and Farm to Fork Strategy impose binding pesticide reduction targets that reshape variety registration priorities toward disease-resistant genetics, while EFSA and national variety testing authorities enforce DUS and VCU protocols before market release. REACH and national biocide rules further constrain seed treatment chemistries, pushing breeders toward biological and physical priming alternatives. Stakeholders must monitor how the EU Seed Marketing Regulation revision and impending genomic technique classifications redraw competitive boundaries between conventional and gene-edited variety pipelines.
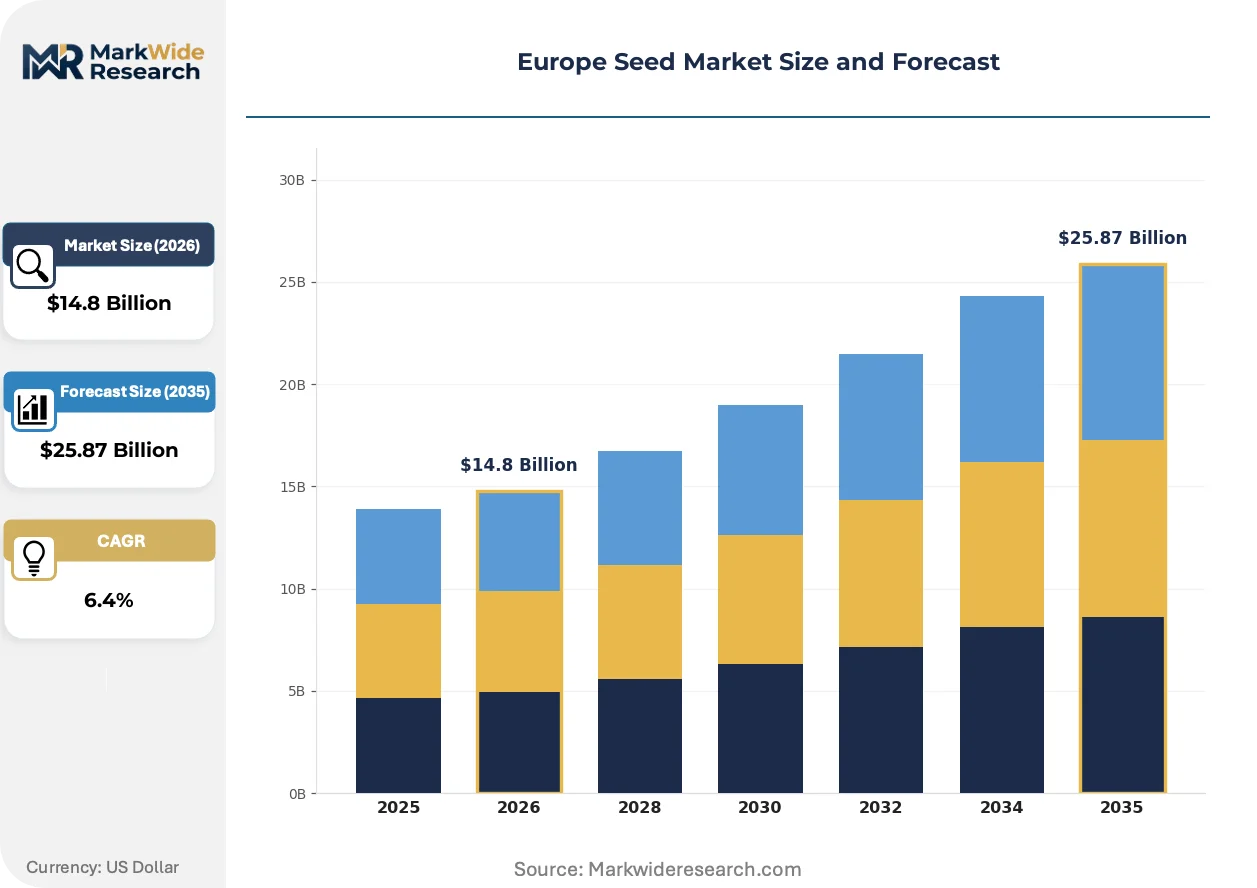
Market Dynamics
The EU Green Deal pesticide reduction mandates are compressing breeding cycles toward disease-resistant genetics, forcing seed companies to accelerate varietal turnover while specialty vegetable growers in Spain and Italy absorb premium pricing for hybrid germplasm that meets Farm to Fork benchmarks.
Growth Catalysts
- EU Green Deal pesticide targets:Binding reduction mandates under the Farm to Fork Strategy are redirecting variety registration priorities toward disease-resistant genetics, creating pull-through demand for advanced breeding pipelines.
- Organic seed subsidy alignment:CAP greening payments and national organic action plans in Germany and France are tightening permitted input lists, accelerating certified propagation material procurement across premium horticulture supply chains.
- Glasshouse expansion in the Netherlands:Dutch and Spanish protected cultivation operators are intensifying hybrid tomato and pepper seed procurement to optimize yield per square meter under energy cost pressures.
Market Restraints
- Energy input cost volatility:Natural gas and electricity price spikes are compressing margins for glasshouse operators in the Netherlands, reducing discretionary spending on premium hybrid vegetable seeds.
- Gene-edited variety classification uncertainty:Pending EFSA and European Commission decisions on genomic technique regulation are freezing investment decisions in CRISPR-based breeding pipelines.
- Farmer seed-saving persistence:Open-pollinated cereal varieties in marginal farming zones of Romania and Poland are limiting addressable market expansion for commercial hybrid seed suppliers.
Strategic Opportunities
- Biological seed treatment convergence:REACH restrictions on neonicotinoid chemistries are opening substitution pathways for microbial inoculant and physical priming technologies.
- Organic seed certification gaps in Eastern Europe:Underdeveloped certified organic propagation material supply in Hungary and Bulgaria offers first-mover positioning ahead of CAP greening enforcement.
- Carbon farming credit integration:Emerging EU carbon removal certification frameworks are creating varietal selection criteria tied to soil carbon sequestration traits in cover crop and forage segments.
Industry Challenges
- DUS and VCU testing backlog:National variety testing authority capacity constraints in France and Germany are extending time-to-market for new registrations, compressing effective patent life.
- Gene-edited trait licensing complexity:Fragmented intellectual property ownership across CRISPR tool patents and trait-specific applications is complicating freedom-to-operate assessments for breeding programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Seed Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hybrid Seeds, Open-Pollinated Seeds, GM Seeds, Organic Seeds End Use Industry: Agriculture, Horticulture, Forestry, Turf Management Distribution Channel: Online Retail, Agro Stores, Distributors, Direct Sales Crop Type: Cereals, Vegetables, Fruits, Oilseeds |
| Companies Covered | KWS SAAT SE & Co. KGaA, Rijk Zwaan, Bayer AG, Bejo Zaden, DLF Seeds, Corteva Agriscience, Syngenta Group, Enza Zaden, Groupe Limagrain, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Seed Market Shifts & Advancements
Gene-editing tools and biological seed treatments are compressing traditional chemistry-dependent breeding models, while regulatory ambiguity around genomic techniques freezes capital allocation decisions across European germplasm pipelines.
CRISPR-Cas9 and related site-directed nuclease platforms are enabling precise trait stacking for disease resistance and abiotic stress tolerance without transgenic marker retention. Dutch and Spanish glasshouse operators are piloting gene-edited tomato varieties with reduced bruising susceptibility. Conventional marker-assisted breeding is displacing slower backcrossing methods in commercial vegetable programs, shortening variety development timelines by multiple breeding cycles.
REACH authorization restrictions on neonicotinoid seed treatments are forcing reformulation toward microbial biostimulants and physical film coatings. ECHA substance evaluation deadlines are compressing registration timelines for remaining chemistries. German and French cereal seed processors are accelerating biological priming infrastructure investments to maintain treated seed market share under tightening biocide rules.
Direct contracting between breeding houses and large-scale specialty crop cooperatives is shortening traditional distribution tiers. Spanish tomato grower associations in Almería and Murcia are consolidating procurement through centralized varietal trialing committees. This channel compression is most visible in southern European protected vegetable sectors where volume concentration supports dedicated breeding program sponsorship.
Europe Seed Market Segmentation
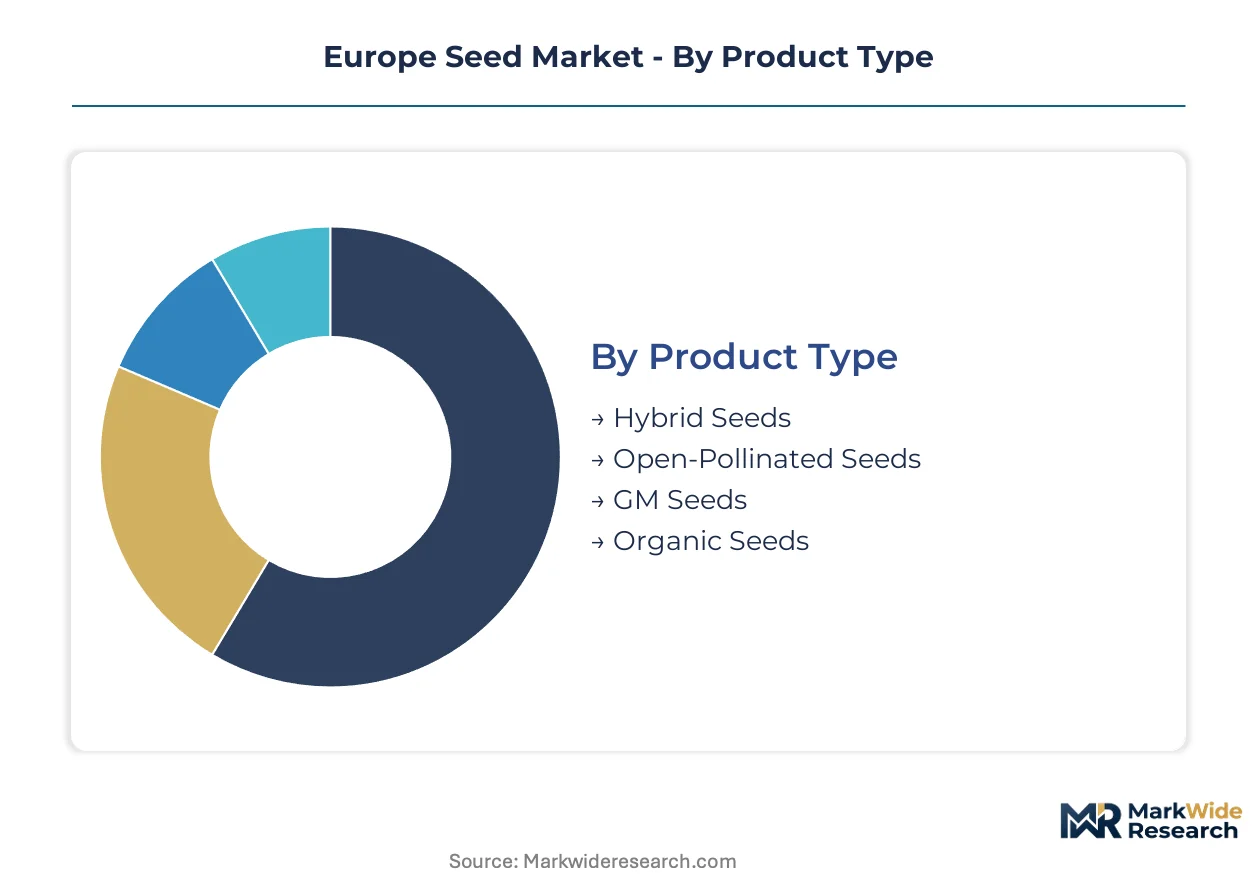
European seed procurement patterns fragment across genetic propagation methods, crop categories, and channel structures. Each dimension carries distinct regulatory footprints under EU seed certification schemes and national variety registration protocols.
Product Type:
REACH authorization restrictions and EU Green Deal pesticide mandates differentiate commercial viability across genetic categories.
- Hybrid Seeds:Cross-pollinated varieties bred for genetic uniformity and heterosis expression in yield and disease resistance. Dutch and Spanish glasshouse operators absorb premium pricing for hybrid vegetable germplasm that satisfies Farm to Fork sustainability benchmarks.
- Organic Seeds:Certified propagation material produced under EU organic regulation without synthetic chemical inputs. German and French premium horticulture supply chains reward certified organic seed procurement as CAP greening payments tighten permitted input lists.
- Open-Pollinated Seeds:Varieties maintaining genetic diversity through natural pollination mechanisms, dominant in marginal farming zones where farmer seed-saving persists.
- GM Seeds:Transgenic varieties restricted to limited maize approvals under national opt-out clauses, with cultivation concentrated in Spain and Portugal.
Hybrid seeds handle the majority of throughput; organic seeds are gaining share fastest on regulatory alignment with CAP greening enforcement.
End Use Industry:
Customer archetypes concentrate procurement power differently across volume scale and margin capture.
- Agriculture:Broadacre cereal and oilseed production demanding genetic uniformity and mechanized sowing compatibility. Eastern European breadbaskets in Poland and Romania drive volume procurement of hybrid corn and wheat varieties.
- Horticulture:Intensive vegetable and ornamental production under protected cultivation or open-field specialty cropping. Almería and Murcia grower associations in Spain consolidate tomato and pepper seed procurement through centralized varietal trialing committees.
- Forestry:Reforestation and timber plantation establishment requiring certified reproductive material under OECD forest reproductive material schemes.
- Turf Management:Managed grass surfaces for sports facilities, golf courses, and amenity landscaping demanding wear tolerance and aesthetic uniformity.
Agriculture commands absolute volume leadership; horticulture extracts the steepest premium pricing per kilogram of seed.
Distribution Channel:
Channel structure reflects customer scale concentration and technical service requirements.
- Direct Sales:Breeding houses contract directly with large-scale specialty crop cooperatives and integrated agribusiness operations. Bayer AG and KWS SAAT SE anchor sugar beet and cereal supply through dedicated breeding program sponsorship.
- Distributors:Regional seed houses and agricultural supply cooperatives managing inventory, credit extension, and local agronomic support across fragmented farm structures.
- Agro Stores:Retail-facing agricultural input outlets serving smallholder and part-time farming operations with immediate availability and local relationship networks.
- Online Retail:Digital platforms emerging for specialty vegetable and home garden seed segments, constrained by varietal registration documentation requirements.
Direct sales capture the highest-margin transactions; distributors maintain the broadest geographic coverage.
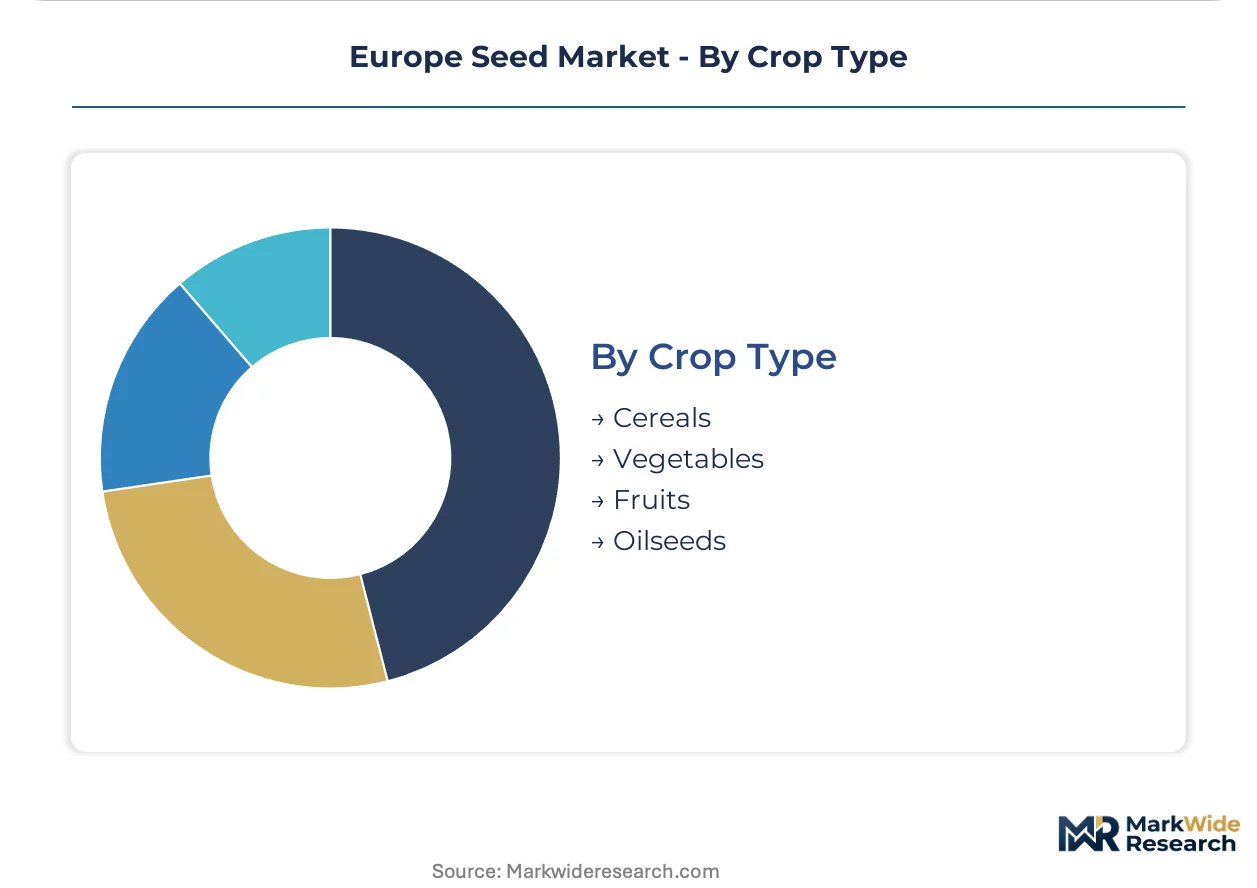
Crop Type:
Biological characteristics and breeding investment intensity shape competitive dynamics.
- Vegetables:High-value hybrid varieties with short breeding cycles and proprietary germplasm protection. Rijk Zwaan controls greenhouse tomato and pepper genetics commanding loyalty from Dutch glasshouse operators.
- Cereals:Volume-driven wheat, barley, and corn seed markets with established hybrid penetration in maize and advancing hybridization in wheat. KWS SAAT SE anchors supply through deep breeding station networks in Germany and France.
- Oilseeds:Rapeseed and sunflower seed markets under pressure from EU renewable energy policy shifts and protein crop diversification mandates.
- Fruits:Vegetatively propagated material including rootstocks and scion varieties for orchard establishment, subject to phytosanitary certification under EU plant health regulations.
Cereals dominate absolute tonnage; vegetables sustain the highest research and development intensity per hectare served.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty vegetable growers concentrate procurement power in Mediterranean zones while German and French operators anchor organic seed demand through premium horticulture supply chains.
Germany
Organic seed demand concentrates among Baden-Württemberg and Bavaria horticulture cooperatives supplying premium retail chains. The Federal Office of Plant Varieties enforces DUS and VCU testing protocols that extend variety registration timelines. KWS SAAT SE anchors cereal and sugar beet breeding through deep station networks across Lower Saxony and Hesse.
Netherlands
Glasshouse operators in Westland and Aalsmeer intensify hybrid tomato and pepper seed procurement under energy cost pressures. The Dutch Food and Consumer Product Safety Authority enforces EU plant health regulations on imported propagation material. Wageningen University clusters anchor public-private breeding partnerships for disease-resistant vegetable genetics.
Spain
Almería and Murcia grower associations consolidate vegetable seed procurement through centralized varietal trialing committees. The Spanish Agency for Food Safety and Nutrition coordinates with EFSA on variety registration under EU Seed Marketing Regulation. Andalusian protected cultivation zones absorb premium hybrid germplasm pricing to meet Farm to Fork sustainability benchmarks.
France
Premium horticulture supply chains in Provence-Alpes-Côte d'Azur and Nouvelle-Aquitaine reward certified organic seed procurement. The National Institute of Origin and Quality enforces organic certification standards for propagation material. Groupe Limagrain anchors cereal and forage breeding through research stations in Auvergne-Rhône-Alpes.
Italy
Specialty crop growers in Emilia-Romagna and Sicily intensify hybrid vegetable seed procurement as CAP greening payments tighten permitted input lists. The Ministry of Agriculture coordinates variety registration with EU harmonized catalog requirements. Po Valley cereal cooperatives maintain open-pollinated variety persistence that limits commercial hybrid seed addressable market expansion.
Europe Seed Market Competitive Landscape
Player mix skews toward integrated breeding houses with deep station networks and specialized vegetable genetics firms with proprietary germplasm control. Market structure concentrates around three strategic archetypes: multinational agrochemical-seed conglomerates with trait pipeline breadth, mid-cap family-owned breeding houses with crop-specific depth, and vegetable specialists with greenhouse variety dominance. Competitive moves center on biological seed treatment convergence and direct contracting with large-scale specialty crop cooperatives.
Among Germany-based breeding houses, KWS SAAT SE exemplifies the family-owned archetype with century-long cereal and sugar beet specialization. Bayer AG occupies a position representing multinational agrochemical-seed integration with corn and oilseed genetics dominance. Rijk Zwaan anchors the vegetable specialist tier through greenhouse tomato and pepper germplasm control.
| Leading Market Players |
|---|
| KWS SAAT SE & Co. KGaA |
| Rijk Zwaan |
| Bayer AG |
| Bejo Zaden |
| DLF Seeds |
| Corteva Agriscience |
| Syngenta Group |
| Enza Zaden |
| Groupe Limagrain |
| Others |
Supply & Pricing Matrix
Eighteen-month breeding-to-certification lead times concentrate pricing power with breeding houses that control proprietary germplasm pipelines, while inventory buffers at Dutch glasshouse cooperatives absorb hybrid vegetable seed premiums before downstream cost pass-through to Spanish grower associations.
Pricing Analysis
Conventional marker-assisted breeding versus CRISPR-edited trait stacks versus open-pollinated legacy varieties stratify pricing across three performance tiers. Contract-based long-term offtake dominates, with price differentiation driven by OECD certification grade and volume scale commitments. Pricing pressure stems from energy cost volatility compressing glasshouse operator margins. Specialty vegetable cooperatives in Almería exhibit highest price sensitivity; Dutch glasshouse operators absorbing disease-resistant hybrid premiums show lowest.
Supply Chain Analysis
Inventory concentration at German and Dutch breeding station networks feeds downstream distribution through specialized agro-input cooperatives. Germplasm development draws from parent seed stocks in France, field multiplication in Poland, and controlled-environment finishing in the Netherlands. Single-source vulnerability sits with proprietary hybrid tomato and pepper genetics controlled by two Dutch specialists. Distribution runs through regional seed houses extending credit and agronomic support to fragmented farm structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's seed market sits in early-cycle expansion as EU Green Deal pesticide mandates force variety turnover toward disease-resistant genetics, accelerating replacement rates across cereal and vegetable programs.
For Market Incumbents: Consolidate germplasm pipelines through backward integration into parent seed production in France and Poland, reducing dependency on third-party multiplication contracts. Lock in direct contracting relationships with Almería and Murcia grower associations before channel compression accelerates. Prioritize biological seed treatment R&D investments ahead of REACH neonicotinoid phase-outs.
For New Entrants and Emerging Players: Anchor in certified organic propagation material supply gaps across Hungary and Bulgaria, where CAP greening enforcement lags Western European adoption curves. Target Eastern European cereal cooperatives with open-pollinated alternatives priced below hybrid premiums. Pursue varietal trialing committee sponsorships in Spanish protected cultivation zones to secure volume commitments before pipeline establishment.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-tension play because EU genomic technique classifications will redraw competitive boundaries between conventional and gene-edited breeding pipelines. Target mid-cap vegetable specialists with proprietary greenhouse germplasm and established DUS registration track records. Monitor EFSA decisions on CRISPR-based trait regulation as the critical inflection signal for capital redeployment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Biological Seed Treatment Convergence | REACH restrictions on neonicotinoids force microbial inoculant substitution investments at German processors. |
| Direct Contracting with Grower Cooperatives | Spanish tomato associations in Almería consolidate procurement through centralized varietal trialing committees. |
| Organic Seed Certification Infrastructure | Underdeveloped certified propagation supply in Hungary offers first-mover positioning ahead of CAP enforcement. |
| Gene-Edited Trait Pipeline Development | Pending EFSA genomic technique decisions freeze capital allocation across CRISPR-based breeding programs. |
| Carbon Farming Credit Integration | Emerging EU carbon removal frameworks create varietal selection criteria tied to soil sequestration traits. |
Research Methodology
Initial hypotheses were tested against primary input from breeding program directors, variety registration officers at national testing authorities, procurement leads at Spanish grower cooperatives, and cereal seed processors in Germany and France, and refined through secondary validation against EU Seed Marketing Regulation documentation, EFSA variety registration databases, OECD seed certification scheme protocols, and CAP greening payment implementation reports, with bottom-up volume builds triangulated against top-down market sizing.
Variance decomposition across the projection horizon isolates drivers by genetic propagation method, crop category, and channel structure, with segmentation modeling spanning hybrid versus organic versus open-pollinated germplasm, vegetable versus cereal versus oilseed applications, and direct sales versus distributor versus agro-store channels. CAGRs derive from logistic diffusion curves fitted to regulatory enforcement timelines and subsidy alignment patterns, incorporating EU Green Deal pesticide reduction mandates and CAP greening payment schedules as structural demand shifters.
Material uncertainties — EFSA genomic technique reclassifications, REACH authorization timelines for remaining chemistries, and national opt-out clause expansions for GM cultivation — sit outside the modeled envelope. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Asia-Pacific Seed Market
Seeds
Pigeon Pea Market
Seeds
Flaxseed (Linseed) Market
Seeds
Africa Peas Market
Seeds
Africa Vegetable Seed Market
Seeds
Asia-Pacific Chia Seed Market
Seeds
Europe Sesame Seed Market
Seeds
Global Oilseed Market
Seeds
Asia-Pacific Rice Seed Market
Seeds
Middle East and Africa Cannabis Seeds Market
Seeds
Avena Sativa Market
Seeds
Europe Amaranth Market
Seeds
Cotton Seed Treatment Market
Seeds
Cucumber Seeds Market
Seeds
India Seed Market
Seeds
Indonesia Seeds Market