
 China Satellite Communication Market | 2026-2036
China Satellite Communication Market Size, Share, and Industry Trends Forecast 2026-2036
China Satellite Communication Market Insights
China's dual carbon goals is decoupling ground station energy profiles from fossil-dependent baselines, forcing new efficiency mandates across terrestrial infrastructure. China Aerospace Science and Technology Corporation leverages its state-backed launch capacity to anchor geostationary deployment timelines. GalaxySpace competes through aggressive LEO constellation density, while SpaceSail specializes in thin-film satellite manufacturing to reduce unit mass.
China satellite communication encompasses orbital and ground-based systems transmitting voice, data, and video via radio frequency links operating across C-band, Ku-band, Ka-band, and emerging Q/V-band spectra, with transponder architectures defining channel capacity and link budgets for commercial and sovereign networks. Broadband and navigation product types capture divergent margin structures, with broadband absorbing capex-intensive HTS investments and navigation sustaining stable government pricing. LEO technology leads deployment velocity among orbital tiers, while GEO retains premium enterprise anchoring for latency-tolerant applications.
MIIT spectrum allocation rules and GB standards for electromagnetic compatibility shape terminal certification timelines, while SAMR antitrust review constrains cross-sector platform consolidation. NMPA-equivalent space quality protocols and MEE environmental assessments for launch sites add compliance layers to facility expansion. Stakeholders must weigh constellation scale economics against ground segment regulatory lag in inland provinces.
Market Dynamics
MIIT spectrum allocation rules and GB electromagnetic compatibility standards are compressing terminal certification timelines while forcing ground station operators to decouple from fossil-dependent power baselines under dual carbon mandates.
Growth Catalysts
- Defense bandwidth procurement:China's military modernization is absorbing dedicated Ka-band and Q/V-band transponder capacity for sovereign secure networks.
- Dual carbon infrastructure mandates:MEE environmental assessments for launch sites and ground stations are accelerating renewable energy integration across terrestrial segments.
- Western province broadband gap:Qinghai, Xinjiang, and Tibet administrative regions present concentrated demand for satellite-based internet access where fiber deployment remains uneconomical.
Market Restraints
- Launch capacity bottlenecks:Geostationary deployment timelines face constraint from limited domestic heavy-lift availability and coastal launch site congestion.
- Thin-film manufacturing yield rates:SpaceSail's specialized production processes exhibit higher defect rates versus traditional bus architectures, elevating unit replacement costs.
- SAMR cross-sector review:Antitrust scrutiny of platform consolidation creates regulatory friction for vertically integrated operators seeking downstream service expansion.
Strategic Opportunities
- IoT maritime coverage:South China Sea fishing fleets and container shipping lanes remain underpenetrated for narrowband satellite connectivity.
- LEO-GEO hybrid architectures:Convergence of low-latency constellations with geostationary anchoring enables tiered service offerings across enterprise and consumer segments.
- Inland ground station buildout:Guizhou and Sichuan provinces offer favorable radio quiet zones for new teleports serving western bandwidth demand.
Industry Challenges
- RF engineer scarcity:Specialized talent for Q/V-band payload design and phased array antenna calibration commands premium compensation in a shallow labor pool.
- NMPA-equivalent space quality protocols:Extended certification timelines for flight-qualified components compress constellation deployment schedules.
- Legacy GEO anchor tenant migration:Enterprise customers with long-term C-band leases resist service transitions despite superior HTS economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Satellite Communication Market |
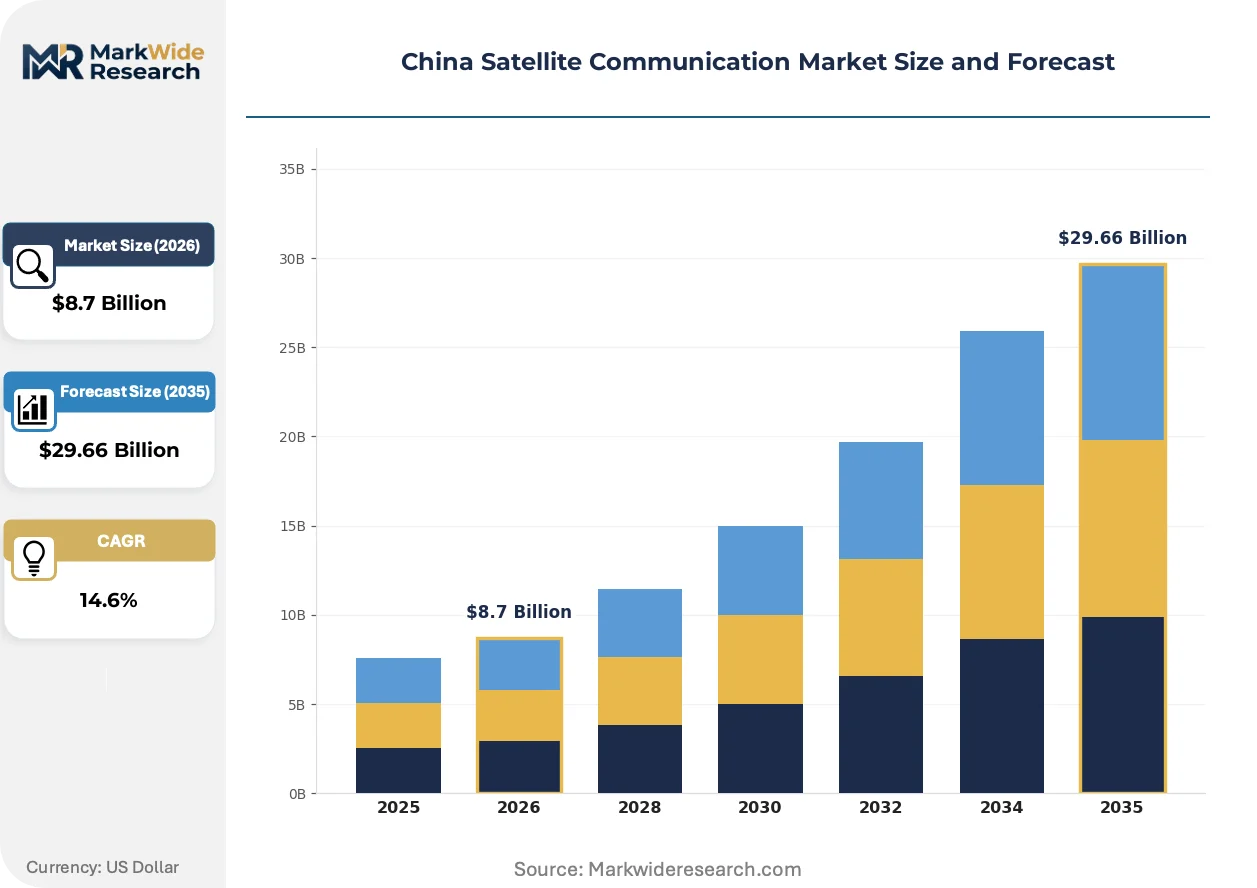
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $29.66 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Broadband, Imaging, Navigation, Communication End User: Government, Defense, Telecommunications, Media Technology: LEO, MEO, GEO, HTS Application: Remote Sensing, Disaster Management, Agriculture, Broadband Access |
| Companies Covered | ChinaSat, China Aerospace Science and Technology Corporation, China SatNet, Tiantong Satellite Communications, China Aerospace Science and Industry Corporation, SpaceSail, GalaxySpace, Guodian Gaoke, China Telecom, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Satellite Communication Market Trends and Innovations
Software-defined payload architectures and digital beamforming are compressing satellite manufacturing cycles while enabling dynamic spectrum reallocation across orbital tiers.
Software-defined radio payloads are replacing fixed transponder designs with reprogrammable channelizers that optimize bandwidth allocation in real-time. China Aerospace Science and Technology Corporation is integrating these architectures into next-generation geostationary platforms. The technology is automating frequency coordination between LEO and GEO operators, reducing manual interference mitigation overhead.
MIIT's revised spectrum allocation framework is tightening electromagnetic compatibility requirements for terminal manufacturers seeking network access licenses. GB standards for satellite earth station equipment now mandate enhanced out-of-band emission controls. Domestic component suppliers are accelerating gallium nitride amplifier development to meet these specifications.
Service unbundling is fragmenting traditional wholesale capacity contracts as provincial telecom operators seek direct satellite access rather than national intermediary arrangements. Xinjiang and Yunnan regional carriers are negotiating dedicated transponder leases for autonomous network management. This pattern is concentrating procurement influence among sub-national infrastructure authorities with specialized coverage requirements.
China Satellite Communication Market Segmentation
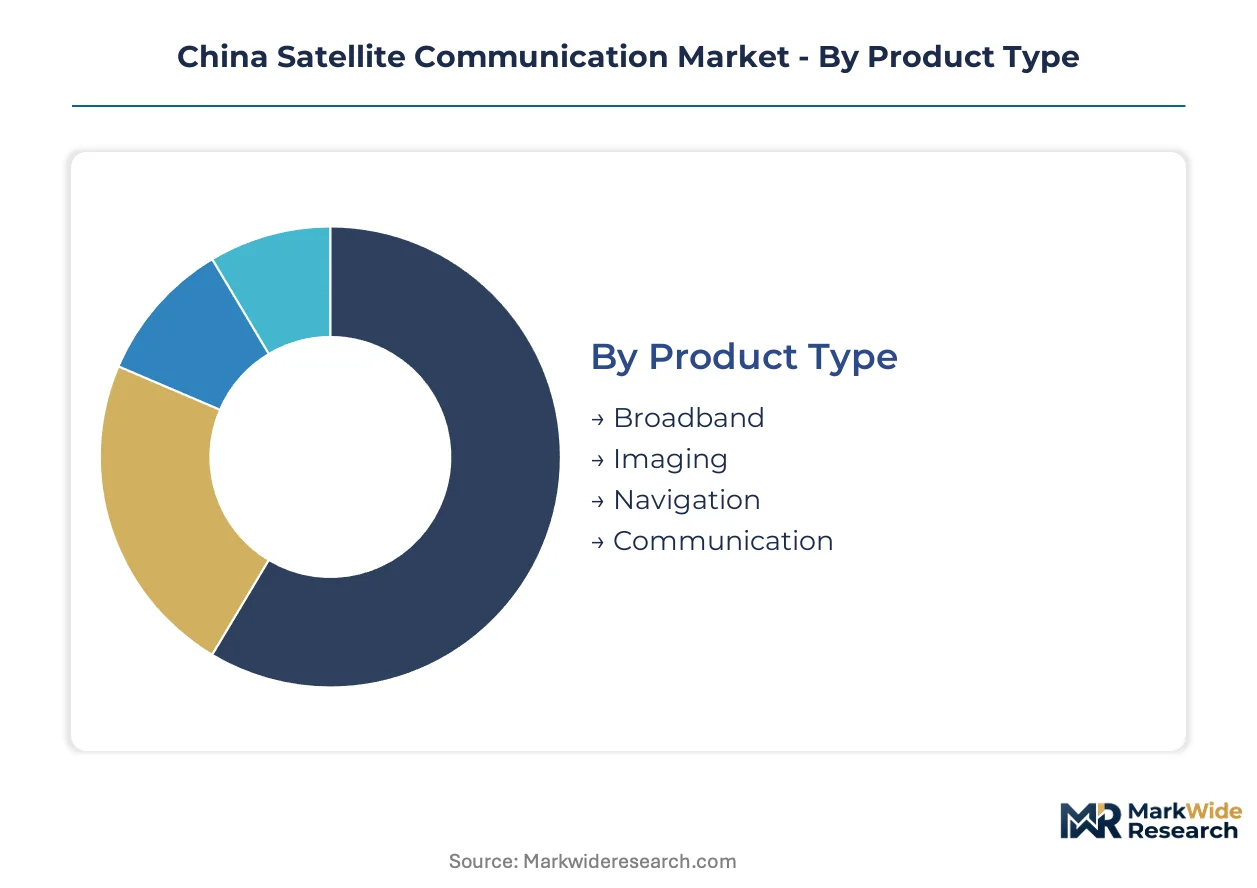
Segmentation in China's satellite communication market reveals divergent investment cycles across orbital tiers and end-use verticals. Procurement patterns differ sharply between sovereign networks absorbing dedicated transponder capacity and commercial operators pursuing HTS economics.
Product Type:
Standalone satellite services operate independently from terrestrial infrastructure, while embedded navigation and communication modules integrate into broader platform architectures.
- Broadband:High-throughput satellite (HTS) architectures deliver concentrated capacity through spot beam configurations. Western provinces including Qinghai and Xinjiang absorb disproportionate bandwidth where fiber deployment remains uneconomical.
- Navigation:BeiDou augmentation services provide centimeter-level positioning through ground-based reference networks. Government pricing protocols stabilize margins despite sovereign network buildout requirements.
- Imaging:Synthetic aperture radar and electro-optical payloads serve environmental monitoring mandates.
- Communication:Traditional bent-pipe transponders persist in legacy enterprise contracts.
Broadband leads volumes today; navigation is gaining share fastest through dual-use deployment.
End User:
Cost tiers separate capex-intensive sovereign procurement from commercial service contracts with shorter renewal cycles.
- Defense:Dedicated Ka-band and Q/V-band transponder capacity supports sovereign secure networks with hardened ground segment requirements. Military modernization programs absorb bandwidth ahead of commercial allocation timelines.
- Government:Civilian agencies procure remote sensing and disaster response capacity through centralized procurement frameworks. MIIT spectrum coordination ensures priority access during emergency activation protocols.
- Telecommunications:Provincial carriers negotiate direct transponder leases bypassing national intermediaries.
- Media:Broadcast distribution contracts concentrate around major event cycles.
Defense leads volumes today; telecommunications is expanding most quickly through provincial unbundling.
Technology:
Orbital altitude determines latency profiles and ground infrastructure requirements, with hybrid architectures emerging across customer tiers.
- LEO:Low Earth orbit constellations deliver sub-50ms latency through dense satellite populations. GalaxySpace and domestic competitors deploy aggressive constellation density for consumer broadband and IoT maritime coverage in the South China Sea.
- GEO:Geostationary platforms anchor enterprise services with proven reliability metrics. China Aerospace Science and Technology Corporation leverages state-backed launch capacity to maintain deployment timelines despite heavy-lift constraints.
- MEO:Medium Earth orbit fills intermediate latency requirements for regional navigation augmentation.
- HTS:High-throughput spot beam technology overlays existing orbital tiers with frequency reuse architectures.
GEO leads volumes today; LEO is climbing the fastest through constellation deployment acceleration.
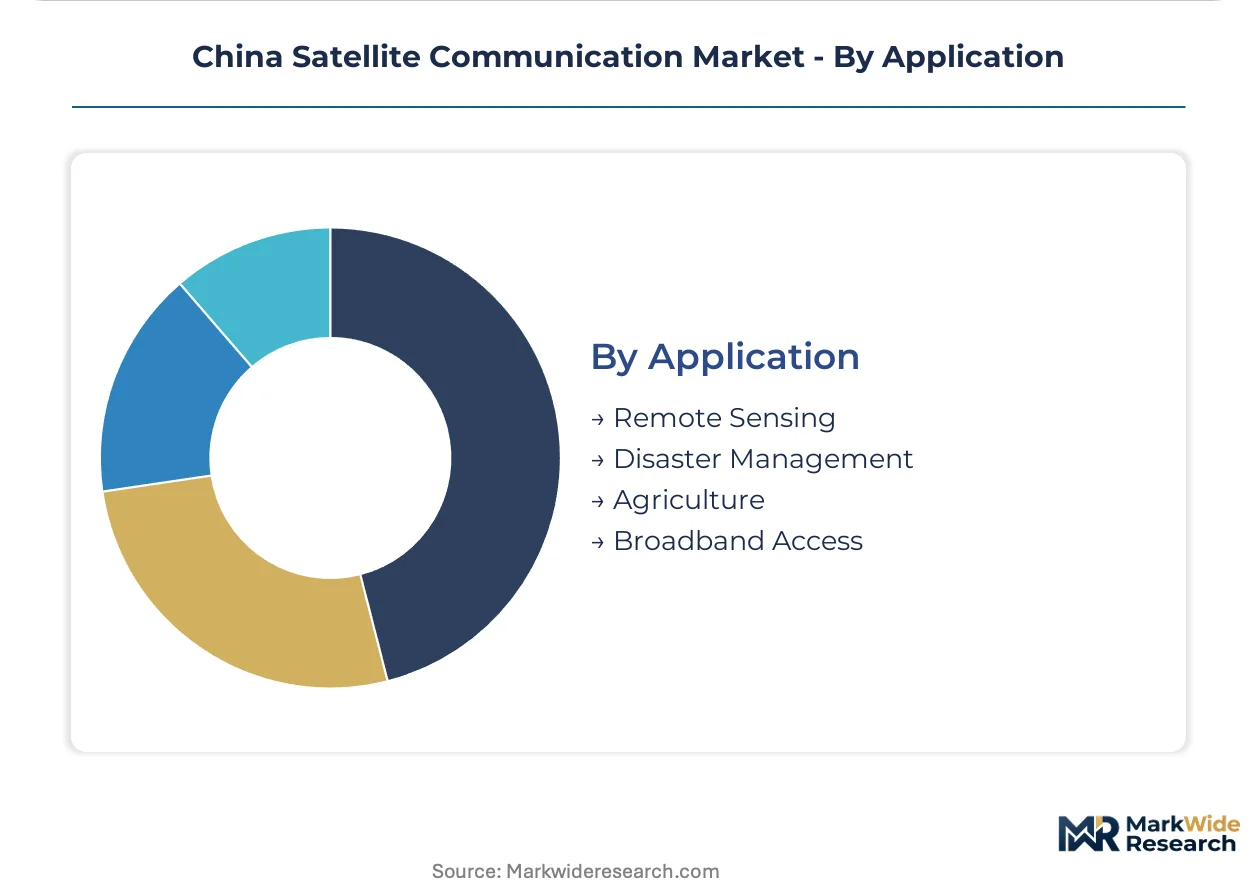
Application:
Customer maturity separates established remote sensing programs from emerging broadband access markets with diverging technical specifications.
- Broadband Access:Satellite internet penetration targets administrative regions with challenging terrain economics. Tibet and Xinjiang present concentrated demand for consumer and small enterprise connectivity.
- Remote Sensing:Agricultural monitoring and environmental surveillance constitute established procurement categories with stable specification requirements.
- Disaster Management:Emergency communications activation protocols prioritize network resilience over bandwidth economics.
- Agriculture:Precision farming applications integrate satellite imagery with ground sensor networks.
Remote sensing leads volumes today; broadband access is gaining share fastest through western province infrastructure gaps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's satellite communication infrastructure originated from state-directed aerospace programs concentrated in Beijing and Xi'an during the 1970s, with commercial expansion accelerating through provincial telecom unbundling in the 2010s.
Beijing-Tianjin-Hebei
Defense bandwidth procurement and sovereign network hardening absorb dedicated Ka-band capacity across military modernization programs. MIIT spectrum allocation rules prioritize electromagnetic compatibility certification for terminal manufacturers headquartered in this corridor. Zhongguancun technology clusters host payload design centers where RF engineers command premium compensation for Q/V-band expertise.
Yangtze River Delta
Shanghai-based maritime operators seek narrowband IoT coverage for South China Sea fishing fleets and container shipping lanes. SAMR antitrust review constrains cross-sector platform consolidation among vertically integrated service providers. Suzhou and Hangzhou industrial parks concentrate thin-film satellite manufacturing facilities where SpaceSail reduces unit mass through specialized production processes.
Pearl River Delta
Guangdong provincial carriers negotiate direct transponder leases bypassing national intermediaries for autonomous network management. MEE environmental assessments for launch sites accelerate renewable energy integration under dual carbon mandates. Shenzhen hardware ecosystems supply gallium nitride amplifiers meeting revised GB standards for out-of-band emission controls.
Sichuan-Chongqing
Radio quiet zones in Guizhou and Sichuan provinces attract new teleport construction serving western bandwidth demand. NMPA-equivalent space quality protocols extend certification timelines for flight-qualified components manufactured in inland facilities. Chengdu satellite integration centers anchor geostationary deployment timelines despite heavy-lift launch capacity constraints.
Western China
Qinghai, Xinjiang, and Tibet administrative regions present concentrated demand for satellite-based internet access where fiber deployment remains uneconomical. Provincial infrastructure authorities absorb HTS spot beam capacity for consumer and small enterprise connectivity across challenging terrain. Kashgar and Lhasa ground stations decouple from fossil-dependent power baselines through solar-hybrid installations.
China Satellite Communication Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across China's satellite communication sector, with state-backed launch capacity anchoring geostationary deployment against private constellation density plays. The vendor base stratifies between sovereign network operators absorbing dedicated transponder capacity and commercial service providers pursuing HTS economics. Three archetypes dominate: aerospace conglomerates with integrated launch-to-service pipelines, specialized constellation operators optimizing LEO density, and provincial telecom carriers unbundling from national intermediaries. Dominant competitive moves include strategic partnerships for ground station buildout and technology licensing for software-defined payload architectures.
Within the state-backed tier, China Aerospace Science and Technology Corporation exemplifies integrated aerospace conglomerates leveraging captive launch capacity. GalaxySpace occupies a position among aggressive LEO constellation operators competing on orbital density metrics. SpaceSail represents specialized manufacturing archetypes focused on thin-film satellite production to reduce unit mass. These three entities anchor divergent strategic vectors across orbital tiers and end-use verticals.
| Leading Market Players |
|---|
| ChinaSat |
| China Aerospace Science and Technology Corporation |
| China SatNet |
| Tiantong Satellite Communications |
| China Aerospace Science and Industry Corporation |
| SpaceSail |
| GalaxySpace |
| Guodian Gaoke |
| China Telecom |
| Others |
Pricing and Supply Chain Analysis
Gallium nitride amplifier costs cascade through satellite terminal manufacturing, compressing margins at mid-tier equipment suppliers while premium phased-array antenna vendors absorb upstream volatility through long-term foundry contracts with domestic semiconductor fabs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs transponder lease markets, with Ka-band spot beam capacity commanding certification-grade premiums for defense-grade electromagnetic compatibility while C-band legacy contracts face price erosion from HTS displacement. Provincial telecom carriers in Xinjiang and Tibet exhibit acute price sensitivity due to infrastructure budget constraints, whereas sovereign network operators absorb premium pricing for Q/V-band hardened ground segments without volume negotiation.
Supply Chain Analysis
Refurbishment flows for decommissioned geostationary satellites remain underdeveloped, leaving stranded orbital assets without secondary component recovery channels. Manufacturing concentration rests on China, South Korea, and Japan for gallium nitride substrates and phased-array antenna modules. Single-source vulnerability permeates domestic heavy-lift launch capacity, with distribution running through state-backed aerospace conglomerates for sovereign procurement and provincial carrier consortia for commercial service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MIIT spectrum reallocation mandates function as a regulatory compounder, accelerating terminal certification demand across electromagnetic compatibility tiers while compressing deployment timelines for ground station operators.
For Market Incumbents: Lock in geostationary anchor tenancy through extended lease structures before LEO constellation density erodes latency-tolerant enterprise contracts. China Aerospace Science and Technology Corporation should deepen backward integration into gallium nitride foundry capacity to secure amplifier supply against foundry allocation constraints. Priority lever rests on software-defined payload architectures enabling dynamic spectrum reallocation without hardware replacement cycles. For New Entrants and Emerging Players: Capture maritime IoT whitespace across South China Sea fishing fleets where narrowband connectivity remains underpenetrated by existing Ku-band broadcast distributors. Guizhou and Sichuan radio quiet zones offer favorable teleport buildout economics for regional carriers seeking autonomous network management. Go-to-market angle should emphasize direct provincial relationships bypassing national intermediary fee structures. For Investors and Strategic Acquirers: Consolidation pressure builds where thin-film manufacturing yield rates compress unit economics below constellation deployment thresholds. Long-term viability favors specialized payload designers with software-defined architectures over pure-play constellation operators facing launch capacity bottlenecks. Signal to monitor: SAMR antitrust clearance velocity for cross-sector platform acquisitions indicating regulatory appetite for vertical integration.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Payload Integration | China Aerospace Science and Technology Corporation automates frequency coordination between LEO and GEO tiers. |
| Thin-Film Manufacturing Scale-Up | SpaceSail reduces unit mass through specialized production processes for dense constellation deployment. |
| Provincial Teleport Buildout | Xinjiang and Tibet carriers negotiate direct transponder leases bypassing national intermediaries. |
| Maritime IoT Coverage Expansion | South China Sea fishing fleets absorb narrowband satellite connectivity through GalaxySpace LEO density. |
| Dual Carbon Ground Station Retrofit | Kashgar and Lhasa teleports decouple from fossil-dependent power baselines through solar-hybrid installations. |
Research Methodology
Multiple input streams — structured interviews with satellite payload engineers, regulatory affairs specialists at MIIT-licensed operators, provincial telecom procurement directors, and defense network architects — were reconciled against secondary validation from GB standards documentation, SAMR antitrust filings, and customs records for gallium nitride component trade flows. Bottom-up triangulation across constellation deployment schedules and top-down reconciliation against MIIT spectrum allocation databases anchored volume estimates.
Data-stream reconciliation applied across the projection horizon modeled segmentation dimensions including orbital tier, end-use vertical, transponder frequency band, and provincial regulatory cluster. CAGRs derived from deployment velocity curves weighted by launch capacity constraints and ground station certification timelines. Industry-specific forecast inputs incorporated MIIT electromagnetic compatibility mandate phase-in schedules and MEE environmental assessment backlogs for inland teleport construction.
Launch schedule delays, thin-film manufacturing yield volatility, and SAMR cross-sector review friction are the dominant revision risks to constellation deployment assumptions. Practitioners should monitor MIIT certification queue lengths and heavy-lift launch manifest updates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
India Satellite-Based Earth Observation Market
Satellite
China Satellite Connectivity Market
Satellite
Germany Satellite-Based Earth Observation Market
Satellite
Reconnaissance Satellite Market
Satellite
Asia-Pacific Remote Sensing Satellites Market
Satellite
Russia Satellite-Based Earth Observation Market
Satellite
EMEA Satellite Antenna Market
Satellite
Latin America Satellite Connectivity Market
Satellite
Tactical Satellite Market
Satellite
Satellite Data Service Market
Satellite
Satellite Transponder Market
Satellite
Cubesat Market
Satellite
Middle East Satellite-Based Earth Observation Market
Satellite
Satellite Communication System Market
Satellite
Satellite Based Augmentation Systems (SBAS) Market
Satellite
Reusable Satellite Launch Vehicle (RSLV) Market