
 Payday Loans Market | 2026-2036
Payday Loans Market Size, Share, and Industry Trends Forecast 2026-2036
Payday Loans Market Intelligence
A capital-intensity divergence between storefront networks and cloud-native platforms is rotating competitive advantage toward technology-heavy operators. Enova International leverages automated risk scoring to sustain lower per-loan acquisition costs across multiple jurisdictions. Advance America anchors its position through dense physical presence in states with permissive rate caps, while MoneyLion competes via embedded banking apps that cross-sell credit to existing deposit customers.
Payday loans are small-dollar, short-term unsecured credit instruments typically issued for amounts under one thousand dollars with two-to-four-week maturities and single-balloon repayment structures. Lenders assess borrower eligibility through automated verification of employment and checking account history rather than traditional credit scores. Installment loan products now capture the fastest growth within the loan type dimension as regulators in several countries restrict single-payment structures. Low-income workers dominate the borrower profile segment where demand concentrates, while direct deposit disbursement leads the payment method category by volume due to instant funding integration with payroll systems.
The Consumer Financial Protection Bureau shapes US market access through underwriting and ability-to-repay requirements, while the Financial Conduct Authority enforces price caps and continuous payment authority restrictions in the United Kingdom. Australia's Australian Securities and Investments Commission administers responsible lending obligations that limit loan frequency and mandate hardship protocols. Stakeholders must monitor whether emerging open-banking data regimes in these jurisdictions will displace legacy credit bureau dependencies and redefine risk-based pricing boundaries.
Market Dynamics
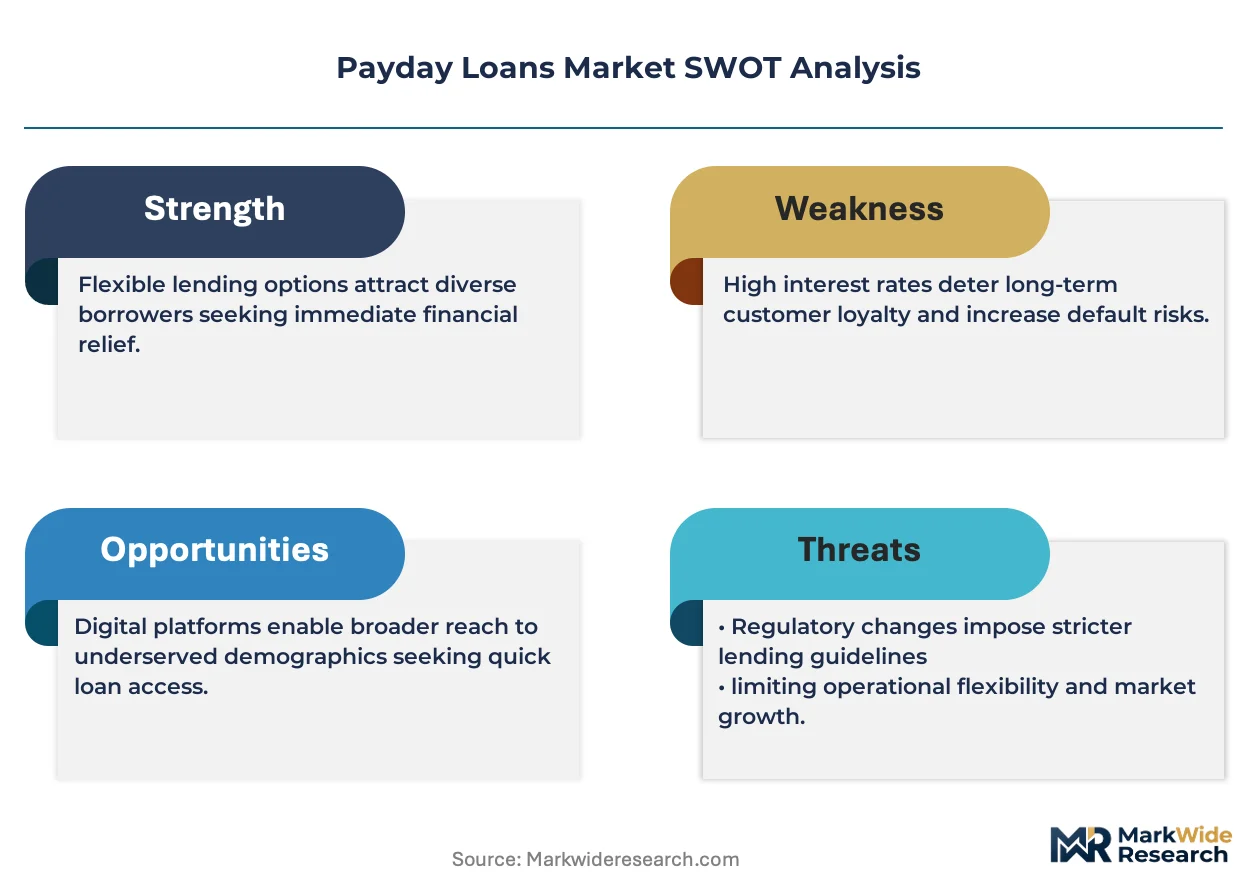
Digital underwriting platforms are displacing storefront origination across licensed lending markets, compressing per-loan acquisition costs while national regulators tighten disclosure rules without eliminating licensed channels. This technology-driven restructuring concentrates competitive advantage with operators possessing cloud-native infrastructure and multi-jurisdictional compliance capabilities.
Growth Catalysts
- Wage stagnation among low-income workers:Households facing flat real wages increasingly turn to short-term credit instruments to bridge cash-flow gaps between pay cycles.
- Automated employment verification:Real-time payroll data integration enables instant eligibility assessment without traditional credit bureau dependency.
- Installment loan product expansion:Regulatory restrictions on single-balloon repayment structures in multiple jurisdictions accelerate multi-payment product adoption.
Market Restraints
- Rate cap heterogeneity:US state-level usury limits create operational complexity for national platforms seeking uniform pricing models.
- Continuous payment authority restrictions:UK Financial Conduct Authority rules limit automated repayment collection methods and increase servicing costs.
- Credit bureau dependency displacement:Open-banking data regimes threaten legacy risk-scoring infrastructure investments and established underwriting workflows.
Strategic Opportunities
- Embedded banking integration:Cross-selling credit through existing deposit relationships reduces customer acquisition expenditure and improves retention metrics.
- Open-banking data utilization:Transaction-level financial data enables more granular risk assessment than traditional credit scores permit.
- Hardship protocol automation:Australian Securities and Investments Commission-mandated restructuring tools create differentiated service capabilities.
Industry Challenges
- Multi-jurisdictional compliance engineering:Software architecture must simultaneously accommodate divergent national disclosure, pricing, and collection regulations.
- Legacy system integration friction:Cloud-native platforms face technical debt when connecting to established core banking infrastructure at partner institutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Payday Loans Market |
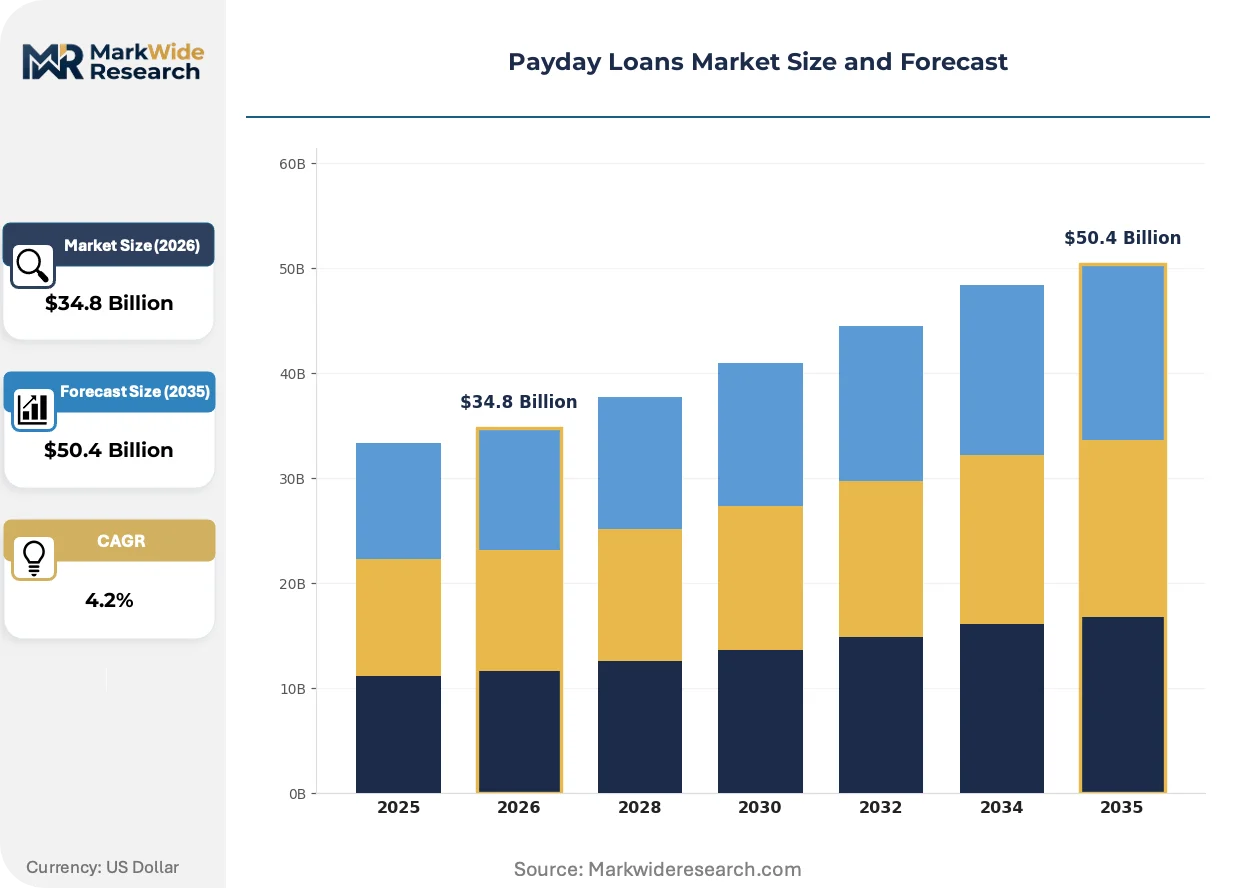
| Market Size in 2026 | $34.8 Billion |
| Market Size in 2035 | $50.4 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Loan Type: Single Payment, Installment, Traditional, Online Borrower Profile: Students, Low-Income Workers, Retirees, Unemployed Duration: Short-Term, Medium-Term, Long-Term, Emergency Payment Method: Direct Deposit, Check, Prepaid Debit, Others |
| Companies Covered | Moneytree, MoneyLion, Enova International, OnDeck, LendingClub, ACE Cash Express, NetCredit, Blue Vine, Advance America, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Payday Loans Market Strategic Shifts & Innovations
Automated risk-scoring algorithms and instant disbursement rails are restructuring how short-term credit reaches borrowers. These capabilities compress origination timelines from days to minutes while reducing human underwriting overhead.
Machine-learning-powered alternative data analysis is displacing traditional FICO-score dependency in borrower qualification protocols. Subprime and thin-file applicants gain access to credit previously unavailable through conventional channels. Lenders adopting these models report improved loss-rate predictability relative to legacy scoring methods.
The Consumer Financial Protection Bureau's ability-to-repay requirements and the UK Financial Conduct Authority's price caps are forcing product-structure innovation across Anglo-American markets. Single-payment payday instruments face compression while installment alternatives expand. Australia, Canada, and New Zealand regulators are monitoring these frameworks for potential adoption.
Borrowers increasingly demand mobile-first application experiences with instant funding confirmation. Storefront networks lose volume to smartphone-originated products offering direct deposit integration. This behavioral shift concentrates fastest in urban labor markets with high gig-economy employment density.
Payday Loans Market Segmentation
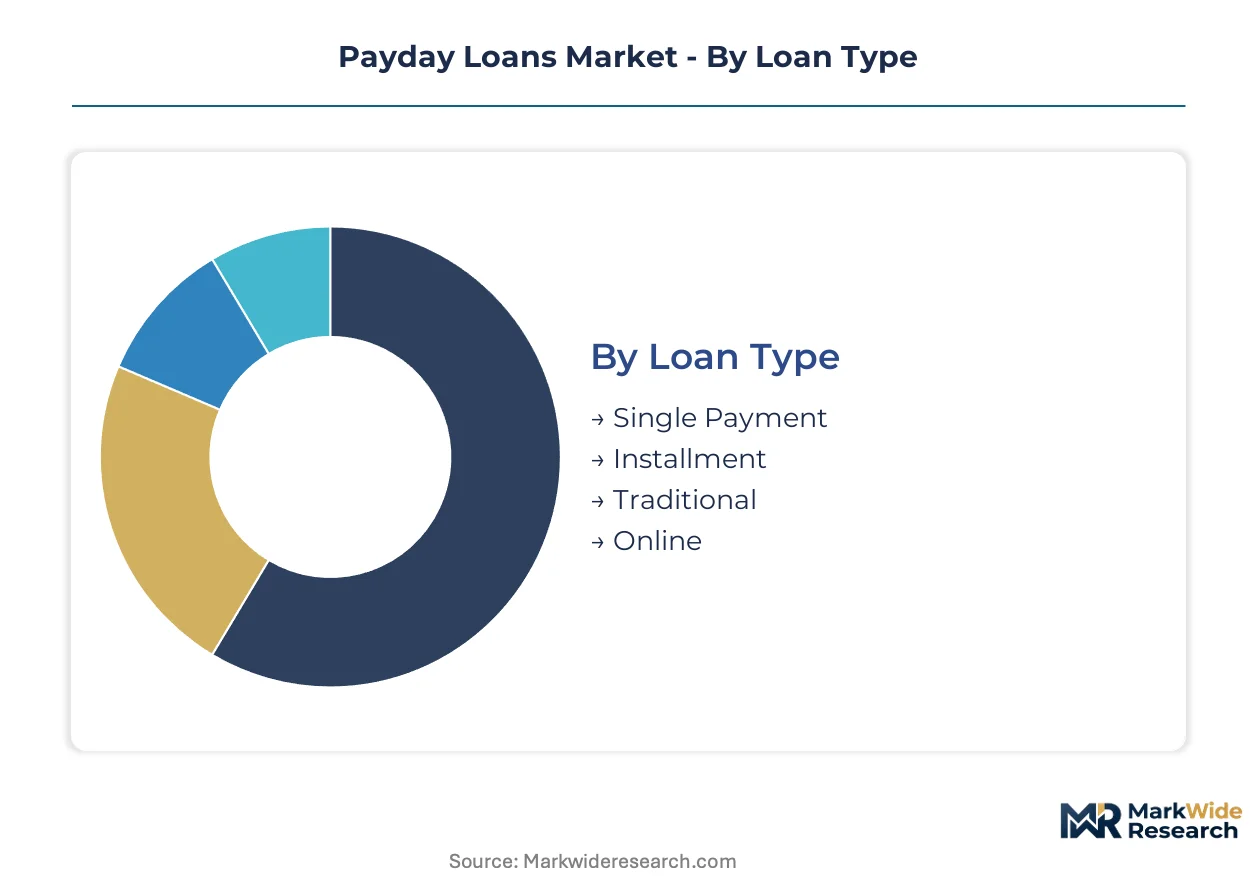
Segmentation in payday lending reveals how product structure, borrower vulnerability, and disbursement technology intersect to determine risk profiles and unit economics. Understanding these dimensions helps operators align underwriting automation with regulatory constraints across licensed markets.
Loan Type:
Single-payment products concentrate in permissive US states and legacy storefront networks, while multi-payment structures dominate export-oriented digital platforms serving multiple jurisdictions.
- Single Payment:Balloon-repayment instruments with two-to-four-week maturities remain prevalent in US states without rate caps. Demand clusters among gig-economy workers in urban labor markets facing irregular income timing.
- Installment:Multi-payment products with three-to-twelve-month terms now lead product innovation. UK Financial Conduct Authority price caps and US state restrictions on balloon structures accelerate adoption across digital-first lenders.
- Traditional:Storefront-originated instruments with paper documentation and cash disbursement. Presence concentrates in rural markets with limited banking infrastructure and older borrower demographics.
- Online:Fully automated origination through mobile applications with instant bank verification. Cloud-native platforms leverage this segment for multi-jurisdictional scale.
Single Payment holds the largest share; momentum sits with Installment.
Borrower Profile:
Cost-tier segmentation separates thin-file applicants requiring alternative data scoring from established subprime borrowers with bureau histories.
- Low-Income Workers:Wage-stagnant households in service-sector employment represent the primary demand concentration. Automated payroll verification enables instant eligibility assessment without traditional credit scores.
- Students:Young borrowers with limited credit histories access small-dollar credit through education-focused fintech platforms. Demand concentrates around tuition payment deadlines and seasonal housing deposits.
- Retirees:Fixed-income seniors with thin credit files use short-term products to bridge Social Security payment gaps. Australian Securities and Investments Commission hardship protocols particularly affect servicing requirements for this cohort.
- Unemployed:Benefit-dependent borrowers face restricted access as ability-to-repay requirements tighten across Anglo-American markets. Alternative income verification through government deposit records enables limited origination.
Low-Income Workers anchor volume concentration; Students are expanding most quickly.
Duration:
Maturity segmentation tracks regulatory pressure toward longer-term structures that amortize risk while increasing total interest cost.
- Short-Term:Products under thirty days face compression from US Consumer Financial Protection Bureau underwriting requirements and UK continuous payment authority restrictions.
- Medium-Term:Thirty-to-ninety-day instruments balance regulatory compliance with borrower preference for rapid obligation clearance. Digital platforms optimize for this duration to minimize default probability curves.
- Long-Term:Multi-month amortizing products resemble traditional personal loans more than classic payday structures. Australian responsible lending obligations mandate detailed suitability assessments for extended maturities.
- Emergency:Same-day disbursement products with twenty-four-to-seventy-two-hour terms command premium pricing. Demand spikes around payroll system failures and unexpected medical obligations.
Short-Term retains historical dominance; Medium-Term shows steepest expansion trajectory.
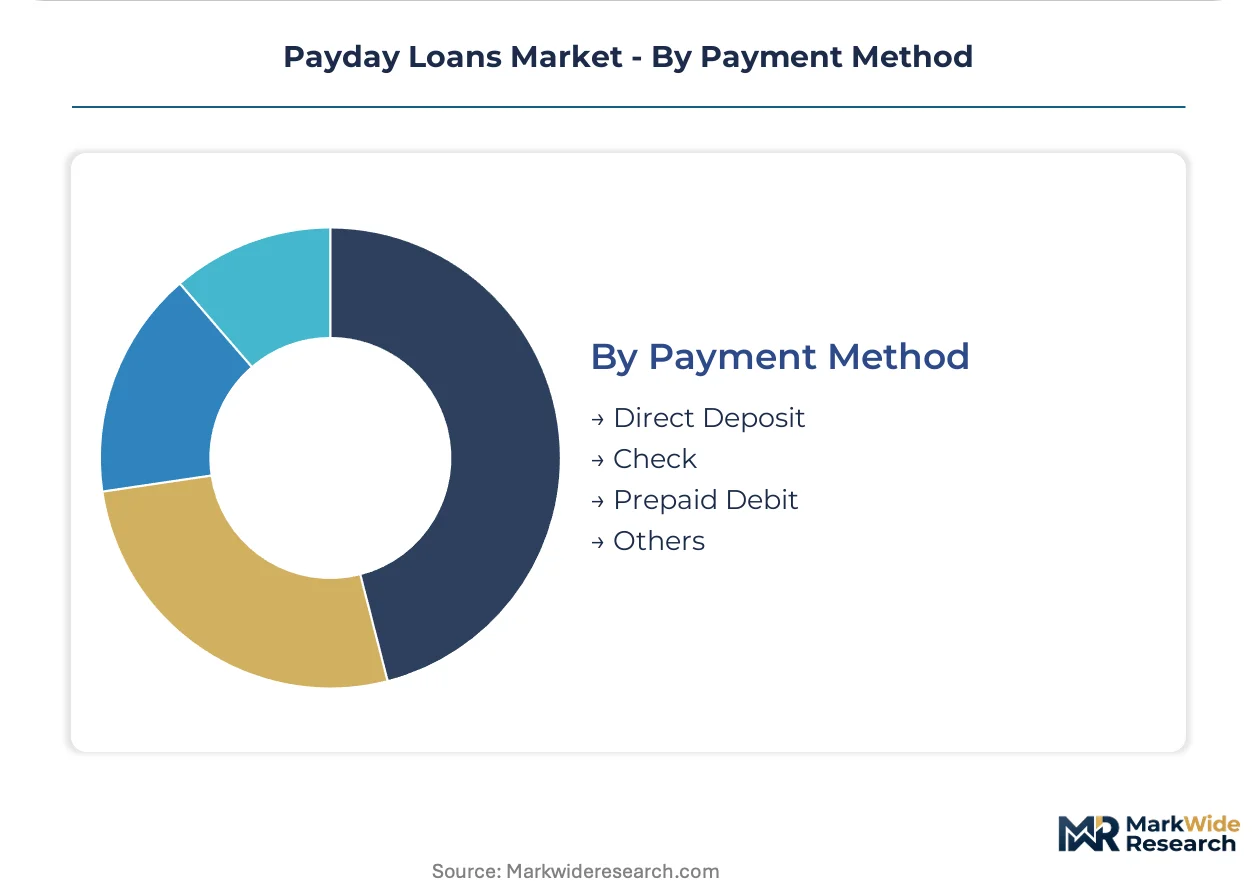
Payment Method:
Disbursement technology segmentation reflects infrastructure modernization and unbanked population access constraints.
- Direct Deposit:Instant funding through automated clearing house rails dominates digital origination. Integration with payroll systems enables real-time eligibility verification and same-day availability.
- Prepaid Debit:Card-based disbursement serves underbanked borrowers without traditional checking accounts. MoneyLion and similar embedded banking platforms leverage this method for cross-selling retention.
- Check:Paper instruments persist in storefront networks serving rural markets and older demographics. Manual processing increases per-loan servicing cost and extends funding timelines.
- Others:Cash pickup locations and mobile wallet transfers serve immigrant communities and gig workers with international remittance needs. Limited regulatory clarity constrains scale.
Direct Deposit commands volume leadership; Prepaid Debit is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The payday lending trade balance tilts toward service exports from technology-intensive operators in Anglo-American markets, while import-dependent regions rely on cross-border digital platforms for credit access. Capital flows concentrate where regulatory clarity permits licensed lending at scale.
United States
Wage stagnation in service-sector employment and gig-economy income volatility sustain demand concentration. The Consumer Financial Protection Bureau enforces ability-to-repay underwriting requirements that reshape product structures. California and New York anchor digital origination volume, while Texas and Florida retain dense storefront networks in permissive regulatory environments.
United Kingdom
Cost-of-living pressures and irregular employment patterns in urban labor markets drive borrower reliance on short-term credit. The Financial Conduct Authority administers price caps and continuous payment authority restrictions that compress margins. London fintech clusters concentrate cloud-native underwriting platform development for export to Commonwealth markets.
Australia
Low-income households facing utility bill spikes and medical cost shocks generate consistent demand for emergency credit products. The Australian Securities and Investments Commission mandates responsible lending obligations and hardship protocols that increase compliance overhead. Sydney and Melbourne host the dominant digital lending infrastructure serving both domestic and regional Asia-Pacific borrowers.
Canada
Provincial rate caps vary from Quebec's restrictive framework to more permissive environments in Alberta and Ontario, creating regulatory arbitrage opportunities. The Financial Consumer Agency of Canada coordinates disclosure standards without federal usury limits. Toronto concentrates alternative lending platform headquarters serving underbanked populations across the Prairie Provinces.
Germany
Migrant worker populations and thin-file EU nationals excluded from traditional banking access create niche demand for short-term credit. BaFin supervision of consumer lending imposes strict affordability assessments and advertising restrictions. Berlin fintech incubators experiment with payroll-integrated microcredit models for gig-economy platform workers.
Payday Loans Market Key Industry Players
Concentration sits with technology-heavy operators possessing multi-jurisdictional compliance infrastructure and automated underwriting capabilities. The vendor base spans legacy storefront networks, cloud-native digital platforms, and embedded banking applications. Three archetypes dominate: rate-cap arbitrageurs maintaining dense physical presence in permissive states, algorithmic risk-scoring specialists compressing acquisition costs through automation, and neobank integrators cross-selling credit to existing deposit relationships. Competitive moves center on geographic expansion into regulatory gray zones and portfolio diversification toward longer-duration installment products.
Within the cloud-native platform tier, Enova International, MoneyLion, and Advance America exemplify divergent strategic positioning. Enova International represents algorithmic underwriting specialization with multi-jurisdictional scale. MoneyLion occupies the embedded banking integration archetype, leveraging deposit relationships for credit cross-sell. Advance America anchors the physical network preservation strategy, maintaining storefront density where rate caps permit legacy product economics.
| Leading Market Players |
|---|
| Moneytree |
| MoneyLion |
| Enova International |
| OnDeck |
| LendingClub |
| ACE Cash Express |
| NetCredit |
| Blue Vine |
| Advance America |
| Others |
Cost & Logistics Intelligence
Balloon-repayment contract structures lock in immediate fee visibility for storefront operators while constraining pricing flexibility for multi-jurisdictional digital platforms. This product-structure rigidity concentrates margin pressure on cloud-native lenders facing divergent state rate caps across the United States.
Pricing Analysis
Low-income workers anchor per-loan pricing structures across single-payment and installment products. Three-tier pricing stratification separates emergency same-day disbursement from standard direct-deposit terms and deferred-funding economy tiers. Cost compression in the economy tier intensifies because automated employment verification reduces underwriting overhead. Gig-economy borrowers exhibit highest price sensitivity; retirees on fixed incomes show lowest elasticity due to limited alternative credit access.
Supply Chain Analysis
Minimal physical inventory and near-zero lead times characterize payday lending's capital-light origination model. Funding liquidity concentrates in the United States, United Kingdom, and Australia where licensed deposit-taking institutions provide wholesale credit lines. Raw material dependencies center on payroll data APIs, automated clearing house rails, and mobile application infrastructure. Single-source vulnerability rests on concentrated payroll processor integrations. Distribution runs through embedded banking apps, standalone mobile platforms, and legacy storefront networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in regulatory arbitrage zones where state-level rate cap heterogeneity creates niche positioning for specialized operators. Wage stagnation among service-sector workers fragments demand across multiple product structures and duration tiers.
For Market Incumbents: Secure multi-jurisdictional compliance architecture before open-banking data regimes displace legacy credit bureau dependencies. Consolidate automated underwriting capabilities through cloud-native infrastructure investment. Advance America and similar storefront-heavy operators face substitution threat from digital-first entrants; vertical integration into payroll data partnerships offers defensive positioning. For New Entrants and Emerging Players: ASIC hardship protocol certification fast-tracks entry into Australia's regulated market with differentiated service capabilities. Target medium-term installment products in US states restricting single-balloon structures. White-space concentration sits in prepaid debit disbursement for underbanked populations lacking traditional checking access. Go-to-market leverage rests on embedded banking partnerships with existing deposit relationships. For Investors and Strategic Acquirers: Capital is best deployed toward algorithmic risk-scoring specialists with multi-jurisdictional scale rather than storefront networks facing volume compression. Long-term viability favors operators possessing cloud-native infrastructure and automated employment verification capabilities. Signal to monitor: regulatory adoption of open-banking data regimes displacing FICO-score dependency in borrower qualification protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Installment Product Expansion | UK Financial Conduct Authority price caps accelerate multi-payment structure adoption across Anglo-American markets. |
| Payroll Data Integration | Real-time employment verification through ADP and Paycom APIs compresses origination timelines to minutes. |
| Hardship Protocol Automation | Australian Securities and Investments Commission mandates create differentiated service capabilities for regulatory compliance. |
| Embedded Banking Partnership | Cross-selling credit through MoneyLion-style deposit relationships reduces customer acquisition expenditure materially. |
| Open-Banking Data Utilization | Transaction-level financial data from Plaid and Yodlee enables granular risk assessment beyond traditional credit scores. |
Research Approach
A standing panel of digital lending platform executives, storefront network operators, regulatory compliance officers, and payroll data integration specialists provided ongoing calibration throughout the study period. Primary interviews with these stakeholders combined with secondary validation against Consumer Financial Protection Bureau enforcement actions, Financial Conduct Authority price cap reviews, Australian Securities and Investments Commission licensing records, and state-level usury statute databases. Bottom-up loan origination volume estimates triangulated against top-down household credit demand surveys.
Consistency checks validated volume and value outputs against external benchmarks including central bank consumer credit statistics and industry association origination reports. The analytical framework modeled segmentation across loan type, borrower profile, duration tier, and payment method dimensions throughout the forecast period. CAGRs derived from trend extrapolation of origination volumes adjusted for regulatory intervention scenarios. Forecast inputs incorporated wage stagnation indices, gig-economy employment density metrics, and automated underwriting penetration rates.
The analysis sits within stated boundaries; outcomes outside sustained wage stagnation or accelerated open-banking adoption would require recalibration. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and technology migration timelines. Credit bureau displacement risk and continuous payment authority restriction expansion represent specific factors that could revise trajectory. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Peer-To-Peer Lending Market
Loans and Leasing
Syndicated Loans Market
Loans and Leasing
Commercial Vehicle Rental and Leasing Market
Loans and Leasing
Online Payday Loans Market
Loans and Leasing
Asia-Pacific Mortgage/Loan Brokers Market
Loans and Leasing
Home Equity Lending Market
Loans and Leasing
India Student Loan Market
Loans and Leasing
US Auto Loan Market
Loans and Leasing
Russia Student Loan Market
Loans and Leasing
Asia-Pacific Used Car Financing Market
Loans and Leasing
Global Automotive Financing Market
Loans and Leasing
Automobile Rental and Leasing Market
Loans and Leasing
Canada Student Loan Market
Loans and Leasing
France Auto Loan Market
Loans and Leasing
India Auto Loan Market
Loans and Leasing
Alternative Financing Market