
 South Korea Auto Loan Market | 2026-2036
South Korea Auto Loan Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Auto Loan Market Insights
MFDS is repositioning consumer protection mandates for financial products, compelling lenders to recalibrate risk models and disclosure protocols. Hyundai Capital Services leverages its captive relationship with the country's dominant automotive manufacturer to sustain preferential pricing on new vehicle portfolios. Hana Capital anchors its position through deep integration with the banking parent's deposit base and branch network. BMW Group Financial Services Korea differentiates by occupying the premium import segment with specialized balloon-payment structures.
A South Korea auto loan represents a secured credit instrument collateralized by vehicle title, typically featuring loan-to-value ratios between 70% and 90% depending on borrower credit tier and vehicle age, with primary purpose of enabling consumer and commercial vehicle acquisition without full upfront capital outlay. New car loans command the largest volume share given Korea's structured replacement cycle and manufacturer-backed incentive programs, while lease financing is expanding fastest among urban professionals seeking lower monthly obligations and defined upgrade paths. Used car loans carry elevated yields but require more intensive collateral valuation given depreciation curve variability across domestic and import nameplates.
The Financial Services Commission enforces debt-service-ratio ceilings and stress-testing protocols that constrain maximum advance amounts and shape product design toward shorter-term structures. MFDS disclosure requirements mandate standardized total-cost-of-credit presentations, reducing opacity in promotional rate offerings. KFTC monitors anti-competitive bundling between captive finance arms and dealership networks. Stakeholders must monitor whether regulatory pressure on household debt aggregates triggers further tightening of auto credit eligibility thresholds or accelerated supervisory review of non-bank lenders.
Market Dynamics
Financial Services Commission debt-service-ratio ceilings are compressing maximum loan advance amounts and forcing product redesign toward shorter-term structures across the South Korean auto credit landscape.
Growth Catalysts
- Lease financing uptake:Young urban professionals in Seoul and Gyeonggi province are gravitating toward lease products that offer lower monthly obligations and defined vehicle upgrade paths.
- MFDS disclosure mandates:Standardized total-cost-of-credit presentations reduce opacity in promotional rate offerings and build borrower trust.
- Seoul metropolitan concentration:Demand clustering in the capital region enables operational efficiencies for lenders with dense branch networks.
Market Restraints
- Household debt scrutiny:Financial Services Commission pressure on aggregate household debt loads threatens further tightening of auto credit eligibility thresholds.
- Used car collateral volatility:Depreciation curve variability across domestic and import nameplates complicates collateral valuation and elevates loss-given-default estimates.
- Captive bundling constraints:Korea Fair Trade Commission monitoring of anti-competitive bundling between captive finance arms and dealership networks limits distribution control.
Strategic Opportunities
- Jeolla and Gyeongsang underpenetration:Secondary metropolitan areas outside Seoul-Incheon corridor present whitespace for specialized used-vehicle financing products.
- Electric vehicle transition:Government carbon-neutral mobility incentives create regulatory tailwinds for green auto loan product development.
- Digital origination platforms:Mobile-first application and approval workflows are capturing time-sensitive borrowers in urban professional segments.
Industry Challenges
- Stress-testing compliance:MFDS-mandated scenario analysis requirements demand enhanced data infrastructure and modeling capabilities at non-bank lenders.
- Legacy system integration:Established banks face friction connecting modern digital lending interfaces to core banking platforms built for traditional installment structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Auto Loan Market |
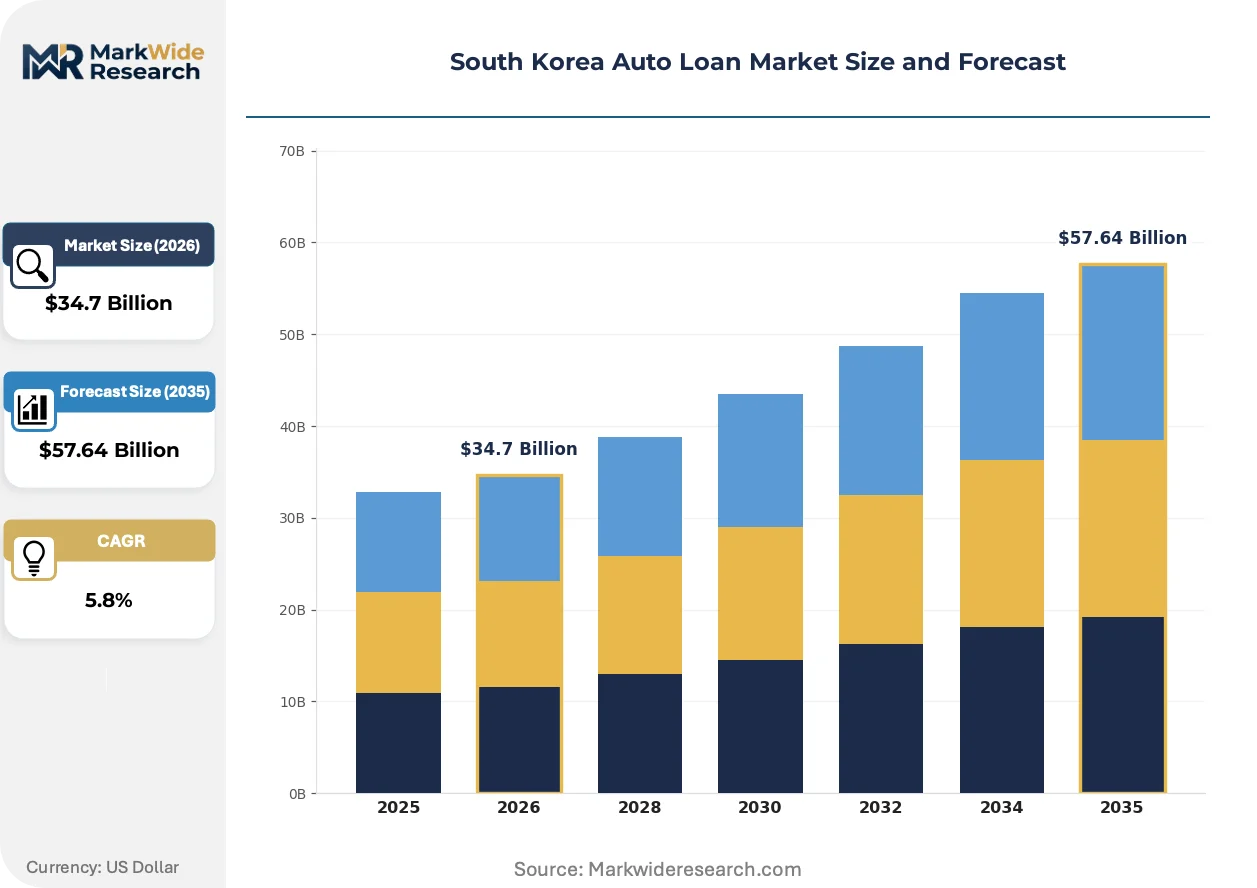
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $57.64 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Loan Type: New Car Loans, Used Car Loans, Refinancing, Lease Financing Customer Type: Individual Buyers, Corporate Fleets, Rental Services, Dealerships Interest Rate Type: Fixed Rate, Variable Rate, Hybrid Rate, Promotional Rate Term Length: Short Term, Medium Term, Long Term, Flexible Term |
| Companies Covered | Hana Capital, BMW Group Financial Services Korea, Hyundai Capital Services, RCI Financial Services, Mercedes Benz Group, IBK (Industrial Bank of Korea), Woori Bank, Toyota Financial Services, SHINHAN FINANCIAL GROUP, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Auto Loan Market Trends and Innovations
Digital underwriting platforms and alternative data sources are compressing approval timelines and expanding credit access to thin-file borrowers across the South Korean auto finance sector.
Artificial intelligence-driven credit scoring is expanding into non-traditional data streams including utility payment histories and mobile subscription records. Tier-2 and tier-3 borrowers in Gyeonggi province are accessing approvals previously unavailable through conventional FICO-equivalent models. This technology is expanding into subprime segments that legacy scorecards systematically excluded.
MFDS consumer protection mandates now require granular breakdowns of total interest costs and early termination penalties in all promotional materials. Lenders must recalibrate marketing copy and sales training to emphasize lifetime cost over headline rates. The used car financing segment faces the steepest compliance adjustment given its historically opaque fee structures.
Subscription-based vehicle access models are displacing traditional ownership among Seoul-based professionals under age 35. Fleet operators and mobility platforms are capturing demand that banks previously served through conventional installment loans. This shift concentrates most visibly in premium import segments where balloon-payment structures already conditioned buyers to non-ownership mentalities.
South Korea Auto Loan Market Segmentation
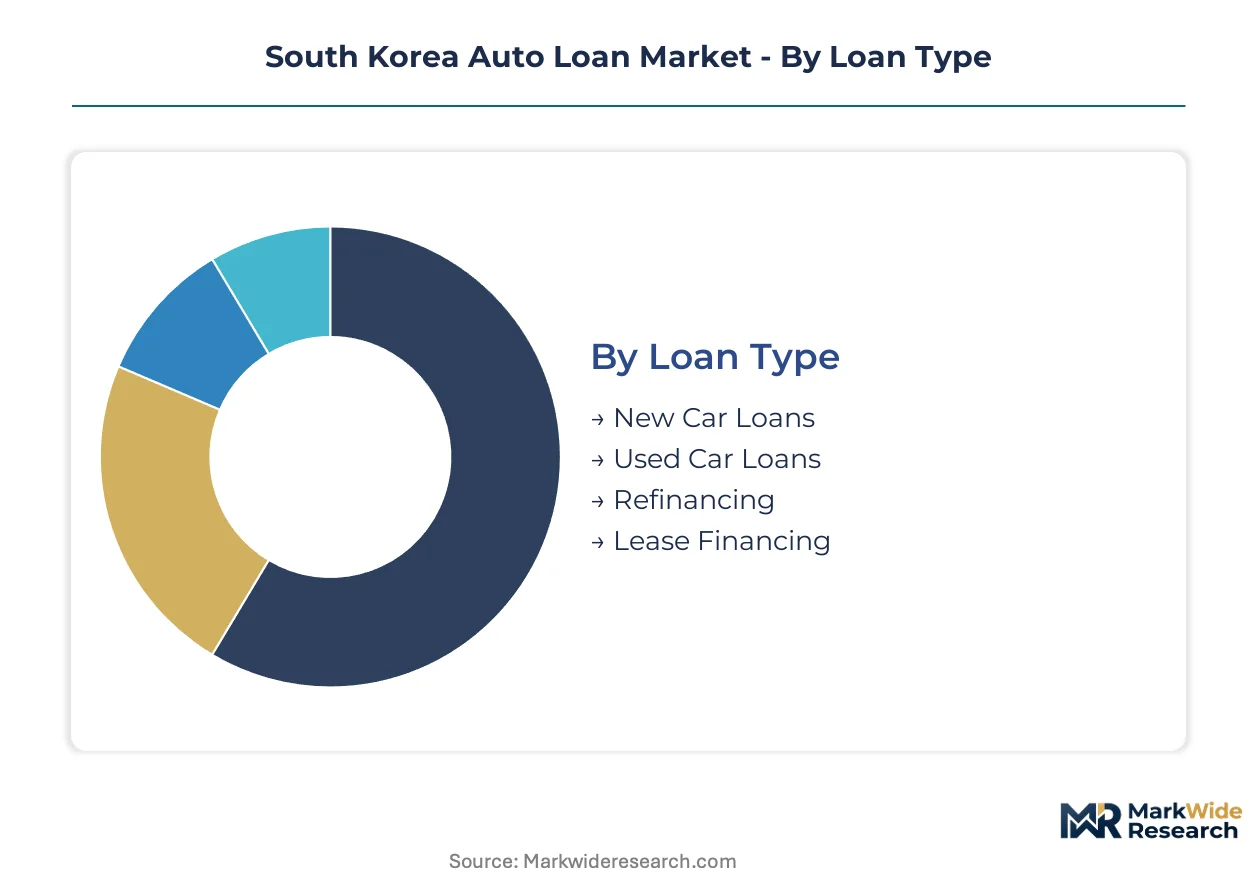
Segmentation in the South Korea auto loan market reveals how regulatory constraints and borrower preferences fragment product design across collateral type, customer risk profiles, and duration structures. Understanding these divisions exposes where Financial Services Commission debt-service-ratio rules compress margins and where lease financing innovations capture underserved urban professionals.
Loan Type:
Collateral age and ownership transfer mechanics define the technical architecture of South Korean auto credit products, with each structure carrying distinct lien perfection requirements and residual value exposure.
- New Car Loans:Secured instruments collateralized by first-title vehicles with manufacturer-backed warranty coverage reducing lender collateral risk. Volume concentrates among Seoul and Gyeonggi province households replacing vehicles on structured three-to-five year cycles, with Hyundai and Kia captive finance arms dominating through bundled dealership incentives.
- Lease Financing:Closed-end lease structures with predetermined residual values and defined upgrade pathways. Young professionals in Seoul's Gangnam and Yeouido districts gravitate toward lower monthly obligations and tax-advantaged business leasing arrangements, driving the steepest expansion trajectory among all loan types.
- Used Car Loans:Higher-yield products requiring intensive collateral valuation given depreciation variability across domestic and import nameplates.
- Refinancing:Rate reduction instruments capturing borrowers from competing lenders through balance transfer promotions.
New Car Loans lead on scale; Lease Financing leads on momentum.
Customer Type:
Borrower organizational form shapes underwriting complexity, with corporate structures accessing fleet pricing and individual applicants facing stricter debt-service-ratio scrutiny.
- Individual Buyers:Retail borrowers subject to Financial Services Commission household debt aggregate monitoring and standardized MFDS disclosure requirements. Applications concentrate in Seoul metropolitan area and Gyeonggi province where digital origination platforms reduce friction for time-sensitive purchasers.
- Corporate Fleets:Commercial borrowers with consolidated credit facilities and bulk purchasing leverage. Tax-optimized leasing structures and maintenance bundling drive concentration among logistics operators and ride-hailing platforms expanding vehicle pools in Busan and Incheon logistics corridors.
- Rental Services:Short-term fleet operators with high turnover collateral pools and accelerated depreciation schedules.
- Dealerships:Inventory floorplan financing for new and used vehicle stock.
Individual Buyers lead on scale; Corporate Fleets lead on momentum.
Interest Rate Type:
Rate structure selection reflects borrower risk tolerance and interest rate outlook, with hybrid instruments gaining traction amid Bank of Korea policy uncertainty.
- Fixed Rate:Predetermined coupon structures eliminating refinancing risk for conservative borrowers. Demand clusters among first-time purchasers in Gyeonggi province seeking payment certainty against household debt scrutiny.
- Variable Rate:Floating instruments indexed to base rate movements. Rate-sensitive borrowers in Seoul's professional segments accept exposure for initial rate discounts.
- Hybrid Rate:Blended structures with fixed initial periods converting to variable terms.
- Promotional Rate:Teaser structures requiring MFDS-mandated total-cost-of-credit disclosure.
Fixed Rate leads on scale; Hybrid Rate leads on momentum.
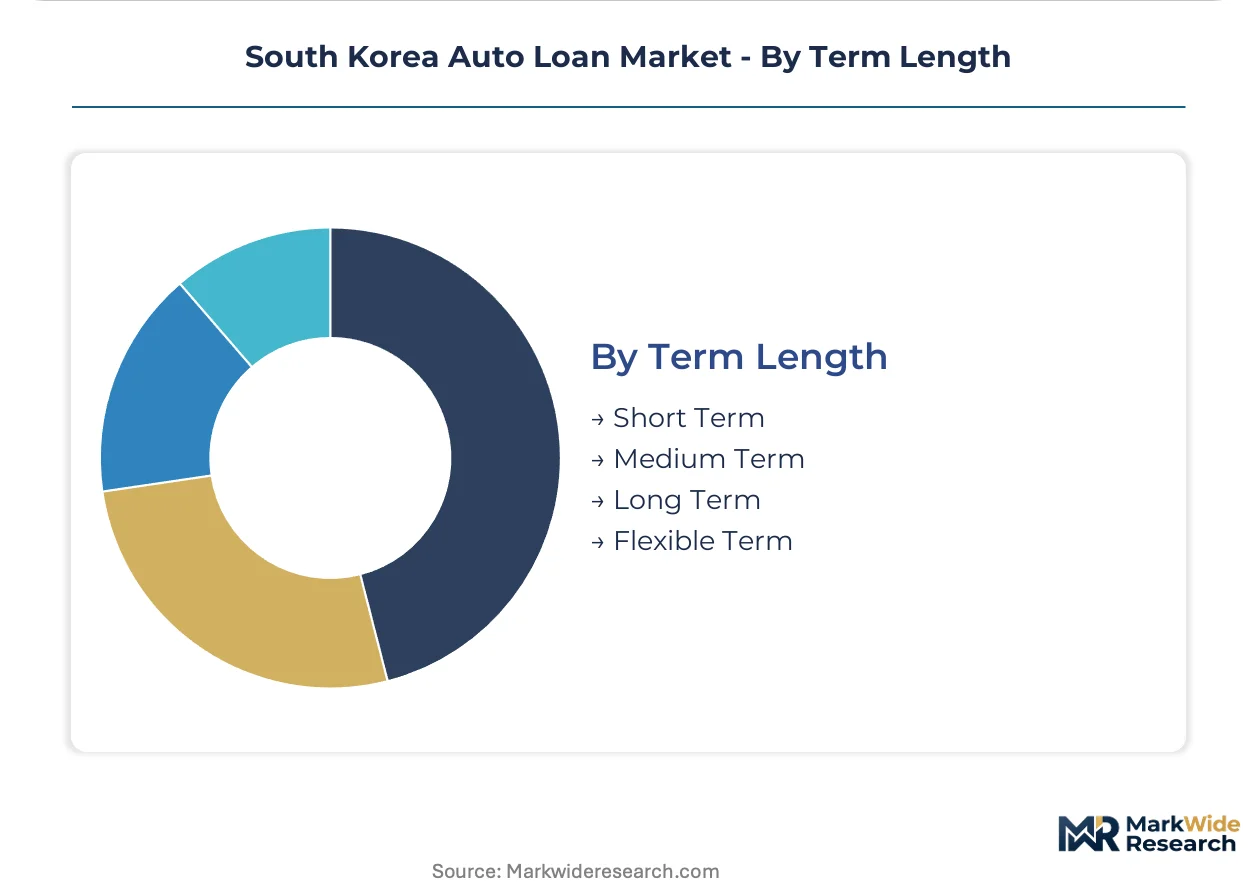
Term Length:
Duration selection interacts directly with Financial Services Commission debt-service-ratio ceilings, compressing maximum advance amounts and favoring shorter structures.
- Short Term:Structures under 36 months minimizing total interest cost and aligning with Korean vehicle replacement cycles. Preferred by high-income borrowers in Seoul's Seocho and Songpa districts seeking rapid equity buildup.
- Medium Term:37-60 month structures balancing monthly affordability with interest exposure. Captures mass-market demand in Gyeonggi province where household debt ratios face regulatory tightening.
- Long Term:Extended durations exceeding 60 months with elevated total cost.
- Flexible Term:Customizable structures with prepayment options and skip-payment features.
Medium Term leads on scale; Short Term leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Financial services talent clusters in Seoul anchor the national auto lending infrastructure, with underwriting expertise and risk management capabilities concentrating in the capital region before radiating outward.
Seoul Capital Area
Digital-first origination platforms capture time-sensitive borrowers in Gangnam and Yeouido districts, where young professionals favor lease structures with defined upgrade cycles. Financial Services Commission debt-service-ratio rules compress maximum advance amounts for households in these high-cost precincts. The concentration of fintech engineering talent in Seongnam and Pangyo enables rapid deployment of AI-driven credit scoring models.
Busan-Ulsan
Commercial fleet demand from logistics operators and port-related transport services drives specialized vehicle financing products. Regional lenders face tighter collateral valuation standards for used commercial vehicles given depreciation variability. The Ulsan industrial corridor hosts captive finance operations tied to domestic automotive manufacturing, channeling preferential rates to dealership networks.
Daegu-Gyeongbuk
Secondary metropolitan demand for used vehicle financing remains underpenetrated relative to Seoul-Gyeonggi benchmarks. Local credit unions and regional banks compete through relationship-based underwriting rather than digital scale. The Daegu metro area shows rising adoption of subscription-based vehicle access among younger cohorts, displacing conventional installment demand.
Daejeon-Sejong
Government administrative relocation to Sejong City has generated steady demand for mid-market vehicle financing among civil servant households. MFDS disclosure mandates receive stricter enforcement in this regulatory-proximate zone, compelling lenders to standardize total-cost-of-credit presentations. Daejeon's research institute cluster supports pilot programs for electric vehicle loan products aligned with carbon-neutral mobility targets.
Gwangju-Honam
Agricultural and small commercial vehicle financing dominates regional lending portfolios, with shorter-term structures preferred by borrower segments facing income seasonality. The Honam region's distance from Seoul-based digital platforms preserves traditional branch-network competition. Regional banks here face elevated funding costs relative to megabank competitors, compressing margins on secured auto products.
South Korea Auto Loan Market Competitive Landscape
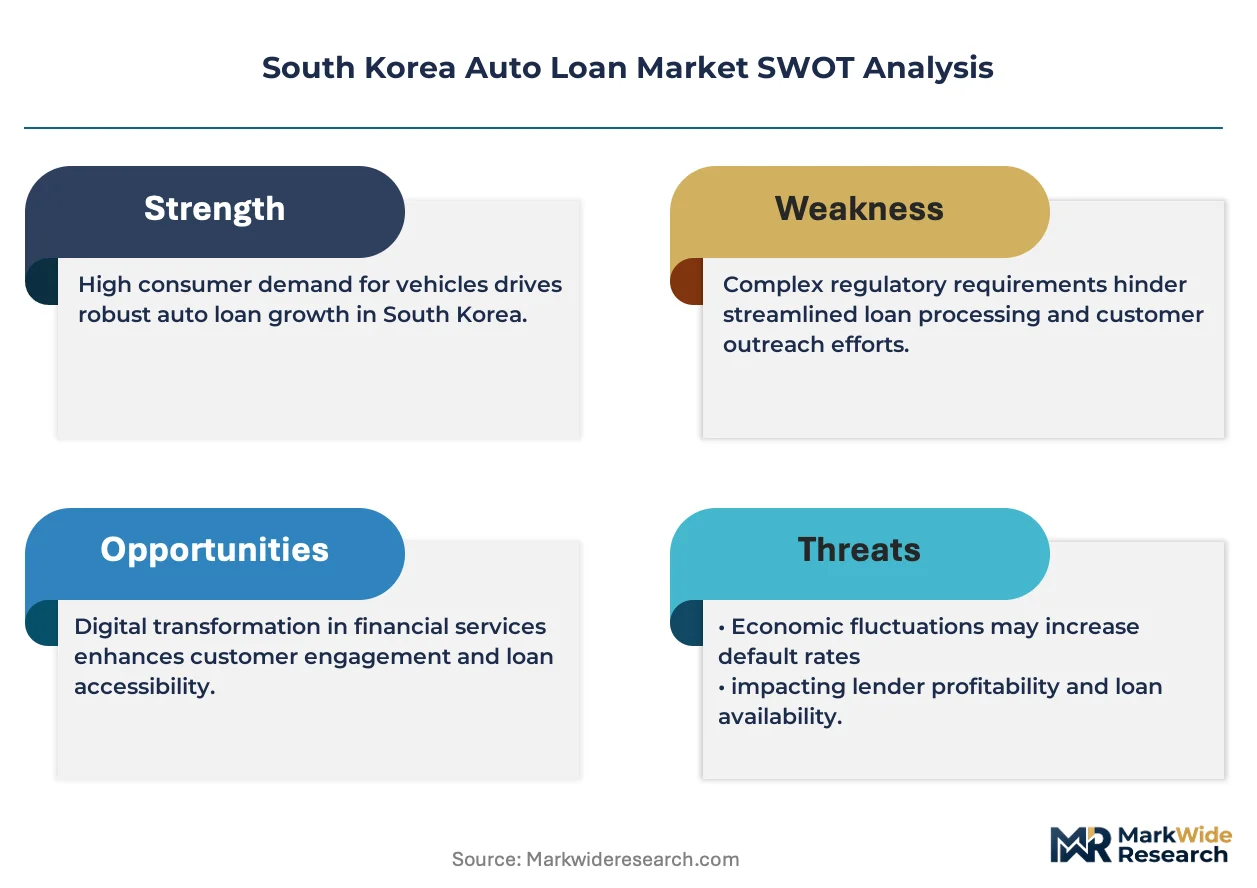
The competitive structure tilts toward captive finance arms integrated with automotive manufacturing and distribution networks. Market concentration reflects the dominance of manufacturer-backed lenders alongside diversified financial holding companies with deposit-funded cost advantages. Three archetypes define positioning: automotive captives leveraging bundled dealership incentives, bank-affiliated capital companies accessing low-cost funding through parent balance sheets, and independent non-bank lenders targeting specialized collateral segments. Primary competitive moves center on digital origination platform investment and geographic expansion into underpenetrated secondary metropolitan areas.
Among bank-affiliated specialists, Hana Capital and IBK occupy positions anchored by parent banking networks and deposit bases. Hyundai Capital Services exemplifies the captive finance archetype through its structural integration with domestic automotive manufacturing. BMW Group Financial Services Korea represents the premium import captive segment, deploying specialized balloon-payment structures in Seoul's high-income districts. These three entities illustrate the tripartite competitive structure: banking-group capital companies, domestic automotive captives, and import-focused financial services arms.
| Leading Market Players |
|---|
| Hana Capital |
| BMW Group Financial Services Korea |
| Hyundai Capital Services |
| RCI Financial Services |
| Mercedes Benz Group |
| IBK (Industrial Bank of Korea) |
| Woori Bank |
| Toyota Financial Services |
| SHINHAN FINANCIAL GROUP |
| Others |
Pricing and Supply Chain Analysis
Financial Services Commission debt-service-ratio ceilings are compressing advance amounts and forcing lenders toward shorter-term product structures that reshape how origination costs flow through pricing tiers. This regulatory pressure concentrates pricing power among deposit-funded bank affiliates and captive finance arms with captive supply advantages.
Pricing Analysis
Bundled manufacturer incentives versus unbundled rate shopping defines the pricing split. Three-tier pricing structure across premium captive, standard bank-affiliated, and economy non-bank tiers separates borrowers by credit tier and collateral age. Price differentiation hinges on loan-to-value ratios and MFDS disclosure compliance costs. Pricing pressure stems from compressed spreads at the standard tier where bank capital companies compete aggressively. Corporate fleet buyers show lowest price sensitivity; thin-file individual borrowers in Gyeonggi province show highest.
Supply Chain Analysis
Regional distribution centers in Seoul, Busan, and Daegu anchor hub-and-spoke patterns for vehicle collateral valuation and documentation. Supply chain configuration draws from domestic automotive manufacturing clusters in Ulsan and Asan, plus import nameplate distribution through Busan port facilities. Raw material exposure centers on semiconductor content for connected vehicles and battery metals for electric transition portfolios. Single-source vulnerability concentrates in captive finance IT platforms. Distribution runs through dealership networks with increasing direct-to-consumer digital bypass.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Korea's auto loan market reads as a late-cycle quality story where lease financing uptake among Seoul professionals signals demand-shift toward premium, flexible specification products. Lenders must now compete on digital origination speed rather than rate alone.
For Market Incumbents: Acquire digital underwriting capabilities and alternative data infrastructure. Hyundai Capital Services and Hana Capital should deepen integration with parent manufacturing and banking networks respectively to defend against fintech origination platforms. MFDS stress-testing compliance demands enhanced modeling investment. Channel control through exclusive dealership arrangements faces Korea Fair Trade Commission scrutiny requiring defensive legal positioning. For New Entrants and Emerging Players: Capture whitespace in used-vehicle financing across Daegu-Gyeongbuk and Gwangju-Honam regions where branch-network incumbents lack digital scale. Subscription-based vehicle access models in Seoul's under-35 professional cohort offer the most penetrable segment. Go-to-market angle should emphasize mobile-first approval workflows with AI-driven credit scoring for thin-file borrowers excluded by conventional scorecards. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized non-bank lenders possessing regulatory compliance infrastructure and secondary metropolitan geographic footprint. Long-term viability favors entities with diversified funding beyond wholesale markets and demonstrated stress-testing capability. Watch Financial Services Commission household debt aggregate thresholds as the signal for regulatory tightening inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Origination Platform Deployment | Mobile-first workflows capture time-sensitive borrowers in Seoul and Gyeonggi province. |
| AI-Driven Credit Scoring Investment | Alternative data models expand access to utility payment and mobile subscription histories. |
| Electric Vehicle Loan Product Development | Carbon-neutral mobility incentives from government policy create regulatory tailwinds. |
| Secondary Metropolitan Expansion | Daegu and Gwangju underpenetration offers whitespace for specialized used-vehicle financing. |
| Captive Finance Integration Deepening | Manufacturer-backed incentive bundling sustains preferential pricing on new vehicle portfolios. |
Research Methodology
Coverage spans Seoul Capital Area, Busan-Ulsan, Daegu-Gyeongbuk, Daejeon-Sejong, and Gwangju-Honam regions, with primary inputs from each. The analysis combines structured interviews with auto finance product managers, dealership operations directors, regulatory compliance officers at non-bank lenders, and fintech platform engineers with secondary validation. Secondary sources include Financial Services Commission regulatory filings, MFDS disclosure requirement documents, Korea Fair Trade Commission bundling enforcement records, and vehicle registration database extracts. Bottom-up origination volume modeling and top-down household debt aggregate analysis provide triangulation.
Granularity-level modeling disaggregates loan type, customer segment, interest rate structure, and term length dimensions across the projection horizon. The analytical framework derives CAGRs from segmented origination flow projections calibrated to debt-service-ratio ceiling impacts and lease financing adoption curves. Electric vehicle transition policy timelines and subscription model displacement rates inform scenario-weighted outputs.
Regulatory tightening beyond current debt-service-ratio ceilings, faster-than-expected subscription model adoption, and wholesale funding cost volatility are the dominant revision risks. Forecasts reflect documented assumptions around household debt aggregate trajectories and MFDS enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Machinery Rental and Leasing Market
Loans and Leasing
US Auto Loan Market
Loans and Leasing
USA Home Loan Market
Loans and Leasing
Housing Finance Market
Loans and Leasing
Automotive Finance Market
Loans and Leasing
Asia-Pacific Motorcycle Loan Market
Loans and Leasing
Commercial Lending Market
Loans and Leasing
India Student Loan Market
Loans and Leasing
Vehicle Leasing Market
Loans and Leasing
China Home Loan Market
Loans and Leasing
Premium Finance Market
Loans and Leasing
Canada Home Equity Lending Market
Loans and Leasing
Brazil Home Loan Market
Loans and Leasing
Debt Financing Market
Loans and Leasing
Europe Used Car Financing Market
Loans and Leasing
Russia Student Loan Market